
 China Automotive Adaptive Lighting System Market | 2026-2036
China Automotive Adaptive Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
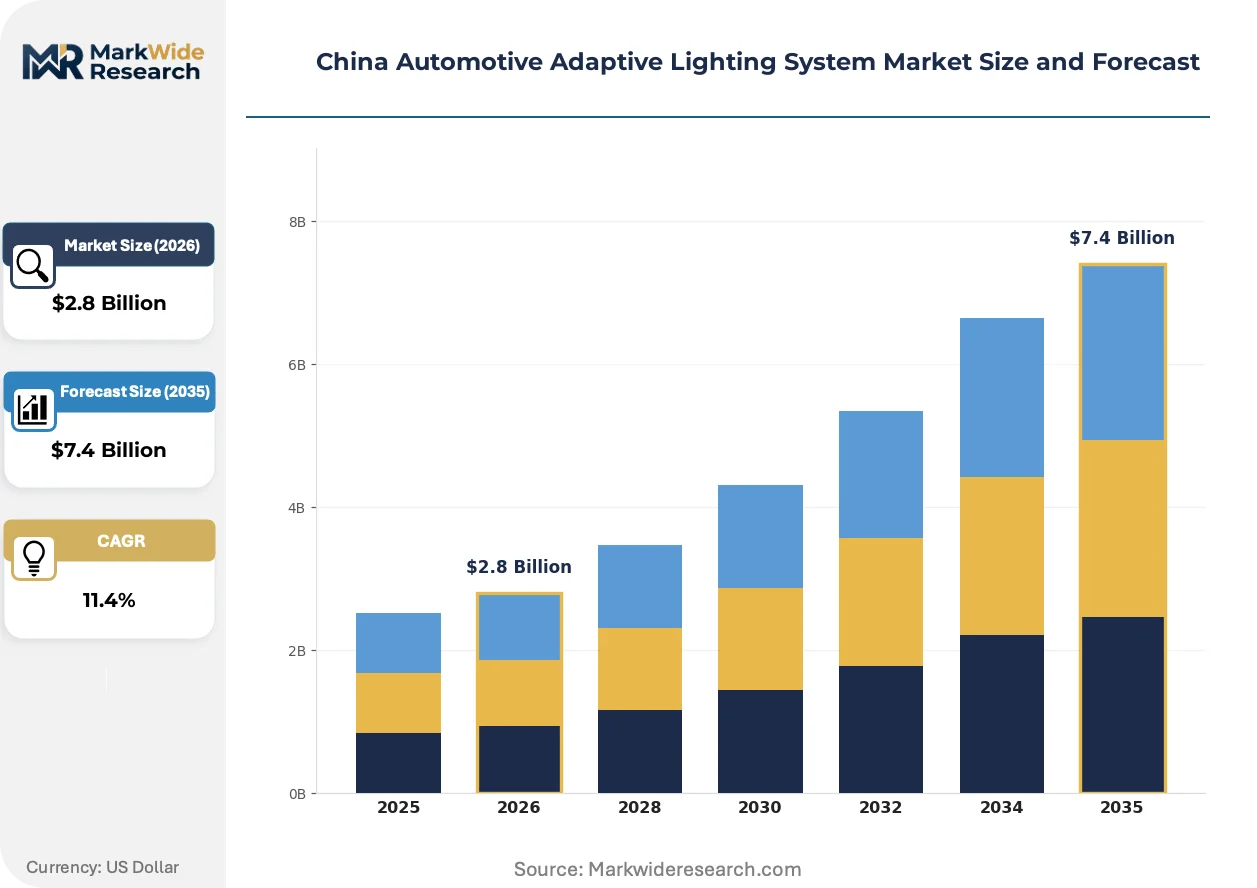
China Automotive Adaptive Lighting System Market Outlook
GB 4785 vehicle lighting certification is bifurcating the competitive landscape between qualified tier-one suppliers and uncertified entrants. Valeo Group leverages its Changshu manufacturing base to sustain localized matrix LED production for domestic OEMs. Koito Manufacturing anchors premium AFS module supply through its joint venture with Shanghai Koito Automotive Lamp. HELLA KGaA Hueck & Co. competes on sensor-integrated control systems that dominate European-branded vehicle platforms assembled in China.
Automotive adaptive lighting systems modulate beam patterns through camera-fed algorithms and servo-controlled actuators, typically operating across 3,000 to 6,000 Kelvin color temperatures with response latencies below 100 milliseconds to prevent oncoming glare. Their primary commercial purpose is to sustain driver visibility during dynamic road conditions without manual intervention. Matrix LED configurations lead volume shipments among product types while laser lighting occupies the premium tier where margin pools concentrate. Control modules and sensors together capture the majority of component-level value as software-defined beam shaping displaces purely hardware-based solutions.
MIIT enforces GB standards compliance through type-approval protocols that gate market access for imported and domestically produced lighting systems alike. SAMR oversees aftermarket certification channels where counterfeit components persist despite tightened inspection regimes. NMPA-aligned vehicle safety assessments increasingly incorporate adaptive lighting performance into overall crash-avoidance scoring. Stakeholders must monitor how dual carbon policy targets reshape supplier qualification criteria for energy-efficient light source technologies.
Market Dynamics
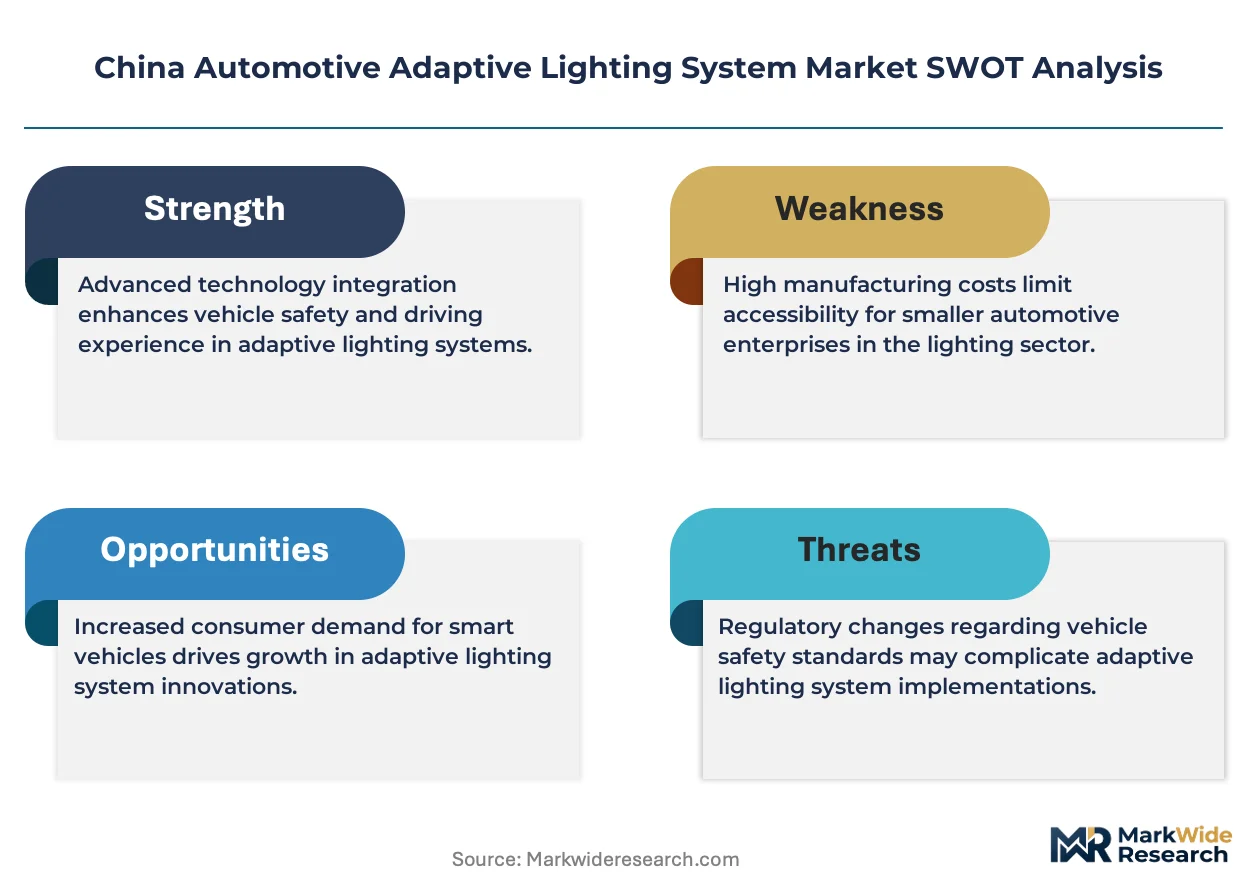
MIIT's updated GB 4785 certification requirements are compressing supplier timelines and redrawing competitive boundaries between certified tier-one lighting system manufacturers and uncertified market entrants.
Growth Catalysts
- New Energy Vehicle Mandates:GB standards now require adaptive beam patterns for NEV type-approval, forcing domestic EV manufacturers to source matrix LED configurations from qualified suppliers.
- Yangtze River Delta Cluster Concentration:Shanghai and Jiangsu province host dense OEM assembly operations that demand localized adaptive lighting module production.
- Dual Carbon Policy Alignment:Energy-efficient light source technologies receive preferential supplier qualification under national decarbonization targets.
Market Restraints
- Sensor Cost Volatility:Camera modules and LiDAR components face input price swings that compress control module margins.
- Changshu Supply Concentration:Valeo's localized production dominance creates single-source risk for domestic OEMs seeking matrix LED volume.
- GB 4785 Certification Friction:Type-approval protocols delay market entry for imported lighting systems by 12-18 months.
Strategic Opportunities
- Software-Defined Beam Shaping:Algorithm-controlled modulation is displacing hardware-only solutions, opening white space for control module specialists.
- Aftermarket Certification Channels:SAMR's tightened inspection regimes create premium positioning for compliant replacement component suppliers.
- Laser Lighting Tier Migration:Premium margin pools above matrix LED configurations attract tier-one investment in solid-state light source R&D.
Industry Challenges
- Embedded Software Talent Scarcity:Real-time image processing and servo-control algorithm development requires scarce automotive software engineering capacity.
- GB Standard Revision Cycle:MIIT's evolving safety assessments force continuous recertification investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive Adaptive Lighting System Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Matrix LEDs, Laser Lighting, AFS, Halogen Component: Control Module, Sensors, Light Source, Power Supply Vehicle Type: SUVs, Sedans, Trucks, Luxury Cars End User: OEMs, Aftermarket Retailers, Fleet Operators, Consumers |
| Companies Covered | HELLA KGaA Hueck & Co., Valeo Group, Koito Manufacturing Co. Ltd, Osram Licht AG, Koninklijke Philips N.V., Hyundai Mobis, Magneti Marelli SpA, Stanley Electric Co. Ltd, Shanghai Koito Automotive Lamp Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive Adaptive Lighting System Market Strategic Shifts
Beam modulation technology is migrating from mechanical actuators to camera-fed algorithmic control, reshaping supplier value capture toward software and sensor integration.
Matrix LED headlamp systems are decomposing the traditional headlamp value chain. These configurations use individually addressable LED segments to shape beam patterns without mechanical movement. Domestic EV manufacturers are accelerating adoption for NEV platform differentiation. Hardware-only suppliers face margin compression as software-defined modulation captures component-level value.
MIIT's enforcement of updated GB 4785 vehicle lighting certification is tightening market access gates. Type-approval protocols now mandate adaptive performance testing for new energy vehicle certifications. Uncertified entrants face exclusion from OEM supply lists. Tier-one suppliers with established compliance infrastructure are consolidating procurement relationships.
Buyer procurement patterns are compressing supplier qualification cycles. OEMs are unbundling after-sales service contracts from initial lighting system supply agreements. Tier-one manufacturers must now compete separately for replacement component business through SAMR-certified aftermarket channels. This shift is most visible in Shanghai-based NEV assembly operations where platform refresh cycles have shortened.
China Automotive Adaptive Lighting System Market Segmentation
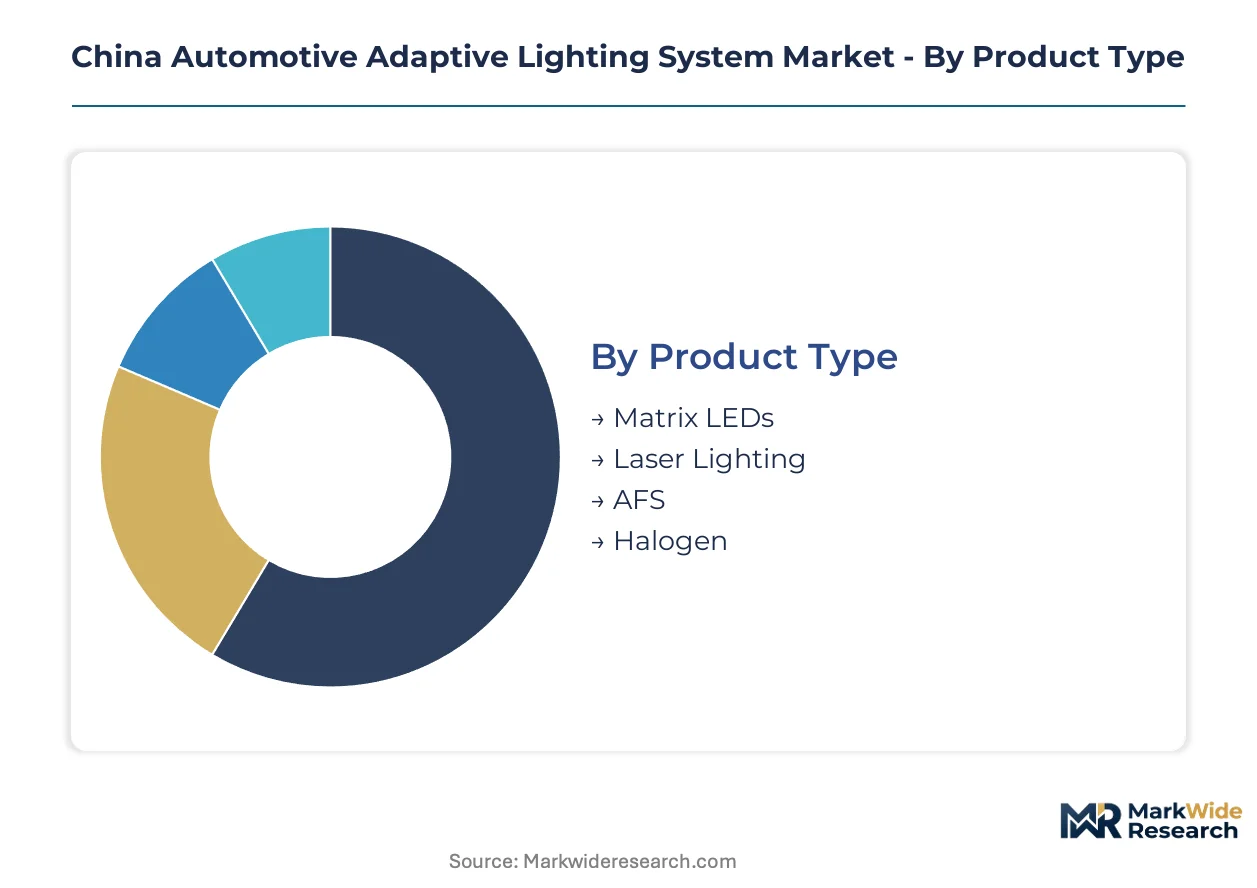
Adaptive lighting system segmentation in China tracks how MIIT's GB 4785 certification tiers create divergent procurement pathways across product configurations and supply tiers. Component-level value capture increasingly concentrates where software-defined beam shaping displaces hardware-only solutions.
Product Type:
GB 4785 type-approval protocols bifurcate procurement between certified matrix LED configurations and uncertified legacy alternatives, reshaping supplier qualification hierarchies.
- Matrix LEDs:Individually addressable LED segments enable algorithmic beam pattern modulation without mechanical actuators. Domestic EV manufacturers in the Yangtze River Delta cluster source these configurations to satisfy NEV certification mandates. Control module and sensor integration captures the majority of component-level value as hardware-only suppliers face margin compression.
- Laser Lighting:Solid-state light sources operate at extended ranges with higher luminous efficacy, commanding premium positioning where margin pools concentrate above matrix LED tiers. Luxury vehicle platforms assembled in Shanghai and Jiangsu province anchor current demand as tier-one suppliers invest in localized solid-state R&D capacity.
- AFS:Adaptive Front-lighting Systems with servo-controlled actuators modulate beam direction through camera-fed inputs, serving mid-tier vehicle segments where cost constraints limit full matrix adoption.
- Halogen:Legacy incandescent technology persists in entry-level vehicle categories and aftermarket replacement channels outside SAMR-certified supply chains.
Matrix LEDs handle the majority of throughput; laser lighting is expanding most quickly on share.
Component:
Cost tier stratification separates software-integrated control modules from commodity light source hardware, with sensor-integrated systems commanding procurement premiums.
- Control Module:Embedded algorithms process real-time camera inputs to direct beam modulation with sub-100 millisecond response latencies. Software-defined solutions displace purely hardware-based actuation, concentrating value capture among tier-one suppliers with automotive software engineering capacity.
- Sensors:Camera modules and LiDAR components feed environmental data to adaptive algorithms, facing input price volatility that compresses margins despite functional criticality.
- Light Source:LED and laser emitters provide the physical illumination substrate, with energy-efficient technologies receiving preferential supplier qualification under dual carbon policy targets.
- Power Supply:Voltage regulation and thermal management hardware supports stable operation across 3,000 to 6,000 Kelvin color temperature ranges.
Control modules command the highest value per unit; sensors are gaining share fastest as camera-fed algorithms proliferate.
Vehicle Type:
Application requirements vary sharply between passenger comfort optimization and commercial duty-cycle durability, segmenting procurement specifications.
- SUVs:Higher ride heights demand extended beam throw and broader horizontal spread patterns, driving adoption of full matrix LED configurations with cornering illumination functions.
- Sedans:Aerodynamic headlamp housings favor compact light source packaging, with mid-tier models balancing AFS servo systems against matrix LED cost premiums.
- Trucks:Commercial duty cycles prioritize durability and serviceability, with procurement favoring modular component architectures over integrated software-defined systems.
- Luxury Cars:Premium positioning justifies laser lighting and advanced sensor fusion, with OEMs unbundling after-sales contracts to capture replacement component value separately.
SUVs anchor current volume demand; luxury cars show the steepest expansion trajectory as premium NEV platforms proliferate.
End User:
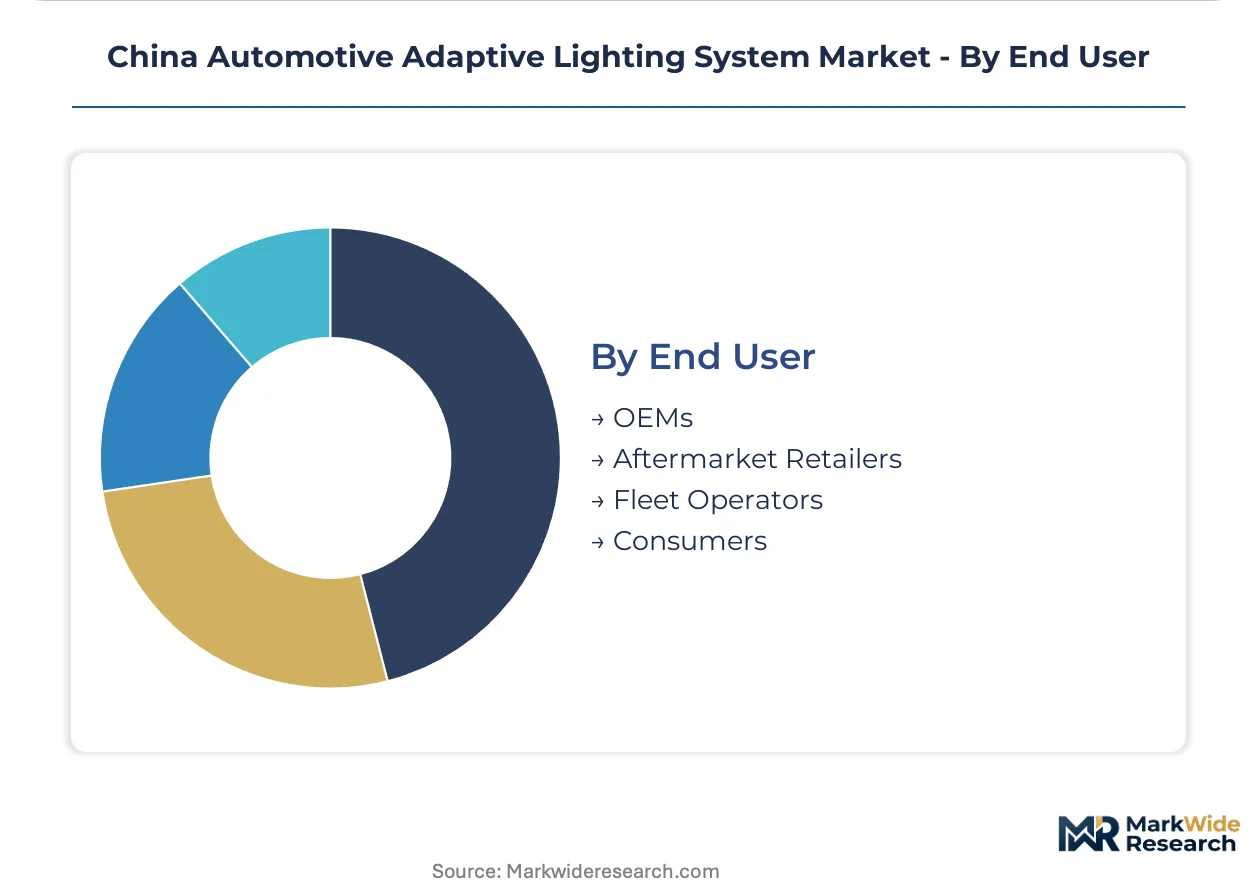
Customer type determines whether procurement flows through OEM type-approval channels or SAMR-certified aftermarket pathways, with divergent margin structures.
- OEMs:Vehicle manufacturers mandate GB 4785 certified systems for type-approval, consolidating procurement relationships with tier-one suppliers possessing established compliance infrastructure and Changshu-based localized production.
- Aftermarket Retailers:SAMR's tightened inspection regimes create premium positioning for compliant replacement component suppliers, though counterfeit products persist in uncertified channels.
- Fleet Operators:Commercial vehicle managers prioritize total cost of ownership and service interval optimization, favoring modular systems with field-replaceable components.
- Consumers:Individual purchasers in replacement markets face information asymmetry between certified and uncertified product tiers, with pricing stratifying across compliance grade rather than performance specifications alone.
OEMs dominate procurement volume; aftermarket retailers are climbing the fastest on share as platform refresh cycles compress replacement demand timing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NEV assemblers and premium passenger vehicle manufacturers anchor procurement across China's automotive clusters, with regulatory certification requirements and localized production infrastructure shaping supplier selection criteria.
Yangtze River Delta
Shanghai and Jiangsu province host dense OEM assembly operations demanding matrix LED volume from Changshu-based production facilities. MIIT's GB 4785 type-approval protocols mandate adaptive beam testing for NEV certification, compressing supplier timelines. Valeo Group's localized manufacturing base sustains matrix LED output for domestic EV manufacturers seeking compliance.
Pearl River Delta
Guangdong province's electronics manufacturing ecosystem supports sensor module and control system fabrication for adaptive lighting integration. SAMR aftermarket certification channels create premium positioning for compliant replacement component suppliers in Shenzhen and Dongguan. Counterfeit products persist in uncertified channels despite tightened inspection regimes.
Beijing-Tianjin-Hebei
State-owned vehicle manufacturers and premium joint ventures anchor demand for AFS modules with servo-controlled actuation. NMPA-aligned vehicle safety assessments incorporate adaptive lighting performance into crash-avoidance scoring. Tianjin's port infrastructure facilitates imported lighting system entry despite 12-18 month GB 4785 certification delays.
Sichuan-Chongqing
Western China's expanding automotive assembly capacity drives procurement of cost-optimized adaptive lighting configurations for mid-tier vehicle segments. Dual carbon policy targets reshape supplier qualification criteria for energy-efficient light source technologies. Chongqing-based OEMs unbundle after-sales service contracts from initial supply agreements.
China Automotive Adaptive Lighting System Market Competitive Environment
Player mix skews toward European and Japanese tier-one lighting system specialists with established GB standards compliance infrastructure. The supplier base concentrates around certified manufacturers possessing localized production and type-approval capabilities. Three strategic archetypes dominate: matrix LED volume producers, sensor-integrated control system specialists, and premium laser lighting developers. Competitive moves center on software-defined beam shaping R&D and SAMR-certified aftermarket channel expansion.
Within the tier-one certified supplier tier, Valeo Group, HELLA KGaA Hueck & Co., and Koito Manufacturing Co. Ltd occupy positions reflecting divergent geographic and technological specializations. Valeo exemplifies the localized volume producer archetype through its Changshu manufacturing presence. HELLA represents the sensor-integrated control systems specialist serving European-branded vehicle platforms assembled in China. Koito Manufacturing anchors the Japanese tier-one contingent through its joint venture structure with Shanghai Koito Automotive Lamp Co. Ltd., exemplifying partnership-based market access strategies.
| Leading Market Players |
|---|
| HELLA KGaA Hueck & Co. |
| Valeo Group |
| Koito Manufacturing Co. Ltd |
| Osram Licht AG |
| Koninklijke Philips N.V. |
| Hyundai Mobis |
| Magneti Marelli SpA |
| Stanley Electric Co. Ltd |
| Shanghai Koito Automotive Lamp Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Twelve-to-eighteen-month GB 4785 certification lead times compress supplier pricing power by gating market access while concentrating procurement leverage among tier-one manufacturers with established compliance infrastructure. This temporal bottleneck reinforces cost-plus contract structures indexed to semiconductor input costs, with domestic OEMs extracting volume concessions from Changshu-based producers.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate procurement between domestic EV manufacturers and tier-one lighting system suppliers. Price differentiation rests on GB 4785 certification tier and after-sales service bundling, with uncertified aftermarket channels undercutting compliant suppliers by fifteen to twenty percent. Pricing pressure intensifies as sensor cost volatility erodes control module margins. Fleet operators exhibit highest price sensitivity due to total cost of ownership scrutiny, while luxury NEV platforms show lowest sensitivity as laser lighting premiums absorb component inflation.
Supply Chain Analysis
Inventory cycles stretching ninety to one hundred twenty days expose Changshu production concentration as a structural vulnerability for matrix LED volume fulfillment. Supply concentrates in China, Japan, and Germany, with camera modules and LiDAR components drawing from Taiwan and South Korean semiconductor fabrication. Single-source risk pervades the Yangtze River Delta cluster where Valeo's localized dominance creates procurement bottlenecks. Distribution runs through OEM direct supply agreements and SAMR-certified aftermarket channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined vehicle architectures threaten hardware-centric lighting system incumbents with disintermediation, forcing defensive repositioning around algorithmic beam control capabilities. Incumbents must navigate this substitution pressure by consolidating software engineering capacity and securing sensor integration partnerships.
For Market Incumbents: Fortify GB 4785 certification moats through continuous compliance investment as MIIT revises safety assessment protocols. Deepen Changshu manufacturing scale to capture Yangtze River Delta NEV platform refresh cycles. Acquire embedded software talent pools to defend against algorithm-native entrants displacing hardware-only suppliers. For New Entrants and Emerging Players: Lead with aftermarket certification channel penetration where SAMR inspection regimes create premium positioning against counterfeit competition. Target Sichuan-Chongqing mid-tier vehicle segments with cost-optimized AFS configurations. Pursue fleet operator direct relationships emphasizing modular serviceability and field-replaceable component architectures. For Investors and Strategic Acquirers: Carve-out targets emerge from European tier-one automotive lighting divisions seeking China market exit due to certification friction and margin compression. Long-term viability favors sensor-integrated control system specialists over commodity light source hardware. Monitor MIIT dual carbon policy enforcement as the signal indicating accelerated supplier qualification for energy-efficient technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Beam Control Investment | Algorithmic modulation displaces mechanical actuators, concentrating value capture in control module development. |
| GB 4785 Certification Infrastructure Expansion | Type-approval capability gates OEM procurement relationships and excludes uncertified aftermarket competitors. |
| Changshu Manufacturing Footprint Scaling | Localized production satisfies Yangtze River Delta NEV assembly demand with reduced logistics exposure. |
| SAMR-Certified Aftermarket Channel Development | Compliant replacement component positioning captures premium margin pools as platform refresh cycles compress. |
| Laser Lighting R&D Partnership | Solid-state light source advancement accesses luxury vehicle margin tiers above matrix LED configurations. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of MIIT regulatory filings, vehicle production databases, and tier-one supplier disclosure documents. Primary inputs drew from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and automotive lighting R&D directors across the Yangtze River Delta and Pearl River Delta clusters. Bottom-up triangulation against top-down market sizing validated component-level value capture estimates and installation rate assumptions.
Segmentation dimensions modeled span product type, component category, vehicle class, and end-user channel across the projection horizon. CAGRs derive from regression analysis of historical NEV penetration curves and adaptive lighting content-per-vehicle trajectories. Forecast inputs incorporate MIIT policy implementation timelines, dual carbon target enforcement intensity, and semiconductor supply elasticity assumptions.
The analysis sits within stated boundaries; outcomes outside sustained NEV platform expansion or accelerated GB standard revision cycles would require recalibration. Forecasts reflect documented assumptions regarding certification timeline stability and sensor cost normalization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Highway Crash Cushion Market
Automotive Safety and Security Systems
Stolen Vehicle Recovery (SVR) Tracking Service Market
Automotive Safety and Security Systems
Two Wheeler Anti-Lock Braking System Market
Automotive Safety and Security Systems
Motorcycle E-Call Market
Automotive Safety and Security Systems
Automotive Airbag Gas Generators Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Wearable Motorcycle Airbags Market
Automotive Safety and Security Systems
LAMEA Hill-Start Assist System Market
Automotive Safety and Security Systems
Automotive Battery Pack Fire Barrier Pad Market
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market
Automotive Safety and Security Systems
Occupant Classification System Market
Automotive Safety and Security Systems
Driving Helmet Market
Automotive Safety and Security Systems
Automotive Brake Pad Wear Sensor Harness Market
Automotive Safety and Security Systems
Automotive Mirror System Market
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market