
 Automotive Mirror Dimming Market | 2026-2036
Automotive Mirror Dimming Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Mirror Dimming Market Analysis
A capital-intensity divergence between in-house electrochromatic glass producers and assembly-only mirror suppliers is bifurcating competitive returns in the Automotive Mirror Dimming Market. Gentex Corporation leverages captive electrochromatic film production to sustain margin capture across interior and exterior mirror lines. Magna International anchors its position through integrated module supply to North American and European OEM platforms. Samvardhana Motherson competes on cost-optimized exterior mirror assemblies for volume vehicle programs.
Automotive mirror dimming encompasses electrochromatic, suspended particle device, liquid crystal, and photochromic technologies that modulate reflective surface opacity in response to ambient light intensity, typically achieving 7-10% visible light transmission in darkened states to eliminate headlamp glare. The primary commercial purpose is enhancing driver safety and visual comfort during nighttime and tunnel transit. Interior mirrors lead value contribution due to higher electrochromatic penetration and replacement frequency, while smart mirrors represent the fastest-expanding category as camera-monitor integration redefines rear-vision architecture. Liquid crystal technology occupies niche positioning in cost-sensitive segments where response-speed requirements are modest.
NHTSA Federal Motor Vehicle Safety Standard 111 shapes mirror field-of-view and glare-control requirements in the United States, while ECE R46 governs mirror installation and performance across European type approvals. ECHA REACH compliance constrains electrochromatic gel chemistry and conductive coating formulations, elevating R&D burdens for formulation suppliers. OEMs and Tier-1 suppliers must monitor camera-based mirror-replacement regulatory pathways in Japan and South Korea, where METI and MFDS standards-setting will determine whether smart mirrors achieve full regulatory substitution for conventional reflective surfaces.
Market Dynamics
Electrochromatic film manufacturing concentration in North America and East Asia is compressing margin capture for assembly-only mirror suppliers while rewarding backward-integrated producers with captive gel chemistry and conductive coating capabilities.
Growth Catalysts
- NHTSA FMVSS 111 glare-reduction mandates:Updated field-of-view requirements in the United States compel OEMs to specify automatic dimming as standard equipment on premium and mid-tier vehicle platforms.
- Camera-monitor system regulatory pathways:Japan's METI and South Korea's MFDS are advancing smart mirror substitution frameworks that expand addressable mirror architecture beyond traditional reflective surfaces.
- ECE R46 visibility standards:European type-approval tightening accelerates electrochromatic penetration across German premium OEM global platforms, cascading specifications to volume manufacturers.
Market Restraints
- Indium tin oxide supply concentration:Conductive coating feedstock dependence on Chinese rare earth processing creates input cost volatility and geopolitical exposure for electrochromatic film producers.
- ECHA REACH compliance burdens:Gel chemistry reformulation requirements elevate R&D fixed costs for formulation suppliers, squeezing mid-scale competitors without captive toxicology testing infrastructure.
- Liquid crystal price-performance ceiling:Response time limitations above 100 milliseconds constrain adoption in applications requiring rapid glare suppression, ceding ground to electrochromatic alternatives.
Strategic Opportunities
- India volume vehicle electrification:BEV platform launches by domestic and multinational OEMs create first-mover positioning for cost-optimized photochromic mirror specifications in price-sensitive segments.
- ISO 16505 camera-monitor standards:Global harmonization of smart mirror performance benchmarks enables regulatory substitution for exterior reflective mirrors in commercial vehicle applications.
- Aftermarket channel digitization:Direct-to-consumer replacement mirror sales through OEM-certified online platforms bypass traditional Tier-1 distribution, capturing margin from collision repair and upgrade demand.
Industry Challenges
- Electrochromatic process engineering talent scarcity:Thin-film deposition and gel encapsulation expertise concentrates at a handful of materials science programs, constraining capacity expansion timelines.
- Smart mirror software-hardware integration complexity:Camera latency compensation, display calibration, and fail-safe redundancy requirements extend development cycles and certification timelines for Tier-1 suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Mirror Dimming Market |
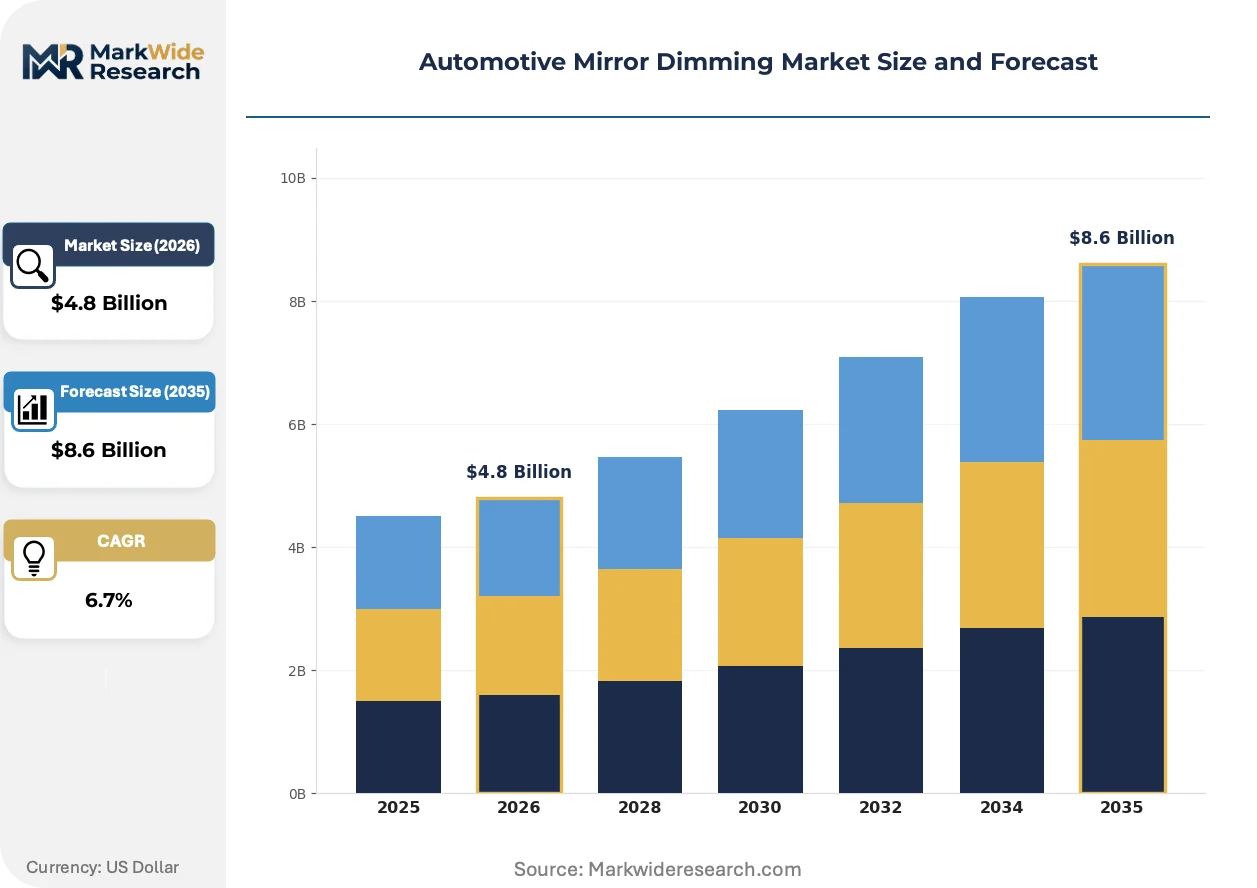
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Mirrors, Exterior Mirrors, Smart Mirrors, Standard Mirrors Technology: Electrochromatic, Suspended Particle Device, Liquid Crystal, Photochromic Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Luxury Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Gentex Corporation, Magna International Inc., Ficosa International S.A., Samvardhana Motherson Group, Murakami Corporation, SL Corporation, Ichikoh Industries Ltd., Honda Lock Mfg. Co. Ltd., FLABEG Automotive Glass Group GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Mirror Dimming Market Emerging Trajectories
Mirror architecture is bifurcating between refined electrochromatic systems for conventional vehicles and camera-monitor replacements for next-generation platforms, with technology selection increasingly determined by regulatory approval status rather than cost alone.
Electrochromatic technology is fragmenting across multiple film deposition methods, with sputtered versus sol-gel manufacturing routes diverging based on scale and performance requirements. German and Japanese OEMs favor sputtered films for premium interior mirrors demanding sub-2-second darkening response. Sol-gel processing gains traction in exterior mirror applications where cost targets dominate absolute performance specifications. This process divergence is fragmenting supplier specialization and fragmenting equipment vendor relationships across regional production clusters.
EU F-Gas Regulation phase-down schedules are accelerating conductive coating chemistry transitions away from fluorinated process gases in electrochromatic manufacturing. Mirror film producers in Germany and the Czech Republic are retrofitting production lines to accommodate fluorine-free etching chemistries ahead of 2030 quota reductions. Exterior mirror assemblies with integrated heating elements face disproportionate compliance burden given larger surface area requirements.
Fleet procurement is consolidating mirror specification authority at OEM platform engineering centers, displacing historical Tier-1 supplier design autonomy. North American and European commercial vehicle operators now defer entirely to factory-installed smart mirror configurations rather than aftermarket specification. This concentration is most visible in long-haul trucking segments where total cost of ownership calculations prioritize integrated warranty coverage over initial component pricing.
Automotive Mirror Dimming Market Segmentation
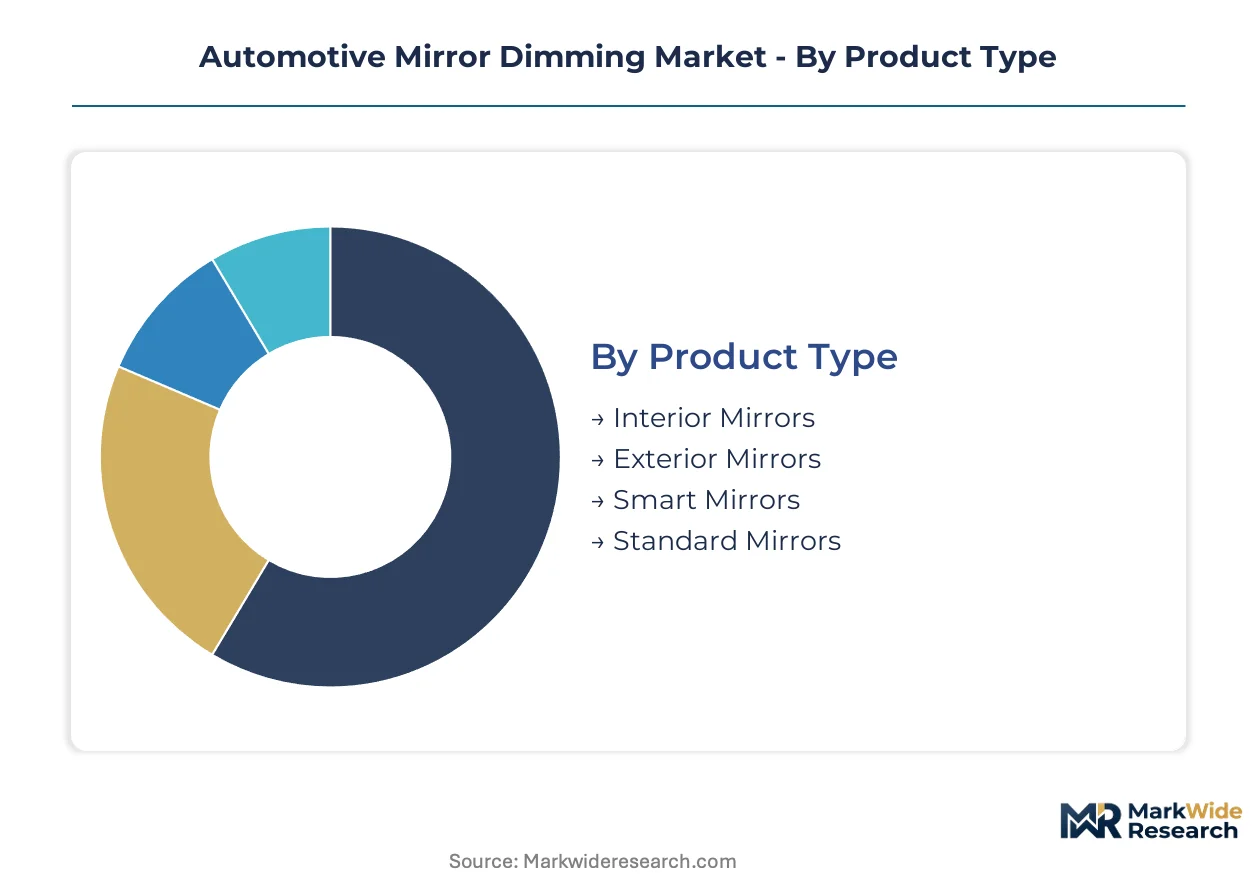
Segmentation in the Automotive Mirror Dimming Market reveals how technology selection and channel configuration determine margin capture. Product architecture and regulatory positioning create divergent competitive returns across interior, exterior, and camera-based mirror systems.
Product Type:
Margin pools concentrate in interior mirror assemblies where electrochromatic penetration is deepest and replacement cycles are shortest.
- Interior Mirrors:Electrochromatic films achieve 7-10% visible light transmission in darkened states through tungsten oxide and viologen gel chemistry. German premium OEMs specify these as standard equipment across mid-tier and luxury platforms, with NHTSA FMVSS 111 glare-reduction mandates accelerating adoption in US passenger vehicles.
- Smart Mirrors:Camera-monitor systems replace reflective surfaces with latency-compensated displays, redefining rear-vision architecture. Japan's METI and South Korea's MFDS are advancing regulatory substitution frameworks that expand addressable mirror architecture beyond traditional reflective surfaces.
- Exterior Mirrors:Larger surface areas and integrated heating elements drive unit economics, with ECE R46 visibility standards tightening performance thresholds across European type approvals.
- Standard Mirrors:Non-dimming reflective surfaces persist in entry vehicle segments where cost targets override glare-control specifications.
Interior mirrors hold installed capacity. Smart mirrors are rotating up the share rankings.
Technology:
Cost tier stratification separates premium electrochromatic systems from liquid crystal alternatives in price-sensitive segments.
- Electrochromatic:Sputtered and sol-gel film deposition routes fragment supplier specialization, with sputtered films commanding premium positioning for sub-2-second darkening response in German and Japanese OEM interior mirrors. EU F-Gas Regulation phase-down schedules are accelerating fluorine-free etching chemistry transitions.
- Suspended Particle Device:Rapid switching speed suits applications requiring immediate glare suppression, though manufacturing scale remains concentrated in North American production clusters.
- Liquid Crystal:Response time limitations above 100 milliseconds constrain adoption where rapid glare suppression is critical, ceding ground to electrochromatic alternatives in premium specifications.
- Photochromic:Light-responsive chemistry without electrical activation suits cost-optimized exterior mirror assemblies for volume vehicle programs in India.
Electrochromatic technology holds installed capacity. Suspended particle device is rotating up the share rankings.
Application:
Customer type determines specification authority, with fleet procurement consolidating mirror decisions at OEM platform engineering centers.
- Passenger Vehicles:Interior electrochromatic mirrors dominate value contribution due to higher penetration rates and replacement frequency in personal transportation segments.
- Luxury Vehicles:Premium OEMs anchor global specification-setting, cascading electrochromatic and smart mirror requirements to volume manufacturers through platform engineering decisions.
- Commercial Vehicles:Long-haul trucking operators defer to factory-installed smart mirror configurations where total cost of ownership calculations prioritize integrated warranty coverage.
- Heavy-Duty Trucks:ISO 16505 camera-monitor standards enable regulatory substitution for exterior reflective mirrors in commercial vehicle applications with expanded field-of-view requirements.
Passenger vehicles hold installed capacity. Luxury vehicles are rotating up the share rankings.
End User:
Channel configuration shapes margin distribution, with aftermarket digitization threatening traditional Tier-1 distribution economics.
- OEMs:Platform engineering centers now control mirror specification authority, displacing historical Tier-1 supplier design autonomy through consolidated fleet procurement.
- Tier-1 Suppliers:Integrated module supply to North American and European OEM platforms rewards backward-integrated producers with captive electrochromatic film capabilities.
- Aftermarket Providers:Direct-to-consumer replacement mirror sales through OEM-certified online platforms bypass traditional distribution, capturing margin from collision repair and upgrade demand.
- Vehicle Assemblers:Final assembly operations source cost-optimized exterior mirror assemblies for volume vehicle programs, particularly in price-sensitive electrification segments.
OEMs hold installed capacity. Aftermarket providers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for electrochromatic interior mirror modules while Chinese suppliers undercut exterior assemblies by 40-60 percent, creating a bifurcated procurement landscape for OEM platform engineers.
United States
NHTSA FMVSS 111 glare-reduction mandates compel domestic OEMs to specify automatic dimming across mid-tier and luxury vehicle lines. Michigan and Ohio anchor Tier-1 module assembly clusters serving Detroit Three platform engineering centers. Gentex Corporation's Zeeland, Michigan headquarters concentrates captive electrochromatic film production for North American supply.
Germany
Premium OEM platform specifications from BMW, Mercedes-Benz, and Volkswagen cascade electrochromatic requirements to global volume manufacturers. ECE R46 mirror-visibility standards tighten performance thresholds through KBA type-approval processes. Bavaria and Baden-Württemberg host specialized conductive coating suppliers retrofitting fluorine-free etching lines ahead of EU F-Gas Regulation 2030 quotas.
Japan
METI regulatory frameworks advance camera-monitor system substitution for conventional reflective mirrors in next-generation vehicle architectures. Kanto and Chubu regions concentrate Murakami Corporation and Ichikoh Industries mirror module production for domestic OEMs. JIS standards harmonization with ISO 16505 accelerates smart mirror commercialization timelines.
South Korea
Hyundai and Kia BEV platform launches drive specification authority toward integrated smart mirror configurations. MFDS automotive safety standards-setting determines regulatory substitution pathways for camera-monitor systems. Gyeonggi and Busan-Ulsan industrial corridors host SL Corporation and Honda Lock Mfg. module assembly operations.
India
Domestic and multinational OEM BEV launches create first-mover positioning for cost-optimized photochromic mirror specifications in price-sensitive segments. BIS automotive component standards govern mirror performance certification for local assembly. Maharashtra and Tamil Nadu vehicle manufacturing clusters source exterior mirror assemblies from Samvardhana Motherson cost-optimized supply programs.
Automotive Mirror Dimming Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with backward-integrated electrochromatic film producers capturing margin premiums while assembly-only suppliers compete on volume scale. The market structure concentrates around three strategic tiers: captive chemistry producers, integrated module suppliers, and cost-optimized assemblers. Dominant competitive moves include strategic partnerships for gel chemistry access and geographic expansion into India BEV platform supply.
Among North American and European integrated producers, Gentex Corporation and Magna International occupy positions exemplifying the backward-integrated archetype, while Ficosa International S.A. represents European module supply specialization. Samvardhana Motherson anchors the cost-optimized tier for volume vehicle program participation.
| Leading Market Players |
|---|
| Gentex Corporation |
| Magna International Inc. |
| Ficosa International S.A. |
| Samvardhana Motherson Group |
| Murakami Corporation |
| SL Corporation |
| Ichikoh Industries Ltd. |
| Honda Lock Mfg. Co. Ltd. |
| FLABEG Automotive Glass Group GmbH |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for indium tin oxide and electrochromatic gel chemistry lock in supply access and price visibility for backward-integrated mirror producers, while assembly-only suppliers face spot-market volatility in conductive coating feedstocks. This contract-structure divergence separates margin-stable captive producers from cost-pressured tier-two assemblers across North American and European supply bases.
Pricing Analysis
The customization-premium spread between sputtered film configurations and sol-gel alternatives runs through German and Japanese OEM interior mirror programs. Three-tier pricing structure across premium, standard, and economy levels stratifies by response-time performance and ECE R46 certification grade. Cost compression in photochromic exterior assemblies is intensifying because Indian BEV platform procurement prioritizes unit economics over glare-suppression specifications. Fleet buyers at commercial vehicle OEMs show least price sensitivity due to total cost of ownership calculations, while volume passenger vehicle segments in emerging markets anchor demand at economy tiers.
Supply Chain Analysis
China and Germany anchor electrochromatic film manufacturing, with Michigan and Ohio hosting final mirror module assembly for Detroit Three platforms. Conductive coating production draws from rare earth processing concentrated in Chinese refining operations, while gel chemistry formulation clusters in Bavaria and Baden-Württemberg. Single-source vulnerability in indium tin oxide supply creates geopolitical exposure for non-integrated producers. Distribution runs through OEM platform engineering centers that have displaced historical Tier-1 supplier design autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive mirror dimming market sits at a platform-economics inflection where camera-monitor system interoperability with ISO 16505 standards is reshaping specification authority away from reflective-component suppliers toward software-integrated module providers.
For Market Incumbents: Consolidate captive electrochromatic film capacity through selective acquisition of specialized gel chemistry suppliers in Germany and the Czech Republic. Deepen backward integration into conductive coating deposition to offset indium tin oxide supply concentration risk. Lock in long-term offtake agreements with Chinese rare earth processors before EU F-Gas Regulation quotas tighten further. For New Entrants and Emerging Players: METI certification fast-tracks for camera-monitor systems in Japan offer regulatory arbitrage against entrenched electrochromatic incumbents. White-space exists in cost-optimized photochromic exterior mirror supply for Indian BEV platforms where Samvardhana Motherson has not fully secured specification authority. Target fleet procurement consolidation at North American commercial vehicle OEMs through integrated warranty offerings rather than component pricing. For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated electrochromatic specialists with captive gel chemistry and established OEM platform relationships. Long-term viability favors producers with fluorine-free etching line retrofits completed ahead of EU quota reductions. Watch for MFDS regulatory substitution signals in South Korea as the inflection indicator for smart mirror addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gel Chemistry | Captive supply of viologen formulations insulates Gentex and Magna from ECHA REACH compliance cost spikes. |
| Fluorine-Free Etching Line Retrofit | German and Czech producers meeting EU F-Gas Regulation quotas ahead of schedule capture premium OEM specification. |
| ISO 16505 Certification Investment | Camera-monitor system approval enables regulatory substitution for exterior mirrors in heavy-duty trucking segments. |
| India BEV Platform Supply Agreement | First-mover positioning in photochromic exterior mirrors secures volume scale before multinational OEM localization accelerates. |
| Aftermarket Channel Digitization | OEM-certified online platforms bypass traditional Tier-1 distribution to capture collision repair margin pools. |
Methodological Framework
The analysis maps electrochromatic film deposition, suspended particle device manufacturing, liquid crystal assembly, and camera-monitor system integration, each validated through Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations managers. Primary interviews across these stakeholder roles combined with vehicle production databases, IHS Markit registration data, NHTSA FMVSS 111 compliance filings, and ECE R46 type-approval records. Bottom-up unit economics and top-down market sizing underwent cross-validation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derived from production ramp schedules and technology penetration curves, with electrochromatic response-time specifications and smart mirror regulatory approval timelines as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside NHTSA mandate enforcement levels, EU F-Gas Regulation quota implementation, or METI/MFDS substitution pathway decisions would require recalibration. Forecasts reflect assumptions about OEM platform standardization timelines and rare earth supply chain stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Automotive Panoramic Sunroof Market
Automotive Interior & Exterior
Automotive Sealants Market
Automotive Interior & Exterior
Vehicle Interior Air Quality Sensor Platforms Market
Automotive Interior & Exterior
Automotive Laser Lighting Market
Automotive Interior & Exterior
China Automotive Seats Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Insulation Market
Automotive Interior & Exterior
Asia-Pacific Automotive Seat Market
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Germany Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Russia Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Automotive Glove Box Market