
 Pedestrian Protection System Market | 2026-2036
Pedestrian Protection System Market Size, Share, and Industry Trends Forecast 2026-2036
Pedestrian Protection System Market Analytics
Platform licensing revenue is reconfiguring competitive economics as Tier 1 suppliers race to monetize software stacks for pedestrian detection algorithms. Continental leverages its sensor fusion expertise across radar-camera integration to sustain development partnerships with European OEMs. Robert Bosch anchors its position through manufacturing scale in semiconductor-dependent perception modules. Autoliv competes on occupant-to-pedestrian safety system interoperability, extending its airbag heritage into active hood lifters.
A pedestrian protection system comprises active and passive safety technologies engineered to detect human presence via electromagnetic or optical sensing and mitigate collision severity through automatic braking, deployable exterior airbags, or pop-up hood actuators operating within milliseconds of impact detection. Camera-based systems and radar technology dominate current deployment, though lidar technology represents the fastest-growing segment as solid-state units achieve automotive-grade cost curves. Sensors constitute the most mature product category with compressed margins, while autonomous braking modules capture the deepest value pools due to embedded software content and calibration complexity.
The National Highway Traffic Safety Administration mandates automatic emergency braking on passenger vehicles, compelling OEM integration of pedestrian-aware detection systems under Federal Motor Vehicle Safety Standards. Euro NCAP assessment protocols assign scoring weight to vulnerable road user protection, directly influencing vehicle manufacturer procurement priorities across EU member states. Stakeholders must monitor divergence between UN R152 homologation requirements and emerging state-level pedestrian safety ordinances in the United States to anticipate compliance architecture investments.
Market Dynamics
Sensor fusion architectures are compressing development timelines as automakers consolidate camera, radar, and lidar inputs into unified perception stacks, forcing Tier 1 suppliers to restructure software licensing models around functional safety certification rather than discrete hardware sales.
Growth Catalysts
- Euro NCAP Vulnerable Road User Protocols:The assessment framework assigns direct scoring weight to pedestrian and cyclist protection, compelling vehicle manufacturers to procure active hood lifters and autonomous braking modules for five-star ratings.
- Urban Vision Zero Commitments:Municipal governments in Germany, Japan, and the United States have enacted crash-reduction targets that mandate fleet operators integrate pedestrian-aware detection systems in high-density transit corridors.
- Solid-State Lidar Cost Curves:Automotive-grade solid-state units are achieving price points compatible with mass-market vehicle segments, expanding addressable volume beyond luxury OEMs.
Market Restraints
- Semiconductor Supply Concentration:Advanced driver-assistance system chips depend on concentrated foundry capacity in Taiwan, exposing perception module manufacturers to allocation volatility and extended lead times.
- Calibration Complexity:Multi-sensor fusion systems require millimeter-precision alignment during vehicle assembly, creating throughput bottlenecks at OEM plants and elevating warranty exposure.
- Regulatory Divergence:UN R152 homologation requirements for automatic emergency braking differ materially from emerging state-level pedestrian safety ordinances in California and New York, fragmenting compliance architecture investments.
Strategic Opportunities
- Aftermarket Retrofit Channels:Fleet operators in Brazil and India face regulatory pressure to upgrade existing vehicle populations without full platform replacement, creating demand for add-on camera-braking kits.
- Vulnerable Road User VRU Insurance Incentives:European insurers are introducing premium reductions for vehicles equipped with pedestrian detection systems, accelerating consumer pull in Germany and France.
- Edge Computing Convergence:Integration of pedestrian detection algorithms with onboard vehicle operating systems enables over-the-air calibration updates, reducing recall costs and extending software monetization windows.
Industry Challenges
- Functional Safety Engineer Scarcity:ISO 26262 certification expertise remains concentrated among semiconductor suppliers and legacy automotive electronics divisions, constraining development velocity for new market entrants.
- Sensor Degradation in Adverse Weather:Camera-based systems experience material performance degradation in heavy precipitation and low-illumination conditions, requiring redundant radar architectures that elevate bill-of-materials costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pedestrian Protection System Market |
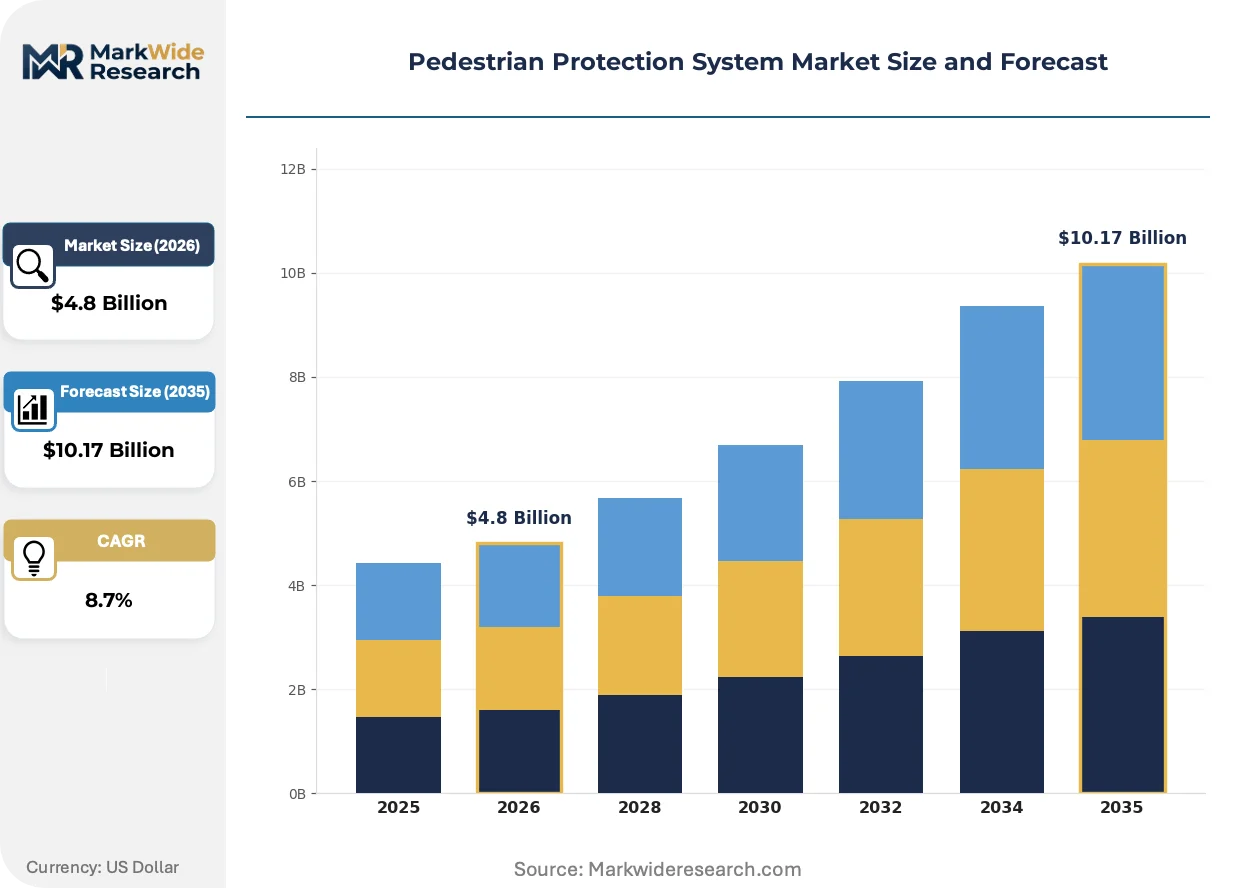
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airbags, Sensors, Autonomous Braking, Pedestrian Detection Systems Technology: Radar Technology, Lidar Technology, Camera-Based Systems, Ultrasonic Sensors End User: OEMs, Aftermarket Providers, Fleet Managers, Vehicle Manufacturers Deployment: On-Road Vehicles, Urban Mobility Solutions, Commercial Vehicles, Two-Wheelers |
| Companies Covered | Robert Bosch, Continental, Denso Corporation, ZF Friedrichshafen, Valeo, Aptiv, Autoliv, Hitachi Astemo, Aumovio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pedestrian Protection System Market Evolving Landscape
Artificial intelligence inference at the edge is restructuring how pedestrian detection algorithms process sensor inputs, shifting computational load from centralized domain controllers to distributed perception modules.
Deep learning-based object classification is digitizing the signal processing pipeline within camera modules, enabling real-time trajectory prediction without dedicated GPU hardware. Mid-market OEMs in South Korea and Spain are adopting these compressed neural network architectures to avoid premium chip sourcing. The technology is digitizing cost structures by eliminating discrete image signal processors and reducing wiring harness complexity.
The European Union's General Safety Regulation mandates automatic emergency braking with pedestrian and cyclist detection on all new vehicle types from mid-decade, with full fleet coverage following shortly thereafter. This regulatory architecture is compelling powertrain and chassis suppliers to integrate braking system actuators with perception software stacks rather than treating them as separable procurement categories. Light commercial vehicle segments face the steepest compliance cost increases due to historically minimal ADAS penetration.
Fleet procurement departments are consolidating supplier relationships around full-stack pedestrian protection system providers capable of assuming liability for functional safety performance. Long-term service agreements with guaranteed uptime metrics are displacing discrete component purchasing in municipal transit and last-mile delivery segments. This consolidation is most visible in Germany, where regional transit authorities have issued unified tenders bundling hardware, software, and maintenance across multi-year contracts.
Pedestrian Protection System Market Segmentation
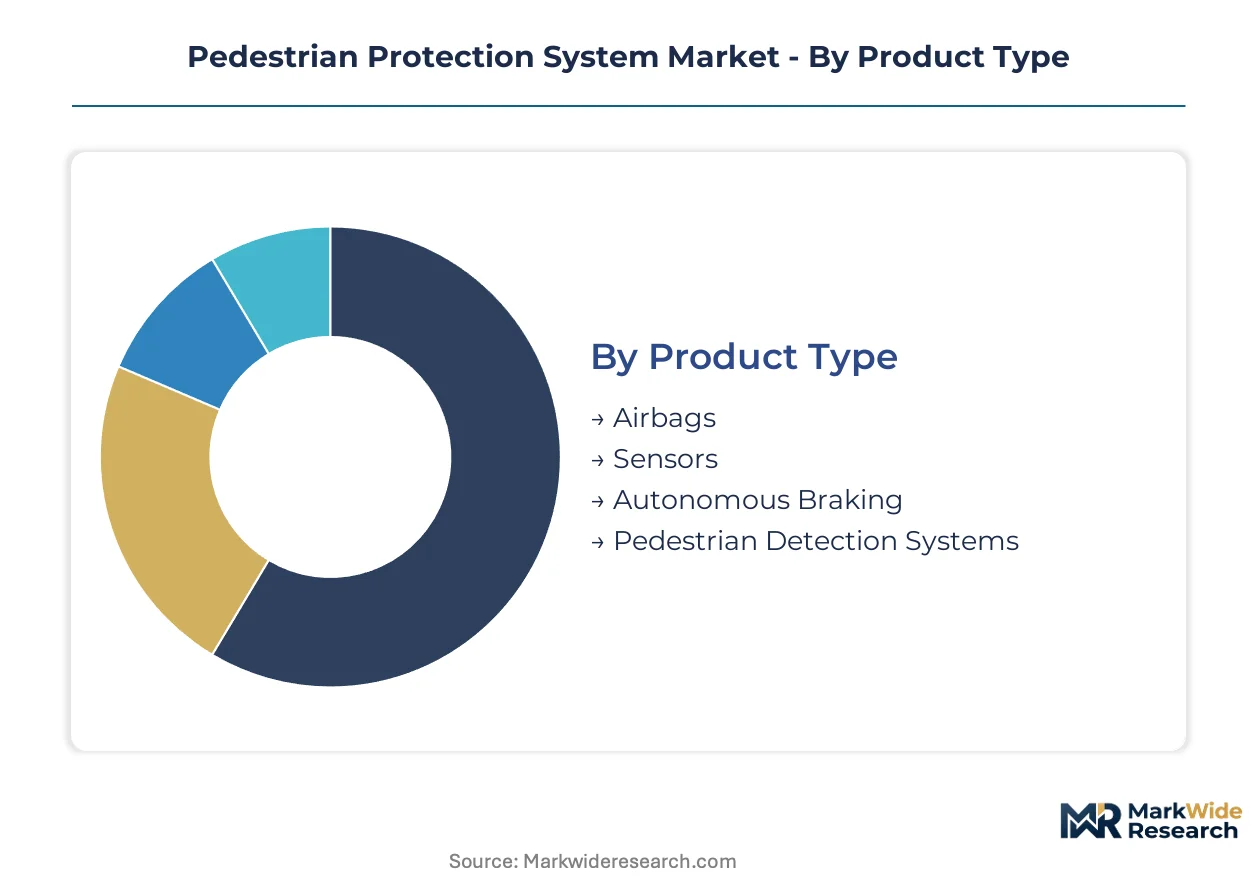
Segmentation reveals how procurement priorities diverge across vehicle classes and technology readiness levels. OEMs structure supplier contracts around sensor modality and deployment environment, creating distinct margin profiles within each category.
Product Type:
After-sales calibration and recertification requirements vary dramatically by product category, with active safety modules demanding continuous software maintenance while passive systems require physical inspection protocols.
- Autonomous Braking:Embedded control units integrate radar-camera fusion with hydraulic actuators to execute emergency deceleration without driver input. German and Japanese OEMs concentrate procurement here due to Euro NCAP scoring weight and domestic homologation mandates. The category captures the deepest software value pools through over-the-air update architectures.
- Sensors:Electromagnetic and optical detection hardware forms the perception layer for all active systems. Demand clusters in radar and camera modules where Bosch and Continental maintain manufacturing scale, though margin compression is accelerating as Chinese suppliers enter automotive-grade production.
- Pedestrian Detection Systems:Algorithm-driven classification software processes sensor inputs to distinguish human movement from static objects. Integration complexity drives Tier 1 licensing revenue models.
- Airbags:Deployable exterior cushions and active hood lifters mitigate impact severity through pyrotechnic or mechanical actuation. Autoliv extends occupant safety heritage into this category with pop-up hood mechanisms.
Autonomous braking holds the largest share; momentum sits with pedestrian detection systems as AI inference migrates to edge modules.
Technology:
Component cost tiers stratify sharply by semiconductor content and automotive qualification requirements, with solid-state lidar commanding premium positioning against mature radar architectures.
- Camera-Based Systems:Optical sensors with embedded neural network processors enable real-time object classification without centralized GPU dependency. South Korean and Spanish OEMs adopt compressed architectures to bypass premium chip sourcing constraints.
- Radar Technology:Frequency-modulated continuous-wave sensors provide all-weather detection with established automotive supply chains. Manufacturing scale concentrates in German and US Tier 1 facilities.
- Lidar Technology:Solid-state optical ranging units achieve automotive-grade cost curves through semiconductor integration. Expanding most quickly as price points penetrate mass-market segments.
- Ultrasonic Sensors:Short-range acoustic detection supports low-speed maneuvering in parking and urban environments. Limited pedestrian-specific deployment due to range constraints.
Camera-based systems dominate current installations; lidar technology is climbing the fastest as solid-state designs achieve volume manufacturing.
End User:
Procurement authority patterns diverge between integrated vehicle manufacturing and retrofit fleet operations, with liability structures shaping contract terms.
- OEMs:Original equipment manufacturers specify full-stack pedestrian protection systems during platform development, bundling hardware, software, and functional safety certification. German regional transit authorities issue multi-year unified tenders with guaranteed uptime metrics.
- Fleet Managers:Municipal and commercial operators face regulatory pressure to upgrade existing vehicle populations without platform replacement. Brazilian and Indian operators drive demand for add-on camera-braking kits.
- Vehicle Manufacturers:Light commercial vehicle producers face steepest compliance cost increases due to historically minimal ADAS penetration.
- Aftermarket Providers:Independent installers serve regulatory retrofit mandates for vehicles outside OEM warranty coverage.
OEMs command the largest procurement volume; fleet managers are gaining share fastest as municipal Vision Zero commitments expand retrofit obligations.
Deployment:
Operating environment dictates sensor redundancy requirements and calibration protocols, with urban density correlating directly to system complexity.
- On-Road Vehicles:Passenger cars and light trucks integrate multi-sensor fusion for highway and urban operation. NHTSA mandates automatic emergency braking with pedestrian detection for this segment under Federal Motor Vehicle Safety Standards.
- Urban Mobility Solutions:Shared transit and micro-mobility platforms require specialized detection for mixed-traffic environments. European insurers introduce premium reductions for equipped vehicles in Germany and France.
- Commercial Vehicles:Heavy-duty trucks and delivery vans face emerging state-level pedestrian safety ordinances in California and New York.
- Two-Wheelers:Motorcycles and scooters present unique packaging constraints for sensor integration.
On-road vehicles represent the largest installed base; urban mobility solutions show the steepest expansion trajectory as shared fleet electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, Japan, and the United States deploy pedestrian protection systems through diverging procurement models: German OEMs bundle full-stack solutions, Japanese suppliers emphasize sensor fusion integration, and U.S. fleet operators face fragmented state-level mandates driving retrofit demand.
United States
Municipal Vision Zero commitments in New York City and Los Angeles are compelling transit authorities to retrofit existing bus and delivery fleets with camera-based detection modules. NHTSA mandates automatic emergency braking with pedestrian detection under Federal Motor Vehicle Safety Standard 127, tightening compliance timelines for light vehicle manufacturers. Detroit's automotive corridor concentrates Tier 1 supplier engineering centers where Bosch and Continental maintain development partnerships with domestic OEMs.
Germany
Euro NCAP assessment protocols assign direct scoring weight to vulnerable road user protection, forcing vehicle manufacturers to procure active hood lifters and autonomous braking modules for five-star ratings. The EU General Safety Regulation mandates automatic emergency braking with pedestrian and cyclist detection on all new vehicle types from July 2024. Bavaria's automotive cluster around Munich and Ingolstadt hosts Continental's sensor fusion development centers and BMW's procurement headquarters for pedestrian safety systems.
Japan
Domestic homologation requirements under Japan's Ministry of Land, Infrastructure, Transport and Tourism accelerate integration of pedestrian-aware detection in kei car and compact vehicle segments. METI funding programs support solid-state lidar development for mass-market cost curves. Toyota City and Nagoya's Chubu region concentrate Denso Corporation and Hitachi Astemo manufacturing facilities for radar-camera fusion modules bound for domestic and export markets.
China
GB standards for pedestrian protection under MIIT oversight are tightening structural requirements for hood deformation and lower leg impact, complementing active safety mandates in major metropolitan jurisdictions. Local suppliers are achieving automotive-grade production scale in camera modules, compressing margins for incumbent radar manufacturers. Shanghai's Yangtze River Delta cluster concentrates domestic Tier 1 development of compressed neural network architectures for edge inference in pedestrian detection.
South Korea
Mid-market OEMs in Seoul and Gyeonggi Province are adopting compressed AI architectures to bypass premium semiconductor sourcing constraints, digitizing signal processing within camera modules rather than relying on centralized domain controllers. The Korea Transportation Safety Authority's testing protocols align with Euro NCAP vulnerable road user benchmarks, driving procurement of multi-sensor fusion systems. Hyundai Motor Group's Uiwang and Namyang R&D centers coordinate pedestrian protection system specification across Kia and Genesis brand portfolios.
Pedestrian Protection System Market Competitive Landscape
Capability concentration sits with sensor fusion specialists possessing ISO 26262 functional safety certification; scale advantage sits with diversified automotive electronics manufacturers leveraging semiconductor procurement relationships. The market structures around three archetypes: full-stack system integrators bundling hardware-software-maintenance contracts, component specialists focusing on discrete sensor or actuator manufacturing, and algorithm licensors monetizing pedestrian detection software stacks. Dominant competitive moves include strategic partnerships between Tier 1 suppliers and solid-state lidar developers, plus geographic expansion into Brazilian and Indian aftermarket retrofit channels.
Within the full-stack integration tier, Robert Bosch and Continental exemplify diverging strategic positions: the Stuttgart-based GmbH anchors manufacturing scale in semiconductor-dependent perception modules, while the Hanover-based supplier leverages radar-camera fusion expertise across European OEM development partnerships. Autoliv occupies a distinct archetype as a specialist extending occupant safety heritage into active hood lifters and deployable exterior protection systems.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental |
| Denso Corporation |
| ZF Friedrichshafen |
| Valeo |
| Aptiv |
| Autoliv |
| Hitachi Astemo |
| Aumovio |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Taiwan-based foundry capacity for ADAS perception chips compresses margin structures across both premium and economy tiers while forcing Tier 1 suppliers to dual-source at elevated qualification costs. This concentration dynamic simultaneously widens pricing spreads between ISO 26262-certified modules and uncertified alternatives while reshaping procurement geography toward Southeast Asian assembly nodes.
Pricing Analysis
Long-term offtake agreements dominate procurement between European OEMs and Tier 1 suppliers, locking in volume commitments for autonomous braking modules over multi-year horizons. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales software maintenance bundling. Cost compression in camera-based detection tiers is intensifying because Chinese suppliers are achieving automotive-grade production scale. Fleet managers in Brazil and India exhibit the highest price sensitivity, while German OEMs absorb premium positioning for Euro NCAP compliance.
Supply Chain Analysis
Upstream feedstock for solid-state lidar units draws from gallium arsenide substrate suppliers concentrated in Taiwan, Japan, and the United States. Radar transceiver modules rest on silicon germanium wafers and specialized RF substrates sourced from German and South Korean semiconductor fabricators. Single-source vulnerability in automotive-grade image sensors exposes perception module manufacturers to allocation volatility during foundry capacity constraints. Distribution runs through Tier 1 system integrators bundling hardware, calibration, and functional safety certification before OEM platform integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards scarce ISO 26262 functional safety engineering talent and validated sensor fusion architectures, creating defensive moats for incumbents while constraining new entrant velocity. Procurement consolidation around full-stack providers accelerates as liability for pedestrian detection performance shifts from OEMs to Tier 1 suppliers.
For Market Incumbents: Harden contractual lock-in through multi-year service agreements with guaranteed uptime metrics for municipal transit authorities. Deepen backward integration into semiconductor-dependent perception modules to defend against foundry allocation volatility. Prioritize certification investment in emerging state-level pedestrian safety ordinances to preempt compliance fragmentation costs. For New Entrants and Emerging Players: Aftermarket retrofit channels in Brazil and India represent the most penetrable entry point for add-on camera-braking kits facing regulatory pressure without platform replacement. Compressed neural network architectures enabling edge inference without centralized GPU dependency offer a go-to-market angle for mid-market OEM procurement in South Korea and Spain. For Investors and Strategic Acquirers: NHTSA Federal Motor Vehicle Safety Standard 127 implementation reshapes the acquisition landscape toward Tier 1 suppliers possessing validated autonomous braking integration. Long-term viability centers on software-defined monetization windows through over-the-air calibration updates. Target acquisition archetypes include sensor fusion specialists with ISO 26262 certification and established European OEM development partnerships. The signal to watch is divergence between UN R152 and emerging U.S. state-level ordinances triggering compliance architecture investment spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Standardization | Reduces calibration complexity at OEM assembly plants while compressing development timelines for multi-sensor architectures. |
| Solid-State Lidar Supply Agreement | Secures automotive-grade cost curves for mass-market penetration beyond luxury vehicle segments. |
| Software-Defined Vehicle Investment | Enables over-the-air pedestrian detection algorithm updates extending monetization windows through subscription models. |
| Geographic Manufacturing Footprint Expansion | Locates production in Southeast Asia to mitigate tariff exposure and foundry concentration risk in Taiwan. |
| Functional Safety Certification Partnership | Accelerates ISO 26262 compliance velocity for new market entrants facing engineer scarcity constraints. |
Research Methodology
Initial hypotheses were tested against primary input from Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution managers, and municipal fleet operations leads and refined through secondary validation. Primary fieldwork combined structured interviews with automotive electronics executives and calibration service technicians. Secondary sources included NHTSA Federal Motor Vehicle Safety Standard filings, Euro NCAP assessment protocol documentation, vehicle production databases, and semiconductor foundry capacity disclosures. Bottom-up volume builds across sensor modality and deployment environment were triangulated against top-down OEM procurement spend estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling pedestrian protection system penetration by vehicle class, propulsion architecture, sensor technology mix, OEM tier positioning, and regional regulatory cluster. Segmentation dimensions included product type, technology modality, end-user procurement authority, and deployment environment. CAGRs were derived from regression analysis of historical procurement patterns against regulatory mandate timelines. Industry-specific inputs incorporated Euro NCAP scoring weight evolution and solid-state lidar cost curve trajectories.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, automotive production volumes, or trade policy stringency would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology cost reduction slopes. Cross-checking against vehicle homologation databases and Tier 1 supplier order backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
In-Cabin Monitoring System (ICMS) Market
Automotive Safety and Security Systems
Automotive Airbags Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
Whiplash Protection System Market
Automotive Safety and Security Systems
Start Stop System Market
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Rear Occupant Alert System Market
Automotive Safety and Security Systems
Forward Collision Warning System for Automotive Market
Automotive Safety and Security Systems
Driver Attention Alert Systems Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Automotive Start-Stop System Market
Automotive Safety and Security Systems
Global Automotive Anti Pinch Window Market
Automotive Safety and Security Systems
Automotive Night Vision Sensors Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market