
 Czech Republic Third-Party Logistics Market | 2026-2036
Czech Republic Third-Party Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Czech Republic Third-Party Logistics Market Outlook
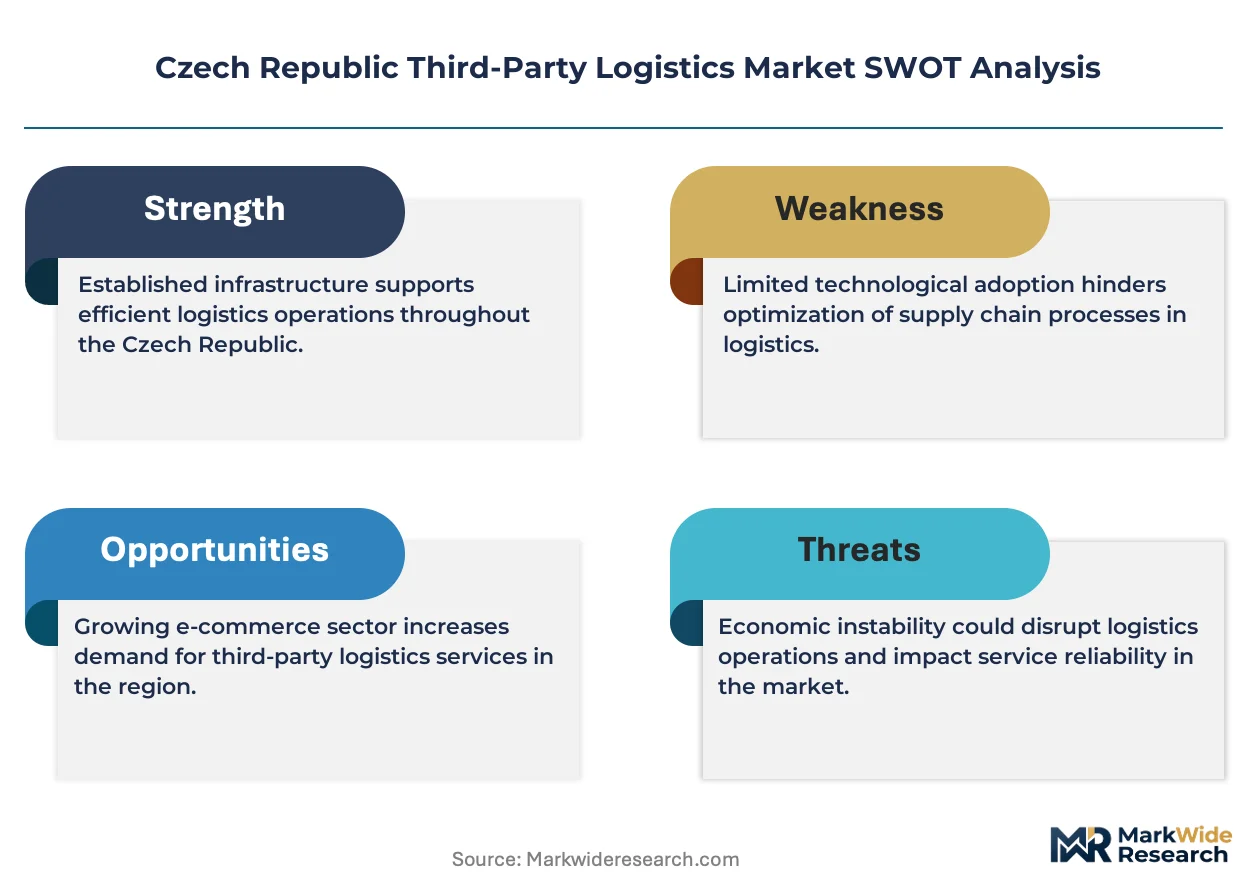
The gap between premium integrated logistics and commodity transport-only services is broadening as Czech shippers demand real-time visibility and carbon-accounted supply chains. DSV Solutions leverages its European network density to anchor high-value contract logistics in the automotive sector. Česká pošta competes through last-mile dominance across secondary cities, while GEFCO specializes in finished-vehicle logistics serving assembly plants along the Polish and Slovak borders.
Third-party logistics encompasses the outsourcing of supply chain execution—transportation, warehousing, inventory control, and customs clearance—to specialized operators who assume operational responsibility under service-level agreements. Temperature-controlled cross-docking, bonded warehousing, and just-in-time sequencing constitute core technical capabilities that manufacturers deploy to reduce working capital and inventory carrying costs. Roadways and intermodal transport command the distribution channel landscape due to the Czech Republic's central European location and dense motorway links to Germany, Poland, and Austria. Warehouse Management Systems and Transportation Management Systems represent the fastest-adopting technology segments as operators replace legacy ERP modules with cloud-native platforms that integrate carrier APIs and customs portals.
Czech logistics operators must comply with EU Green Deal emission targets, CE marking for handling equipment, and national road freight regulations enforced by the country's transport authority. The EU AI Act will soon classify automated warehouse robotics and route-optimization algorithms, creating compliance obligations for technology-deploying 3PLs. Stakeholders should monitor how forthcoming EU carbon border adjustments reshape cross-border freight economics and whether Czech operators accelerate fleet electrification ahead of regulatory deadlines.
Market Dynamics
EU Green Deal emissions mandates are compressing fleet replacement cycles and forcing warehouse energy retrofits across Czech automotive and e-commerce logistics clusters.
Growth Catalysts
- Cross-border e-commerce corridors:Prague's position at the intersection of German, Polish, and Austrian motorway networks draws fulfillment center investment from pan-European retailers seeking single-day delivery radii.
- EU Green Deal fleet standards:Tighter CO2 caps for heavy-duty vehicles accelerate outsourced logistics adoption as manufacturers seek operators with capital to electrify before 2030 deadlines.
- Automotive just-in-time sequencing:Assembly plants along the Polish and Slovak borders demand synchronized inbound parts flows that specialized 3PLs can orchestrate better than captive fleets.
Market Restraints
- Driver labor scarcity:Czech road freight faces acute shortages of qualified HGV operators as neighboring German and Austrian carriers bid up wages for cross-border haulage.
- Intermodal terminal congestion:Container-handling capacity at Lovosice and Ostrava intermodal hubs limits rail-sea alternatives to road freight for Asia-Europe cargo.
- Warehouse construction cost inflation:Steel and insulation material prices have doubled automation-project payback periods for speculative logistics park developers.
Strategic Opportunities
- Secondary city last-mile networks:Brno, Plzeň, and Olomouc remain underserved by temperature-controlled parcel consolidation compared to Greater Prague saturation.
- EU carbon border adjustment preparedness:Czech 3PLs can position as compliance partners for exporters needing embedded-emissions documentation for CBAM-covered goods.
- Battery-electric fleet leasing:The convergence of vehicle-as-a-service financing and charging infrastructure buildout creates asset-light electrification paths for mid-sized operators.
Industry Challenges
- Warehouse automation technician shortage:Czech vocational pipelines produce insufficient mechatronics specialists to maintain robotic picking systems at required uptime levels.
- Legacy WMS integration friction:Cloud-native transportation platforms struggle to synchronize with on-premise ERP systems still common among Czech manufacturing SMEs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Czech Republic Third-Party Logistics Market |
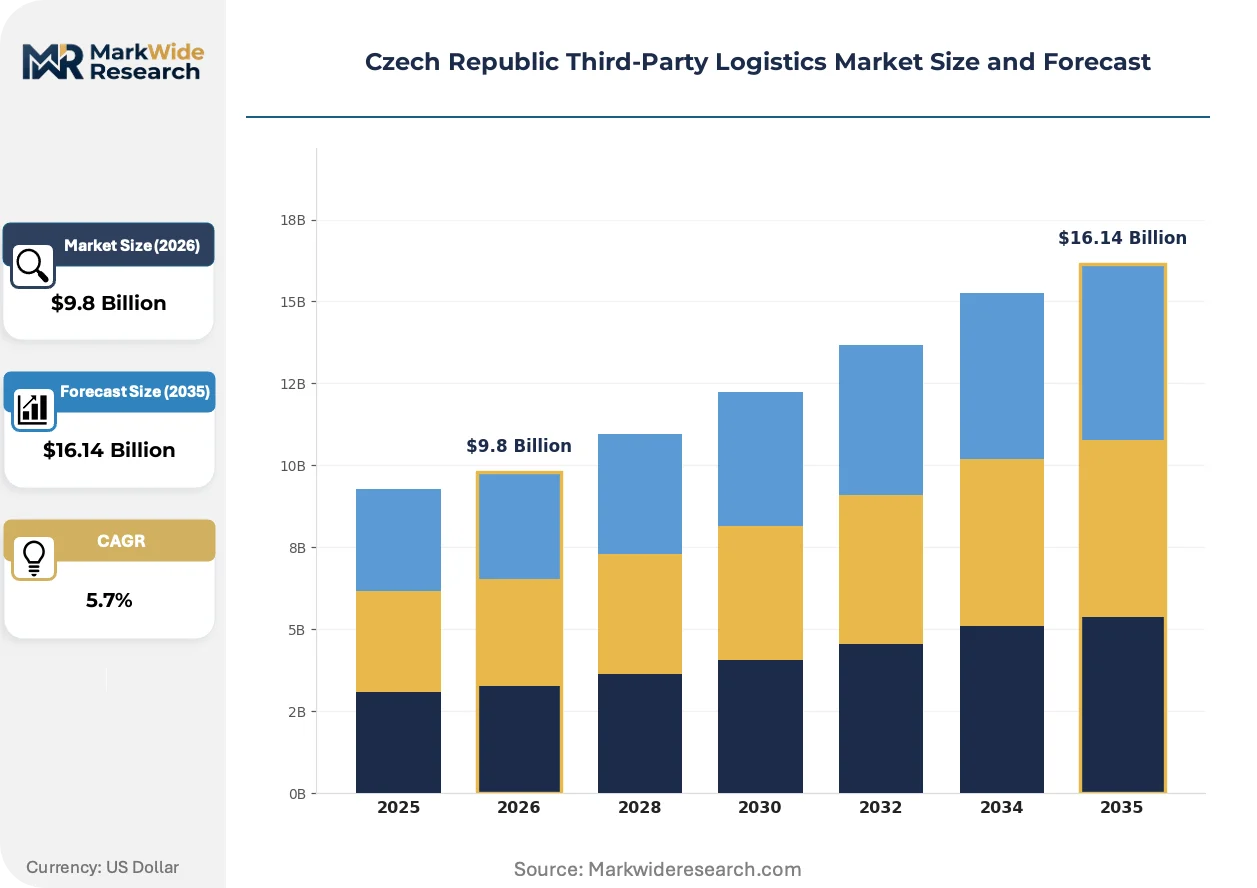
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage, Inventory Management Customer Type: Manufacturers, Wholesalers, E-commerce Businesses, Distributors, Retailers Technology: Warehouse Management System, Transportation Management System, GPS Tracking, Robotics, Automated Storage Distribution Channel: Roadways, Railways, Air Freight, Sea Freight, Intermodal Transport |
| Companies Covered | Hellmann Worldwide Logistics, DSV Solutions, DB Schenker, Agility Logistics, Ceva Logistics, Kuehne + Nagel, Dachser Czech Republic, Česká pošta, GEFCO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Czech Republic Third-Party Logistics Market Strategic Shifts
Digital freight matching and automated yard management are compressing asset utilization gaps between integrated operators and fragmented trucking fleets.
Cloud-native Transportation Management Systems is modularizing how mid-sized Czech carriers access carrier APIs, customs portals, and real-time visibility layers without multi-year IT capital commitments. Regional freight aggregators serving the automotive sector are adopting these platforms fastest. The shift is compressing the technology gap between national integrators and asset-light brokers.
The EU AI Act classification of automated warehouse robotics and route-optimization algorithms creates compliance obligations for technology-deploying 3PLs. Czech operators must document risk management systems for AI-driven picking and sequencing decisions. Automotive contract logistics providers near Ostrava are establishing algorithmic audit trails ahead of enforcement timelines.
Shippers now unbundle freight procurement from warehousing contracts, compressing switching cycles and forcing 3PLs to prove standalone value in each service line. Czech manufacturers previously locked into integrated packages now tender transport and storage separately. This pattern concentrates in the Greater Prague metropolitan area where e-commerce fulfillment alternatives are densest.
Czech Republic Third-Party Logistics Market Segmentation
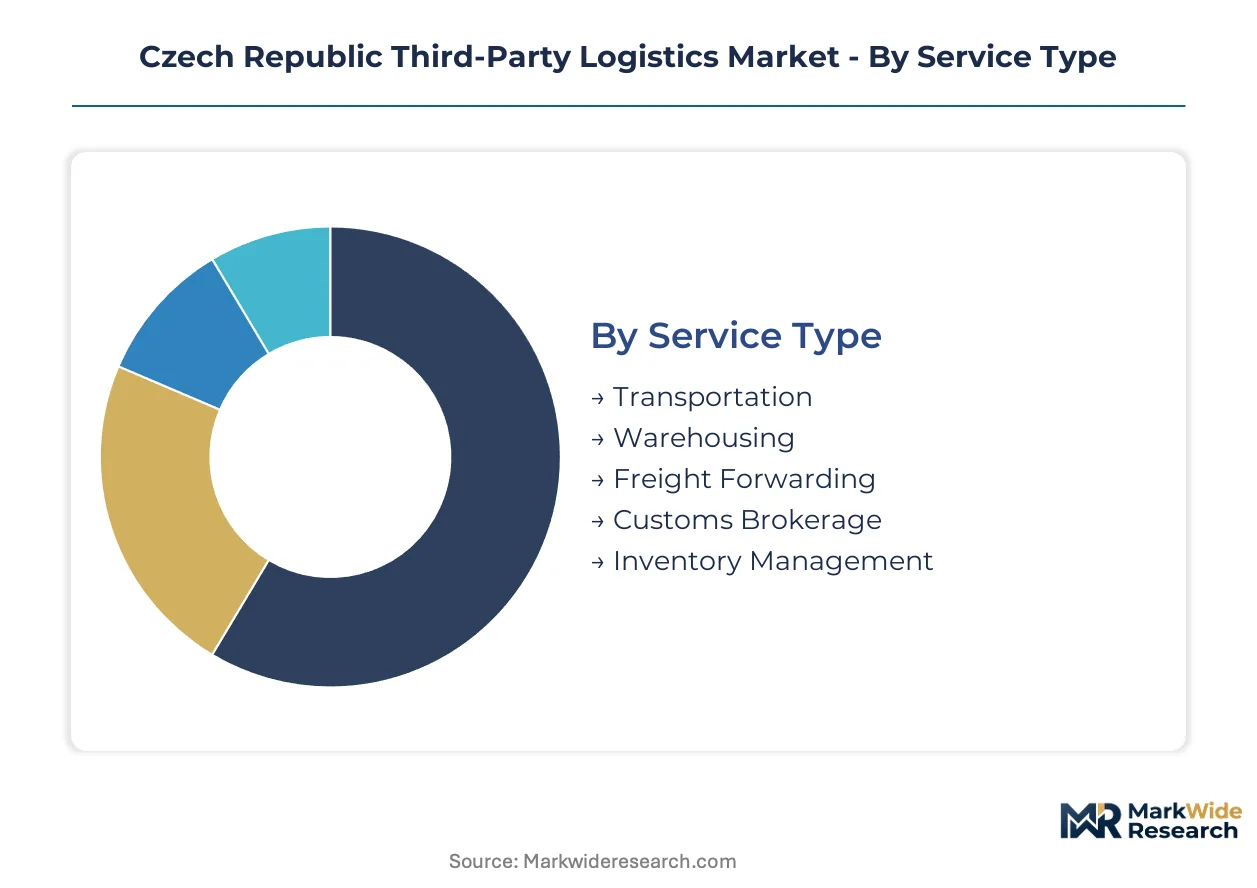
Segmentation reveals how Czech logistics operators allocate capital across service lines and infrastructure modes. Shippers select providers based on whether they need integrated execution or standalone functions, with technology readiness now filtering contract awards.
Service Type:
Replacement cycles for legacy service contracts are accelerating as Czech manufacturers unbundle bundled offerings and demand standalone excellence in each function.
- Transportation:Road-based freight execution dominates contract value, with fleet electrification investments concentrated in automotive corridors serving Ostrava-Karviná assembly plants. Tighter EU Green Deal CO2 caps for heavy-duty vehicles are compressing replacement timelines for diesel assets.
- Warehousing:Temperature-controlled and bonded storage facilities anchor contract logistics in Greater Prague, where e-commerce fulfillment centers require rapid inventory turns and cross-border customs deferment. Energy retrofit costs for existing stock are reshaping developer returns.
- Freight Forwarding:Pan-European coordination of multi-modal movements, particularly Asia-Europe rail-sea combinations through Lovosice terminal.
- Customs Brokerage:Documentation and duty management for EU carbon border adjustment compliance, especially for steel and aluminum exporters.
- Inventory Management:Vendor-managed stock programs reducing working capital for automotive just-in-time sequencing operations.
Transportation sits at the top of the volume ranking, with Warehousing climbing the fastest as fulfillment center demand outstocks traditional storage.
Customer Type:
Margin profiles diverge sharply across buyer categories, with capital intensity and contract duration varying by sector concentration.
- Manufacturers:Automotive and electronics producers drive demand for synchronized inbound logistics, with Czech assembly plants along Polish and Slovak borders requiring precise sequencing. EU Green Deal compliance costs are pushing these buyers toward outsourced fleet operators with electrification capital.
- E-commerce Businesses:Pan-European retailers anchor fulfillment center investment in Greater Prague, seeking single-day delivery radii into Germany, Poland, and Austria. Last-mile density requirements separate viable providers from commodity truckers.
- Wholesalers:Consolidated distribution of fast-moving consumer goods through secondary city networks in Brno and Plzeň.
- Distributors:Specialty chemical and pharmaceutical intermediaries requiring temperature-controlled cross-docking.
- Retailers:Omnichannel replenishment combining store delivery with click-and-collect node operations.
Manufacturers command the largest contract values, while E-commerce Businesses are expanding their share of provider revenue most rapidly.
Technology:
Adoption maturity separates integrated operators from fragmented competitors, with cloud-native platforms now table stakes for automotive contract awards.
- Warehouse Management System:Cloud-native platforms replacing legacy ERP modules, with real-time inventory visibility and robotic integration becoming standard in Greater Prague fulfillment centers. The EU AI Act will soon classify automated decision systems, creating compliance documentation burdens.
- Transportation Management System:Modular access to carrier APIs and customs portals compresses technology gaps between national integrators and mid-sized carriers. Czech automotive freight aggregators are adopting these systems fastest.
- GPS Tracking:Real-time shipment visibility for cross-border road corridors into Germany and Austria.
- Robotics:Automated picking systems in temperature-controlled facilities, constrained by mechatronics technician shortages in Czech vocational pipelines.
- Automated Storage:High-density retrieval systems for e-commerce SKU proliferation in land-constrained Prague logistics parks.
Warehouse Management System leads technology spending, with Transportation Management System gaining adoption momentum among mid-tier carriers.
Distribution Channel:
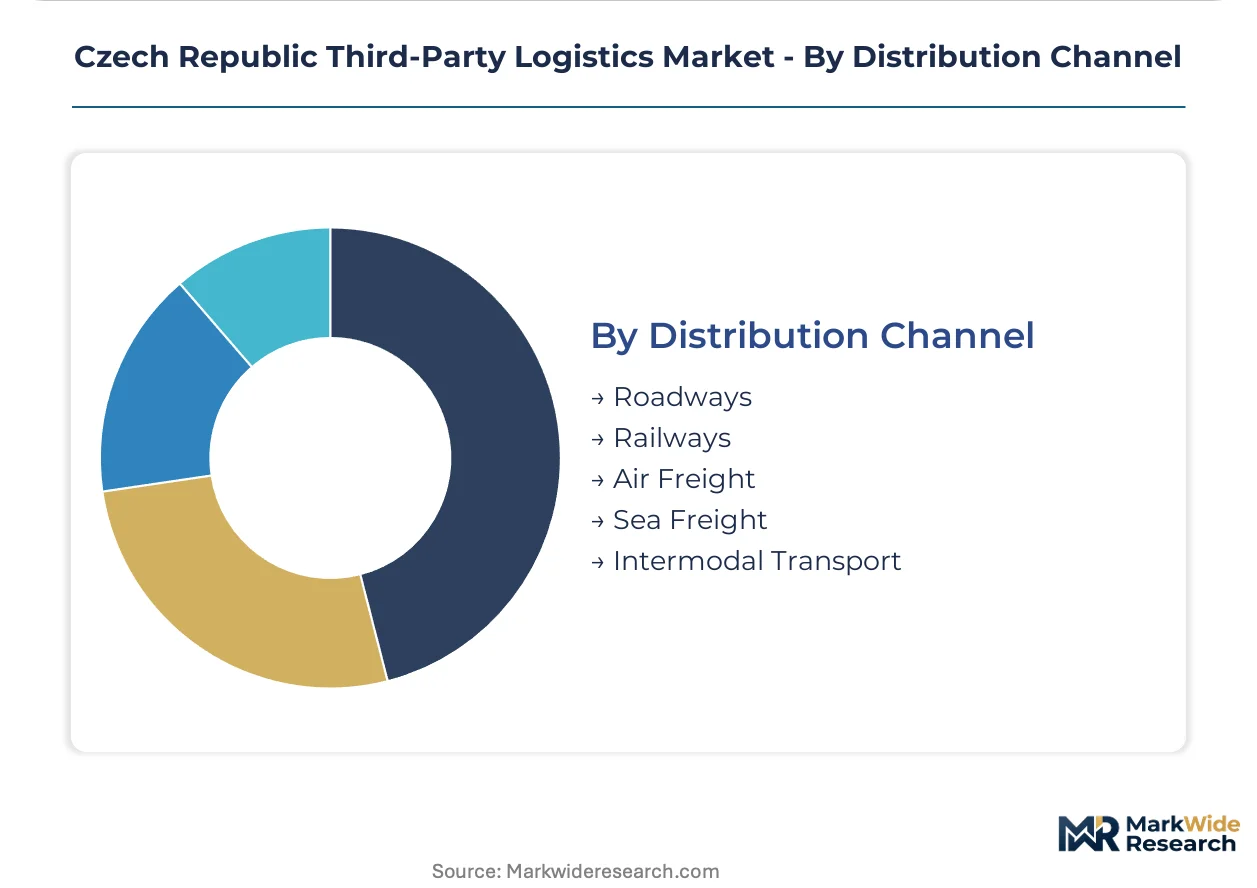
Channel selection reflects the Czech Republic's central European geography and the density of motorway links to neighboring economies.
- Roadways:Dominant mode for time-sensitive automotive parts and e-commerce parcels, with the D1 and D8 motorways forming critical corridors to Germany and Poland. Driver labor scarcity is constraining capacity expansion.
- Intermodal Transport:Rail-sea combinations through Lovosice and Ostrava terminals offer Asia-Europe alternatives to pure road freight, though container-handling bottlenecks limit volume growth.
- Railways:Bulk commodity movements and automotive finished-vehicle transport on dedicated wagon fleets.
- Air Freight:High-value electronics and pharmaceutical shipments through Prague Václav Havel Airport.
- Sea Freight:Limited to container feeder connections via Hamburg and Rotterdam for Czech importers.
Roadways maintain the highest throughput volume, while Intermodal Transport is expanding its modal share as terminal capacity investments proceed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled logistics workforce concentrations in Greater Prague and the Ostrava-Karviná corridor anchor the Czech Republic's third-party logistics capacity. These talent pools support specialized automotive sequencing and e-commerce fulfillment operations that demand precision inventory control.
Greater Prague Metropolitan Area
E-commerce fulfillment centers and cross-border road corridors intersect here, drawing pan-European retailer investment for single-day delivery radii into Germany, Poland, and Austria. EU Green Deal emissions rules tighten warehouse energy standards across speculative logistics parks. Temperature-controlled bonded warehousing clusters in Prague's eastern industrial zones serve pharmaceutical and electronics exporters.
Ostrava-Karviná Industrial Cluster
Automotive manufacturers expand outsourced logistics operations as assembly plants along Polish and Slovak borders demand synchronized inbound parts flows. The EU AI Act classification of automated warehouse robotics creates compliance documentation burdens for technology-deploying 3PLs. Finished-vehicle logistics specialists operate dedicated wagon fleets and sequencing yards serving Škoda Auto supplier networks.
Brno
Secondary city last-mile networks remain underserved by temperature-controlled parcel consolidation compared to Greater Prague saturation. National road freight regulations enforced by the country's transport authority govern cross-border haulage licensing. Engineering talent from Brno University of Technology feeds warehouse automation technician pipelines for robotic picking system maintenance.
Plzeň
Consolidated distribution of fast-moving consumer goods through this western hub connects to German motorway corridors. CE marking requirements for handling equipment shape warehouse retrofit investment decisions. Chemical and pharmaceutical intermediaries requiring temperature-controlled cross-docking concentrate near the German border for REACH compliance proximity.
Lovosice Intermodal Terminal Zone
Rail-sea combinations through this northern hub offer Asia-Europe alternatives to pure road freight. Container-handling bottlenecks limit volume growth despite terminal capacity investments. Bonded warehousing and customs deferment facilities support steel and aluminum exporters preparing for EU carbon border adjustment documentation requirements.
Czech Republic Third-Party Logistics Market Competitive Environment
Capital-heavy fleet operators compete with asset-light freight brokers for contract awards across Czech automotive and e-commerce corridors. The market structure tilts toward integrated European networks that can bundle transportation, warehousing, and customs brokerage under single service-level agreements. Three archetypes dominate: pan-European integrators with dense network coverage, national postal operators with last-mile density, and specialized automotive logistics providers with finished-vehicle expertise. Competitive moves concentrate on fleet electrification partnerships and cloud-native platform deployment to compress technology gaps.
Among integrated operators, DSV Solutions and Hellmann Worldwide Logistics exemplify the network-density archetype, while Česká pošta occupies a distinct position rooted in secondary city last-mile coverage. GEFCO represents the specialized tier, anchoring finished-vehicle logistics capabilities near border assembly plants. These operators illustrate how service unbundling pressures providers to prove standalone value in each function rather than relying on bundled contract lock-in.
| Leading Market Players |
|---|
| Hellmann Worldwide Logistics |
| DSV Solutions |
| DB Schenker |
| Agility Logistics |
| Ceva Logistics |
| Kuehne + Nagel |
| Dachser Czech Republic |
| Česká pošta |
| GEFCO |
| Others |
Value Chain & Pricing Dynamics
Driver wage inflation across Czech-German border corridors feeds directly into three-tier pricing structure across premium, standard, and economy levels, with integrated operators commanding premium spreads for electrified fleet guarantees while commodity truckers absorb margin compression in spot markets.
Pricing Analysis
Bundled service contracts are fragmenting into standalone transport and warehousing tenders, compressing switching costs and intensifying price transparency. Price differentiation rests on real-time visibility layers and carbon-accounted supply chain documentation under EU Green Deal compliance. Pricing pressure stems from shippers unbundling procurement and demanding standalone excellence in each function. E-commerce businesses show highest price sensitivity to last-mile density guarantees, while automotive manufacturers prioritize sequencing reliability over transport rates.
Supply Chain Analysis
Regional distribution centers cluster in Greater Prague and Ostrava-Karviná, forming hub-and-spoke patterns that feed secondary city spokes in Brno and Plzeň. The network draws steel and insulation materials from Germany and Poland, warehouse automation components from China and Germany, and HGV chassis from Czech and Slovak assembly plants. Single-source vulnerability concentrates in mechatronics technician pipelines from Brno University of Technology. Distribution runs through bonded warehousing nodes at Lovosice terminal for Asia-Europe rail-sea combinations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Czech third-party logistics has entered a late-cycle quality phase where premium specifications around real-time visibility and EU Green Deal compliance separate viable operators from commodity truckers facing margin erosion.
For Market Incumbents: Hedge fleet electrification capital commitments through vehicle-as-a-service financing partnerships that transfer residual value risk to lessors. Lock in automotive sequencing contracts with algorithmic audit trails ahead of EU AI Act enforcement timelines. Consolidate secondary city last-mile density through selective acquisition of temperature-controlled parcel networks in Brno and Olomouc before new entrants capture whitespace. For New Entrants and Emerging Players: EU AI Act classification of automated warehouse robotics in the Czech Republic opens a window for compliance-documentation specialists serving Ostrava-Karviná automotive clusters. Target battery-electric fleet leasing as the most penetrable segment, using charging infrastructure buildout partnerships as the go-to-market angle. Secondary city temperature-controlled consolidation in Plzeň offers lower competitive density than Greater Prague saturation. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-sized carriers lack capital for EU Green Deal fleet replacement cycles and cloud-native platform deployment. Long-term viability favors operators with captive automotive sequencing relationships and electrification financing structures already in place. Watch for inflection when EU carbon border adjustment documentation requirements trigger exporter demand for embedded-emissions tracking capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| EU Green Deal Fleet Electrification | Heavy-duty vehicle CO2 caps from the EU Green Deal compress diesel asset replacement timelines for automotive corridor operators. |
| Cloud-Native TMS Deployment | Modular platforms integrating carrier APIs and customs portals compress technology gaps between national integrators and mid-tier carriers. |
| Secondary City Last-Mile Expansion | Temperature-controlled parcel consolidation in Brno and Olomouc addresses underserved demand relative to Greater Prague saturation. |
| EU AI Act Compliance Documentation | Algorithmic audit trails for automated picking and sequencing decisions create defensible positioning ahead of enforcement timelines. |
| Carbon Border Adjustment Partnership | Embedded-emissions documentation services for steel and aluminum exporters leverage Lovosice terminal bonded warehousing infrastructure. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with logistics park developers, fleet operations directors, automotive procurement leads, and customs brokerage specialists with secondary validation against Czech transport authority filings, EU customs databases, Lovosice terminal throughput disclosures, and operator sustainability reports. Bottom-up service line sizing and top-down macroeconomic anchoring were triangulated to constrain estimate variance.
Comparable historical periods anchored the projection horizon to observed fleet replacement cycles and e-commerce fulfillment center investment waves across the analysis window. Segmentation dimensions modeled include service type, customer vertical, technology adoption tier, and distribution channel modality. CAGRs were derived from logistic diffusion curves fitted to electrification capital deployment patterns and cloud platform adoption velocities observed in automotive freight aggregators.
Revisions become necessary when EU carbon border adjustment implementation timelines shift, battery-electric vehicle total cost of ownership curves steepen unexpectedly, or intermodal terminal capacity investments at Lovosice and Ostrava accelerate modal share transitions beyond modeled rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Poland Freight and Logistics Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
Global 3PL Market
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
Global Freight Broker Software Market
Logistics and Shipping
Food Delivery Logistic Market
Logistics and Shipping
ASEAN Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Australia Cold Chain Logistics Market
Logistics and Shipping
Terminal Tractors Market
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
Turkey Courier Express and Parcel (CEP) Market
Logistics and Shipping
Japan E-Commerce Logistics Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
Mexico 3PL Market