
 Automotive Digital Rear View Mirror Market | 2026-2036
Automotive Digital Rear View Mirror Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Digital Rear View Mirror Market Outlook
OEM direct supply contracts for digital mirror modules is tilting toward vertically integrated Tier-1 systems houses. Denso Corporation leverages its captive semiconductor sourcing to control cost positions on LCD driver boards. Continental AG anchors European OEM programs through its mirror-integrated ADAS packaging expertise. Gentex Corporation dominates the North American factory-installed channel with electrochromic-to-digital hybrid architectures.
An automotive digital rear view mirror replaces conventional glass reflectors with camera-fed display surfaces, typically employing CMOS image sensors paired with LCD or OLED panels operating at 60Hz refresh rates to eliminate motion blur during vehicle reversal. The primary commercial purpose is eliminating rear blind spots while enabling augmented overlay of parking guidance and proximity alerts. Integrated Mirror configurations capture the bulk of current OEM revenue as automakers bundle displays with roof-mounted camera modules. OLED technology variants represent the fastest-expanding technology slice due to contrast ratios that preserve night-vision clarity. Aftermarket Providers face margin compression as Factory Installed penetration deepens in premium vehicle segments.
NHTSA Federal Motor Vehicle Safety Standard No. 111 governs rear visibility field-of-view requirements and directly shapes camera placement and display latency specifications for US-bound vehicles. Euro NCAP assessment protocols reward expanded rear vision scores, compelling European OEMs to spec digital mirrors across mid-range trims. Japan's Ministry of Land, Infrastructure, Transport and Tourism permits camera-monitor systems as legal mirror replacements, creating regulatory precedent for Asian harmonization. Stakeholders must monitor divergent homologation timelines across major markets to align product development cycles with certification windows.
Market Dynamics
OEM captive sourcing of CMOS sensors and LCD driver boards is compressing supplier margins while accelerating the displacement of glass mirror architectures in premium vehicle programs.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard No. 111:Updated rear visibility mandates in the United States are compelling automakers to widen camera placement and reduce display latency specifications, directly expanding addressable module volume.
- Euro NCAP assessment protocols:Expanded rear vision scoring rewards are pushing European OEMs to spec digital mirrors across mid-range trims previously limited to electrochromic glass.
- Japan's camera-monitor system legalization:Ministry of Land, Infrastructure, Transport and Tourism precedent permits full mirror replacement, creating regulatory harmonization pressure across Asian markets.
Market Restraints
- Semiconductor input cost volatility:CMOS image sensor and LCD driver IC pricing fluctuation constrains module cost predictability for Tier-1 suppliers negotiating multi-year OEM contracts.
- Supply concentration in East Asian foundries:Display panel fabrication concentrates in South Korea and Taiwan, exposing procurement timelines to single-source geographic risk.
- Power consumption and thermal management:OLED panel heat dissipation requirements limit integration into compact mirror housings without active cooling subsystems.
Strategic Opportunities
- Commercial vehicle penetration:Heavy-duty truck fleets in Germany and Japan represent underpenetrated demand for blind-spot elimination in long-haul configurations.
- ADAS convergence with mirror displays:Parking guidance overlay and proximity alert integration creates bundled value propositions for mid-range passenger vehicles.
- Aftermarket channel digitization:Direct-to-installer platforms and subscription-based firmware update services are emerging as alternatives to traditional parts distribution.
Industry Challenges
- Embedded software talent scarcity:Real-time image processing and low-latency display pipeline engineering skills concentrate at semiconductor vendors, not traditional mirror suppliers.
- Homologation timeline fragmentation:Divergent certification windows across NHTSA, KBA, and Japan's MLIT force parallel development tracks that strain R&D resource allocation.
- Legacy vehicle integration complexity:Retrofit installation of camera-monitor systems requires CAN bus reprogramming and power distribution reconfiguration that most independent workshops cannot execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Digital Rear View Mirror Market |
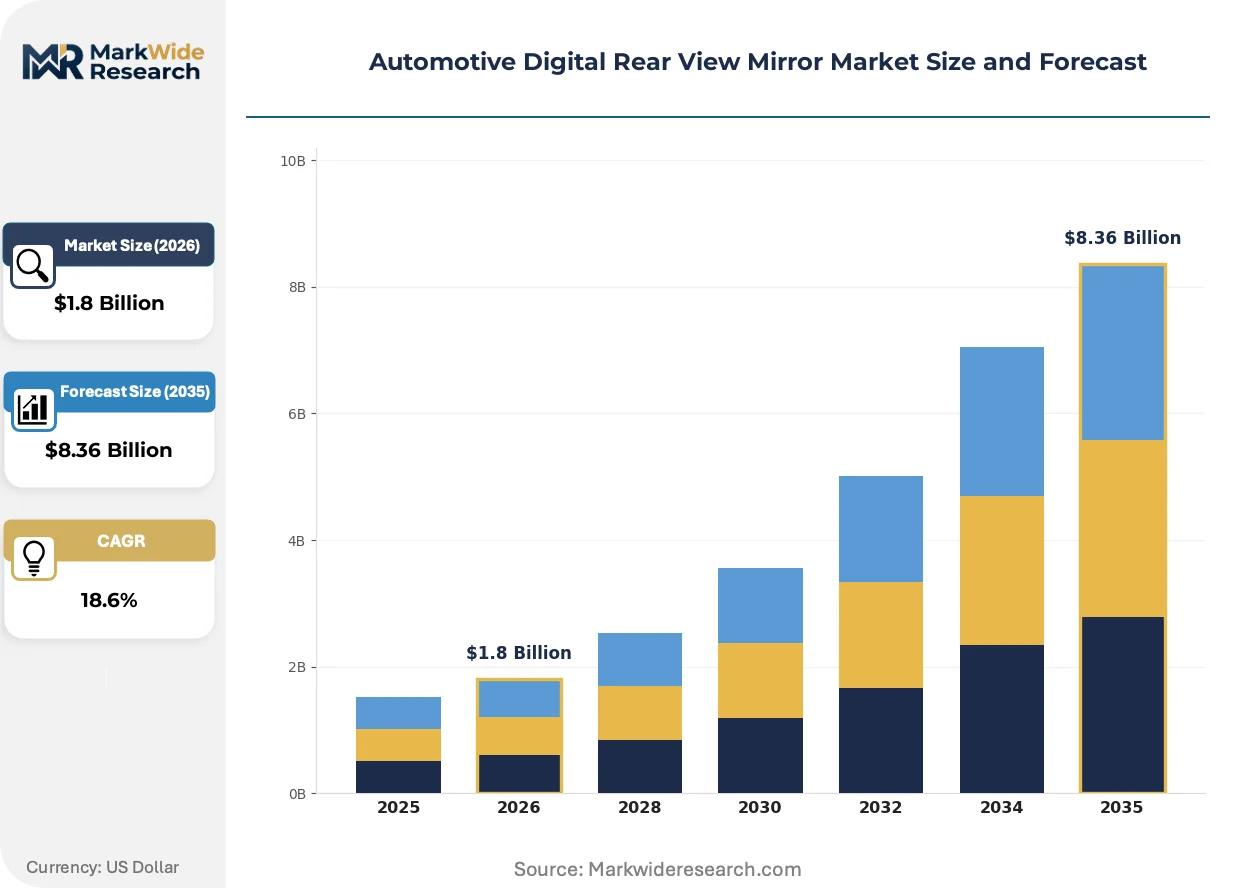
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Mirror, Standalone Mirror, Smart Display, Rear Camera System End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: LCD, OLED, LED, Night Vision Installation: Factory Installed, Aftermarket Installation, Retrofit Solutions, Custom Fit |
| Companies Covered | Denso Corporation, Continental AG, Gentex Corporation, Ficosa International S.A., Magna International Inc., Robert Bosch GmbH, Hyundai Mobis Co. Ltd., Foryou Corporation, Panasonic Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Digital Rear View Mirror Market Strategic Shifts
Display technology maturation and regulatory scorecard redesign are converging to reposition the digital rear view mirror from premium novelty to standard safety equipment.
OLED panel technology is migrating from flagship luxury sedans into mid-range crossovers as unit costs decline and automotive-grade burn-in mitigation improves. BMW and Mercedes-Benz program specifications now demand contrast ratios exceeding one million to one for night-vision clarity. This technology shift is compressing the price-performance gap that previously separated electrochromic glass from full digital replacement.
Japan's camera-monitor system approval under MLIT guidelines established the first G7 regulatory framework permitting complete mirror elimination. European regulators at KBA and France's DGAC are harmonizing type-approval procedures to reduce certification duplication across member states. Heavy-duty commercial vehicle segments in Germany are responding fastest, speculating digital mirrors will satisfy impending blind-spot mandates without the aerodynamic penalty of extended mirror arms.
Fleet procurement departments are consolidating supplier relationships around vertically integrated Tier-1 systems houses capable of delivering mirror-integrated ADAS modules as single-SKU contracts. Traditional glass mirror specialists without semiconductor sourcing capabilities are losing access to OEM RFQ shortlists. This consolidation pattern is most visible in United States premium SUV programs where factory installation rates now exceed ninety percent of trim configurations.
Automotive Digital Rear View Mirror Market Segmentation
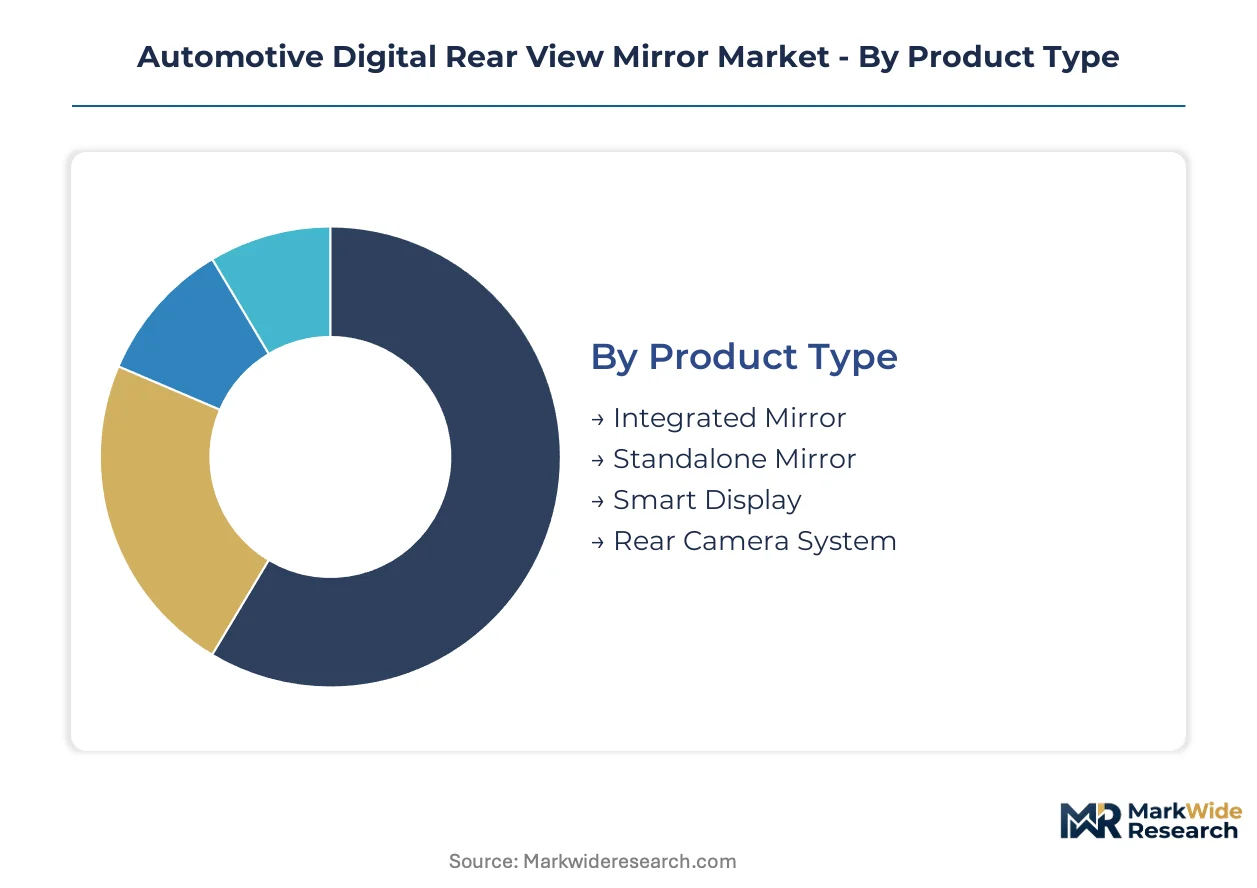
Digital rear view mirror segmentation reveals how procurement authority, display technology maturity, and integration depth determine margin capture across the value chain. Understanding these fault lines exposes where OEM captive sourcing displaces third-party suppliers and which technology transitions command pricing power.
Product Type:
Cost tier stratification separates bundled factory systems from discrete upgrade paths, with integration complexity driving procurement channel selection.
- Integrated Mirror:Combines roof-mounted camera modules with windshield-embedded display surfaces in unified housing architectures. Luxury passenger vehicle programs across Germany, Japan, and the United States concentrate procurement here, driven by NHTSA rear visibility compliance deadlines that favor single-source supplier accountability.
- Standalone Mirror:Self-contained replacement units with internal CMOS sensors and proprietary display panels. Mid-range crossover fleets in European markets rotate toward this configuration as Euro NCAP scoring rewards expand, though margin compression accelerates as OEMs internalize specification control.
- Smart Display:Augmented overlay systems integrating parking guidance and proximity alerts through software-defined interfaces.
- Rear Camera System:Component-level camera modules sold separately from display hardware for custom integration programs.
Integrated Mirror holds installed capacity. Standalone Mirror is rotating up the share rankings.
End User:
Customer type distribution tracks how procurement authority has consolidated around vertically capable systems integrators versus fragmented aftermarket channels.
- OEMs:Direct vehicle manufacturer programs specifying mirror-integrated ADAS modules as standard equipment across trim configurations. German and Japanese OEMs dominate volume allocation, leveraging captive semiconductor sourcing to compress Tier-1 supplier margins on multi-year contracts.
- Aftermarket Providers:Independent distributors and installer networks serving vehicle owners outside factory warranty periods. Channel economics deteriorate as Factory Installed penetration deepens in premium segments, forcing digitization of direct-to-installer platforms.
- Tier-1 Suppliers:Systems houses delivering complete mirror modules to OEM assembly lines under single-SKU contracts.
- Vehicle Assemblers:Contract manufacturing operations integrating subsystems from multiple component sources.
OEMs command specification authority. Tier-1 Suppliers are climbing fastest in contract value.
Technology:
Display maturity curves separate established LCD cost positions from emerging OLED performance premiums in night-vision applications.
- OLED:Organic electroluminescent panels delivering contrast ratios exceeding one million to one for glare-free night operation. BMW and Mercedes-Benz program specifications now mandate this technology across mid-range crossovers as automotive-grade burn-in mitigation improves and unit economics compress the premium versus electrochromic glass.
- LCD:Liquid crystal display panels with 60Hz refresh rates and established supply chains through South Korean and Taiwanese fabrication facilities. Volume concentration persists in entry-luxury segments where cost predictability outweighs contrast performance requirements.
- LED:Edge-lit or direct-backlit configurations for supplementary illumination and status indication.
- Night Vision:Infrared-augmented imaging systems for low-light pedestrian and obstacle detection.
LCD holds installed capacity. OLED is expanding most quickly in specification share.
Installation:
Application timing determines regulatory compliance burden and technical integration complexity across vehicle lifecycle stages.
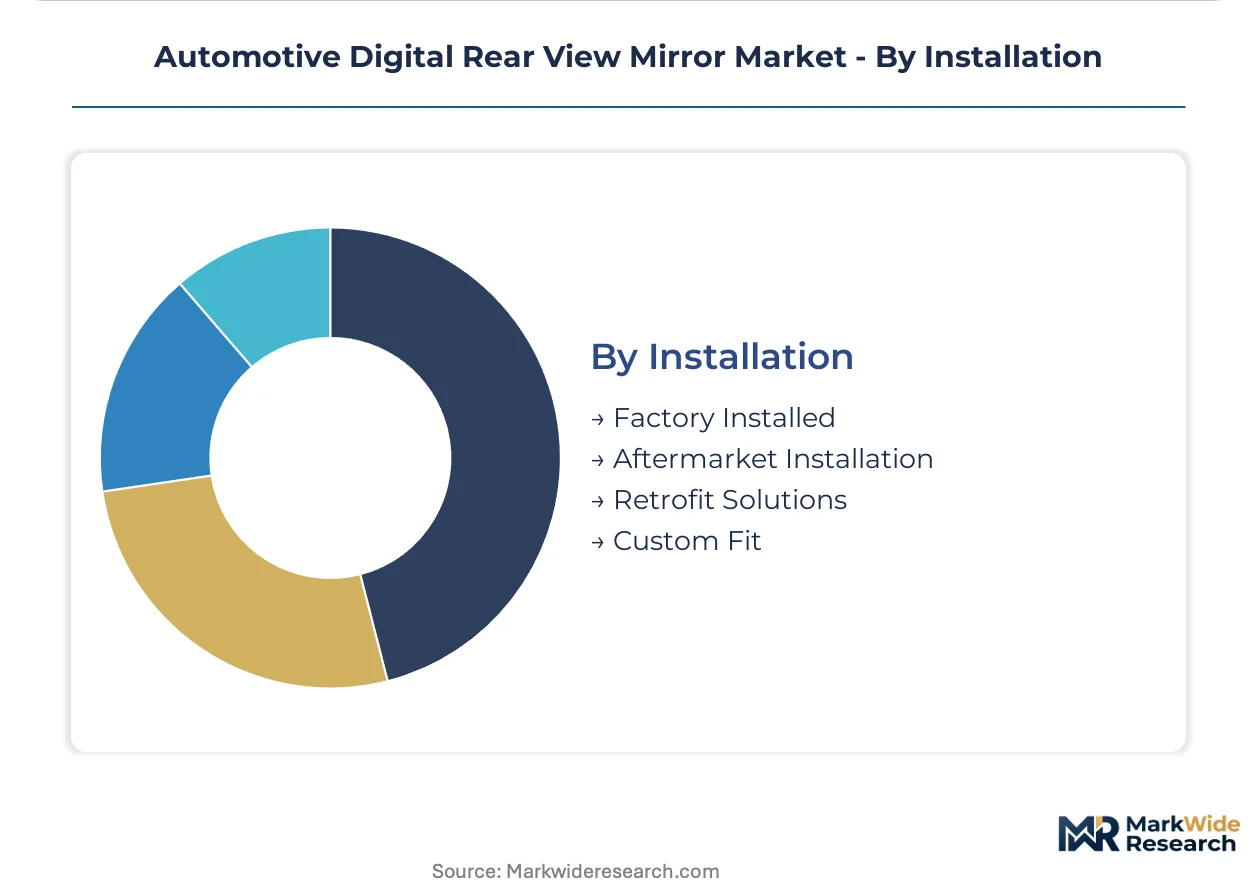
- Factory Installed:Original equipment specification at vehicle assembly with full CAN bus integration and homologation certification. North American premium SUV programs now exceed ninety percent penetration of this channel, driven by NHTSA Federal Motor Vehicle Safety Standard No. 111 compliance requirements that favor OEM-controlled type approval.
- Aftermarket Installation:Post-purchase upgrade through authorized dealer networks or independent specialists. Japan's MLIT camera-monitor system legalization created regulatory precedent enabling this channel, though technical complexity limits viable service providers.
- Retrofit Solutions:Legacy vehicle adaptation requiring power distribution reconfiguration and control module reprogramming.
- Custom Fit:Bespoke integration for commercial vehicle fleets and specialized transportation applications.
Factory Installed holds installed capacity. Aftermarket Installation is gaining share fastest through regulatory harmonization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEMs command pricing premiums through captive semiconductor sourcing, while Japanese suppliers absorb margin compression from display panel volatility. This asymmetry concentrates procurement authority in Stuttgart and Nagoya corridors.
United States
NHTSA Federal Motor Vehicle Safety Standard No. 111 mandates expanded rear visibility fields, compelling Detroit Three automakers to factory-install digital mirrors across premium SUV configurations. Michigan-based Tier-1 integration hubs now process ninety percent of North American module volume through single-source contracts.
Germany
KBA type-approval harmonization accelerates Euro NCAP scoring compliance across Mercedes-Benz and BMW mid-range programs. Bavarian engineering clusters in Munich and Ingolstadt concentrate ADAS-mirror packaging expertise, displacing electrochromic glass suppliers from RFQ shortlists.
Japan
MLIT camera-monitor system legalization permits complete mirror elimination, creating regulatory precedent for Asian harmonization. Toyota City and Nagoya corridors anchor CMOS sensor sourcing decisions, with Denso leveraging captive semiconductor positions to control LCD driver board costs.
South Korea
Display panel fabrication concentrates in Seoul and Suwon corridors, exposing procurement timelines to single-source geographic risk. Hyundai Mobis anchors domestic OEM programs through backward integration into OLED driver IC supply chains.
China
MIIT automotive-grade display standards tighten contrast ratio specifications for night-vision clarity. Shanghai and Shenzhen clusters host emerging domestic mirror module assemblers targeting mid-range electric vehicle platforms with cost-optimized LCD architectures.
Automotive Digital Rear View Mirror Market Competitive Environment
Vertically integrated systems houses and specialized mirror fabricators split the market along ADAS convergence fault lines. Consolidation pressure favors players with captive semiconductor sourcing and mirror-integrated packaging capabilities. Three archetypes dominate: Tier-1 automotive suppliers with display integration expertise, electrochromic glass incumbents pivoting to digital architectures, and Asian electronics conglomerates leveraging panel fabrication scale. M&A activity concentrates on CMOS sensor sourcing rights and OLED burn-in mitigation IP.
Among Japanese and German Tier-1 systems houses, Denso Corporation and Continental AG occupy positions defined by backward integration into semiconductor supply chains. Denso anchors Asian OEM programs through captive LCD driver board production, while Continental exemplifies European mirror-integrated ADAS packaging. Gentex Corporation represents the electrochromic-to-digital pivot archetype in North American factory-installed channels.
| Leading Market Players |
|---|
| Denso Corporation |
| Continental AG |
| Gentex Corporation |
| Ficosa International S.A. |
| Magna International Inc. |
| Robert Bosch GmbH |
| Hyundai Mobis Co. Ltd. |
| Foryou Corporation |
| Panasonic Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on South Korean and Taiwanese display panel fabrication compresses module cost predictability while widening the spread between configured-to-order OLED specifications and standard LCD architectures. This geographic concentration forces Tier-1 suppliers to absorb semiconductor input volatility through extended payment terms and inventory financing, reshaping how procurement contracts allocate price risk across OEM direct supply and aftermarket channels.
Pricing Analysis
Configured-to-order pricing for OLED mirror modules commands substantial premiums over standard LCD configurations, with differentiation anchored in automotive-grade burn-in mitigation certification and night-vision contrast performance. Three-tier pricing structure across premium, standard, and economy levels stratifies by display technology grade and ADAS integration depth, though cost compression in entry-luxury LCD segments is intensifying because OEMs internalize specification control through captive semiconductor sourcing. Fleet procurement departments exhibit highest price sensitivity, while German and Japanese OEMs with backward integration into driver IC supply chains demonstrate lowest sensitivity to component volatility.
Supply Chain Analysis
Extended payment terms from OEMs to Tier-1 suppliers now stretch 90-120 days, with supply-chain finance facilities bridging working capital gaps for mirror module assemblers. CMOS image sensor fabrication draws from Japan and Taiwan, LCD driver IC production rests on South Korean foundries, and final module assembly concentrates in China and Mexico. Single-source vulnerability in OLED panel supply exposes procurement timelines to geographic concentration risk. Distribution runs through vertically integrated systems houses delivering single-SKU contracts to OEM assembly lines, displacing traditional glass mirror distributors from factory-installed channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has consolidated around vertically integrated OEMs with captive semiconductor sourcing, fragmenting pricing leverage among Tier-2 component suppliers and aftermarket distributors. This shift demands differentiated strategic positioning across incumbent, entrant, and investor archetypes.
For Market Incumbents: Harden ADAS packaging capabilities against displacement by semiconductor vendors expanding into mirror-integrated modules. Deepen backward integration into CMOS sensor sourcing to defend margin positions against Denso and Continental captive supply advantages. Invest in OLED burn-in mitigation IP to maintain specification access as BMW and Mercedes-Benz mandate contrast ratios exceeding one million to one across mid-range programs. For New Entrants and Emerging Players: Build out aftermarket digitization platforms targeting independent installer networks in Japan and European markets where MLIT and KBA harmonization enables regulatory-compliant retrofit channels. Commercial vehicle fleets in Germany represent the most penetrable white-space segment, with blind-spot elimination mandates driving demand without aerodynamic penalty of extended mirror arms. Pursue direct-to-installer subscription models for firmware updates as an alternative to traditional parts distribution economics. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors electrochromic-to-digital pivot specialists with established OEM relationships and semiconductor sourcing rights. Long-term viability over the next decade hinges on ADAS convergence capabilities and mirror-integrated packaging expertise rather than standalone display hardware. Monitor NHTSA and Euro NCAP regulatory harmonization timelines as the critical inflection signal for capacity deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| OLED Supply Agreement | Secures automotive-grade panel allocation from LG Display or Samsung for night-vision specifications. |
| CMOS Sensor Backward Integration | Captures Sony or Omnivision sourcing rights to control LCD driver board cost positions. |
| ADAS Software Licensing | Enables parking guidance overlay integration for mid-range OEM trim configurations. |
| European Homologation Investment | Accelerates KBA type-approval for camera-monitor system replacement of conventional mirrors. |
| Commercial Vehicle Platform Standardization | Addresses impending blind-spot mandates for heavy-duty truck fleets in Germany and Japan. |
Study Parameters
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and semiconductor vendor automotive sales leads provided ongoing calibration across primary fieldwork. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standard filings, Euro NCAP assessment protocol documentation, Japan MLIT camera-monitor system approval records, and vehicle production databases. Bottom-up module shipment estimates triangulated against top-down OEM program specification analysis.
Scenario-bracketing around semiconductor input cost volatility and regulatory harmonization timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, display technology maturity, installation timing, and regional regulatory cluster. CAGRs were derived from installation rate trajectories and content-per-vehicle assumptions, with OLED penetration curves and factory-installed share evolution serving as key forecast inputs.
Stress conditions across CMOS sensor pricing fluctuation, display panel supply disruption, and divergent homologation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about OEM captive sourcing trends and regulatory scorecard redesign. Macroeconomic contraction, trade policy disruption, or breakthrough display technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Europe Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Flock Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Vehicle Interior Air Quality Sensor Platforms Market
Automotive Interior & Exterior
Asia-Pacific Automotive Seat Market
Automotive Interior & Exterior
Automotive Telescopic Mirror Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Global Automotive Rear Window Blinds Market
Automotive Interior & Exterior
Auto Glass Encapsulation Market
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market
Automotive Interior & Exterior
Automotive Insulation Market
Automotive Interior & Exterior
China Automotive Sunroof Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Automotive Glove Compartment Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market