
 Engine Fogging Oil Market | 2026-2036
Engine Fogging Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Fogging Oil Market Analysis
Synthetic additive formulation is fragmenting the traditional petroleum-based fogging oil landscape as manufacturers pursue extended storage protection and lower emission residues. ExxonMobil leverages its integrated base oil supply chain to control cost positions across marine and automotive channels. AMSOIL INC. differentiates through synthetic-heavy product lines targeting high-performance recreational engines. CRC Industries competes on aerosol delivery systems and retail shelf presence in North American hardware and marine supply stores.
Engine fogging oil is a corrosion-inhibiting lubricant sprayed or poured into internal combustion engine cylinders to protect metal surfaces during seasonal or long-term storage, typically formulated with light mineral or synthetic base stocks combined with anti-oxidant and film-forming additives. The aerosol segment dominates unit volume due to convenience in marine and recreational applications where precise cylinder targeting matters. Liquid formulations lead in industrial end-user channels where bulk application and cost-per-gallon drive procurement decisions. Gel variants occupy a niche in extreme-climate storage scenarios where gravity-driven drain-off poses corrosion risks.
EPA marine engine standards constrain volatile organic compound content in aerosol fogging products sold in the United States, pushing reformulation toward lower-VOC propellant systems and liquid alternatives. REACH registration requirements in Europe govern corrosion-inhibitor chemistries, particularly zinc-based and barium-derived additives, forcing suppliers to document substance safety profiles for market access. Stakeholders must monitor regulatory divergence between North American VOC limits and European chemical authorization timelines when planning product portfolios and regional manufacturing footprints.
Market Dynamics
Synthetic base oil substitution is compressing the petroleum-based fogging oil value chain as marine and automotive OEMs demand extended storage protection with lower residue profiles. This shift reconfigures raw material sourcing, reformulation R&D priorities, and competitive positioning across aerosol and liquid delivery formats.
Growth Catalysts
- EPA marine engine standards:Volatile organic compound limits in the United States are accelerating reformulation toward lower-VOC propellant systems and liquid alternatives, expanding addressable product portfolios.
- Recreational boating fleet expansion:Vessel owners in coastal U.S. states and Mediterranean port clusters are extending seasonal storage periods, driving systematic winterization protocol adoption.
- Synthetic additive chemistry:Advanced corrosion inhibitors and film-forming compounds are enabling multi-year storage guarantees that petroleum-based formulations cannot match.
Market Restraints
- Base oil supply concentration:Integrated petroleum majors control synthetic and mineral base stock production, creating input cost volatility for independent formulators.
- REACH authorization timelines:European corrosion-inhibitor registration requirements for zinc-based and barium-derived additives create regulatory friction and documentation burdens.
- Propellant chemistry limitations:Technical constraints in aerosol systems restrict VOC reduction without compromising spray pattern precision and cylinder targeting.
Strategic Opportunities
- Industrial bulk channels:Untapped demand exists in fleet maintenance operations and power generation storage applications where cost-per-gallon economics favor liquid formulations.
- Gel formulation niche:Extreme-climate storage scenarios in northern latitudes present white space for gravity-resistant products addressing drain-off corrosion risks.
- EU Green Deal alignment:Biodegradable and bio-based fogging oil development aligns with sustainability procurement mandates in European marine and industrial sectors.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in corrosion-inhibitor synergy and propellant compatibility remains concentrated within legacy lubricant companies.
- Dual regulatory compliance:Manufacturers must simultaneously satisfy divergent U.S. VOC limits and European substance authorization timelines, complicating product portfolio architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Fogging Oil Market |
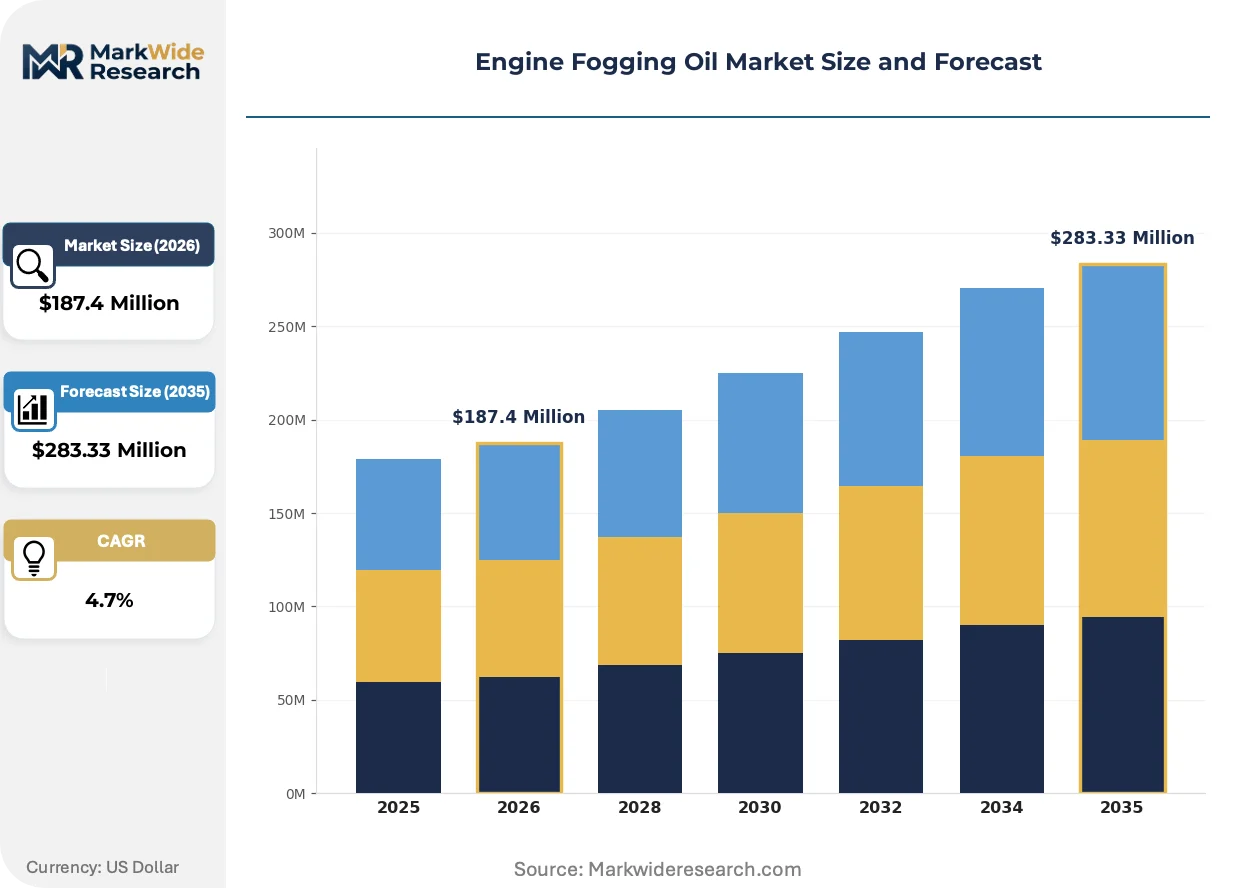
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $283.33 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol, Liquid, Gel, Spray End User: Marine, Automotive, Industrial, Recreational Application: Engine Maintenance, Corrosion Protection, Storage, Cleaning Distribution Channel: Retail, Online, Wholesale, Direct |
| Companies Covered | ExxonMobil, Chevron Corporation, BP plc, AMSOIL INC., CRC Industries, Yamaha Motor Corporation, AeroShell, Motul, Lucas Oil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Fogging Oil Market Emerging Trajectories
Synthetic-heavy formulations are redrawing competitive boundaries as performance specifications tighten and environmental compliance deepens. Three interconnected developments are reshaping how fogging oil products are designed, regulated, and procured.
Polyalphaolefin (PAO) and ester-based synthetic base stocks are collapsing the performance gap between premium and standard fogging oil tiers. High-performance recreational engine owners in North American coastal markets are adopting these formulations for multi-year storage protection. This collapse is compressing mid-tier product margins and forcing petroleum-dependent suppliers toward specialty niches or upstream integration.
REACH registration requirements in Europe are governing corrosion-inhibitor chemistries with increasing granularity. ECHA substance evaluation processes are extending authorization timelines for traditional additives, forcing reformulation toward pre-registered alternatives. Marine product lines destined for Mediterranean and Baltic port clusters face the most acute compliance pressure, with several suppliers accelerating bio-based inhibitor development.
Fleet maintenance managers are consolidating fogging oil procurement under multi-product lubricant supply agreements. Marine dealerships and industrial equipment servicers in the United States are unbundling after-sales chemical purchases from OEM service contracts. This consolidation is most visible in Great Lakes marina networks and Gulf Coast vessel service operations, where volume aggregation is shifting bargaining power toward distributors with broad synthetic product ranges.
Engine Fogging Oil Market Segmentation
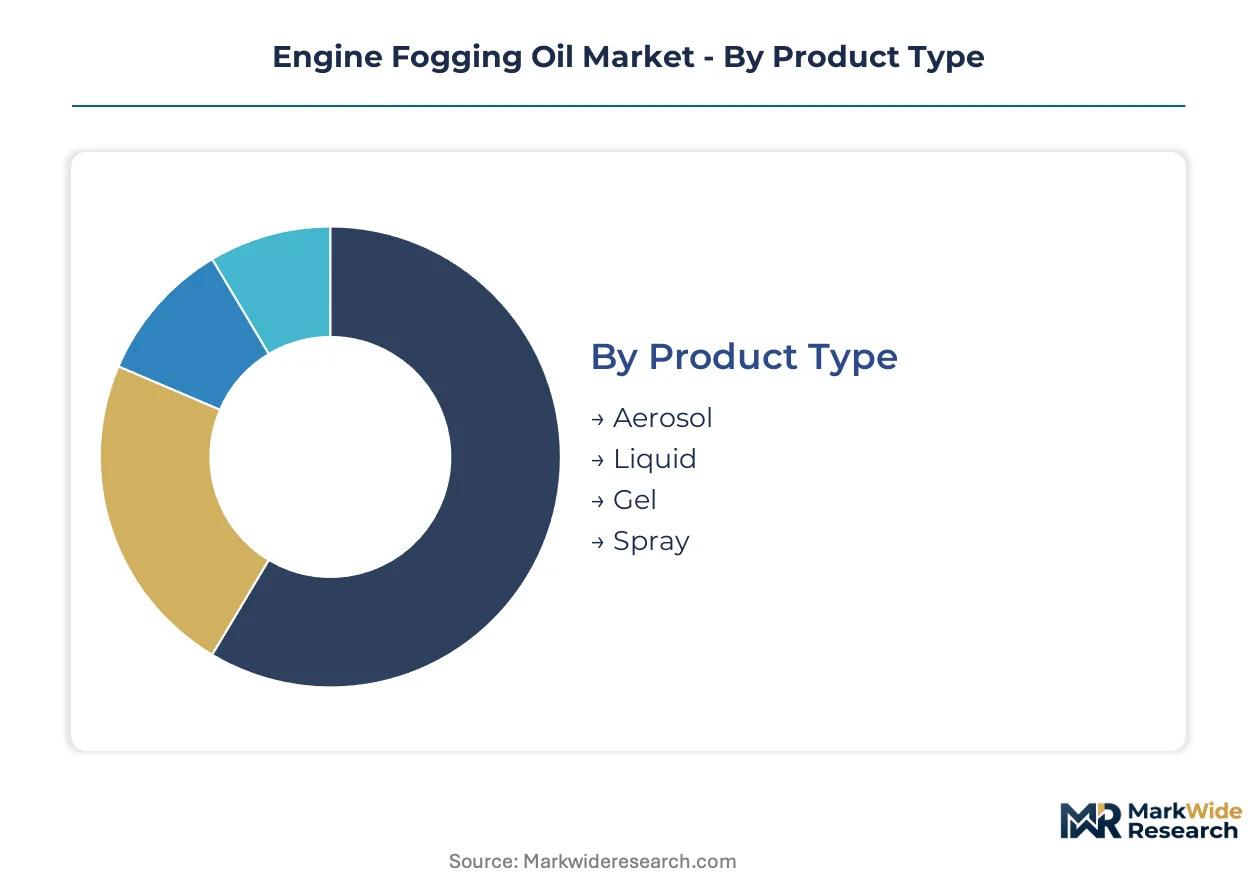
Engine fogging oil segmentation reflects divergent user workflows across seasonal storage, fleet maintenance, and precision application scenarios. Product form factors and channel access determine procurement patterns in marine harbors, automotive service bays, and industrial facilities.
Product Type:
Use-case spectrum spans from precision cylinder targeting in recreational winterization to bulk fleet application where cost-per-gallon dominates.
- Aerosol:Pressurized delivery systems combine light mineral or synthetic base stocks with propellant chemistry for directed spray into combustion chambers. Coastal U.S. states and Mediterranean port clusters drive volume as vessel owners execute systematic winterization protocols requiring exact cylinder coverage. EPA marine engine standards constrain volatile organic compound content, pushing reformulation toward lower-VOC propellant alternatives.
- Liquid:Pourable formulations in quart and gallon containers serve industrial end users and fleet maintenance operations where bulk application economics outweigh convenience premiums. Great Lakes marinas and Gulf Coast vessel service operations consolidate procurement under multi-product lubricant agreements, shifting volume toward liquid alternatives. Cost-per-gallon procurement criteria favor this format in power generation storage and heavy equipment seasonal mothballing.
- Gel:Thickened matrix resists gravity-driven drain-off in extreme-climate storage scenarios, maintaining protective film integrity on vertical cylinder walls. Northern latitude applications with extended sub-zero dormancy periods generate specialized demand.
- Spray:Trigger-operated pump systems deliver atomized fogging oil without pressurized propellants, bridging convenience and regulatory compliance for VOC-restricted jurisdictions.
The dominant share belongs to Aerosol, while Liquid is closing the gap fastest.
End User:
Customer type concentration varies sharply by procurement scale, technical specification tolerance, and seasonal predictability.
- Marine:Recreational vessel owners and commercial fleet operators in North American coastal waters and European port clusters constitute the core demand base. Extended seasonal storage periods and corrosion risks from salt-air exposure mandate systematic fogging protocols. EPA marine engine standards and REACH corrosion-inhibitor requirements shape product selection across Atlantic and Mediterranean basins.
- Recreational:High-performance engine owners pursue synthetic-heavy formulations for multi-year storage guarantees, compressing mid-tier petroleum product margins. This segment exhibits the steepest expansion trajectory as power sports and classic vehicle collectors professionalize preservation practices.
- Automotive:Classic car collectors, seasonal vehicle operators, and dealership service departments apply fogging oils during extended layup periods. Demand concentrates in regions with harsh winter cycles.
- Industrial:Fleet maintenance managers and power generation facilities prioritize cost-per-gallon economics and bulk availability over formulation sophistication. Procurement consolidates under integrated lubricant supply agreements.
Marine commands the largest revenue pool, though Recreational applications are gaining share fastest through premium synthetic adoption.
Application:
Functional purpose determines formulation chemistry, application frequency, and performance guarantee requirements.
- Storage:Long-term metal surface protection during seasonal or multi-year dormancy drives core fogging oil demand. Film-forming additives and corrosion inhibitors must maintain integrity across temperature cycling and humidity variation.
- Corrosion Protection:Salt-air environments and humid climates require enhanced inhibitor packages, particularly zinc-based and barium-derived chemistries facing REACH authorization scrutiny in Europe.
- Engine Maintenance:Pre-storage preparation and post-reactivation protocols incorporate fogging oil as a standard service line item in marine dealerships and automotive service centers.
- Cleaning:Light solvent properties in some formulations assist carbon deposit loosening during maintenance intervals, though this remains a secondary application.
Storage applications generate the highest absolute volume, while Corrosion Protection formulations command the strongest pricing premium.
Distribution Channel:
Channel economics reflect fragmentation between convenience-driven retail, price-sensitive wholesale, and relationship-based direct supply.
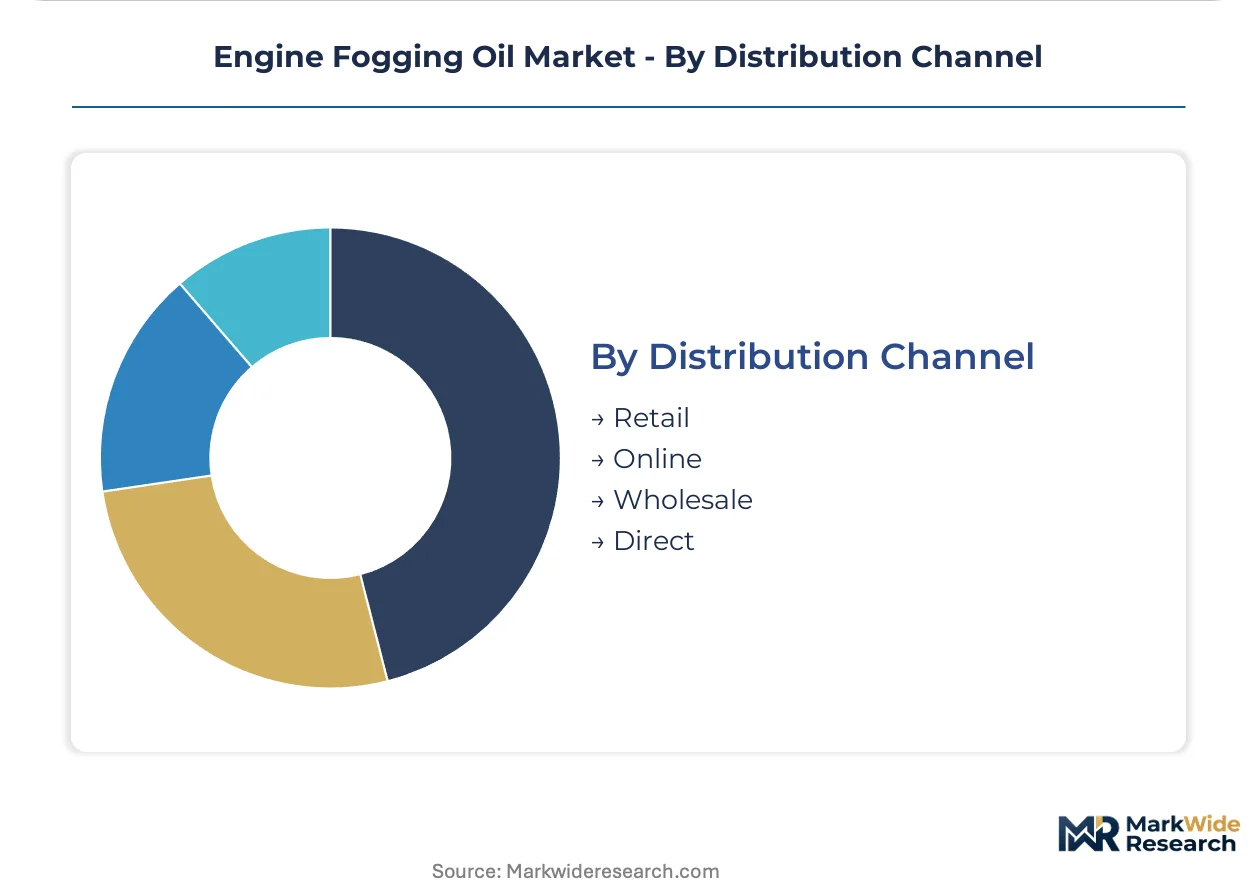
- Retail:Hardware stores, marine supply outlets, and automotive parts retailers stock aerosol formats for walk-in vessel owners and DIY enthusiasts. Shelf presence and brand recognition drive selection in coastal U.S. states.
- Wholesale:Distributors serving marina networks and fleet maintenance operations aggregate volume across synthetic product ranges, shifting bargaining power toward suppliers with broad formulation portfolios.
- Direct:Marine dealerships and industrial equipment servicers unbundle after-sales chemical purchases from OEM service contracts, creating direct procurement relationships with formulators.
- Online:E-commerce platforms capture specialized formulations and bulk liquid purchases where shipping economics permit, particularly for synthetic-heavy products with limited retail distribution.
Retail maintains the widest reach, yet Wholesale is consolidating volume fastest as procurement professionalizes across marina networks and fleet operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recreational vessel owners and fleet operators cluster in coastal jurisdictions with harsh seasonal cycles and stringent environmental protocols. Procurement patterns track marina density, winterization service penetration, and regulatory enforcement intensity across major boating corridors.
United States
Coastal states from Florida to Maine and Great Lakes marinas generate concentrated demand for aerosol and liquid fogging formulations. EPA marine engine standards enforce volatile organic compound limits on aerosol products, accelerating reformulation toward lower-VOC propellant systems. Gulf Coast vessel service operations around Houston and Tampa Bay consolidate procurement under multi-product lubricant agreements.
Germany
Industrial fleet maintenance operations and recreational boating on the Baltic and North Sea coasts sustain steady consumption. REACH authorization requirements govern corrosion-inhibitor chemistries, particularly zinc-based additives, forcing documentation-intensive compliance. Hamburg and Bremen port clusters anchor distribution networks serving northern European marine channels.
Italy
Mediterranean recreational boating fleets in Liguria, Campania, and Sicily extend seasonal storage periods, driving systematic winterization adoption. EU Green Deal procurement mandates push marine servicers toward biodegradable formulation alternatives. Port clusters around Genoa and Naples concentrate demand for premium synthetic products.
Canada
Extended sub-zero dormancy periods across Ontario, Quebec, and British Columbia create specialized demand for gel formulations resisting gravity-driven drain-off. Health Canada and PMRA oversight aligns with EPA frameworks on propellant chemistry while maintaining distinct registration pathways. Great Lakes marina networks in Ontario professionalize procurement through distributor consolidation.
Australia
Coastal recreational boating in New South Wales, Queensland, and Western Australia operates with less pronounced seasonality but faces salt-air corrosion risks requiring enhanced inhibitor packages. TGA chemical oversight and state-level environmental regulations shape product availability. Sydney and Melbourne marine service centers drive premium synthetic adoption among high-performance engine owners.
Engine Fogging Oil Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tiering. Integrated petroleum majors leverage captive base oil supply and established marine distribution networks. Independent formulators differentiate through synthetic-heavy portfolios and aerosol delivery innovation. Strategic moves concentrate on upstream integration into additive chemistry and geographic expansion through distributor partnerships.
Within the integrated petroleum tier, ExxonMobil and Chevron Corporation anchor positions through scale advantages in base stock production. Among independent specialists, AMSOIL INC. and CRC Industries exemplify divergent positioning—one through synthetic formulation focus, the other through retail channel penetration. These four entities represent the competitive spectrum from upstream-integrated volume players to targeted segment specialists.
| Leading Market Players |
|---|
| ExxonMobil |
| Chevron Corporation |
| BP plc |
| AMSOIL INC. |
| CRC Industries |
| Yamaha Motor Corporation |
| AeroShell |
| Motul |
| Lucas Oil |
| Others |
Supply Flow & Price Mechanics
Integrated petroleum majors in the United States and Western Europe control synthetic and mineral base stock production, concentrating upstream margin capture and forcing independent formulators into cost-plus contracts indexed to crude oil and PAO spot markets. This supply concentration shifts pricing power toward base oil producers while compressing margins for aerosol packagers and regional blenders serving marine and automotive channels.
Pricing Analysis
Cost-plus contracts with crude-linked indexation dominate procurement between base oil suppliers and independent formulators, with pass-through clauses resetting quarterly. Pricing stratifies across premium synthetic tiers anchored by AMSOIL and Motul, mid-tier petroleum blends from CRC Industries and Lucas Oil, and economy private-label offerings. Cost compression in mid-tier petroleum products is intensifying because PAO-based synthetics are collapsing performance gaps at comparable price points. Fleet maintenance managers in industrial channels exhibit highest price sensitivity, while high-performance recreational engine owners accept premium positioning for multi-year storage guarantees.
Supply Chain Analysis
Toll blending and contract-manufacturing capacity concentrates with regional lubricant packagers in Texas, Louisiana, and Rotterdam serving marine distribution networks. Raw material sourcing draws from Group II/III base oil refineries in the United States Gulf Coast, PAO production facilities in Belgium and Singapore, and corrosion-inhibitor additive suppliers governed by REACH authorization in Europe. Single-source vulnerability runs through zinc-based and barium-derived additive chemistries facing extended ECHA evaluation timelines. Distribution runs through marina network distributors, automotive aftermarket wholesalers, and direct procurement relationships with marine dealerships unbundling chemical purchases from OEM service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense as bio-based fogging oils and biodegradable corrosion inhibitors align with EU Green Deal procurement mandates, threatening petroleum-dependent formulations with regulatory obsolescence.
For Market Incumbents: Pre-empt bio-based substitution by accelerating synthetic-heavy product line expansion and securing backward integration into pre-registered corrosion-inhibitor chemistries ahead of REACH authorization bottlenecks. Anchor capacity in Rotterdam and Singapore port clusters to serve Mediterranean and Asia-Pacific marine demand. Channel control through marina network exclusivity agreements defends against distributor consolidation shifting bargaining power. For New Entrants and Emerging Players: Northern latitude gel formulation white space offers entry with gravity-resistant products addressing drain-off corrosion risks in Canadian and Scandinavian markets. Industrial bulk channels present second target, where cost-per-gallon procurement criteria favor liquid alternatives and fleet maintenance managers consolidate under multi-product lubricant agreements. Go-to-market through direct relationships with Great Lakes marina networks bypasses retail shelf competition dominated by CRC Industries and ExxonMobil. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed marine chemical specialists holding distributor relationships but lacking synthetic formulation capabilities and REACH compliance infrastructure. Five-to-ten-year viability hinges on successful petroleum-to-synthetic transition and geographic expansion beyond North American coastal markets. Monitor ECHA substance evaluation timelines for zinc-based additives as inflection indicator—accelerated restrictions would force rapid reformulation and consolidate advantage with pre-registered suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive PAO production from ExxonMobil and Chevron insulates margin compression from crude volatility. |
| REACH-Compliant Additive Reformulation | Pre-registration of corrosion inhibitors with ECHA secures European market access ahead of authorization bottlenecks. |
| Gel Formulation Development | Gravity-resistant products address sub-zero storage demand in Canadian and Scandinavian marina networks. |
| Marina Network Distribution Partnerships | Exclusive supply agreements with Great Lakes and Gulf Coast distributors lock out competitor shelf presence. |
| Bio-Based Product Line Launch | Biodegradable formulations align with EU Green Deal procurement mandates in Mediterranean port clusters. |
Methodological Framework
Initial hypotheses were tested against primary input from marine service technicians, fleet maintenance managers, lubricant procurement directors, and marina network distributors, then refined through secondary validation. Primary fieldwork encompassed technical directors at synthetic base oil producers, aerosol packaging specialists, and regulatory affairs leads navigating EPA marine engine standards and REACH authorization timelines. Secondary sources included customs and trade data on base oil imports, ECHA substance registration databases, SEC 10-K filings from integrated petroleum majors, and marina industry association procurement surveys. Bottom-up volume estimates from product-form and end-user segmentation were triangulated against top-down market sizing from regional boating fleet data and winterization protocol penetration rates.
Demand-supply-balance modeling across the analysis window linked recreational boating fleet expansion, seasonal storage period extension, and regulatory reformulation cycles to volume projections by product type. Segmentation dimensions encompassed delivery format (aerosol, liquid, gel, spray), end-user category (marine, recreational, automotive, industrial), application purpose (storage, corrosion protection, maintenance), and distribution channel (retail, wholesale, direct, online). CAGRs were derived from regression analysis of historical base oil price elasticity, regulatory compliance cost trajectories, and substitution patterns between petroleum and synthetic formulations. Industry-specific inputs included EPA VOC limit enforcement intensity and ECHA authorization timeline probability distributions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated petroleum majors or accelerated bio-based substitution by European formulators would shift outcomes beyond modeled ranges. Quarterly review of ECHA substance evaluation progress, EPA enforcement actions on marine engine standards, and marina network distributor consolidation activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Tonneau Market
Automotive Parts
Mobile Diesel Heaters Market
Automotive Parts
Off-Road Hoses Market
Automotive Parts
Germany Automotive Hydraulic Actuators Market
Automotive Parts
Connecting Rods Market
Automotive Parts
Nigeria Automotive Lubricants Market
Automotive Parts
Automotive Trailing Arm Bushing Market
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Brake Lathe Machine Market
Automotive Parts
Global Automotive Gasket and Seal Market
Automotive Parts
Automotive Trim Part Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
Engine Bearings Market
Automotive Parts
Heavy Duty Engines Market
Automotive Parts
Electromagnetic Clutch System Market