
 Speed Bumps & Humps Market | 2026-2036
Speed Bumps & Humps Market Size, Share, and Industry Trends Forecast 2026-2036
Speed Bumps & Humps Market Insights
Aftermarket service revenue is narrowing as manufacturers bundle installation and maintenance into original equipment contracts. CABKA Group leverages its recycled polymer expertise to dominate temporary installation channels across European municipalities. Reliance Foundry anchors permanent cast-iron solutions for North American commercial parking applications. Innoplast competes through specialized rubber formulations that extend product lifespan in high-traffic school zones.
Speed bumps and humps are raised traffic-calming devices typically measuring 76 to 100 millimeters in height and 2.4 to 4.3 meters in length, manufactured from vulcanized rubber, cast concrete, thermoplastic polymers, or asphalt composite to reduce vehicle speeds to 15 to 25 kilometers per hour in controlled zones. Their primary purpose is pedestrian protection and collision prevention in high-conflict areas. Rubber bumps lead product type demand due to modular installation and lower surface damage, while embedded concrete humps capture the permanent infrastructure margin pool as municipalities prioritize decades-long asset life. Temporary plastic installations represent the fastest-growing installation type segment as event-driven and construction-zone applications multiply.
The Federal Highway Administration's Manual on Uniform Traffic Control Devices governs geometric standards and placement protocols in the United States, while the EU Road Infrastructure Safety Directive mandates systematic risk assessment for traffic-calming measures across member states. BSI's PAS 3003 standard in the United Kingdom specifies performance testing for recycled rubber products, directly shaping material selection by procurement officers. Stakeholders must monitor evolving lifecycle cost methodologies as municipalities shift from lowest-bid awards to total cost of ownership frameworks.
Market Dynamics
Municipal procurement officers are abandoning lowest-bid awards for total cost of ownership frameworks, compressing margins for commodity-grade rubber bumps while rewarding engineered polymer solutions with documented lifecycle performance.
Growth Catalysts
- EU Road Infrastructure Safety Directive:Systematic risk assessment mandates across member states are accelerating replacement of unregulated legacy installations with certified traffic-calming devices.
- Urban densification clusters:German, British, and American metropolitan authorities are expanding pedestrian priority zones in historic city cores and school-adjacent corridors.
- Recycled polymer formulations:CABKA Group's technical validation of post-consumer plastic performance is normalizing circular material specifications in temporary installation tenders.
Market Restraints
- Petroleum-based input volatility:Synthetic rubber and thermoplastic feedstock costs fluctuate with crude oil indices, squeezing margin predictability for mid-tier manufacturers without backward integration into resin production.
- Embedded concrete duopoly:Permanent infrastructure contracts concentrate among precast concrete specialists with municipal bonding capacity, locking out smaller rubber and polymer competitors from decades-long asset classes.
- Asphalt composite substitution:In-house road crews in budget-constrained municipalities increasingly form speed tables from native paving materials, bypassing manufactured product procurement entirely.
Strategic Opportunities
- Smart city integration:Sensor-embedded polymer humps capable of real-time traffic flow monitoring are capturing pilot contracts from Dutch and Scandinavian municipal technology departments.
- Construction-zone temporary demand:Highway maintenance outsourcing in the United States is creating recurring rental-model revenue streams distinct from traditional capital purchase cycles.
- BSI PAS 3003 certification gap:United Kingdom procurement frameworks now require recycled rubber performance validation, advantaging early certifiers against uncertified import competition.
Industry Challenges
- Geotechnical installation expertise:Proper substrate preparation and drainage engineering for permanent concrete humps requires specialized civil contractor relationships that product manufacturers struggle to cultivate directly.
- MUTCD compliance documentation:Federal Highway Administration geometric standard updates demand continuous product re-engineering and third-party testing investment without guaranteed specification adoption timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speed Bumps & Humps Market |
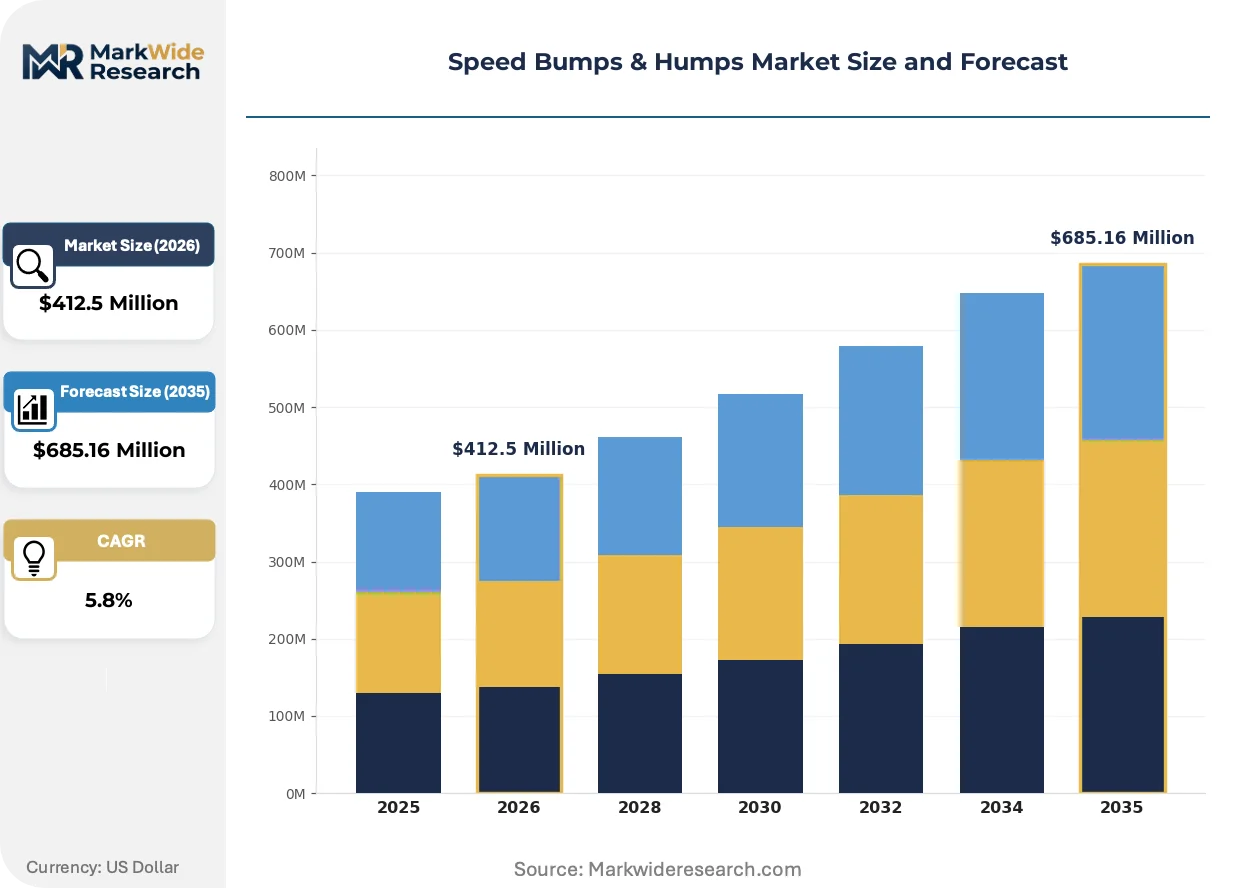
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Bumps, Asphalt Humps, Plastic Bumps, Concrete Humps Installation Type: Permanent, Temporary, Surface Mount, Embedded Application: Residential Areas, School Zones, Parking Lots, Commercial Areas End User: Municipalities, Property Developers, Schools, Businesses |
| Companies Covered | Barrier Group, Ecobam Europa, CABKA Group, Innoplast, Gradus, Axelent, BENITO URBAN, JSP, Reliance Foundry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speed Bumps & Humps Market Trends and Innovations
Material science advances and procurement digitization are compressing product lifecycles while elevating performance verification requirements above historical specification compliance.
Photoluminescent polymer composites incorporating strontium aluminate pigments are rendering obsolete traditional painted surface markings for nighttime visibility. Airport authorities and hospital emergency access routes in Germany and the Netherlands specify these self-illuminating formulations for critical pathway identification. The technology eliminates recurring maintenance contracts for reflective coating renewal, collapsing a recurring revenue stream that surface-applied product lines previously captured.
The Federal Highway Administration's 2023 MUTCD revision tightened height and slope tolerances for speed humps in school zones, invalidating legacy product inventories that predated the geometric standard. State departments of transportation in California and Texas are enforcing the updated specifications through qualified product lists, forcing manufacturer redesign cycles. Rubber compounders with in-house molding flexibility are capturing specification advantage against rigid-tool competitors.
Municipal fleet managers are consolidating vendor relationships through cooperative purchasing agreements administered by the National Association of State Procurement Officials. Small and mid-sized cities in the American Midwest are accessing pre-negotiated pricing and technical support previously available only to major metropolitan buyers. This concentration is marginalizing independent distributors who historically served fragmented municipal procurement departments.
Speed Bumps & Humps Market Segmentation
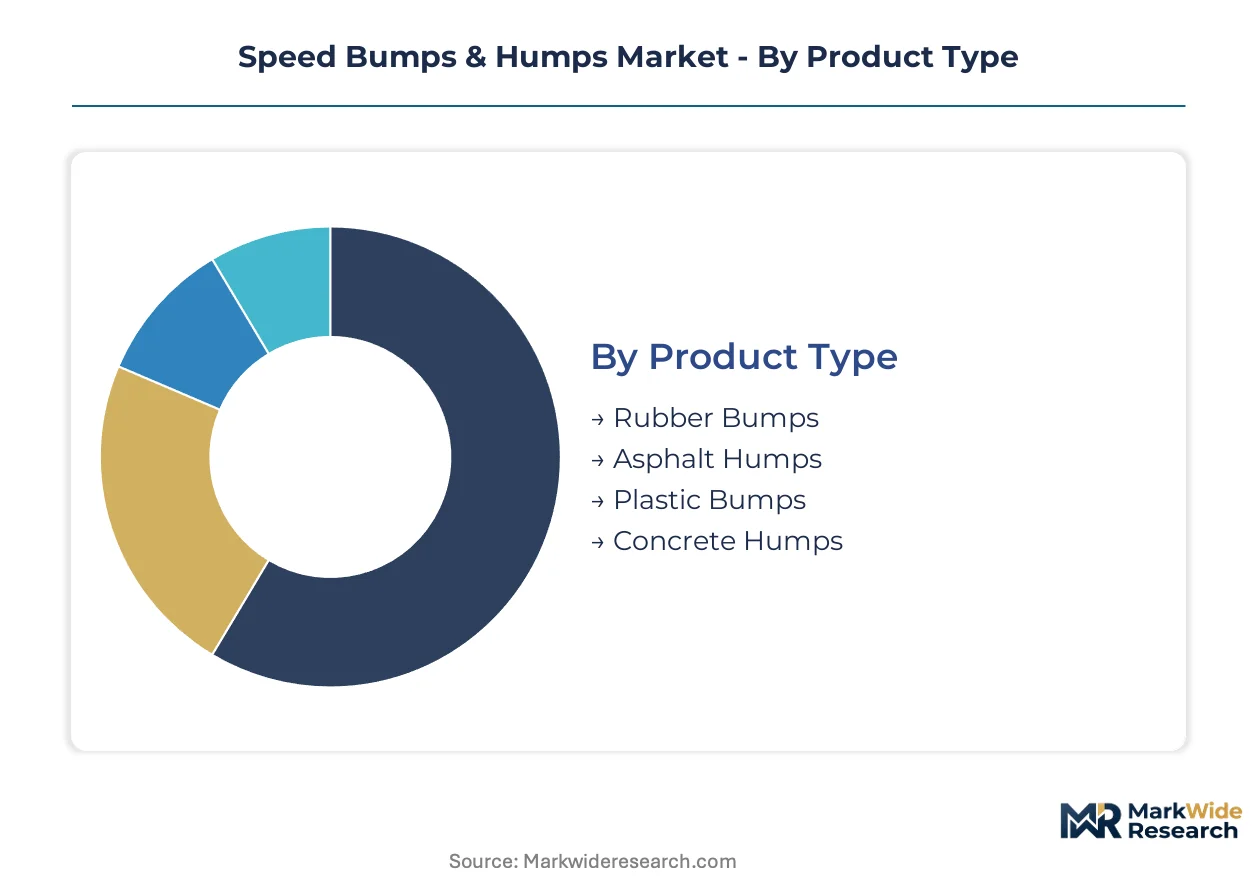
Traffic-calming procurement decisions hinge on lifecycle economics and installation permanence. Material selection and deployment methodology determine total cost of ownership for municipal buyers and private facility managers.
Product Type:
Mature vulcanized rubber formulations dominate volume, while emerging polymer composites reshape temporary deployment economics.
- Rubber Bumps:Modular vulcanized rubber segments with embedded reflectors allow rapid bolt-down installation without substrate excavation. German and British municipalities specify these for school zone retrofits where surface preservation matters. Petroleum feedstock volatility squeezes compounders lacking backward integration into resin production.
- Asphalt Humps:Road crews form these from native paving materials using standard compaction equipment. Budget-constrained municipalities in the American Midwest increasingly bypass manufactured procurement entirely, collapsing product revenue for traditional suppliers.
- Plastic Bumps:CABKA Group's recycled polymer formulations normalize circular material specifications in European temporary installation tenders.
- Concrete Humps:Precast reinforced units deliver decades-long asset life for permanent infrastructure corridors.
Rubber Bumps retains volume leadership; Plastic Bumps holds the steepest expansion curve.
Installation Type:
Cost tier stratification separates capital-intensive permanent foundations from operational rental models.
- Permanent:Excavated and poured concrete or embedded asphalt solutions require civil contractor bonding capacity. Municipal bonding requirements lock out smaller rubber competitors from decades-long asset classes.
- Temporary:Modular polymer units deploy for construction zones and event-driven applications. Highway maintenance outsourcing in the United States creates recurring rental-model revenue streams distinct from traditional capital purchase cycles.
- Surface Mount:Bolt-down rubber or polymer systems enable rapid retrofit without road closure.
- Embedded:Subgrade-integrated concrete demands specialized geotechnical preparation and drainage engineering.
Permanent installations dominate infrastructure budgets; Temporary deployments gain share fastest in maintenance outsourcing contracts.
Application:
Customer type concentration varies by liability exposure and pedestrian conflict intensity.
- School Zones:Federal Highway Administration MUTCD geometric standards mandate specific height and slope tolerances. Innoplast's specialized rubber formulations extend product lifespan under daily bus and parent vehicle loading.
- Parking Lots:North American commercial property managers prioritize cast-iron solutions from Reliance Foundry for load-bearing durability.
- Residential Areas:Neighborhood traffic calming drives demand for low-profile humps compatible with emergency vehicle passage.
- Commercial Areas:Retail and logistics facilities specify heavy-duty polymer or concrete for truck aprons and loading zones.
School Zones command specification premiums; Parking Lots generate the highest unit volume.
End User:
Procurement authority concentration determines vendor relationship structures and contract terms.
- Municipalities:Cooperative purchasing agreements through the National Association of State Procurement Officials consolidate vendor relationships. Small and mid-sized cities access pre-negotiated pricing previously available only to major metropolitan buyers.
- Schools:District-level procurement prioritizes MUTCD compliance documentation and third-party safety certification.
- Property Developers:Commercial parking installation specifications favor permanent concrete for long-term asset transfer.
- Businesses:Private facility managers balance upfront cost against maintenance liability in retail and industrial applications.
Municipalities drive standardization; Property Developers concentrate permanent infrastructure demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Budget-constrained municipalities in the American Midwest exhibit the highest price elasticity, while Dutch and Scandinavian authorities prioritize lifecycle performance over upfront cost. Procurement sophistication varies sharply across geographies. The analysis tracks five national markets where traffic-calming infrastructure demand concentrates.
United States
Federal Highway Administration MUTCD compliance documentation dominates procurement specifications for school zone installations. State departments of transportation in California and Texas enforce qualified product lists that invalidate legacy inventory. The National Association of State Procurement Officials consolidates vendor relationships for Midwestern cities previously served by fragmented distributors.
Germany
Historic city core densification drives pedestrian priority zone expansion in Berlin and Munich metropolitan authorities. The EU Road Infrastructure Safety Directive mandates systematic risk assessment for traffic-calming measures across federal states. KBA technical validation requirements shape material specifications for recycled polymer installations in temporary deployment channels.
United Kingdom
BSI PAS 3003 certification now governs recycled rubber performance validation for municipal procurement frameworks. London and Southeast authorities lead specification adoption, advantaging early certifiers against uncertified import competition. District-level procurement prioritizes third-party safety certification documentation for school-adjacent corridor retrofits.
Netherlands
Municipal technology departments in Amsterdam and Rotterdam pilot sensor-embedded polymer humps for real-time traffic flow monitoring. Smart city integration contracts command specification premiums absent in conventional procurement. Dutch authorities normalize circular material specifications through technical validation of post-consumer plastic performance.
Canada
Health Canada and PMRA environmental standards influence material selection for school zone applications in Ontario and Quebec. Provincial transportation authorities balance budget constraints against liability exposure in pedestrian conflict zones. Toronto and Vancouver metropolitan procurement offices access cooperative purchasing agreements mirroring American consolidation patterns.
Speed Bumps & Humps Market Competitive Landscape
Capability concentration sits with polymer compounders possessing in-house formulation expertise; scale advantage sits with precast concrete specialists holding municipal bonding capacity. The market structures around three tiers: temporary installation specialists, permanent infrastructure contractors, and modular retrofit providers. Two strategic archetypes dominate competitive positioning—recycled material innovators and cast-metal durability anchors. Consolidation pressures favor backward integration into resin production and civil contractor partnership cultivation.
Among European recycled polymer specialists, CABKA Group exemplifies circular material specification leadership in temporary installation channels. Reliance Foundry anchors the permanent cast-metal tier for North American commercial parking applications. Innoplast occupies a position within specialized rubber formulation for high-traffic school zone durability requirements.
| Leading Market Players |
|---|
| Barrier Group |
| Ecobam Europa |
| CABKA Group |
| Innoplast |
| Gradus |
| Axelent |
| BENITO URBAN |
| JSP |
| Reliance Foundry |
| Others |
Pricing and Supply Chain Analysis
Petroleum-based input volatility determines both pricing tier spreads and supply chain shape across the speed bumps and humps market. Synthetic rubber and thermoplastic feedstock costs fluctuate with crude oil indices, compressing margins for mid-tier manufacturers without backward integration into resin production while rewarding compounders with captive supply arrangements.
Pricing Analysis
Aftermarket service revenue from installation and maintenance contracts drives lifetime value for municipal procurement relationships. Three-tier pricing structure across premium engineered polymer, standard vulcanized rubber, and economy asphalt composite levels stratifies by certification grade and lifecycle documentation. Cost compression in commodity rubber tiers is intensifying because petroleum feedstock volatility squeezes compounders lacking vertical integration. Small and mid-sized municipalities exhibit highest price sensitivity, while Dutch and Scandinavian authorities prioritize lifecycle performance over upfront cost.
Supply Chain Analysis
Extended payment terms from municipal procurement offices strain working capital for mid-tier manufacturers competing against precast concrete specialists with deeper balance sheets. Raw material sourcing concentrates in Germany, China, and the United States for vulcanized rubber compounds, thermoplastic polymers, and cast-iron foundry outputs respectively. Feedstock dependencies rest on petroleum derivatives, recycled post-consumer plastics, and scrap metal reclamation. Tariff exposure on Chinese polymer imports poses structural risk for European temporary installation specialists. Distribution runs through cooperative purchasing agreements administered by the National Association of State Procurement Officials and fragmented municipal procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The speed bumps and humps market functions as a service-attach opportunity where rental-model revenue streams for temporary construction-zone deployments expand faster than capital purchase hardware cycles. Recurring installation and maintenance contracts embedded in original equipment agreements capture margin pools that transactional product sales cannot access.
For Market Incumbents: Pre-empt specification displacement by embedding sensor technology into polymer humps before Dutch and Scandinavian pilot contracts scale to broader municipal adoption. Deepen civil contractor partnerships to secure bonding capacity for permanent infrastructure contracts that lock out smaller competitors. Defend against asphalt composite substitution by documenting total cost of ownership advantages in cooperative purchasing agreement frameworks. For New Entrants and Emerging Players: Establish a beachhead in United Kingdom municipal procurement by securing BSI PAS 3003 certification before recycled rubber performance validation requirements harden into mandatory specifications. Target construction-zone temporary demand channels where highway maintenance outsourcing creates recurring rental-model revenue streams distinct from traditional capital purchase cycles. Pursue go-to-market positioning through cooperative purchasing agreement pre-qualification rather than fragmented distributor relationships. For Investors and Strategic Acquirers: Municipal-bonding-capable precast concrete specialists with civil contractor integration represent the most defensible acquisition archetype for permanent infrastructure exposure. Long-term viability hinges on positioning for decades-long asset life contracts as municipalities abandon lowest-bid awards for total cost of ownership frameworks. Watch for MUTCD geometric standard updates as inflection indicators forcing manufacturer redesign cycles and inventory obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Smart City Sensor Integration | Sensor-embedded polymer humps capture pilot contracts from Dutch and Scandinavian municipal technology departments. |
| Circular Material Certification | BSI PAS 3003 validation advantages early certifiers against uncertified import competition in United Kingdom tenders. |
| Cooperative Purchasing Pre-Qualification | NASPO consolidation marginalizes independent distributors serving fragmented municipal procurement departments. |
| Civil Contractor Partnership Cultivation | Specialized geotechnical expertise secures bonding capacity for permanent infrastructure contracts. |
| Rental Model Revenue Structuring | Highway maintenance outsourcing creates recurring revenue streams distinct from capital purchase cycles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Federal Highway Administration MUTCD documentation, EU Road Infrastructure Safety Directive implementation reports, and municipal procurement database records. Primary interviews engaged municipal traffic engineers, commercial property facility managers, civil contractor procurement leads, and polymer compounder technical directors. Secondary validation drew from BSI PAS 3003 certification registries, KBA technical validation databases, and National Association of State Procurement Officials cooperative agreement disclosures. Bottom-up unit shipment modeling triangulates against top-down municipal infrastructure budget allocation analysis.
Forecast inputs include material substitution elasticity, regulatory compliance cost trajectories, and petroleum feedstock price band assumptions across the projection horizon. Segmentation dimensions span product type, installation permanence, application intensity, and procurement authority concentration. CAGRs derive from regression analysis against historic municipal infrastructure spending patterns and urban densification cluster projections. Industry-specific inputs incorporate MUTCD geometric standard update probability and EU member state risk assessment mandate implementation timelines.
Stress conditions across petroleum price volatility bands, tariff regime shifts, and municipal budget contraction scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory adoption timelines and material substitution thresholds. Macroeconomic contraction, accelerated MUTCD revision cycles, or breakthrough asphalt composite durability improvements would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Automotive Front-End Collision Warning System Market
Automotive Safety and Security Systems
Global Automotive Hill Descent Control Market
Automotive Safety and Security Systems
India Airbag Systems Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Automotive Biometric Identification Market
Automotive Safety and Security Systems
Automotive Anti Lock Braking System and Electronic Stability Control Market
Automotive Safety and Security Systems
Motorcycle Start Stop Systems Market
Automotive Safety and Security Systems
Europe Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Automotive Airbag Inflator Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market
Automotive Safety and Security Systems
Smart Motorcycle Helmet Market
Automotive Safety and Security Systems
Air Brake System Market
Automotive Safety and Security Systems
Traffic Jam Assist (TJA) Market
Automotive Safety and Security Systems
Latin America Airbag Systems Market