
 Automotive Crash Barriers Market | 2026-2036
Automotive Crash Barriers Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Crash Barriers Market Analysis
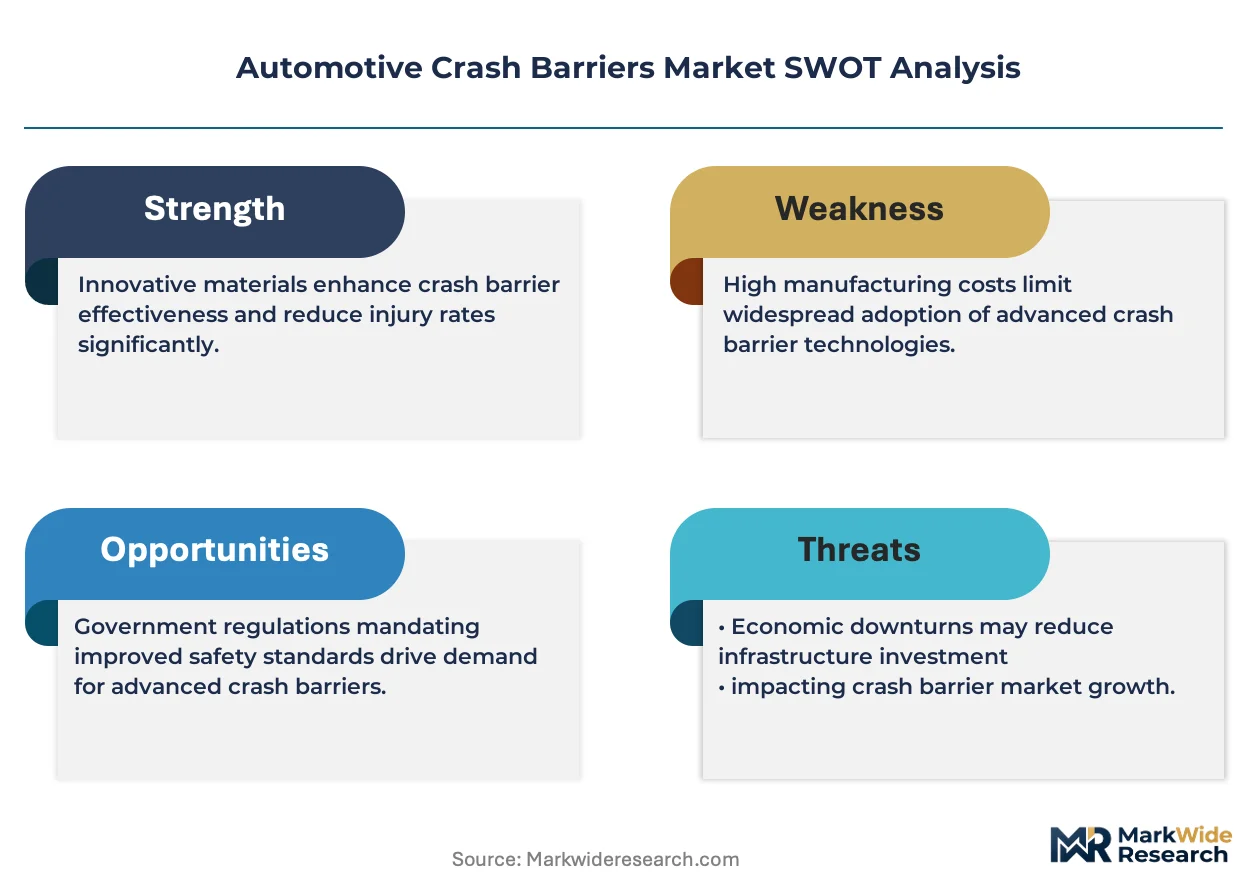
The gap between premium MASH-tested systems and commodity metal guardrails is repositioning procurement criteria across developed road networks. Trinity Industries leverages in-house galvanizing capacity to sustain price competitiveness on high-volume highway contracts. N.V. Bekaert SA anchors its position through specialized wire rope technology for flexible barrier systems. Valmont Industries differentiates via integrated coating and fabrication operations that control lead times on custom barrier profiles.
Automotive crash barriers are engineered roadside safety structures designed to contain or redirect errant vehicles through controlled deformation, typically fabricated from galvanized steel W-beams, reinforced concrete, or high-density polyethylene modules rated to specific impact force thresholds. Their primary purpose is to reduce occupant injury severity and protect roadside hazards including bridge piers, median crossings, and work zones. Metal barriers dominate installed base value due to decades of DOT specification entrenchment, while flexible wire rope systems capture the fastest growth trajectory as European transportation authorities prioritize narrow-median solutions with reduced foundation requirements. Water-filled barriers occupy the temporary installation segment where construction zone mobility demands rapid deployment and relocation cycles.
The Federal Highway Administration enforces MASH compliance for all new federal-aid projects, creating a de facto technical barrier for non-certified suppliers seeking access to US transportation authority contracts. EMA-equivalent frameworks and EN 1317 crash-test protocols govern European product approval, while India's BIS certification requirements under Ministry of Road Transport directives shape supplier qualification for subcontinent expressway programs. Stakeholders must monitor evolving test-speed elevations and material circularity mandates that will determine which fabrication investments retain regulatory relevance through the forecast horizon.
Market Dynamics
Federal MASH compliance mandates in the United States and EU Green Deal circularity requirements are bifurcating supplier capabilities, forcing capital reallocation toward certified testing facilities and closed-loop material recovery systems.
Growth Catalysts
- Federal-Aid Highway Program:The FHWA's MASH compliance requirement for all new projects creates guaranteed demand for certified energy-absorbing systems. State DOTs in Texas, California, and Florida are consolidating procurement around pre-qualified vendor pools.
- EU Green Deal steel recycling mandates:Circular economy frameworks require minimum recycled content thresholds in infrastructure metals, redirecting galvanizing investments toward electric-arc furnace feedstock integration.
- Expressway expansion in China:The Ministry of Transport's 14th Five-Year Plan prioritizes median barrier installation on mountainous corridors, sustaining import demand for high-tensile wire rope assemblies.
Market Restraints
- Zinc price volatility:Hot-dip galvanizing costs fluctuate with London Metal Exchange zinc futures, compressing margins on fixed-price highway contracts with 18-24 month delivery horizons.
- Testing facility concentration:Full-scale vehicle crash testing for MASH certification is available at only three North American sites, creating bottlenecks for new market entrants.
- Concrete barrier substitution:Precast reinforced concrete median systems retain specification preference on low-speed urban arterials where maintenance access is limited.
Strategic Opportunities
- India's Bharatmala expressway program:Ministry of Road Transport directives mandate 35,000 kilometers of new access-controlled highway, generating demand for BIS-certified flexible barrier systems.
- Smart highway integration:Embedding fiber-optic strain sensors within polymer-composite modules enables real-time impact detection and predictive maintenance scheduling.
- Work-zone mobility contracts:State DOTs are shifting temporary barrier procurement from purchase to lease models, favoring suppliers with regional depot networks for rapid deployment cycles.
Industry Challenges
- Welding technician scarcity:Galvanized steel fabrication requires AWS-certified welders skilled in low-hydrogen electrode techniques, with training pipelines failing to match retirement rates in the Upper Midwest.
- MASH 2016 test-speed elevations:The 110 km/h design vehicle criteria demand heavier foundation anchoring, extending civil engineering review timelines and delaying project closeouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Crash Barriers Market |
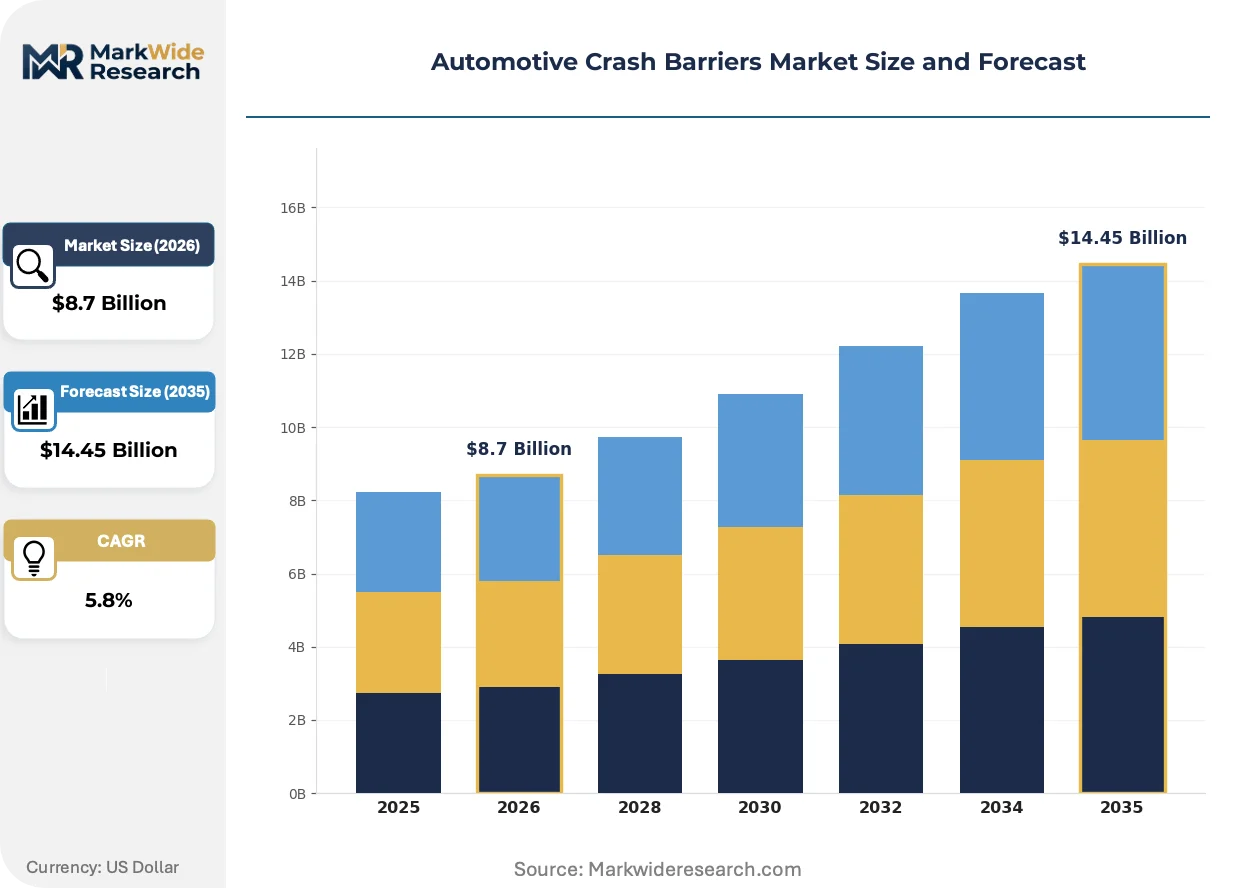
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete Barriers, Metal Barriers, Water-Filled Barriers, Flexible Barriers Installation Type: Permanent Installation, Temporary Installation, Removable Installation, Modular Installation End User: Government Agencies, Construction Companies, Transportation Authorities, Private Sector Compliance Standard: EN Standard, NCHRP Standard, MASH Compliance, Local Regulations |
| Companies Covered | Lindsay Corporation, N.V. Bekaert SA, Tata Steel, Transpo Industries, Trinity Industries, Valmont Industries, Nucor Corporation, RoadSafe Traffic Systems, Hill and Smith Holdings PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Crash Barriers Market Emerging Trajectories
Material science advances and procurement digitization are compressing product development cycles while elevating performance verification standards across federal and state transportation authorities.
Polymer-composite crash cushions containing high-density polyethylene cores with steel reinforcement cages are absorbing impact energy through controlled deformation rather than fragmentation. State DOT maintenance divisions in Arizona and Nevada are specifying these systems for high-frequency collision zones where repair labor costs exceed material replacement. The technology is absorbing market share from traditional sand-filled barrel arrays by reducing lane closure duration from six hours to ninety minutes.
EMA-equivalent testing protocols under EN 1317 are mandating narrower working widths for flexible barriers installed on European motorways with constrained medians. German transportation authorities through KBA oversight are rejecting legacy wire rope systems that exceed 1.3 meter dynamic deflection. Manufacturers are responding with hybrid tensioned-cable designs that integrate composite posts to reduce foundation concrete volumes by forty percent.
Buyers are consolidating vendor relationships around integrated coating-fabrication-testing capabilities, displacing fragmented supply chains where galvanizing, forming, and certification were sourced separately. Large highway contractors in the United States are awarding multi-year blanket purchase agreements to single-source suppliers with captive MASH testing partnerships. This concentration is most visible in the Southwest, where Texas and Arizona DOTs have reduced qualified bidders from twelve to four on major corridor projects.
Automotive Crash Barriers Market Segmentation
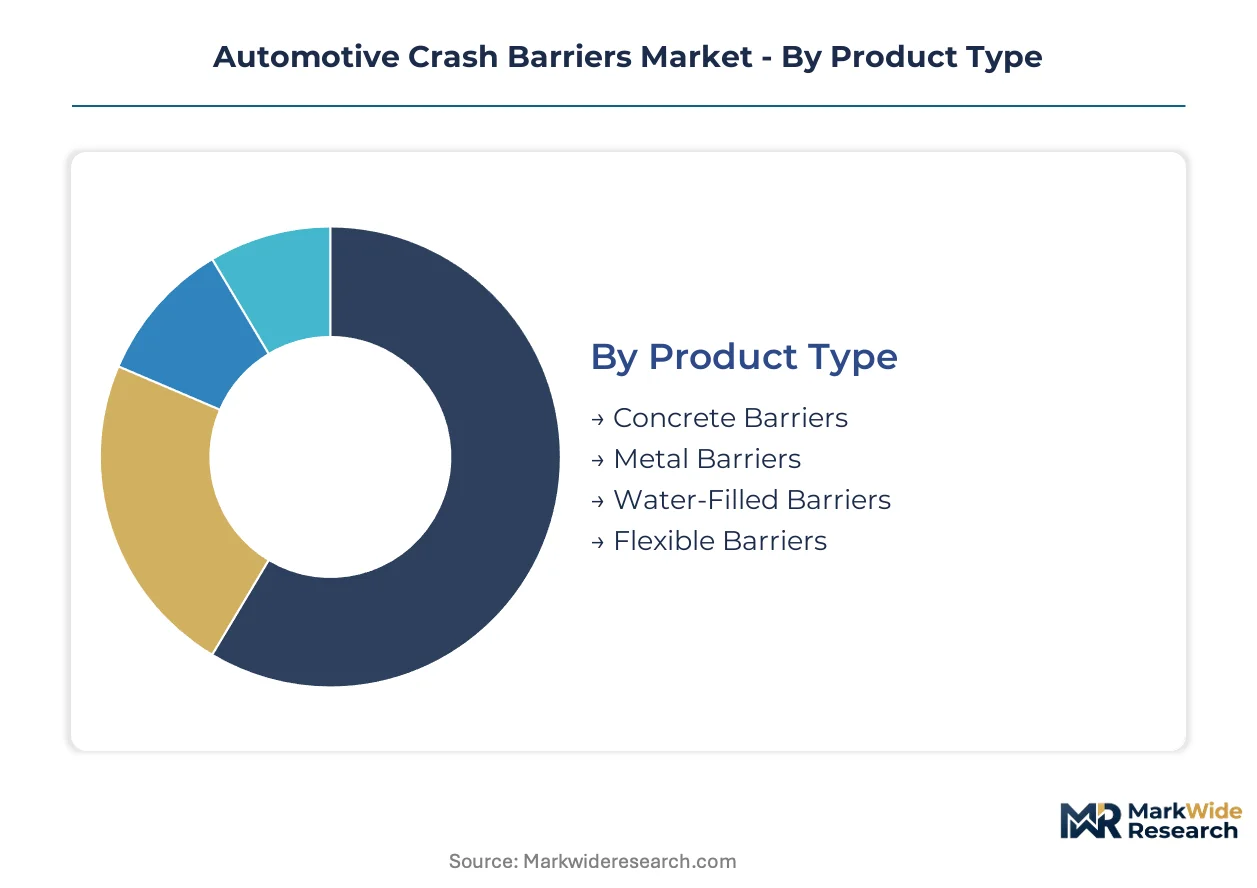
Barrier specification varies sharply by deployment duration, impact severity, and regulatory jurisdiction. Procurement officers weigh life-cycle cost against crash-test performance tiers when allocating federal highway budgets across product categories.
Product Type:
Standardization dominates commodity metal systems while concrete and flexible designs demand project-specific engineering customization.
- Metal Barriers:Galvanized steel W-beam and thrie-beam configurations dominate federal-aid highway installations. Texas DOT and Caltrans specify these for high-speed corridors where MASH compliance is mandatory. Zinc coating thickness and post-spacing calculations determine field performance.
- Flexible Barriers:Tensioned wire rope systems with energy-absorbing terminals reduce foundation concrete by half versus rigid alternatives. German KBA approval requirements are narrowing acceptable dynamic deflection windows, favoring hybrid cable-composite post designs on constrained European medians.
- Concrete Barriers:Precast reinforced units specified for low-speed urban arterials with limited maintenance access.
- Water-Filled Barriers:High-density polyethylene modules for construction zone mobility and rapid redeployment cycles.
Most installed capacity flows through metal barriers. Expansion is steepest in flexible barriers.
Installation Type:
Duration of deployment determines foundation engineering intensity and material selection across this category.
- Permanent Installation:Driven steel posts with reinforced concrete footings anchor metal and flexible systems for 30-year design lives. FHWA mandates these for interstate medians and bridge approaches. Geotechnical surveys dictate embedment depths in rocky or flood-prone terrain.
- Temporary Installation:Water-filled and surface-mounted modular units deploy without excavation. State DOTs in Arizona and Nevada lease these for work-zone contracts where lane closure windows compress to overnight hours.
- Removable Installation:Bolted baseplate systems for reversible lane configurations and special event management.
- Modular Installation:Interlocking polymer-composite segments enabling rapid reconfiguration.
Permanent systems absorb the majority of capital expenditure. Modular formats are climbing the fastest as smart highway integration demands adaptable infrastructure.
End User:
Budget scale and technical specification authority separate large public programs from fragmented private procurement.
- Government Agencies:Federal and state transportation departments consolidate demand through multi-year blanket purchase agreements. FHWA oversight ensures MASH compliance across all federal-aid projects. Procurement volumes concentrate in Texas, California, and Florida DOTs.
- Transportation Authorities:Turnpike commissions and regional mobility agencies operate under distinct funding mechanisms with accelerated project timelines.
- Construction Companies:Prime contractors source temporary barriers through lease arrangements with regional depot networks.
- Private Sector:Industrial facilities and commercial developments specify barriers for parking structure and perimeter protection.
Government agencies command the largest contract values. Transportation authorities are gaining share fastest through public-private delivery models.
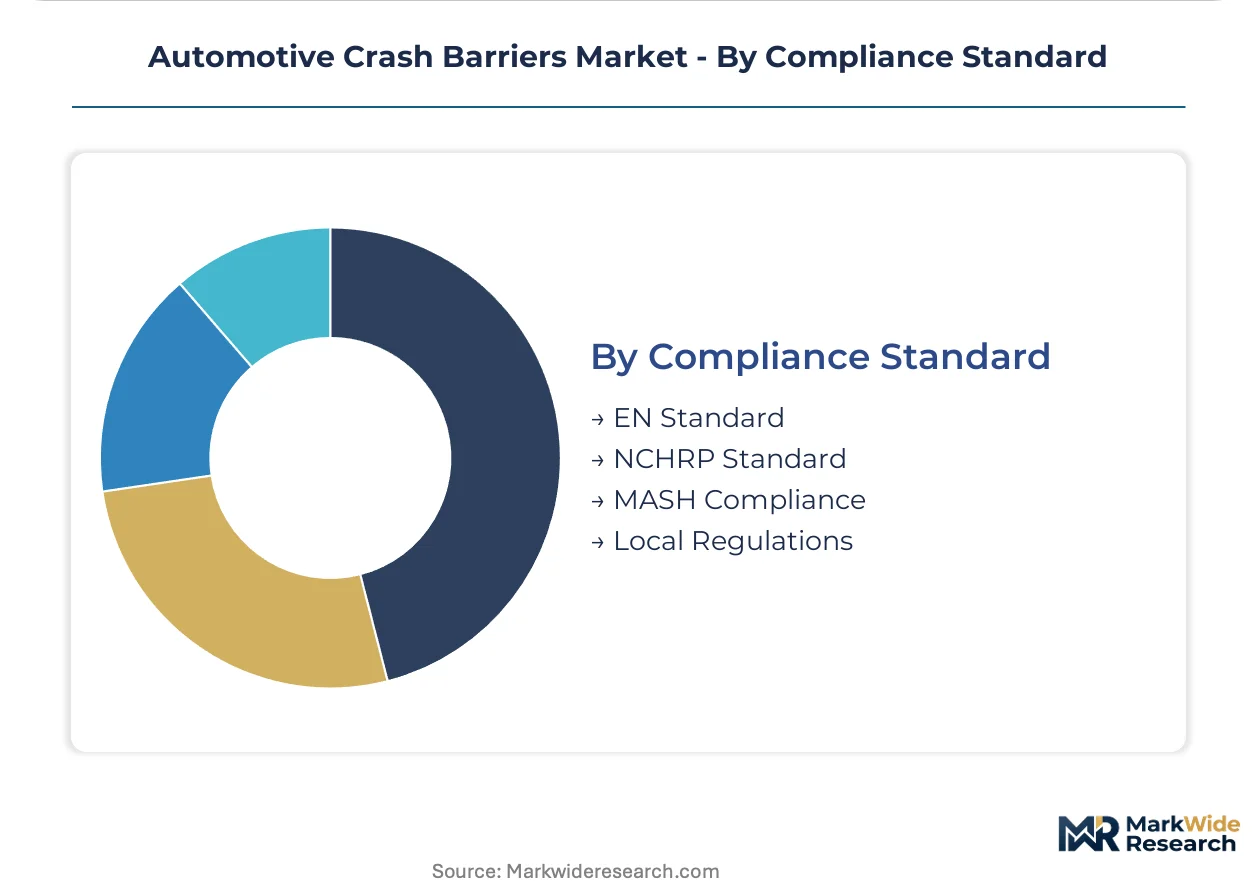
Compliance Standard:
Regulatory fragmentation forces suppliers to maintain parallel certification portfolios for cross-border project participation.
- MASH Compliance:The FHWA mandates this US testing protocol for all federal-aid highway barriers. Full-scale vehicle crash testing at 110 km/h design speeds creates technical barriers for uncertified suppliers. Only three North American facilities conduct validation.
- EN Standard:European EN 1317 protocols govern working width and containment levels on EU motorways. EMA-equivalent testing is mandatory for KBA approval in Germany.
- NCHRP Standard:Legacy US guidelines still referenced in some state specifications during transition periods.
- Local Regulations:India's BIS certification under Ministry of Road Transport directives shapes supplier qualification for Bharatmala expressway segments.
MASH certification unlocks the largest addressable contract pool. EN Standard alignment is expanding most quickly as EU Green Deal circularity mandates redirect supplier investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled welding technicians and AWS-certified fabricators concentrate in the Upper Midwest and industrial belts of Germany, creating regional supply advantages for galvanized steel barrier production.
United States
State DOTs in Texas, California, and Florida drive procurement volumes through multi-year blanket purchase agreements. The FHWA enforces MASH compliance for all federal-aid highway projects, filtering supplier access. Fabrication clusters in Dallas-Fort Worth and Chicago supply galvanized W-beam systems to interstate corridor programs.
Germany
The KBA oversees EMA-equivalent testing protocols that narrow acceptable dynamic deflection windows for flexible barriers. The EU Green Deal mandates steel recycling thresholds, redirecting galvanizing investments toward electric-arc furnace feedstock. Industrial concentration in the Ruhr Valley and Baden-Württemberg supports precision wire rope manufacturing for narrow-median motorway installations.
China
The Ministry of Transport's 14th Five-Year Plan prioritizes median barrier deployment across mountainous expressway corridors. BIS certification requirements shape supplier qualification for Bharatmala-linked import demand. Manufacturing clusters in Jiangsu and Shandong provinces produce high-tensile wire rope assemblies for domestic and export markets.
India
The Bharatmala expressway program mandates 35,000 kilometers of new access-controlled highway with BIS-certified flexible barrier systems. Ministry of Road Transport directives enforce crash-test standards for subcontinent expressway segments. Fabrication activity concentrates in Maharashtra and Gujarat, where steel rolling capacity serves western and southern corridor projects.
Automotive Crash Barriers Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated supplier base. Integrated fabricators with captive galvanizing and coating operations dominate high-volume highway contracts, while specialized wire rope technology providers capture premium flexible barrier segments. Three archetypes define competitive positioning: integrated steel-coating-fabrication conglomerates, tensioned-cable technology specialists, and regional temporary barrier lessors. Capacity expansion into certified testing partnerships and backward integration into zinc recovery systems represent the dominant competitive moves.
Within the integrated fabrication tier, Trinity Industries and Valmont Industries exemplify scale-driven positioning through combined coating and forming operations. N.V. Bekaert SA occupies a distinct specialist position anchored in wire rope technology for flexible barrier systems. These three companies represent divergent strategic postures—steel-centric integration, multi-process fabrication control, and materials science specialization—without implying specific market share rankings or operational details beyond their visible industry presence.
| Leading Market Players |
|---|
| Lindsay Corporation |
| N.V. Bekaert SA |
| Tata Steel |
| Transpo Industries |
| Trinity Industries |
| Valmont Industries |
| Nucor Corporation |
| RoadSafe Traffic Systems |
| Hill and Smith Holdings PLC |
| Others |
Supply Flow & Price Mechanics
FHWA MASH compliance mandates for federal-aid highway projects are compressing supplier pools and forcing capital-intensive certification investments that reshape pricing power toward integrated fabricators with captive testing partnerships. State DOT consolidation around pre-qualified vendor pools in Texas, California, and Florida amplifies this concentration, elevating procurement leverage for multi-process operators while marginalizing fragmented suppliers lacking in-house galvanizing or coating capabilities.
Pricing Analysis
Bundled coating-fabrication-testing services command premium positioning against unbundled component sourcing, with three-tier pricing structure across premium, standard, and economy levels separating MASH-certified systems from legacy NCHRP-compliant alternatives and commodity metal guardrails. Price differentiation hinges on certification tier and geographic delivery cost, with zinc price volatility exerting downward pressure on fixed-price highway contracts. Government agencies exhibit lowest price sensitivity given life-cycle cost mandates, while construction companies leasing temporary barriers prioritize per-unit economy.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth, Chicago, and the Ruhr Valley anchor hub-and-spoke patterns for galvanized steel barrier delivery to interstate corridor programs. Manufacturing concentrates in the United States, Germany, and China, with raw material flows drawing from zinc refining capacity, high-tensile steel rolling mills, and polymer resin suppliers. Single-source vulnerability around MASH testing facilities—only three North American sites conduct full-scale validation—creates bottleneck risk. Distribution runs through state DOT procurement offices and prime contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive crash barriers market functions as a stable compounder, with federal highway safety budgets and expressway expansion programs sustaining predictable demand cycles regardless of economic volatility.
For Market Incumbents: Cement market position through backward integration into electric-arc furnace feedstock systems to meet EU Green Deal recycling thresholds, while acquiring captive MASH testing partnerships to lock out uncertified competitors. Polymer-composite substitution in high-frequency collision zones threatens traditional metal barrier volumes, demanding R&D investment in hybrid cable-composite post designs.
For New Entrants and Emerging Players: Fiber-optic strain sensor integration for smart highway impact detection offers technology-first wedge into predictive maintenance contracts with transportation authorities. India's Bharatmala program presents the most penetrable geography, with BIS certification requirements still evolving and domestic fabrication capacity insufficient for 35,000 kilometers of planned expressway. Target state DOT work-zone mobility lease contracts as the go-to-market angle, bypassing capital-intensive permanent installation barriers.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized wire rope technology providers holding KBA-approved narrow-median designs for constrained European motorway applications. The five-to-ten year viability window favors asset-light designers with certification moats over commodity metal fabricators facing zinc margin compression. Watch MASH test-speed elevation announcements as the inflection signal for foundation engineering intensity and supplier consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| MASH Certification Partnership | Captive testing access filters competition for FHWA federal-aid contracts. |
| Electric-Arc Furnace Integration | Closed-loop steel recycling satisfies EU Green Deal circularity mandates. |
| Smart Highway Sensor Embedding | Fiber-optic strain detection enables predictive maintenance revenue streams. |
| Regional Depot Network Expansion | Lease-model temporary barrier deployment captures work-zone mobility demand. |
| Hybrid Cable-Composite Development | Reduced foundation concrete volumes meet German KBA deflection standards. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with state DOT procurement officers, highway contractor project managers, steel fabrication plant engineers, and wire rope manufacturing technical directors with secondary validation. Secondary sources include FHWA MASH compliance filings, EN 1317 test protocol documentation, EU Green Deal circular economy framework texts, and Ministry of Transport five-year plan publications. Bottom-up project pipeline aggregation and top-down infrastructure budget allocation analysis triangulate volume estimates.
Rate-of-change decomposition separates volume growth from price evolution across the analysis window, with segmentation modeling across product type, installation duration, end-user category, and compliance standard dimensions. CAGRs derive from infrastructure budget trajectory analysis and expressway kilometer expansion targets. Forecast inputs incorporate zinc price futures curves, welding technician pipeline data from AWS certification records, and state DOT vendor pool consolidation trends.
The model holds under steady federal and state highway funding commitments; deviation in infrastructure stimulus cycles or MASH test-speed elevation timing would shift capacity utilization assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Video Event Data Recorder Market
Automotive Safety and Security Systems
Automotive Mirror System Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Africa Vehicle Tracking System Market
Automotive Safety and Security Systems
Automotive Airbag Silicone Market
Automotive Safety and Security Systems
Automotive Driver Drowsiness Detection System Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Germany Traffic Sign Recognition Market
Automotive Safety and Security Systems
China Traffic Sign Recognition Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
Pedestrian Protection System Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Stolen Vehicle Recovery (SVR) Tracking Service Market