
 Electromagnetic Clutches Market | 2026-2036
Electromagnetic Clutches Market Size, Share, and Industry Trends Forecast 2026-2036
Electromagnetic Clutches Market Insights
Skilled electromechanical technician availability is collapsing across Midwestern US manufacturing zones, forcing clutch suppliers to automate final assembly and testing lines. Mitsubishi Electric leverages captive motor-controller integration to anchor premium positioning in precision torque applications. Ogura Clutch specializes in compact multidisc configurations for robotics OEMs, while Kendrion sustains European market presence through automotive electromagnetic brake-clutch combinations.
Electromagnetic clutches are torque transmission devices utilizing electrically actuated magnetic fields to engage and disengage mechanical power flow, typically operating at coil voltages from 12V to 400V DC with response times under 50 milliseconds for precision cycle control. Their primary industrial purpose is enabling automated start-stop indexing, overload protection, and synchronized drive control in machinery where mechanical linkage replacement would sacrifice speed or accuracy. Single disc variants dominate volume shipments in cost-sensitive automotive auxiliary drives, while multidisc and tapered configurations capture margin pools in aerospace and high-cycle industrial robotics where heat dissipation and axial compactness command premium pricing. Wrap spring electromagnetic clutches occupy a mature niche in packaging and printing machinery, competing primarily on replacement cycle predictability rather than performance differentiation.
NHTSA Federal Motor Vehicle Safety Standards and EPA industrial energy efficiency regulations jointly shape electromagnetic clutch specifications in US automotive and manufacturing end markets, mandating fail-safe disengagement and minimum efficiency thresholds that favor electronically controlled designs over mechanical alternatives. ISO 9001 and IEC 60947 quality frameworks govern international supplier qualification, creating certification barriers for new entrants in aerospace and medical device torque control segments. Stakeholders must monitor how EPA industrial electrification timelines and evolving ISO electromagnetic compatibility standards reshape coil insulation and thermal management requirements across the supplier base.
Market Dynamics
Automotive electrification and industrial automation are compressing clutch cycle times while demanding higher thermal endurance, forcing manufacturers to redesign coil insulation systems and magnetic circuit geometries for sustained high-frequency engagement.
Growth Catalysts
- NHTSA braking safety mandates:Fail-safe disengagement requirements in US commercial vehicles are accelerating electronically controlled clutch adoption over mechanical alternatives in heavy-duty transmission systems.
- Precision engineering corridors:Germany's robotics and CNC machinery clusters are sourcing high-reliability multidisc assemblies for synchronized motion control in automated production lines.
- Material handling automation:Warehouse robotics OEMs are specifying compact electromagnetic clutches for indexing conveyors and automated guided vehicle drive systems.
Market Restraints
- Copper and rare earth magnet volatility:Coil winding materials and permanent magnet components face price instability from concentrated mining operations in specific geographic zones.
- Skilled technician scarcity:Midwestern US manufacturing zones report collapsing availability of electromechanical specialists capable of precision assembly and magnetic field calibration.
- Mechanical clutch substitution:Pneumatic and hydraulic torque limiters retain cost advantages in low-cycle, high-torque agricultural and mining equipment applications.
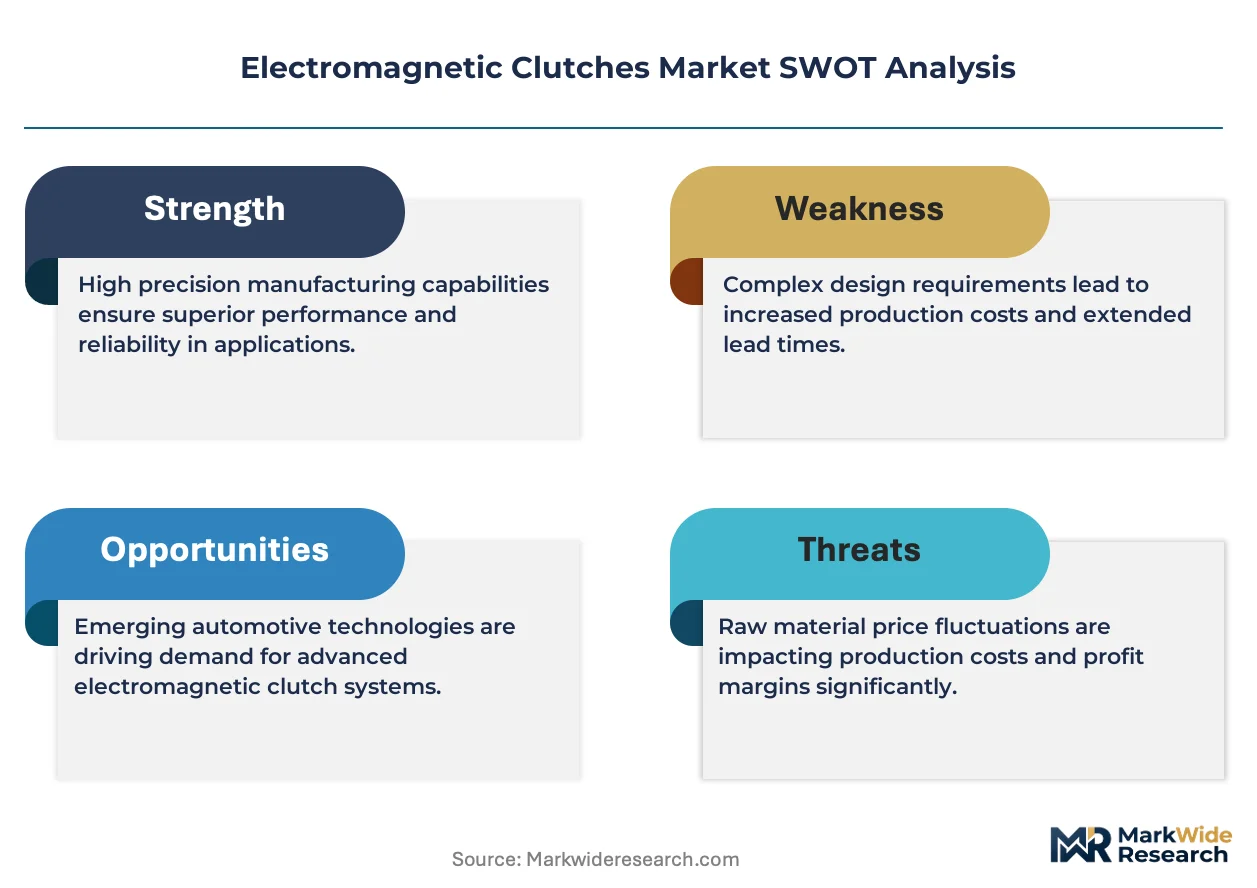
Strategic Opportunities
- EPA industrial electrification timelines:Efficiency mandates are creating specification windows for electronically modulated clutches that minimize standby energy losses in continuous-duty machinery.
- Aerospace thermal management:Tapered and multidisc configurations command premium positioning where axial compactness and heat dissipation determine airframe system integration feasibility.
- Medical device torque control:IEC 60947 certification pathways open surgical robotics and diagnostic imaging equipment to qualified electromagnetic clutch suppliers.
Industry Challenges
- ISO electromagnetic compatibility evolution:Coil insulation standards are tightening faster than supplier qualification timelines can accommodate, delaying product certification cycles.
- Legacy system integration friction:Retrofitting electronically controlled clutches into mechanical drive trains requires custom adapter engineering and extended validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electromagnetic Clutches Market |
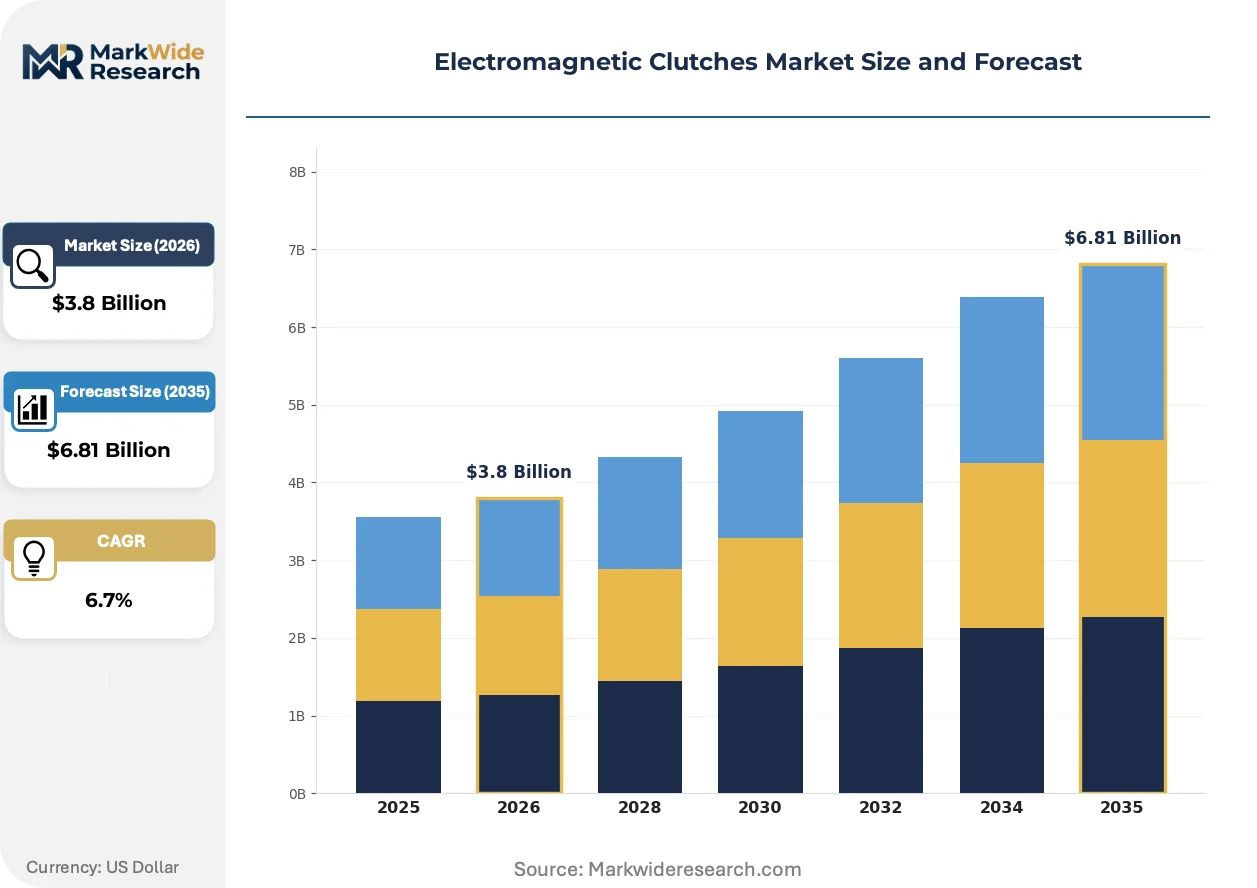
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Disc, Multidisc, Wrap Spring, Tapered Application: Automotive, Industrial Machinery, Marine, Aerospace End User: OEMs, Aftermarket Providers, Parts Distributors, Repair Services Installation: Direct Mounting, Remote Mounting, Inline, Modular |
| Companies Covered | Altra Industrial Motion, Mitsubishi Electric, Miki Pulley, Ogura Clutch, Karl E. Brinkmann, Minebea, Osaki, Danaher, Kendrion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electromagnetic Clutches Market Trends and Innovations
Torque transmission architecture is pivoting toward electronically modulated engagement systems that replace mechanical linkages with software-defined control boundaries. This shift compresses response latencies while expanding programmable safety interlocks.
Integrated motor-clutch-controller modules are supplanting discrete component assemblies in precision robotics and semiconductor manufacturing equipment. Japanese and German automation OEMs are specifying these consolidated subsystems for indexing tables and wafer handling robots. The consolidation is compressing supplier margins on standalone clutch sales while rewarding captive motor-controller integration capabilities.
REACH substance restrictions and evolving RoHS directives in Europe are phasing out specific coil insulation chemistries and bearing lubricants in electromagnetic clutch production. Manufacturers serving EU automotive and industrial markets are reformulating material specifications and requalifying supply chains. German clutch suppliers report accelerated R&D spending on halogen-free insulation systems to maintain CE marking compliance.
Specification authority is migrating from maintenance departments to procurement teams with total cost-of-ownership mandates. Industrial buyers are unbundling clutch replacement cycles from OEM service contracts and negotiating direct supplier relationships for aftermarket inventory. This pattern is most pronounced in North American automotive assembly plants and automated distribution centers where uptime metrics dominate supplier selection criteria.
Electromagnetic Clutches Market Segmentation
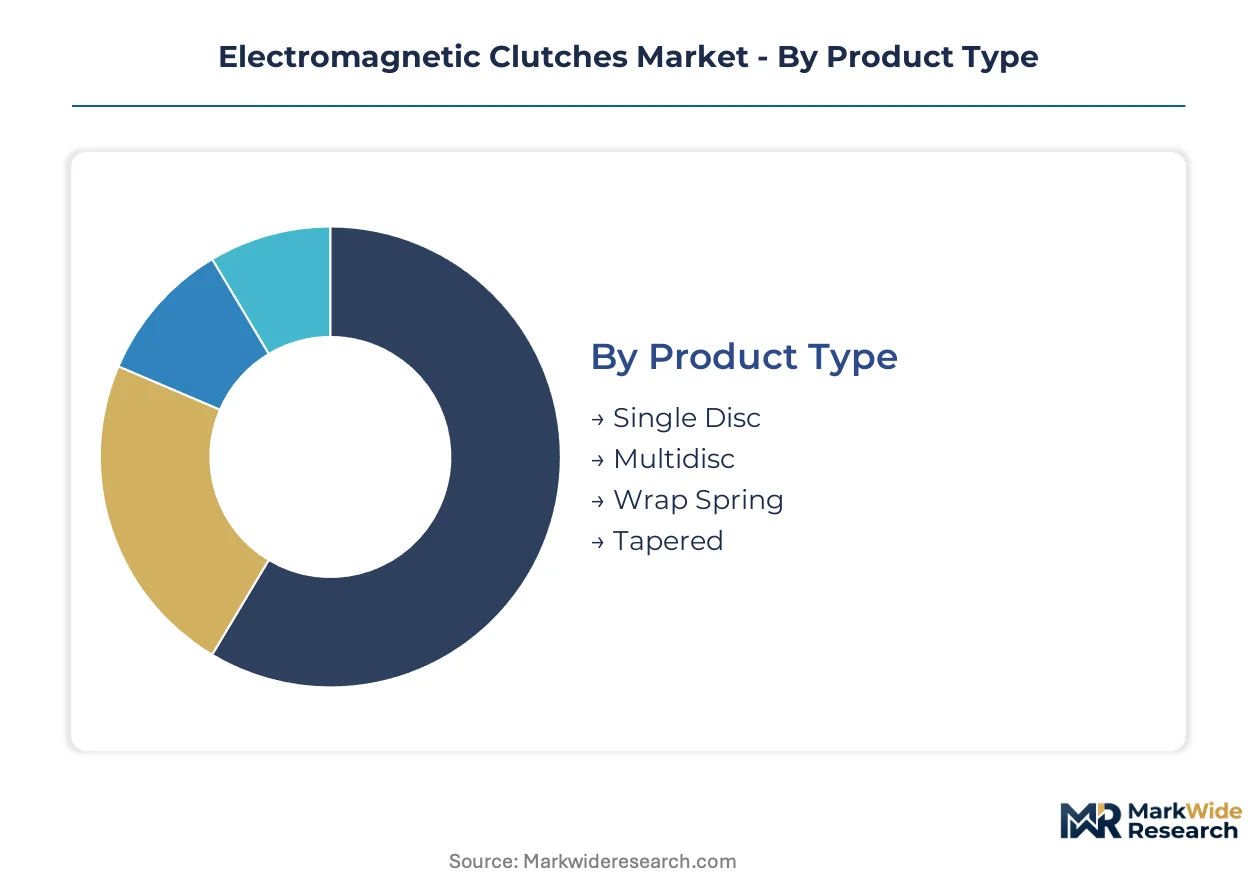
Electromagnetic clutch segmentation reflects divergent technical requirements across torque transmission applications. Product architecture, installation constraints, and procurement channel preferences each reshape supplier positioning and margin capture opportunities.
Product Type:
Single disc configurations face the most intense substitution pressure from pneumatic torque limiters in cost-sensitive agricultural equipment, while multidisc and tapered variants defend their positioning through thermal performance advantages that mechanical alternatives cannot replicate.
- Single Disc:These clutches utilize a single friction plate between armature and rotor assemblies, typically rated for torque transmission up to 500 Nm with coil voltages spanning 12V to 48V DC. Automotive auxiliary drives in US commercial vehicle manufacturing concentrate demand here, though EPA standby efficiency standards are forcing coil redesigns to minimize parasitic losses during extended idling periods.
- Multidisc:Stacked friction plate architectures multiply torque density within constrained axial envelopes, achieving engagement forces exceeding 2,000 Nm in compact form factors. German robotics OEMs in Stuttgart and Munich precision engineering corridors specify these for CNC indexing tables and automated guided vehicle drive systems where cycle frequency exceeds 100 engagements per hour.
- Wrap Spring:Helical spring mechanisms engage through electromagnetic coil excitation, offering predictable wear characteristics valued in packaging machinery replacement cycles. These occupy mature niches where reliability metrics outweigh response time optimization.
- Tapered:Conical friction surfaces maximize heat dissipation surface area per unit volume, serving aerospace actuator systems where axial compactness and thermal endurance determine airframe integration feasibility.
Single disc architectures anchor the volume base while multidisc configurations gain share at the steepest rate.
Application:
End-use concentration varies sharply by thermal duty cycle and precision requirements, with automotive and industrial machinery absorbing divergent product architectures.
- Automotive:NHTSA fail-safe disengagement mandates in heavy-duty commercial vehicles are compressing mechanical clutch replacement timelines. Electronically controlled electromagnetic designs now dominate Class 8 truck transmission auxiliaries and electric power steering systems where torque response must synchronize with vehicle stability control modules.
- Industrial Machinery:Warehouse automation and semiconductor manufacturing equipment specify compact multidisc assemblies for indexing conveyors and wafer handling robots. Japanese automation OEMs increasingly demand integrated motor-clutch-controller modules rather than discrete components.
- Marine:Salt corrosion resistance requirements favor sealed coil housings and stainless steel friction surfaces in propulsion system clutches. These applications prioritize maintenance accessibility over response time optimization.
- Aerospace:Tapered configurations with ceramic-composite friction materials command premium positioning in flight control actuators and landing gear systems where MIL-STD-810G thermal cycling qualification governs supplier selection.
Automotive applications absorb the highest shipment volumes while aerospace segments sustain the most favorable margin structures.
End User:
Procurement authority migration from maintenance departments to strategic sourcing teams is fragmenting traditional OEM-aftermarket channel relationships.
- OEMs:Original equipment manufacturers specify electromagnetic clutches during initial machinery design, capturing volume discounts through multi-year supply agreements. German automotive tier-1 suppliers increasingly require ISO 9001 and IEC 60947 certification as baseline qualification thresholds.
- Aftermarket Providers:Independent distributors stock replacement inventories for legacy equipment fleets, competing on availability rather than technical specification. Midwestern US manufacturing zones report inventory consolidation among surviving distributors as electromechanical technician scarcity reduces field service capacity.
- Parts Distributors:These intermediaries aggregate demand across fragmented maintenance departments, though direct supplier relationships are eroding their relevance in large automated distribution centers.
- Repair Services:Field service organizations perform clutch replacement and magnetic field recalibration, facing margin compression as OEMs extend predictive maintenance contracts that bundle component replacement.
OEMs dominate specification authority while aftermarket providers face structural compression from direct procurement trends.
Installation:
Mounting configuration selection reflects legacy infrastructure constraints versus greenfield optimization opportunities.
- Direct Mounting:Armature assemblies bolt directly to driven shafts, minimizing backlash and torsional compliance. These dominate new automotive auxiliary drive designs where space constraints preclude intermediate coupling elements.
- Remote Mounting:Coil and friction assemblies separate from primary shaft lines via belt or chain drives, enabling thermal isolation in high-duty-cycle industrial applications. Packaging machinery OEMs favor this architecture for heat-sensitive indexing mechanisms.
- Inline:Shaft-to-shaft configurations integrate within existing drivetrain envelopes, simplifying retrofit installations where mechanical clutch replacement timelines drive procurement decisions.
- Modular:Standardized interface dimensions permit rapid field reconfiguration across multiple machinery platforms, reducing spare parts proliferation in multi-site manufacturing operations.
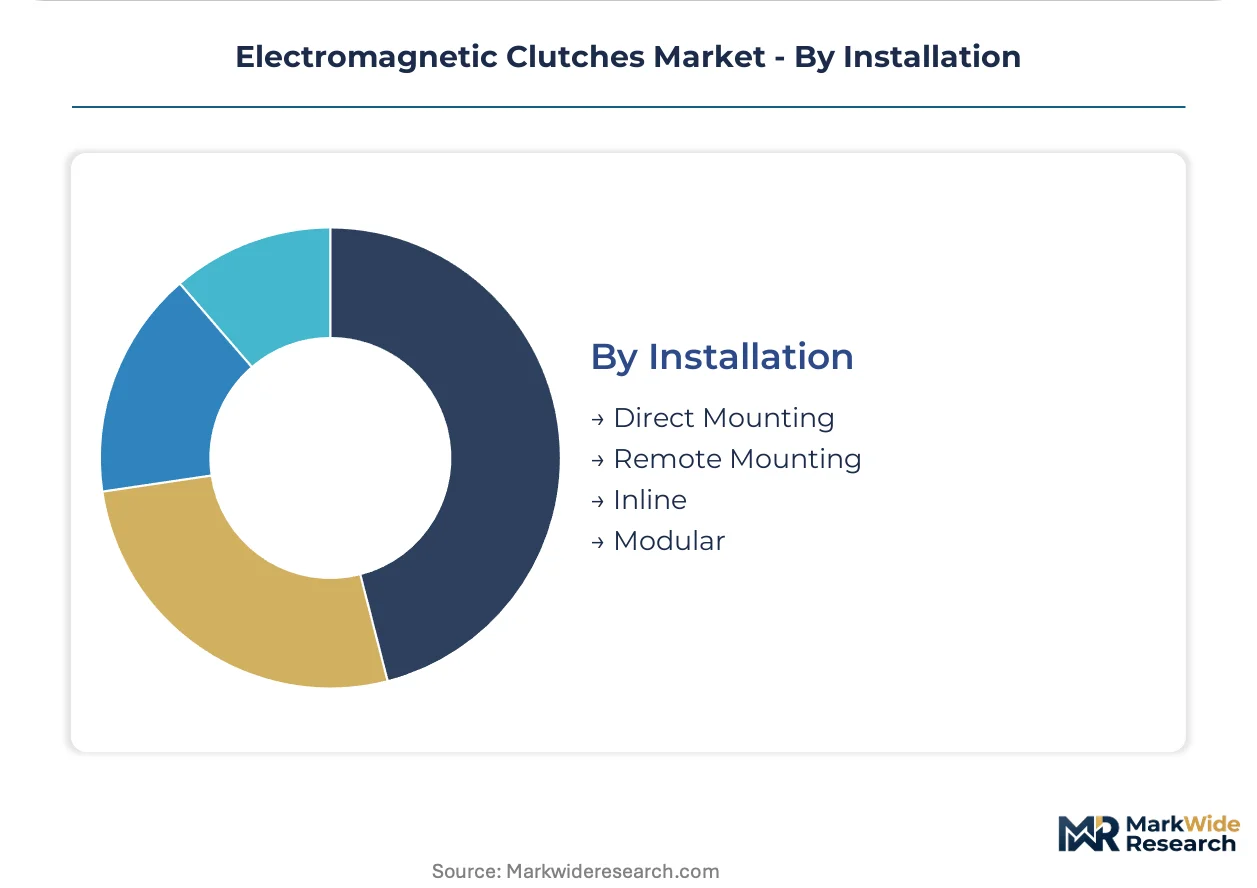
Direct mounting captures the majority of new equipment specifications while modular architectures expand most quickly in distributed manufacturing networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA safety mandates and EPA efficiency standards anchor the United States as the dominant geography shaping electromagnetic clutch specifications and procurement volumes.
United States
Commercial vehicle electrification and automated material handling systems drive clutch demand across Michigan and Ohio manufacturing corridors. NHTSA Federal Motor Vehicle Safety Standards mandate fail-safe disengagement in Class 8 truck transmission auxiliaries. Detroit-area automotive tier-1 suppliers source electronically controlled multidisc assemblies for electric power steering integration.
Germany
Precision engineering clusters in Stuttgart and Munich specify high-reliability clutch assemblies for CNC machinery and robotics integration. REACH substance restrictions and RoHS directives phase out legacy coil insulation chemistries, forcing reformulation investments. Bavarian automation OEMs increasingly demand integrated motor-clutch-controller modules over discrete components.
Japan
Semiconductor manufacturing equipment and warehouse robotics OEMs concentrate demand for compact multidisc configurations with sub-50 millisecond response times. METI industrial efficiency guidelines favor electronically modulated designs that minimize standby energy losses. Nagoya-area fabrication plants supply indexing table mechanisms to Asian electronics assembly networks.
China
Domestic robotics manufacturing and automotive electrification programs expand specification windows for electromagnetic torque control devices. GB standards and MIIT industrial automation directives accelerate substitution of mechanical linkages in production machinery. Yangtze River Delta machinery builders integrate compact clutches into automated guided vehicle drive systems for distribution centers.
South Korea
Electronics contract manufacturing and display panel production equipment sustain demand for precision indexing clutches with high-cycle endurance. MFDS medical device regulations and KOSHA industrial safety standards govern supplier qualification for surgical robotics applications. Seoul Capital Area automation integrators specify tapered configurations for cleanroom wafer handling systems.
Electromagnetic Clutches Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure reflecting divergent technical capabilities across torque density and thermal management vectors. Japanese and German conglomerates anchor premium positioning through captive motor-controller integration, while mid-scale specialists defend niche segments through multidisc compactness or aerospace qualification. Competitive dynamics center on backward integration into coil winding and magnetic circuit fabrication, alongside strategic partnerships with robotics OEMs for integrated subsystem development.
Within the integrated tier, Mitsubishi Electric and Minebea represent archetypes of captive motor-controller capabilities that consolidate specification authority in precision robotics applications. Ogura Clutch occupies a position among compact multidisc specialists serving warehouse automation OEMs with space-constrained drive requirements. Kendrion anchors European market presence through automotive electromagnetic brake-clutch combinations that satisfy German OEM qualification protocols.
| Leading Market Players |
|---|
| Altra Industrial Motion |
| Mitsubishi Electric |
| Miki Pulley |
| Ogura Clutch |
| Karl E. Brinkmann |
| Minebea |
| Osaki |
| Danaher |
| Kendrion |
| Others |
Pricing and Supply Chain Analysis
ISO 9001 and IEC 60947 certification frameworks gate supplier qualification and simultaneously stratify price tiers across the electromagnetic clutch market, forcing uncertified manufacturers into commodity positioning while accredited producers capture premium positioning in aerospace and medical device segments.
Pricing Analysis
German and Japanese suppliers command 15-25% price premiums over North American and Chinese counterparts for equivalent torque ratings, reflecting captive motor-controller integration capabilities and precision engineering reputations. Pricing stratifies across aerospace-qualified, industrial-grade, and automotive-economy tiers, with MIL-STD-810G thermal cycling certification and REACH-compliant insulation systems driving differentiation. Cost compression in single-disc automotive auxiliary drives intensifies as pneumatic torque limiters erode market share in agricultural equipment. Aftermarket distributors exhibit highest price sensitivity, while OEM procurement teams with total cost-of-ownership mandates prioritize reliability metrics over unit cost.
Supply Chain Analysis
Just-in-time coil winding and magnetic circuit fabrication dominates Japanese and German manufacturing corridors, while Chinese suppliers maintain strategic stockpiles of copper magnet wire and rare earth permanent magnets to buffer commodity volatility. Supply concentrates in Germany, Japan, and China for precision-machined armature assemblies, with copper winding materials and neodymium magnet components drawing from concentrated mining operations in Chile and China. Single-source vulnerability in rare earth magnet supply chains exposes tier-2 suppliers to price spikes and export restriction risk. Distribution runs through automotive tier-1 suppliers and industrial automation OEMs rather than fragmented aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromagnetic clutch incumbents face sustained substitution pressure from electronically modulated direct-drive motors and pneumatic torque limiters, requiring defensive capability investments to preserve specification authority in precision robotics and aerospace applications.
For Market Incumbents: Fortify backward integration into coil winding and magnetic circuit fabrication to defend margin pools against modular motor-controller suppliers. Accelerate IEC 60947 and ISO electromagnetic compatibility certification investments ahead of evolving insulation standards. Prioritize captive integration of motor-controller subsystems to anchor specification authority in Japanese and German robotics OEM procurement decisions. For New Entrants and Emerging Players: Lead with aerospace thermal management specialization or medical device torque control certification as unguarded white-space entry points. Target South Korean semiconductor manufacturing equipment and Chinese automated guided vehicle builders where incumbent presence remains underdeveloped. Pursue direct procurement relationships with automated distribution center operators bypassing traditional aftermarket distributor channels. For Investors and Strategic Acquirers: EPA industrial electrification timelines and evolving ISO electromagnetic compatibility standards reshape the acquisition landscape toward suppliers with halogen-free insulation R&D capabilities and established robotics OEM partnerships. Five-to-ten year viability hinges on positioning for electronically modulated clutch substitution of mechanical linkages in continuous-duty machinery. Prioritize acquisition targets with certified aerospace qualification and integrated motor-controller engineering capacity. Monitor NHTSA braking safety mandate implementation velocity as inflection indicator for heavy-duty commercial vehicle clutch demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Winding | Captive supply of magnet wire insulation systems buffers copper price volatility from Chilean mining concentration. |
| Integrated Motor-Controller Module Development | Consolidated subsystems anchor specification authority with Mitsubishi Electric and Minebea in precision robotics. |
| Halogen-Free Insulation R&D Investment | REACH and RoHS compliance maintains CE marking access for German automotive and industrial OEM qualification. |
| Aerospace Thermal Management Specialization | Tapered configurations with ceramic-composite friction materials capture MIL-STD-810G qualified supplier status. |
| Direct Procurement Channel Establishment | Bypassing aftermarket distributors captures total cost-of-ownership mandates from North American automated distribution centers. |
Research Methodology
Desk research of SEC 10-K filings, customs trade databases, and IEC certification registries preceded structured interviews with automotive tier-1 procurement directors, industrial automation OEM platform engineers, and aftermarket service organization heads. Primary fieldwork encompassed maintenance directors at Midwestern US manufacturing plants, robotics integration specialists in Stuttgart and Nagoya precision engineering corridors, and electromagnetic component distribution channel managers. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standards documentation, EPA industrial efficiency regulation filings, and REACH substance restriction updates. Bottom-up shipment data triangulated against top-down manufacturing capacity assessments across the analysis window.
Variance decomposition across product type, application, end user, and installation configuration dimensions shaped the analytical framework for volume and value projections over the projection horizon. CAGRs derived from segment-level growth rate blending weighted by baseline shipment shares. Industry-specific forecast inputs incorporated NHTSA braking safety mandate implementation schedules, EPA industrial electrification timeline milestones, and robotics OEM capital expenditure patterns for integrated motor-clutch-controller modules.
Underlying assumptions cover sustained copper and rare earth magnet supply continuity, stable NHTSA and EPA regulatory enforcement trajectories, and continued German-Japanese robotics OEM preference for precision torque control subsystems, with deviation risk concentrated in ISO electromagnetic compatibility standard acceleration and pneumatic torque limiter substitution in agricultural equipment. Forecasts reflect these documented assumptions. Revision becomes warranted when rare earth export restrictions or coil insulation chemistry bans cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
Tappet Market
Automotive Parts
Argentina Automotive Parts Aluminium Die Casting Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Heavy Duty Engines Market
Automotive Parts
India Automotive Parts Aluminum Die Casting Market
Automotive Parts
Global Automotive Door Hinges Market
Automotive Parts
Europe Passenger Vehicles Lubricants Market
Automotive Parts
Vehicle Transfer Case Market
Automotive Parts
Latin America Automotive Airfilters Market
Automotive Parts
Two-Wheeler Lubricants Market
Automotive Parts
Japan Automotive Parts Zinc Die Casting Market
Automotive Parts
Global Inductive Loop Vehicle Detector Market
Automotive Parts
Europe Motorcycle Parts and Accessories Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
Automotive Brake Shims Market