
 Automotive Rear Spoiler Market | 2026-2036
Automotive Rear Spoiler Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Rear Spoiler Market Analysis
Aftermarket customization revenue is reconfiguring margin pools away from pure component supply toward design-to-install service bundles. Magna International Inc. leverages its integrated stamping and assembly footprint to dominate OEM factory-installed spoiler programs across North American light-truck platforms. Plastic Omnium anchors European supply relationships through its polymer-exterior systems expertise, while SMP Deutschland GmbH specializes in precision blow-molded and thermoformed aerodynamic components for German premium brands.
An automotive rear spoiler is an aerodynamic device mounted to the rear decklid or hatch, typically manufactured from injection-molded ABS plastic, compression-molded carbon fiber prepreg, or hand-laid fiberglass, and engineered to reduce lift coefficient and improve high-speed stability. Carbon fiber variants command premium positioning in sports car and coupe applications where mass reduction justifies material cost escalation, while ABS plastic sustains volume leadership across sedan and SUV segments through thermoform efficiency and paint-integration compatibility. Factory-installed programs capture the dominant value pool as OEMs integrate spoilers into platform aerodynamic strategies, though bolt-on aftermarket channels retain growth velocity among tuning shops pursuing personalized vehicle differentiation.
The EPA Corporate Average Fuel Economy standards and NHTSA safety regulations shape spoiler design through mandated drag-reduction targets and rear-visibility requirements, while EMA emissions frameworks in Europe push OEMs toward active aerodynamic elements that deploy at speed. ISO 9001 and TS 16949 quality certifications govern supplier market access, particularly for carbon fiber suppliers serving German OEMs. Stakeholders must monitor evolving active-aerodynamic integration trends where spoilers merge with deployable wing systems and sensor housings for advanced driver-assistance platforms.
Market Dynamics
Active aerodynamic integration is compressing the traditional boundary between static spoilers and deployable wing systems as OEMs chase drag-reduction targets under tightening emissions frameworks.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Mandated fleet efficiency targets push automakers to factory-install spoilers as standard aerodynamic equipment across sedan and light-truck platforms.
- Carbon fiber prepreg molding:Mass reduction imperatives in Stuttgart and Toyota City production clusters sustain premium material adoption despite cost escalation.
- Aftermarket tuning shops:Personalized vehicle differentiation demand drives bolt-on spoiler revenue velocity outside OEM channels.
Market Restraints
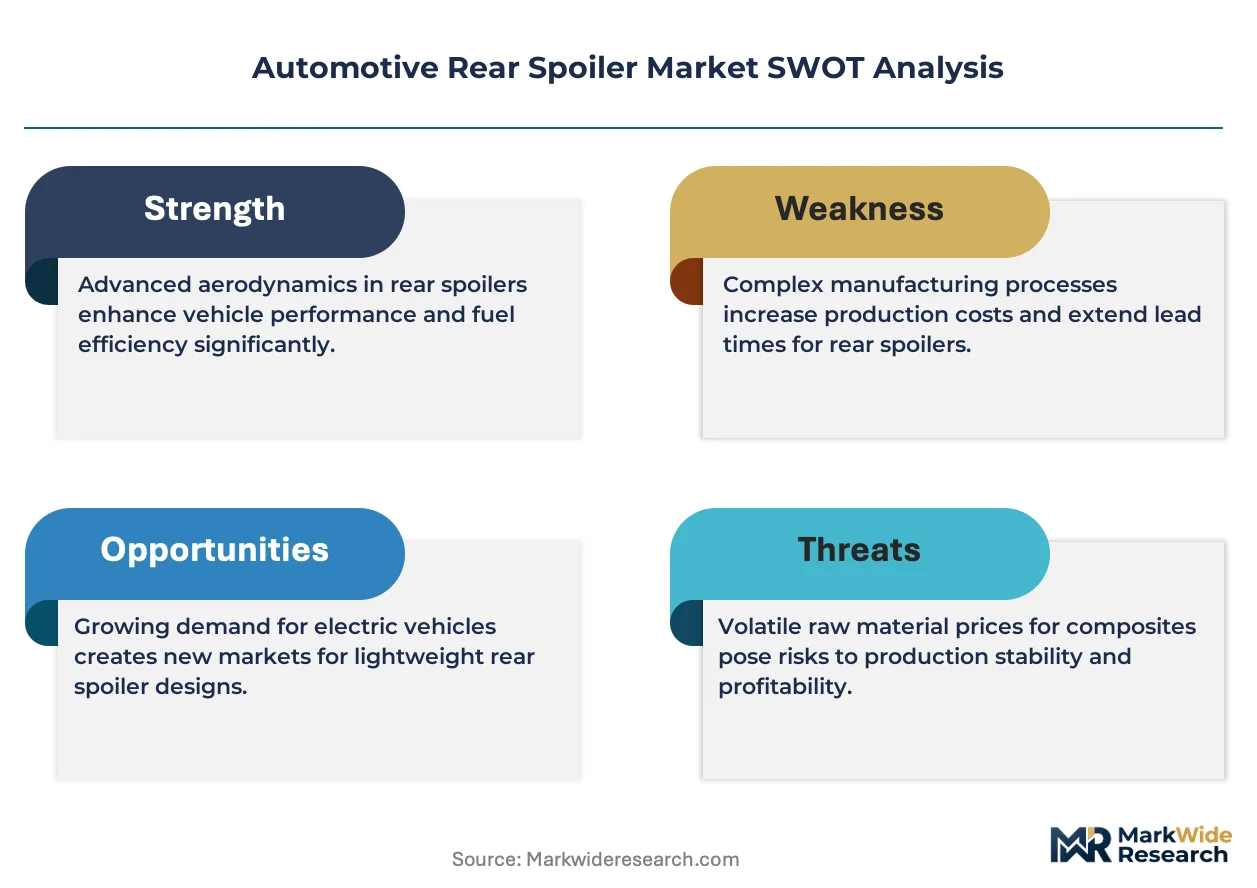
- ABS resin price volatility:Injection-molding feedstock cost swings compress margin pools for volume spoiler suppliers serving mid-market segments.
- German carbon fiber supply concentration:Prepreg manufacturing clusters around Stuttgart create geographic single-point vulnerability for premium OEM programs.
- Rear-visibility regulatory friction:NHTSA safety requirements constrain spoiler height and angle specifications, limiting aerodynamic optimization freedom.
Strategic Opportunities
- Sensor-integrated spoiler housings:Convergence of static aerodynamics with ADAS platform hardware creates new content-per-vehicle expansion vectors.
- EMA active-aerodynamic mandates:European emissions frameworks incentivize deployable elements that retract at low speed, opening electromechanical system revenue.
- Design-to-install service bundles:Aftermarket channels in Japan and Germany capture margin migration from pure component supply toward fitted customization.
Industry Challenges
- TS 16949 certification timelines:German OEM supplier qualification cycles extend 18-24 months, gating market access for new carbon fiber entrants.
- Paint-integration compatibility:Thermoformed ABS surface preparation protocols require capital-intensive robotic finishing lines that strain mid-tier supplier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Rear Spoiler Market |
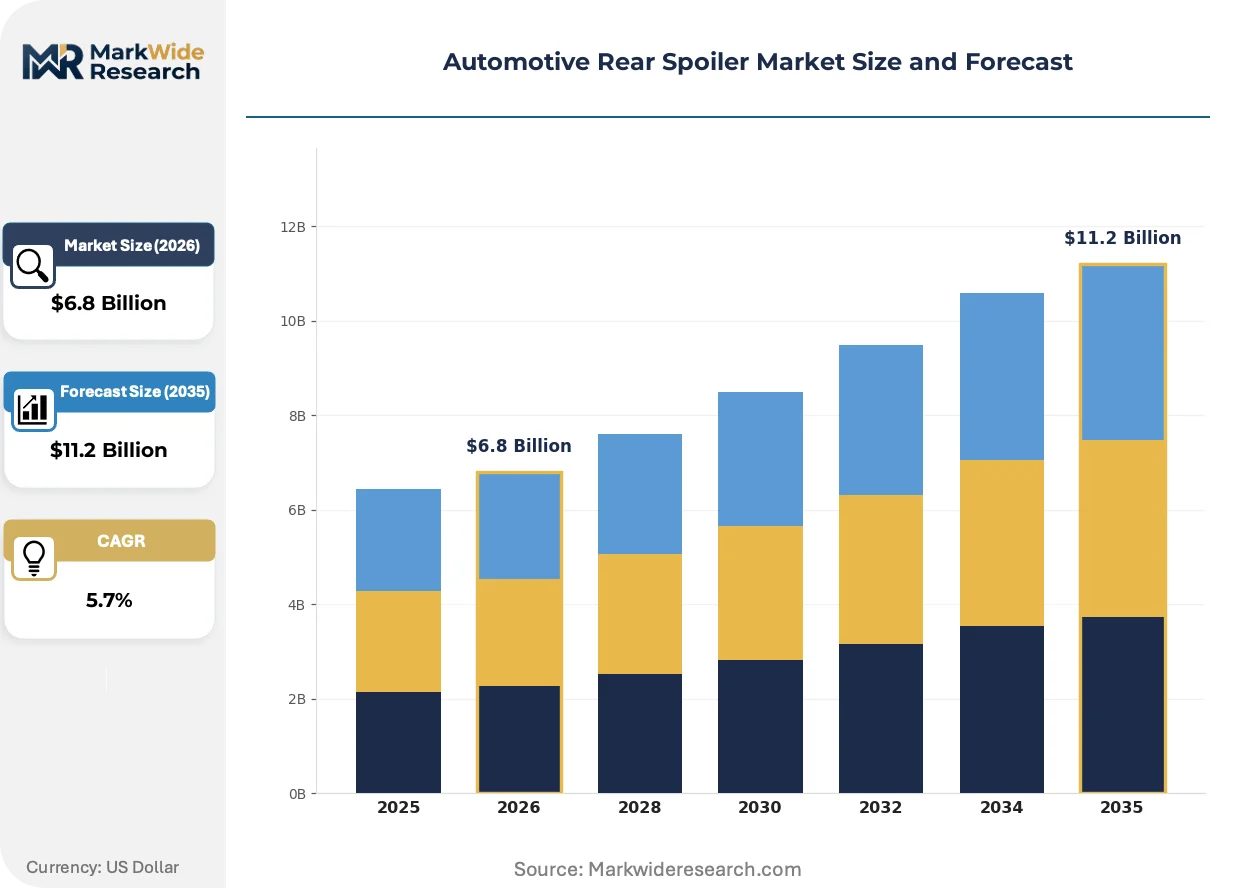
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Carbon Fiber, ABS Plastic, Polyurethane Application: Sports Cars, Sedans, SUVs, Coupes End User: OEMs, Aftermarket Retailers, Tuning Shops, Individual Consumers Installation Type: Bolt-On, Adhesive, Factory Installed, Custom Fit |
| Companies Covered | SMP Deutschland GmbH, Aisin Corporation, Magna International Inc., Inoac Corporation, DAR Spoilers, Plastic Omnium, Polytec Holding AG, Thai Rung Union Car Public Company Limited, Albar Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Rear Spoiler Market Emerging Trajectories
Electromechanical actuation and embedded sensing hardware are redefining spoiler architecture from passive sheet metal to intelligent vehicle subsystems.
Active deployable spoiler systems is collapsing the historical separation between aerodynamic devices and chassis control electronics. Porsche and Mercedes-AMG integrate these units across their GT and sports car lineups. The technology is collapsing static supplier business models by demanding electromechanical integration competencies that stamping houses cannot easily acquire.
REACH substance restrictions on halogenated flame retardants in polymer compounds force ABS formulation changes across European supply chains. Compounders must certify replacement chemistries without sacrificing paint adhesion or UV stability. German premium brands are responding by qualifying alternative resin grades through accelerated weathering protocols.
Fleet procurement contracts now specify lifetime aerodynamic performance guarantees rather than component replacement schedules. Rental and corporate fleet operators in the US Midwest push this model to minimize total cost of ownership. The shift concentrates buying power among national fleet managers who negotiate direct OEM spoiler program access, bypassing traditional distribution tiers.
Automotive Rear Spoiler Market Segmentation
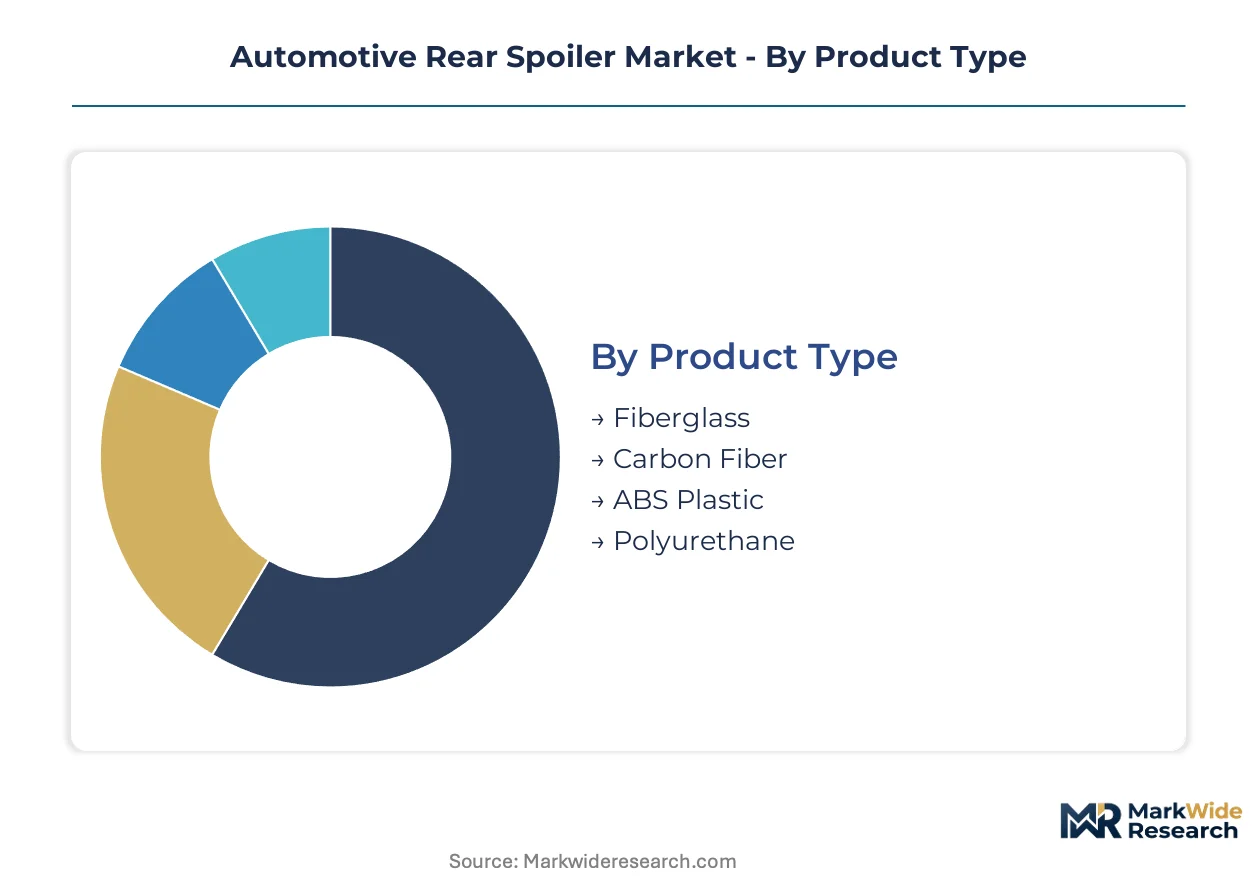
Material selection and installation channel determine margin architecture across spoiler supply chains. Factory-installed programs compete with aftermarket customization for design influence and revenue capture.
Product Type:
Material choice spans mass-production thermoplastics to aerospace-grade composites, with cost-per-kilogram and paint-integration requirements driving adoption patterns.
- Carbon Fiber:Compression-molded prepreg construction delivers maximum stiffness-to-weight ratio for high-performance applications. Stuttgart and Toyota City production clusters sustain demand concentration despite raw material cost escalation, with German OEMs mandating TS 16949 certification for supplier qualification.
- ABS Plastic:Injection-molded acrylonitrile butadiene styrene dominates volume production through thermoform efficiency and robotic paint-line compatibility. Mid-market sedan and SUV platforms in North American light-truck segments anchor demand, though resin price volatility compresses supplier margins.
- Fiberglass:Hand-laid or spray-up construction serves cost-sensitive aftermarket channels and classic vehicle restoration.
- Polyurethane:Reaction injection molding enables complex geometries with superior impact resistance for tuning shop applications.
The dominant share belongs to ABS Plastic, while Carbon Fiber is closing the gap fastest through active-aerodynamic integration in premium sports cars.
Application:
Vehicle platform characteristics dictate spoiler sizing, deployment mechanisms, and regulatory compliance requirements.
- SUVs:Extended rooflines and higher center-of-gravity positions generate substantial lift forces at highway speeds. Factory-installed programs across North American light-truck platforms integrate spoilers into platform aerodynamic strategies under EPA Corporate Average Fuel Economy mandates.
- Sports Cars:Low-drag coefficient targets and track-performance credibility require deployable wing systems with electromechanical actuation. Porsche and Mercedes-AMG GT lineups specify active elements that retract at low speed per EMA emissions frameworks.
- Sedans:Trunk-integrated lip spoilers balance aesthetic differentiation with minimal drag penalty for fleet efficiency compliance.
- Coupes:Fastback rooflines enable integrated ducktail designs that merge styling with functional downforce generation.
SUVs command the largest installed base, yet Sports Cars generate the highest content-per-vehicle through active-aerodynamic system integration.
End User:
Procurement authority determines specification control, with OEMs dictating design standards and aftermarket channels pursuing margin migration toward fitted services.
- OEMs:Factory-installed spoiler programs capture dominant value pools through platform-integrated aerodynamic strategies. Magna International leverages stamping and assembly footprint across North American programs, while Plastic Omnium anchors European supply through polymer-exterior systems expertise.
- Tuning Shops:Design-to-install service bundles reconfigure margin pools away from pure component supply toward personalized vehicle differentiation. German and Japanese aftermarket channels lead this shift.
- Aftermarket Retailers:Bolt-on distribution serves price-sensitive consumers through standardized fitment kits.
- Individual Consumers:Direct procurement concentrates in online channels for DIY installation projects.
OEMs retain specification authority, though Tuning Shops are expanding fastest through service-bundle revenue migration.
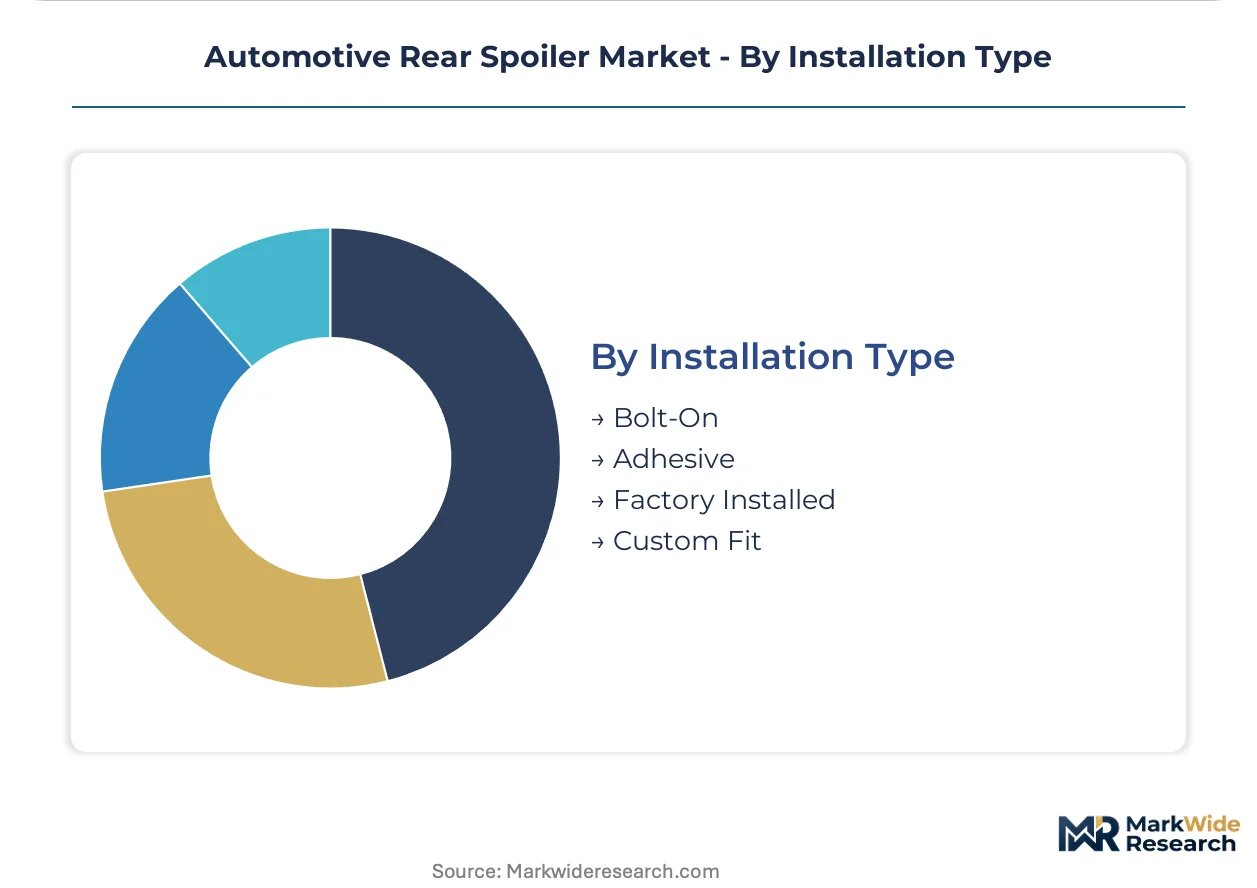
Installation Type:
Mounting method determines warranty liability, finish quality, and regulatory compliance burden.
- Factory Installed:Robotically applied adhesive bonding with integrated paint finishing ensures OEM warranty coverage and NHTSA rear-visibility compliance. SMP Deutschland GmbH specializes in precision blow-molded components for German premium brand programs.
- Bolt-On:Mechanical fastening enables reversible customization without permanent vehicle modification. Aftermarket tuning shops favor this method for personalized differentiation projects.
- Adhesive:Structural bonding tapes and urethane adhesives serve both OEM secondary operations and professional aftermarket installation.
- Custom Fit:Vehicle-specific fabrication accommodates non-standard body modifications and show-car applications.
Factory Installed maintains volume leadership, while Bolt-On channels gain share fastest through tuning shop expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan and Germany absorb carbon fiber premiums with minimal elasticity, while mid-market consumers in the United States and Thailand treat ABS spoilers as price-commoditized accessories. This demand-elasticity divide shapes regional supply chain investments and margin architectures.
United States
Fleet procurement contracts specifying lifetime aerodynamic performance guarantees concentrate buying power among national rental operators in the Midwest. NHTSA rear-visibility regulations constrain spoiler height specifications, forcing design compromises on sedan platforms. Detroit-area stamping houses supply robotically finished ABS components to light-truck OEM programs.
Germany
EMA emissions frameworks incentivize active deployable elements that retract at low speed, opening electromechanical system revenue for Stuttgart production clusters. REACH substance restrictions on halogenated flame retardants force ABS formulation changes across polymer supply chains. SMP Deutschland GmbH anchors precision blow-molded component supply for premium brand programs.
Japan
Toyota City production clusters sustain carbon fiber prepreg demand for mass-reduction imperatives in sports car applications. METI industrial standards govern supplier qualification timelines extending 18-24 months for new entrants. Aftermarket tuning shops in Osaka and Nagoya capture margin migration toward design-to-install service bundles.
China
MIIT fuel efficiency mandates push domestic OEMs to factory-install spoilers as standard equipment across sedan and SUV platforms. GB standards for automotive exterior components shape quality certification requirements for local suppliers. Yangtze River Delta injection molders serve volume production for mid-market electric vehicle platforms.
Thailand
Regional export hub status attracts ABS resin compounders serving Southeast Asian assembly plants with cost-sensitive specifications. The country's national automotive regulator enforces ASEAN harmonized safety standards for rear-visibility compliance. Thai Rung Union Car Public Company Limited occupies a position among Bangkok-based fabricators supplying bolt-on aftermarket channels.
Automotive Rear Spoiler Market Vendor Landscape
Capability concentration sits with precision molders serving German premium OEMs; scale advantage sits with integrated stamping houses supplying North American light-truck platforms. The market structure tiers into three archetypes: electromechanical system integrators pursuing active-aerodynamic convergence, polymer-exterior specialists leveraging paint-line compatibility, and carbon fiber prepreg suppliers clustered around Stuttgart and Toyota City. Dominant competitive moves include backward integration into resin compounding and strategic partnerships for ADAS sensor housing integration.
Within the German precision-molding tier, SMP Deutschland GmbH exemplifies capability concentration around blow-molded aerodynamic components. Magna International Inc. occupies a position at the scale-driven end, leveraging integrated stamping and assembly footprints across North American programs. Plastic Omnium represents the polymer-exterior systems archetype, anchoring European supply relationships through thermoformed component expertise.
| Leading Market Players |
|---|
| SMP Deutschland GmbH |
| Aisin Corporation |
| Magna International Inc. |
| Inoac Corporation |
| DAR Spoilers |
| Plastic Omnium |
| Polytec Holding AG |
| Thai Rung Union Car Public Company Limited |
| Albar Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Japanese carbon fiber prepreg facilities is compressing lead times and amplifying pricing power for Stuttgart-based suppliers serving German premium OEMs. This utilization squeeze propagates through OEM factory-installed programs and aftermarket tuning channels alike, forcing ABS plastic alternatives to absorb volume overflow at thinner margins.
Pricing Analysis
Design-to-install service bundles capture the dominant after-sales revenue tier that drives lifetime value in this market. Three-tier pricing structure across premium carbon fiber, standard ABS, and economy fiberglass levels separates factory-installed OEM programs from bolt-on aftermarket channels. Cost compression in ABS injection-molding feedstock is intensifying because of resin price volatility, squeezing mid-market supplier margins. Fleet procurement managers in the US Midwest exhibit highest price sensitivity, while Japanese sports car buyers absorb carbon fiber premiums with minimal elasticity.
Supply Chain Analysis
Contract-manufacturing concentration sits with Magna International's integrated stamping and assembly footprint across North American light-truck platforms and Plastic Omnium's polymer-exterior systems in Europe. Geographic supply concentrates in Germany, Japan, and China, with raw material dependencies spanning carbon fiber prepreg, ABS resin compounds, and thermoformed polymer sheets. Single-source vulnerability around Stuttgart prepreg manufacturing clusters creates structural risk for premium OEM programs. Distribution runs through OEM direct supply agreements, national fleet procurement contracts, and specialized tuning shop networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active-aerodynamic convergence with ADAS platform hardware marks a platform-economics inflection, where spoiler architectures must interoperate with sensor fusion and chassis control electronics rather than operate as standalone components.
For Market Incumbents: Build electromechanical integration moats through backward integration into actuator manufacturing and sensor housing fabrication. SMP Deutschland GmbH exemplifies defensive positioning through precision blow-molded component specialization that stamping houses cannot easily replicate. Incumbents should deepen certification investments in TS 16949 quality systems to extend German OEM supplier qualification timelines that gate new entrants. Channel control through exclusive design-to-install service partnerships with tuning shops in Osaka and Nagoya locks in aftermarket margin migration. For New Entrants and Emerging Players: Southeast Asian underpenetration in active-aerodynamic electromechanical systems offers white-space expansion outside German and Japanese production clusters. Thailand's regional export hub status attracts cost-sensitive ABS compounders, yet deployable spoiler actuation remains undersupplied for domestic electric vehicle platforms. Bolt-on aftermarket channels in Bangkok and emerging Chinese tier-2 cities present the most penetrable entry point. A go-to-market angle targeting fleet procurement contracts with lifetime aerodynamic performance guarantees bypasses traditional OEM supply tier barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electromechanical system integrators with active-aerodynamic competencies, as deployable spoiler programs generate service contract attachment through actuator maintenance and software updates. Long-term viability across the analysis window favors precision molders serving German premium brands over commodity ABS stampers exposed to resin price volatility. Acquisition targets should display polymer-exterior systems expertise with paint-line integration capabilities. The signal to watch is EMA emissions framework acceleration toward mandatory active-aerodynamic deployment, which would inflect electromechanical content-per-vehicle expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Active-Aerodynamic System Integration | Convergence with ADAS sensor housings expands content-per-vehicle for electromechanical suppliers serving Porsche and Mercedes-AMG programs. |
| Carbon Fiber Backward Integration | Upstream control over prepreg manufacturing mitigates Stuttgart supply concentration risk for German OEM spoiler programs. |
| Design-to-Install Service Expansion | Margin migration from component supply toward fitted customization captures aftermarket revenue in Japanese tuning shop networks. |
| Polymer Formulation Certification | REACH-compliant ABS compound qualification opens European supply access despite halogenated flame retardant restrictions. |
| Fleet Procurement Direct Access | Bypassing distribution tiers through national rental operator contracts concentrates buying power and locks in volume commitments. |
Methodological Framework
The analysis maps material-grade segments, installation channel archetypes, and active-aerodynamic technology tiers, each validated through Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations heads. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, EPA CAFE compliance filings, and EMA emissions framework documentation. Bottom-up segment sizing triangulated with top-down OEM program value estimates to reconcile factory-installed and aftermarket revenue pools.
Assumptions held fixed include EPA and EMA emissions trajectory continuity, carbon fiber prepreg cost structures, and TS 16949 certification requirements; variables tested included active-aerodynamic adoption velocity and fleet procurement contract penetration. The analytical framework modeled vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions across the projection horizon. CAGRs derived from segment-level production volume forecasts weighted by material-grade pricing tiers, with electromechanical actuator attachment rates and sensor integration penetration as automotive-specific inputs.
Practitioners should monitor EMA regulatory acceleration, ABS resin price volatility, and German OEM supplier qualification timeline extensions for early signals of forecast revision. Forecasts reflect documented assumptions about emissions framework stringency and material cost trajectories. Quarterly review of active-aerodynamic program announcements, prepreg manufacturing capacity utilization, and fleet procurement contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Undercarriage Systems Market
Automotive Parts
Russia Automotive Hydraulic Actuators Market
Automotive Parts
Heavy Duty Clutches Market
Automotive Parts
Global Automotive Leaf Spring Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Smart Adaptive Headlights Market
Automotive Parts
India Automotive Parts Magnesium Die Casting Market
Automotive Parts
Odometer Market
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
Automotive Windshield Washer System Market
Automotive Parts
France Automotive Parts Aluminium Die Casting Market
Automotive Parts
Center and Drag Link Market
Automotive Parts
Morocco Passenger Vehicles Lubricants Market
Automotive Parts
Indonesia Passenger Vehicles Lubricants Market
Automotive Parts
South Korea Automotive Parts Aluminium Die Casting Market
Automotive Parts
South America Passenger Vehicles Lubricants Market