
 Cycloid Gear Market | 2026-2036
Cycloid Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Cycloid Gear Market Insights
Modular actuator-gear bundling is broadening buyer choice across robotics and packaging lines. Nabtesco Corporation leverages captive production of precision reducers to dominate collaborative robot supply chains. Sumitomo Drive Technologies anchors heavy-industry demand through hardened gear variants for conveyor and mining applications. Spinea differentiates via European-centric precision positioning systems for semiconductor wafer handling equipment.
A cycloid gear transmits torque through eccentrically mounted cycloidal discs engaging pin gears, achieving reduction ratios exceeding 100:1 in compact envelopes with backlash below one arc-minute. Its primary purpose centers on precision motion control where servo motors require high torque density and positional repeatability. Precision cycloid gears capture premium margin pools in semiconductor manufacturing and aerospace systems where arc-second accuracy commands price premiums. Standard cycloid gears sustain volume leadership across conveyor drives and textile machinery where cost efficiency outweighs extreme precision requirements. Additive manufacturing technology for cycloid disc production is attracting R&D investment for topology-optimized weight reduction in aerospace and robotic joint applications.
Japan's METI enforces JIS standards governing gear efficiency and noise emissions in industrial equipment sold domestically. China's SAMR administers GB standards for mechanical transmission efficiency that constrain import eligibility for non-compliant gear systems. The EU Machinery Directive through CE marking mandates functional safety documentation for cycloid gearboxes integrated into automated production lines. Stakeholders must monitor evolving efficiency regulations across multiple jurisdictions while assessing captive versus outsourced manufacturing strategies for precision disc grinding capacity.
Market Dynamics
Precision cycloid gear demand from semiconductor fabrication facilities is compressing supplier lead times while China's GB efficiency standards and Japan's JIS noise regulations are bifurcating procurement requirements across East Asian manufacturing clusters.
Growth Catalysts
- Semiconductor capital equipment cycles:Wafer handling robots require sub-arc-minute backlash specifications that only precision cycloid reducers deliver, expanding addressable demand from lithography to inspection stages.
- China's dual carbon goals:Industrial efficiency mandates under SAMR-administered GB standards are forcing retrofits of legacy gearboxes with high-efficiency cycloidal systems in coastal manufacturing zones.
- Additive manufacturing adoption:Topology-optimized cycloid disc production via metal 3D printing is reducing weight for aerospace and robotic joint applications without sacrificing torque density.
Market Restraints
- Precision grinding capacity concentration:Specialized disc grinding equipment for sub-arc-minute tolerances concentrates among Japanese and German machine tool suppliers, creating input bottlenecks.
- Hardened steel alloy volatility:Cycloid disc and pin gear production depends on vacuum-degassed bearing steels subject to energy-intensive processing cost swings.
- Harmonic drive substitution:Strain wave reducers from collaborative robot supply chains compete for precision positioning applications below 100 Nm torque requirements.
Strategic Opportunities
- India manufacturing expansion:PLI scheme incentives for industrial automation and robotics are creating first-mover positioning for cycloid gearbox localization in Pune and Chennai clusters.
- Modular actuator integration:Bundled servo motor-reducer assemblies are displacing discrete component procurement in packaging and material handling OEM specifications.
- EU Machinery Directive tailwinds:CE marking requirements for functional safety documentation favor suppliers with integrated safety-rated encoder and brake configurations.
Industry Challenges
- Precision metrology talent scarcity:Cycloid profile measurement and correction requires specialized coordinate measuring machine operators with gear-specific ISO training that outpaces vocational pipeline output.
- Legacy system integration friction:Retrofitting cycloid reducers into existing conveyor and textile machinery requires custom adapter plates and shaft modifications that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cycloid Gear Market |
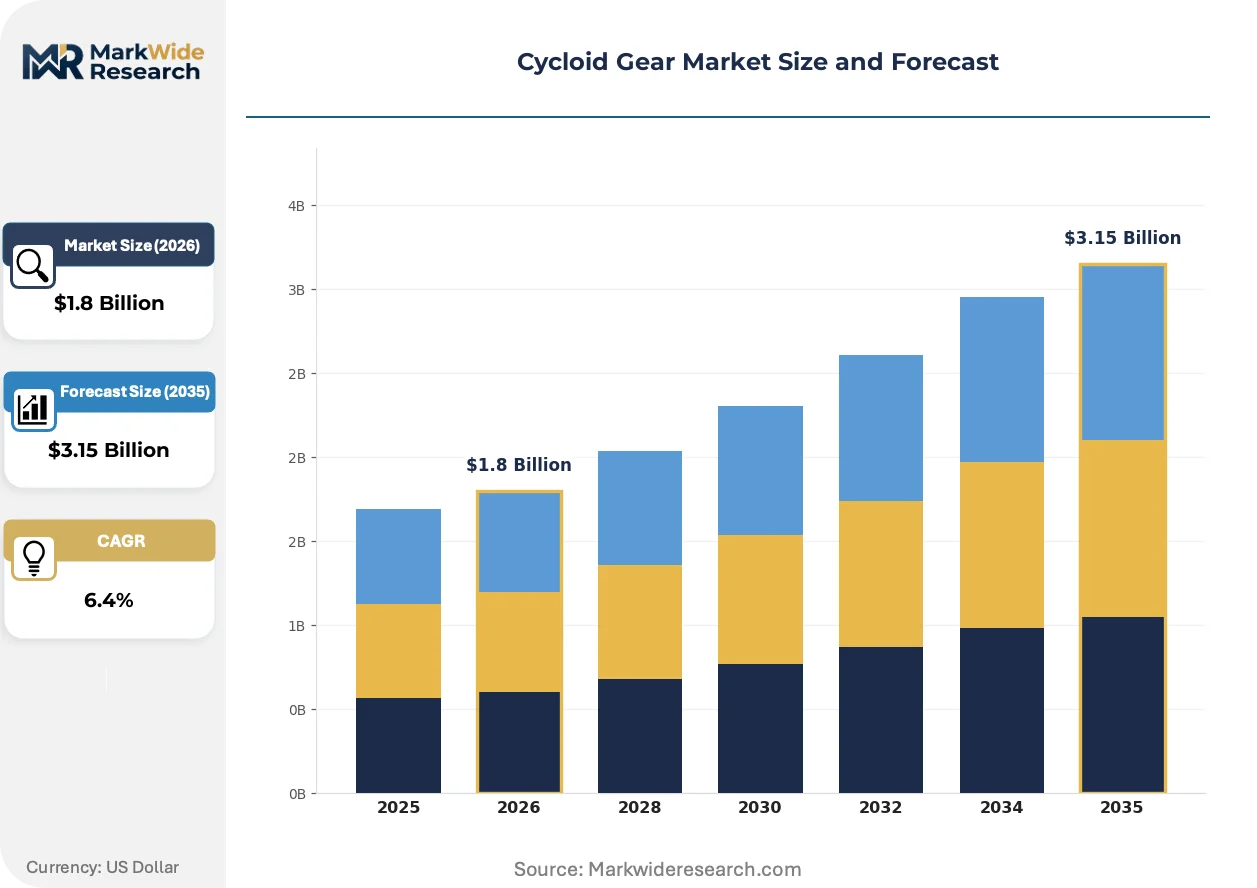
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cycloid Gears, Precision Cycloid Gears, Hardened Cycloid Gears, Miniature Cycloid Gears, Custom Cycloid Gears Technology: Machining, Casting, Additive Manufacturing, Powder Metallurgy, Laser Cutting Application: Robotics, Aerospace Systems, Packaging Machines, Conveyor Drives, Textile Machinery End User Industry: Automotive OEMs, Marine Engineering, Heavy Equipment Manufacturers, Semiconductor Manufacturing, Renewable Energy |
| Companies Covered | Nabtesco Corporation, Sumitomo Drive Technologies, Spinea, NIDEC, ONVIO, Transmission Machinery, Fixed Star Group, EGT Eppinger, Varitron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cycloid Gear Market Trends and Innovations
Additive manufacturing is compressing cycloid disc development cycles while regulatory efficiency mandates across Japan, China, and the EU are hardening technical specifications. Demand patterns are fragmenting as buyer procurement models evolve toward bundled subsystems.
Topology-optimized metal 3D printing for cycloid disc production is decentralizing precision gear manufacturing away from concentrated grinding centers. Aerospace tier-1 suppliers and collaborative robot OEMs are adopting printed titanium and maraging steel discs for weight-critical joints. This is decentralizing supply chain risk and enabling rapid prototyping of custom reduction ratios without dedicated cutting tool investments.
Japan's METI is enforcing revised JIS B 1702-1 accuracy grades for industrial gearboxes sold domestically, tightening allowable transmission error tolerances. Chinese SAMR is aligning GB/T 10095 with ISO 1328 for import eligibility, creating dual compliance burdens. Semiconductor equipment manufacturers in South Korea and Taiwan are prioritizing suppliers with concurrent JIS and GB certification to streamline multi-factory deployments.
Buyer specifications are consolidating around integrated servo-gear-actuator bundles rather than discrete component sourcing. Packaging machinery OEMs in Germany and material handling integrators in the United States are specifying complete motion subsystems from single suppliers. This consolidation is most visible in collaborative robot and delta robot applications where engineering resource constraints favor pre-validated kinematic chains over in-house reducer selection.
Cycloid Gear Market Segmentation
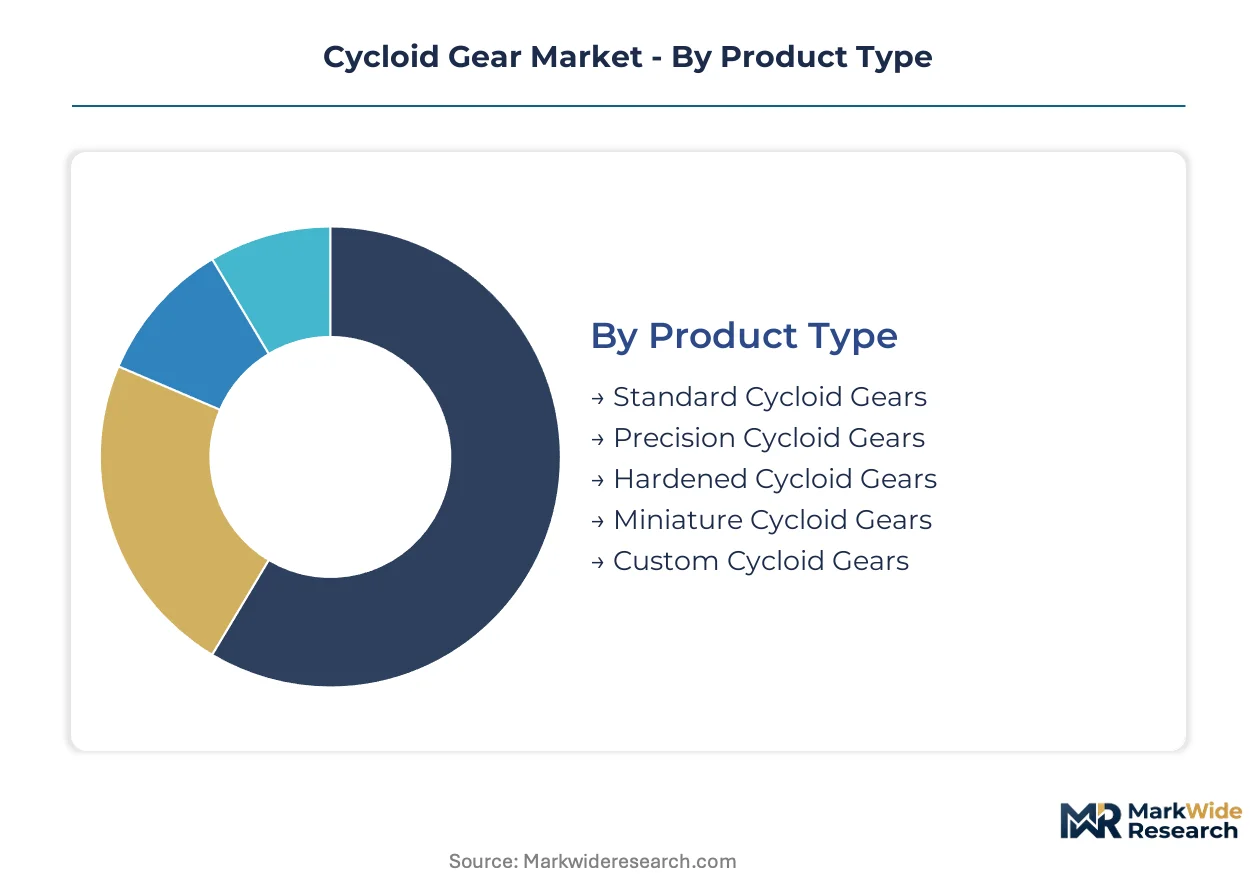
Cycloid gear segmentation reveals distinct certification and performance thresholds that reshape supplier qualification requirements across semiconductor, aerospace, and heavy equipment verticals. Buyers segment procurement by precision grade, manufacturing method, and end-use criticality to align with JIS, GB, and CE marking mandates.
Product Type:
Precision grades dictate regulatory burden intensity, with sub-arc-minute variants requiring JIS B 1702-1 certification for Japanese semiconductor fabs and GB/T 10095 alignment for Chinese import eligibility.
- Standard Cycloid Gears:Volume production targets conveyor drives and textile machinery where cost efficiency dominates over extreme precision. Procurement concentrates in China's coastal manufacturing zones under SAMR efficiency retrofit mandates, with buyers prioritizing GB-compliant suppliers for textile OEM specifications.
- Precision Cycloid Gears:Sub-arc-minute backlash specifications serve wafer handling robots and lithography stages. Demand compresses supplier lead times as South Korean and Taiwanese semiconductor equipment manufacturers require concurrent JIS and GB certification for multi-factory deployments.
- Hardened Cycloid Gears:Vacuum-degassed bearing steel variants withstand mining and heavy conveyor loads. Sumitomo Drive Technologies anchors this segment through captive heat treatment capacity.
- Miniature Cycloid Gears:Compact envelopes below 50mm diameter enable collaborative robot joint integration. Additive manufacturing is reducing prototyping cycles for custom reduction ratios.
- Custom Cycloid Gears:Non-standard reduction ratios and adapter configurations address legacy system retrofits. Extended commissioning timelines frustrate textile and packaging machinery upgrade projects.
Standard Cycloid Gears sits at the top of the volume ranking, with Precision Cycloid Gears climbing the fastest.
Technology:
Manufacturing method selection correlates directly with cost tier positioning and aerospace qualification pathways.
- Machining:Conventional CNC grinding achieves sub-arc-minute tolerances for precision segments. Capacity concentrates among Japanese and German machine tool suppliers, creating input bottlenecks for disc grinding equipment.
- Casting:Near-net-shape production reduces material waste for standard gear housings. Heavy equipment manufacturers in mining and marine applications favor ductile iron castings for shock load absorption.
- Additive Manufacturing:Topology-optimized titanium and maraging steel discs reduce weight for aerospace joints and collaborative robots without sacrificing torque density. Metal 3D printing decentralizes supply chain risk away from concentrated grinding centers.
- Powder Metallurgy:Net-shape forming suits miniature gear production at volume. European precision positioning system suppliers leverage this for cost-efficient small-batch runs.
- Laser Cutting:Rapid prototyping of cycloid disc profiles enables custom ratio development without dedicated cutting tool investments. Packaging machinery OEMs specify laser-cut prototypes for validation before machining commitment.
Machining retains the dominant share, though Additive Manufacturing is gaining share fastest among aerospace tier-1 suppliers and robot OEMs.
Application:
End-use criticality determines whether buyers prioritize arc-second accuracy or total cost of ownership.
- Robotics:Collaborative and delta robot joints require compact, zero-backlash reducers. Modular actuator-gear bundling is displacing discrete component procurement as engineering resource constraints favor pre-validated kinematic chains.
- Aerospace Systems:Flight control surface actuators and satellite positioning mechanisms demand weight-optimized, radiation-hardened variants. Topology-optimized additive manufacturing is qualifying for titanium disc production in this segment.
- Packaging Machines:High-speed cartoning and palletizing lines specify integrated servo-gear-actuator bundles from single suppliers. German packaging OEMs are consolidating procurement around pre-engineered motion subsystems.
- Conveyor Drives:Mining and bulk material handling prioritize hardened gear variants for shock load endurance. Retrofit demand from China's dual carbon efficiency mandates is accelerating gearbox replacement cycles.
- Textile Machinery:Ring spinning and weaving equipment requires cost-efficient standard reducers. Legacy system integration friction extends commissioning timelines due to custom adapter plate requirements.
Conveyor Drives commands the largest installed base, with Robotics showing the steepest expansion trajectory as collaborative automation penetrates assembly lines.
End User Industry:
Customer scale and technical sophistication fragment procurement patterns across project-based and OEM volume buyers.
- Automotive OEMs:EV powertrain testing rigs and battery assembly lines specify precision reducers for repeatability. Tier-1 suppliers are qualifying cycloid alternatives to harmonic drives for torque density advantages.
- Marine Engineering:Winch and propulsion systems require corrosion-resistant hardened variants. Classification society approval processes extend supplier qualification timelines.
- Heavy Equipment Manufacturers:Excavator swing drives and crane hoists demand shock-resistant hardened gears. Mining conveyor applications anchor volume demand for this segment.
- Semiconductor Manufacturing:Wafer handling robots and inspection stages drive premium pricing for sub-arc-minute precision. South Korean and Taiwanese fabs prioritize suppliers with concurrent JIS and GB certification.
- Renewable Energy:Wind turbine pitch and yaw systems are evaluating cycloid alternatives to planetary gears for compact envelope advantages. Grid-scale solar tracking mechanisms present emerging volume opportunity.
Heavy Equipment Manufacturers maintains the top volume position, with Semiconductor Manufacturing expanding most quickly as capital equipment cycles intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cycloid gear manufacturing originated in Japanese precision engineering clusters during the 1970s, establishing Kobe and Osaka as foundational centers for eccentric disc reducer technology. Production lineage traces through German machine tool corridors and Chinese coastal industrial zones, creating a three-pole supply geography.
Japan
Wafer handling robot demand from Tokyo Electron and Nikon Precision compresses lead times for sub-arc-minute reducers. METI enforces revised JIS B 1702-1 accuracy grades tightening transmission error tolerances for domestic industrial equipment. Kobe's precision reducer corridor concentrates captive grinding capacity serving collaborative robot OEMs.
China
Dual carbon retrofit mandates accelerate gearbox replacement in Jiangsu and Zhejiang textile clusters. SAMR-administered GB/T 10095 standards constrain import eligibility for non-compliant transmission systems. Shenzhen and Dongguan automation integrators specify locally certified reducers for battery assembly line contracts.
Germany
Packaging machinery OEMs in Bavaria consolidate procurement around integrated servo-gear-actuator bundles. EU Machinery Directive CE marking mandates functional safety documentation for automated production line integration. Stuttgart's automotive tier-1 suppliers qualify cycloid alternatives to harmonic drives for EV powertrain testing rigs.
South Korea
Semiconductor capital equipment cycles drive precision reducer demand from Samsung and SK Hynix fabs. Korean industrial safety regulations align with concurrent JIS and GB certification requirements for multi-factory deployments. Suwon and Pyeongtaek manufacturing clusters prioritize suppliers with cross-border compliance documentation.
United States
Material handling integrators in Michigan and Ohio specify complete motion subsystems over discrete component sourcing. OSHA machinery safety standards influence automated line specifications for conveyor and palletizing applications. Detroit's automotive testing equipment manufacturers specify precision reducers for battery assembly repeatability.
Cycloid Gear Market Competitive Landscape
The competitive structure tilts toward vertically integrated precision specialists with captive heat treatment and grinding capacity. Japanese and German fabricators anchor premium tiers through certified production lines, while Chinese and Taiwanese suppliers capture volume in standard efficiency retrofits. Two strategic archetypes dominate: precision motion specialists serving semiconductor and aerospace verticals, and hardened gear producers targeting mining and heavy conveyor applications. Capacity expansion in additive manufacturing for topology-optimized discs and backward integration into vacuum-degassed bearing steel supply represent the dominant competitive vectors.
Among Japanese precision engineering houses, Nabtesco Corporation and Sumitomo Drive Technologies exemplify divergent specialization archetypes. Nabtesco occupies the collaborative robot precision reducer tier through captive production of eccentric disc systems. Sumitomo anchors heavy-industry demand segments through hardened gear variants. European positioning is represented by Slovakia-based Spinea, which sits within the semiconductor wafer handling equipment specialization cluster.
| Leading Market Players |
|---|
| Nabtesco Corporation |
| Sumitomo Drive Technologies |
| Spinea |
| NIDEC |
| ONVIO |
| Transmission Machinery |
| Fixed Star Group |
| EGT Eppinger |
| Varitron |
| Others |
Pricing and Supply Chain Analysis
Vacuum-degassed bearing steel index fluctuations cascade through cycloid gear manufacturing tiers, compressing margins on standard reducers while amplifying premium capture for JIS-certified precision variants. China's SAMR efficiency mandates and Japan's METI noise regulations bifurcate procurement, forcing suppliers to absorb alloy volatility or pass through costs to price-sensitive textile OEMs.
Pricing Analysis
Three-tier pricing structure across precision, standard, and hardened levels separates semiconductor-grade sub-arc-minute reducers from conveyor-drive commodity variants. Certification burden intensity and captive grinding capacity drive differentiation, with JIS B 1702-1 and GB/T 10095 compliance adding qualification premiums. Pricing pressure stems from harmonic drive substitution in collaborative robot joints below 100 Nm torque. Heavy equipment manufacturers exhibit highest price sensitivity; semiconductor fabs accept premiums for arc-second repeatability.
Supply Chain Analysis
Precision metrology talent scarcity in Kobe, Osaka, and Stuttgart constrains expansion of sub-arc-minute grinding capacity. Cycloid disc production draws from vacuum-degassed bearing steels, specialized CNC grinding equipment, and topology-optimized additive manufacturing feedstocks. Single-source vulnerability concentrates in Japanese and German machine tool suppliers for disc grinding equipment. Distribution runs through OEM direct contracts for semiconductor equipment and automation integrator channels for packaging machinery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cycloid gear market compounds steadily as semiconductor capital equipment cycles renew precision reducer demand across lithography and inspection stages.
For Market Incumbents: Anchor defensive positioning through captive heat treatment capacity and concurrent JIS-GB certification to lock out multi-factory semiconductor deployments. Counter harmonic drive substitution by emphasizing torque density advantages above 100 Nm. Deepen backward integration into vacuum-degassed bearing steel supply to buffer alloy volatility. For New Entrants and Emerging Players: India's PLI-scheme automation integrators present the most penetrable buyer archetype for first-mover localization in Pune and Chennai clusters. Target modular actuator-gear bundling specifications displacing discrete component procurement in packaging lines. Pursue rapid prototyping partnerships with collaborative robot OEMs seeking custom reduction ratios via additive manufacturing. For Investors and Strategic Acquirers: Asymmetric upside sits with additive manufacturing-enabled precision specialists qualifying topology-optimized titanium discs for aerospace tier-1 supply. Five-to-ten-year viability favors captive grinding capacity over outsourced disc production. Watch for CE marking enforcement intensification under EU Machinery Directive revisions as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bearing Steel Supply | Captive vacuum-degassed steel capacity insulates margin compression from energy-intensive processing cost swings. |
| Concurrent JIS-GB Certification Investment | Dual compliance streamlines multi-factory deployments for Samsung and SK Hynix semiconductor equipment suppliers. |
| Additive Manufacturing Qualification | Topology-optimized titanium disc production qualifies for Boeing and Airbus flight control actuator specifications. |
| Modular Actuator-gear Bundle Development | Pre-validated kinematic chains capture packaging machinery OEM specifications consolidating procurement. |
| India Manufacturing Localization | PLI scheme incentives enable first-mover positioning in Pune and Chennai automation clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with precision reducer procurement managers, semiconductor equipment engineers, automation integrator technical directors, and aftermarket service heads with secondary validation. Trade data from Japan's METI machinery statistics, China's SAMR industrial efficiency filings, EU CE marking registries, and SEC 10-K disclosures from listed transmission suppliers anchored supply-side sizing. Bottom-up unit economics and top-down industrial automation capex flows were triangulated for segment reconciliation.
Segment-weighting across precision grade, manufacturing method, and end-use criticality shaped the analytical framework across the projection horizon. Product type splits by standard, precision, hardened, miniature, and custom variants combined with technology tiers spanning machining, casting, additive manufacturing, powder metallurgy, and laser cutting. Robotics, aerospace, packaging, conveyor, and textile application CAGRs were derived from equipment shipment correlations and replacement cycle assumptions. Semiconductor capital expenditure intensity and China's dual carbon retrofit mandates served as primary demand drivers.
Underlying measurement precision varies by segment; precision cycloid gears carry tighter precision than standard variants given concentrated supplier visibility. Forecasts reflect documented assumptions on alloy price trajectories, regulatory enforcement timelines, and additive manufacturing qualification rates. Material deviation in semiconductor equipment capex, GB standard implementation pace, or bearing steel supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Plastics Market
Automotive Parts
Automotive Spring Market
Automotive Parts
Global Automotive Gasket and Seal Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Electric Parking Brake Actuator Components Market
Automotive Parts
Automotive Steering Knuckle Market
Automotive Parts
Engine Oil Market
Automotive Parts
Automotive Valve Stem Seal Market
Automotive Parts
Global Automotive Timing Belt Market
Automotive Parts
Brazil Automotive Airfilters Market
Automotive Parts
Vietnam Passenger Vehicles Lubricants Market
Automotive Parts
Tow Bar Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
United States Automotive Glass Market
Automotive Parts
Global All Wheel Drive Market