
 Mexico Automotive Parts Zinc Die Casting Market | 2026-2036
Mexico Automotive Parts Zinc Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Automotive Parts Zinc Die Casting Market Foresight
Tier-1 suppliers serving EV powertrain programs is reorganizing procurement priorities toward lighter zinc-alloy housings that accommodate integrated electronics. Pace Industries leverages its multi-plant footprint across central Mexico to sustain just-in-time delivery contracts with major assemblers. Dynacast differentiates through precision miniaturization capabilities that serve sensor-enclosure demand from electrified vehicle architectures.
Automotive parts zinc die casting involves injecting molten zinc-aluminum alloys into hardened steel molds at pressures exceeding 1,000 psi, producing complex geometries with wall thicknesses below one millimeter for under-hood and chassis applications. The process yields components with excellent corrosion resistance and dimensional stability for transmission cases, engine brackets, and electrical connector housings. Structural Parts occupies the dominant share of product-type value pools due to crashworthiness requirements in lightweight vehicle platforms. Electrical Housings represents the fastest-expanding segment as 48-volt mild-hybrid architectures multiply connector and control-module demand. OEM direct sourcing from captive foundry operations anchors the End User landscape, though Tier-1 Suppliers are gaining share through consolidated module assembly responsibilities.
NOM-001-SECRE energy efficiency standards and PROFEPA emissions protocols govern foundry operations across Mexico's industrial belt, mandating heat-recovery systems and particulate filtration that elevate capital thresholds for new entrants. The central bank's automotive sector lending guidelines indirectly shape supplier working-capital availability through assembler financing conditions. Stakeholders must monitor how NOM-052-SEMARNAT hazardous waste classifications affect slag disposal costs and regional foundry siting decisions.
Market Dynamics
Electrification of Mexican automotive assembly is compressing design cycles for zinc die-cast transmission housings, forcing Tier-1 suppliers to requalify alloys for 48-volt mild-hybrid thermal loads within 18-month windows.
Growth Catalysts
- PROFEPA emissions protocols:Stringent particulate filtration mandates are accelerating consolidation toward capitalized foundries capable of continuous emissions monitoring.
- Guanajuato corridor clustering:Proximity of transmission housing foundries to assembly plants reduces logistics costs and enables just-in-time delivery contracts.
- Zinc-aluminum alloy miniaturization:Thinner-wall casting capabilities below one millimeter accommodate integrated sensor packaging for electrified powertrains.
Market Restraints
- Aluminum substitution pressure:Magnesium-aluminum alloys in structural brackets threaten zinc's share in non-corrosive chassis applications.
- Energy cost volatility:Natural gas price swings directly impact molten metal holding furnace operating economics.
- NOM-001-SECRE compliance thresholds:Heat-recovery system investments elevate minimum viable scale for new market entrants.
Strategic Opportunities
- Electrical housing expansion:Connector and control-module demand from 48-volt architectures outpaces current foundry capacity allocation.
- Baja California supplier development:Underdeveloped foundry infrastructure near Tijuana assembly plants offers first-mover positioning.
- NOM-052-SEMARNAT reclassification:Anticipated hazardous waste rule changes may dislocate slag disposal economics toward centralized processing hubs.
Industry Challenges
- Tooling engineer scarcity:Hardened steel mold design expertise for sub-millimeter wall thicknesses concentrates among retiring specialists.
- Dual certification timelines:Simultaneous OEM qualification for traditional ICE and EV thermal profiles extends approval cycles.
- Legacy furnace integration:Retrofitting heat-recovery systems onto existing molten metal handling lines disrupts production continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Automotive Parts Zinc Die Casting Market |
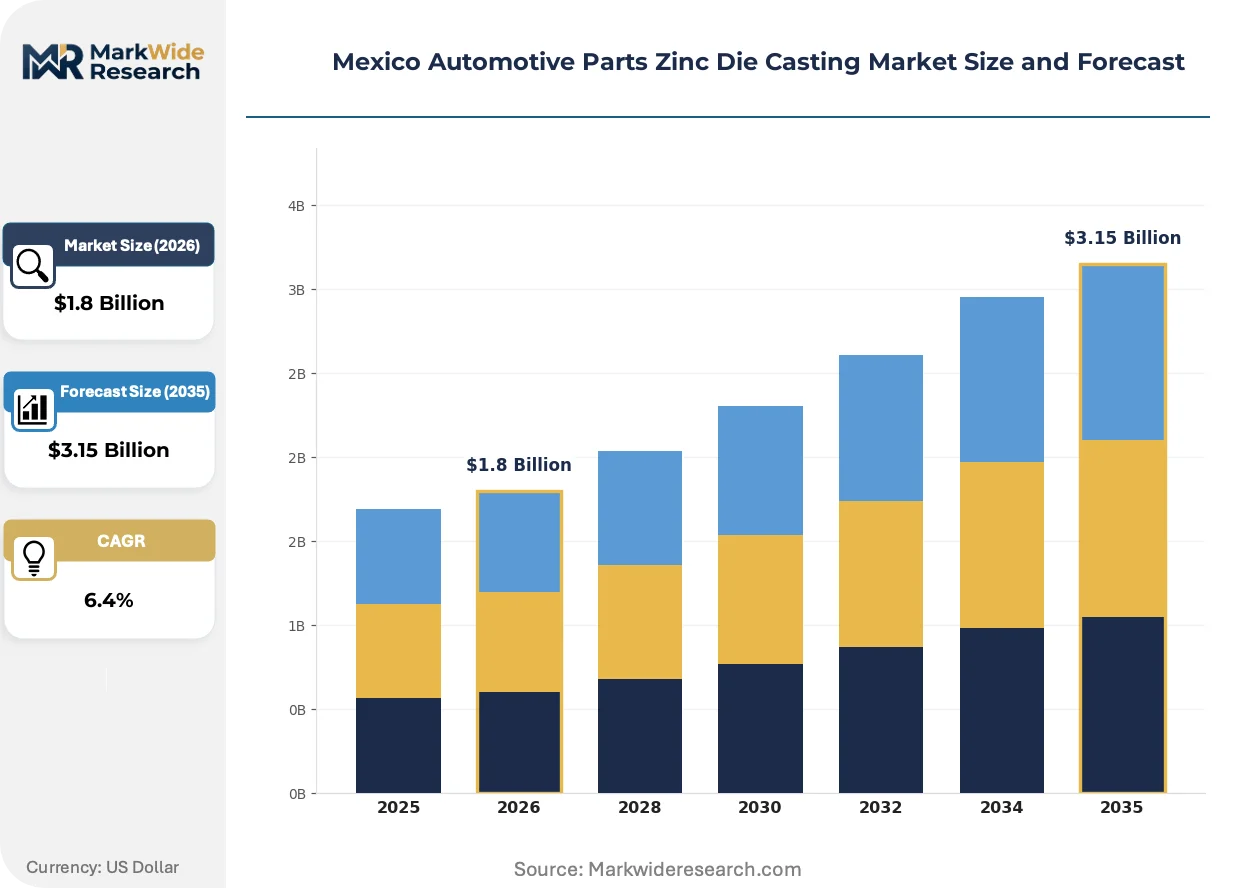
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Parts, Electrical Housings, Structural Parts Application: Light Vehicles, Heavy-Duty Vehicles, Commercial Vehicles, Motorcycles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Manufacturing Stage: Prototype, Mass Production, Casting, Finishing |
| Companies Covered | Pace Industries, Empire Casting Co, Sandhar Technologies Ltd, Kemlows Diecasting Products Ltd, Ningbo Die Casting Company, Brillcast Manufacturing LLC, Ashok Minda Group, Cascade Die Casting Group, Dynacast, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Automotive Parts Zinc Die Casting Market Shifts & Advancements
Process digitization and alloy formulation advances are redefining competitive capability thresholds across Mexican zinc die-casting operations, with thermal management requirements from electrified vehicles driving the most consequential technical pivots.
Thin-wall zinc-aluminum casting technology is fragmenting the traditional segmentation between structural and electrical applications. Tier-1 suppliers serving EV programs now specify single-alloy solutions spanning transmission cases and sensor enclosures. This convergence compresses supplier qualification lists while elevating precision requirements.
NOM-001-SECRE energy efficiency standards mandate heat-recovery systems and real-time molten metal temperature monitoring across all industrial-scale foundries. Compliance investments favor multi-plant operators with centralized engineering resources. Guanajuato-based suppliers are retrofitting existing lines ahead of enforcement deadlines.
Consolidated module assembly responsibilities are compressing Tier-1 procurement hierarchies. OEMs now source complete powertrain housings with integrated electrical connectors rather than discrete castings. This pattern concentrates volume with foundries capable of precision machining and sub-assembly finishing within Mexico's central manufacturing belt.
Mexico Automotive Parts Zinc Die Casting Market Segmentation
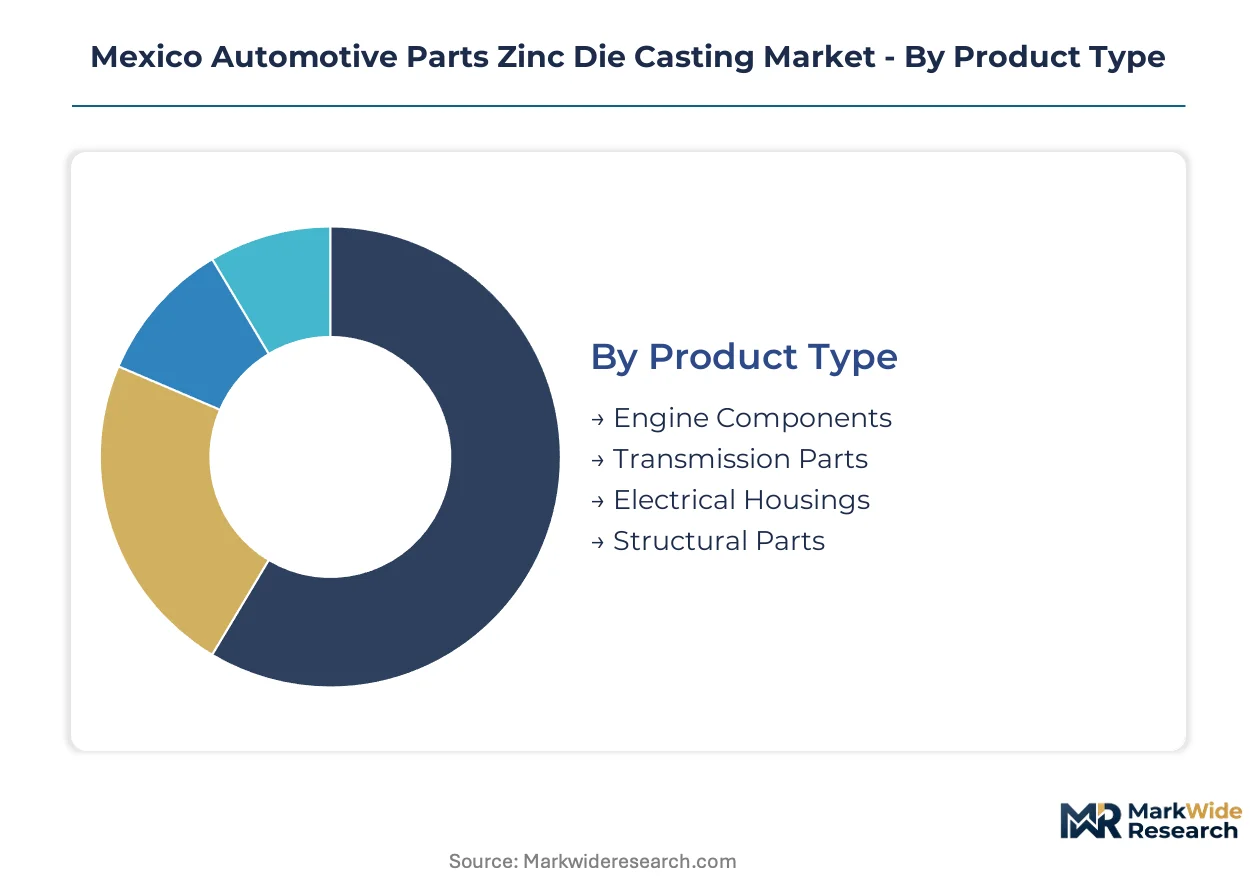
Zinc die-cast component demand fragments across four distinct dimensions. Each segmentation layer exposes different vulnerability to aluminum substitution and divergent compliance burdens under NOM-001-SECRE standards.
Product Type:
Structural Parts faces the most acute substitution pressure from magnesium-aluminum alloys in crash-critical applications, while Electrical Housings enjoys alloy-specific advantages that resist displacement.
- Structural Parts:Transmission housings and chassis brackets demand zinc-aluminum alloys with superior creep resistance under mechanical load. Guanajuato foundry clusters dominate supply for GM Silao and Volkswagen Puebla assembly lines, though OEMs now qualify hybrid material stacks that blend cast zinc with extruded aluminum.
- Electrical Housings:Sensor enclosures and 48-volt connector modules specify ZA-8 and ZA-12 alloys for electromagnetic shielding and thermal conductivity. Dynacast's precision miniaturization capabilities capture expanding connector demand from electrified powertrain architectures across central Mexico.
- Engine Components:Brackets and mounting hardware retain zinc dominance in corrosion-exposed under-hood positions.
- Transmission Parts:Gearbox casings and shift mechanisms concentrate in captive Tier-1 operations near assembly plants.
Structural Parts retains volume leadership; Electrical Housings holds the steepest expansion curve.
Application:
Cost tier stratification separates premium light-vehicle programs from price-sensitive commercial vehicle procurement, with divergent alloy specification tolerances.
- Light Vehicles:Passenger car and SUV programs specify thin-wall ZA-27 castings below one millimeter for integrated electronics packaging. Pace Industries sustains just-in-time contracts with Nissan Aguascalientes through multi-plant redundancy across the Bajío region.
- Heavy-Duty Vehicles:Commercial truck transmission cases prioritize structural integrity over weight reduction, favoring thicker-wall zinc alloys with established fatigue databases.
- Commercial Vehicles:Fleet procurement emphasizes unit cost over performance differentiation, compressing foundry margins on high-volume orders.
- Motorcycles:Two-wheeler electrical systems generate modest connector demand from export-oriented assembly in Querétaro.
Light Vehicles commands the premium pricing tier; Heavy-Duty Vehicles offers volume stability against electrification headwinds.
End User:
Customer-type concentration determines qualification timelines and technical collaboration intensity, with OEM direct sourcing consolidating fastest.
- OEMs:Captive foundry operations at major assemblers anchor procurement for transmission housings and structural brackets. Volkswagen de México maintains in-house zinc casting at Puebla for proprietary powertrain designs.
- Tier-1 Suppliers:Consolidated module assemblers like Nemak and Metalsa now source complete housing assemblies with integrated electrical connectors rather than discrete castings.
- Vehicle Assemblers:Contract manufacturers without captive metalworking capabilities rely on qualified supplier networks for just-in-time delivery.
- Aftermarket Providers:Replacement component distributors serve aging vehicle populations with limited alloy innovation requirements.
Tier-1 Suppliers are gaining procurement share through module consolidation; Aftermarket Providers remain structurally peripheral.
Manufacturing Stage:
Process maturity separates established mass production from emerging prototype capabilities, with capital intensity escalating across the value chain.
- Mass Production:High-pressure die-casting cells with automated ladling and real-time temperature monitoring dominate Guanajuato corridor output. PROFEPA emissions compliance mandates elevate minimum viable scale for continuous operations.
- Casting:Molten metal handling and injection operations concentrate technical expertise for sub-millimeter wall thickness achievement.
- Finishing:CNC machining, surface treatment, and sub-assembly integration capture incremental margin from consolidated module supply.
- Prototype:Tooling development and alloy qualification for 18-month EV requalification windows demand specialized engineering partnerships.
Mass Production anchors revenue concentration; Prototype services command premium pricing for accelerated EV program timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican zinc die-cast exports flow primarily to US and Canadian automotive assembly plants, with cross-border supply chains tightening as nearshoring accelerates under USMCA trade provisions.
Guanajuato
Transmission housing demand from GM Silao and Volkswagen supply contracts anchors regional output. NOM-001-SECRE energy efficiency mandates drive heat-recovery retrofits across foundry clusters. Irapuato-León corridor suppliers sustain just-in-time delivery contracts through multi-plant redundancy.
Nuevo León
Heavy-duty vehicle transmission cases for export-oriented truck assembly generate stable zinc alloy consumption. PROFEPA emissions protocols elevate capital thresholds for new furnace installations. Monterrey metropolitan foundries concentrate on thicker-wall castings for commercial vehicle fatigue requirements.
Puebla
Volkswagen de México's captive casting operations power proprietary powertrain designs for domestic and export programs. The state's environmental regulator enforces hazardous waste classifications affecting slag disposal economics. Cuautlancingo supplier parks enable consolidated module assembly with integrated electrical connectors.
Baja California
Tijuana assembly plants serving US West Coast markets create underdeveloped foundry infrastructure opportunity. Mexico's federal automotive sector lending guidelines shape supplier working-capital availability through assembler financing conditions. Tecate-Mexicali corridor offers first-mover positioning for electrical housing specialists targeting 48-volt mild-hybrid demand.
Querétaro
Two-wheeler electrical systems from export-oriented motorcycle assembly generate modest connector demand. State industrial development incentives target precision miniaturization capabilities for sensor-enclosure applications. El Marqués aerospace-adjacent manufacturing base transfers tooling expertise toward sub-millimeter wall thickness achievement.
Mexico Automotive Parts Zinc Die Casting Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and customer qualification timelines. The vendor base concentrates around multi-plant operators with centralized engineering resources and single-site precision specialists serving accelerated EV program windows. Three archetypes dominate: scale-driven mass producers, miniaturization-focused precision houses, and captive Tier-1 module assemblers. Consolidation pressures favor M&A among heat-recovery compliant foundries and strategic partnerships for 18-month alloy requalification cycles.
Among US-based fabricators, Pace Industries and Dynacast exemplify divergent strategic positioning within the Mexican market. Pace Industries represents the multi-plant scale archetype with distributed capacity across central Mexico. Dynacast occupies the precision miniaturization tier serving sensor-enclosure specifications. Sandhar Technologies Ltd anchors the India-origin specialist contingent targeting electrical housing expansion. Brillcast Manufacturing LLC and Cascade Die Casting Group sit within the North American mid-cap foundry segment. Empire Casting Co exemplifies private specialist structure without public capital constraints.
| Leading Market Players |
|---|
| Pace Industries |
| Empire Casting Co |
| Sandhar Technologies Ltd |
| Kemlows Diecasting Products Ltd |
| Ningbo Die Casting Company |
| Brillcast Manufacturing LLC |
| Ashok Minda Group |
| Cascade Die Casting Group |
| Dynacast |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Guanajuato foundry clusters and Tier-1 module assemblers lock in zinc-alloy supply access while insulating buyers from natural gas price swings that otherwise disrupt molten metal holding economics. These arrangements concentrate pricing power among multi-plant operators with NOM-001-SECRE compliant heat-recovery infrastructure, compressing margins for spot-market participants.
Pricing Analysis
Thin-wall casting technology commands premium positioning over conventional structural housing production, with ZA-8 and ZA-12 alloy formulations for 48-volt electrical connectors pricing above legacy transmission case grades. Three-tier pricing structure across precision miniaturization, standard structural, and commodity bracket tiers reflects certification burden and tooling complexity dispersion. Pricing pressure stems from magnesium-aluminum substitution in non-corrosive chassis positions, forcing zinc foundries to absorb alloy development costs. Fleet procurement managers at commercial vehicle assemblers exhibit highest price sensitivity, while EV powertrain engineers prioritize electromagnetic shielding performance over unit cost.
Supply Chain Analysis
Inbound logistics costs from Veracruz port congestion and container availability constraints on Asia-Mexico trade lanes elevate specialty alloy inventory carrying requirements for central Mexico foundries. Primary zinc ingot supply draws from Peruvian and Australian mining operations, with secondary alloy feedstock sourcing from US and Canadian automotive scrap recovery networks. Single-source vulnerability concentrates in high-purity zinc cathode supply chains tethered to smelter consolidation in East Asia. Distribution runs through captive Tier-1 module assembly parks adjacent to OEM transmission plants, bypassing traditional aftermarket warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Module-level service contracts encompassing tooling maintenance and alloy requalification support are expanding faster than discrete casting revenue, creating attach-rate opportunities for engineering-intensive suppliers.
For Market Incumbents: Compound defensive positioning through backward integration into captive zinc-alloy recycling and heat-recovery system standardization across multi-plant footprints. Aluminum substitution in structural brackets threatens volume retention; counter with integrated sensor-enclosure sub-assembly capabilities that capture electrical housing expansion. Prioritize NOM-052-SEMARNAT pre-compliance on slag disposal to preempt competitor dislocation. For New Entrants and Emerging Players: PROFEPA emissions certification fast-tracks for Baja California greenfield sites exploit underdeveloped foundry infrastructure near Tijuana assembly plants. White-space concentration sits in 48-volt connector module capacity for electrical housing specialists; secondary opportunity emerges in prototype tooling partnerships for 18-month EV requalification windows. Go-to-market positioning should emphasize precision miniaturization credentials transferred from aerospace-adjacent Querétaro engineering bases. For Investors and Strategic Acquirers: Capital is best deployed toward heat-recovery compliant mid-cap foundries with consolidated module assembly relationships and captive OEM qualification status. Long-term viability hinges on exposure to electrification-resistant applications and regulatory compliance infrastructure rather than commodity structural casting. Monitor NOM-001-SECRE enforcement timing as inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Recovery Retrofit Program | NOM-001-SECRE compliance elevates capital barriers against unconsolidated competitors. |
| Electrical Housing Capacity Expansion | 48-volt mild-hybrid architectures multiply connector demand beyond current foundry allocation. |
| Alloy Recycling Integration | Captive secondary zinc feedstock reduces ingot cost exposure and slag disposal burden. |
| Prototype Engineering Partnership | Accelerated EV requalification windows command premium pricing for tooling expertise. |
| Baja California Geographic Entry | First-mover positioning near Tijuana assembly plants captures nearshoring supply chain reconfiguration. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews across foundry operations, Tier-1 procurement functions, and OEM platform engineering teams. Secondary validation incorporated Mexican federal regulatory filings including PROFEPA emissions disclosures and NOM-001-SECRE compliance certifications, alongside SEC filings from listed automotive suppliers and vehicle production databases tracking assembly plant output. Bottom-up volume estimates from individual foundry capacity utilization were triangulated against top-down alloy consumption projections derived from transmission housing content-per-vehicle assumptions.
Across the analysis window, the forecasting framework modeled demand evolution across product type, application vehicle class, end-user procurement tier, and manufacturing stage maturity. CAGRs were synthesized from alloy-specific growth differentials between structural and electrical housing segments, with inputs including OEM electrification program timelines and NOM-052-SEMARNAT hazardous waste rule anticipation. Regional production cluster development and cross-border USMCA trade flow intensities informed geographic allocation.
Decision-makers should treat outputs as directional under assumptions of sustained nearshoring momentum and stable NOM-001-SECRE enforcement timelines; material deviation in natural gas price volatility or aluminum substitution acceleration would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Automotive Power Window Regulator Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Autonomous Forklift Market
Automotive Parts
Air Suspension Systems Market
Automotive Parts
Mobile Emission Catalysts Market
Automotive Parts
Off-Road Hoses Market
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
North America Passenger Vehicles Lubricants Market
Automotive Parts
Philippines Passenger Vehicles Lubricants Market
Automotive Parts
United States Passenger Vehicles Lubricants Market
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Steering System Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
Automotive Coupling Replacement Kit Market
Automotive Parts
Diesel Common Rail Injection System Market