
 Philippines Automotive Engine Oils Market | 2026-2036
Philippines Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Automotive Engine Oils Market Analytics
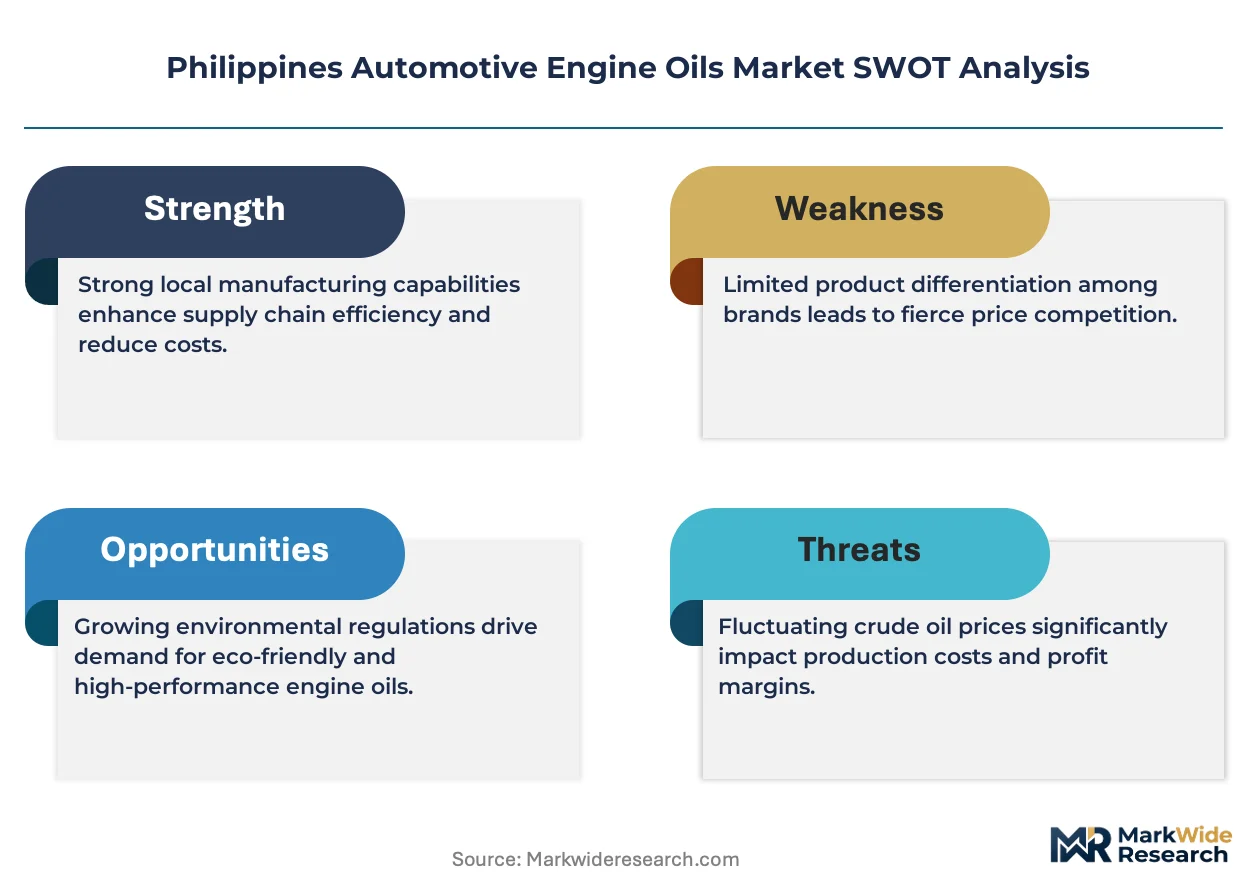
A shortage of certified lubricant blending technicians is unwinding capacity expansion plans at several Philippine refiners. Petron Corporation leverages its Bataan refinery integration to control feedstock costs for domestic engine oil production. Phoenix Petroleum competes through its archipelago-wide depot network, reaching service stations in secondary ports from Palawan to Mindanao. Seaoil Philippines anchors its position with dedicated logistics fleets serving provincial workshops outside Metro Manila.
Automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and prevent corrosion in internal combustion engines, with viscosity grades typically ranging from 0W-16 to 20W-50 under SAE classifications. Full synthetic formulations command premium positioning as turbocharged gasoline direct injection engines proliferate in Philippine passenger vehicle parc, while mineral oils retain volume leadership in price-sensitive two-wheeler service intervals. Fleet services represent the fastest-growing end user channel as corporate logistics operators centralize lubricant procurement under maintenance contracts. Workshops dominate distribution for commercial vehicle segments where owner-operators rely on mechanic recommendations rather than retail shelf selection.
The Department of Energy enforces fuel and lubricant quality standards through its Oil Industry Management Bureau, while the Department of Trade and Industry's Bureau of Philippine Standards mandates labeling and performance claims compliance under PNS specifications. These frameworks elevate compliance costs for importers but create barriers that favor domestic blenders with established laboratory certification. Stakeholders must monitor how proposed Euro 5 emission standards reshape OEM fill specifications and aftermarket viscosity grade preferences.
Market Dynamics
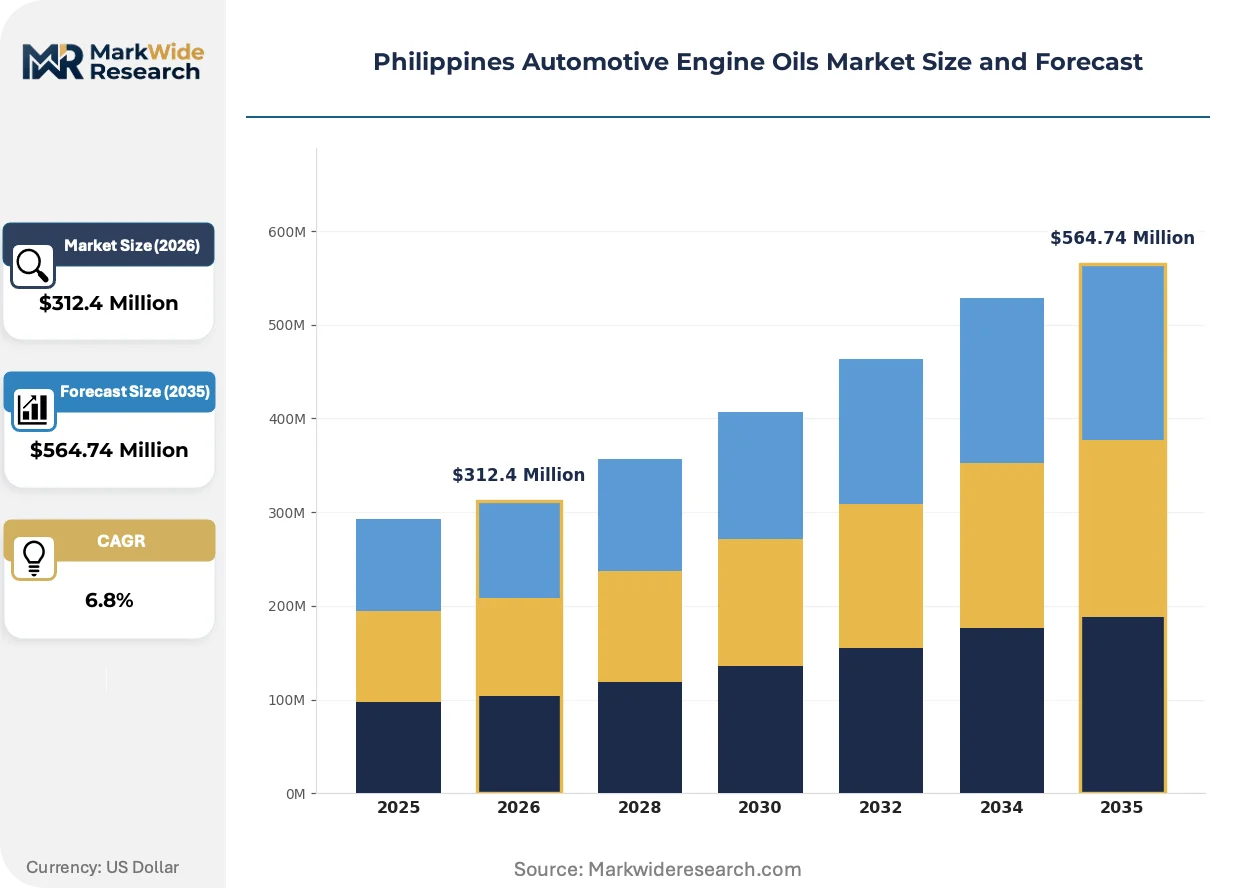
The Philippine automotive engine oils market is being reshaped by the Department of Energy's escalating fuel quality mandates, which are forcing blenders to migrate toward higher-grade Group II and III base stocks while certified technician shortages throttle capacity expansion at domestic refiners.
Growth Catalysts
- Euro 5 Pre-Compliance:Anticipated emission standards are accelerating OEM fill specification upgrades, creating pull-through demand for low-SAPS synthetic formulations in commercial vehicle workshops across Cavite and Laguna manufacturing corridors.
- Fleet Centralization:Logistics operators in Luzon are consolidating lubricant procurement under multi-year maintenance contracts, shifting volume from fragmented retail channels toward direct supplier relationships with certified blenders.
- Visayas Logistics Modernization:Port infrastructure upgrades in Cebu and Iloilo are extending service intervals for inter-island trucking fleets, driving consumption of extended-drain synthetic products previously concentrated in Metro Manila.
Market Restraints
- Base Stock Import Dependency:Philippine blenders rely on Group II/III feedstock shipments from Singapore and South Korea, exposing margin structures to freight volatility and currency fluctuation against the dollar-denominated spot market.
- Technician Certification Bottleneck:The Technical Education and Skills Development Authority lacks accredited training capacity for lubricant blending operations, constraining workforce expansion at Bataan and Batangas production facilities.
- Two-Wheeler Price Ceiling:Mineral oil formulations dominate motorcycle service intervals due to owner-operator resistance to synthetic premiums, limiting value-per-liter growth in the highest-volume vehicle segment.
Strategic Opportunities
- Mindanao Depot Network Gaps:Secondary ports from General Santos to Cagayan de Oro remain underserved by integrated lubricant logistics, creating white space for depot-based distribution models reaching provincial motorcycle repair clusters.
- Turbocharged Gasoline Direct Injection Proliferation:Japanese and Korean OEM assembly expansion in Santa Rosa is expanding the parc of TGDI engines requiring API SP/ILSAC GF-6 specifications, opening premium positioning for full synthetic portfolios.
- Bureau of Philippine Standards Enforcement:Tighter PNS labeling audits are disadvantaging gray-market importers, creating compliance-driven market share redistribution toward domestic blenders with certified laboratory infrastructure.
Industry Challenges
- Additive Package Sourcing Complexity:Formulators face extended lead times for friction modifier and detergent chemistry from European suppliers, complicating just-in-time blending schedules for fleet contract fulfillment.
- Workshop Channel Fragmentation:Owner-operators in commercial vehicle segments rely on mechanic recommendations rather than brand loyalty, requiring disproportionate technical service investment to secure volume commitments across dispersed provincial garages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Automotive Engine Oils Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Synthetic, Full Synthetic, Conventional, Mineral End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Fleet Services Distribution Channel: Retail Stores, Online Platforms, Service Stations, Workshops Packaging Type: Bottles, Drums, Totes, Bulk Containers |
| Companies Covered | Royal Dutch Shell Plc, Phoenix Petroleum, Petron Corporation, ExxonMobil Corporation, Seaoil Philippines, BP Plc (Castrol), TotalEnergies, ENEOS Corporation, Chevron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Automotive Engine Oils Market Evolving Landscape
Formulation chemistry and procurement architecture are undergoing parallel transformation as emission standards tighten and fleet operators professionalize lubricant sourcing. Three distinct vectors are compressing legacy market structures.
Full synthetic engine oil formulations is bifurcating the Philippine passenger vehicle aftermarket. These lubricants deliver thermal stability and deposit control required by turbocharged gasoline direct injection engines. Japanese and Korean OEM assemblers in Laguna and Cavite are specifying 0W-20 and 5W-30 grades for new vehicle fills. The technology is bifurcating workshop inventory requirements, forcing service stations to stock dual viscosity portfolios or surrender TGDI-equipped vehicles to dealer channels.
Department of Energy fuel quality regulations are cascading into lubricant specification mandates through the Oil Industry Management Bureau. The framework elevates base stock purity requirements and additive performance thresholds for products marketed as "energy conserving." Blenders without integrated refinery access face capital-intensive laboratory upgrades to maintain PNS certification. Metro Manila commercial vehicle corridors are experiencing the fastest compliance-driven product turnover as fleet operators pre-empt warranty disputes.
Corporate logistics procurement is consolidating lubricant purchasing under outcome-based maintenance contracts rather than transactional spot buying. Third-party fleet management providers in Luzon are specifying drain interval guarantees and used oil analysis inclusion. Provincial workshops outside Metro Manila are losing direct fleet relationships as procurement authority centralizes at headquarters level. The shift is most visible in Cavite manufacturing zones where electronics and automotive component exporters operate captive vehicle pools exceeding five hundred units.
Philippines Automotive Engine Oils Market Segmentation
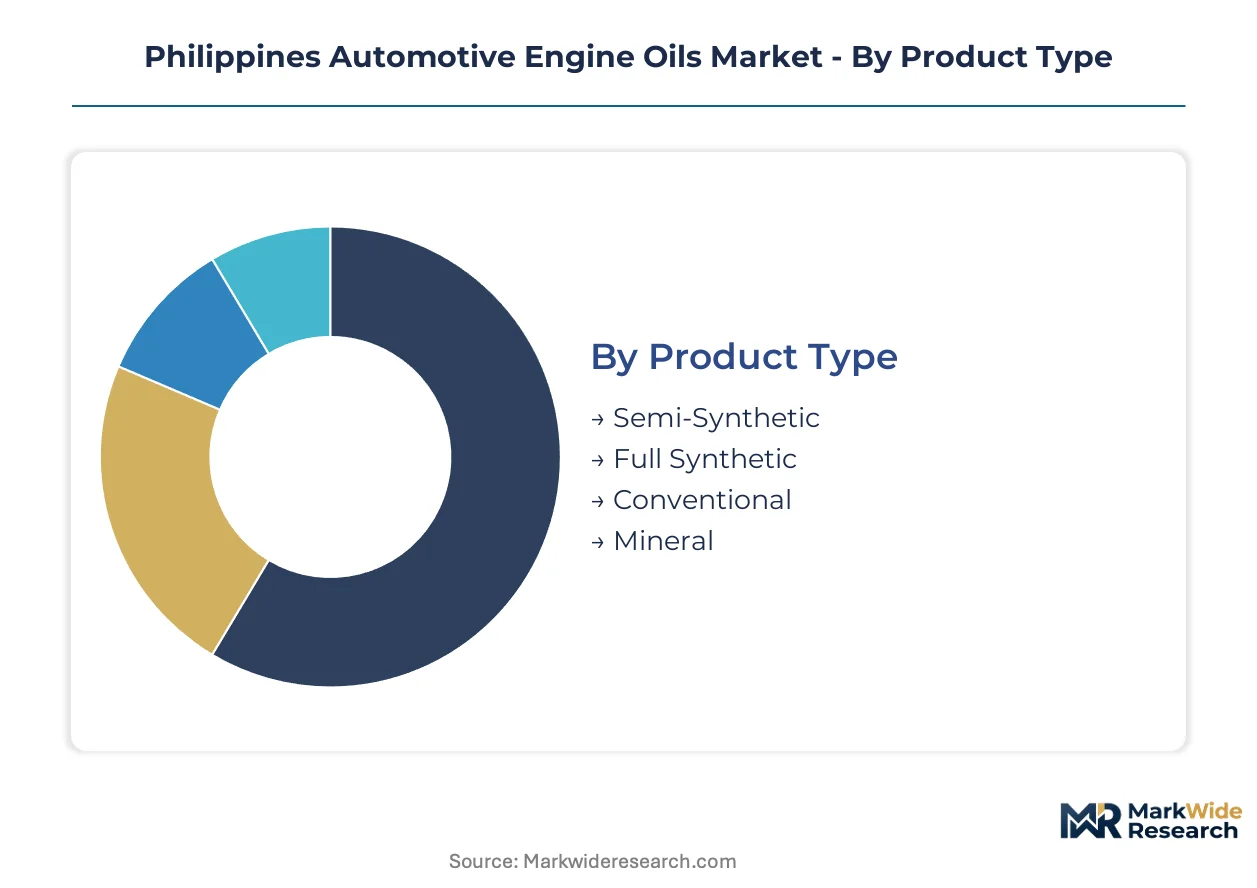
Segmentation in the Philippines automotive engine oils market reveals how procurement authority, technical specifications, and logistics infrastructure reshape competitive access. Each dimension exposes distinct margin architectures and channel control points that suppliers must navigate.
Product Type:
Premium formulations capture disproportionate margin pools as OEM fill specifications escalate and fleet operators professionalize sourcing decisions.
- Full Synthetic:These formulations blend Group III base stocks with high-performance additive packages delivering thermal stability for turbocharged gasoline direct injection engines. Demand concentrates in Cavite and Laguna manufacturing corridors where Japanese and Korean OEM assemblers specify 0W-20 and 5W-30 grades for new vehicle fills, constrained by additive package import lead times from European suppliers.
- Semi-Synthetic:Hybrid formulations balance performance upgrade paths against price sensitivity in the Philippine passenger vehicle aftermarket. Metro Manila service stations stock these grades for owners transitioning from mineral oils toward extended drain intervals, though workshop mechanics often default to full synthetic recommendations for TGDI-equipped vehicles.
- Conventional:Refined mineral base stocks with standard additive treat rates serve price-conscious owner-operators in provincial commercial vehicle segments.
- Mineral:Unadditized or lightly treated base oil formulations dominate motorcycle service intervals across Mindanao and Visayas repair clusters where synthetic premiums face resistance.
The dominant share belongs to Mineral, while Full Synthetic is closing the gap fastest.
End User:
Procurement centralization separates volume concentration from value capture across vehicle ownership models.
- Fleet Services:Corporate logistics operators in Luzon are consolidating lubricant purchasing under multi-year maintenance contracts with drain interval guarantees and used oil analysis inclusion. Cavite electronics exporters operating captive vehicle pools exceeding five hundred units have shifted procurement authority from provincial workshops to headquarters level, creating direct supplier relationships with certified blenders.
- Commercial Vehicles:Inter-island trucking fleets across Cebu and Iloilo port corridors drive consumption of extended-drain synthetic products as infrastructure upgrades extend service intervals. Owner-operators in this segment rely on mechanic recommendations rather than brand loyalty, requiring disproportionate technical service investment.
- Passenger Vehicles:Individual owners in Metro Manila's dense corridors follow OEM dealer specifications for warranty compliance, particularly for TGDI engine fills.
- Two-Wheelers:Motorcycle repair shops from General Santos to Cagayan de Oro represent high-volume, low-margin service intervals where mineral oil formulations retain near-total penetration.
Fleet Services commands the steepest expansion trajectory as procurement professionalizes, though Two-Wheelers still moves the largest absolute volumes.
Distribution Channel:
Channel selection determines technical service intensity and inventory carrying cost allocation between supplier and intermediary.
- Workshops:Provincial garages outside Metro Manila dominate commercial vehicle segment distribution where owner-operators depend on mechanic recommendations. These relationships require sustained technical service investment to secure volume commitments across dispersed geographic footprints.
- Service Stations:Integrated depot networks from Palawan to Mindanao anchor archipelago-wide reach for volume suppliers. Phoenix Petroleum leverages this infrastructure to compete against refinery-integrated players.
- Retail Stores:Shelf selection serves DIY passenger vehicle owners in urban corridors with established brand recognition.
- Online Platforms:Emerging channel for standardized viscosity grades in Metro Manila where buyers bypass workshop markup.
Workshops retain the dominant share in commercial vehicle segments, while Fleet Services procurement bypass is eroding their position fastest in Luzon.
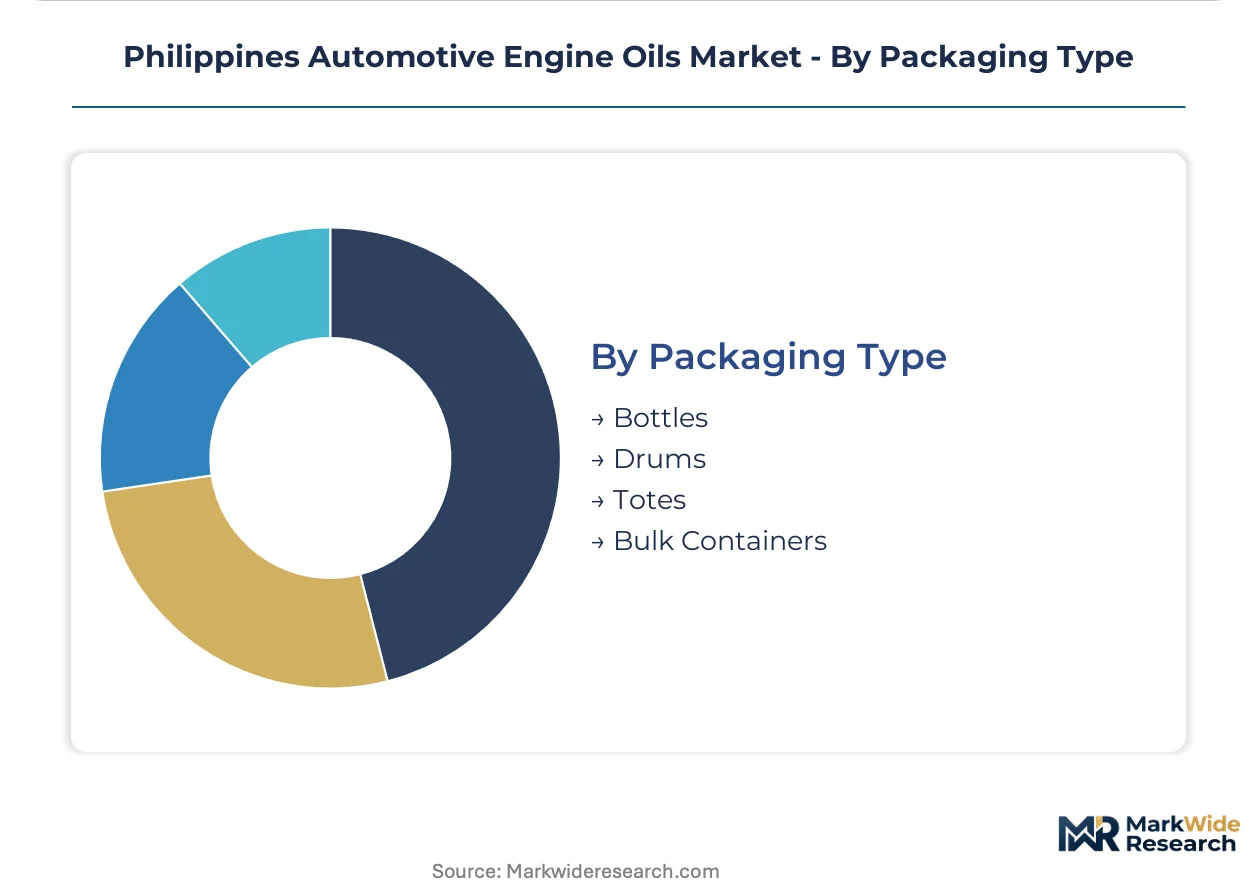
Packaging Type:
Packaging economics track procurement scale and logistics infrastructure maturity across the Philippine archipelago.
- Drums:Standard 200-liter containers serve fleet maintenance facilities and large workshops in Metro Manila and Cavite manufacturing zones with predictable consumption patterns and storage capacity.
- Bulk Containers:Direct-to-tank delivery supports high-volume fleet operators with captive vehicle pools and integrated depot infrastructure.
- Bottles:Retail-ready packaging for passenger vehicle DIY segments and small workshop replenishment.
- Totes:Intermediate bulk containers bridge drum and bulk economics for mid-scale fleet operators upgrading from transactional purchasing.
Drums dominate fleet and workshop procurement, though Bulk Containers are gaining share fastest as logistics centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Department of Energy's Oil Industry Management Bureau enforces fuel and lubricant quality standards that concentrate blending capacity around integrated refinery infrastructure and major demand corridors across the Philippine archipelago.
Metro Manila
Dense commercial vehicle corridors generate concentrated demand for fleet-grade synthetic formulations. The Department of Energy mandates PNS certification for all lubricants sold through retail channels. Cavite and Laguna manufacturing zones anchor OEM fill specification requirements for Japanese and Korean assemblers.
Luzon
Logistics modernization across Central Luzon and CALABARZON extends service intervals for inter-island trucking fleets. The Technical Education and Skills Development Authority lacks accredited training capacity for lubricant blending technicians. Bataan refinery integration supports domestic base stock production for regional supply.
Visayas
Port infrastructure upgrades in Cebu and Iloilo reshape fleet consumption patterns toward extended-drain synthetic products. The Bureau of Philippine Standards mandates labeling compliance for all imported lubricant formulations. Provincial workshops outside major metros depend on depot-based distribution from integrated suppliers.
Mindanao
Secondary ports from General Santos to Cagayan de Oro remain underserved by integrated lubricant logistics networks. The Department of Trade and Industry enforces PNS performance claims through periodic market surveillance. Motorcycle repair clusters in Davao and Zamboanga retain mineral oil dominance due to price-sensitive owner-operator segments.
Palawan
Archipelago-wide depot networks extend reach to isolated service stations dependent on maritime logistics. The Department of Energy's fuel quality regulations apply uniformly regardless of geographic remoteness. Puerto Princesa and Coron tourism corridors generate seasonal demand spikes for passenger vehicle service intervals.
Philippines Automotive Engine Oils Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with refinery-backed players controlling feedstock economics while depot-network operators compete on geographic reach. The market structure rewards backward integration into base stock supply and punishes blenders dependent on imported Group II/III shipments. Two strategic archetypes dominate: integrated refiners with captive laboratory certification and archipelago-wide logistics specialists with secondary port penetration. Competitive moves center on depot network expansion into Mindanao white space and formulation upgrades toward Euro 5 pre-compliance specifications.
Among integrated domestic players, Petron Corporation leverages Bataan refinery infrastructure to anchor supply security, while Phoenix Petroleum exemplifies the depot-network archetype through archipelago-wide distribution reach. Seaoil Philippines occupies a position bridging integrated and specialist tiers with dedicated logistics fleets serving provincial workshops. These three companies represent the competitive vectors reshaping procurement relationships as fleet operators centralize lubricant purchasing under multi-year maintenance contracts.
| Leading Market Players |
|---|
| Royal Dutch Shell Plc |
| Phoenix Petroleum |
| Petron Corporation |
| ExxonMobil Corporation |
| Seaoil Philippines |
| BP Plc (Castrol) |
| TotalEnergies |
| ENEOS Corporation |
| Chevron Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Luzon-based fleet operators and certified blenders lock in both Group II/III base stock supply access and price visibility across multi-year maintenance agreements, insulating procurement teams from freight volatility in the Singapore spot market while exposing smaller provincial workshops to transactional spot pricing.
Pricing Analysis
Contract-based long-term offtake dominates fleet procurement in Cavite manufacturing zones, while spot transactions prevail in Mindanao motorcycle repair clusters. Price differentiation rests on API certification tier and volume scale, with PNS-certified synthetics commanding premiums over gray-market mineral formulations. Cost compression in the two-wheeler segment is intensifying due to owner-operator resistance to synthetic upgrades. Fleet services exhibit lowest price sensitivity due to warranty compliance mandates, while provincial owner-operators show highest sensitivity to per-liter differentials.
Supply Chain Analysis
Singapore Strait transit underwrites Philippine blender access to Group II and III base stocks from South Korean and Singaporean refineries, with Batangas port serving as the primary receiving hub. Formulators draw from European additive suppliers for friction modifier and detergent chemistry, while domestic Bataan refinery production anchors regional supply security. Single-source vulnerability concentrates in additive package lead times from European specialty chemical houses. Distribution runs through archipelago-wide depot networks reaching secondary ports from Palawan to Mindanao.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement fragmentation across owner-operated commercial vehicles and centralized fleet contracts creates multiple entry niches for specialized positioning, as the shift toward outcome-based maintenance agreements concentrates volume authority at headquarters level while leaving provincial service intervals underserved.
For Market Incumbents: Fortify laboratory certification infrastructure to preempt Bureau of Philippine Standards enforcement actions that disadvantage gray-market competitors. Deepen backward integration into Bataan refinery feedstock streams to control margin structures against currency-exposed importers. Secure depot network expansion into General Santos and Cagayan de Oro before archipelago-wide logistics specialists capture Mindanao white space. For New Entrants and Emerging Players: Differentiate on technical service intensity targeting provincial commercial vehicle workshops where mechanic recommendations drive brand selection. Penetrate the Visayas inter-island trucking segment through Cebu and Iloilo port corridor relationships as infrastructure upgrades extend drain intervals. Deploy direct sales teams with used oil analysis capabilities to bypass fragmented retail channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet management providers with multi-year maintenance contracts and captive vehicle pools exceeding five hundred units. Long-term viability favors blenders with integrated refinery access and PNS-certified laboratory infrastructure over import-dependent formulators. Monitor Euro 5 pre-compliance timelines as the inflection indicator for specification upgrade cycles and premium synthetic penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Network Expansion | Archipelago-wide reach from Palawan to Mindanao secondary ports secures fleet contract access. |
| Backward Integration into Base Stocks | Bataan refinery integration insulates Petron Corporation from Singapore spot market volatility. |
| PNS Certification Investment | Laboratory infrastructure compliance creates barriers against gray-market importers under tighter audits. |
| Long-term Fleet Contracting | Multi-year maintenance agreements with drain interval guarantees lock in volume from Cavite exporters. |
| Technical Service Team Buildout | Provincial workshop relationships in commercial vehicle segments require sustained mechanic engagement investment. |
Research Methodology
A spread of perspectives from lubricant blending technicians, fleet procurement managers, provincial workshop owners, and Oil Industry Management Bureau regulators converged on the working assumptions underlying demand forecasts. Primary fieldwork combined structured interviews with downstream channel partners and upstream base stock procurement leads. Secondary validation drew from Bureau of Philippine Standards certification records, Department of Energy fuel quality directives, customs import data for Group II/III base oils, and SEC filings of integrated petroleum companies. Bottom-up volume estimates from end-user segments were triangulated against top-down capacity assessments of domestic blending facilities.
Segmentation dimensions modeled include product formulation tier, end-user procurement authority structure, distribution channel control points, and regional logistics infrastructure maturity across the analysis window. CAGRs were derived from elasticity-adjusted demand projections incorporating vehicle parc growth, service interval extension trends, and specification upgrade cycles. Industry-specific inputs encompassed OEM fill specification timelines from Japanese and Korean assemblers in Laguna and Cavite, plus TESDA technician training pipeline constraints affecting capacity expansion feasibility.
The analysis sits within stated boundaries; outcomes outside sustained Department of Energy enforcement of PNS labeling standards or accelerated Euro 5 adoption timelines would require recalibration. Forecasts reflect assumptions regarding fleet procurement centralization rates and additive package import lead time stability. Practitioners should keep alternative scenarios live as Technical Education and Skills Development Authority training capacity expansion and Singapore refinery output allocations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Bumper Beam Market
Automotive Parts
Car Phone Holder Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Global Automotive Door Hinges Market
Automotive Parts
Colombia Automotive Lubricants Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Wheel Arch Liner Market
Automotive Parts
Automotive Wheel Speed Sensor Tone Ring Market
Automotive Parts
South Africa Automotive Lubricants Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Engine Oil Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
Automotive Belts Market
Automotive Parts
Aluminum Parts Gravity Die Casting Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
Europe Automotive Parts Die Casting Market