
 Automotive Parts Aluminum Die Casting Market | 2026-2036
Automotive Parts Aluminum Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Parts Aluminum Die Casting Market Analysis
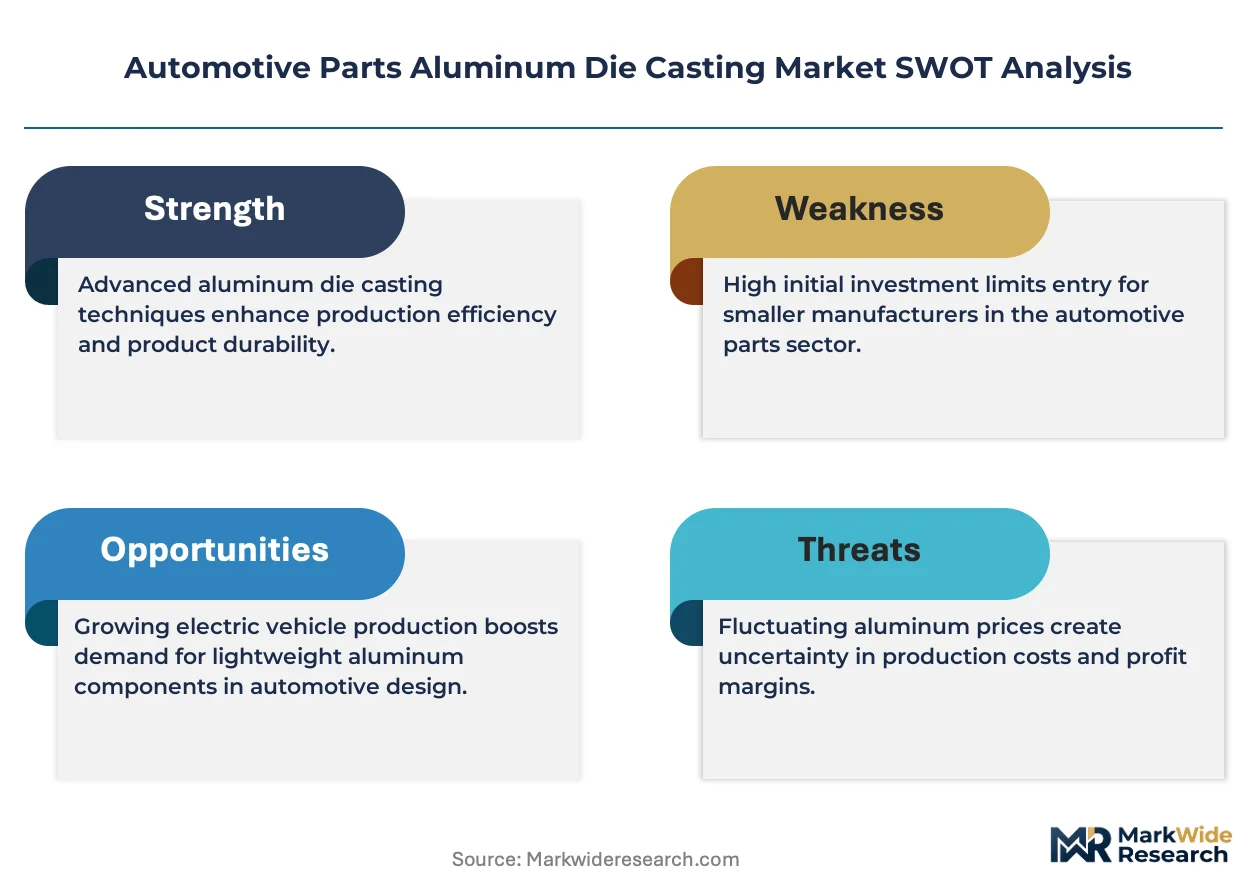
The EU Green Deal is broadening the cost-of-entry calculus for aluminum die casting suppliers serving European automotive OEMs. Nemak leverages its captive aluminum smelting capacity to sustain margin control across structural parts programs. GF Casting Solutions anchors its competitive position through vacuum die casting expertise for battery housing applications. Ryobi Die Casting dominates high-volume engine component supply to Japanese transplants in North America.
Automotive parts aluminum die casting involves injecting molten aluminum alloys—typically A380, A383, or AlSi10Mg—into hardened steel molds at pressures exceeding 1,000 bar to produce near-net-shape components with wall thicknesses below 2.5 millimeters. This process yields parts with excellent thermal conductivity and strength-to-weight ratios essential for powertrain thermal management and crash-critical structures. Structural parts, particularly battery trays and motor housings for electric vehicles, represent the fastest-expanding margin pool as OEMs consolidate multi-part assemblies into single castings. High pressure die casting maintains volume leadership in engine blocks and transmission cases, though vacuum die casting is displacing conventional methods for porosity-sensitive safety components.
The EPA, NHTSA, and EU F-Gas Regulation collectively shape product standards by mandating lightweighting credits, crash performance thresholds, and restrictions on process emissions from die casting foundries. China's MIIT enforces dual carbon goals that compel domestic foundries to retrofit melting operations with electric holding furnaces, altering equipment procurement patterns. Stakeholders must monitor how battery-electric platform architectures redefine casting complexity requirements versus traditional internal combustion part families.
Market Dynamics
Platform consolidation around battery-electric architectures is compressing part counts while demanding larger, more complex single-cast structural components that legacy foundry footprints cannot produce without substantial retooling.
Growth Catalysts
- EU Green Deal fleet CO2 mandates:OEMs must achieve 55% emissions reductions by 2030, forcing rapid aluminum substitution for steel in chassis and body-in-white structures to meet weight targets.
- Gigacasting process maturation:Tesla's 6,000-9,000 ton press deployments have validated single-piece rear underbody castings, prompting BMW and Volkswagen to qualify similar equipment for their Neue Klasse and Trinity platforms.
- China MIIT dual carbon enforcement:Domestic foundries face mandatory electric furnace retrofits and renewable energy quotas, accelerating capacity consolidation toward technically advanced producers capable of serving export-tier EV supply chains.
Market Restraints
- Primary aluminum price volatility:LME aluminum contracts swing with Chinese smelter curtailments and European energy costs, compressing margins on fixed-price annual supply agreements common in German OEM sourcing.
- High-purity alloy supply concentration:Low-carbon primary aluminum and specialized AlSi10MgCu alloys for thin-wall castings concentrate among Norwegian and Middle Eastern smelters, creating single-source vulnerability for European structural parts programs.
- Porosity limitations in conventional HPDC:Air entrapment in high-pressure die casting yields reject rates above 15% for vacuum-sensitive safety components, restricting process applicability for crash-critical B-pillar and suspension nodes.
Strategic Opportunities
- India PLI scheme for auto component manufacturing:Tier-2 foundries can access 8-13% production-linked incentives for advanced aluminum components, establishing export capacity before domestic EV assembly scales.
- Integration of real-time X-ray inspection with AI defect classification:Machine vision systems trained on porosity patterns enable 100% inline quality verification, opening closed-loop process control contracts with premium EV brands.
- EU F-Gas Regulation phase-down:Restrictions on SF6 cover gas for magnesium die casting create competitive opening for aluminum substitutes in steering columns and seat frames previously magnesium-dominated.
Industry Challenges
- Tooling engineer scarcity:Design of thermal management systems for 4,000+ ton dies requires specialized simulation expertise that foundries struggle to recruit against semiconductor and aerospace sectors.
- Heat treatment bottleneck capacity:T7 solution aging for high-strength structural castings demands continuous roller hearth furnaces with 18-month lead times, constraining qualification schedules for new EV platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Parts Aluminum Die Casting Market |
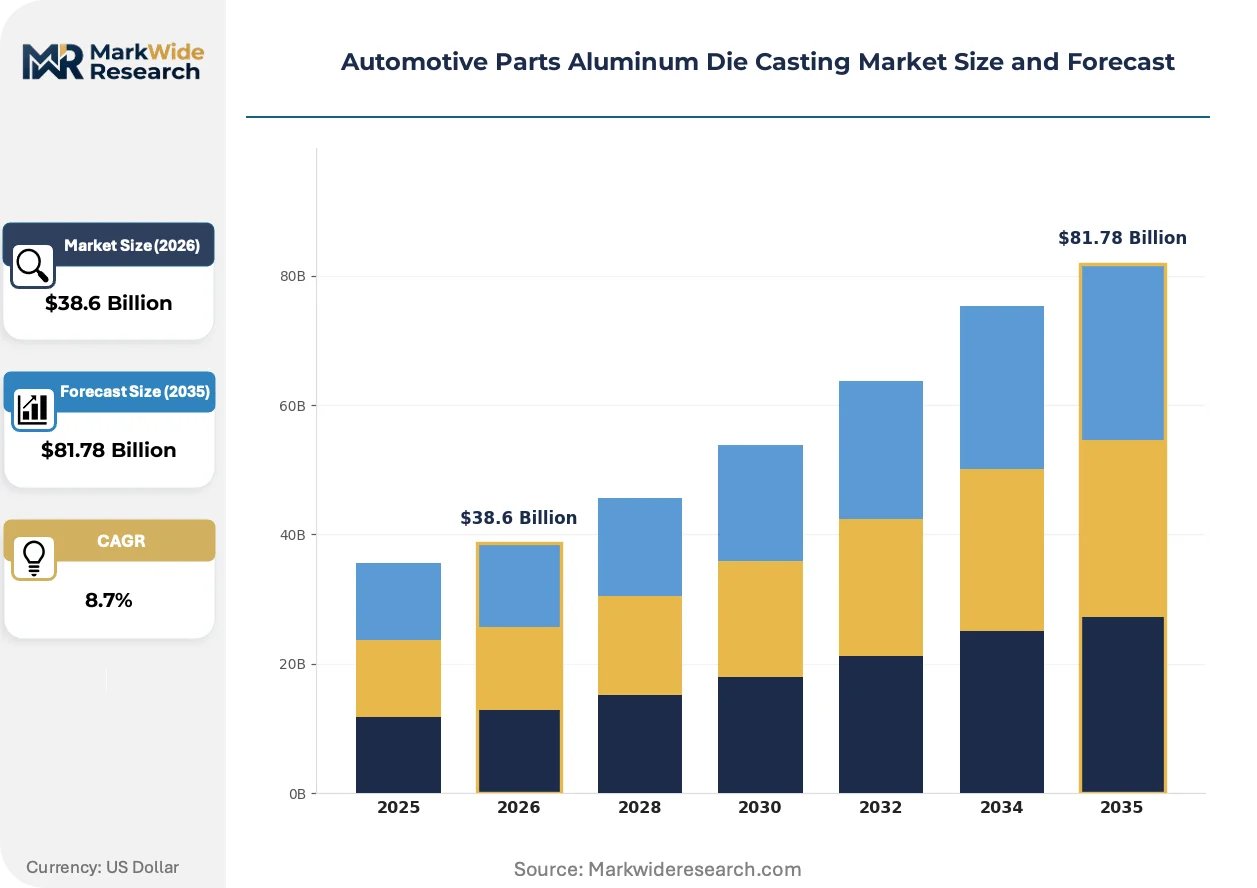
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Housings, Structural Parts, Chassis Components End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Off-Road Vehicles Technology: High Pressure Die Casting, Low Pressure Die Casting, Vacuum Die Casting, Cold Chamber Die Casting |
| Companies Covered | Pace Industries, Gibbs Die Casting, Nemak, Linamar Corporation, Endurance Technologies, Ryobi Die Casting, GF Casting Solutions, Martinrea International, Form Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Parts Aluminum Die Casting Market Emerging Trajectories
Process physics and regulatory chemistry are converging to redefine acceptable defect thresholds and energy intensity benchmarks across aluminum foundry operations worldwide.
AlSi10MgCu alloys with optimized copper content are electrifying the feasibility of 1.2-millimeter wall thicknesses in battery tray castings. European premium EV manufacturers are specifying these grades for 2026 platform launches. This chemistry is electrifying the displacement of multi-piece extrusion-and-weld assemblies with single-cast structural nodes.
The EU F-Gas Regulation's 2030 phase-down of hydrofluorocarbon blowing agents is compelling foundries to retrofit lost-foam and sand core processes with inorganic binder systems. Industrial consequence includes 12-18 month requalification cycles for existing part approvals. Battery housing suppliers serving Stuttgart and Munich OEM clusters are most affected, accelerating partnerships with Spanish and Italian chemical specialists for water-glass alternative binders.
Consolidated procurement of mega-castings is compressing supplier bases from fifteen-plus Tier-2 foundries per vehicle program to three or fewer capable of 4,000-ton-plus press operation. Direct sourcing relationships are replacing traditional Tier-1 integrator structures for structural aluminum. This concentration is most visible in California and Shanghai, where Tesla's verticalized supply model has trained purchasing teams to negotiate directly with foundry operators for Class A surface finish components.
Automotive Parts Aluminum Die Casting Market Segmentation
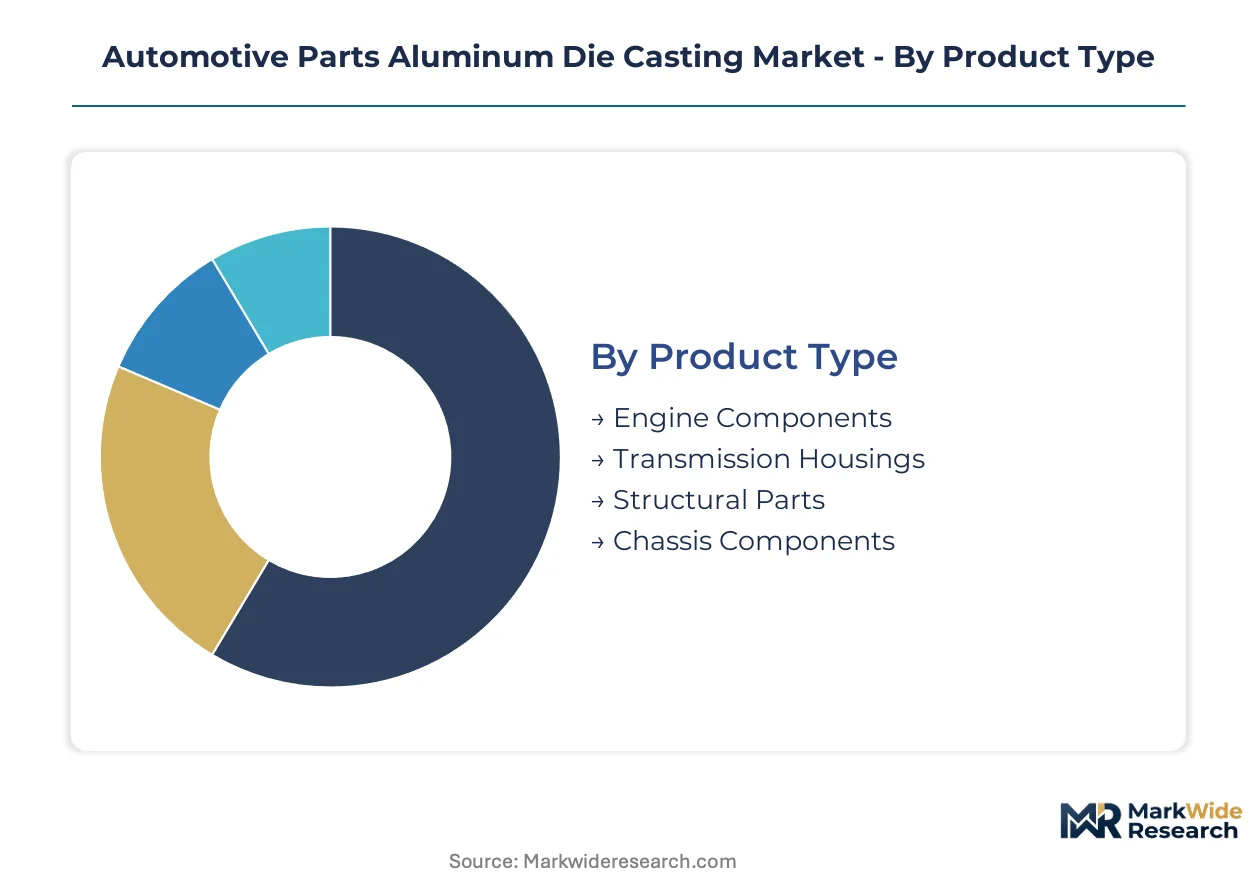
Aluminum die casting segments split sharply between legacy powertrain applications and emerging structural roles for electric platforms. Understanding these fault lines reveals where capital deployment and technical qualification cycles concentrate.
Product Type:
Standalone castings for thermal management contrast with embedded structural nodes that integrate crash management and battery mounting functions.
- Engine Components:Cylinder heads, blocks, and covers utilize A380 alloy for thermal conductivity above 96 W/mK. Demand clusters in Stuttgart, Munich, and Wolfsburg where German OEMs maintain internal combustion production lines alongside electrification transitions.
- Transmission Housings:These enclosures require pressure-tight integrity for fluid retention across -40°C to 150°C operating ranges. BMW and Volkswagen dual-clutch programs in Germany sustain volume despite platform consolidation pressures.
- Structural Parts:Battery trays and motor housings consolidate multi-part assemblies.
- Chassis Components:Steering knuckles and control arms serve suspension systems.
Volume placements concentrate in Engine Components; the faster expansion belongs to Structural Parts.
End User:
Procurement authority shifts with casting complexity—simple geometry flows through intermediaries while mega-castings demand direct foundry relationships.
- OEMs:Volkswagen, BMW, and Mercedes-Benz source structural aluminum directly for Neue Klasse and Trinity platforms, bypassing traditional Tier-1 integrators for 4,000-ton press capacity.
- Tier-1 Suppliers:Continental and ZF aggregate engine components from multiple foundries, managing logistics and quality gates for German OEM assembly plants.
- Aftermarket Providers:Replacement cylinder heads and transmission cases serve aging vehicle populations.
- Vehicle Assemblers:Contract manufacturers without captive casting capabilities purchase finished subassemblies.
Contract structures favor OEMs for structural programs; Tier-1 Suppliers retain engine component intermediation.
Application:
Weight reduction mandates penetrate differently across vehicle classes, with electrification forcing the steepest aluminum intensity gains.
- Electric Vehicles:Battery enclosures and motor housings demand AlSi10MgCu alloys for 1.2-millimeter wall feasibility. Tesla's gigacasting validation in California and Shanghai has reset OEM technical specifications.
- Passenger Vehicles:Internal combustion models in Germany and Japan sustain transmission and engine block demand even as platform share erodes.
- Commercial Vehicles:Truck chassis and suspension components prioritize durability over weight minimization.
- Off-Road Vehicles:Construction and agricultural equipment uses aluminum for corrosion resistance in harsh environments.
Capital allocation tilts toward Electric Vehicles; Passenger Vehicles maintain absolute volume leadership.
Technology:
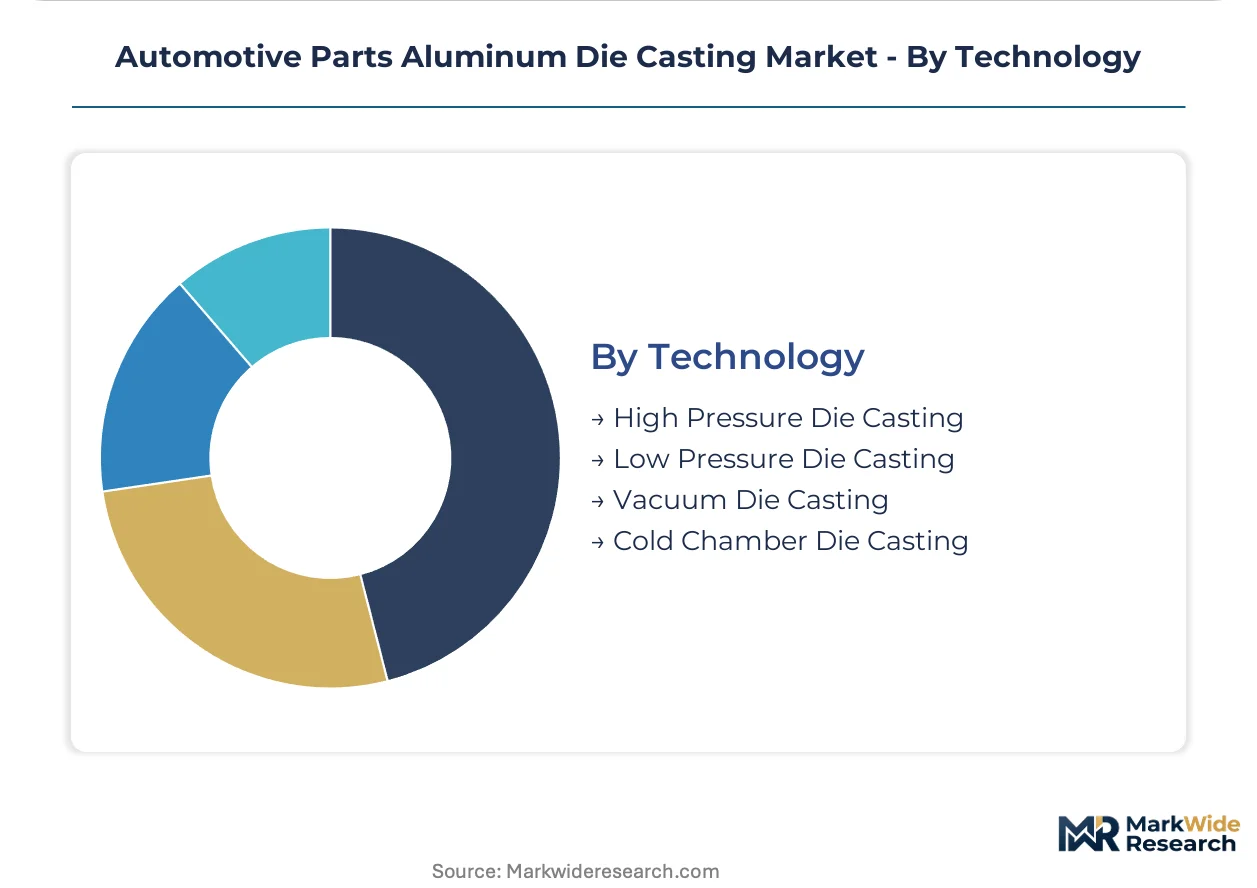
Process selection trades cycle time against porosity tolerance, with vacuum methods gaining share in safety-critical applications.
- Vacuum Die Casting:Reduced air entrapment enables heat-treatable T7 temper for crash-critical B-pillars and suspension nodes. GF Casting Solutions anchors German supply for battery housings requiring leak-tight integrity.
- High Pressure Die Casting:Cycle times under 60 seconds dominate engine block production. Nemak's captive smelting in Mexico and Europe sustains margin control across high-volume programs.
- Low Pressure Die Casting:Slower fill rates suit wheel and structural node applications.
- Cold Chamber Die Casting:Molten metal ladling accommodates high-melting-point alloys.
Equipment investment concentrates in High Pressure Die Casting; qualification momentum favors Vacuum Die Casting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automotive aluminum die castings concentrates where German OEMs operate dense supplier networks and where Chinese EV manufacturers scale battery platform production. The report examines five countries where foundry capacity, regulatory pressure, and vehicle assembly intersect.
Germany
BMW, Mercedes-Benz, and Volkswagen sustain high-pressure die casting demand for Neue Klasse and Trinity platform components. The EU Green Deal's 55% fleet CO2 reduction mandate by 2030 accelerates aluminum substitution in chassis structures. Stuttgart and Munich anchor supplier networks where foundries retool for 4,000-ton press capacity.
China
Domestic EV manufacturers deploy gigacasting for rear underbody single-piece structures. MIIT enforces dual carbon goals requiring electric furnace retrofits at domestic foundries. Yangtze River Delta clusters around Shanghai concentrate technically advanced producers serving export-tier battery supply chains.
United States
Detroit Three OEMs source transmission housings and structural nodes from regional foundries. EPA and NHTSA lightweighting credits push aluminum intensity in pickup truck platforms. Southeast Michigan and Indiana maintain legacy engine component capacity alongside EV transition investments.
India
Maruti Suzuki and Tata Motors expand aluminum casting procurement for domestic passenger vehicle programs. PLI scheme incentives offer 8-13% production-linked support for advanced auto components. Tamil Nadu and Maharashtra host Tier-2 foundries building export capacity ahead of domestic EV assembly scale.
Japan
Toyota and Honda sustain precision die casting demand for hybrid powertrain thermal management components. METI carbon neutrality roadmaps pressure foundries to adopt electric melting and renewable energy. Aichi Prefecture around Nagoya maintains concentrated supplier networks for high-volume engine part programs.
Automotive Parts Aluminum Die Casting Market Vendor Landscape
German and Japanese producers anchor one tier; Mexican and Indian specialists hold cost-optimized positions for high-volume engine components. The vendor base splits between consolidated multi-press operators and fragmented single-site foundries. Three archetypes dominate: captive smelting integrated players, vacuum die casting technology specialists, and scale-driven high-volume engine component suppliers. Competitive moves concentrate on 4,000-ton press capacity expansion and direct OEM qualification partnerships that bypass traditional Tier-1 integrators.
Among North American fabricators, Pace Industries and Gibbs Die Casting occupy positions within the high-volume automotive supply tier. Nemak exemplifies captive smelting integration with aluminum production capacity in Mexico and Europe. GF Casting Solutions represents vacuum die casting specialization for porosity-sensitive structural applications. These three companies illustrate how geographic footprint and process technology stratify competitive positioning across engine, transmission, and emerging EV structural segments.
| Leading Market Players |
|---|
| Pace Industries |
| Gibbs Die Casting |
| Nemak |
| Linamar Corporation |
| Endurance Technologies |
| Ryobi Die Casting |
| GF Casting Solutions |
| Martinrea International |
| Form Technologies |
| Others |
Supply Flow & Price Mechanics
German OEM direct sourcing teams for Neue Klasse and Trinity platforms command project-based long-term contracts with price adjustment clauses tied to LME aluminum volatility. This buyer concentration shifts pricing power toward foundries with captive smelting or 4,000-ton press capacity, while Tier-2 suppliers without technical differentiation face margin compression on fixed-price annual agreements.
Pricing Analysis
Short lead-time premiums for T7 heat treatment capacity now separate qualified suppliers from spot-market foundries with 18-month equipment backlogs. Three-tier pricing structure across vacuum-certified, conventional HPDC, and spot-resale tiers reflects certification investment and press scale. Cost compression in conventional engine components is intensifying because platform consolidation erodes volume commitments. Aftermarket distributors exhibit highest price sensitivity; OEM structural programs show lowest sensitivity due to qualification switching costs.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Detroit manage hub-and-spoke patterns for just-in-time assembly plant delivery. Primary supply concentrates in Germany, China, and Mexico, with German foundries serving premium structural programs and Mexican operators handling high-volume engine components. The chain draws from low-carbon primary aluminum in Norway, specialized AlSi10MgCu alloy from Middle Eastern smelters, and hardened steel die tooling from Japanese specialists. Single-source vulnerability for high-purity alloy creates structural risk. Distribution runs through direct OEM contracts for mega-castings, bypassing traditional Tier-1 integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a die-casting technology-transition phase where vacuum-assisted and gigacasting processes displace conventional HPDC for structural EV applications.
For Market Incumbents: Anticipate qualification delays from tooling engineer scarcity and heat treatment bottlenecks by securing exclusive furnace partnerships before Neue Klasse platform ramp. Defend margin position through backward integration into aluminum smelting or alloy formulation, following Nemak's captive supply model. Prioritize T7 temper certification for crash-critical battery tray programs to differentiate against commodity casting competitors. For New Entrants and Emerging Players: Tier-2 foundry partnerships in Tamil Nadu and Maharashtra offer the most penetrable entry channel under India's PLI scheme incentives. Target vacuum die casting qualification for battery housing applications where GF Casting Solutions holds limited capacity expansion. Pursue direct OEM engineering relationships rather than Tier-1 integrator channels, as Tesla's verticalized sourcing model trains purchasing teams to evaluate foundry capabilities directly. For Investors and Strategic Acquirers: The window for entry favors vacuum die casting specialists with existing T7 qualification and 4,000-ton press operational experience. Mid-cap foundries with technical capability but underutilized heat treatment capacity represent prime acquisition targets. Monitor MIIT enforcement patterns in China as the inflection signal—accelerated electric furnace retrofit mandates will consolidate domestic capacity toward export-tier producers, creating distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Gigacasting Capacity Expansion | 4,000-ton press deployment qualifies suppliers for BMW and Volkswagen mega-casting programs. |
| Vacuum Die Casting Qualification | T7 temper capability opens battery housing contracts with Stuttgart and Munich OEM clusters. |
| Captive Aluminum Smelting Integration | Backward integration into primary metal production insulates margins from LME volatility. |
| Heat Treatment Furnace Partnership | Exclusive roller hearth access compresses EV platform launch qualification schedules. |
| AI-Enabled Quality Verification | Real-time X-ray inspection contracts secure closed-loop partnerships with premium EV brands. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, foundry operations directors, and heat treatment equipment specialists combined with secondary validation from EPA and NHTSA regulatory databases, EU F-Gas Regulation implementation reports, and MIIT dual carbon enforcement notices. Bottom-up part-level build-up and top-down OEM production planning triangulated volume estimates across the analysis window.
Data-stream reconciliation across vehicle production databases, IHS Markit registration data, and foundry capacity utilization surveys shaped the analytical framework. Segmentation dimensions modeled include propulsion architecture, casting complexity tier, OEM sourcing tier, and regional production cluster. CAGRs were derived from fitted growth curves applied to technology-penetration assumptions, with EV platform launch schedules and alloy qualification timelines as critical forecast inputs.
Caveats apply where MIIT enforcement intensity, EU Green Deal fleet mandate calibration, or primary aluminum price volatility could materially shift the outlook. Forecasts reflect documented assumptions regarding gigacasting adoption rates and heat treatment capacity expansion timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Coupling Replacement Kit Market
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
Automotive Composite Leaf Springs Market
Automotive Parts
Global Automotive Muffler Tip Market
Automotive Parts
Autocatalyst Market
Automotive Parts
Cam Trigger Kits Market
Automotive Parts
Automotive Fluids Market
Automotive Parts
Road Marking Machine Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Electric Brake Booster Market
Automotive Parts
Automotive Electric Water Pump Market
Automotive Parts
Automotive Propeller Shaft Couplings Market
Automotive Parts
Spain Passenger Vehicles Lubricants Market
Automotive Parts
North America Automotive Actuators Market
Automotive Parts
South America Automotive Lubricants Market