
 Global Automotive Plain Carbon ERW Tubes Market | 2026-2036
Global Automotive Plain Carbon ERW Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Plain Carbon ERW Tubes Market Intelligence
Just-in-time inventory management and custom-length cutting services are repositioning the value proposition beyond mere material supply. ArcelorMittal leverages its extensive global manufacturing footprint to serve multinational automotive platforms. Nippon Steel Corporation specializes in developing advanced high-strength steel grades for safety-critical applications. Tata Steel sustains its market presence through integrated production facilities and strong distribution networks in India and Europe.
Automotive plain carbon ERW tubes are cylindrical steel products made by cold-forming a steel strip and welding the seam with an electric current. They are produced to precise outer diameter and wall thickness specifications for structural use in vehicles. Within applications, chassis and frame components represent a mature, high-volume segment. Concurrently, demand for cold rolled ERW tubes is rising for suspension systems where dimensional accuracy is critical.
Product quality is governed by standards like ISO 9001 and national material codes such as China's GB standards. Emissions regulations from the US EPA and under the EU Green Deal indirectly influence material choice by promoting vehicle lightweighting. Tube manufacturers must therefore balance the cost of plain carbon steel with performance needs for next-generation vehicle architectures.
Market Dynamics
The imperative for vehicle lightweighting, driven by stringent global emissions regulations, is the central force shaping the automotive plain carbon ERW tube market. This pressure compels a continuous evolution in material science and manufacturing precision to meet next-generation vehicle design requirements.
Growth Catalysts
- Lightweighting Mandates:Regulations such as the EU's CO2 emission performance standards for new passenger cars and the US EPA's fuel economy targets compel automakers to use lighter components, increasing the specification of high-strength, thin-wall ERW tubes in chassis and suspension systems.
- Automotive Production in China:The sustained expansion of automotive manufacturing capacity in China creates a large, concentrated demand base for ERW tubes, particularly for domestic vehicle platforms and joint ventures adhering to national GB standards for materials.
- Suspension System Complexity:Increasing consumer expectations for ride comfort and handling performance drive demand for more sophisticated suspension designs, which rely on the dimensional accuracy and strength of cold rolled ERW tubes for components like control arms and shock absorber bodies.
Market Restraints
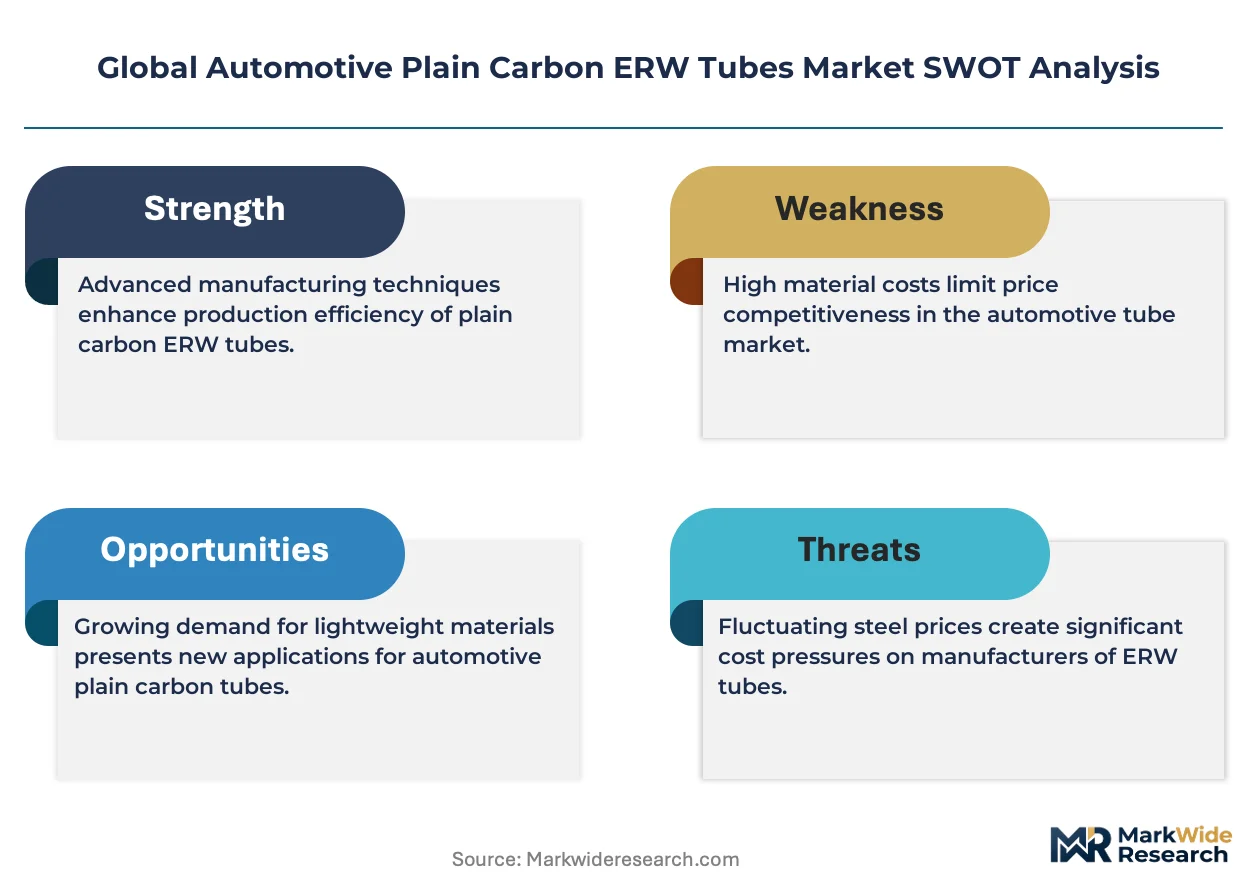
- Input Cost Volatility:The price of hot-rolled steel coil, the primary raw material for ERW tubes, is subject to significant fluctuations based on global supply, energy costs, and trade policies, creating margin pressure and planning uncertainty for tube manufacturers.
- Substitution from Alternative Materials:In certain non-structural or semi-structural applications, plain carbon steel tubes face competition from lighter materials like aluminum extrusions and advanced polymer composites, especially in the premium and electric vehicle segments.
- Technical Limitations:While strong, plain carbon steel has a lower strength-to-weight ratio compared to advanced high-strength steels or aluminum alloys, limiting its use in applications where mass reduction is the absolute primary design goal.
Strategic Opportunities
- Electric Vehicle Architectures:The shift to battery electric vehicles (BEVs) creates new applications for ERW tubes in battery pack frames, cooling circuit conduits, and specialized sub-frame structures designed to protect powertrain components.
- High-Strength Carbon Steel Grades:Developing new, more formable grades of plain carbon steel that offer higher tensile strength presents an opportunity to provide a cost-effective alternative to more expensive alloyed steels for safety and structural parts.
- Automotive Growth in Mexico:Mexico's expanding role as a key automotive manufacturing hub for the North American market offers significant growth potential for tube suppliers that can establish local production or efficient supply chains to serve assembly plants there.
Industry Challenges
- Capital Investment for Precision:Upgrading ERW mills to produce tubes with the extremely tight tolerances on wall thickness and outer diameter required for modern suspension and chassis parts demands significant capital expenditure.
- Welding and Forming Expertise:A shortage of skilled metallurgists and process engineers who specialize in the high-frequency induction welding and cold-forming of advanced high-strength carbon steels can constrain a manufacturer's ability to innovate.
- OEM Qualification Timelines:Gaining approval as a supplier for a new automotive platform is a lengthy and resource-intensive process, involving rigorous testing and validation that can create a barrier to entry for new market participants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Plain Carbon ERW Tubes Market |
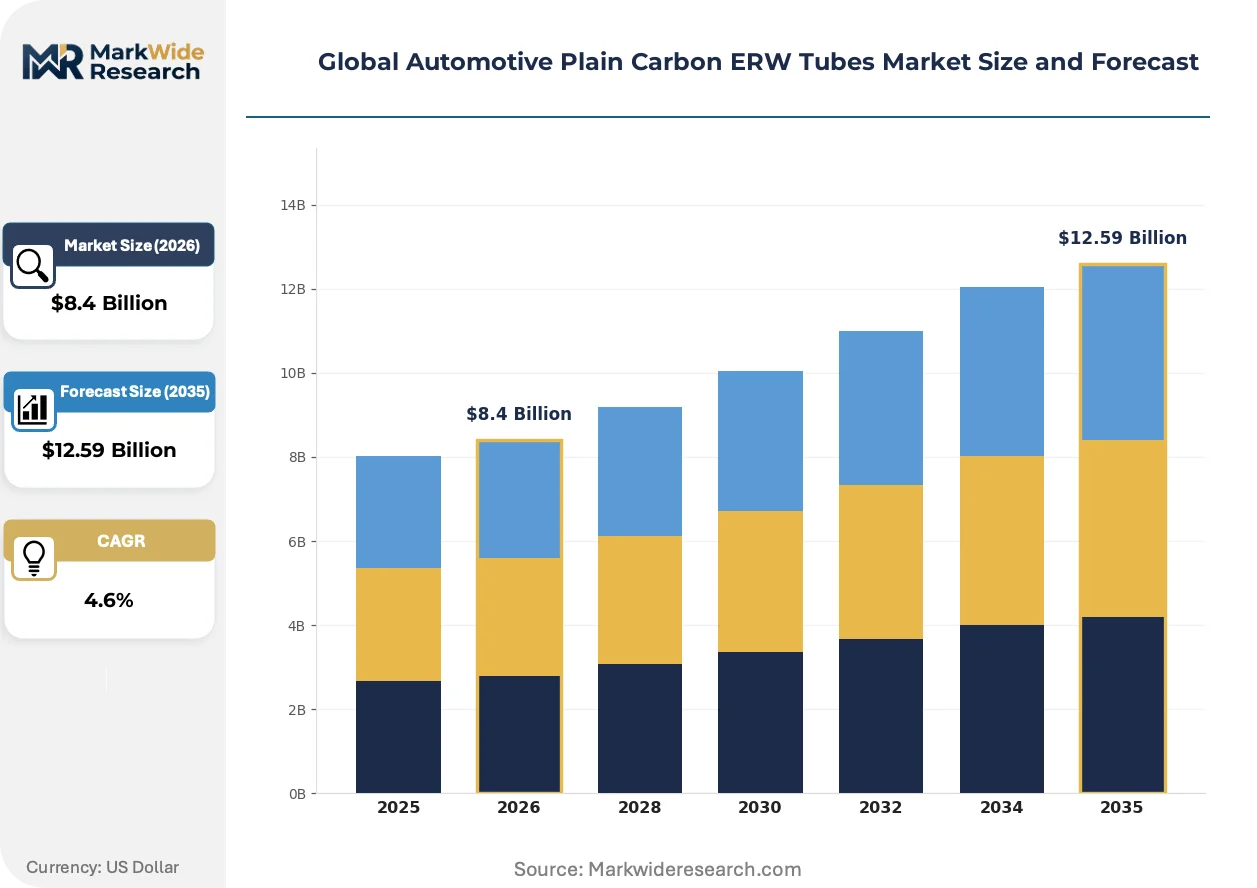
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Rolled ERW Tubes, Cold Rolled ERW Tubes, Galvanized ERW Tubes, Black ERW Tubes Technology: Electric Resistance Welding, High Frequency Welding, Seamless Manufacturing, Induction Heating Welding Application: Chassis & Frame, Suspension Systems, Gear Box Sleeves, Engine Components, Steering Systems End User Industry: Vehicle Assemblers, Tier-1 Suppliers, Aftermarket Providers, Specialty Vehicle Manufacturers |
| Companies Covered | ArcelorMittal, Nippon Steel Corporation, Tata Steel, JFE Steel Corporation, Vallourec, Tenaris, Maharashtra Seamless Ltd., Welspun Corp Ltd., Thyssenkrupp AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Plain Carbon ERW Tubes Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from supplying a commodity product to providing engineered solutions. This includes offering advanced material grades and integrated services like custom cutting and just-in-time logistics, which are becoming standard expectations from automotive clients.
Advanced high-strength steel (AHSS) grades are a key product evolution for ERW tube production. Automotive OEMs increasingly specify these materials for safety-critical components like side-impact beams and A-pillars to meet stringent crash test standards. The adoption of AHSS is accelerating across mainstream vehicle platforms, and this technology is modularizing chassis development by allowing for tailored strength in specific areas without altering component geometry.
Regulatory frameworks focused on sustainability are influencing material specifications beyond just lightweighting. The EU Green Deal and its associated directives, for example, are pushing for greater use of recycled materials and lower-carbon production processes throughout the automotive supply chain. This affects ERW tube manufacturers by creating demand for products with documented recycled content and a lower cradle-to-gate carbon footprint, impacting sourcing and production decisions.
Supplier relationships are transforming from transactional orders to deep-seated co-development partnerships. Tier 1 suppliers and OEMs now involve tube manufacturers early in the vehicle design process to optimize component performance and manufacturability, bypassing traditional multi-layered distribution. This collaborative model is most prominent within the highly integrated automotive clusters of Germany and Japan, where supply chain efficiency is paramount.
Global Automotive Plain Carbon ERW Tubes Market Segmentation
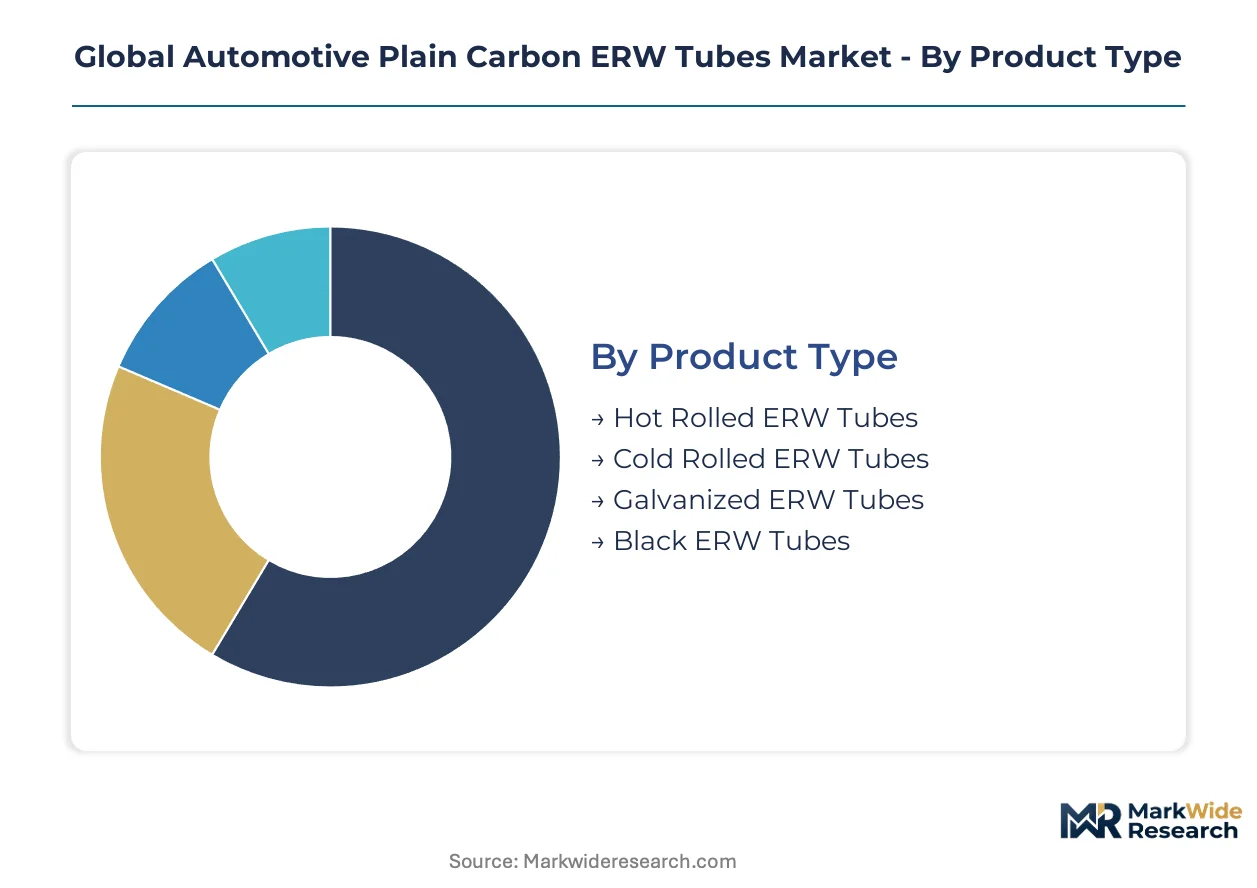
The Global Automotive Plain Carbon ERW Tubes Market is segmented to understand how diverse product specifications, manufacturing processes, end-use applications, and customer types influence demand dynamics. This granular analysis reveals specific areas of growth and competition across the automotive supply chain.
Product Type:
Buyer selection in this category is differentiated by required mechanical properties, surface finish, and corrosion resistance for specific vehicle components.
- Cold Rolled ERW Tubes:These tubes undergo additional cold working after welding, resulting in superior dimensional accuracy, smoother surface finish, and enhanced mechanical strength for precision applications. Demand for these tubes is concentrating in European suspension systems, driven by stringent performance and dimensional tolerance requirements.
- Hot Rolled ERW Tubes:Formed from hot-rolled steel coil, these tubes offer good strength and cost-effectiveness, suitable for less demanding structural applications where surface finish is not critical. Chinese automotive manufacturing platforms utilize significant volumes of hot rolled ERW tubes for chassis and frame components, adhering to national GB standards.
- Galvanized ERW Tubes:Coated with a layer of zinc, these tubes provide enhanced corrosion protection, making them suitable for exterior or moisture-exposed vehicle parts. Automakers in regions with harsh weather conditions, such as Canada, specify these tubes to extend vehicle lifespan.
- Black ERW Tubes:These tubes retain the black scale from the hot rolling process and are typically used in applications where corrosion resistance is not a primary concern or where they will be further processed. Manufacturers frequently use them for internal structural elements.
Volume sits with Hot Rolled ERW Tubes; growth tilts toward Cold Rolled ERW Tubes.
Technology:
The chosen manufacturing technology directly impacts the tube's structural integrity, weld quality, and production efficiency, influencing its suitability for critical automotive parts.
- Electric Resistance Welding:This fundamental method forms tubes by passing an electric current through the edges of a steel strip, heating and fusing them under pressure without filler metal. It is a widely adopted, cost-effective process for high-volume production of automotive tubes.
- High Frequency Welding:A refinement of ERW, this technology uses high-frequency current to heat the strip edges very rapidly, creating a narrow heat-affected zone and a cleaner, stronger weld. This technology is increasingly specified for safety-critical components in Japanese vehicle architectures due to superior weld quality.
- Seamless Manufacturing:Tubes produced without a weld seam, typically by piercing a solid billet, offer uniform strength and are preferred for high-pressure applications where weld integrity is paramount. These tubes serve specialized niches within engine and hydraulic systems.
- Induction Heating Welding:This process uses electromagnetic induction to heat the strip edges, offering precise temperature control and a clean welding environment. Manufacturers leverage this technology for tubes requiring consistent metallurgical properties.
The adoption of High Frequency Welding is accelerating, while Electric Resistance Welding maintains foundational market presence.
Application:
The specific functional role a tube plays within a vehicle dictates its required dimensions, material properties, and performance characteristics.
- Chassis & Frame:These components form the foundational structure of a vehicle, requiring tubes with high strength-to-weight ratios and robust fatigue resistance to ensure vehicle integrity and occupant safety. Demand for these tubes is substantial across global automotive production, particularly in China for light commercial vehicles.
- Suspension Systems:Tubes in suspension systems, such as control arms and shock absorber bodies, demand exceptional dimensional accuracy, consistent wall thickness, and precise formability for optimal ride comfort and handling performance. European premium vehicle manufacturers increasingly specify advanced ERW tubes for these critical dynamic components.
- Gear Box Sleeves:These components require tubes with tight tolerances and good machinability to facilitate precise fitment and smooth operation within the transmission system. Manufacturers use these sleeves to house internal gears and shafts.
- Engine Components:Tubes are utilized in various engine parts, including exhaust systems, fluid lines, and structural supports, where they must withstand high temperatures, vibrations, and corrosive environments. These applications demand specific material grades.
- Steering Systems:Tubes in steering columns and linkages require high torsional strength and dimensional stability to ensure precise control and driver safety. Automotive OEMs specify tubes that meet stringent fatigue life requirements.
Demand for Chassis & Frame remains substantial, with Suspension Systems showing the steepest expansion trajectory.
End User Industry:
The position of the end-user within the automotive supply chain influences procurement volumes, specification requirements, and the nature of supplier relationships.
- Vehicle Assemblers:These are the final manufacturers of automobiles, directly integrating plain carbon ERW tubes into their vehicle production lines. They demand high-volume, just-in-time delivery and often engage in co-development with tube suppliers for new vehicle platforms.
- Tier-1 Suppliers:These companies supply complete modules or systems directly to vehicle assemblers, incorporating ERW tubes into sub-assemblies like suspension modules or seating structures. Tier-1s require tubes that meet strict performance specifications and often manage complex logistics.
- Aftermarket Providers:These entities supply replacement parts for vehicles already in operation, sourcing ERW tubes for repair and maintenance purposes. Demand here is characterized by a need for broad product availability and competitive pricing.
- Specialty Vehicle Manufacturers:This segment includes producers of niche vehicles such as agricultural machinery, construction equipment, or recreational vehicles, which often have unique structural and performance requirements for ERW tubes. These manufacturers often require customized tube solutions.
Vehicle Assemblers represent a stable demand base, while Tier-1 Suppliers increasingly influence product specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive plain carbon ERW tubes market exhibits a distinct production and consumption divide. Demand concentration in major automotive manufacturing hubs drives localized supply chain development. Vehicle lightweighting mandates and expanding production capacities shape regional market dynamics.
China
Demand for ERW tubes in China stems from its expanding automotive manufacturing capacity. National GB standards govern material specifications for domestic vehicle platforms. Shanghai and Guangzhou host significant automotive manufacturing clusters, driving high-volume ERW tube consumption.
Germany
European premium vehicle manufacturers in Germany increasingly specify advanced ERW tubes for sophisticated suspension systems. The EU's CO2 emission performance standards influence material choices for lightweighting. The Stuttgart region, a hub for automotive engineering, pushes demand for high-precision cold rolled ERW tubes.
United States
Stringent US EPA fuel economy targets compel automakers in the United States to adopt lighter components. This increases the specification of high-strength, thin-wall ERW tubes for chassis and suspension. Michigan's automotive corridor remains a central demand area for ERW tubes in vehicle assembly.
Mexico
Mexico's growing role as a North American automotive manufacturing hub creates significant potential for tube suppliers. The country's automotive industry benefits from trade agreements facilitating component supply. Production facilities in Puebla and Saltillo require diverse ERW tube specifications for export-oriented vehicle platforms.
Japan
Japanese vehicle architectures increasingly specify high-frequency welded ERW tubes for safety-critical applications. JIS standards ensure the quality and performance of these components. Toyota City and other manufacturing centers drive consistent demand for advanced ERW tubes in domestic and export models.
Global Automotive Plain Carbon ERW Tubes Market Key Industry Players
Top-tier vendors anchor the global automotive plain carbon ERW tubes market, while specialized manufacturers cater to niche applications. The competitive landscape features a mix of multinational steel producers and regional tube fabricators. Strategic archetypes include integrated steelmakers, advanced material specialists, and localized volume suppliers. Companies often engage in capacity expansion and strategic partnerships to secure their market positions.
Among the global integrated steelmakers, ArcelorMittal exemplifies a broad manufacturing footprint, serving multinational automotive platforms with diverse ERW tube solutions. Nippon Steel Corporation represents a focus on advanced high-strength steel grades, developing materials for safety-critical applications requiring superior weld quality. Tata Steel, with its integrated production facilities, sustains a significant market presence through robust distribution networks in India and Europe, catering to both high-volume and specialized needs. These companies demonstrate diverse approaches to meeting evolving automotive material demands, from global scale to specialized product development.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nippon Steel Corporation |
| Tata Steel |
| JFE Steel Corporation |
| Vallourec |
| Tenaris |
| Maharashtra Seamless Ltd. |
| Welspun Corp Ltd. |
| Thyssenkrupp AG |
Cost & Logistics Intelligence
High Frequency Welding adoption reshapes cost economics by demanding specialized equipment, concentrating production capability among fewer suppliers, and influencing pricing power for precision ERW tubes.
Pricing Analysis
Margin tightening in the automotive plain carbon ERW tubes market reflects the volatility of hot-rolled steel coil prices. The dominant pricing model involves contract-based long-term offtake agreements, often incorporating raw material price adjustments. Price differentiation stems from quality grade, such as advanced high-strength steel (AHSS) for safety-critical components, and the level of customization provided. Vehicle assemblers and Tier-1 suppliers exhibit lower price sensitivity for high-precision suspension components, while aftermarket providers prioritize competitive pricing for replacement parts.
Supply Chain Analysis
Single-source vulnerability sits with specific regions for high-grade raw materials, particularly hot-rolled steel coil, impacting the ERW tube supply chain. Geographic supply concentration for finished tubes centers in China, Germany, and Japan, reflecting automotive manufacturing hubs. The industry depends on consistent access to energy and steel coil, creating a structural risk from commodity price volatility. Distribution runs primarily direct to vehicle assemblers and Tier-1 suppliers, with specialized distributors serving aftermarket providers and niche manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive plain carbon ERW tubes market is fundamentally a cost-of-compliance story, with stringent regulations like the EU's CO2 emission performance standards creating a barrier-to-entry moat for manufacturers capable of producing lightweight, high-strength tubes.
For Market Incumbents: Deepen R&D investments into advanced high-strength steel grades to counter substitution from alternative materials like aluminum extrusions. Incumbents should expand their global manufacturing footprint, particularly in growing automotive hubs such as Mexico, to serve multinational platforms efficiently. Securing long-term supply contracts with Tier-1 suppliers can also mitigate margin pressure. This strategic focus reinforces market position against emerging material threats.
For New Entrants and Emerging Players: Capture opportunities within electric vehicle architectures by specializing in battery pack frames and cooling circuit conduits. New entrants should target the most penetrable segment: specialized sub-frame structures for BEVs, where design flexibility is high. A go-to-market angle focusing on rapid prototyping and collaborative design with EV OEMs can secure early market share. This strategy allows smaller players to differentiate through agility and technical expertise.
For Investors and Strategic Acquirers: Re-rating potential sits with advanced material specialists given the imperative for vehicle lightweighting and stringent emissions regulations. Investors should seek acquisition targets among mid-sized manufacturers possessing proprietary high-frequency welding and cold-forming expertise. Long-term viability favors companies able to consistently meet evolving dimensional accuracy and strength requirements for next-generation vehicle architectures. A key signal to watch is the acceleration of OEM qualification timelines for new, higher-strength plain carbon steel grades.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in High-Frequency Welding Technology | This enhances weld quality and precision for safety-critical components, meeting stringent Japanese vehicle architecture standards. |
| Develop Advanced High-Strength Carbon Steel Grades | This provides cost-effective alternatives to expensive alloyed steels for structural parts, meeting lightweighting mandates. |
| Establish Local Production in Mexico | This serves the expanding North American automotive manufacturing hub, facilitating efficient supply to Puebla and Saltillo plants. |
| Offer Integrated Just-in-Time Logistics | This streamlines inventory management for vehicle assemblers, reducing lead times and operational costs in Germany. |
| Pursue OEM Co-development Partnerships | This integrates tube manufacturers early into vehicle design processes, optimizing component performance for European premium cars. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with industry stakeholders. OEM platform engineers, Tier 1 supplier procurement leads, metallurgists, and distribution channel partners provided critical qualitative insights. Secondary validation drew from vehicle production databases, national material standards like GB and JIS, and company annual reports. This approach ensured robust bottom-up and top-down triangulation of market data.
Market sizing and forecasts were modeled with granular detail across product type, technology, application, end-user industry, and regional automotive production clusters. Compound annual growth rates were derived from historical trends, projected growth drivers, and expert consensus throughout the forecast period. Key industry-specific inputs included vehicle lightweighting mandates and electric vehicle adoption rates. The analytical framework integrated these dimensions across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to raw material price volatility and geopolitical trade policies. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automatic Bus Door System Market
Automotive Parts
Philippines Automotive Engine Oils Market
Automotive Parts
Heavy Duty Clutches Market
Automotive Parts
Automotive Brake Wheel Cylinder Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Global Intelligent All-Wheel Drive System Market
Automotive Parts
Automotive Thermal Management Systems for Electric Vehicles Market
Automotive Parts
Canada Passenger Vehicles Lubricants Market
Automotive Parts
Accelerator Pedal Module Market
Automotive Parts
Wiper Blade Market
Automotive Parts
Plastic Fuel Tanks Market
Automotive Parts
Automotive Electric Water Pump Market
Automotive Parts
AWD Coupling System Market
Automotive Parts
Global Automotive Cylinder Liner Market
Automotive Parts
Automotive Crankcase Additives Market
Automotive Parts
Automotive Bearing Seals Market