
 Automotive Fuel Accumulator Market | 2026-2036
Automotive Fuel Accumulator Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fuel Accumulator Market Outlook
The capital-intensity divergence between integrated system suppliers and component specialists is unwinding competitive stability across the supply base. Robert Bosch GmbH leverages captive fuel-injection expertise to bundle accumulator modules with high-pressure pump assemblies. Continental AG anchors its position through R&D intensity in composite accumulator materials for lightweighting. HYDAC International specializes in hydraulic accumulator variants that serve commercial-vehicle braking and suspension systems.
An automotive fuel accumulator stores pressurized fuel or hydraulic fluid to dampen pulsation, maintain system pressure during transient demand, and protect downstream components from cavitation damage. These devices typically operate at pressures ranging from 5 to 200 bar depending on application, employing elastomeric bladders or piston separators to isolate gas charge from working fluid. Metal cylinders dominate current OEM fitments due to proven durability under underhood thermal cycling, while composite tanks represent the fastest-growing product category as manufacturers pursue mass reduction for hybrid powertrains. Diaphragm accumulators command premium positioning in aftermarket channels where service life and serviceability determine replacement value. Electronic control integration across accumulator pressure management is displacing purely mechanical regulation in new platform designs.
EPA Tier 3 evaporative-emission standards and Euro 7 particulate limits force accumulator sealing-grade upgrades and permeation-resistant material transitions. NHTSA brake-system reliability requirements and ECE R13-H commercial-vehicle braking standards sustain demand for hydraulic accumulators in air-over-hydraulic actuation circuits. Stakeholders must monitor how zero-emission vehicle mandates in California, the EU, and China reshape accumulator content per vehicle as internal-combustion platforms face production-phaseout timelines.
Market Dynamics
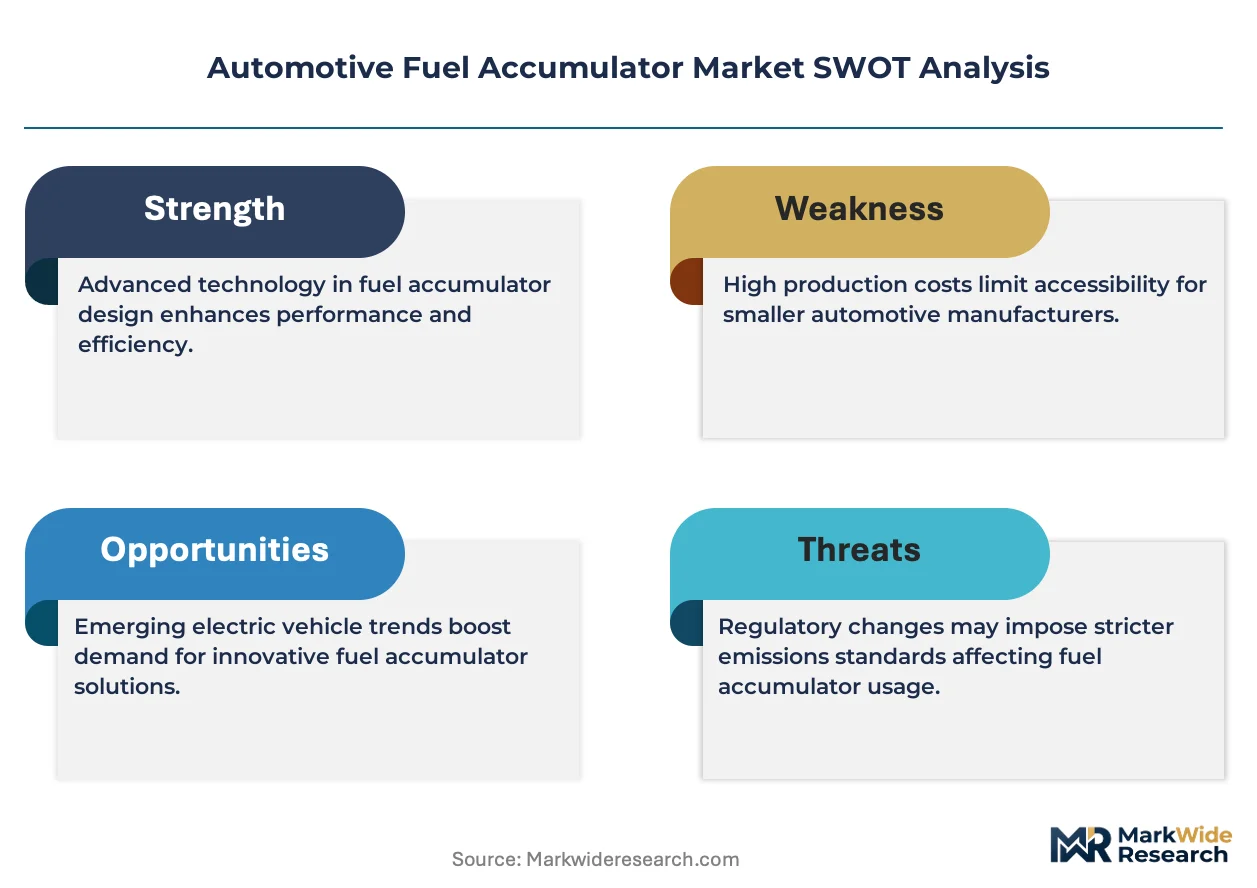
The automotive fuel accumulator market faces a fundamental restructuring as powertrain electrification timelines compress internal-combustion investment horizons while simultaneously extending hybrid system production runs. Suppliers must calibrate capacity across diverging OEM strategies where some platforms require enhanced accumulator performance for mild-hybrid architectures and others face outright phaseout.
Growth Catalysts
- EPA Tier 3 evaporative-emission standards:These regulations mandate sub-1.0 gram per day permeation limits for fuel-system components, forcing accumulator sealing upgrades that expand addressable content per vehicle across US-bound production.
- Hybrid powertrain proliferation:Stop-start and mild-hybrid architectures require accumulators with faster pressure response cycles to manage frequent engine restarts, creating specification tiers absent from conventional ICE platforms.
- China's dual carbon goals:The MIIT's fuel-consumption targets for 2025 sustain hybrid production quotas that preserve accumulator demand even as NEV penetration accelerates in coastal provinces.
Market Restraints
- Specialized elastomer supply concentration:Fluorocarbon bladder materials for high-pressure gasoline applications source primarily from Japanese and German chemical suppliers, exposing tier-one accumulator manufacturers to input cost volatility and allocation constraints.
- Zero-emission vehicle mandates:California's Advanced Clean Cars II regulation and the EU's 2035 ICE sales ban create definitive demand ceilings for accumulator-requiring powertrains in two of the three largest historical markets.
- Composite material qualification timelines:OEM validation cycles for carbon-fiber-wrapped accumulator vessels extend 18-24 months beyond metal-cylinder equivalents, compressing adoption windows within shrinking platform lifecycles.
Strategic Opportunities
- Commercial-vehicle hydraulic applications:Air-over-hydraulic braking systems for medium-duty trucks in India and Brazil remain underpenetrated by accumulator specialists currently focused on passenger-car fuel systems.
- Sensor-integrated smart accumulators:Convergence of MEMS pressure sensing with accumulator bodies enables real-time leakage detection and predictive maintenance alerts, opening software-recurring revenue streams alongside hardware sales.
- Aftermarket service bundling:Independent repair networks in Germany and the United States seek accumulator replacement programs paired with fuel-system diagnostic tools, creating channel partnerships outside OEM captive supply.
Industry Challenges
- Multi-physics simulation expertise:The shift toward composite accumulator design demands engineers proficient in coupled thermal-structural-fluid analysis, a skill set concentrated among aerospace contractors rather than traditional automotive suppliers.
- Euro 7 certification parallelism:Accumulator manufacturers must validate products against divergent EPA and Euro 7 test protocols simultaneously, doubling certification engineering headcount without corresponding revenue recognition timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fuel Accumulator Market |
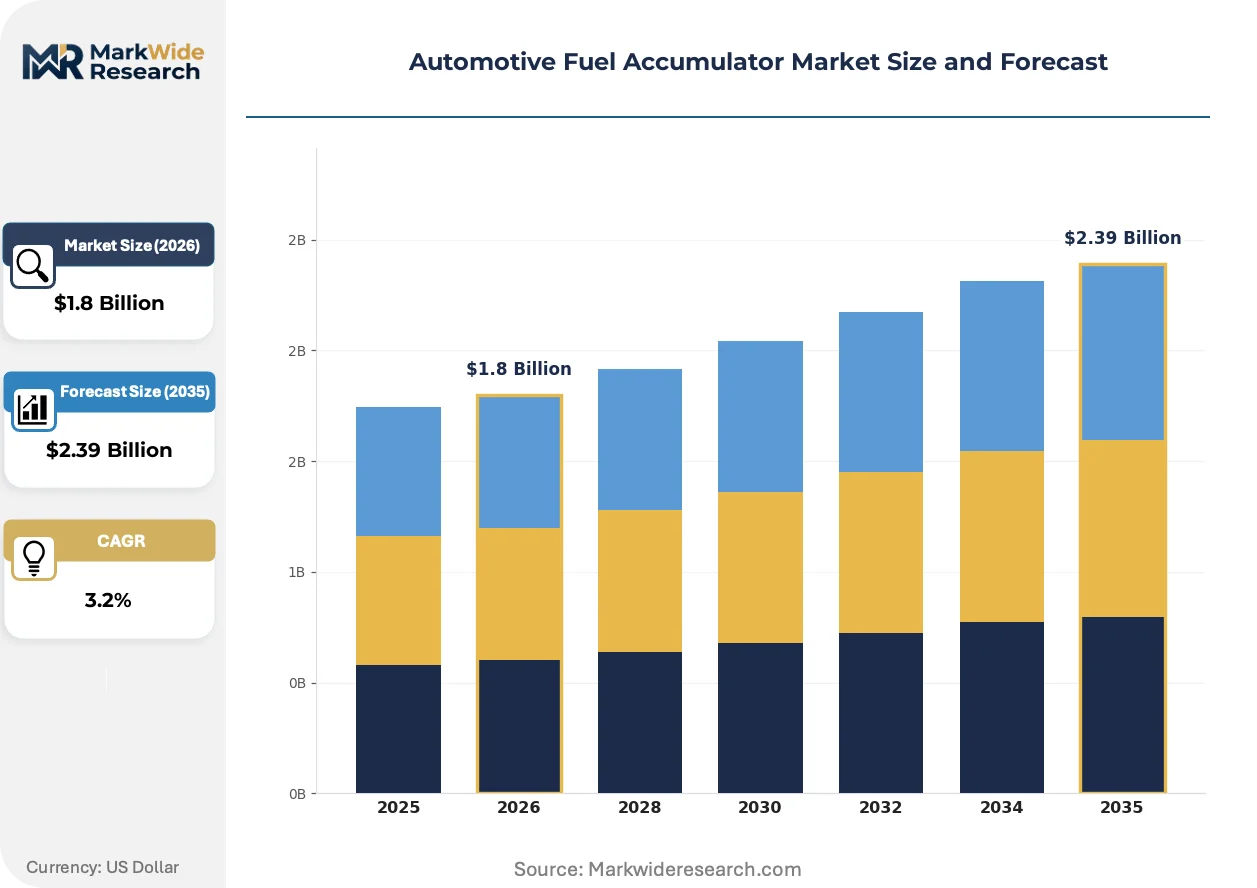
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Cylinders, Plastic Accumulators, Composite Tanks, Diaphragm Accumulators End User: OEMs, Aftermarket Suppliers, Fleet Operators, Workshops Component: Valves, Filters, Accumulator Bladders, Pressure Transducers Technology: Hydraulic Systems, Pneumatic Systems, Electronic Control, Mechanical Systems |
| Companies Covered | Bosch Rexroth AG, Denso Corporation, Continental AG, NOK Corporation, Eaton Corporation, Robert Bosch GmbH, TI Fluid Systems, Delphi Technologies, HYDAC International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fuel Accumulator Market Strategic Shifts
Active materials research and control-system miniaturization are redefining accumulator performance benchmarks faster than platform development cycles can absorb them. The gap between laboratory-proven capabilities and production-hardened specifications is widening competitive differentiation among suppliers.
Composite cylinder construction is fragmenting the traditional metal-dominant accumulator market. Carbon-fiber-reinforced polymer vessels reduce mass 40-60% versus steel equivalents while maintaining 200-bar pressure ratings. BMW and Mercedes-Benz hybrid platforms have adopted these units for underfloor packaging constraints. The technology is fragmenting supplier tiers as aerospace composite specialists enter automotive qualification pipelines previously controlled by hydraulic component incumbents.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing material transitions in accumulator bladders and seals. The industrial consequence is a qualification race for hydrogenated nitrile rubber and thermoplastic elastomer alternatives that match fluorocarbon permeation resistance. Passenger-car direct-injection systems face the tightest compliance deadlines, with German OEMs accelerating supplier audits to secure 2026-2027 model-year certification.
Fleet operators and leasing companies are compressing specification cycles for accumulator replacement decisions. Where traditional aftermarket purchasing prioritized unit cost, total-cost-of-ownership models now weight failure-mode probability and roadside-assistance exposure. This behavioral shift favors premium diaphragm accumulators with published service-life data over commodity piston alternatives. The pattern is most visible in US commercial-fleet procurement, where telematics-enabled predictive maintenance contracts bundle accumulator health monitoring with replacement scheduling.
Automotive Fuel Accumulator Market Segmentation
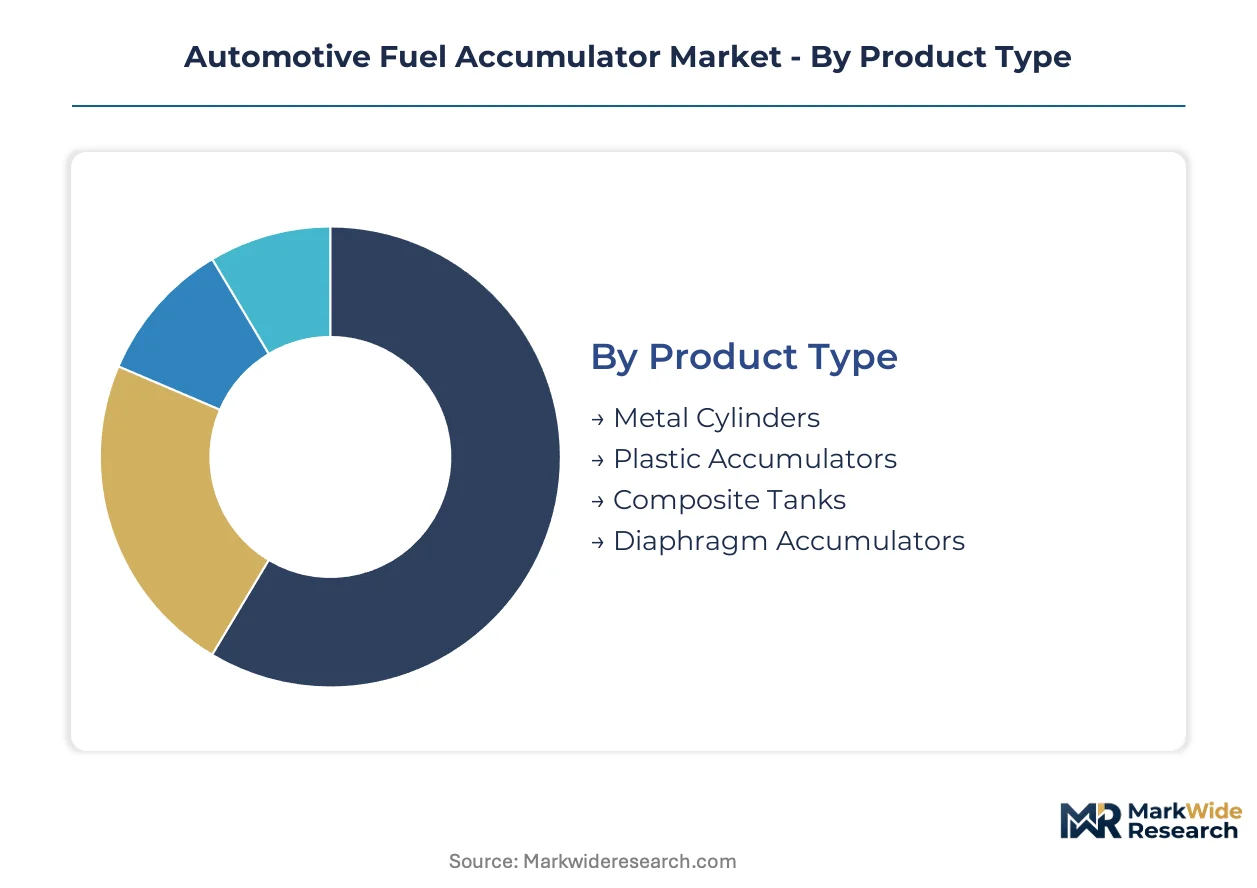
Accumulator segmentation reveals how material science and control architecture determine pricing power across diverging OEM strategies. Each dimension—product construction, procurement channel, internal components, and actuation method—carries distinct regulatory exposure and margin profiles that suppliers must navigate.
Product Type:
EPA Tier 3 permeation limits and Euro 7 particulate thresholds force material-grade differentiation that separates premium-certified from standard-fitment accumulators.
- Metal Cylinders:Steel and aluminum vessels dominate current OEM fitments due to proven thermal cycling durability under underhood conditions. German and US manufacturers specify these units for direct-injection gasoline systems where 150-200 bar operating pressures demand structural reliability.
- Composite Tanks:Carbon-fiber-reinforced polymer construction reduces mass 40-60% versus metal equivalents while maintaining equivalent pressure ratings. BMW and Mercedes-Benz hybrid platforms have adopted these for underfloor packaging constraints where weight reduction preserves electric range.
- Plastic Accumulators:Glass-reinforced nylon variants serve cost-sensitive applications in emerging-market compact vehicles with lower pressure requirements.
- Diaphragm Accumulators:Elastomeric membrane designs command aftermarket premiums where published service-life data reduces fleet roadside-assistance exposure.
Established volume favors metal cylinders; emerging adoption favors composite tanks.
End User:
Procurement authority concentrates with entities controlling platform specification cycles and replacement scheduling decisions.
- OEMs:Vehicle manufacturers dictate accumulator specifications through fuel-system integration contracts, with direct-injection platform volumes determining supplier capacity allocation across Germany, China, and the United States.
- Fleet Operators:Leasing companies and commercial-vehicle aggregators in the US increasingly specify accumulators through total-cost-of-ownership models that weight failure-mode probability against unit price.
- Aftermarket Suppliers:Independent distributors stock replacement units for service networks seeking bundled fuel-system diagnostic tools alongside accumulator replacement programs.
- Workshops:Repair facilities in Germany prioritize diaphragm accumulators with field-serviceable components to minimize bay-occupancy time during maintenance events.
Platform-level purchasing power rests with OEMs; margin expansion opportunity concentrates with fleet operators adopting predictive maintenance contracts.
Component:
Subsystem specialization determines which suppliers capture value from electronic integration trends versus commodity replacement cycles.
- Accumulator Bladders:Fluorocarbon elastomer membranes isolate gas charge from working fluid in piston-separator designs. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing qualification races for hydrogenated nitrile rubber alternatives.
- Pressure Transducers:MEMS sensing elements enable real-time leakage detection and predictive maintenance alerts, opening software-recurring revenue streams alongside hardware sales.
- Valves:Pressure regulation and isolation mechanisms maintain system integrity during transient demand spikes.
- Filters:Contamination control elements protect downstream injection components from particulate damage.
Hardware commoditization pressures valves and filters; sensor integration elevates pressure transducers toward platform-critical status.
Technology:
Control-system architecture determines response speed, diagnostic capability, and regulatory compliance depth across hybrid and conventional powertrains.
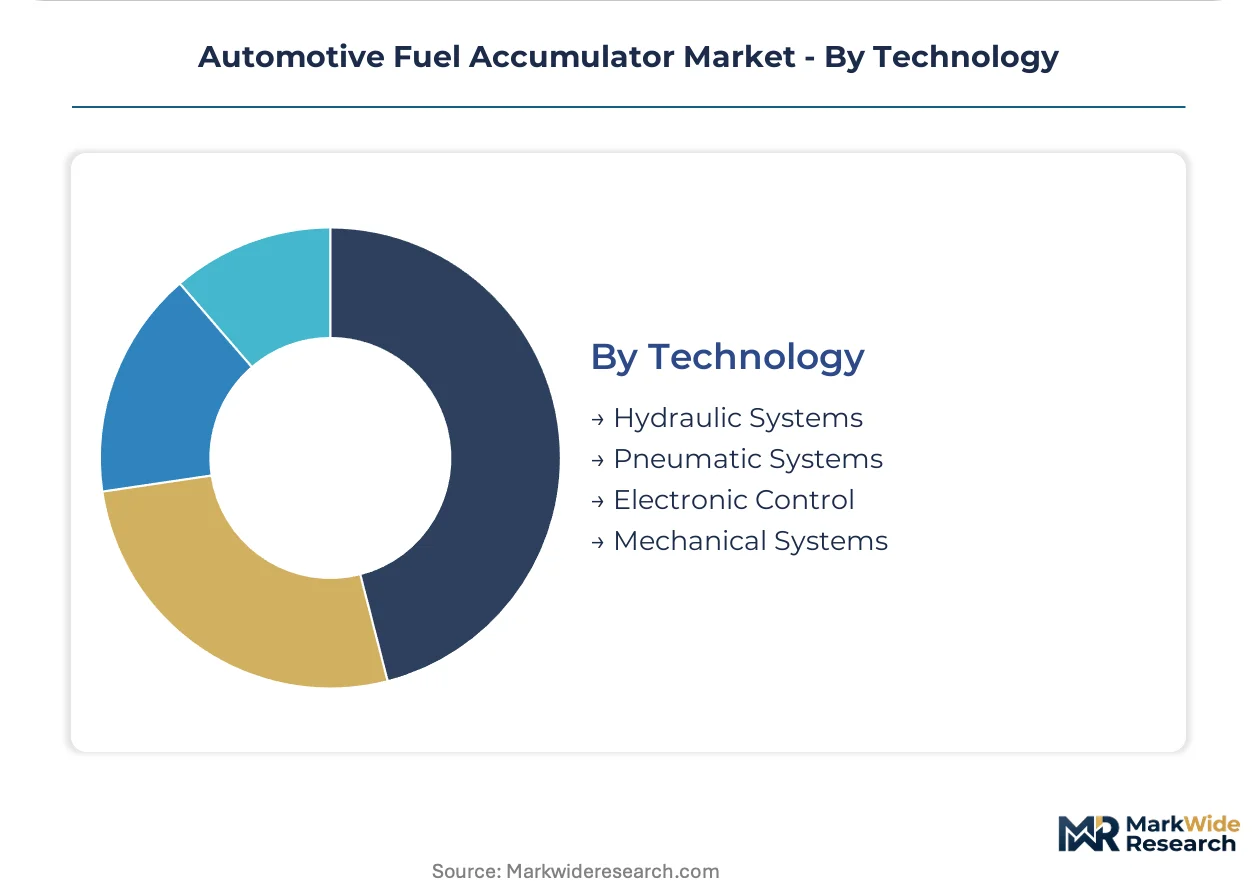
- Electronic Control:Microprocessor-managed pressure regulation displaces purely mechanical systems in new platform designs, enabling adaptive response to stop-start cycling demands.
- Hydraulic Systems:Fluid-power accumulators serve commercial-vehicle braking and suspension applications where NHTSA reliability requirements and ECE R13-H standards sustain demand.
- Pneumatic Systems:Compressed-gas storage supports air-over-hydraulic actuation circuits in medium-duty truck applications.
- Mechanical Systems:Spring-loaded and weight-based pressure maintenance persists in cost-optimized emerging-market vehicles with minimal electronic content.
Mechanical systems retain installed-base replacement demand; electronic control gains specification share in hybrid platform development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across national markets. German fleet buyers prioritize total-cost-of-ownership metrics over unit price, while Indian commercial-vehicle operators remain acutely price-sensitive in accumulator procurement decisions.
United States
EPA Tier 3 evaporative-emission standards mandate sub-1.0 gram per day permeation limits for fuel-system components. The NHTSA sustains demand for hydraulic accumulators through brake-system reliability requirements for medium-duty trucks. Detroit's automotive corridor hosts accumulator integration facilities serving domestic OEM direct-injection platform volumes.
Germany
Domestic OEMs specify metal-cylinder accumulators for 150-200 bar direct-injection gasoline systems. Euro 7 particulate limits force sealing-grade upgrades across fuel-system suppliers. Stuttgart and Munich anchor development activity for composite accumulator materials targeting hybrid powertrain lightweighting.
China
MIIT fuel-consumption targets for 2025 preserve hybrid production quotas sustaining accumulator demand. The country's dual carbon goals accelerate NEV penetration in coastal provinces while inland manufacturing clusters maintain ICE component output. Yangtze River Delta facilities supply both domestic OEMs and export-bound production.
Japan
METI industrial policy supports precision manufacturing capabilities for fluorocarbon bladder materials. Domestic chemical suppliers concentrate high-pressure gasoline application inputs. Toyota City and Nagoya industrial zones maintain accumulator component production for hybrid platform integration.
India
Commercial-vehicle braking applications in medium-duty trucks remain underpenetrated by accumulator specialists focused on passenger-car segments. BIS standards govern automotive component certification timelines. Pune and Chennai manufacturing corridors expand supplier presence for cost-optimized compact vehicle specifications.
Automotive Fuel Accumulator Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the automotive fuel accumulator market. Tier-one system suppliers bundle accumulator modules with fuel-injection assemblies, while component specialists focus on hydraulic variants for commercial-vehicle applications. Three archetypes dominate: integrated powertrain suppliers, hydraulic system specialists, and composite material innovators. Competitive moves concentrate on R&D intensity in lightweight materials and strategic partnerships for sensor-integrated smart accumulator development.
Among Germany-based integrated suppliers, Robert Bosch GmbH and Continental AG exemplify the bundled-system archetype. HYDAC International represents the hydraulic specialist tier with commercial-vehicle braking and suspension system expertise. These three entities anchor distinct competitive vectors: captive fuel-injection integration, composite material R&D, and hydraulic application specialization.
| Leading Market Players |
|---|
| Bosch Rexroth AG |
| Denso Corporation |
| Continental AG |
| NOK Corporation |
| Eaton Corporation |
| Robert Bosch GmbH |
| TI Fluid Systems |
| Delphi Technologies |
| HYDAC International |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between German OEMs and Japanese fluorocarbon suppliers lock in bladder material access while capping price volatility for tier-one accumulator manufacturers serving EPA Tier 3 and Euro 7 platforms. These arrangements concentrate procurement power among integrated system suppliers while exposing component specialists to spot-market exposure for REACH-compliant elastomer alternatives.
Pricing Analysis
After-sales service bundling with predictive maintenance contracts drives lifetime value for fleet operators and leasing companies adopting telematics-enabled accumulator health monitoring. Pricing stratifies across premium-certified, standard-fitment, and economy tiers based on permeation-grade certification and pressure-response specifications. Cost compression in the economy tier intensifies as Chinese manufacturers expand glass-reinforced nylon accumulator output for emerging-market compact vehicles. Fleet operators in the United States exhibit the lowest price sensitivity due to total-cost-of-ownership modeling, while Indian commercial-vehicle operators prioritize unit cost above service-life metrics.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for carbon-fiber prepregs and fluorocarbon elastomers destined for German composite accumulator facilities. Manufacturing concentrates in Germany, China, and Japan, with raw material dependencies spanning Japanese fluorocarbon polymers, Chinese carbon-fiber intermediates, and German precision-machined valve components. Single-source vulnerability in high-pressure bladder materials exposes tier-one suppliers to allocation constraints from METI-supported chemical producers. Distribution runs through OEM captive supply chains for original fitment, with independent aftermarket networks in Germany and the United States handling replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Accumulator demand sits in early-cycle expansion as hybrid powertrain proliferation extends internal-combustion platform lifecycles beyond prior phaseout assumptions. EPA Tier 3 and Euro 7 regulatory tightening sustains specification upgrades even as zero-emission mandates advance.
For Market Incumbents: Consolidate backward integration into fluorocarbon elastomer production or secure exclusive offtake arrangements with Japanese chemical suppliers to defend against emerging-market competitors developing hydrogenated nitrile rubber alternatives. Expand composite accumulator capacity in Stuttgart and Munich development clusters to capture BMW and Mercedes-Benz hybrid platform specifications. Prioritize Euro 7 certification parallelism investments to maintain dual-market access against EPA-Tier-3-only specialists. For New Entrants and Emerging Players: EPA Tier 3 certification fast-track programs for permeation-resistant accumulator designs open procurement channels with Detroit OEMs seeking second-source supply security. Target underpenetrated commercial-vehicle hydraulic applications in India and Brazil where air-over-hydraulic braking standards sustain demand absent passenger-car fuel-system competition. Pursue fleet operator direct contracts with predictive maintenance software bundles to bypass entrenched OEM captive supply relationships. For Investors and Strategic Acquirers: Composite material innovators with aerospace-to-automotive qualification pipelines present acquisition targets as BMW and Mercedes-Benz hybrid platforms accelerate carbon-fiber-wrapped vessel adoption. Long-term viability hinges on accumulator content per vehicle stabilizing in mild-hybrid architectures rather than collapsing under battery-electric substitution. Monitor California Advanced Clean Cars II implementation pace as the critical inflection signal for demand ceiling timing in the second-largest historical market.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Qualification | Carbon-fiber-wrapped vessels from aerospace suppliers penetrate BMW and Mercedes-Benz hybrid platforms. |
| Sensor-Integrated Smart Accumulator Development | MEMS pressure sensing enables real-time leakage detection and predictive maintenance revenue streams. |
| REACH-Compliant Elastomer Transition | Hydrogenated nitrile rubber alternatives replace fluorocarbon bladders under Annex XVII restrictions. |
| Commercial-Vehicle Hydraulic Expansion | Air-over-hydraulic braking systems in India and Brazil remain underpenetrated by accumulator specialists. |
| Aftermarket Service Bundling | Independent German and US repair networks seek accumulator replacement paired with diagnostic tools. |
Study Parameters
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet maintenance directors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, EPA certification filings, and ECHA REACH substance restriction timelines. Bottom-up accumulator content-per-vehicle estimates triangulated against top-down fuel-system market sizing.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the analysis window. CAGRs derived from production-volume forecasts weighted by accumulator specification tier and regional regulatory phase-in schedules. Industry-specific forecast inputs include MIIT fuel-consumption target compliance trajectories and Euro 7 particulate limit implementation timing.
Decision-makers should treat outputs as directional under assumptions of sustained hybrid production quotas and gradual zero-emission mandate phase-in; material deviation would warrant model refresh. Specific risk factors include accelerated ICE platform cancellations, fluorocarbon supply disruptions, or composite material qualification timeline compression. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Motorcycle Carbon Ceramic Brake Rotors Market
Automotive Parts
Germany Automotive Pneumatic Actuators Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Canada Passenger Vehicles Lubricants Market
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
Russia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Iran Automotive Engine Oils Market
Automotive Parts
Global Automotive Flywheel Market
Automotive Parts
Plastic Fuel Tanks Market
Automotive Parts
Two-Wheeler Lubricants Market
Automotive Parts
Automotive Propeller Shaft Couplings Market
Automotive Parts
Camshaft Bearings Market
Automotive Parts
Brake Lathe Machine Market
Automotive Parts
Automotive Electric Turbocharger Market
Automotive Parts
Timing Gear Market
Automotive Parts
Bearing Steel Balls for New Energy Vehicles Market