
 Automotive PCB Market | 2026-2036
Automotive PCB Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive PCB Market Analysis
EU Green Deal compliance is broadening the cost-of-entry calculus for automotive PCB suppliers targeting European OEM programs. AT&S leverages its Austrian manufacturing base to sustain qualification pipelines for high-reliability multi-layer boards. Unimicron Technology anchors capacity expansion in Taiwan to compete for HDI-intensive infotainment contracts.
Automotive PCBs are laminated circuit substrates built from copper-clad epoxy resin or polyimide, fabricated through photolithography, etching, and lamination cycles to deliver signal integrity under thermal cycling and vibration loads. These boards distribute power, transmit sensor data, and host microcontrollers across vehicle electronic architectures. Multi-layer PCB configurations dominate powertrain and ADAS applications where density and thermal management command premium positioning, while flexible PCB formats gain traction in lighting and interior routing where form-factor constraints override raw cost. HDI Technology segments attract disproportionate engineering investment as trace miniaturization enables embedded component integration.
FCC electromagnetic compatibility rules, EPA fuel-economy standards that drive electronic substitution for mechanical systems, and China's GB/T automotive electronics standards collectively shape PCB material selection, layer-count minimums, and supplier certification requirements. EMA's MDR-adjacent quality expectations for automotive-grade components further tighten traceability and reliability testing protocols. Stakeholders must monitor how NHTSA's evolving autonomous vehicle guidance rewrites PCB redundancy and fail-safe specifications before committing long-term capacity.
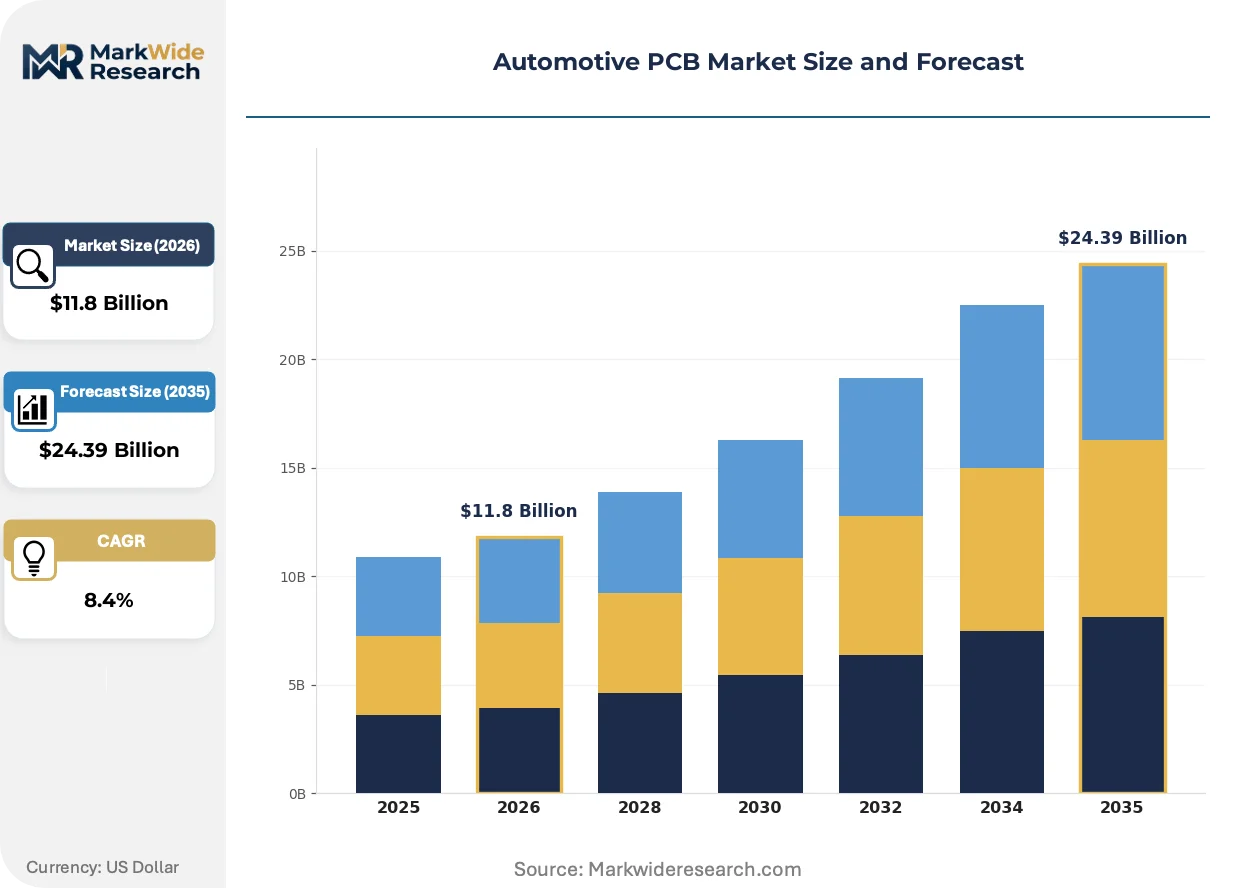
Market Dynamics
Powertrain electrification is compressing PCB qualification cycles as OEMs consolidate multi-layer and HDI sourcing around suppliers capable of thermal cycling reliability under 150°C continuous operation. Tier-1 system integrators now mandate AEC-Q100 compliance as a non-negotiable gate for power electronics contracts.
Growth Catalysts
- EU Green Deal embedded electronics mandates:European OEM procurement teams are expanding PCB layer-count minimums for battery management systems to meet 2035 zero-emission vehicle targets.
- ADAS sensor fusion architectures:Camera-radar-lidar integration is driving 10+ layer HDI board demand from German and Japanese tier-1 suppliers.
- China dual carbon goals:Domestic EV production quotas are accelerating local PCB capacity expansion for power inverter modules.
Market Restraints
- Copper-clad laminate cost volatility:Epoxy resin and copper foil pricing swings compress gross margins for mid-tier fabricators serving infotainment segments.
- Japan-Taiwan supply concentration:ABF substrate and high-Tg laminate sourcing remains dependent on concentrated East Asian chemical suppliers.
- RoHS/REACH material substitution limits:Lead-free solder and halogen-free resin alternatives impose thermal performance trade-offs in high-density automotive applications.
Strategic Opportunities
- India PLI scheme localization:Component manufacturing incentives are opening PCB assembly opportunities for EV powertrain modules serving domestic OEM programs.
- Vehicle-to-everything communication modules:5G-V2X antenna integration requires flexible-rigid hybrid boards in connected vehicle architectures.
- ISO 26262 functional safety certification:ASIL-D qualified PCB suppliers can capture premium positioning in autonomous drive-by-wire systems.
Industry Challenges
- Signal integrity engineering scarcity:High-speed digital design expertise for 10Gbps+ automotive Ethernet routing remains concentrated among senior specialists at top-tier fabricators.
- AEC-Q100 qualification timelines:18-24 month reliability testing cycles delay revenue recognition for new PCB material formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive PCB Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid PCB, Flexible PCB, Rigid-Flex PCB, Multi-layer PCB End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Technology: Standard Technology, HDI Technology, Embedded Component Technology, Hybrid Technology Application: Powertrain, Infotainment, Advanced Driver Assistance Systems, Lighting |
| Companies Covered | AT&S, Unimicron Technology, Zhen Ding Technology, Sanmina, Suzhou Dongshan Precision Manufacturing, DSBJ, Nippon Mektron, Ventec International Group, TTM Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive PCB Market Emerging Trajectories
Automotive PCB technology is bifurcating between ultra-high-density substrates for autonomous compute and thermally robust laminates for power electronics. Material science and fabrication process boundaries are being redrawn by electrification and sensor fusion requirements.
Embedded die packaging is converging with traditional PCB fabrication as OEMs demand component miniaturization for zonal E/E architectures. German luxury EV platforms are adopting substrate-like PCB technology to integrate power stages and logic within the same board footprint. This convergence is compressing the traditional separation between semiconductor packaging and board-level interconnection.
REACH substance restrictions are forcing reformulation of flame-retardant epoxy systems used in engine-compartment applications. The European Chemicals Agency's candidate list expansion is accelerating supplier transitions to phosphorus-based and inorganic filler alternatives. Powertrain PCB procurement teams are now requiring full material disclosure documentation to preempt regulatory obsolescence.
Long-term supply agreements are displacing spot-market purchasing as OEMs secure capacity for 800V inverter and battery disconnect modules. Tier-1 power electronics suppliers are locking 3-5 year contracts with qualified PCB fabricators in Germany and Japan. This shift is most pronounced in high-voltage platforms where second-source qualification costs exceed $2 million per design.
Automotive PCB Market Segmentation
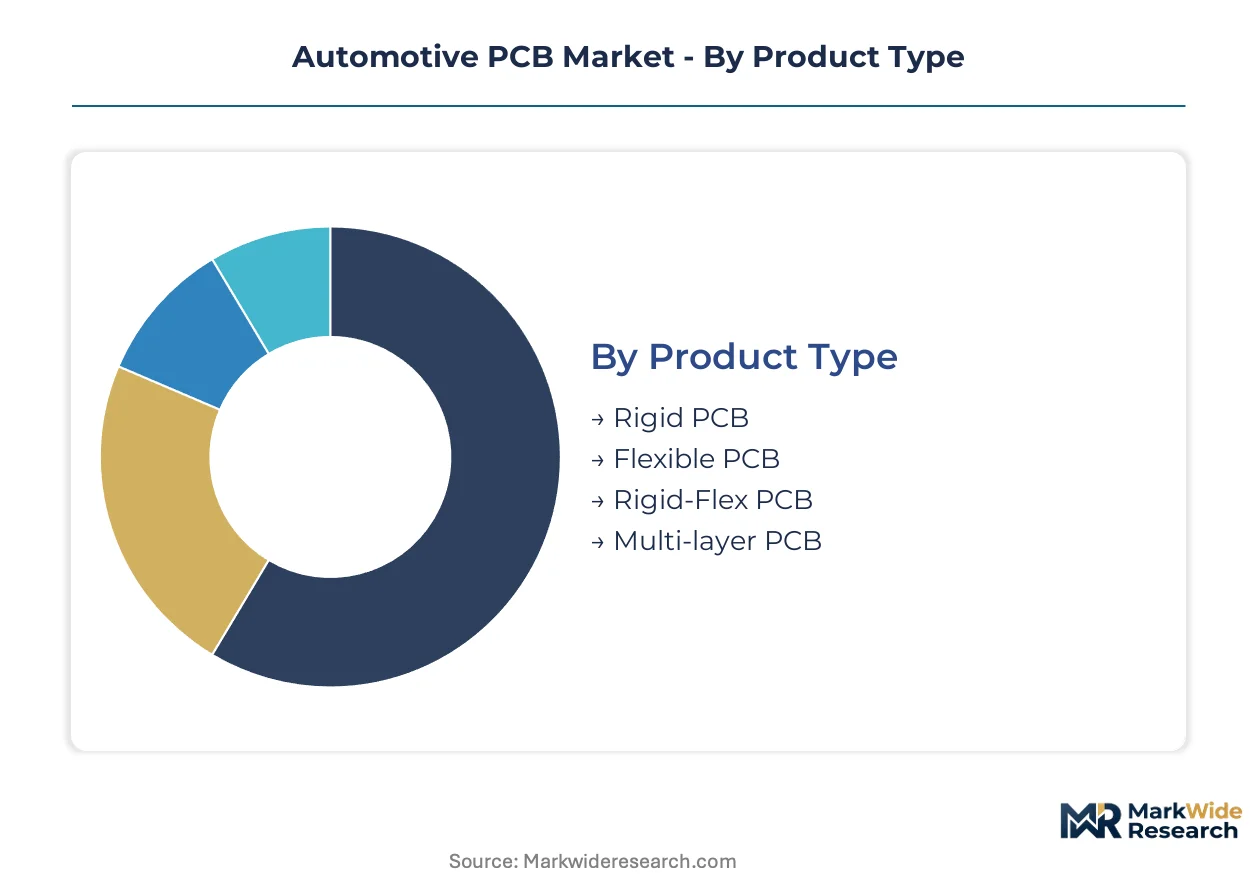
Automotive PCB segmentation reflects the tension between cost-optimized volume production and premium reliability requirements. Electrification and autonomous driving are fragmenting procurement patterns across material grades, layer counts, and certification tiers.
Product Type:
Volume applications favor rigid substrates while premium positioning concentrates in multi-layer and flexible configurations that command thermal cycling premiums.
- Multi-layer PCB:These stack 4-16 copper-clad laminates with drilled and plated vias to manage high-current distribution and signal isolation. German and Japanese OEM procurement for 800V battery management systems and inverter modules concentrates demand here, with AEC-Q100 qualification serving as the non-negotiable entry gate.
- Flexible PCB:Polyimide-based substrates with etched copper traces accommodate bending radii below 5mm for interior routing and lighting applications. Tier-1 suppliers serving luxury vehicle programs in Japan are expanding flexible capacity for zonal E/E architectures where form-factor constraints override raw substrate cost.
- Rigid PCB:Standard FR-4 epoxy laminates dominate high-volume infotainment and body electronics where thermal loads remain moderate.
- Rigid-Flex PCB:Hybrid constructions combine rigid mounting zones with flexible interconnect sections for space-constrained engine-compartment sensors.
Today's leader: Multi-layer PCB. Tomorrow's challenger: Flexible PCB.
End User:
Procurement authority is shifting from fragmented aftermarket channels toward consolidated OEM and Tier-1 direct sourcing with embedded electronics mandates.
- Tier-1 Suppliers:Continental, Bosch, and Denso-class system integrators now mandate AEC-Q100 compliance and 18-24 month qualification timelines for power electronics contracts. These suppliers consolidate multi-layer and HDI sourcing around fabricators capable of thermal cycling reliability under continuous 150°C operation for inverter modules.
- OEMs:Direct procurement from Volkswagen, Toyota, and BYD for battery management and autonomous compute platforms is accelerating substrate-like PCB adoption. OEM technical teams are rewriting specifications to integrate power stages and logic within single board footprints.
- Aftermarket Providers:Fragmented demand for replacement infotainment and lighting modules operates on spot-market purchasing with compressed margin structures.
- Dealerships:Minimal PCB exposure limited to diagnostic equipment and service tool procurement.
Tier-1 Suppliers capture the steepest expansion trajectory as OEMs outsource powertrain electrification integration.
Technology:
Trace miniaturization and component embedding are bifurcating the technology stack between mature standard processes and engineering-intensive advanced formats.
- HDI Technology:Microvia drilling and sequential lamination enable trace widths below 75μm for camera-radar-lidar sensor fusion. German and Japanese Tier-1 ADAS suppliers are driving 10+ layer HDI board demand as camera resolutions climb toward 8MP and data throughput exceeds 10Gbps.
- Embedded Component Technology:Passive and active die placement within PCB substrates eliminates discrete component footprints. This technology is gaining traction in zonal E/E architectures where Volkswagen and Mercedes-Benz EV platforms demand component miniaturization for autonomous compute modules.
- Standard Technology:Through-hole and standard surface-mount processes serve cost-sensitive body electronics and legacy power distribution applications.
- Hybrid Technology:Combinations of HDI density with embedded component integration target next-generation domain controller applications.
HDI Technology leads current procurement volumes. Embedded Component Technology represents the fastest-climbing trajectory as zonal architectures mature.
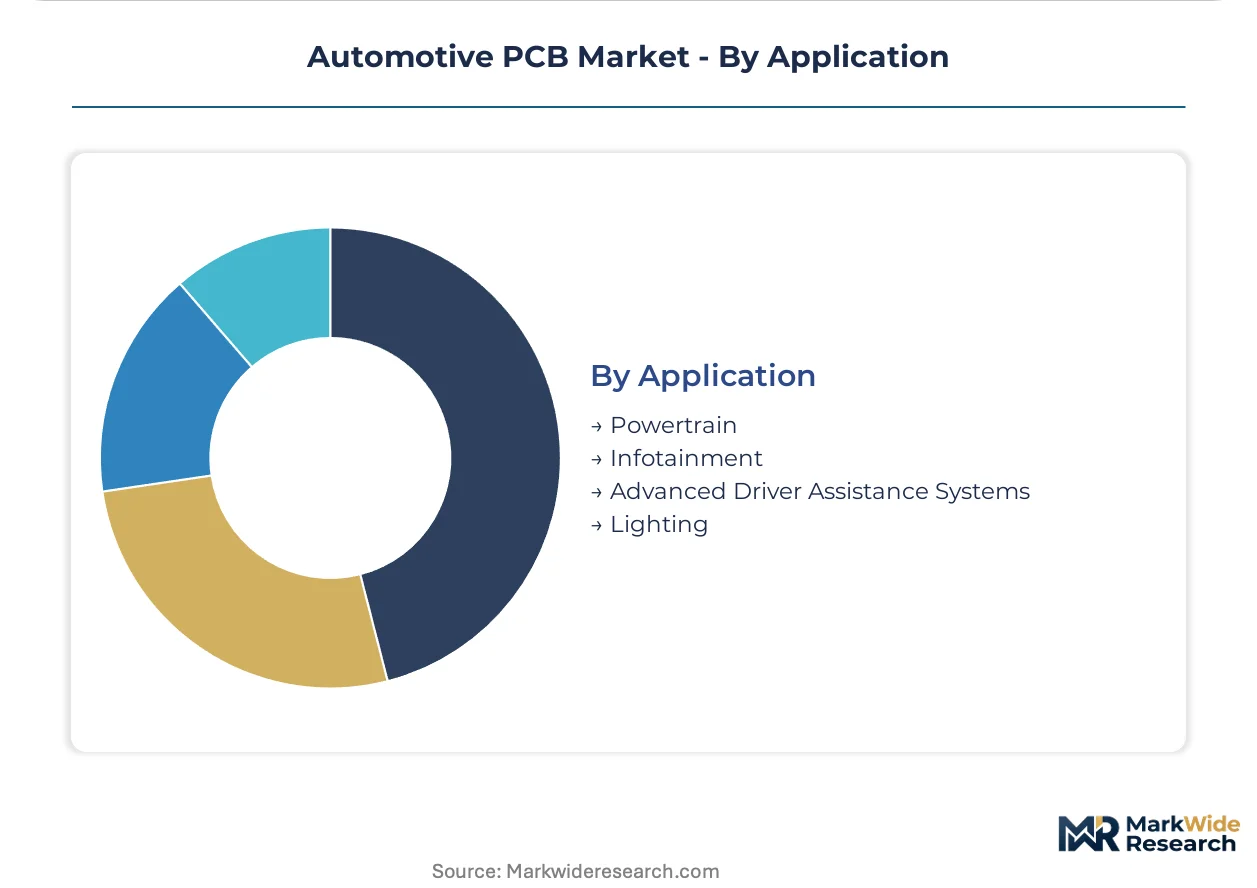
Application:
Thermal and reliability requirements stratify sharply between powertrain electrification and cabin-centric electronics.
- Powertrain:Inverter modules, battery management systems, and DC-DC converters demand high-Tg laminates with continuous operation above 150°C. China's domestic EV production quotas are accelerating local PCB capacity expansion for these modules, with long-term supply agreements displacing spot purchasing.
- Advanced Driver Assistance Systems:Sensor fusion architectures require HDI boards with controlled impedance for high-speed signal integrity. German Tier-1 suppliers anchor demand here as EU Green Deal embedded electronics mandates tighten.
- Infotainment:Copper-clad laminate cost volatility compresses gross margins for mid-tier fabricators serving display and connectivity modules.
- Lighting:Flexible PCB formats gain share in LED headlamp and interior ambient lighting applications where form-factor flexibility matters.
Powertrain commands premium positioning today. Advanced Driver Assistance Systems are gaining share fastest as Level 2+ autonomy penetrates mass-market vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in precision electronics manufacturing anchor regional competitiveness. PCB fabrication clusters concentrate where automotive OEMs, Tier-1 system integrators, and materials science expertise co-locate.
Germany
Battery management system procurement from Volkswagen and BMW drives multi-layer PCB demand. EU Green Deal zero-emission vehicle targets tighten embedded electronics mandates through 2035. Bavaria's manufacturing corridor hosts qualification pipelines for high-reliability boards serving 800V inverter platforms.
China
Domestic EV production quotas under dual carbon goals accelerate power inverter module sourcing. MIIT automotive electronics standards and GB/T certification protocols shape supplier selection. The Yangtze River Delta cluster anchors capacity expansion for local OEM programs including BYD and NIO.
Japan
ADAS sensor fusion architectures from Denso and Panasonic drive HDI board procurement. METI industrial standards and JIS certification requirements enforce thermal cycling reliability benchmarks. The Nagoya-Toyota industrial corridor concentrates Tier-1 system integration expertise for autonomous compute modules.
United States
NHTSA autonomous vehicle guidance evolution rewrites PCB redundancy specifications for domestic OEMs. EPA fuel-economy standards accelerate electronic substitution for mechanical systems. Michigan's automotive engineering cluster and Texas electronics manufacturing base split powertrain and infotainment sourcing.
South Korea
Hyundai-Kia EV platform electrification compresses qualification cycles for power electronics suppliers. MFDS-adjacent quality expectations and KTL certification requirements align with AEC-Q100 compliance. The Seoul Capital Area concentrates HDI fabrication capacity for camera-radar integration modules.
Automotive PCB Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers. Market structure stratifies between AEC-Q100 qualified premium fabricators and cost-optimized volume producers. Three archetypes dominate: Austrian and German precision specialists, Taiwanese and Chinese scale-driven manufacturers, and Japanese technology-integrated conglomerates. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEMs lock long-term supply agreements.
Among European-based fabricators, AT&S exemplifies the precision-specialist archetype through its Austrian manufacturing footprint. Unimicron Technology and Zhen Ding Technology occupy positions within the East Asian scale-driven tier, with the former anchoring Taiwan's HDI-intensive capacity and the latter representing Chinese volume fabrication. Nippon Mektron sits within the technology-integrated conglomerate category, reflecting Japanese industrial group structures that combine materials science with board-level manufacturing.
| Leading Market Players |
|---|
| AT&S |
| Unimicron Technology |
| Zhen Ding Technology |
| Sanmina |
| Suzhou Dongshan Precision Manufacturing |
| DSBJ |
| Nippon Mektron |
| Ventec International Group |
| TTM Technologies |
| Others |
Supply Flow & Price Mechanics
Tier-1 power electronics procurement teams now mandate AEC-Q100 qualification as a non-negotiable gate, compressing supplier pools and forcing mid-tier fabricators toward either premium certification investment or volume retreat into cost-optimized infotainment tiers.
Pricing Analysis
Board-and-certification bundling dominates transactional structures, with AEC-Q100-qualified multi-layer boards commanding substantial premiums over standard-grade alternatives. Price differentiation rests on thermal cycling reliability grades and layer-count density, with powertrain applications showing lowest price sensitivity due to $2 million-plus second-source qualification costs. Cost compression in infotainment rigid PCB tiers is intensifying because copper-clad laminate volatility erodes fabricator margins.
Supply Chain Analysis
Dual-sourcing requirements from German and Japanese OEMs mandate qualified secondary suppliers for 800V inverter modules, stretching qualification pipelines across 18-24 month cycles. Manufacturing concentrates in Germany, Japan, and Taiwan, with high-Tg laminates and ABF substrates drawing from concentrated East Asian chemical suppliers. Single-source vulnerability in specialty resin formulations threatens thermal performance tiers. Distribution runs through Tier-1 system integrators consolidating multi-layer and HDI procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive PCB Market reads as a late-cycle quality story where electrification and ADAS penetration are shifting procurement authority toward AEC-Q100-qualified fabricators capable of 150°C continuous operation.
For Market Incumbents: Hedge against margin erosion in infotainment rigid PCB tiers by locking long-term supply agreements for 800V powertrain modules. Prioritize backward integration into high-Tg laminate sourcing to preempt Japan-Taiwan supply concentration risks. Defend positioning through ISO 26262 ASIL-D certification investment for autonomous drive-by-wire programs.
For New Entrants and Emerging Players: Launch via India's PLI scheme localization incentives targeting EV powertrain module assembly for domestic OEM programs. White-space targets include flexible PCB capacity for zonal E/E architectures and embedded component technology for domain controllers. Penetrate through 5G-V2X antenna integration partnerships requiring flexible-rigid hybrid board expertise.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision specialists holding AEC-Q100 and ISO 26262 dual certification alongside established European OEM relationships. Long-term viability favors fabricators with captive high-Tg laminate supply and qualification pipelines locked through 2035 zero-emission vehicle program ramps. Watch NHTSA autonomous vehicle guidance evolution as the inflection signal for PCB redundancy specification rewrites.
| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Certification Investment | Unlocks Tier-1 power electronics contracts from Continental, Bosch, and Denso procurement teams. |
| High-Tg Laminate Backward Integration | Reduces exposure to Japan-Taiwan epoxy resin concentration for 150°C thermal cycling applications. |
| India PLI Scheme Manufacturing Footprint | Captures domestic EV module assembly demand under component localization incentives. |
| ISO 26262 ASIL-D Qualification | Positions suppliers for premium autonomous drive-by-wire system procurement from German luxury OEMs. |
| Long-Term Supply Agreement Lock | Secures capacity allocation for 800V battery disconnect and inverter platforms before qualification bottlenecks intensify. |
Methodological Framework
Multiple input streams — primary interviews with Tier-1 procurement directors and OEM platform engineers, secondary validation through vehicle production databases and IHS Markit registration data, and technical specification analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder roles engaged included automotive PCB fabrication executives, AEC-Q100 testing laboratory directors, high-Tg laminate supplier technical leads, and aftermarket distribution channel managers. Secondary sources encompassed SEC filings from listed fabricators, MIIT automotive electronics standard documentation, and EU Green Deal regulatory filings.
Historical volume trajectories were cross-referenced against panel input from procurement executives to establish baseline assumptions across the analysis window. Segmentation dimensions modeled include product type, end-user authority tier, technology density grade, and application thermal severity. CAGRs were derived from shipment volume reconciliation against OEM platform rollout schedules and electrification content-per-vehicle curves. Forecast inputs incorporated battery electric vehicle production quotas under China's dual carbon goals and EU zero-emission vehicle mandate compliance pathways.
Several conditions sit outside the modeled scope, including unannounced OEM platform cancellations, abrupt REACH substance list expansions affecting flame-retardant formulations, and geopolitical disruptions to Taiwan Strait shipping lanes. Deviation in NHTSA autonomous vehicle guidance timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Electronic Expansion Valve Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Market
Automotive Electrical & Electronics
Automotive Thermoelectric Generator Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
On-Board Fuse Box Market
Automotive Electrical & Electronics
TPMS Battery Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Automotive Thermal Management System Market
Automotive Electrical & Electronics
Europe Automotive EPS Market
Automotive Electrical & Electronics
Automotive EMC Test Equipment Market
Automotive Electrical & Electronics
Europe Automotive LED Lighting Market
Automotive Electrical & Electronics
E-Bike Lights Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
Wire Harness Market