
 Automotive Zonal Gateway ECU Market | 2026-2036
Automotive Zonal Gateway ECU Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Zonal Gateway ECU Market Insights
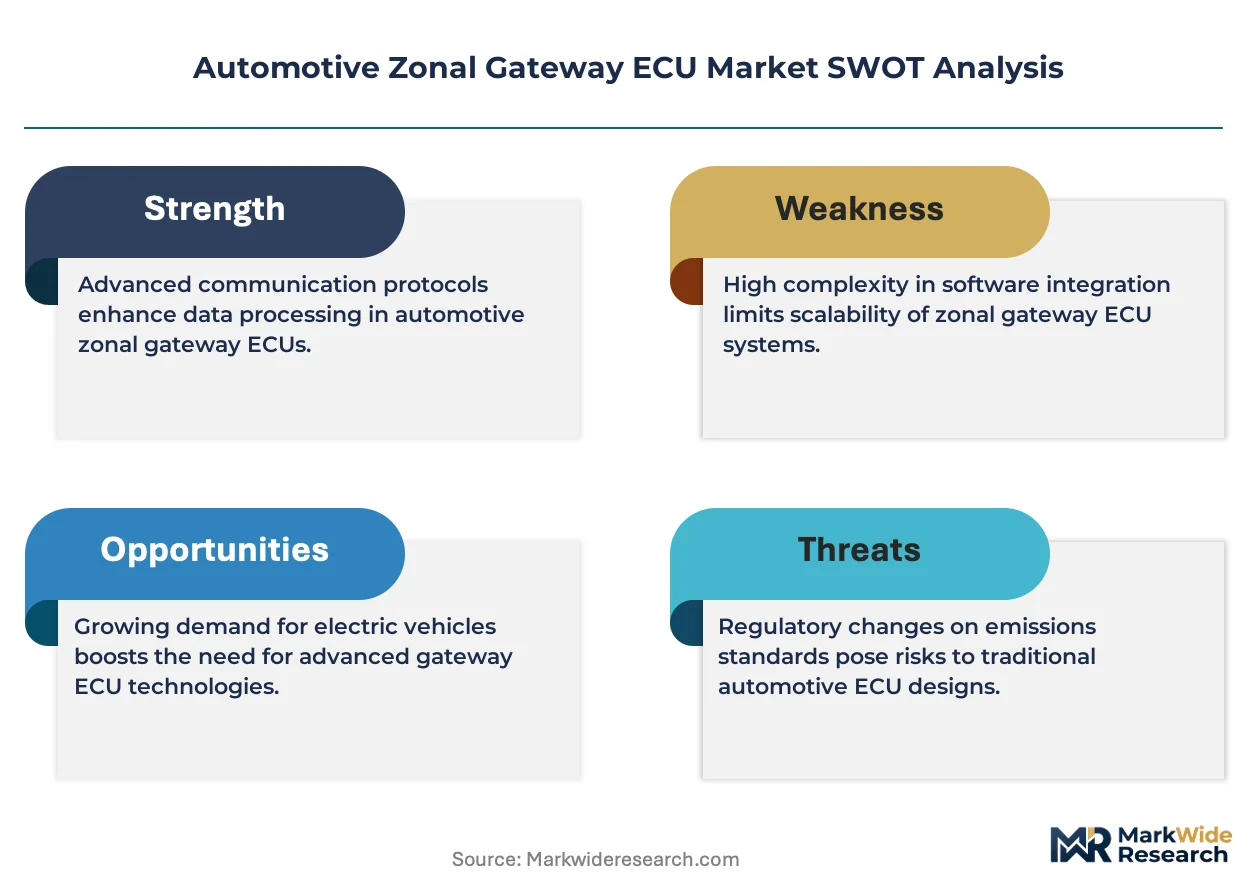
UNECE WP.29 Regulation No. 155 is recalibrating the cost-of-entry calculus for automotive cybersecurity certification across zonal gateway architectures. Robert Bosch leverages its captive semiconductor partnerships to sustain vertical integration from chip design to ECU assembly. Continental AG anchors European supply through dedicated manufacturing in Regensburg. NXP Semiconductors dominates the silicon layer with ASIL-D qualified gateway processors that compete on functional safety benchmarks.
Automotive Zonal Gateway ECUs are centralized communication nodes that route data between vehicle domains using Ethernet backbone switches with 1-10 Gbps throughput and embedded hardware security modules. Their primary purpose is to replace distributed CAN/LIN architectures with zone-based topologies that reduce wiring harness mass and enable over-the-air software updates. Domain Gateway ECUs lead current revenue as automakers transition through hybrid architectures, while Ethernet-based systems represent the fastest-growing technology segment as 10BASE-T1S and 100BASE-T1 standards displace legacy CAN-FD in new platforms. Auxiliary ECUs occupy a mature margin pool serving legacy fleet retrofits where full zonal conversion remains uneconomical.
FCC Part 15 in the United States governs unintentional radiated emissions from high-speed Ethernet links within gateway modules, while EU Cyber Resilience Act mandates vulnerability disclosure timelines and secure-by-design obligations for connected vehicle components. Japan's METI has aligned its automotive software update guidelines with UNECE frameworks, creating convergent compliance burdens for suppliers serving multiple export markets. Stakeholders must monitor whether regional divergence in cybersecurity audit requirements fragments platform development or accelerates consolidation around standardized reference designs.
Market Dynamics
Automotive OEMs are dismantling distributed CAN architectures in favor of zone-based Ethernet backbones that slash wiring harness mass and enable centralized compute consolidation.
Growth Catalysts
- Ethernet backbone proliferation:10BASE-T1S and 100BASE-T1 standards are displacing legacy CAN-FD in new vehicle platforms, creating socket demand for high-throughput gateway processors.
- UNECE WP.29 R155:Mandatory cybersecurity management systems for vehicle type approval are forcing ECU redesigns with embedded hardware security modules across export markets.
- Premium passenger vehicle OEMs:German and Japanese luxury manufacturers are accelerating zonal architecture adoption to support software-defined vehicle roadmaps.
Market Restraints
- Silicon supply concentration:ASIL-D qualified gateway processors depend on a narrow base of semiconductor foundries concentrated in Taiwan and South Korea.
- Regulatory fragmentation:Divergent cybersecurity audit timelines between EU Cyber Resilience Act and FCC Part 15 certification are extending platform development cycles.
- Legacy fleet inertia:Auxiliary ECU retrofits for existing CAN-based vehicles face uneconomical conversion costs, capping addressable volume in mature vehicle parcs.
Strategic Opportunities
- Software-defined vehicle convergence:Over-the-air update infrastructure is converging with zonal gateway deployment, opening recurring revenue streams for cybersecurity subscription services.
- EU Cyber Resilience Act tailwind:Secure-by-design mandates and vulnerability disclosure obligations are creating certification moats for compliant ECU suppliers.
- Domain gateway transition:Hybrid architectures bridging legacy domains with zonal backbones represent a multi-year intermediate market before full Ethernet conversion.
Industry Challenges
- Functional safety certification timelines:ASIL-D qualification for gateway processors requires 18-24 month validation cycles that compress product refresh windows.
- Cross-domain integration complexity:Routing between legacy powertrain CAN segments and new zonal Ethernet domains demands protocol translation engineering that strains development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Zonal Gateway ECU Market |
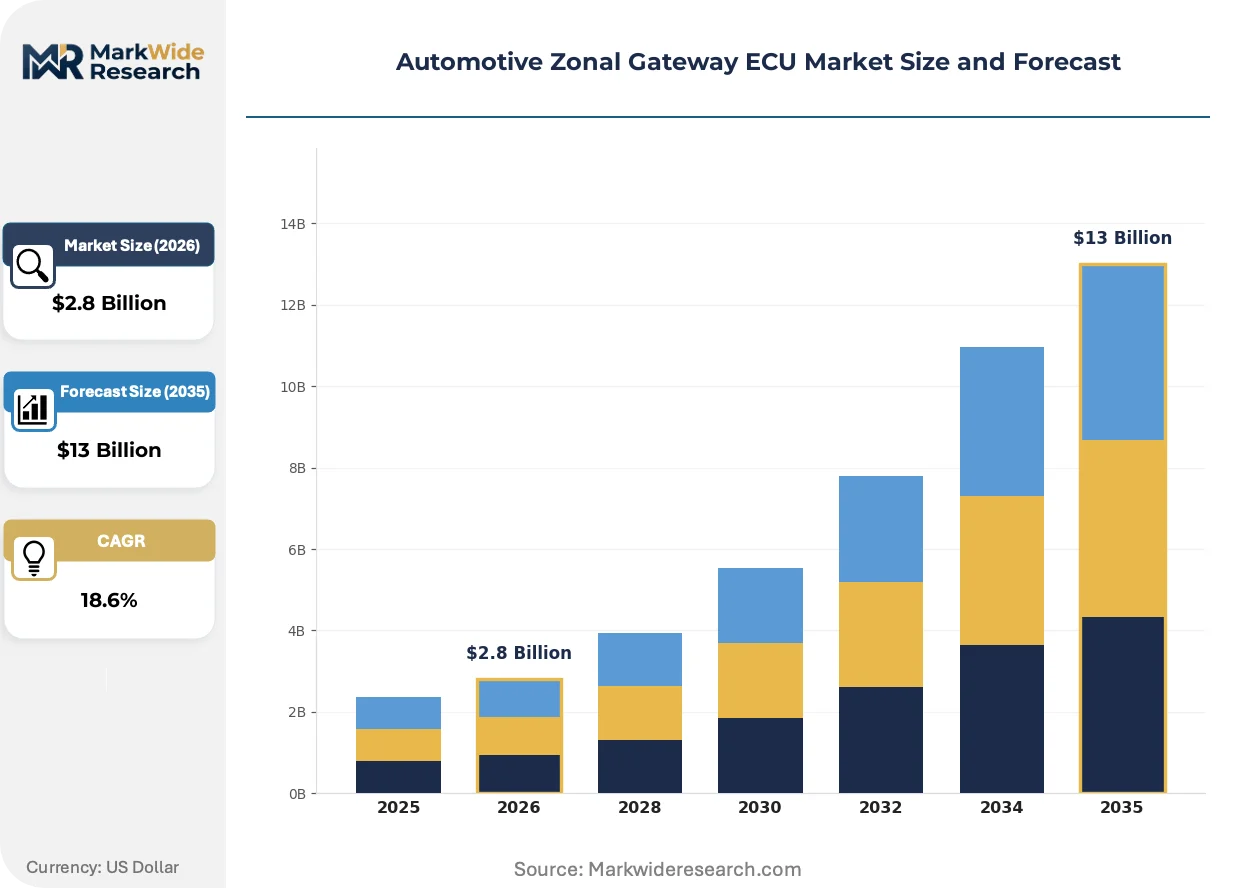
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Central Gateway ECU, Domain Gateway ECU, Auxiliary ECU, Communication Gateway Technology: CAN, LIN, Ethernet, FlexRay, MOST Application: Powertrain Control, Body Electronics, Infotainment Systems, Safety Systems, Autonomous Driving End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Robert Bosch, Continental AG, Aptiv PLC, Denso Corporation, ZF Friedrichshafen AG, Valeo SA, Visteon Corporation, Harman International Industries, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Zonal Gateway ECU Market Trends and Innovations
Gateway ECU development is pivoting from hardware-centric designs to software-configurable platforms that decouple physical zone boundaries from functional domain assignments.
Hardware security modules are converging with Ethernet switch silicon to create single-chip gateway solutions that reduce board space and power draw. Tier 1 suppliers in Germany and Japan are qualifying these integrated devices for 2026 platform launches. This convergence is compressing the supplier base around semiconductor vendors capable of delivering combined safety and security certification.
EU Cyber Resilience Act mandates are forcing ECU suppliers to embed automated vulnerability scanning and signed firmware update mechanisms. The regulation's secure-by-design obligations are reshaping development workflows to front-load security architecture decisions. Premium vehicle platforms targeting European type approval are absorbing these compliance costs fastest.
Automaker procurement teams are consolidating gateway ECU awards around suppliers offering end-to-end cybersecurity liability coverage. Tier 1 vendors with captive semiconductor partnerships are capturing expanded scope contracts that bundle silicon supply with ECU assembly. This consolidation is most visible in German OEM supply chains where Bosch and Continental anchor multi-year platform agreements.
Automotive Zonal Gateway ECU Market Segmentation
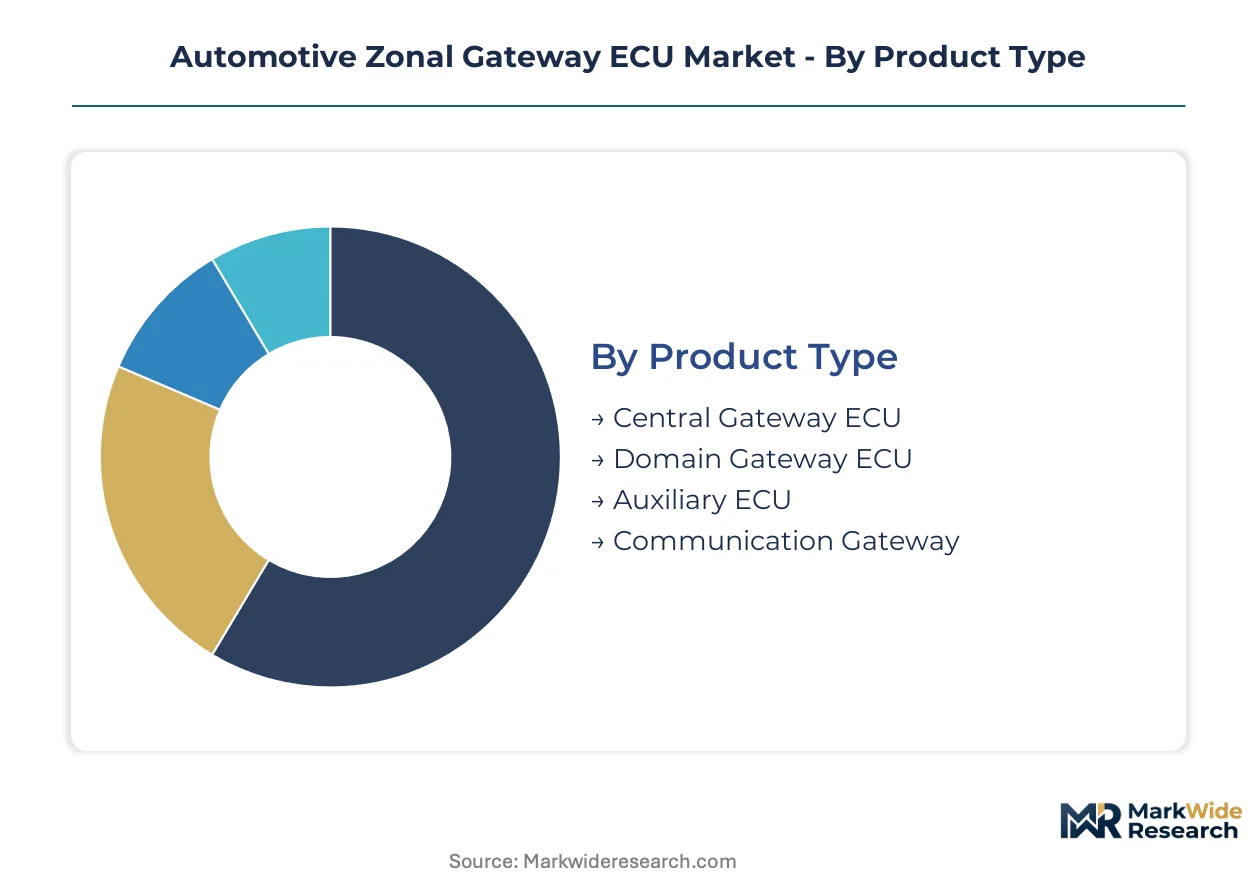
Zonal gateway ECU procurement divides sharply between volume platforms seeking cost-optimized domain bridging and premium architectures demanding centralized compute consolidation. Segmentation discipline separates transitional hybrid deployments from native Ethernet backbone designs.
Product Type:
Volume concentration currently favors intermediate solutions bridging legacy CAN domains, while premium platforms absorb full centralization costs.
- Domain Gateway ECU:Intermediate nodes translate between legacy powertrain CAN segments and emerging zonal Ethernet backbones using protocol conversion stacks. German and Japanese luxury OEMs dominate current procurement as they transition through hybrid architectures before full centralization. Functional safety certification to ASIL-D anchors supplier selection.
- Central Gateway ECU:Unified routing hubs consolidate all vehicle domain traffic through high-throughput Ethernet switches with embedded hardware security modules. Native zonal architectures in next-generation premium platforms absorb these modules despite per-unit cost premiums over distributed alternatives.
- Auxiliary ECU:Supplementary nodes extend zonal coverage to legacy vehicle segments without full architecture conversion.
- Communication Gateway:Specialized modules handling external connectivity including V2X and telematics integration.
Today's leader: Domain Gateway ECU. Tomorrow's challenger: Central Gateway ECU.
Technology:
Physical layer selection tracks automaker position on the software-defined vehicle roadmap, with cost-sensitive applications preserving legacy buses longer.
- Ethernet:10BASE-T1S and 100BASE-T1 single-pair standards enable 1-10 Gbps backbone throughput with 15-meter unshielded reach, slashing wiring harness mass versus equivalent CAN-FD bundles. Premium passenger vehicle platforms in Germany and Japan specify Ethernet-native zonal gateways to support over-the-air update bandwidth requirements.
- CAN:Controller Area Network persists in powertrain and chassis domains where deterministic latency requirements meet severe cost constraints. Legacy fleet retrofits and economy vehicle platforms sustain demand despite bandwidth limitations.
- LIN:Low-cost single-wire bus serves door modules, seat controls, and other body electronics with modest data requirements.
- FlexRay:Time-triggered deterministic protocol retains niche position in brake-by-wire and steer-by-wire safety systems.
- MOST:Media-oriented systems transport infotainment audio and video streams in legacy premium vehicles.
Ethernet climbs fastest on new platform launches; CAN defends installed base through fleet longevity.
Application:
Safety-critical domains impose the steepest certification burdens, filtering supplier participation toward vertically integrated tier-1s with captive semiconductor partnerships.
- Autonomous Driving:Sensor fusion gateways aggregate camera, radar, and lidar data streams at multi-gigabit rates for centralized perception compute. ASIL-D functional safety and ISO 21434 cybersecurity certification create dual compliance moats that concentrate supply among German and Japanese tier-1s with dedicated foundry relationships.
- Safety Systems:Airbag, ABS, and stability control gateways demand deterministic latency below 10 milliseconds with fail-operational redundancy.
- Powertrain Control:Engine and transmission management retains CAN-FD dominance in internal combustion platforms.
- Body Electronics:Climate, lighting, and comfort systems migrate gradually from LIN to CAN-FD as feature complexity rises.
- Infotainment Systems:Consumer electronics integration drives Ethernet adoption for high-resolution displays and streaming bandwidth.
Autonomous driving specifications set the performance ceiling; body electronics capture unit volume.
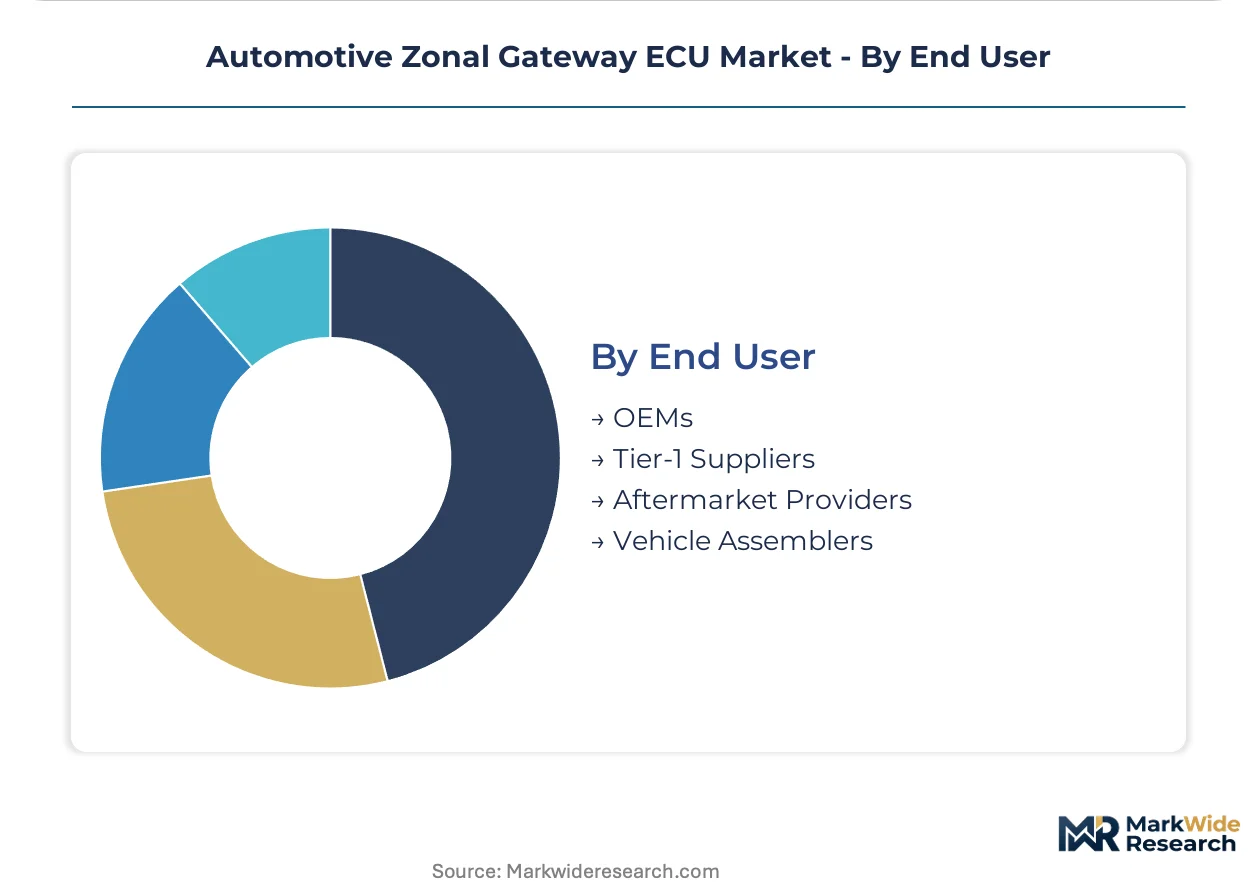
End User:
Procurement authority concentration favors direct OEM relationships over tier-1 intermediation in cybersecurity-sensitive platforms.
- OEMs:German premium manufacturers increasingly source gateway ECUs directly from semiconductor vendors for software-defined vehicle platforms, bypassing traditional tier-1 assembly margins. End-to-end cybersecurity liability coverage and long-term silicon supply commitments dominate sourcing criteria.
- Tier-1 Suppliers:Bosch and Continental anchor European supply through captive manufacturing in Regensburg and dedicated semiconductor partnerships.
- Aftermarket Providers:Retrofit specialists serve legacy fleet auxiliary ECU demand where full zonal conversion remains uneconomical.
- Vehicle Assemblers:Contract manufacturers integrate gateway modules into complete vehicle electrical architectures.
OEM direct procurement gains share fastest; tier-1 suppliers defend position through integrated safety-security certification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered automotive gateway architecture through Bosch and Continental engineering centers in Stuttgart and Hanover, establishing the technical foundations that now diffuse across premium vehicle platforms worldwide.
Germany
Bosch and Continental anchor European zonal gateway supply through captive semiconductor partnerships and dedicated manufacturing in Regensburg. KBA vehicle type approval processes enforce UNECE WP.29 R155 cybersecurity certification timelines that compress supplier qualification windows. Bavaria's automotive electronics cluster concentrates ASIL-D functional safety engineering talent for next-generation Ethernet backbone platforms.
United States
Detroit Three OEMs and Tesla drive demand for centralized compute consolidation in software-defined vehicle architectures. FCC Part 15 governs unintentional radiated emissions from high-speed Ethernet links within gateway modules, creating pre-market testing burdens. Michigan's automotive corridor hosts Tier-1 integration facilities serving domestic premium platform launches.
Japan
Toyota, Honda, and Nissan accelerate zonal adoption to support autonomous driving sensor fusion requirements. METI aligned automotive software update guidelines with UNECE frameworks, creating convergent compliance obligations for export-oriented suppliers. Nagoya's Chubu region concentrates Denso engineering resources for gateway processor qualification.
China
Domestic EV manufacturers BYD and NIO deploy zonal architectures to reduce wiring harness mass in battery-electric platforms. MIIT cybersecurity standards for connected vehicles mandate hardware security module integration in gateway designs. Shanghai's Yangtze River Delta cluster attracts NXP and local semiconductor packaging for gateway processor supply.
South Korea
Hyundai Motor Group and Kia specify Ethernet-native gateways for Genesis luxury platforms and EV-dedicated architectures. MFDS automotive cybersecurity guidelines shape supplier development workflows for domestic type approval. Seoul Capital Area concentration of Samsung Electronics and SK Hynix foundry capacity supports ASIL-D silicon supply security.
Automotive Zonal Gateway ECU Market Competitive Landscape
The competitive structure tilts toward vertically integrated Tier-1s with captive semiconductor access. Consolidation around German and Japanese engineering centers produces a concentrated supplier base where functional safety certification creates entry barriers. Three archetypes dominate: diversified automotive electronics conglomerates, specialized gateway module suppliers, and semiconductor vendors forward-integrating into ECU assembly. Competitive moves center on multi-year platform agreements locking in silicon supply security and cybersecurity liability coverage expansion.
Among diversified automotive electronics conglomerates, Robert Bosch GmbH and Continental AG exemplify the integrated engineering-and-manufacturing archetype that anchors European supply chains. Denso Corporation occupies a parallel position in Japanese OEM procurement structures. These entities represent the premium-tier vector where end-to-end certification capabilities and captive foundry relationships determine contract awards.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental AG |
| Aptiv PLC |
| Denso Corporation |
| ZF Friedrichshafen AG |
| Valeo SA |
| Visteon Corporation |
| Harman International Industries |
| NXP Semiconductors |
| Others |
Pricing and Supply Chain Analysis
Captive semiconductor partnerships anchor both supply security and pricing power for Tier 1 suppliers serving premium OEM platforms. Bosch and Continental leverage in-house production of ASIL-D qualified gateway processors to command premium positioning against competitors dependent on merchant silicon.
Pricing Analysis
Bundled cybersecurity liability coverage increasingly separates contract winners from price-takers in gateway ECU procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ASIL-D qualified modules commanding substantial premiums over lower safety tiers. Cost compression in standard-grade domain gateways is intensifying because Chinese EV manufacturers are vertically integrating ECU design. Aftermarket retrofit providers exhibit the highest price sensitivity, while German luxury OEMs absorb premium pricing for end-to-end security coverage.
Supply Chain Analysis
Ocean freight volatility and air cargo premiums for semiconductor wafers are reshaping landed cost structures for gateway module assembly. Taiwan, South Korea, and Germany anchor silicon supply for ASIL-D processors, while China and Mexico host downstream ECU integration. Raw material dependencies include automotive-grade epoxy resins, copper alloy interconnects, and rare-earth magnet materials for shielding. Single-source vulnerability concentrates in Taiwan foundry capacity for advanced node gateway processors. Distribution runs through OEM direct procurement channels for premium platforms and Tier 1 supplier networks for volume applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive Zonal Gateway ECU Market functions as a stable compounder where regulatory cybersecurity mandates create durable demand visibility across vehicle replacement cycles.
For Market Incumbents: Lock in multi-year silicon supply agreements with foundry partners before capacity allocation tightens further. Deepen backward integration into hardware security module design to defend margin position against semiconductor vendors forward-integrating into ECU assembly. Prioritize ASIL-D certification pipeline expansion as emerging Chinese competitors shortcut validation timelines.
For New Entrants and Emerging Players: Mid-size European commercial vehicle OEMs represent an underserved buyer archetype with unconsolidated gateway procurement and lower cybersecurity sophistication than premium passenger car divisions. Target this segment through white-label domain gateway modules that bridge legacy CAN architectures with zonal Ethernet backbones. Pursue regulatory consulting partnerships to accelerate UNECE WP.29 R155 compliance for smaller OEMs lacking in-house certification resources.
For Investors and Strategic Acquirers: Roll-up economics work for specialized gateway software stack providers because OEM consolidation around standardized reference designs is compressing the vendor base for protocol translation layers. Five-to-ten-year viability hinges on recurring cybersecurity subscription revenue attachment rates. Monitor ASIL-D qualification backlog duration as the signal to watch for inflection in supplier pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Bosch and Continental leverage standardized Ethernet switch reference designs to reduce OEM integration costs. |
| Software-Defined Vehicle Investment | NXP Semiconductors qualifies combined safety-security silicon for 2026 premium platform launches. |
| Geographic Manufacturing Footprint | Denso expands Nagoya engineering capacity to serve Toyota zonal architecture roadmaps. |
| Charging Infrastructure Partnership | Gateway ECU suppliers bundle V2X communication modules with zonal backbone contracts. |
| Battery Supply Agreement | EV-dedicated architectures from BYD and NIO drive zonal gateway socket demand in China. |
Research Methodology
Coverage spans Germany, Japan, the United States, China, and South Korea, with primary inputs from each automotive production cluster. The research combines structured interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and semiconductor vendor automotive sales leads with secondary validation. Secondary sources include vehicle production databases, IHS Markit registration data, UNECE regulatory filings, and SEC 10-K automotive segment disclosures. Bottom-up unit demand estimates triangulate against top-down market value reconstruction.
Granularity-level modeling disaggregates volume and value across the projection horizon by product type, technology, application, end user, and regional production cluster. The analytical framework incorporates vehicle class stratification, propulsion architecture differentiation, content-per-vehicle trajectories, OEM tier positioning, and regional regulatory cluster alignment. CAGRs derive from segment-level unit forecasts multiplied by technology-specific average selling price evolution. Forecast inputs include semiconductor foundry capacity expansion schedules, UNECE type approval timeline acceleration, and software-defined vehicle platform launch calendars.
Underlying measurement precision varies by segment; Ethernet-native central gateway forecasts carry tighter precision than auxiliary ECU retrofits where fleet longevity assumptions dominate uncertainty. Forecasts reflect assumptions about regulatory harmonization pace, foundry yield recovery, and OEM platform consolidation patterns. A model refresh is warranted upon material change in UNECE cybersecurity audit timeline harmonization or Taiwan semiconductor export control expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Electric Vehicle HV Cables Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Module Market
Automotive Electrical & Electronics
Automotive Thermoelectric Generator Market
Automotive Electrical & Electronics
On-Board Charger Market
Automotive Electrical & Electronics
Global Automotive Multifunctional Lamp Market
Automotive Electrical & Electronics
Automotive Electric Actuator Market
Automotive Electrical & Electronics
Russia Automotive Eps Market
Automotive Electrical & Electronics
Nox Automotive Sensors Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Ambulance Power Inverter Market
Automotive Electrical & Electronics
Global Automotive on Board AC-DC Power Inverters Market
Automotive Electrical & Electronics
Automotive Power Module Packaging Market