
 Wire Harness Market | 2026-2036
Wire Harness Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Harness Market Outlook
Mexico's automotive manufacturing corridor is fragmenting as capacity expands across multiple OEM-tier supplier ecosystems. LEONI leverages its vertical integration from copper drawing to final assembly to sustain margin control in high-complexity automotive harnesses. Yazaki Corporation anchors volume leadership through captive relationships with Japanese OEM transplant factories in Guanajuato and Baja California.
A wire harness comprises bundled conductors, connectors, terminals, and protective sleeving organized into discrete electrical distribution subsystems, typically engineered to carry currents from milliamps in sensor circuits to over 300 amps in battery-electric powertrains. Its primary purpose is to transmit electrical power and signals reliably across mechanically dynamic assemblies while withstanding vibration, thermal cycling, and chemical exposure. Automotive harnesses dominate value capture due to electrification-driven copper intensity and safety-critical redundancy requirements, while fiber optic segments within data communication applications are expanding fastest as vehicle architectures shift to zonal computing topologies. Industrial equipment harnesses occupy a mature, price-competitive tier where polyurethane-jacketed cable assemblies differentiate on abrasion resistance in mobile machinery.
NHTSA crashworthiness standards and FMVSS electrical safety rules in the United States, combined with ECE R100 high-voltage compliance in Europe and China's GB/T standards for new energy vehicles, collectively elevate barrier costs for harness suppliers seeking cross-regional OEM qualification. REACH substance restrictions and the EU Green Deal's embodied carbon tracking requirements are forcing material substitutions away from PVC toward thermoplastic elastomers in European-bound production. Stakeholders must monitor zonal E/E architecture adoption timelines, as domain consolidation threatens to displace discrete harness counts even as per-vehicle copper content rises.
Market Dynamics
Automotive electrification is compressing harness architectures from distributed domain controllers toward zonal computing nodes, reducing discrete wire counts while multiplying copper intensity per high-voltage assembly. This topological inversion forces suppliers to requalify termination technologies and thermal management materials at unprecedented speed.
Growth Catalysts
- GB/T High-Voltage Standards:China's mandatory insulation and shielding specifications for new energy vehicles are pulling specialized harness capacity into domestic joint ventures.
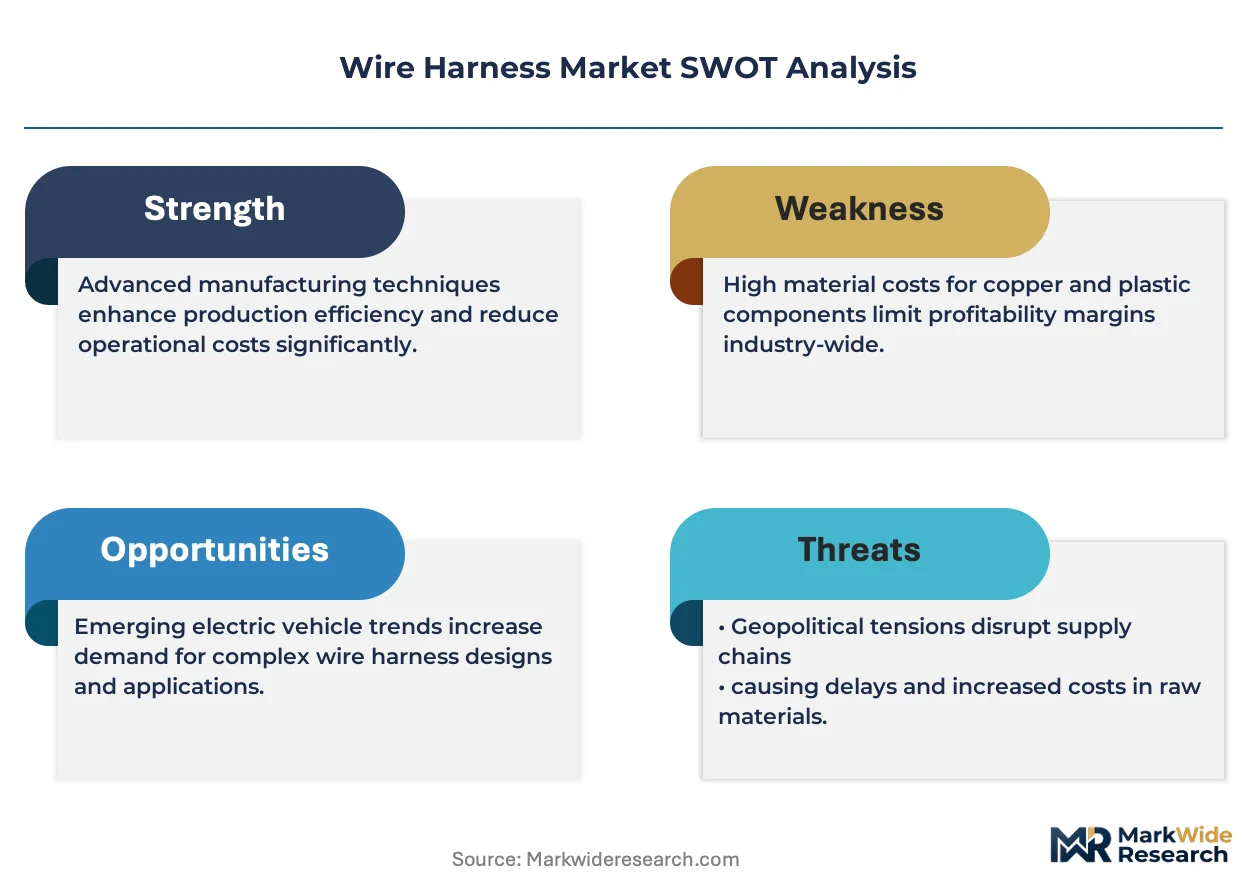
- Battery Platform Proliferation:Electric vehicle OEMs are expanding procurement of 800-volt harness assemblies as cell-to-pack designs multiply connection points.
- Mexico Nearshoring:Assembly operations are concentrating in Guanajuato and Baja California as Japanese and German OEMs relocate capacity from Asian supply bases.
Market Restraints
- Copper Price Volatility:Conductor material represents 35-45% of finished harness cost, exposing margins to LME commodity swings without pass-through mechanisms.
- REACH Halogen Restrictions:ECHA substance limitations on brominated flame retardants are forcing PVC-to-TPE substitutions that reduce supplier material options.
- Qualification Timelines:NHTSA FMVSS electrical safety certification and ECE R100 high-voltage compliance collectively extend OEM approval cycles beyond 18 months.
Strategic Opportunities
- India Automotive Corridor:PLI scheme incentives for electric vehicle component manufacturing are opening greenfield harness assembly opportunities in Tamil Nadu and Gujarat.
- Fiber Optic Convergence:Zonal E/E architectures are creating white space for optical backbone harnesses that multiplex sensor data at gigabit speeds.
- EU Green Deal Embodied Carbon Tracking:First-mover suppliers capturing Scope 3 copper provenance data are securing preferred supplier status with European OEMs.
Industry Challenges
- High-Voltage Technician Scarcity:Qualified termination specialists for 300+ amp battery connections remain concentrated in Germany and Japan, constraining expansion velocity.
- Legacy 12V Integration Friction:Hybrid architectures requiring simultaneous low-voltage signal and high-voltage power distribution are multiplying connector complexity without standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Harness Market |
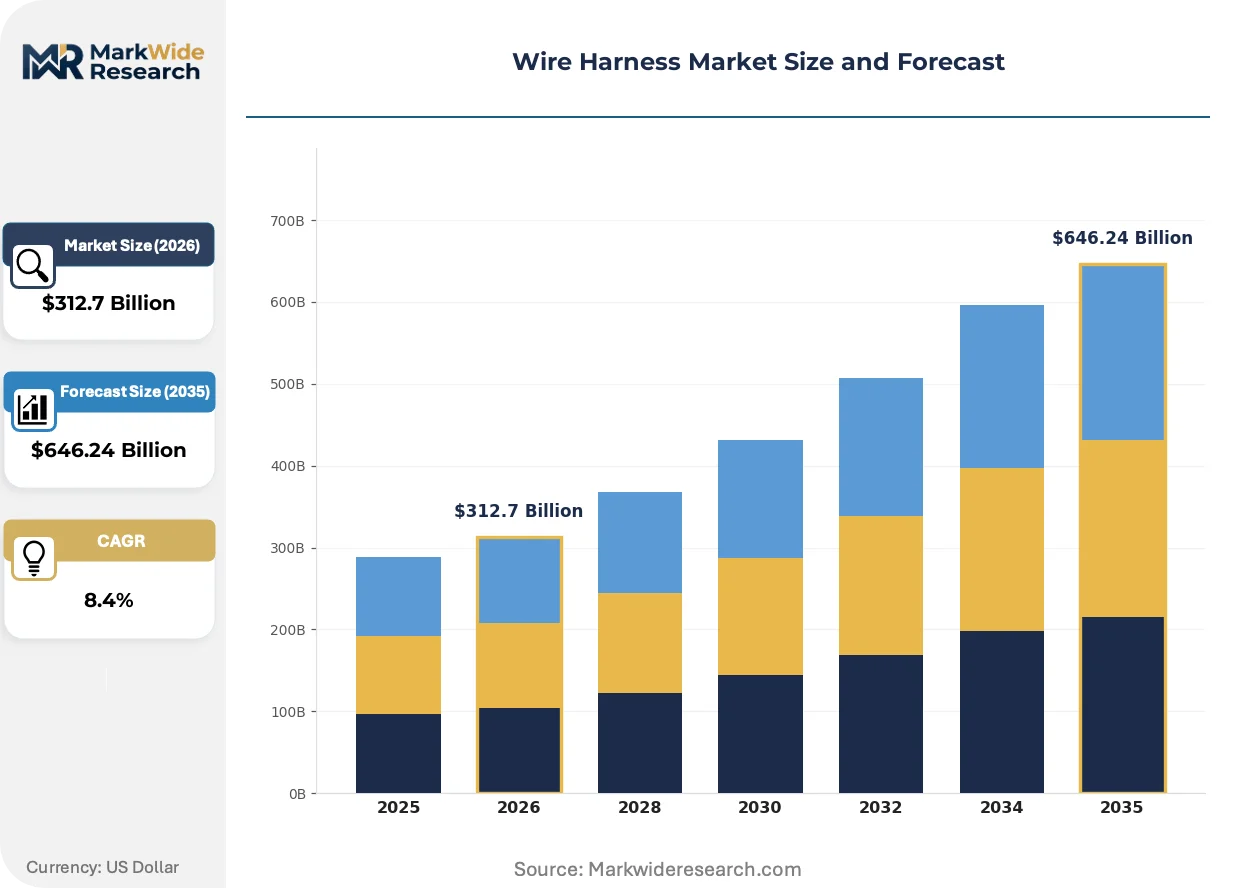
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $646.24 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automotive, Aerospace, Industrial Equipment, Consumer Electronics Material: Copper, Aluminum, Fiber Optic, Polyurethane Application: Power Distribution, Signal Transmission, Data Communication, Lighting End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Maintenance Services |
| Companies Covered | LEONI, Draxlmaier Group, Yazaki Corporation, Fujikura, Lear Corporation, Sumitomo Electric, Furukawa Electric, Molex, Aptiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Harness Market Strategic Shifts
Signal transmission architectures are bifurcating between copper-intensive power distribution and optical data backbones, with material selection now determined by zonal computing topology rather than vehicle class.
Optical harness segments employing polymer-clad silica fibers are virtualizing traditional copper sensor circuits in premium electric vehicle platforms. Mercedes-Benz and BMW Group are qualifying fiber-to-the-zone architectures for their 2026 model year computing consolidations. This virtualization is compressing the discrete harness count per vehicle even as aggregate data bandwidth requirements expand tenfold.
REACH substance restrictions and the EU Green Deal's embodied carbon tracking requirements are forcing material substitutions across European-bound production. ECHA evaluations of halogenated flame retardants are accelerating thermoplastic elastomer adoption in passenger compartment assemblies. Suppliers serving Stellantis and Volkswagen Group are restructuring compounding partnerships to secure bio-based TPE feedstocks ahead of 2027 reporting deadlines.
Buyer concentration among electric vehicle pure-plays is compressing harness procurement cycles from annual to quarterly negotiations. NIO, Rivian, and Lucid Motors are unbundling after-sales harness inventory liability onto tier-one suppliers. This concentration is most visible in California and Shanghai, where direct OEM-supplier engineering relationships are displacing traditional distributor channels for prototype-to-production transitions.
Wire Harness Market Segmentation
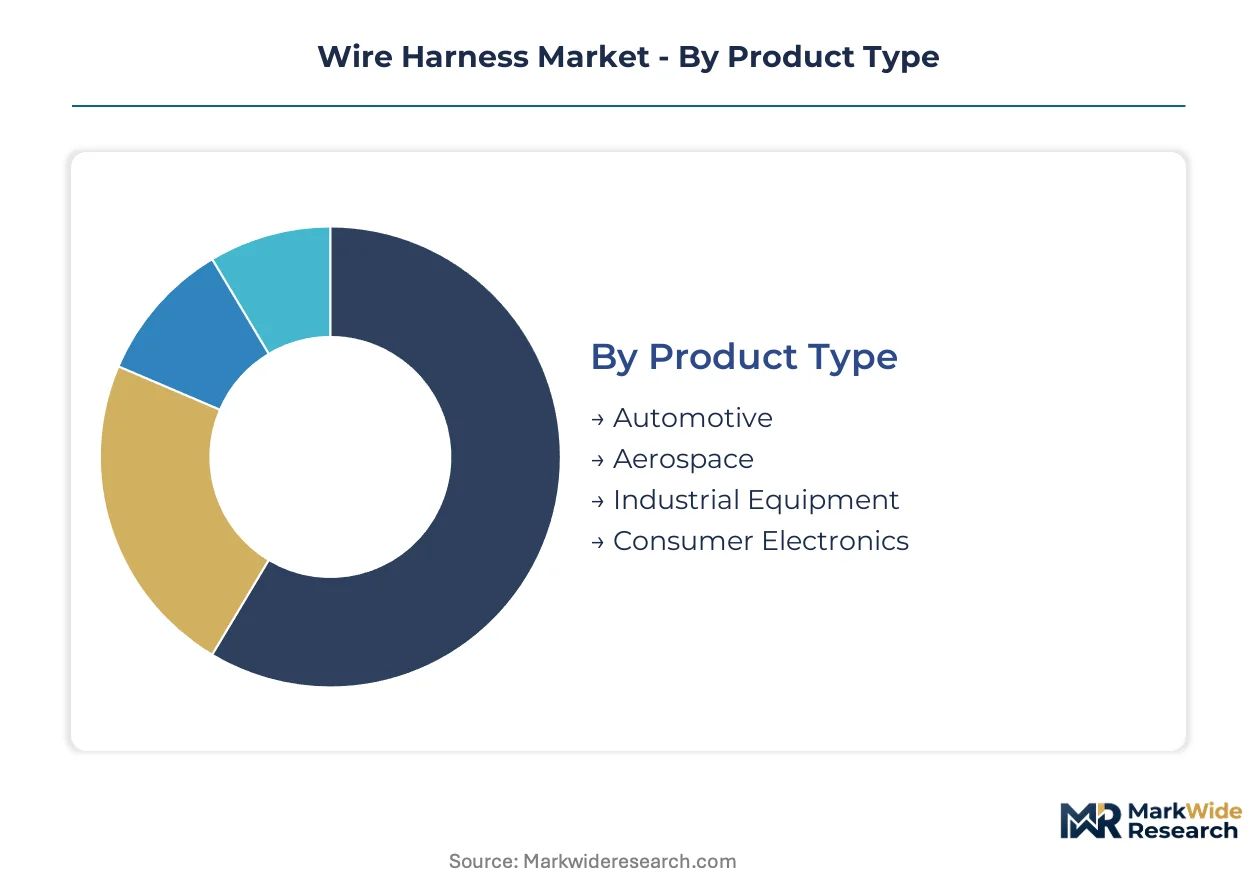
Wire harness segmentation reflects divergent material intensity and qualification barriers across end-use verticals. Electrification timelines and regulatory exposure vary sharply by product category, creating asymmetric growth profiles within the same supplier portfolios.
Product Type:
Application context determines copper density, shielding complexity, and thermal management requirements across vertical markets.
- Automotive:High-voltage battery assemblies carrying 300+ amps dominate material consumption as 800-volt platforms multiply connection points. OEM procurement concentrates in Guanajuato and Baja California nearshoring clusters, where Japanese and German transplant factories anchor volume demand.
- Aerospace:Mil-spec shielding and fire-resistant insulation meet FAA airworthiness standards for flight-critical power distribution. Qualification cycles extend beyond 24 months, locking incumbent suppliers into long-term airframe programs with Boeing and Airbus tier-1 ecosystems.
- Industrial Equipment:Abrasion-resistant polyurethane jackets differentiate mobile machinery harnesses in construction and agriculture applications.
- Consumer Electronics:Miniaturized flex circuits and ribbon cables serve device internal power routing with compressed lead times.
Automotive commands the established base. The steepest expansion runs through Aerospace as next-generation electric propulsion aircraft multiply high-voltage harness counts.
Material:
Conductor selection balances conductivity requirements against weight constraints and regulatory substance restrictions.
- Copper:Oxygen-free high-conductivity grades remain mandatory for automotive power distribution and battery interconnects. LME price volatility exposes 35-45% of finished harness cost to commodity swings without contractual pass-through mechanisms in spot procurement relationships.
- Aluminum:Lightweight substitution gains traction in aerospace harnesses where every kilogram reduction translates to fuel burn savings. Termination reliability challenges constrain adoption in high-vibration automotive environments despite cost advantages.
- Fiber Optic:Polymer-clad silica fibers multiplex sensor data at gigabit speeds for zonal E/E architectures in premium electric vehicles.
- Polyurethane:Jacketing compounds deliver abrasion resistance for industrial equipment exposed to hydraulic fluid and mechanical wear.
Copper retains volume leadership. Fiber optic is climbing the fastest as Mercedes-Benz and BMW Group qualify optical backbone architectures.
Application:
Functional purpose dictates shielding layers, connector density, and signal integrity specifications.
- Power Distribution:High-current busbars and laminated copper sheets distribute battery energy across electric vehicle platforms. China's GB/T insulation standards and ECE R100 high-voltage compliance force specialized shielding configurations that differentiate qualified from unqualified suppliers.
- Signal Transmission:Twisted-pair and coaxial constructions preserve data integrity for sensor circuits in ADAS and powertrain control modules. Domain controller consolidation is compressing discrete signal harness counts even as per-vehicle copper content rises.
- Data Communication:Optical and shielded twisted-pair assemblies serve infotainment and telematics backbone requirements.
- Lighting:Low-gauge harnesses route power to LED headlamp and interior illumination systems with simplified thermal profiles.
Power Distribution anchors supplier revenue. Data Communication is expanding most quickly as vehicle architectures virtualize copper sensor circuits.
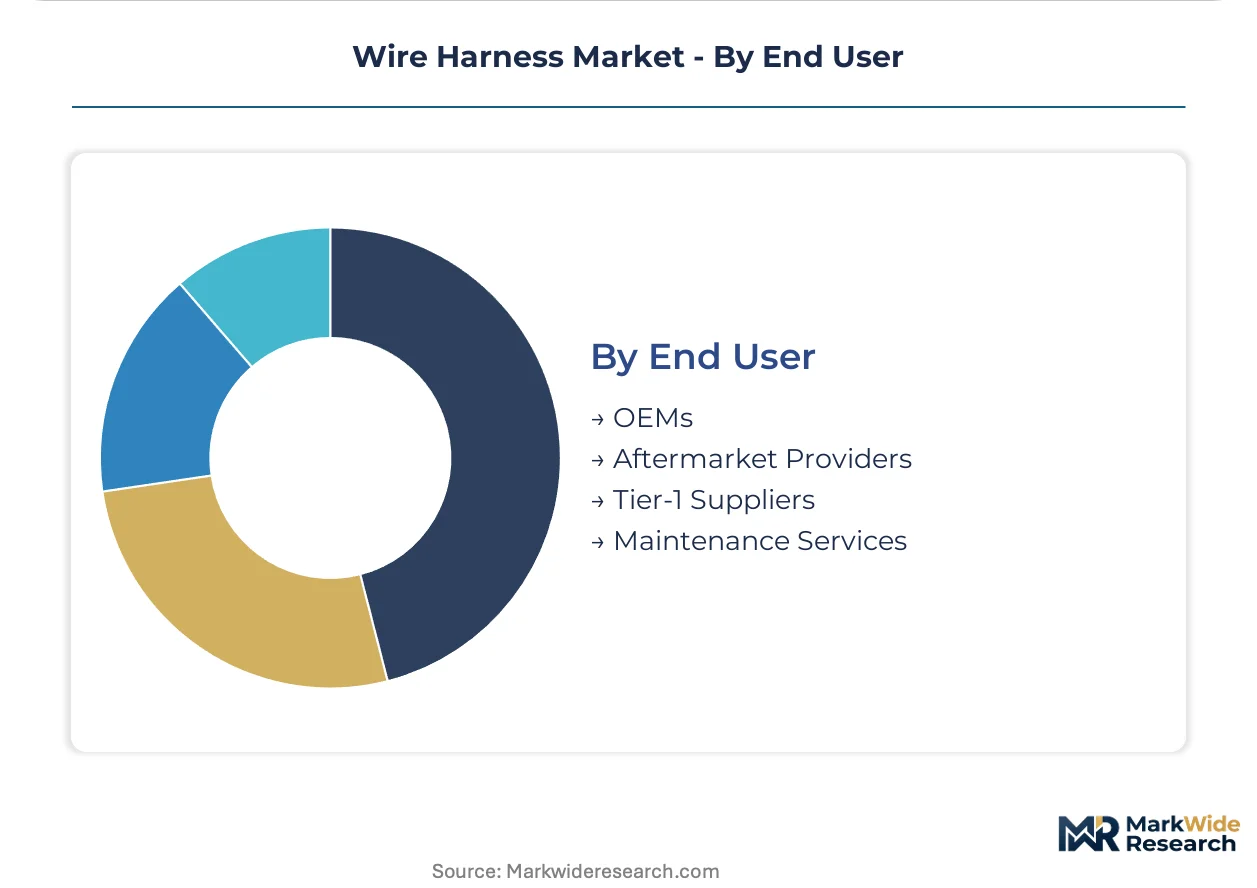
End User:
Procurement authority and technical integration responsibility vary across the value chain.
- OEMs:Direct engineering relationships with harness suppliers are displacing traditional distributor channels for prototype-to-production transitions. NIO, Rivian, and Lucid Motors unbundle after-sales inventory liability onto tier-one partners, compressing procurement cycles to quarterly negotiations.
- Tier-1 Suppliers:LEONI and Yazaki Corporation integrate backward into copper drawing and connector manufacturing to sustain margin control. Captive relationships with Japanese OEM transplant factories in Mexico secure volume allocation.
- Aftermarket Providers:Independent distributors serve collision repair and vehicle modification demand with reverse-engineered harness assemblies.
- Maintenance Services:Authorized service networks manage warranty-period harness replacements with OEM-specified components.
Tier-1 Suppliers control production volume. OEM direct procurement is gaining share fastest as electric vehicle pure-plays consolidate supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes wire harnesses primarily for battery-electric powertrain integration, while Germany and Japan emphasize high-voltage shielding for premium vehicle architectures, and Mexico concentrates on nearshored assembly for North American OEM transplant factories.
China
Domestic NEV manufacturers are multiplying 800-volt battery platform designs, pulling specialized high-voltage harness capacity into joint ventures with European and Japanese tier-one suppliers. GB/T insulation and shielding specifications for new energy vehicles mandate specialized material qualifications that differentiate approved from unqualified suppliers. Production clusters concentrate in the Yangtze River Delta around Shanghai and Jiangsu province, where CATL and BYD anchor cell-to-pack assembly ecosystems.
Germany
Premium OEM electrification timelines are compressing harness procurement cycles from annual to quarterly negotiations as Mercedes-Benz and BMW Group accelerate zonal E/E architecture adoption. ECE R100 high-voltage compliance and REACH substance restrictions on halogenated flame retardants force PVC-to-TPE material substitutions across supplier portfolios. Manufacturing gravity centers on Bavaria and Baden-Württemberg, where Stuttgart and Munich anchor Mercedes-Benz, BMW, and Porsche assembly operations with captive harness supply relationships.
Japan
Japanese OEM transplant factories in Guanajuato and Baja California are consolidating harness procurement through captive relationships with home-country suppliers as nearshoring accelerates. METI industrial policy supports domestic high-voltage termination specialist training to address technician scarcity for 300+ amp battery connections. Production remains concentrated in Aichi prefecture around Toyota City and Nagoya, where Denso and Yazaki maintain integrated copper drawing-to-assembly operations.
Mexico
Japanese and German OEM assembly operations are concentrating in Guanajuato and Baja California as manufacturers relocate capacity from Asian supply bases to serve North American demand. NHTSA FMVSS electrical safety certification requirements extend OEM approval cycles beyond 18 months for suppliers seeking US market access. The Bajío automotive corridor spanning Guanajuato, Querétaro, and Aguascalientes hosts expanding tier-one harness assembly plants supplying Honda, Mazda, and Volkswagen transplant factories.
United States
Electric vehicle pure-plays including Rivian and Lucid Motors are unbundling after-sales harness inventory liability onto tier-one partners while compressing procurement cycles. NHTSA crashworthiness standards and FMVSS electrical safety rules elevate barrier costs for cross-regional supplier qualification. Manufacturing concentrates in California and Michigan, where Tesla, Rivian, and Lucid anchor engineering-intensive prototype-to-production transitions with direct OEM-supplier relationships displacing traditional distributor channels.
Wire Harness Market Competitive Environment
Capability concentration sits with specialized high-voltage termination specialists in Germany and Japan; scale advantage sits with integrated copper-to-assembly operators in China and Mexico. The supplier base stratifies into three tiers: captive Japanese keiretsu relationships serving transplant factories, European vertically integrated specialists controlling material qualification timelines, and emerging Chinese joint ventures capturing domestic NEV platform share. Dominant competitive moves include backward integration into copper drawing operations to hedge LME price volatility, and strategic partnerships with battery cell manufacturers to secure high-voltage assembly allocation.
Among European integrated specialists, LEONI represents the vertically integrated archetype spanning copper drawing through final harness assembly. Yazaki Corporation and Sumitomo Electric occupy positions within the Japanese keiretsu tier, anchoring volume relationships with Toyota, Honda, and Nissan transplant operations. These three exemplify how geographic origin and corporate structure shape competitive positioning: LEONI's GmbH heritage reflects German engineering-intensive qualification protocols, while Yazaki and Sumitomo's corporate forms signal captive customer access through long-term OEM supply agreements.
| Leading Market Players |
|---|
| LEONI |
| Draxlmaier Group |
| Yazaki Corporation |
| Fujikura |
| Lear Corporation |
| Sumitomo Electric |
| Furukawa Electric |
| Molex |
| Aptiv |
| Others |
Value Chain & Pricing Dynamics
The Port of Lázaro Cárdenas freight corridor links Asian copper concentrate arrivals to Guanajuato assembly plants, its container cost dynamics amplifying supplier concentration effects while forcing three-tier price stratification across OEM, tier-one, and aftermarket channels.
Pricing Analysis
Long-term offtake contracts dominate high-voltage automotive harness procurement, insulating qualified suppliers from LME copper volatility while spot relationships expose unqualified competitors to margin compression. Price differentiation rests on ECE R100 certification tier and GB/T compliance status, with REACH-compliant TPE formulations commanding premiums over legacy PVC assemblies. Cost compression in standard-grade industrial harnesses is intensifying because polyurethane-jacketed alternatives from Southeast Asian suppliers erode regional margin buffers. Aftermarket distributors exhibit highest price sensitivity due to reverse-engineering competition, whereas OEM direct procurement prioritizes qualification speed over unit cost.
Supply Chain Analysis
Tariff exposure between China and North America dominates supply chain risk calculus, compelling Japanese OEMs to relocate assembly capacity to Baja California and Guanajuato. Raw material flows draw from Chilean copper cathode, German specialty TPE compounding, and Japanese high-voltage connector manufacturing. Single-source vulnerability concentrates in qualified termination specialists for 300+ amp battery connections, currently anchored in Aichi prefecture and Bavaria. Distribution runs through captive tier-one relationships with LEONI and Yazaki Corporation, bypassing traditional distributor networks for prototype-to-production transitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat: ECE R100 and GB/T qualification timelines exceeding eighteen months create switching costs that lock OEMs into existing supplier relationships despite periodic price pressure.
For Market Incumbents: Entrench defensive positioning by deepening backward integration into oxygen-free copper drawing operations to hedge LME volatility, while accelerating bio-based TPE compounding partnerships ahead of EU Green Deal reporting deadlines. Optical backbone harness capability represents the critical R&D lever against copper-intensive virtualization threats from fiber optic convergence. For New Entrants and Emerging Players: India's Tamil Nadu and Gujarat automotive corridors under PLI scheme incentives represent the most penetrable entry point, with greenfield high-voltage assembly plants serving domestic NEV joint ventures. Fiber optic convergence in zonal E/E architectures offers a technology-jump entry angle, bypassing legacy copper qualification barriers through polymer-clad silica specialization. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists controlling material qualification timelines over pure-play assembly operators. Long-term viability hinges on Scope 3 copper provenance data capture for EU Green Deal compliance. The signal to watch is zonal architecture adoption timelines, as domain consolidation velocity determines whether aggregate harness counts compress faster than per-vehicle copper intensity expands.| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Termination Specialist Training | METI-supported programs in Aichi prefecture address technician scarcity constraining 300+ amp battery connection expansion. |
| Bio-Based TPE Compounding Partnership | REACH-compliant material substitutions secure preferred supplier status with Stellantis and Volkswagen Group ahead of reporting deadlines. |
| Optical Backbone Harness Qualification | Mercedes-Benz and BMW Group zonal architecture adoption creates first-mover advantage in polymer-clad silica fiber assemblies. |
| Copper Provenance Data Capture | Scope 3 tracking systems satisfy EU Green Deal embodied carbon requirements for European OEM procurement eligibility. |
| Mexico Nearshoring Capacity Expansion | Guanajuato and Baja California assembly plants capture volume from Japanese and German OEM transplant factory relocations. |
Study Parameters
Desk research of customs trade databases, vehicle production registries, and regulatory filing repositories preceded structured interviews with OEM platform engineers, tier-one supplier procurement leads, high-voltage termination specialists, and aftermarket distribution channel managers. Primary fieldwork combined with secondary validation from SEC filings, IHS Markit registration data, and ECHA substance restriction evaluations. Bottom-up segment sizing and top-down macro constraint triangulation were applied throughout.
Assumptions around copper price band stability, zonal E/E architecture adoption velocity, and GB/T standard enforcement consistency were held fixed across the projection horizon, while battery platform proliferation rates and nearshoring relocation timelines were stress-tested across scenarios. Segmentation modeling incorporated vehicle propulsion architecture, harness voltage tier, material composition, and regional production cluster dimensions. CAGRs were derived from installed base evolution and content-per-vehicle expansion trajectories, with fiber optic penetration and high-voltage copper intensity serving as primary demand drivers.
Stress conditions across LME copper volatility, REACH substance restriction acceleration, and NHTSA FMVSS certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OEM electrification commitments and joint venture localization policies. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Stepper Motors Market
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Personal Mobility Devices Market
Automotive Electrical & Electronics
Automotive Alternator Market
Automotive Electrical & Electronics
Automotive Battery Market
Automotive Electrical & Electronics
On-Board Charger Market
Automotive Electrical & Electronics
Global Automotive Electrical Distribution System Market
Automotive Electrical & Electronics
Ambulance Power Inverter Market
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market
Automotive Electrical & Electronics
Automotive Starting System Market
Automotive Electrical & Electronics
India Automotive LED Lighting Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
Automotive Charge Port Actuator Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market
Automotive Electrical & Electronics
Electrical Steering Column Lock Market