
 Europe Automotive EPS Market | 2026-2036
Europe Automotive EPS Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive EPS Market Foresight
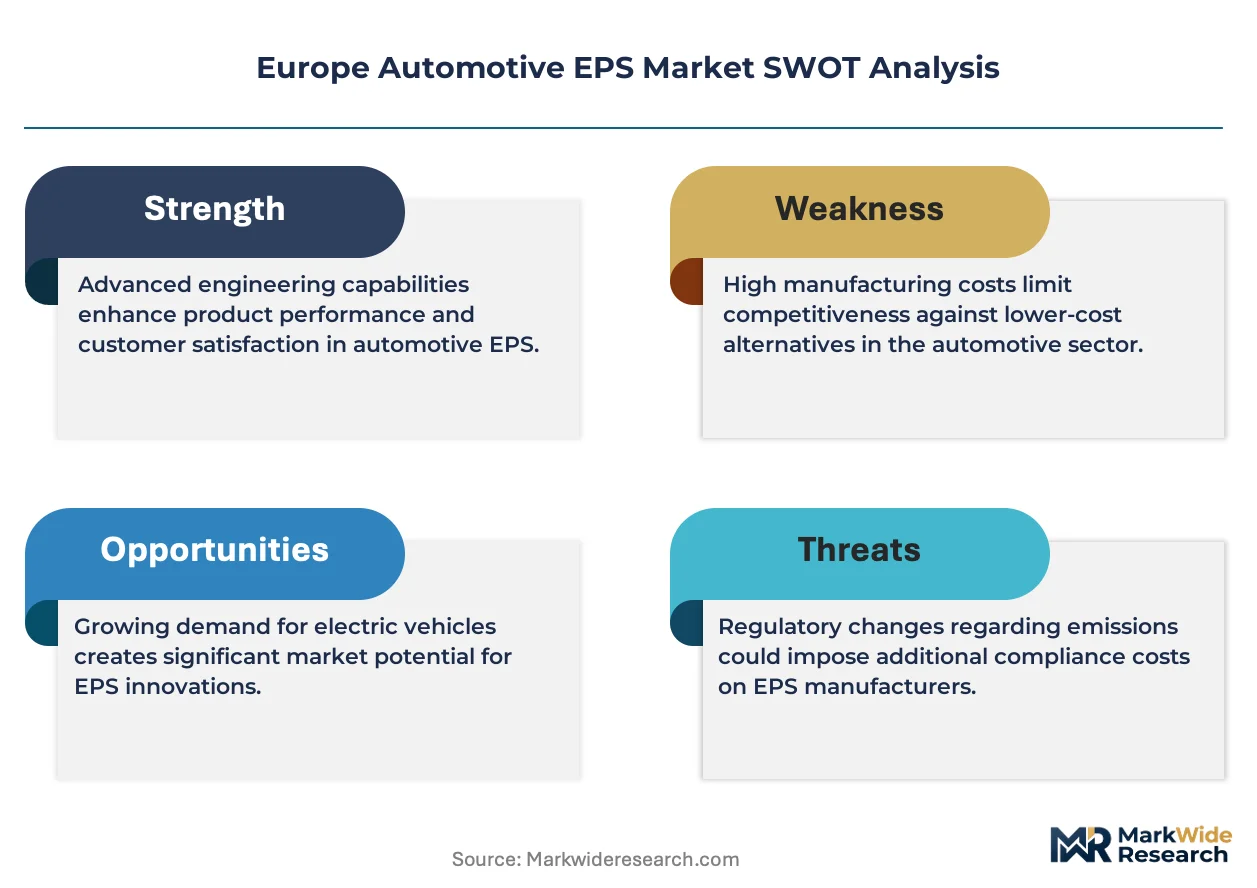
A widening capital-intensity gap between integrated Tier 1 suppliers and component specialists is reorganizing competitive dynamics in European automotive steering. Robert Bosch GmbH leverages its in-house semiconductor and sensor capabilities to control full EPS system architecture. ZF Friedrichshafen AG anchors its position through manufacturing scale across German and Czech production hubs. JTEKT Corporation competes via specialized torque-sensor technology leadership for premium passenger vehicle applications.
Electric power steering replaces hydraulic assist with an electric motor mounted on the steering column or rack, reducing fuel consumption by eliminating engine-driven hydraulic pumps and enabling variable assist algorithms. Rack-assist configurations dominate European OEM supply contracts due to superior road-feel calibration for heavier vehicle platforms. Column-assist systems occupy the fastest-growing segment as compact electric vehicles from French and Italian manufacturers prioritize packaging efficiency. Drive-by-wire technology, though nascent, concentrates margin pools in validation and functional-safety certification services.
The EU Green Deal and F-Gas Regulation shape product roadmaps by penalizing hydraulic fluid leakage and rewarding electrified subsystems. ECE R79 and the EU AI Act impose steer-by-wire validation protocols and algorithmic transparency requirements that extend development timelines. Stakeholders must monitor how the CSRD's supply-chain disclosure rules alter sourcing economics for rare-earth motor materials.
Market Dynamics
The EU Green Deal's fleet emissions mandates are compressing hydraulic steering replacement timelines across European OEM supply chains. Tier 1 suppliers must revalidate entire system architectures as electrification thresholds tighten, creating a structural acceleration in rack-assist and column-assist EPS procurement cycles.
Growth Catalysts
- F-Gas Regulation penalties:Hydraulic fluid leakage risks now carry direct cost consequences under EU environmental enforcement, redirecting R&D budgets toward sealed electric motor architectures.
- German automotive corridor concentration:OEM integration hubs in Stuttgart, Munich, and Wolfsburg generate clustered demand for validated EPS platforms with shortened qualification windows.
- Rack-assist road-feel calibration:Heavier European vehicle platforms require precise torque mapping that electric rack systems deliver more reliably than column-mounted alternatives.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium and dysprosium sourcing dependencies on limited processor geographies create input cost volatility for permanent-motor EPS designs.
- ECE R79 validation timelines:Steer-by-wire functional-safety protocols extend development cycles by 18-24 months, freezing capital in pre-revenue certification phases.
- Hydraulic aftermarket residual:Legacy commercial vehicle fleets in Eastern Europe sustain parallel service infrastructure that delays full EPS penetration in cost-sensitive segments.
Strategic Opportunities
- Italian compact EV packaging:Column-assist systems from Turin and Milan design centers address space-constrained urban electric vehicles with integrated motor-controller units.
- CSRD supply-chain disclosure:Early compliance with EU sustainability reporting rules positions Tier 1 suppliers for preferred sourcing status as OEM procurement teams requalify vendors.
- Drive-by-wire validation services:Algorithmic transparency requirements under the EU AI Act create margin pools for specialized functional-safety engineering consultancies.
Industry Challenges
- Embedded software talent scarcity:Functional-safety engineering competence for ISO 26262 ASIL-D compliance concentrates among a limited pool of specialists in Germany and France.
- Legacy platform integration friction:CAN bus architecture mismatches between new EPS controllers and existing vehicle networks demand costly bridge hardware development.
- Dual-source qualification delays:OEM requirements for redundant supplier validation compress margin recovery timelines across multiple simultaneous homologation programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive EPS Market |
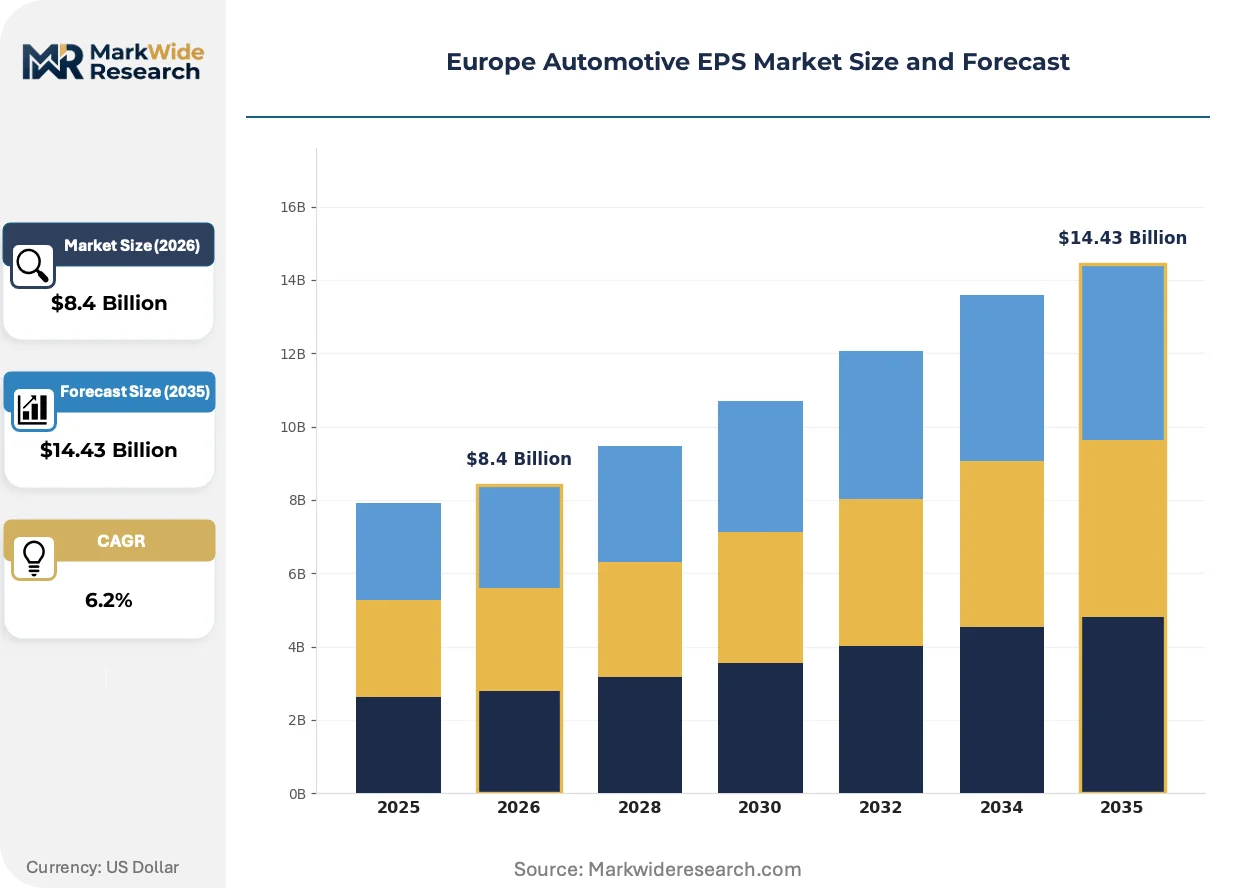
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column Assist, Rack Assist, Electric Power Steering, Electro-Hydraulic Steering End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles Installation: OEM, Aftermarket, Retrofit, Direct Install Technology: Integrated Steering, Drive-By-Wire, Active Steering, Torque Vectoring |
| Companies Covered | Robert Bosch GmbH, ZF Friedrichshafen AG, JTEKT Corporation, NSK Ltd., Nexteer Automotive Group Ltd, Thyssenkrupp Presta AG, Hyundai Mobis, Denso Corporation, Hitachi Astemo, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive EPS Market Shifts & Advancements
Algorithmic steering control and motor packaging miniaturization are converging to redefine system architecture boundaries. Tier 1 engineering teams now optimize across thermal management, electromagnetic compatibility, and functional-safety domains simultaneously.
Brushless DC motor designs with integrated torque sensing are supplanting discrete sensor configurations in next-generation EPS platforms. French and Italian OEMs are adopting these consolidated architectures for compact electric vehicle launches. The consolidation is compressing component supplier tiers and reallocating margin toward semiconductor-integrated system houses.
EU AI Act algorithmic transparency mandates are forcing disclosure of steering-assist decision logic to regulators. This regulatory friction extends validation timelines for steer-by-wire programs. German OEMs are responding by segregating safety-critical code bases from convenience features to isolate certification scope.
Fleet procurement teams are unbundling EPS hardware from software calibration services in contract negotiations. Direct sourcing of base rack mechanisms from Czech and Polish manufacturing hubs is displacing fully integrated system purchases. This pattern is most visible in commercial vehicle segments where internal engineering teams retain calibration competence.
Europe Automotive EPS Market Segmentation
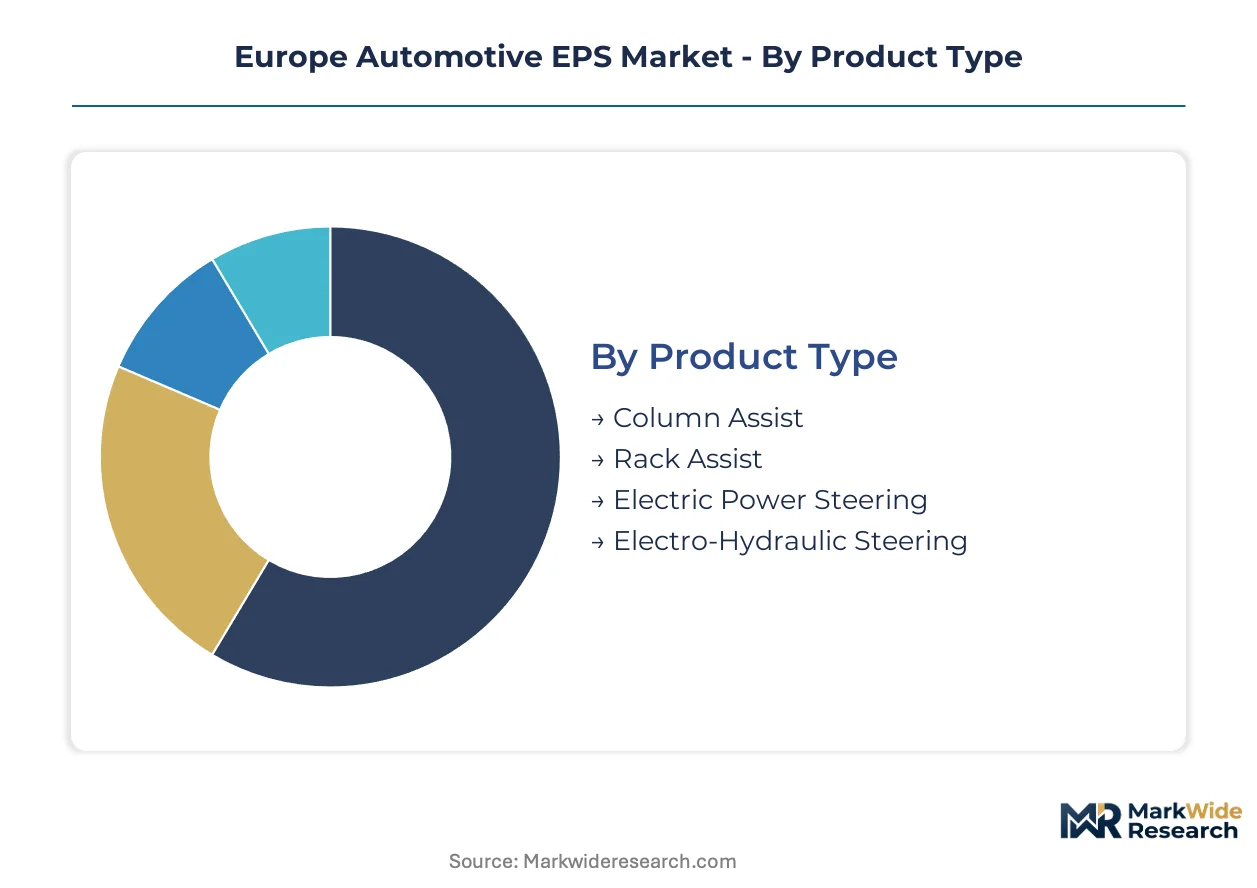
EPS procurement patterns diverge sharply across European OEM architectures, with regulatory pressure on fleet emissions and functional-safety certification reshaping how suppliers configure system offerings. Segmentation clarity determines qualification pathways and margin capture for Tier 1 vendors competing in German, French, and Italian supply corridors.
Product Type:
ECE R79 validation protocols and F-Gas Regulation penalties create tiered compliance burdens that segment product strategies across European OEM supply chains.
- Rack Assist:Electric motor mounted directly on the steering rack delivers precise torque mapping for heavier vehicle platforms. German OEMs in Stuttgart and Munich specify rack-assist configurations for mid-size and premium passenger vehicles where road-feel calibration demands exceed column-mount capabilities.
- Column Assist:Integrated motor-controller units mounted on the steering column optimize packaging efficiency for space-constrained architectures. French and Italian manufacturers prioritize column-assist systems for compact urban electric vehicles where hood-space minimization enables battery-pack expansion.
- Electric Power Steering:Base electric architectures without hydraulic backup dominate new vehicle platforms across EU Green Deal compliance timelines.
- Electro-Hydraulic Steering:Hybrid systems retain hydraulic assist with electric pump control, sustaining residual demand in Eastern European commercial vehicle segments where full electrification capital costs encounter resistance.
Established volume favors rack-assist configurations; emerging adoption favors column-assist systems for compact EV packaging.
End User:
Customer-type economics concentrate engineering resources toward segments with bundled software calibration and fastest homologation cycles.
- Electric Vehicles:Purpose-built EPS architectures with integrated torque sensing and brushless DC motor designs address packaging and efficiency mandates unique to battery-electric platforms. Italian and French OEMs specify these systems for dedicated EV platforms where EU Green Deal fleet targets drive procurement priority.
- Passenger Vehicles:Volume production contracts across German manufacturing corridors demand validated platforms with shortened qualification windows and dual-source redundancy.
- Commercial Vehicles:Fleet procurement teams unbundle hardware from software services, sourcing base rack mechanisms from Czech and Polish hubs while retaining internal calibration competence.
- Luxury Vehicles:Premium segment buyers fund development of steer-by-wire and active steering technologies where functional-safety certification costs amortize across lower-volume, higher-margin programs.
Passenger vehicles anchor current procurement volume; electric vehicles command the steepest expansion trajectory across OEM platform roadmaps.
Installation:
Channel configuration determines margin allocation between hardware manufacturing and engineering services across European supply networks.
- OEM:Factory-integrated systems with bundled calibration and warranty obligations capture the majority of European EPS value, with German OEMs demanding simultaneous dual-source qualification that compresses supplier margin recovery timelines.
- Aftermarket:Service-channel demand sustains parallel infrastructure for legacy hydraulic replacement and warranty repair, concentrated in Eastern European commercial vehicle fleets with extended asset lifecycles.
- Retrofit:Electrification conversion programs for legacy platforms encounter ECE R79 revalidation barriers that limit addressable scope to non-steer-by-wire architectures.
- Direct Install:Specialized integration for motorsport and limited-production applications bypasses standard OEM qualification pathways.
OEM integration commands dominant value share; aftermarket channels retain residual importance in cost-sensitive fleet segments.
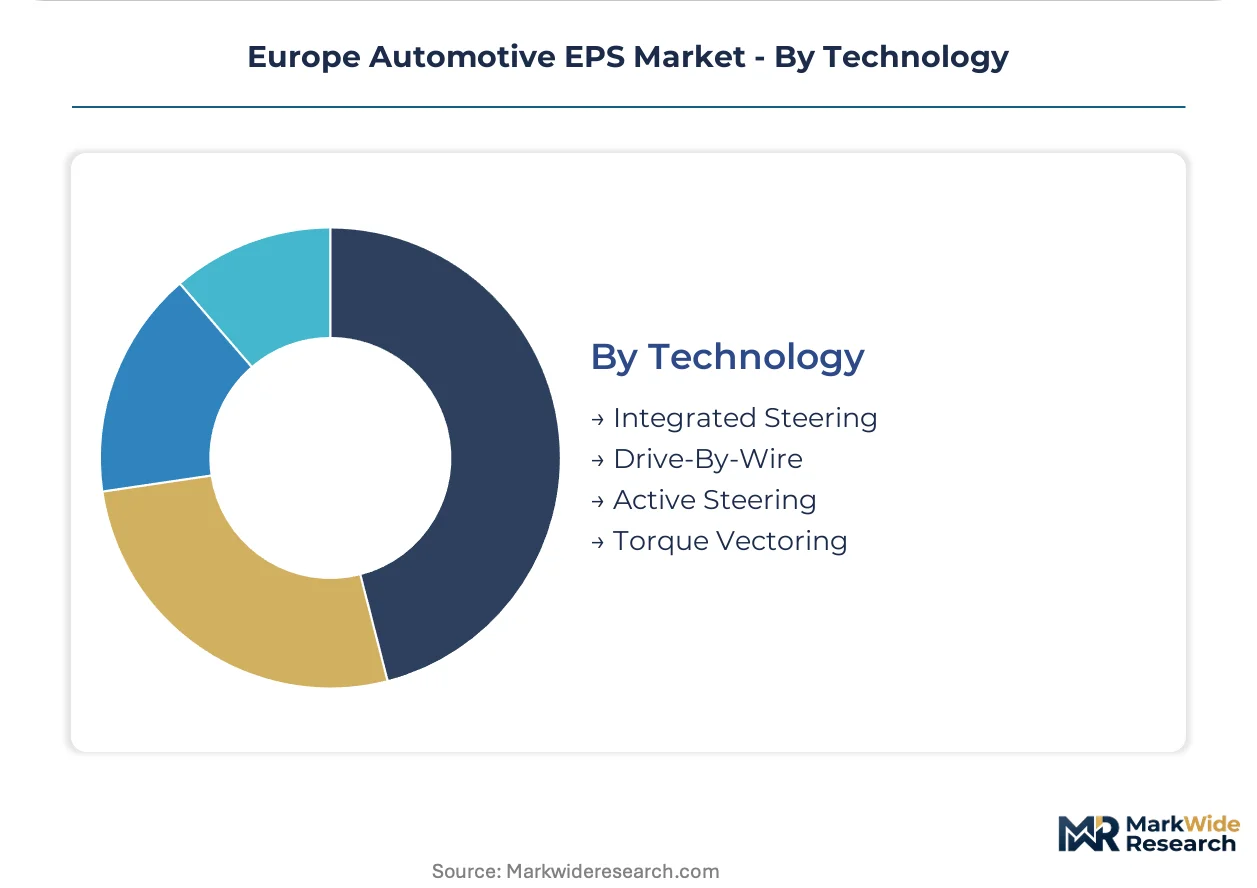
Technology:
Maturity gradients separate revenue-generating platforms from pre-commercial architectures awaiting regulatory clearance.
- Integrated Steering:Consolidated brushless DC motor designs with embedded torque sensing compress component tiers and reallocate margin toward semiconductor-integrated system houses. French OEMs adopt these architectures for next-generation compact EV launches.
- Drive-By-Wire:Steer-by-wire systems eliminate mechanical steering columns, concentrating margin pools in validation and functional-safety certification services. EU AI Act algorithmic transparency mandates extend German OEM development cycles by isolating safety-critical code bases from convenience features.
- Active Steering:Variable-ratio systems enhance maneuverability for urban and highway driving modes through software-controlled actuator response.
- Torque Vectoring:Differential braking integration with steering control enhances vehicle dynamics for premium performance applications.
Integrated steering architectures dominate near-term revenue; drive-by-wire systems represent the longest development-cycle opportunity contingent on regulatory clearance timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across European automotive corridors. German OEMs absorb premium rack-assist costs for road-feel calibration, while Eastern European fleet buyers delay full EPS conversion due to residual hydraulic infrastructure economics.
Germany
Stuttgart and Munich manufacturing hubs generate clustered demand for validated EPS platforms with shortened qualification windows. The EU Green Deal's fleet emissions mandates compress hydraulic replacement timelines across OEM supply chains. Wolfsburg integration centers accelerate dual-source qualification requirements that compress supplier margin recovery.
France
Paris-based OEM procurement teams prioritize column-assist systems for compact urban electric vehicles where hood-space minimization enables battery-pack expansion. The EU AI Act imposes algorithmic transparency requirements that extend steer-by-wire validation cycles. Lyon design centers consolidate brushless DC motor architectures with embedded torque sensing.
Italy
Turin and Milan engineering teams specify space-constrained EPS configurations for dedicated EV platforms. F-Gas Regulation penalties redirect R&D budgets toward sealed electric motor architectures away from hydraulic fluid risks. Emilia-Romagna component suppliers concentrate on integrated motor-controller units.
United Kingdom
Midlands manufacturing corridors sustain demand for rack-assist road-feel calibration in premium passenger segments. ECE R79 validation protocols extend development cycles for steer-by-wire functional-safety certification. London procurement offices unbundle hardware from software calibration services in commercial vehicle contracts.
Poland
Czech and Polish manufacturing hubs attract direct sourcing of base rack mechanisms from fleet procurement teams retaining internal calibration competence. The CSRD's supply-chain disclosure rules alter sourcing economics for rare-earth motor materials. Warsaw logistics corridors serve Eastern European aftermarket residual demand for legacy hydraulic replacement.
Europe Automotive EPS Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European EPS supply base. The market structure consolidates around integrated Tier 1 suppliers with in-house semiconductor capabilities alongside specialized component houses with torque-sensor expertise. Three archetypes dominate: full-system integrators controlling architecture definition, component specialists capturing margin on discrete sensing technologies, and Asian manufacturers competing on motor manufacturing scale. Competitive moves center on backward integration into rare-earth magnet supply and functional-safety certification service expansion.
Among German-based integrated suppliers, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify the full-system archetype with control over complete EPS architecture. JTEKT Corporation represents the specialized component tier with positioning around torque-sensor technology leadership. These three anchors illustrate how geographic concentration in Germany's automotive corridor intersects with differentiated capability profiles across integrated and specialist business models.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| JTEKT Corporation |
| NSK Ltd. |
| Nexteer Automotive Group Ltd |
| Thyssenkrupp Presta AG |
| Hyundai Mobis |
| Denso Corporation |
| Hitachi Astemo |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between German OEMs and Tier 1 suppliers lock in rare-earth magnet supply access while capping price volatility for permanent-motor EPS designs. These arrangements bundle hardware procurement with software calibration services, compressing margin transparency across the EU Green Deal compliance timeline.
Pricing Analysis
After-sales revenue from extended warranty and software update contracts drives lifetime value capture for integrated EPS suppliers. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume scale, with ECE R79 ASIL-D compliance commanding substantial premiums. Price erosion runs through base rack mechanisms as Czech and Polish manufacturing hubs attract direct fleet procurement. Commercial vehicle buyers exhibit highest price sensitivity due to unbundled hardware sourcing, while luxury OEMs absorb premium costs for steer-by-wire validation services.
Supply Chain Analysis
Inventory buffers for neodymium and dysprosium magnets stretch to 16-20 weeks as processors in China and Vietnam dominate rare-earth refining. German and Czech manufacturing hubs draw from these concentrated sources, with motor winding and controller assembly anchored in Emilia-Romagna and Stuttgart corridors. Single-source vulnerability in magnet supply creates exposure to export restriction shocks under EU-China trade friction. Distribution runs through just-in-time OEM integration centers rather than aftermarket stocking points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Automotive EPS Market represents high-growth disruption as steer-by-wire architectures displace mechanical steering columns under EU AI Act algorithmic transparency mandates. This regulatory inflection compresses development timelines while concentrating margin pools in functional-safety certification services.
For Market Incumbents: Fortify captive supply of rare-earth magnets through backward integration into processor partnerships or long-term offtake with Vietnamese refiners. Expand functional-safety engineering capacity in Stuttgart and Munich to capture steer-by-wire validation demand before ECE R79 timelines extend further. Defend against Asian motor manufacturers by embedding torque-sensor IP into consolidated brushless DC architectures that compress component tiers. For New Entrants and Emerging Players: ECE R79 certification fast-tracks for column-assist systems offer entry into French and Italian compact EV supply chains where packaging efficiency commands procurement priority. Target Turin and Milan design centers with integrated motor-controller units that address hood-space constraints. Pursue white-label calibration services for commercial vehicle fleets unbundling hardware from software in Czech and Polish sourcing hubs. For Investors and Strategic Acquirers: Capital is best deployed toward semiconductor-integrated system houses with in-house torque-sensing capabilities and ISO 26262 ASIL-D certification competence. Long-term viability hinges on exposure to dedicated EV platform volumes rather than legacy passenger vehicle retrofit opportunities. Watch for EU AI Act enforcement intensity as the signal indicating steer-by-wire regulatory clearance acceleration or delay.| Strategic Initiative | Industry Significance |
|---|---|
| Rare-Earth Magnet Supply Agreement | Secures neodymium and dysprosium access for permanent-motor EPS designs against export restriction risk. |
| Functional-Safety Certification Expansion | Builds ASIL-D engineering capacity in Stuttgart to capture steer-by-wire validation margin pools. |
| Column-Assist Platform Standardization | Enables Turin and Milan OEMs to minimize hood-space for battery-pack expansion in compact EVs. |
| Software-Defined Steering Investment | Isolates safety-critical code bases from convenience features under EU AI Act transparency mandates. |
| Czech Manufacturing Footprint Expansion | Positions suppliers for direct fleet procurement of base rack mechanisms with retained calibration competence. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and functional-safety certification specialists; and secondary validation against vehicle production databases, IHS Markit registration data, EU regulatory filings, and customs trade records. Bottom-up segmentation modeling triangulated with top-down market sizing across the analysis window.
Across the projection horizon, forecasts integrated vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from production volume trajectories and technology penetration curves, with specific inputs including EU Green Deal fleet emission mandate compliance schedules and F-Gas Regulation enforcement intensity.
Decision-makers should treat outputs as directional under base assumptions of sustained EU electrification policy and stable rare-earth supply access; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Automotive Emission Sensors Market
Automotive Electrical & Electronics
Automotive Electronic Logging Device (ELD/E-Log) Market
Automotive Electrical & Electronics
Global Automotive Starter and Alternator Market
Automotive Electrical & Electronics
X-By-Wire Systems Market
Automotive Electrical & Electronics
On-Board Fuse Box Market
Automotive Electrical & Electronics
South Korea Automotive Camera Market
Automotive Electrical & Electronics
India Automotive LED Lighting Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
Automotive E-Compressor Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Japan X by Wire Systems Market
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Electric Vehicle High-Voltage Cables Market
Automotive Electrical & Electronics
Automotive Immersion Cooling Dielectric Fluid Market
Automotive Electrical & Electronics
Europe Automotive Display Market