
 Europe Automotive LED Lighting Market | 2026-2036
Europe Automotive LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive LED Lighting Market Insights
A multi-source-to-dual-source procurement pattern is realigning how European vehicle assemblers contract LED module suppliers. ZKW Group leverages its Austrian engineering base to sustain matrix LED development programs for German premium OEMs. HELLA GmbH & Co. KGaA anchors aftermarket distribution networks across Central Europe while competing in adaptive front-lighting system tenders. Valeo SE differentiates through vertically controlled optical design and thermal management capabilities.
Europe Automotive LED Lighting encompasses solid-state illumination systems for exterior vehicle applications, utilizing semiconductor diodes with typical luminous efficacy exceeding 130 lumens per watt and operating temperatures from minus forty to one hundred twenty degrees Celsius. These systems replace halogen and xenon architectures to reduce energy draw on vehicle electrical systems and enable programmable beam patterns. Headlamps and adaptive LED technologies command the dominant share of value pools, with matrix LED systems capturing premium positioning due to their pixel-level beam control and compliance with stringent EU pedestrian safety standards. Standard LED applications in taillights occupy mature volume positions, while OLED segments in signature lighting applications represent emerging design differentiation territory.
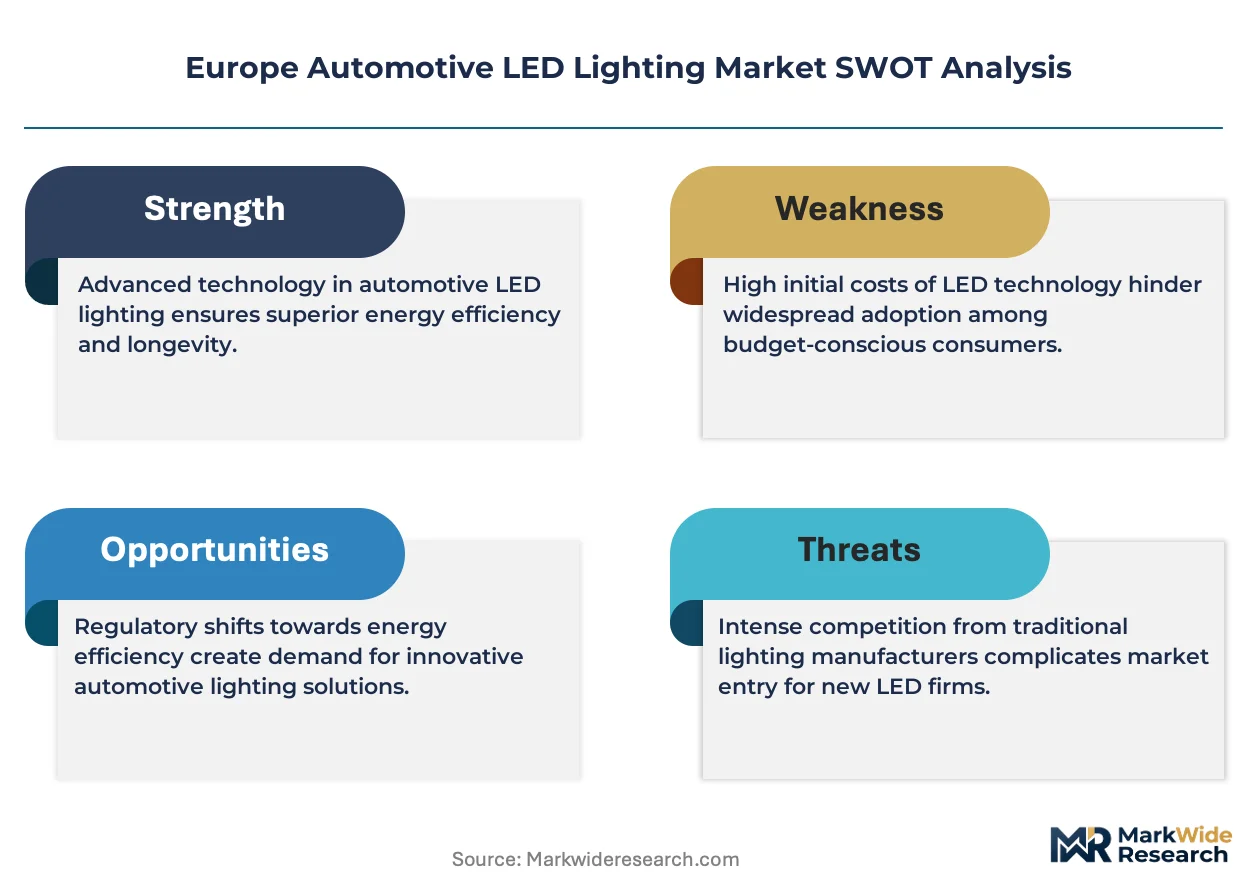
ECE Regulation 48 governs vehicle lighting installation and performance across EU member states, with EMA and national type-approval authorities enforcing compliance. The EU Green Deal's embedded carbon requirements and REACH substance restrictions are forcing material substitutions in phosphor coatings and substrate metallization. Stakeholders must monitor how the EU AI Act's safety-critical system classifications interact with adaptive beam algorithms and sensor fusion architectures.
Market Dynamics
The EU Green Deal's embedded carbon mandates are compressing supplier margins while forcing rapid material substitutions in LED phosphor coatings and substrate metallization across European automotive lighting value chains.
Growth Catalysts
- ECE Regulation 48:Harmonized type-approval standards across EU member states reduce certification duplication costs for LED headlamp suppliers serving multiple national markets.
- Matrix LED pixel control:German premium OEMs are expanding adaptive beam architectures to comply with stringent EU pedestrian safety standards while differentiating vehicle positioning.
- Stuttgart-Munich corridor:Concentrated automotive engineering talent and tier-1 supplier presence accelerate prototype-to-production cycles for advanced lighting systems.
Market Restraints
- Gallium nitride substrate costs:Raw material price volatility for high-brightness LED chips constrains margin expansion for mid-tier module suppliers.
- Phosphor supply concentration:Rare-earth element processing dependencies in specific Asian supply nodes create input vulnerability for European phosphor-converted white LED production.
- REACH substance restrictions:Cadmium and lead exemptions in semiconductor packaging face tightening ECHA scrutiny, forcing costly material reformulations.
Strategic Opportunities
- Eastern European manufacturing:Slovakia and Czech Republic offer cost-competitive assembly locations with EU regulatory alignment for LED module production serving German OEMs.
- OLED signature lighting:Italian luxury design houses are pioneering exterior surface-illumination applications for brand differentiation in premium segments.
- EU AI Act safety-critical classifications:Adaptive beam algorithms with sensor fusion architectures create compliance-driven service revenue streams for lighting system integrators.
Industry Challenges
- Thermal management engineering:Scarce expertise in high-flux LED junction temperature control limits supplier capacity to support 150+ lumen-per-watt architectures.
- Homologation timeline compression:Accelerated vehicle platform cycles compress EMA type-approval windows, straining validation laboratory capacity across the continent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive LED Lighting Market |
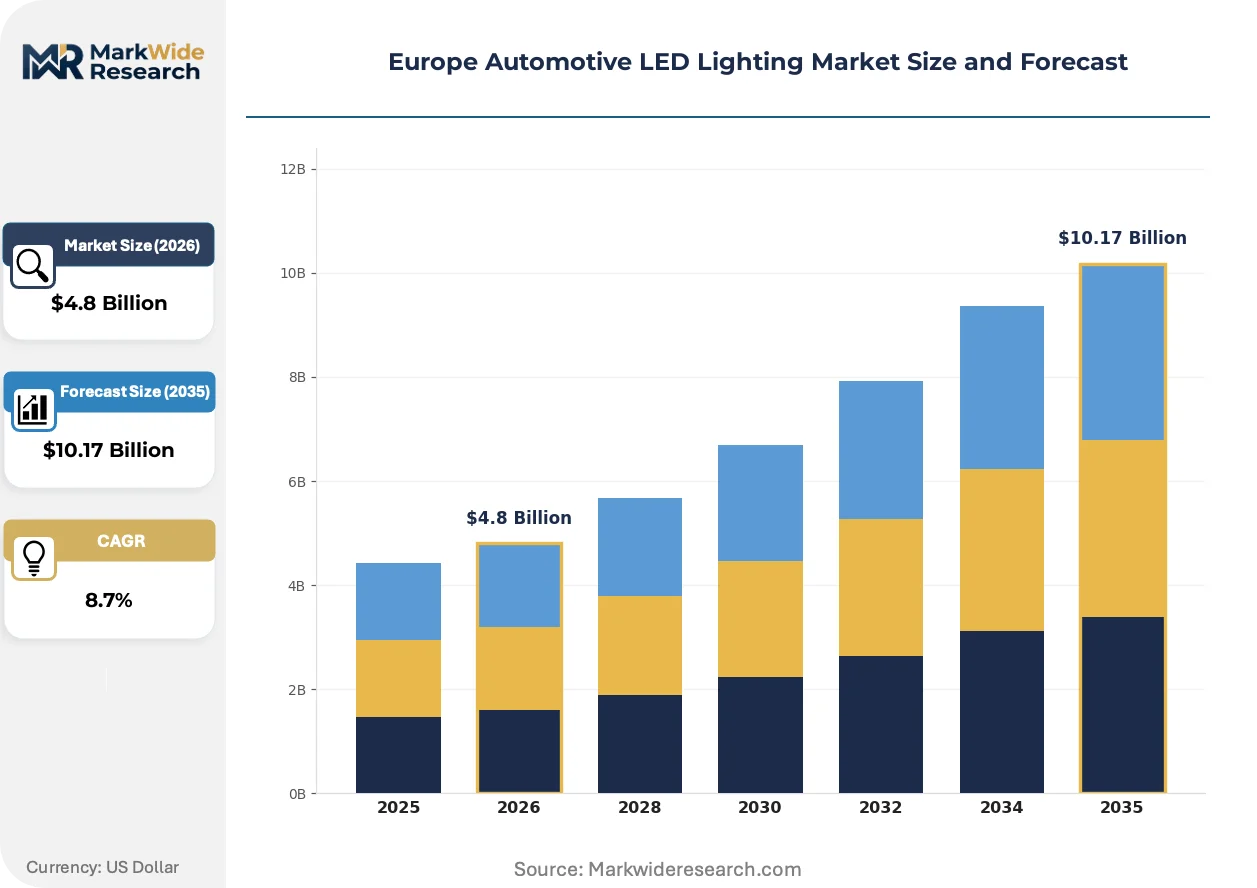
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlamps, Taillights, Fog Lights, Turn Signal Lights Technology: Matrix LED, OLED, Standard LED, Adaptive LED End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Cars, Commercial Vehicles, Heavy-duty Trucks, Buses |
| Companies Covered | ZKW Group, ams-OSRAM AG, HELLA GmbH & Co. KGaA, Lumileds, Stanley Electric Co., Ltd., Valeo SE, Koito Manufacturing Co., Ltd., Nichia, Automotive Lighting (Marelli Holdings Co., Ltd.), Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive LED Lighting Market Trends and Innovations
Silicon-carbide thermal substrates and adaptive beam software architectures are converging to redefine performance benchmarks for European automotive lighting systems.
Micro-LED arrays are absorbing the functional role of mechanical shutter systems in adaptive driving beam applications. German premium OEMs are specifying these solid-state alternatives for next-generation matrix headlamp platforms. The technology is absorbing capital previously allocated to electromechanical beam-shaping components, compressing supplier tier structures.
REACH substance restrictions are forcing phosphor reformulations across European LED packaging facilities. ECHA's expanding candidate list of substances of very high concern now targets specific rare-earth dopants in conventional white-light conversion. French and Italian lighting suppliers are accelerating cerium-free phosphor development programs to maintain market access.
Dual-source contracting patterns are replacing single-source legacy agreements for LED module procurement. German vehicle assemblers are splitting matrix LED headlamp awards between Austrian engineering specialists and vertically integrated French suppliers. This behavior is most pronounced in Stuttgart and Munich headquarters, where procurement functions seek supply resilience alongside technical performance.
Europe Automotive LED Lighting Market Segmentation
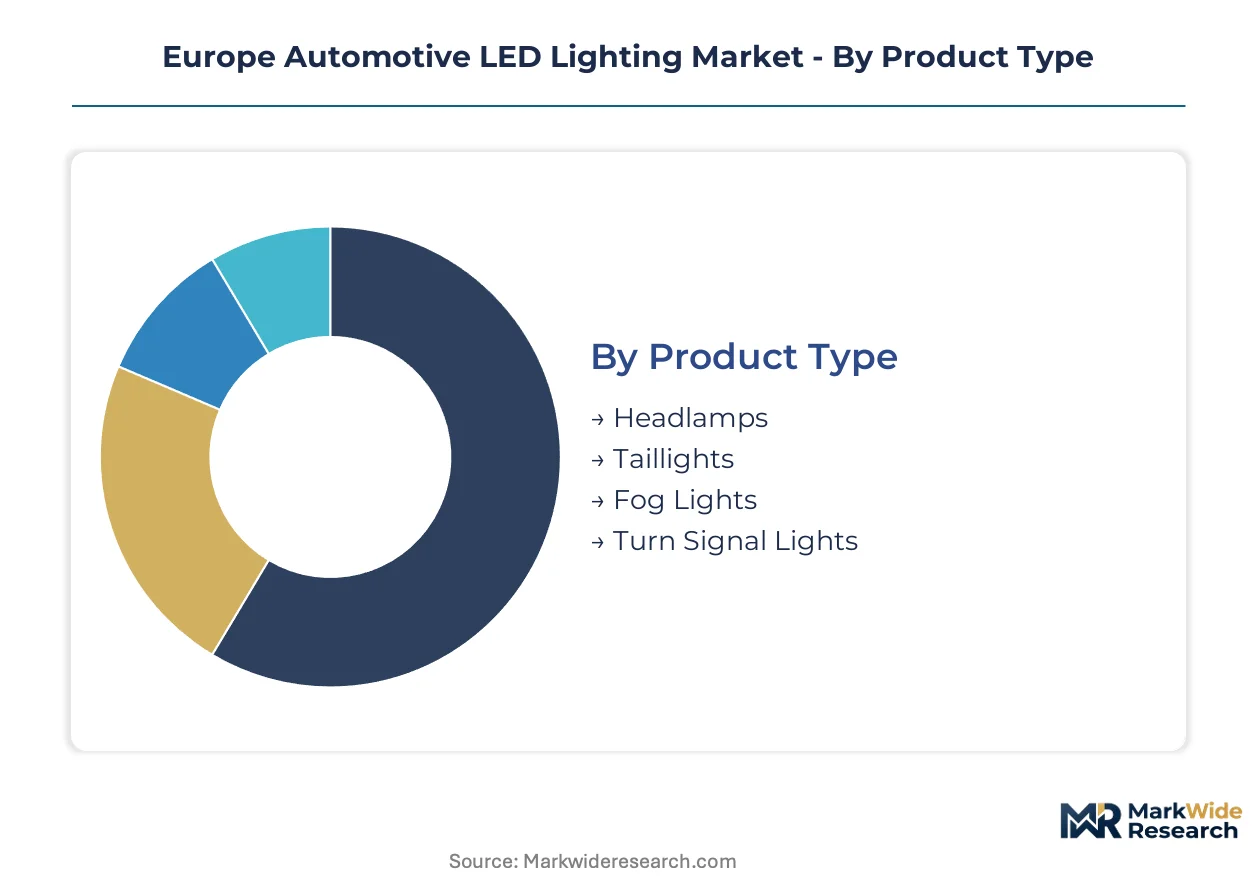
LED module suppliers in Europe configure production lines around distinct technical specifications and customer integration requirements. Segmentation reveals where engineering investment concentrates and which contract structures dominate procurement decisions across German, French, and Italian automotive manufacturing corridors.
Product Type:
Supply concentration for high-lumen LED chips clusters around headlamp and adaptive beam applications serving Stuttgart-Munich OEM headquarters.
- Headlamps:Matrix LED architectures with pixel-level beam control require GaN substrates and precision thermal management. German premium OEMs in Baden-Württemberg and Bavaria command the dominant share of engineering validation capacity for these systems.
- Taillights:Standard LED configurations with red phosphor conversion occupy mature volume positions. French and Czech assembly plants source these modules through established tier-1 contracts with shorter qualification cycles than headlamp programs.
- Fog Lights:Compact LED modules with wide beam dispersion serve secondary lighting positions in passenger car platforms.
- Turn Signal Lights:Amber LED sequences with sequential activation capabilities support EU pedestrian visibility mandates.
Headlamps absorb the bulk of installed capacity; taillights are expanding most quickly through platform standardization across mid-volume vehicle lines.
Technology:
Cost tier separation between premium matrix systems and commodity LED packages determines supplier margin structures across European lighting value chains.
- Matrix LED:Micro-LED arrays with software-defined beam patterns replace mechanical shutters in adaptive driving beam applications. Austrian engineering specialists and French vertically integrated suppliers split procurement awards from German premium OEMs seeking dual-source resilience.
- Standard LED:Phosphor-converted white LED packages with 130+ lumen-per-watt efficacy serve high-volume taillight and interior applications. REACH substance restrictions on rare-earth dopants are forcing cerium-free phosphor reformulations at French and Italian packaging facilities.
- OLED:Thin-film organic electroluminescent panels enable surface-illumination exterior designs. Italian luxury design houses in Turin and Modena pioneer signature lighting applications for brand differentiation.
- Adaptive LED:Sensor-fusion beam control algorithms classified under EU AI Act safety-critical systems create compliance-driven service revenue for lighting integrators.
Matrix LED captures the steepest expansion trajectory; standard LED maintains volume dominance across mass-market platforms.
End User:
Customer type dictates contract duration, technical specification authority, and module integration depth across European automotive lighting procurement.
- OEMs:German premium vehicle manufacturers retain direct specification authority for matrix LED headlamp architectures. Engineering teams in Stuttgart, Munich, and Ingolstadt define pixel control algorithms and thermal substrate requirements.
- Tier-1 Suppliers:Lighting system integrators manage optical design, thermal management, and ECE Regulation 48 homologation for vehicle assemblers. ZKW Group leverages Austrian engineering bases; Valeo SE controls vertical optical design capabilities.
- Aftermarket Providers:HELLA GmbH & Co. KGaA anchors distribution networks across Central Europe for replacement LED modules and retrofit kits.
- Vehicle Assemblers:Contract manufacturers in Eastern Europe source pre-validated LED module assemblies for platform integration.
OEMs command specification authority for advanced systems; tier-1 suppliers are gaining share fastest through integrated module and software offerings.
Application:
Volume concentration in passenger car platforms contrasts with specialized thermal and durability requirements for commercial vehicle segments.
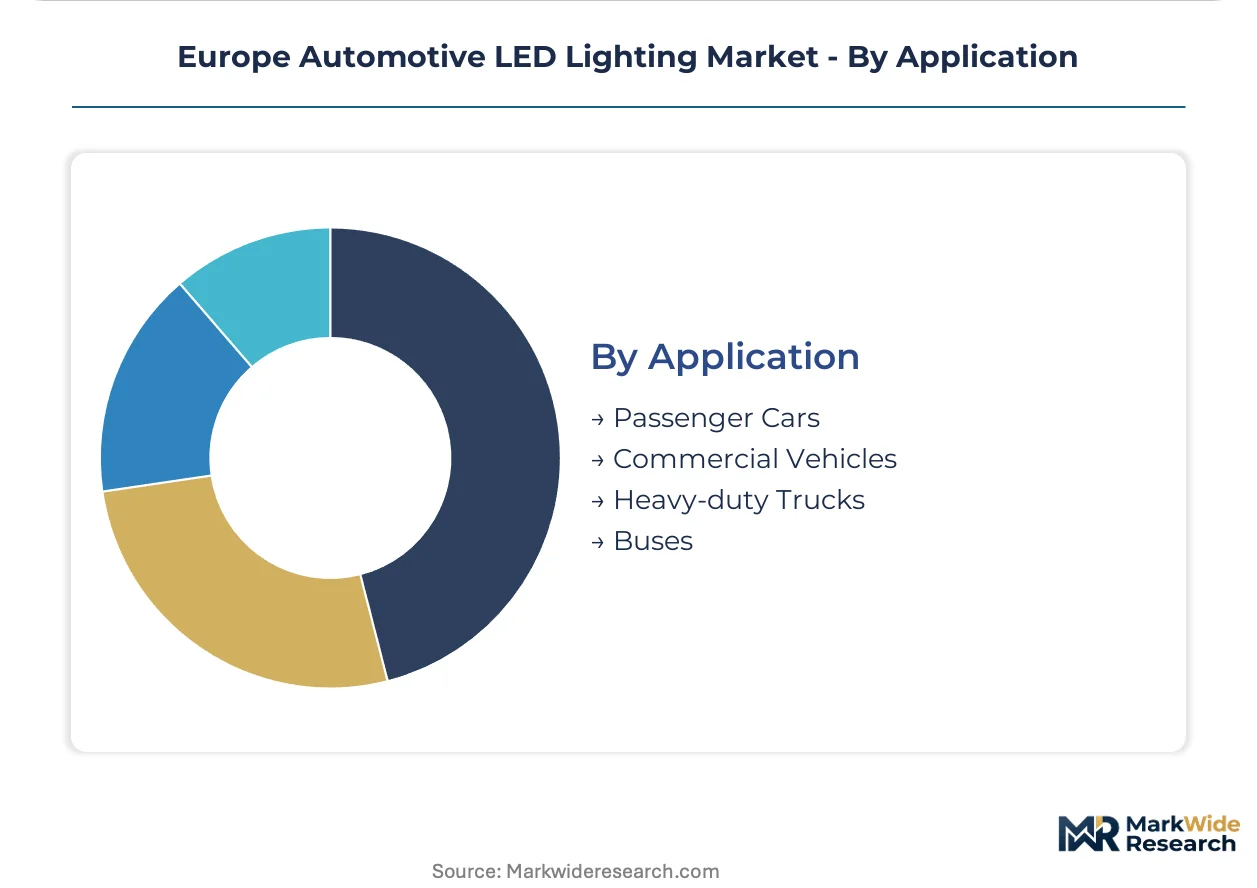
- Passenger Cars:Premium German and Italian marques drive matrix LED adoption for adaptive beam compliance with EU pedestrian safety standards. Stuttgart-Munich engineering corridors accelerate prototype-to-production cycles.
- Commercial Vehicles:Heavy-duty LED modules with extended operating temperature ranges serve logistics fleets. Slovakia and Czech Republic assembly locations offer cost-competitive production with EU regulatory alignment.
- Heavy-duty Trucks:High-reliability LED headlamp systems withstand vibration and thermal cycling across long-haul routes.
- Buses:Interior and exterior LED configurations prioritize energy efficiency for electric and hybrid powertrain compatibility.
Passenger cars absorb the bulk of installed capacity; commercial vehicles are expanding most quickly through fleet electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium nitride substrate processing and rare-earth phosphor refining concentrate in specific European industrial basins, anchoring LED module production to established automotive engineering corridors.
Germany
Baden-Württemberg and Bavaria house Stuttgart-Munich engineering clusters where premium OEMs specify matrix LED architectures. ECE Regulation 48 harmonization reduces certification costs for suppliers serving multiple EU markets. Ingolstadt and Munich headquarters accelerate prototype-to-production cycles for adaptive beam systems.
France
Vertically integrated lighting suppliers control optical design and thermal management capabilities for domestic vehicle assemblers. EU Green Deal embedded carbon mandates compress margins while forcing phosphor coating substitutions. Paris-region engineering centers validate cerium-free phosphor formulations for export compliance.
Italy
Turin and Modena design houses pioneer OLED signature lighting for luxury brand differentiation. REACH substance restrictions target rare-earth dopants in conventional white-light conversion. Piedmont-based suppliers accelerate surface-illumination development programs for premium exterior applications.
Austria
Engineering specialists leverage technical bases to sustain matrix LED development for German premium OEMs. Dual-source procurement patterns split awards between Austrian and French suppliers. Vienna-Graz corridor concentrates thermal management expertise for high-flux LED architectures.
Czech Republic
Cost-competitive assembly locations serve German OEMs with full EU regulatory alignment. Slovakia and Czech plants source pre-validated LED modules for platform integration. Brno-region facilities expand capacity to meet compressed homologation timelines from Stuttgart procurement offices.
Europe Automotive LED Lighting Market Competitive Landscape
Dual-source contracting dominates the current landscape as German vehicle assemblers split matrix LED awards between engineering specialists and vertically integrated suppliers. The vendor base organizes around three archetypes: Austrian engineering-focused developers, French vertically integrated optical designers, and Japanese precision manufacturers. M&A activity and capacity expansion in Eastern European assembly locations represent the two principal competitive vectors reshaping supplier relationships.
Within the engineering-specialist tier, ZKW Group and HELLA GmbH & Co. KGaA exemplify divergent strategic positions. ZKW Group occupies a position anchored in Austrian technical development for premium OEM programs. HELLA GmbH & Co. KGaA represents the aftermarket distribution archetype across Central European replacement markets. Valeo SE sits within the vertically integrated tier, controlling captive optical design and thermal management capabilities.
| Leading Market Players |
|---|
| ZKW Group |
| ams-OSRAM AG |
| HELLA GmbH & Co. KGaA |
| Lumileds |
| Stanley Electric Co., Ltd. |
| Valeo SE |
| Koito Manufacturing Co., Ltd. |
| Nichia |
| Automotive Lighting (Marelli Holdings Co., Ltd.) |
| Others |
Pricing and Supply Chain Analysis
Micro-LED array adoption is simultaneously collapsing electromechanical component costs and concentrating procurement leverage among German premium OEMs with direct specification authority over pixel-control architectures.
Pricing Analysis
Software and calibration service bundling separates matrix LED headlamp contracts from unbundled standard LED module transactions. Pricing stratifies across premium, standard, and economy tiers with differentiation driven by ECE Regulation 48 certification grade and thermal substrate performance specifications. Cost compression in mid-tier phosphor-converted packages is intensifying because REACH substance restrictions force cerium-free reformulation investments. Fleet procurement offices at commercial vehicle assemblers exhibit highest price sensitivity; Stuttgart-based premium OEM engineering teams prioritize beam-control precision over unit economics.
Supply Chain Analysis
Aftermarket refurbishment flows for failed LED modules are creating reverse-logistics revenue streams for HELLA GmbH & Co. KGaA across Central European distribution networks. Gallium nitride substrate processing concentrates in Austria and Germany; rare-earth phosphor refining draws from French and Italian chemical facilities. Single-source vulnerability persists for high-purity cerium feedstock subject to ECHA candidate list restrictions. Distribution runs through tier-1 lighting integrators holding EMA type-approval validation capacity for direct OEM platform integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Automotive LED Lighting is transitioning from electromechanical beam-shaping to solid-state micro-LED architectures, compressing supplier tier structures while elevating software-defined optical design capabilities.
For Market Incumbents: Extend thermal management engineering capacity to support 150+ lumen-per-watt architectures before scarce expertise becomes a binding constraint. Deepen backward integration into GaN substrate sourcing to defend margin position against raw material price volatility. Prioritize ECE Regulation 48 homologation laboratory capacity expansion to meet compressed validation windows from Stuttgart and Munich procurement offices. For New Entrants and Emerging Players: The price-point gap between Austrian-engineered matrix LED systems and Czech-assembled standard modules creates entry space for mid-tier adaptive beam specialists. Target commercial vehicle fleet retrofit segments in Slovakia and Poland where EU regulatory alignment meets cost-competitive assembly economics. Pursue OEM co-development partnerships rather than tier-2 module supply to capture specification authority early in platform cycles. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated optical designers given EU AI Act safety-critical classification requirements for sensor-fusion beam algorithms. Long-term viability over a five-to-ten-year horizon favors suppliers controlling both phosphor formulation intellectual property and thermal substrate engineering. Monitor ECHA substance restriction expansion timelines as the inflection signal for cerium-free phosphor technology valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Matrix LED Platform Standardization | Reduces per-vehicle engineering validation costs for Baden-Württemberg OEMs. |
| GaN Substrate Backward Integration | Secures margin control against rare-earth price volatility from Asian supply nodes. |
| Cerium-Free Phosphor R&D Investment | Ensures REACH compliance continuity for French and Italian packaging facilities. |
| Eastern European Manufacturing Expansion | Captures cost-competitive assembly capacity with full EU regulatory alignment. |
| EU AI Act Compliance Service Development | Creates recurring revenue streams from adaptive beam algorithm classification. |
Research Methodology
Vehicle production databases, EMA type-approval registries, and IHS Markit registration data formed the secondary backbone for volume and specification analysis. Primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and ECHA regulatory affairs specialists validated demand assumptions and technology transition timelines. Bottom-up and top-down triangulation reconciled module-level shipment data with vehicle production counts across German, French, and Italian manufacturing corridors.
Bottom-up modeling aggregated content-per-vehicle assumptions across passenger car and commercial vehicle segments, while top-down analysis anchored aggregate market evolution to EU Green Deal efficiency mandate compliance trajectories. Segmentation dimensions included vehicle class, propulsion architecture, LED technology tier, and regional production cluster. CAGRs were derived from fitted adoption curves for matrix LED penetration rates and standard LED replacement cycles. Forecast inputs incorporated REACH substance restriction implementation schedules and ECE Regulation 48 amendment pathways.
Inputs from OEM procurement offices and tier-1 supplier engineering centers were available through the study window; gaps in real-time phosphor material cost data introduce uncertainty bands around mid-tier module pricing projections. Forecasts reflect assumptions about EU AI Act enforcement timing and ECHA candidate list expansion scope. Practitioners should monitor EMA homologation backlog indicators and GaN substrate spot market liquidity for early signals of supply constraint severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Chassis Electronics Market
Automotive Electrical & Electronics
Africa and Middle East Automotive Tpms Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
Automotive Thermal Management System Market
Automotive Electrical & Electronics
In-Chassis Cooling Market
Automotive Electrical & Electronics
Stair Lift Motors Market
Automotive Electrical & Electronics
Automotive Scroll E-Compressor Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Automotive Battery Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
Electric Motor Horn Market
Automotive Electrical & Electronics
Global Automotive on Board AC-DC Power Inverters Market
Automotive Electrical & Electronics
Global Automotive Electronically Controlled Air Suspension System Market
Automotive Electrical & Electronics
Automotive Immersion Cooling Dielectric Fluid Market
Automotive Electrical & Electronics
Stepper Motors Market