
 Automotive Electronic Expansion Valve Market | 2026-2036
Automotive Electronic Expansion Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Electronic Expansion Valve Market Analysis
Buyer concentration among electric vehicle original equipment manufacturers is consolidating as battery thermal management requirements intensify. Denso Corporation leverages its integrated HVAC-thermal system architecture to capture multi-component contracts. Danfoss Group anchors its position through deep specialization in refrigerant control algorithms and compact valve geometries. Sanhua Automotive competes aggressively on manufacturing scale from its Zhejiang production base.
An automotive electronic expansion valve is a precision electromechanical device that meters refrigerant flow through variable orifice control, typically operating at response times under 50 milliseconds to maintain evaporator superheat within two degrees Celsius. Its primary purpose is to optimize thermal efficiency in vehicle climate systems while minimizing energy draw from the powertrain. Variable displacement valves lead the product type segment due to their superior efficiency across partial-load conditions common in electric vehicles. Electronic control technology captures the fastest expansion trajectory as automakers phase out thermal and pneumatic actuation in favor of sensor-driven feedback loops.
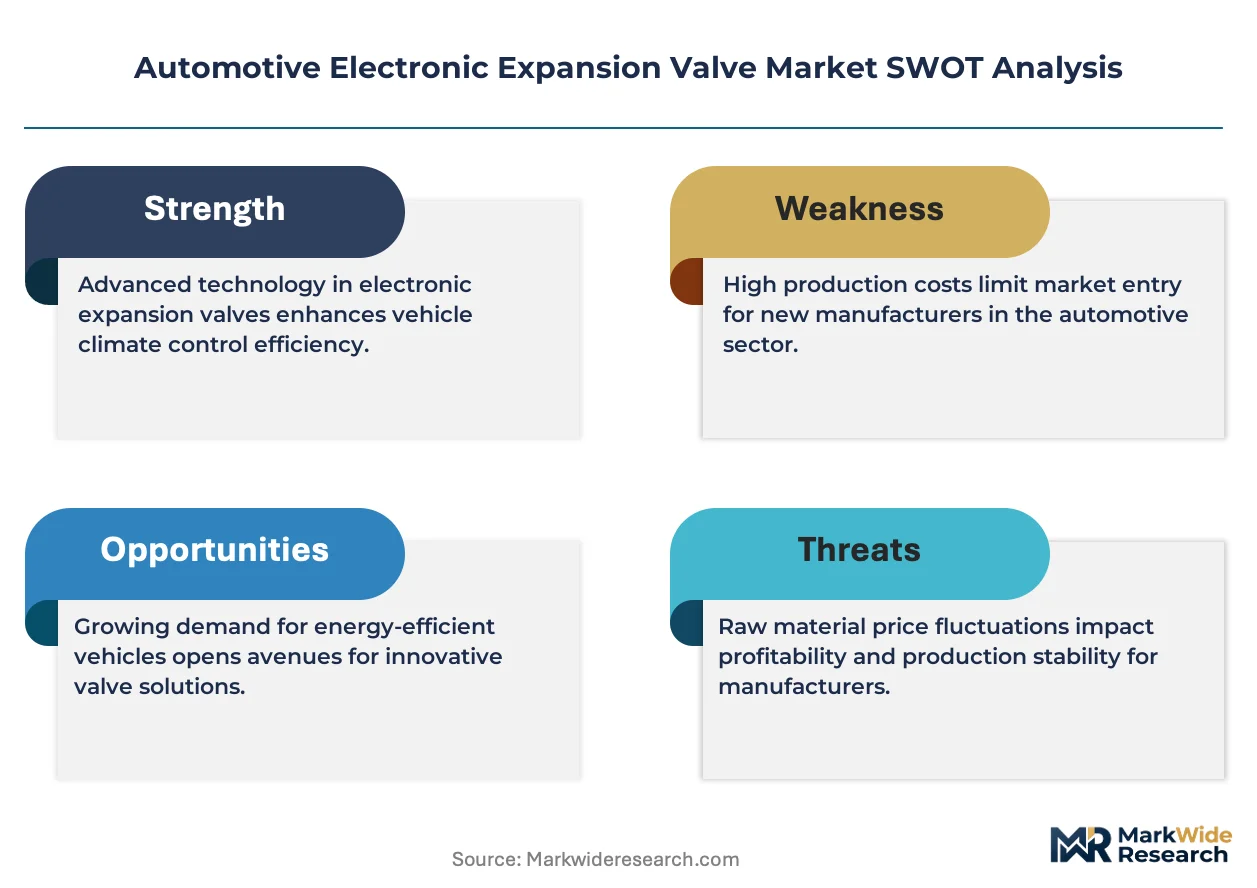
The EPA enforces Corporate Average Fuel Economy standards that indirectly mandate more efficient HVAC systems, while the EU F-Gas Regulation imposes strict refrigerant leakage limits that require precision valve control. China MIIT administers dual carbon goals that push domestic automakers toward electrified thermal architectures with lower energy intensity. Stakeholders must monitor how refrigerant chemistry transitions toward low-global-warming-potential alternatives reshape valve material specifications and certification requirements.
Market Dynamics
Battery thermal management requirements are compressing valve response specifications from 100 milliseconds to sub-50 millisecond thresholds, forcing component suppliers to redesign electromagnetic actuation architectures around electric vehicle platform constraints.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant leakage mandates below 3% annually require precision orifice control, accelerating replacement of mechanical expansion devices with sensor-driven electronic valves in European vehicle fleets.
- China MIIT dual carbon goals:Domestic automakers face binding energy intensity reduction targets that prioritize electrified thermal architectures with variable refrigerant metering across partial-load operating conditions.
- Copper rotor windings:Advanced electromagnetic materials enable faster actuation cycles without thermal degradation, supporting the transition from pneumatic to fully electronic climate control systems in premium electric vehicle segments.
Market Restraints
- Rare earth magnet supply:Neodymium price volatility from Chinese export quotas creates input cost instability for valve actuator manufacturers dependent on high-coercivity permanent magnets.
- Single-source controller ASICs:Semiconductor fabrication for proprietary valve driver chips concentrates in Taiwanese foundries, exposing supply continuity risks during geopolitical trade friction.
- Refrigerant chemistry transition:R-1234yf compatibility requirements impose material specification changes that delay product recertification timelines by 18-24 months for existing valve platforms.
Strategic Opportunities
- Commercial vehicle electrification:Heavy-duty battery electric trucks in Germany and the United States present untapped demand for high-capacity thermal management valves capable of 15-20 kilowatt cooling loads.
- Heat pump convergence:Integration of cabin heating and battery conditioning through reversible refrigerant circuits creates specification openings for bidirectional expansion valve designs.
- India PLI scheme:Production-linked incentives for automotive component manufacturing attract valve assembly localization to serve domestic electric vehicle production scaling through 2030.
Industry Challenges
- Embedded software certification:ISO 26262 functional safety validation for valve control algorithms demands specialized automotive software engineering talent that remains scarce outside Germany and Japan.
- Legacy HVAC integration:Electronic valve retrofits into existing internal combustion vehicle platforms require mechanical interface adapters that complicate inventory management and service training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electronic Expansion Valve Market |
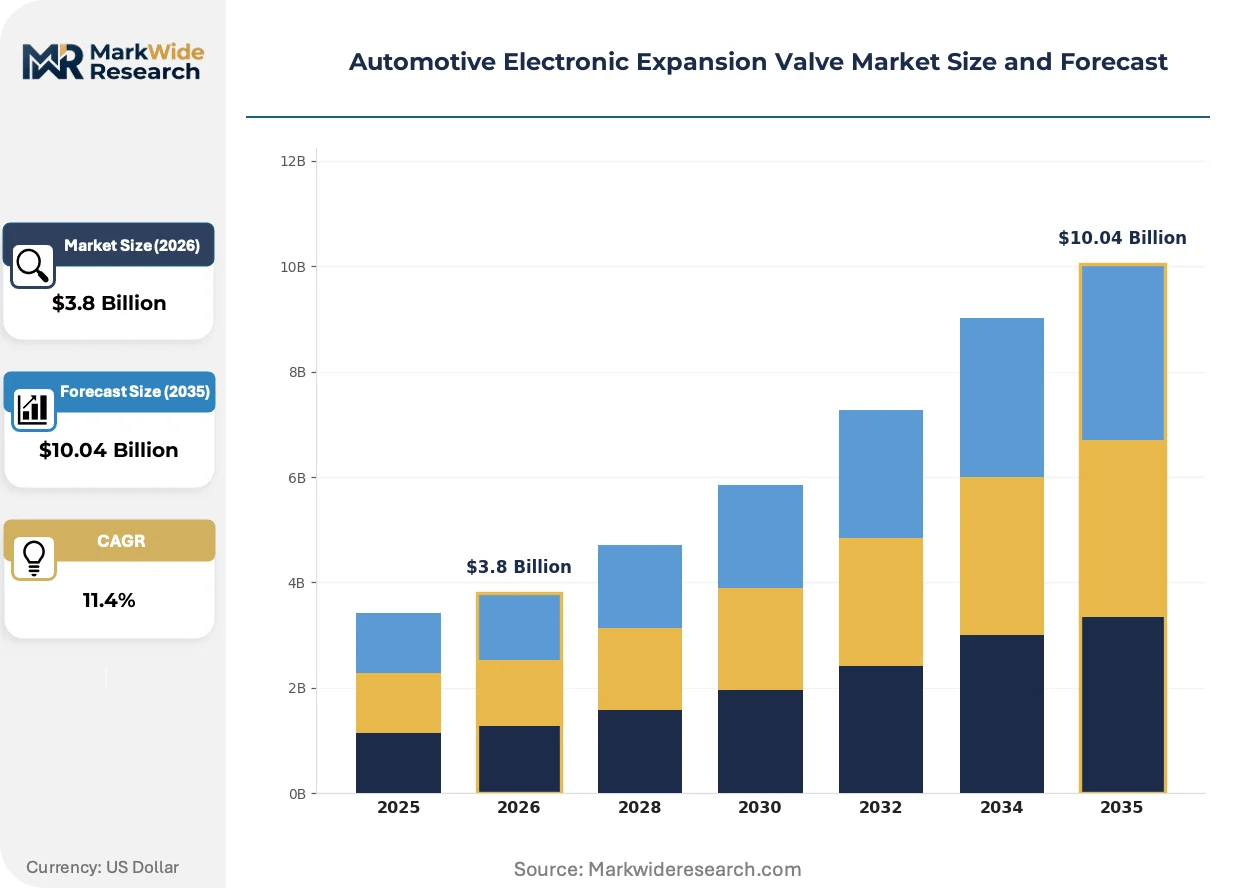
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Variable Displacement, Integrated, Modular Technology: Thermal, Magneto-Rheological, Electronic Control, Pneumatic Application: HVAC Systems, Refrigeration, Climate Control, Automotive Chillers End User: Passenger Vehicles, Commercial Trucks, Electric Vehicles, Aftermarket Providers |
| Companies Covered | Hanon Systems, Danfoss Group, Denso Corporation, Zhejiang DunAn Automotive Parts Co., Ltd., Parker Hannifin Corporation, Sanhua Automotive, Valeo SA, Mitsubishi Electric Corporation, Fujikoki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electronic Expansion Valve Market Emerging Trajectories
Refrigerant system electrification is compressing the gap between climate control hardware and powertrain thermal management, creating unified component specifications that span cabin comfort and battery safety functions.
Silicon carbide power semiconductors are absorbing switching losses in valve driver circuits that previously limited actuation frequency. Tier 1 suppliers in Germany and Japan are qualifying SiC-based motor controllers for 100-kilohertz pulse-width modulation. This frequency expansion is absorbing the performance margin between standard electronic valves and next-generation magnetostrictive alternatives.
EPA Corporate Average Fuel Economy standards are tightening indirect HVAC efficiency requirements through 2032 model years. The regulation forces automakers to deploy predictive thermal load algorithms that anticipate cabin conditioning needs before occupant demand signals. United States electric vehicle programs are responding with integrated vehicle thermal management controllers that coordinate expansion valve positioning with battery state-of-charge optimization.
Direct procurement relationships between electric vehicle original equipment manufacturers and valve specialists are displacing traditional Tier 2 supply hierarchies. Battery platform engineers in China and the United States now specify thermal component performance parameters directly, bypassing consolidated HVAC system suppliers. This channel compression is most visible in California and Zhejiang province, where vertical integration strategies prioritize in-house thermal system architecture control.
Automotive Electronic Expansion Valve Market Segmentation
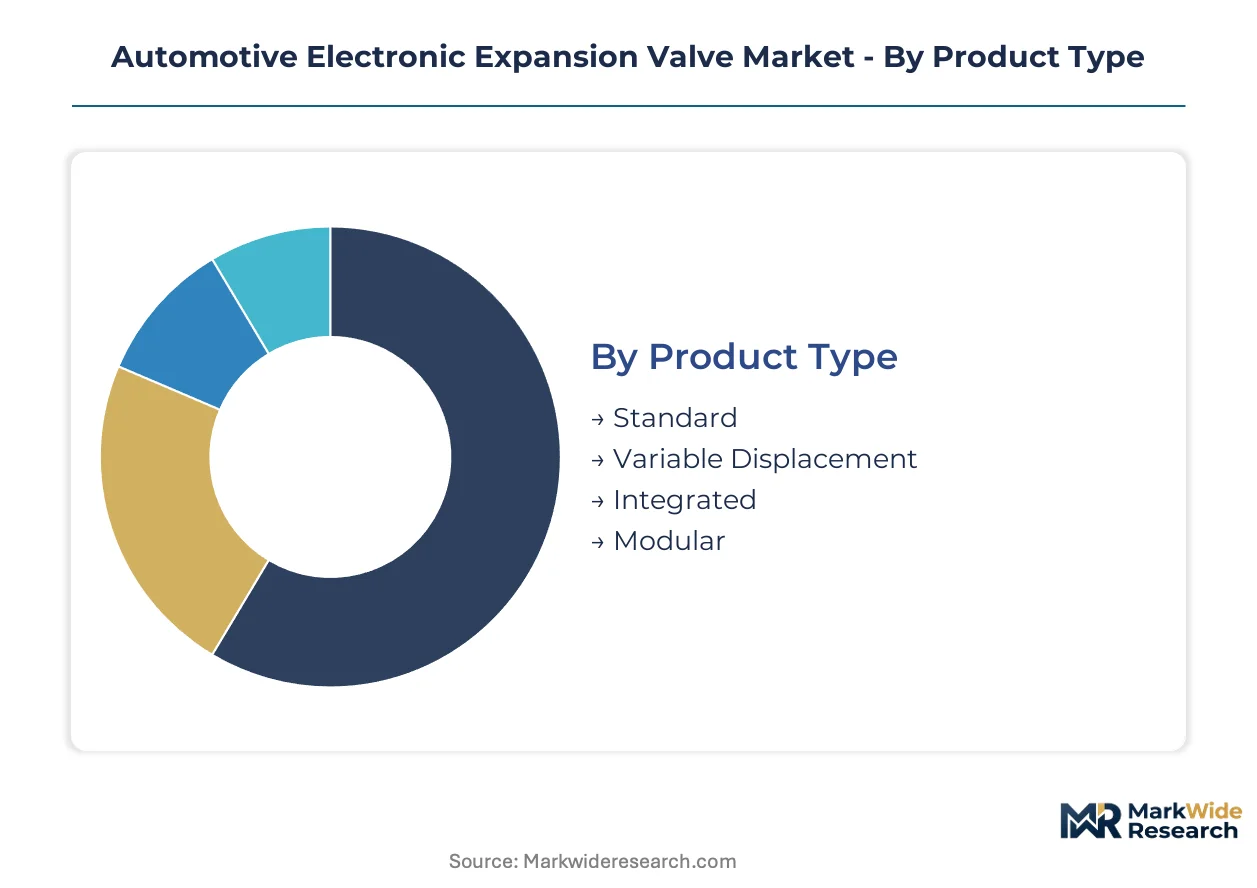
Segmentation in automotive electronic expansion valves tracks how thermal management requirements diverge across electrification pathways. Product architecture, control methodology, and vehicle platform each impose distinct specification thresholds that reshape supplier priorities.
Product Type:
Cost tier determines procurement patterns, with automakers tiering valve specifications by vehicle class and thermal load requirements.
- Variable Displacement:These valves modulate refrigerant flow through continuously adjustable orifice geometries rather than stepped positions. Demand concentrates in premium battery electric vehicles from Germany and China, where partial-load efficiency optimization justifies the 15-20% cost premium over standard designs.
- Integrated:Combined valve-sensor-controller units reduce wiring complexity and assembly time for OEMs pursuing platform consolidation. Chinese electric vehicle manufacturers in Zhejiang province specify these for new dedicated battery platforms, accepting higher unit costs to simplify supply chain coordination.
- Standard:Fixed-orifice electronic valves serve cost-sensitive internal combustion vehicle programs and entry-level hybrid architectures.
- Modular:Field-replaceable cartridge designs target aftermarket channels and commercial fleet operators prioritizing service interval minimization.
Volume sits with Standard; growth tilts toward Variable Displacement.
Technology:
Application environment dictates actuation method selection, with response time specifications hardening most rapidly in battery thermal management loops.
- Electronic Control:Closed-loop systems using temperature-pressure feedback achieve sub-50 millisecond positioning accuracy through pulse-width modulated stepper motors. United States and Chinese OEMs mandate these for all new battery electric platforms, phasing out thermal and pneumatic alternatives by the current model cycle.
- Magneto-Rheological:Fluid-based actuation enables damping-integrated valve response for vibration-sensitive cabin comfort applications. German luxury manufacturers specify these for flagship electric sedans, accepting material cost premiums for noise reduction benefits.
- Thermal:Wax-element actuation persists in legacy internal combustion vehicle programs with minimal electrification content.
- Pneumatic:Vacuum-driven valves remain confined to commercial vehicle segments with established air brake infrastructure and slower thermal response requirements.
Deployment clusters on Electronic Control; Magneto-Rheological is climbing the fastest.
Application:
Customer type shapes performance specifications, with battery safety requirements imposing tighter tolerances than occupant comfort systems.
- HVAC Systems:Cabin climate control demands multi-zone refrigerant distribution with 2-degree Celsius superheat maintenance across variable ambient conditions. Chinese and United States electric vehicle platforms integrate these with heat pump architectures for year-round efficiency.
- Automotive Chillers:Dedicated battery cooling circuits require 15-20 kilowatt capacity valves with bidirectional flow capability for fast-charge thermal management. German heavy-duty electric truck programs specify these for 350-kilowatt charging compatibility.
- Refrigeration:Commercial vehicle cargo cooling uses higher-displacement variants with corrosion-resistant coatings for transport refrigeration.
- Climate Control:Entry-level passenger vehicles combine simplified HVAC and battery conditioning through single-circuit designs.
Revenue concentrates in HVAC Systems; specification intensity peaks in Automotive Chillers.
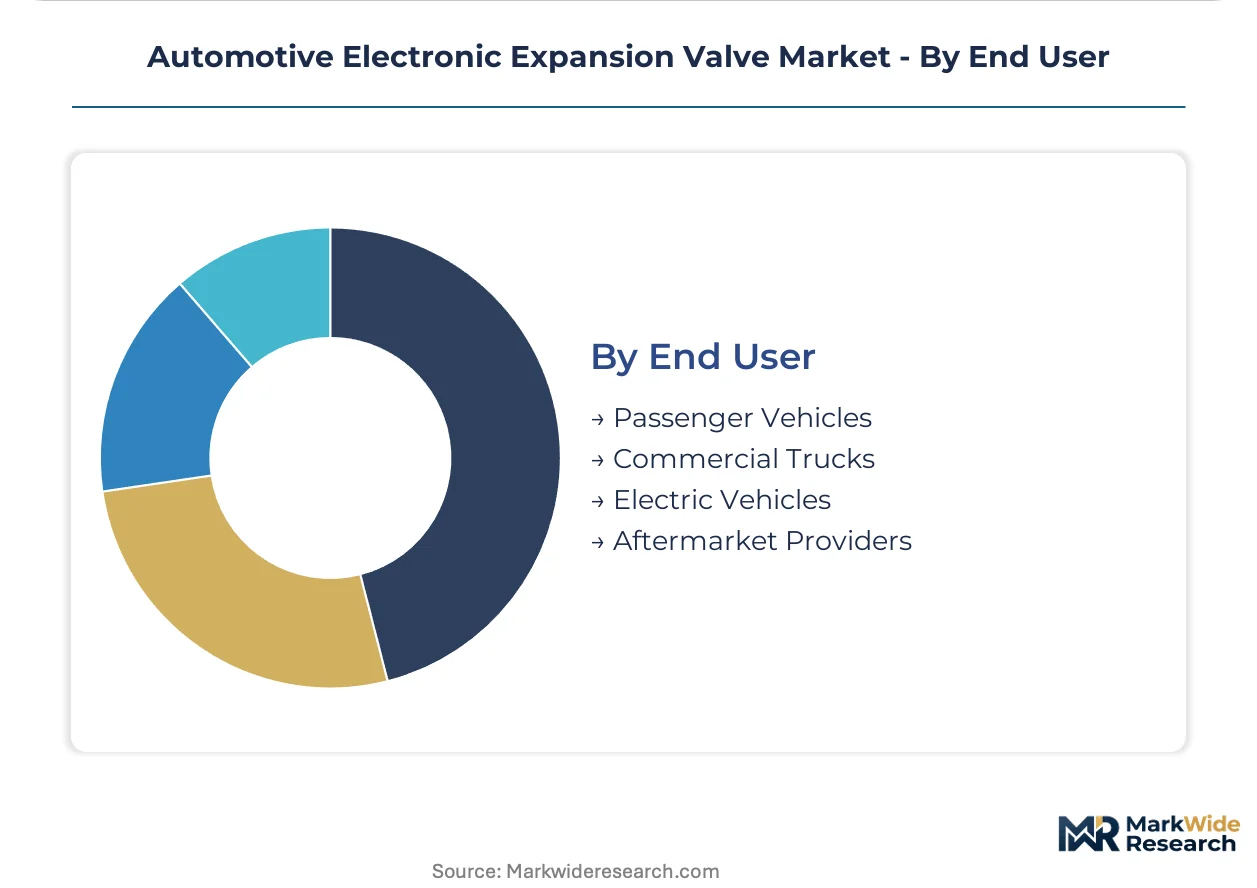
End User:
Volume scale and margin structure diverge sharply between captive OEM supply and fragmented aftermarket channels.
- Electric Vehicles:Dedicated battery platforms specify precision valves as standard equipment, with thermal management integrated into vehicle architecture from design inception. Chinese MIIT dual carbon goals accelerate procurement through binding energy intensity regulations.
- Passenger Vehicles:Hybrid and mild-hybrid architectures in Germany and Japan represent transitional demand, blending electronic and conventional thermal components.
- Commercial Trucks:Heavy-duty battery electric programs in the United States and Germany drive demand for high-capacity, extended-lifecycle designs.
- Aftermarket Providers:Service replacement demand lags OEM fitment by 5-7 years, concentrated in mechanical-to-electronic retrofit applications.
Procurement volume favors Passenger Vehicles; specification evolution centers on Electric Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, Germany, and the United States concentrate procurement for automotive electronic expansion valves as battery electric vehicle production scales. These three markets drive specification evolution through distinct regulatory frameworks and industrial clustering patterns.
China
Domestic automakers under MIIT dual carbon goals prioritize electrified thermal architectures with lower energy intensity. Binding energy intensity reduction targets push procurement toward variable refrigerant metering systems. Zhejiang province hosts concentrated valve assembly operations serving BYD, NIO, and XPeng platform requirements.
Germany
Heavy-duty battery electric truck programs from MAN and Daimler Truck generate demand for high-capacity thermal management valves. EU F-Gas Regulation mandates refrigerant leakage limits below 3% annually, forcing precision orifice control adoption. Stuttgart and Munich engineering centers specify valve performance parameters directly for dedicated battery platforms.
United States
EPA Corporate Average Fuel Economy standards tighten indirect HVAC efficiency requirements through 2032 model years. California electric vehicle programs deploy integrated thermal management controllers coordinating expansion valve positioning with battery state-of-charge optimization. Detroit-area battery platform engineering teams bypass traditional Tier 2 suppliers for direct valve procurement.
Japan
Hybrid and mild-hybrid architectures in Toyota and Honda programs represent transitional demand blending electronic and conventional thermal components. METI industrial policy supports domestic valve actuator manufacturing for export markets. Nagoya-area suppliers qualify compact valve geometries for integration with heat pump cabin systems.
South Korea
Hyundai and Kia battery electric platforms specify sub-50 millisecond response valves for fast-charge thermal management compatibility. National semiconductor fabrication capabilities reduce dependency on external controller ASIC supply. Seoul Capital Area engineering centers coordinate valve specifications with in-house battery thermal system architecture teams.
Automotive Electronic Expansion Valve Market Vendor Landscape
Japanese and German producers anchor the premium tier; Chinese specialists hold volume manufacturing positions. The supplier base organizes around three strategic archetypes: integrated HVAC-thermal system architects, precision refrigerant control specialists, and scale-driven component fabricators. Consolidation pressures intensify as battery platform engineers specify performance parameters directly. Dominant competitive moves include backward integration into electromagnetic actuator manufacturing and capacity expansion near Zhejiang and Detroit battery production clusters.
Within the integrated system architect tier, Denso Corporation and Mitsubishi Electric Corporation exemplify players capturing multi-component contracts through unified thermal management architectures. Among precision refrigerant specialists, Danfoss Group anchors a position through deep algorithmic expertise. At the scale-driven end, Sanhua Automotive and Zhejiang DunAn Automotive Parts Co., Ltd. occupy manufacturing positions serving domestic Chinese electric vehicle production scaling.
| Leading Market Players |
|---|
| Hanon Systems |
| Danfoss Group |
| Denso Corporation |
| Zhejiang DunAn Automotive Parts Co., Ltd. |
| Parker Hannifin Corporation |
| Sanhua Automotive |
| Valeo SA |
| Mitsubishi Electric Corporation |
| Fujikoki |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation refrigerant leakage mandates below 3% annually gate qualified supply access and premium-tier pricing power, forcing valve manufacturers to absorb 18-24 month recertification cycles while Tier 1 OEMs concentrate procurement among pre-certified suppliers with proven algorithmic control architectures.
Pricing Analysis
Volume sits with standard fixed-orifice electronic valves serving cost-sensitive internal combustion and entry-level hybrid programs, while margins concentrate in variable displacement designs commanding 15-20% premiums for partial-load efficiency optimization in premium battery electric vehicles. Price differentiation hinges on response time certification tier—sub-50 millisecond platforms versus 100 millisecond legacy designs—and electromagnetic material specification grade. Cost compression in standard-tier valves is intensifying because Chinese domestic automakers under MIIT dual carbon goals negotiate aggressive scale contracts for new dedicated battery platforms. Fleet operators and commercial truck buyers exhibit highest price sensitivity due to total cost of ownership calculations, whereas German luxury OEMs prioritize performance specifications over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand as battery platform engineers in California and Zhejiang province bypass traditional Tier 2 HVAC system suppliers to specify valve performance parameters directly. Manufacturing concentrates in China, Germany, and Japan, with electromagnetic actuator coil winding and precision machining anchored in Zhejiang province and Stuttgart engineering centers. Raw material dependencies draw from neodymium permanent magnets, copper rotor windings, and silicon carbide power semiconductors for driver circuits. Single-source vulnerability in Taiwanese foundry fabrication for proprietary valve controller ASICs exposes supply continuity risks during geopolitical trade friction. Distribution runs through captive OEM supply agreements with limited aftermarket penetration lagging OEM fitment by 5-7 years.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU F-Gas Regulation refrigerant leakage mandates and EPA Corporate Average Fuel Economy standards erect barrier-to-entry moats favoring incumbents with pre-certified algorithmic control platforms and established electromagnetic actuator manufacturing capabilities.
For Market Incumbents: To counter direct procurement channel compression by battery platform engineers, deepen backward integration into copper rotor winding and silicon carbide driver circuit manufacturing to secure input cost stability and response time performance margins. Anchor position through capacity expansion near Detroit and Zhejiang battery production clusters, qualifying integrated valve-sensor-controller units that reduce OEM wiring complexity and assembly time. For New Entrants and Emerging Players: Tier 2 HVAC system suppliers represent the most penetrable channel partner type for modular field-replaceable cartridge designs targeting commercial fleet operators prioritizing service interval minimization. White-space opportunities concentrate in heavy-duty battery electric truck thermal management valves for 15-20 kilowatt cooling loads in German and United States programs, plus bidirectional expansion valve designs for heat pump convergence applications. Pursue qualification partnerships with Indian domestic electric vehicle manufacturers leveraging PLI scheme localization incentives through 2030. For Investors and Strategic Acquirers: First-tier supplier acquisition of electromagnetic actuator specialists is the leading indicator that in-house thermal system architecture control is becoming a competitive necessity. Long-term viability favors vertically integrated players with captive algorithm development and manufacturing scale positions serving Chinese MIIT-regulated domestic automakers. Monitor neodymium export quota announcements from Chinese supply authorities for early signals of input cost volatility affecting valve actuator manufacturer margins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electromagnetic Actuator Manufacturing | Secures copper rotor and neodymium magnet supply against Chinese export quota volatility for Tier 1 suppliers. |
| Heat Pump Convergence Platform Development | Captures bidirectional valve specification openings as German and United States OEMs unify cabin and battery thermal circuits. |
| Indian PLI Scheme Localization Partnership | Positions valve assembly operations to serve domestic electric vehicle production scaling through MIIT-equivalent Indian regulations. |
| Silicon Carbide Driver Circuit Qualification | Enables 100-kilohertz pulse-width modulation actuation frequencies absorbing performance margins from magnetostrictive alternatives. |
| ISO 26262 Functional Safety Certification Investment | Addresses embedded software engineering talent scarcity outside Germany and Japan for valve control algorithm validation. |
Methodological Framework
Vehicle production databases, IHS Markit registration data, and SEC filings from Tier 1 thermal system suppliers formed the secondary backbone, supplemented by customs and trade flow records for refrigerant system component movements. Primary fieldwork incorporated structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and electromagnetic actuator manufacturing specialists across China, Germany, and the United States. Bottom-up unit economics modeling triangulated against top-down market sizing from regulatory mandate penetration curves and battery electric vehicle production forecasts.
Historical trendline analysis examined valve content per vehicle trajectories across hybrid, plug-in hybrid, and dedicated battery electric architectures, with segmentation modeling across propulsion type, vehicle class, thermal load requirement, and regional production cluster. CAGRs were derived from fitted growth curves incorporating technology substitution rates for pneumatic-to-electronic actuation transitions and refrigerant chemistry compatibility cycles. Forecast inputs included MIIT dual carbon goal binding energy intensity reduction targets and EPA model year efficiency tightening schedules.
Caveats apply where refrigerant chemistry transitions toward low-global-warming-potential alternatives, rare earth magnet supply disruptions, or semiconductor fabrication capacity constraints could materially shift the outlook for valve material specifications and certification timelines. Practitioners should monitor Chinese neodymium export policy announcements, Taiwanese foundry utilization rates, and EU F-Gas Regulation enforcement precedent for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
South Korea Automotive Camera Market
Automotive Electrical & Electronics
TPMS Battery Market
Automotive Electrical & Electronics
Stair Lift Motors Market
Automotive Electrical & Electronics
Electrical Park Brake (EPB) Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
Automotive Electronic Manufacturing Services Market
Automotive Electrical & Electronics
Automotive Speed Sensor Market
Automotive Electrical & Electronics
Automotive Scroll E-Compressor Market
Automotive Electrical & Electronics
Personal Mobility Devices Market
Automotive Electrical & Electronics
Asia Pacific Automotive Camera Market
Automotive Electrical & Electronics
Automotive Electronic Logging Device (ELD/E-Log) Market
Automotive Electrical & Electronics
Automotive Alternator and Starter Motor Market
Automotive Electrical & Electronics
On-Board Charger Market