
 New Energy Automotive Antenna Market | 2026-2036
New Energy Automotive Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
New Energy Automotive Antenna Market Insights
REACH compliance is rebalancing the cost-of-entry calculus for European suppliers, forcing reformulation of antenna housing materials and surface coatings. Continental AG leverages its captive PCB manufacturing to absorb these compliance costs internally. TE Connectivity anchors its position through high-volume production of 5G-ready connectorized antenna modules for North American EV platforms. Harada Industry Co. Ltd specializes in shark-fin form factors that dominate the Japanese domestic OEM supply base.
New energy automotive antennas are RF transducers engineered to operate across 700 MHz to 28 GHz bands, incorporating low-loss substrates such as liquid crystal polymer and ceramic-filled PTFE to maintain signal integrity in high-density electromagnetic environments. Their primary purpose is enabling vehicle-to-everything communication, over-the-air software updates, and precise positioning for autonomous driving stacks. Active antennas command margin pools due to integrated low-noise amplifiers and filtering stages that passive architectures cannot replicate. 5G technology segments are expanding fastest as OEMs embed C-V2X protocols directly into platform designs rather than treating connectivity as an aftermarket add-on.
FCC certification requirements in the United States, ETSI standards in Europe, and MIIT radio type approval in China collectively dictate antenna gain patterns, spurious emission limits, and modular approval pathways that shape product development timelines. OEMs and tier-1 suppliers must now validate antenna performance across regional spectrum allocations before platform freeze, compressing design cycles and favoring suppliers with multi-homologation expertise. Stakeholders should monitor spectrum reallocation decisions in major automotive markets, as these will determine which frequency bands require dedicated antenna apertures versus shared multifunction arrays.
Market Dynamics
OEM platform consolidation around battery electric architectures is compressing antenna design cycles while multiplying RF performance requirements per vehicle. Suppliers must now validate multi-band arrays before platform freeze, eliminating traditional development buffers.
Growth Catalysts
- C-V2X Protocol Integration:China's MIIT mandates for connected-vehicle certification require dedicated V2X antenna modules, creating pull-through demand for integrated multi-band systems in domestic EV platforms.
- Over-the-Air Update Proliferation:Automotive software stacks now require persistent high-bandwidth connectivity, forcing antenna upgrades from passive to active architectures with embedded amplification.
- Yangtze River Delta Cluster Density:Tier-1 suppliers co-located with BYD, NIO, and Tesla Shanghai operations benefit from same-day logistics loops for antenna module just-in-sequence delivery.
Market Restraints
- Liquid Crystal Polymer Supply Concentration:Three Japanese chemical conglomerates control low-loss substrate supply for high-frequency antenna designs, exposing buyers to allocation risk during demand spikes.
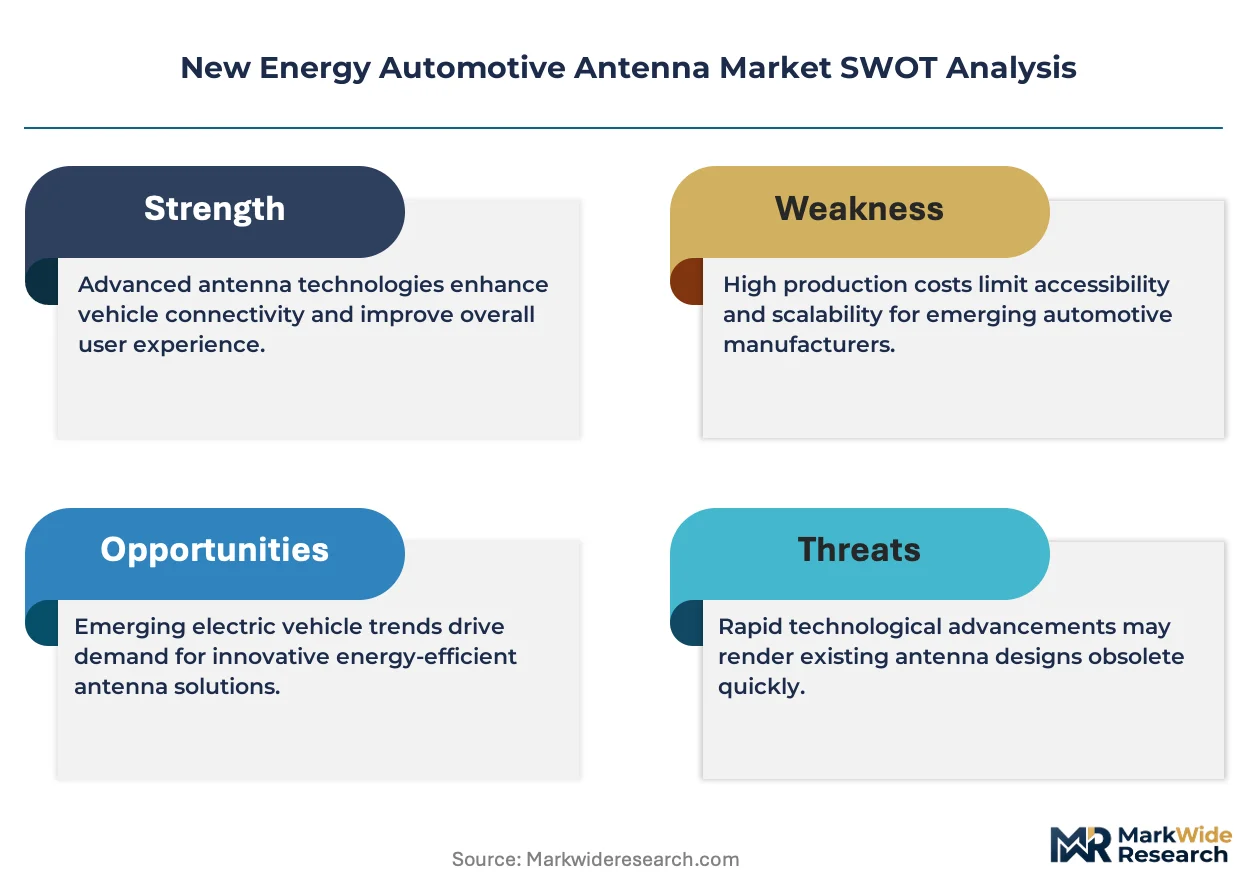
- REACH Compliance Cost Burden:ECHA restrictions on halogenated flame retardants force European suppliers to reformulate antenna housing resins, adding 12-18 months to material qualification timelines.
- Passive Architecture Obsolescence:Legacy single-band shark-fin designs face displacement by active multifunction arrays, stranding invested tooling and engineering expertise at smaller suppliers.
Strategic Opportunities
- Sub-6 GHz and mmWave Convergence:Antenna suppliers combining C-V2X and 5G NR arrays into shared apertures capture platform-level design wins as OEMs reduce rooftop module count.
- India PLI Scheme for Auto Components:Domestic manufacturing incentives for connected vehicle electronics create localization pathways for antenna module production serving Maruti Suzuki and Tata Motors EV programs.
- Insurance Telematics Integration:Usage-based insurance mandates in several European markets require dedicated antennas for real-time driving data transmission, opening aftermarket retrofit demand.
Industry Challenges
- Multi-Homologation Expertise Scarcity:FCC, ETSI, and MIIT certification pathways diverge on spurious emission testing protocols, forcing suppliers to maintain parallel validation labs or outsource to specialized test houses.
- RF Simulation Talent Gap:Electromagnetic modeling for 28 GHz automotive radar coexistence requires engineers with combined antenna and semiconductor packaging experience, a profile concentrated at aerospace and telecom defectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Energy Automotive Antenna Market |
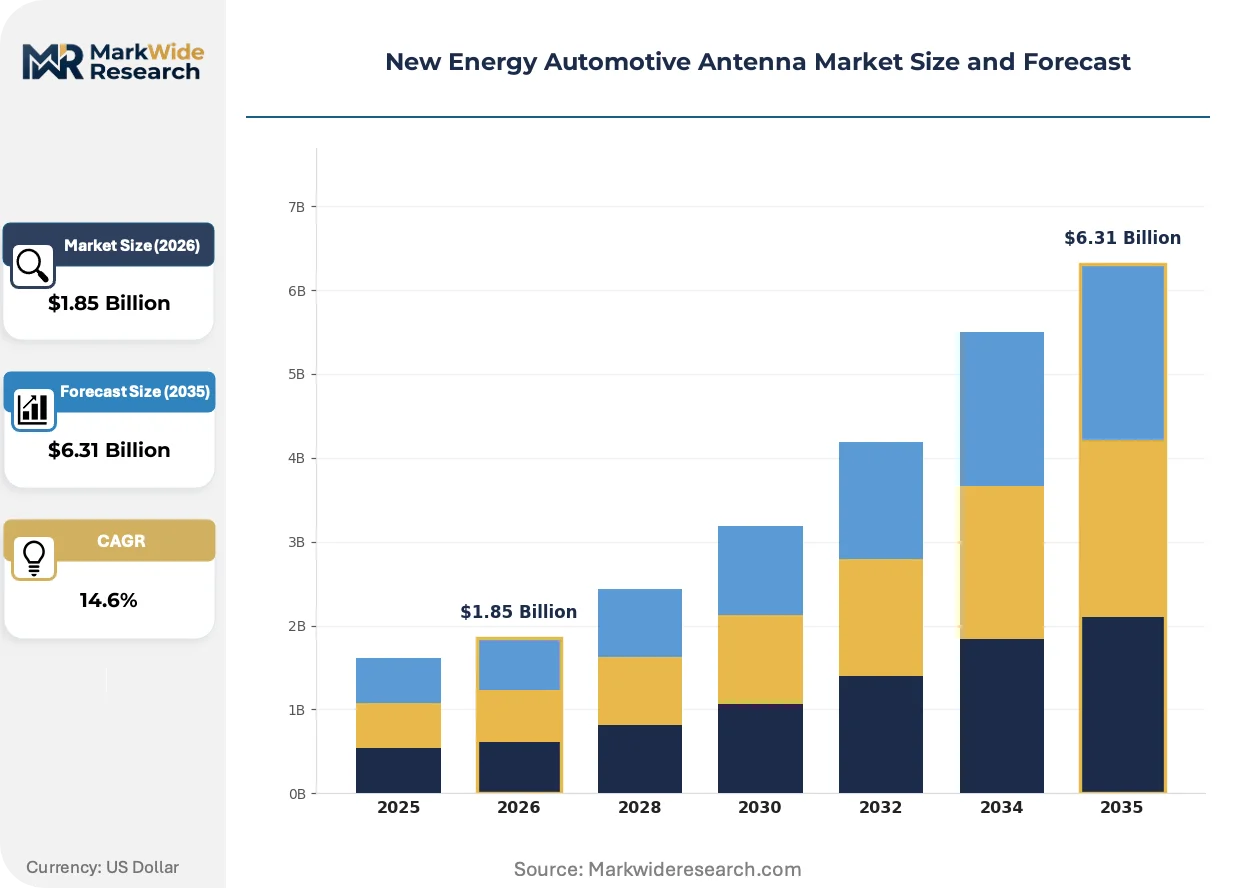
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.31 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Antennas, Passive Antennas, Diversity Antennas, Integrated Antennas Technology: 3G, 4G, 5G, Satellite End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Deployment: In-Vehicle Systems, Remote Monitoring, Vehicle-to-Infrastructure, Fleet Management |
| Companies Covered | Continental AG, DENSO Corporation, TE Connectivity, Ficosa International SA, HELLA GmbH & Co. KGaA, Robert Bosch GmbH, Harada Industry Co. Ltd, Kathrein SE, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Energy Automotive Antenna Market Trends and Innovations
Antenna architectures are transitioning from discrete single-function modules to integrated multifunction arrays as vehicle connectivity requirements multiply. This convergence demands new substrate materials, simulation capabilities, and supplier-customer technical collaboration models.
Ceramic-filled PTFE laminates are absorbing thermal and mechanical stress in high-density antenna arrays while maintaining dielectric stability across temperature extremes. Tier-1 suppliers in Germany and Japan are qualifying these substrates for 5G-ready roof-mounted modules. The material shift is absorbing margin pressure from precious metal cost volatility by extending field reliability warranties.
ETSI harmonized standards for C-V2X Day-2 services are mandating antenna diversity requirements that exceed current single-aperture performance. European OEMs must now validate dual-polarized arrays for intersection collision avoidance protocols. The regulatory push is accelerating supplier consolidation around firms with in-house electromagnetic simulation and vehicle-level testing capabilities.
Fleet operators now specify antenna performance through guaranteed connectivity uptime metrics rather than hardware specifications alone. Commercial vehicle buyers in North America are displacing traditional component procurement with service-level agreements covering installation, maintenance, and over-the-air diagnostics. This behavioral shift concentrates demand on suppliers with captive installation networks and remote monitoring infrastructure.
New Energy Automotive Antenna Market Segmentation
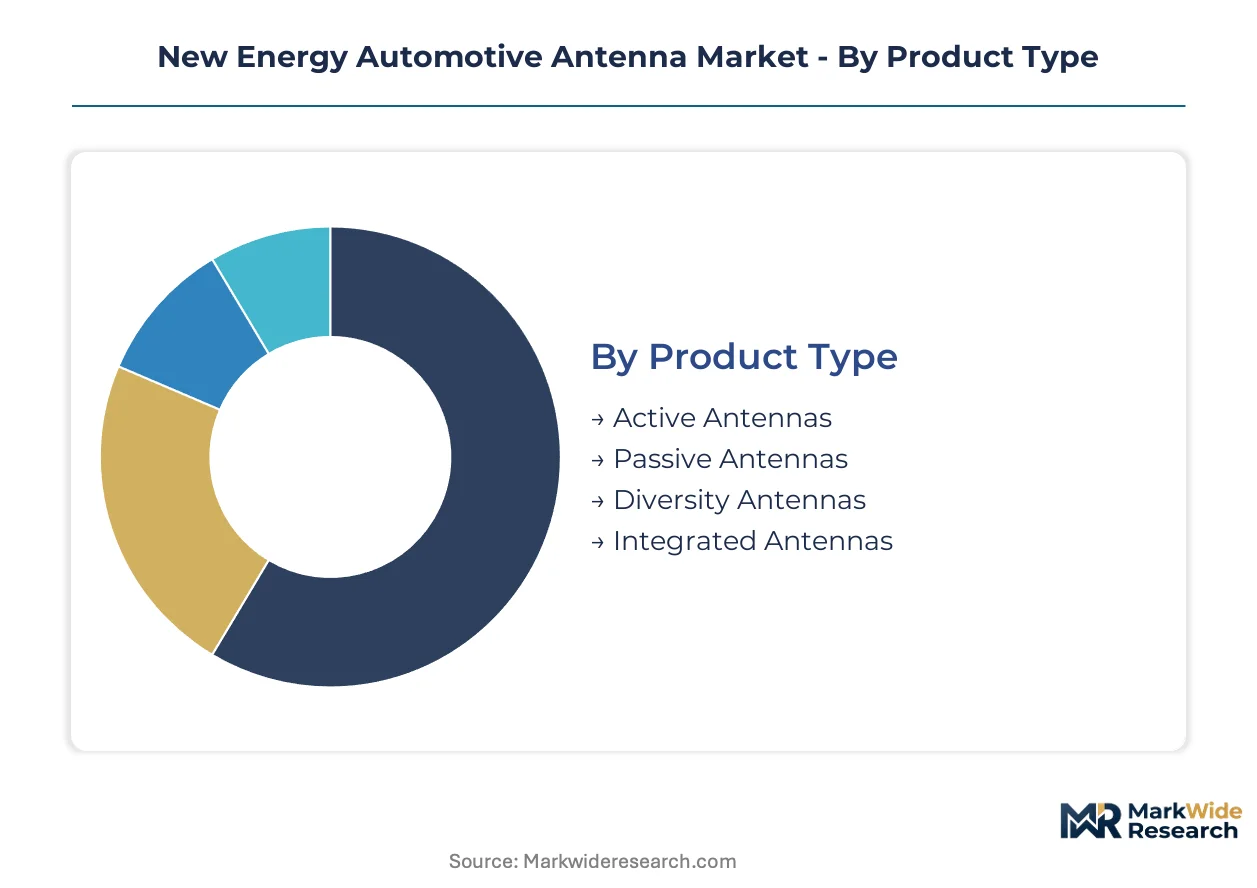
Antenna procurement patterns fragment sharply across product architectures and connectivity protocols. OEM platform decisions cascade through technology choices, deployment models, and supply chain tiers with unequal margin capture.
Product Type:
Supply concentration in low-loss substrates and RF amplification components favors suppliers with backward integration into semiconductor packaging and ceramic substrate manufacturing.
- Active Antennas:These architectures embed low-noise amplifiers, filtering stages, and power management circuits directly into the antenna module. Integrated amplification compensates for cable losses in multi-band arrays spanning 700 MHz to 28 GHz. Demand concentrates in premium battery electric platforms from Tesla and BYD, where persistent high-bandwidth connectivity for over-the-air updates is non-negotiable.
- Passive Antennas:Simple radiating elements without onboard electronics dominate legacy internal combustion platforms and economy EV segments. Cost pressure from OEMs has compressed margins to single digits, forcing smaller suppliers to exit or seek acquisition by module integrators with active antenna capabilities.
- Diversity Antennas:Spatially separated aperture pairs mitigate multipath fading in urban canyon environments. These configurations are mandatory under ETSI C-V2X Day-2 standards for intersection collision avoidance.
- Integrated Antennas:Multi-function arrays combining cellular, satellite, and V2X bands into shared physical volumes reduce rooftop module count. Harada Industry and Continental AG have developed proprietary molding processes for these compact form factors.
Today's leader: Active Antennas. Tomorrow's challenger: Integrated Antennas.
Technology:
Cost tier stratification separates premium platforms with full 5G mmWave capability from mid-market vehicles relying on sub-6 GHz architectures.
- 5G:New Radio arrays operating in sub-6 GHz and mmWave bands enable C-V2X direct communication and high-throughput infotainment streaming. China's MIIT mandates for connected-vehicle certification are accelerating 5G antenna adoption in domestic EV platforms from BYD, NIO, and Xpeng. Module complexity drives qualification timelines beyond 24 months.
- 4G:LTE-M and Cat-1 bis modules persist in commercial vehicle telematics and entry-level passenger EVs where bandwidth requirements remain modest. Fleet operators in North America specify 4G antennas through connectivity uptime service agreements rather than hardware specifications.
- 3G:Legacy networks are being sunset by carriers across Germany, Japan, and the United States, rendering 3G-capable antennas obsolete for new vehicle programs.
- Satellite:L-band and Ku-band apertures enable positioning augmentation and emergency messaging in remote coverage gaps. These modules command premium pricing due to qualification requirements from agencies including FCC and ETSI.
5G architectures are climbing the fastest, while 3G faces accelerated displacement.
End User:
Volume concentration varies dramatically across the supply chain, with OEM direct procurement favoring suppliers capable of vehicle-level electromagnetic validation.
- OEMs:Tesla, BYD, and Volkswagen Group specify antenna performance at platform level, compressing tier-1 supplier margins but locking in multi-year supply agreements. Direct OEM relationships require in-house electromagnetic simulation capabilities and multi-homologation expertise across FCC, ETSI, and MIIT pathways.
- Tier-1 Suppliers:Continental AG, TE Connectivity, and Yageo intermediate between antenna specialists and vehicle assemblers, capturing value through module integration and logistics coordination. These firms co-locate engineering teams with OEM platform development centers in the Yangtze River Delta and Stuttgart region.
- Vehicle Assemblers:Contract manufacturers and joint venture operations in India and Southeast Asia procure pre-certified antenna modules from established tier-1 suppliers rather than developing direct sourcing relationships.
- Aftermarket Providers:Insurance telematics mandates in European markets and fleet retrofit demand in North America sustain niche demand for plug-and-play antenna kits with simplified installation protocols.
Procurement gravity centers on OEMs and tier-1 integrators; aftermarket expansion depends on regulatory mandates.
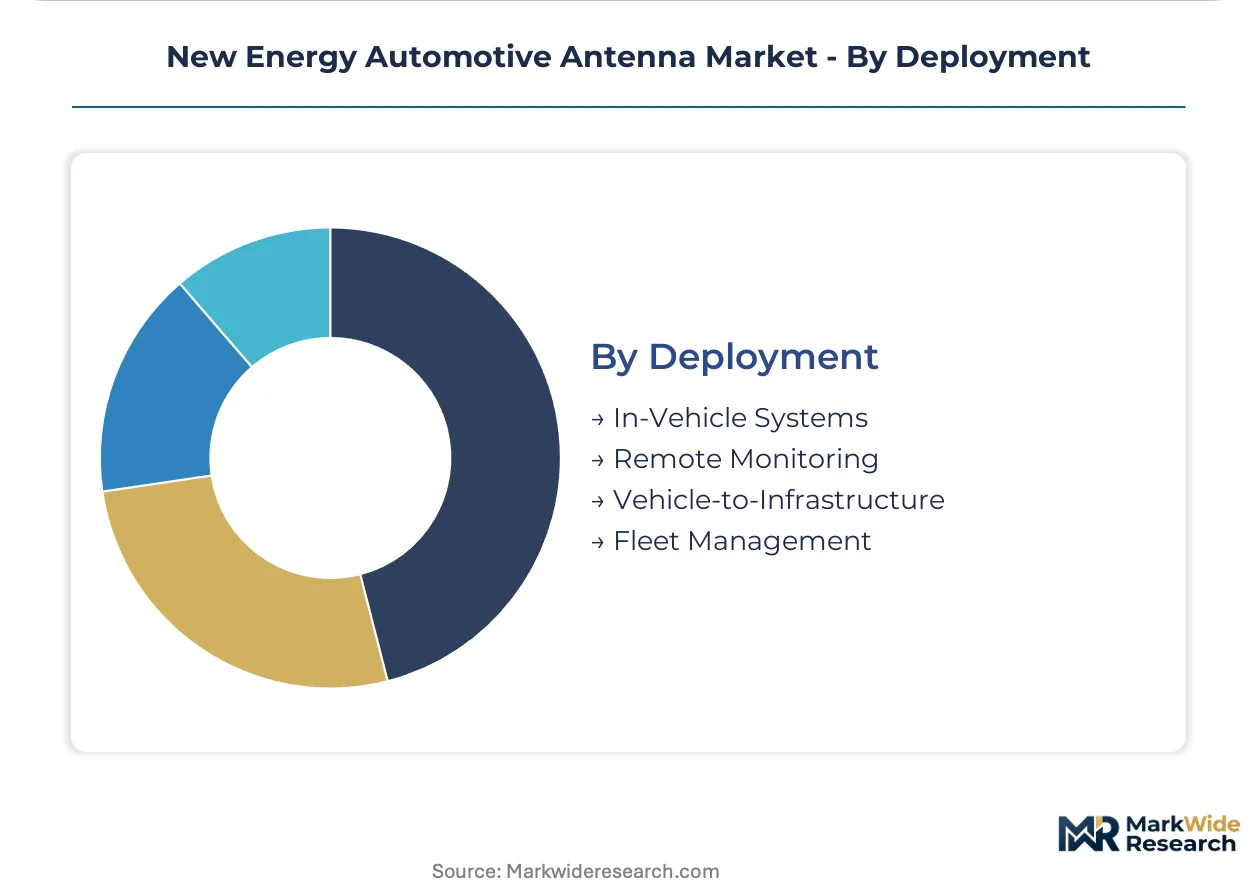
Deployment:
Application maturity diverges sharply, with in-vehicle connectivity approaching commodity status while V2X infrastructure remains nascent.
- Vehicle-to-Infrastructure:C-V2X PC5 interface antennas enable direct communication with traffic signals and roadside units without cellular network dependency. China's MIIT certification requirements for connected vehicles are creating dedicated demand for V2X modules in domestic EV platforms. These deployments require coordination with municipal infrastructure investment cycles.
- In-Vehicle Systems:Cabin-mounted antennas for Wi-Fi hotspot, Bluetooth, and UWB key fob localization are standard equipment across all price tiers. Module specifications are tightening as OEMs integrate antenna arrays into interior trim components.
- Fleet Management:Commercial vehicle operators specify antenna performance through guaranteed connectivity uptime metrics rather than hardware specifications alone. This behavioral shift concentrates demand on suppliers with captive installation networks.
- Remote Monitoring:Battery electric vehicle platforms require persistent telemetry for thermal management and charge state optimization, driving demand for ruggedized antennas with automotive-grade temperature and vibration tolerance.
In-Vehicle Systems dominate current volumes. Vehicle-to-Infrastructure offers the steepest expansion trajectory as C-V2X mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF engineering talent clusters in Stuttgart, Shanghai, and Nagoya anchor antenna development for next-generation vehicle platforms. These metropolitan concentrations house electromagnetic simulation labs and vehicle-level testing facilities that compress homologation timelines. Regional regulatory divergence on spectrum allocation and emission standards fragments procurement strategies across major automotive markets.
China
BYD and NIO production volumes pull multi-band antenna demand through the Yangtze River Delta manufacturing corridor. MIIT connected-vehicle certification mandates for C-V2X modules force suppliers to maintain parallel validation labs in Shanghai and Beijing. Tier-1 antenna specialists co-locate engineering teams with Tesla Shanghai and domestic OEM platform centers to enable same-day prototype iteration.
Germany
Volkswagen Group and BMW platform consolidation around 800-volt architectures multiplies RF performance requirements per vehicle. ECHA REACH restrictions on halogenated flame retardants extend material qualification timelines for antenna housing resins. Stuttgart and Munich host captive electromagnetic simulation centers where Continental AG and Robert Bosch GmbH validate multi-homologation performance before platform freeze.
United States
Fleet operators in Michigan and California specify antenna performance through connectivity uptime service agreements rather than hardware procurement. FCC certification requirements for 5G NR and C-V2X direct communication diverge from ETSI and MIIT testing protocols on spurious emission limits. Detroit-area tier-1 suppliers maintain parallel validation labs to serve both domestic OEMs and export programs.
Japan
Harada Industry Co. Ltd and DENSO Corporation anchor domestic supply relationships with Toyota and Honda through shark-fin form factor specialization. METI carbon neutrality roadmaps accelerate BEV platform shifts that displace legacy passive antenna architectures. Nagoya and Tokyo metropolitan clusters concentrate RF substrate manufacturing for liquid crystal polymer supply to high-frequency antenna designs.
India
Maruti Suzuki and Tata Motors EV programs create pull-through demand for localized antenna module production under the PLI scheme for auto components. TRAI spectrum allocation decisions for C-V2X deployment remain pending, compressing supplier preparation timelines. Tamil Nadu and Gujarat automotive corridors attract tier-1 suppliers establishing captive manufacturing for domestic OEM just-in-sequence delivery.
New Energy Automotive Antenna Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists for platform-level design wins in antenna module supply. The vendor base stratifies into three tiers: integrated automotive electronics suppliers with captive RF capabilities, connectivity-focused component specialists, and regional antenna fabricators serving single OEM relationships. Market structure favors suppliers with backward integration into semiconductor packaging and ceramic substrate manufacturing. Consolidation pressure intensifies as active antenna architectures displace legacy passive designs and smaller suppliers face stranded tooling exposure.
Within the diversified automotive electronics tier, Continental AG and Robert Bosch GmbH occupy positions anchored by captive electromagnetic simulation and multi-homologation expertise. TE Connectivity represents the connectivity-specialist archetype with high-volume production capabilities for 5G-ready modules. Harada Industry Co. Ltd exemplifies the form-factor-focused specialist model that dominates Japanese domestic OEM supply relationships through proprietary molding processes.
| Leading Market Players |
|---|
| Continental AG |
| DENSO Corporation |
| TE Connectivity |
| Ficosa International SA |
| HELLA GmbH & Co. KGaA |
| Robert Bosch GmbH |
| Harada Industry Co. Ltd |
| Kathrein SE |
| NXP Semiconductors |
| Others |
Pricing and Supply Chain Analysis
Active antenna architectures are displacing legacy passive designs, simultaneously compressing module economics and concentrating procurement power among suppliers with captive semiconductor packaging capabilities. This technology transition forces tier-2 fabricators to absorb margin erosion or exit, while integrated players capture value from embedded amplification and filtering stages.
Pricing Analysis
The bundled-vs-unbundled service split separates hardware-only transactions from connectivity-uptime contracts. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with MIIT-connected-vehicle certification commanding substantial premiums. Price differentiation hinges on multi-homologation expertise and after-sales diagnostic bundling. Cost compression in passive architectures is intensifying because OEMs treat basic connectivity as commodity input. Fleet operators show least price sensitivity, while economy EV platforms exhibit maximum procurement pressure.
Supply Chain Analysis
Single-source vulnerability sits with Japanese chemical conglomerates controlling liquid crystal polymer substrate supply for high-frequency designs. Manufacturing gravity centers on China, Germany, and Japan, with the Yangtze River Delta hosting dense tier-1 co-location with BYD and Tesla Shanghai. Raw material dependencies span ceramic-filled PTFE laminates, low-noise amplifier semiconductors, and halogen-free housing resins. Regulatory restriction from ECHA REACH compliance extends material qualification timelines. Distribution runs through just-in-sequence logistics loops serving OEM platform freeze schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with China's MIIT connected-vehicle certification mandates creating structural demand pull-through for C-V2X-enabled antenna modules.
For Market Incumbents: Cement platform-level design wins by deepening backward integration into semiconductor packaging and ceramic substrate manufacturing. Acquire electromagnetic simulation capabilities to compress multi-homologation timelines before rival module integrators consolidate tier-2 fabricators facing stranded tooling exposure from passive architecture obsolescence. For New Entrants and Emerging Players: The premium-to-economy price-point gap in 5G-ready modules offers white-space entry for mid-tier suppliers with sub-6 GHz specialization. Target India's PLI scheme for auto components localization, where Maruti Suzuki and Tata Motors EV programs lack domestic antenna module sourcing. Lead with insurance telematics retrofit kits for European aftermarket mandates. For Investors and Strategic Acquirers: Valuations sit cheapest among regional antenna fabricators with single-OEM relationships and legacy passive tooling. Long-term viability favors targets with in-house RF simulation talent and MIIT/FCC/ETSI certification track records. Watch C-V2X spectrum allocation decisions in India and Southeast Asia as inflection indicators for geographic demand migration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Homologation Certification Investment | Compresses platform freeze timelines for suppliers serving Tesla, BYD, and Volkswagen Group simultaneously. |
| Backward Integration into Substrate Manufacturing | Absorbs margin pressure from Japanese chemical conglomerate supply concentration for liquid crystal polymer. |
| C-V2X Module Localization Partnership | Captures MIIT-mandated demand in Yangtze River Delta cluster through same-day logistics loops. |
| Active Architecture R&D Expansion | Displaces stranded passive tooling at smaller suppliers while embedding low-noise amplification capabilities. |
| Insurance Telematics Channel Development | Opens aftermarket retrofit demand from European usage-based insurance mandates requiring real-time data transmission. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and electromagnetic simulation specialists with secondary validation. Sources included vehicle production databases, MIIT radio type approval filings, ETSI harmonized standards documentation, and customs records for low-loss substrate trade flows. Bottom-up antenna module shipment estimates and top-down OEM platform connectivity specifications were triangulated to anchor volume assumptions.
Comparable-period anchoring linked historical platform adoption curves for 4G LTE modules to projected 5G NR and C-V2X penetration rates across the analysis window. Segmentation dimensions spanned product architecture, connectivity protocol, end-user procurement tier, and regional regulatory cluster. CAGRs were derived from fitted adoption curves incorporating OEM platform freeze schedules and certification timeline constraints. Forecast inputs included MIIT mandate implementation pacing and ECHA REACH compliance cost pass-through assumptions.
The model assumes a particular technology adoption path; alternative pathways for mmWave antenna integration would alter the outlook. Forecasts reflect assumptions about C-V2X infrastructure deployment coordination and liquid crystal polymer supply elasticity. Spectrum reallocation decisions or accelerated 3G network sunsets could revise module demand trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Japan X by Wire Systems Market
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
Automotive LED Market
Automotive Electrical & Electronics
Automotive Starting System Market
Automotive Electrical & Electronics
Automotive Alternator Market
Automotive Electrical & Electronics
Automotive Ecall Market
Automotive Electrical & Electronics
Automotive Electronic Control Unit Market
Automotive Electrical & Electronics
Automotive Magnetic Sensor Market
Automotive Electrical & Electronics
Automotive Electric Power Steering ECU Market
Automotive Electrical & Electronics
Stepper Motors Market
Automotive Electrical & Electronics
Automotive Camera Market
Automotive Electrical & Electronics
Automotive E-Axle Disconnect Actuator Market
Automotive Electrical & Electronics
Automotive Thermal Management System Market
Automotive Electrical & Electronics
India Automotive Sensors Market
Automotive Electrical & Electronics
Commercial Vehicle Switches and Relays Market