
 Europe Automotive Camera Market | 2026-2036
Europe Automotive Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Camera Market Analysis
Commercial vehicle fleets is repositioning procurement priorities toward surround-view and driver-monitoring configurations across European logistics operators. Valeo SA leverages its vertically integrated lens-to-software pipeline to dominate premium OEM contracts. Continental AG sustains engineering density in Stuttgart and Hanover through dedicated ADAS research centers. Robert Bosch GmbH anchors volume supply relationships with major German and Swedish vehicle assemblers.
Europe Automotive Camera denotes a vision-sensing subsystem integrating solid-state image sensors, typically CMOS arrays with 1.3 to 8 megapixel resolution, signal-processing chipsets, and automotive-grade housing rated for temperatures spanning minus forty to eighty-five degrees Celsius; its primary commercial purpose is real-time environmental perception to enable automated braking, lane-keeping, and parking maneuvers. Front Camera modules command the largest revenue share due to mandatory emergency braking preconditions under Euro NCAP protocols. Surround View Camera configurations represent the fastest-expanding product category as luxury and mass-market OEMs converge on three-hundred-sixty-degree perception stacks. CMOS technology leads unit economics against legacy CCD alternatives through superior low-light sensitivity and reduced power draw.
The EU AI Act, Euro NCAP testing protocols, and ECE R79 steering regulations collectively mandate minimum camera resolution and latency thresholds for any vehicle claiming automated lane-keeping or emergency intervention capability. EMA and national type-approval authorities in Germany, France, and Italy enforce these standards through homologation gates that block non-compliant systems from series production. Stakeholders must monitor whether forthcoming delegated acts under the EU AI Act expand algorithmic transparency requirements to camera-based perception software.
Market Dynamics
Fleet operators across European logistics corridors are consolidating camera specifications into unified surround-view and driver-monitoring bundles, compressing procurement cycles and forcing tier-one suppliers to restructure software-hardware integration roadmaps around Euro NCAP timelines.
Growth Catalysts
- Euro NCAP 2026 protocols:Mandatory camera-based emergency braking and lane-keeping assist preconditions create binding demand pull across all vehicle classes sold in EU member states.
- CMOS sensor migration:Solid-state imaging arrays with enhanced low-light sensitivity are displacing legacy CCD architectures in front-camera modules, reducing power draw and thermal management costs.
- German premium OEM corridor:Stuttgart, Munich, and Wolfsburg assembly clusters concentrate engineering procurement for Level 2+ perception stacks, anchoring regional supply chain density.
Market Restraints
- Semiconductor input volatility:Automotive-grade image signal processors and SerDes chipsets face allocation constraints from foundry capacity competition with consumer electronics.
- Homologation timeline friction:ECE R79 steering regulation amendments and delegated acts under the EU AI Act extend type-approval cycles, delaying series production ramps.
- Lidar substitution pressure:Solid-state lidar cost curves in highway automation applications threaten camera-dominant perception architectures above Level 2 functionality.
Strategic Opportunities
- Eastern European fleet penetration:Polish, Czech, and Romanian commercial vehicle operators remain underpenetrated for surround-view configurations relative to Western European adoption baselines.
- EU AI Act algorithmic transparency:Delegated acts mandating explainable perception software create first-mover advantages for suppliers with documented training data governance.
- Camera-radar fusion convergence:Integration of 4D imaging radar with 8-megapixel front cameras enables single-sensor-stack redundancy for automated lane-keeping systems.
Industry Challenges
- Embedded vision engineering scarcity:Shortage of automotive perception software architects with ISO 26262 functional safety certification compresses R&D throughput at tier-one suppliers.
- Legacy platform integration complexity:Retrofitting surround-view architectures into mid-cycle vehicle platforms with constrained electrical bandwidth forces costly harness redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Camera Market |
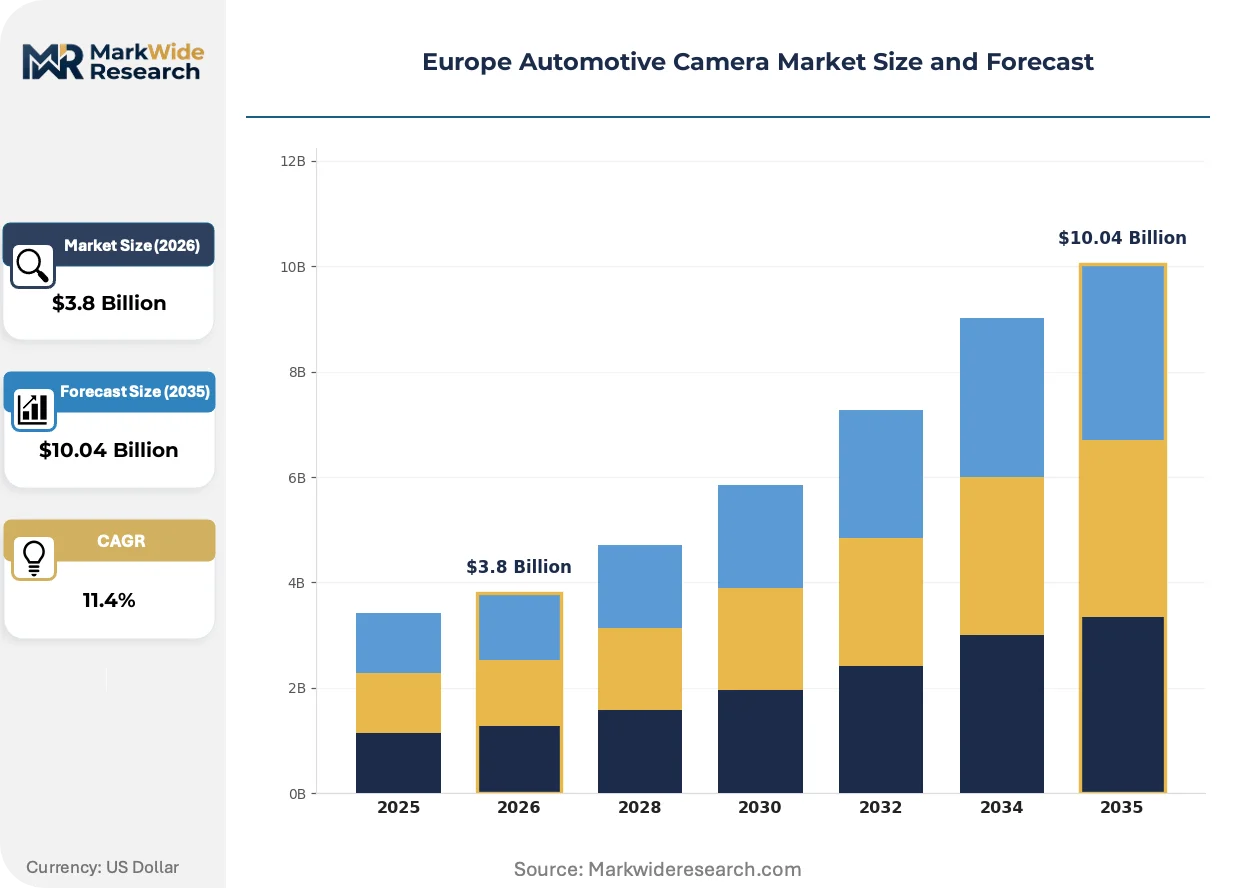
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Camera, Rear Camera, Surround View Camera, Advanced Driver Assistance Systems Technology: CCD, CMOS, Infrared, Night Vision End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Parking Assistance, Lane Departure Warning, Collision Avoidance, Traffic Monitoring |
| Companies Covered | Valeo SA, Magna International Inc., Continental AG, Hella GmbH & Co KGaA, Aptiv PLC, Robert Bosch GmbH, Ficosa Internacional SA, Mobileye NV, ZF Friedrichshafen AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Camera Market Emerging Trajectories
Perception software architectures and sensor fusion methodologies are restructuring competitive advantage around real-time latency benchmarks and training data governance, separating suppliers with captive AI pipelines from hardware-only component vendors.
8-megapixel CMOS front cameras with HDR and LED flicker mitigation are overtaking 1.3-megapixel legacy modules in premium and mass-market OEM programs. German and Swedish vehicle assemblers have accelerated validation timelines for high-resolution stacks. This resolution tier is overtaking mid-range specifications as the baseline for Euro NCAP five-star eligibility, compressing margin structures for suppliers without in-house image sensor design.
The EU AI Act's risk-based classification for automated driving systems imposes documentation burdens on camera-based perception software exceeding Level 2 automation. EMA and KBA homologation authorities are interpreting algorithmic transparency requirements through type-approval gates that demand traceable training data provenance. Front-camera modules with emergency braking functionality face the most intensive scrutiny, forcing suppliers to restructure development workflows around documented AI governance.
Logistics fleet operators are consolidating camera procurement through long-term supply agreements with direct tier-one relationships, bypassing traditional aftermarket distribution channels. Large European haulage groups with centralized technical specifications now negotiate surround-view and driver-monitoring bundles at the corporate level. This concentration is most visible in German and Dutch commercial vehicle markets, where procurement functions have absorbed technical specification authority from regional maintenance divisions.
Europe Automotive Camera Market Segmentation
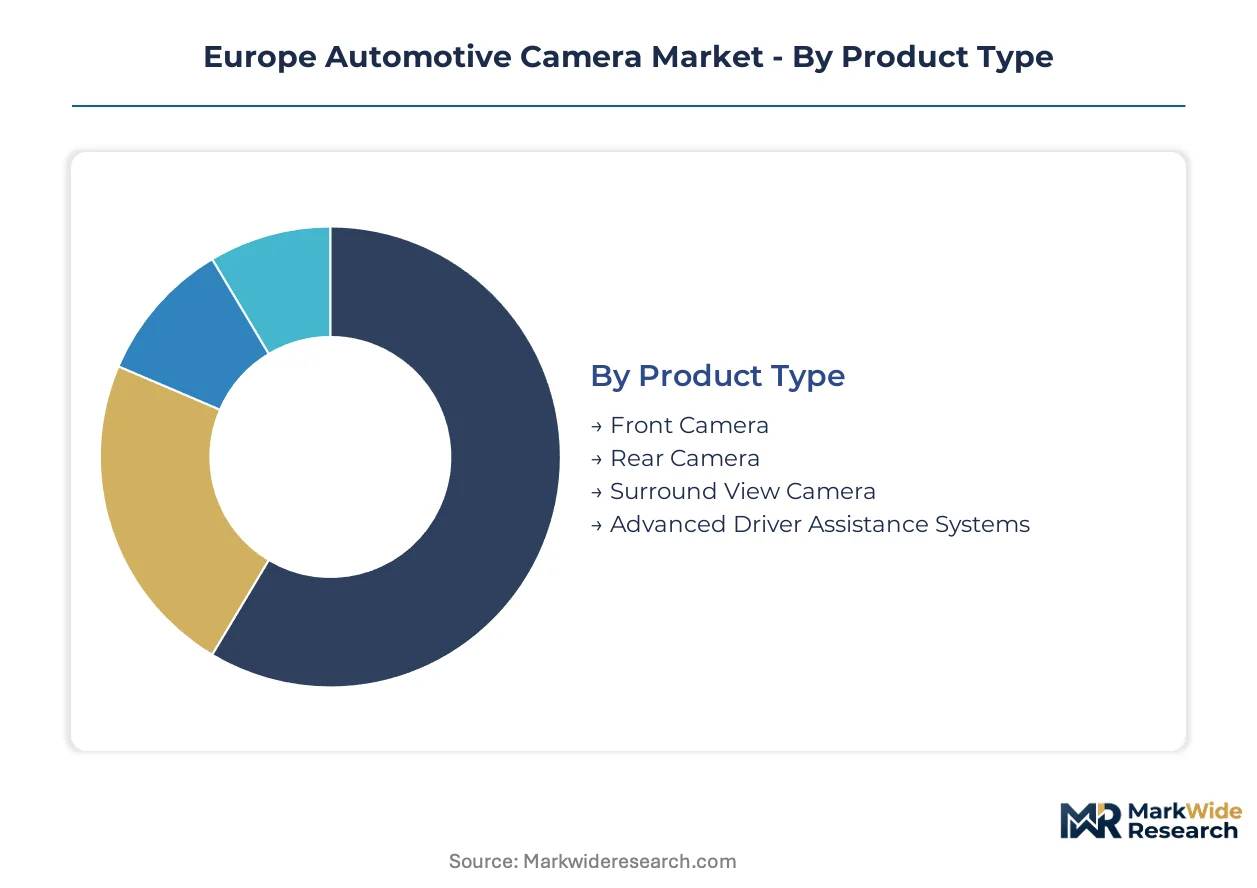
Camera module specifications diverge sharply across vehicle price tiers and automation levels. Procurement patterns in European automotive clusters concentrate engineering resources on high-resolution front-facing arrays while surround-view configurations penetrate commercial fleets at accelerating rates.
Product Type:
Capital intensity peaks with surround-view architectures requiring synchronized multi-camera calibration and centralized image processing units.
- Front Camera:Single-module units positioned behind windshields integrate 1.3 to 8 megapixel CMOS sensors with HDR processing for emergency braking preconditions under Euro NCAP protocols. German premium OEMs in Stuttgart and Munich anchor procurement volumes for Level 2+ perception stacks, compressing supplier margins through consolidated specification authority.
- Surround View Camera:Four to six synchronized modules generate stitched three-hundred-sixty-degree environmental models demanding precise geometric calibration and thermal management across minus forty to eighty-five degrees Celsius operating ranges. Dutch and German logistics fleet operators are consolidating procurement through long-term tier-one supply agreements, bypassing traditional aftermarket channels.
- Rear Camera:Single-point modules for parking assistance carry lower resolution requirements and standardized mounting interfaces.
- Advanced Driver Assistance Systems:Integrated perception stacks combining cameras with radar and ultrasonic sensors.
Front Camera absorbs the bulk of installed capacity; Surround View Camera is expanding most quickly.
Technology:
Sensor architecture selection determines power budgets, thermal profiles, and low-light performance thresholds across Nordic winter operating conditions.
- CMOS:Solid-state imaging arrays with reduced power draw and enhanced sensitivity are displacing legacy alternatives in volume production programs. Swedish vehicle assemblers have accelerated validation timelines for 8-megapixel specifications with LED flicker mitigation.
- CCD:Charge-coupled devices persist in specialized night-vision applications requiring extended exposure control.
- Infrared:Thermal imaging modules for pedestrian detection in zero-illumination environments.
- Night Vision:Near-infrared augmented systems with active illumination for unlit rural roadways.
CMOS dominates production volumes; Night Vision commands premium positioning in German luxury segments.
End User:
Procurement authority is migrating from regional maintenance divisions toward centralized technical specification functions at fleet headquarters.
- OEMs:German premium vehicle manufacturers in Wolfsburg, Stuttgart, and Munich exercise direct engineering oversight of perception stack validation.
- Tier-1 Suppliers:Valeo SA and Continental AG structure software-hardware integration roadmaps around Euro NCAP timeline requirements.
- Aftermarket Providers:Independent distributors face compression as logistics operators consolidate through direct tier-one relationships.
- Vehicle Assemblers:Contract manufacturers with limited electrical architecture bandwidth.
OEMs retain specification authority; Tier-1 Suppliers capture expanding integration scope.
Application:
Functional safety certification requirements under ISO 26262 vary dramatically across intervention timing windows and failure-mode criticality.
- Collision Avoidance:Emergency braking functionality demands sub-one-hundred-millisecond latency from image acquisition to actuator command, triggering the most intensive EU AI Act algorithmic transparency scrutiny.
- Lane Departure Warning:Road-edge detection systems with lower criticality ratings permit relaxed homologation timelines.
- Parking Assistance:Low-speed maneuvering with ultrasonic sensor fusion.
- Traffic Monitoring:Surrounding vehicle trajectory prediction for adaptive cruise control.
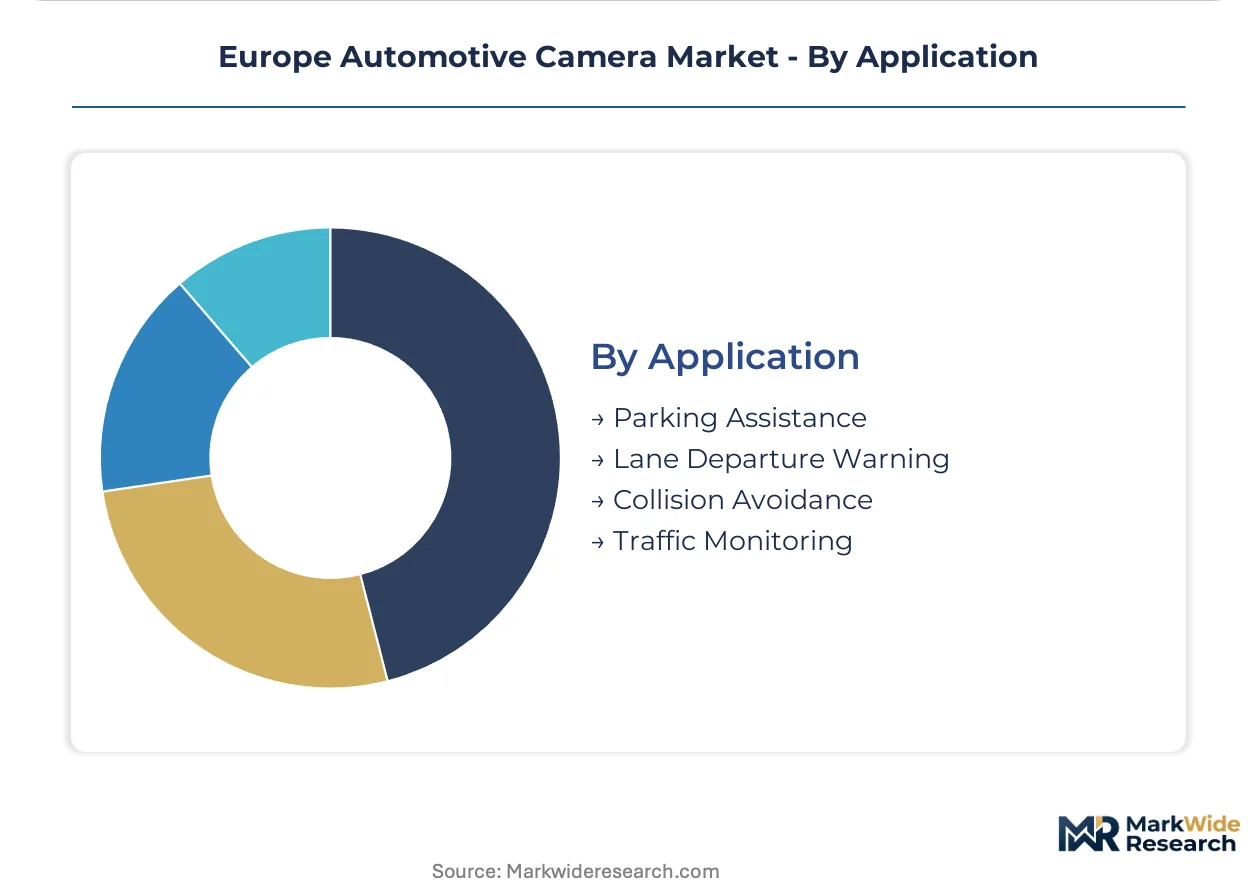
Collision Avoidance carries the heaviest compliance burden; Lane Departure Warning scales most rapidly across mass-market platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive special-economic zones and R&D tax incentives concentrate camera module engineering around Stuttgart, Munich, and Wolfsburg, drawing tier-one suppliers into dense supplier corridors.
Germany
KBA homologation authorities enforce Euro NCAP camera-resolution mandates through type-approval gates that block non-compliant systems. Stuttgart anchors Level 2+ perception stack procurement for premium OEMs, with Continental AG and Robert Bosch GmbH maintaining dedicated ADAS research centers. Munich assemblers accelerate validation timelines for 8-megapixel front-camera specifications.
France
ANSM and CNIL interpret EU AI Act algorithmic transparency requirements through delegated acts affecting camera-based perception software. Paris-region engineering clusters concentrate on surround-view system integration for luxury vehicle programs. Valeo SA leverages vertically integrated lens-to-software pipelines to dominate premium OEM contracts.
Sweden
Vehicle assemblers in Gothenburg and Stockholm validate high-resolution CMOS specifications with LED flicker mitigation for Nordic winter operating conditions. The Swedish Transport Agency aligns national type-approval with ECE R79 steering regulations. Engineering procurement concentrates on camera-radar fusion architectures for automated lane-keeping systems.
Netherlands
Dutch logistics fleet operators consolidate surround-view and driver-monitoring procurement through long-term tier-one supply agreements. EMA coordinates with national regulators on EU AI Act implementation timelines for commercial vehicle automation. Rotterdam and Eindhoven clusters concentrate on fleet-scale technical specification authority migrating from regional maintenance divisions.
Poland
Commercial vehicle operators in Warsaw and Krakow corridors remain underpenetrated for surround-view configurations relative to Western European adoption baselines. Polish automotive regulators align with EU-wide Euro NCAP protocols through delegated harmonization procedures. Eastern European fleet penetration represents a structural expansion opportunity as procurement standardization spreads.
Europe Automotive Camera Market Vendor Landscape
Top-tier vendors anchor premium OEM supply relationships, while mid-scale specialists occupy fleet-integration niches. The vendor base structures around three tiers: vertically integrated system houses, component-focused module suppliers, and software-centric perception stack developers. Strategic moves concentrate on backward integration into image sensor design and geographic expansion into Eastern European fleet markets.
Within the vertically integrated tier, Valeo SA and Continental AG exemplify archetypes combining captive lens production with algorithm development pipelines. Robert Bosch GmbH anchors volume supply positioning with German and Swedish vehicle assemblers. These three entities represent the dominant competitive anchors structuring procurement authority around Euro NCAP timeline requirements.
| Leading Market Players |
|---|
| Valeo SA |
| Magna International Inc. |
| Continental AG |
| Hella GmbH & Co KGaA |
| Aptiv PLC |
| Robert Bosch GmbH |
| Ficosa Internacional SA |
| Mobileye NV |
| ZF Friedrichshafen AG |
| Others |
Supply Flow & Price Mechanics
German premium OEM procurement clusters in Stuttgart, Munich, and Wolfsburg anchor contract-based pricing with long-term offtake structures that reward volume scale and certification tier alignment. Pricing power concentrates with tier-one suppliers holding in-house image sensor design and ISO 26262 functional safety certification, compressing margins for module-only vendors.
Pricing Analysis
Short lead-time premiums apply to emergency braking front-camera modules facing Euro NCAP 2026 protocol deadlines, while spot inventory discounts emerge for legacy 1.3-megapixel specifications. Three-tier pricing structure across premium, standard, and economy levels separates 8-megapixel HDR stacks with LED flicker mitigation from mid-range 2-megapixel units and entry-level parking assistance modules. Cost compression in mid-tier specifications is intensifying because CMOS sensor foundry allocation constraints force tier-two suppliers toward price concessions. Fleet procurement functions in Dutch and German logistics corridors demonstrate highest price sensitivity, while premium OEM engineering departments prioritize latency benchmarks over unit cost.
Supply Chain Analysis
Freight cost volatility from Asian semiconductor foundries to German assembly corridors elevates landed costs for automotive-grade image signal processors and SerDes chipsets. Manufacturing concentration centers on Germany for lens-to-module integration, Taiwan and South Korea for CMOS wafer fabrication, and Japan for specialized optical glass. Raw material dependencies include rare-earth elements for lens coatings, high-purity silicon for sensor substrates, and copper alloys for thermal management housings. Single-source vulnerability characterizes 8-megapixel CMOS array supply from leading foundry operators. Distribution runs through direct tier-one contracts with OEM platform engineering teams, bypassing traditional aftermarket wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity constraints for automotive-grade image processors prop pricing premiums across the analysis window. Supply scarcity favors incumbent tier-ones with allocated wafer starts.
For Market Incumbents: Deepen backward integration into CMOS sensor design to defend margin position against commoditization pressure from Chinese module suppliers. Secure dedicated foundry capacity through multi-year supply agreements with Taiwanese and South Korean wafer operators. Prioritize certification investment in EU AI Act algorithmic transparency documentation to maintain homologation gate access. For New Entrants and Emerging Players: Camera-radar fusion algorithms offer entry leverage into Swedish and German automated lane-keeping supply chains where incumbent software stacks remain unconsolidated. Polish and Romanian commercial fleet corridors present the most penetrable geography for surround-view bundle penetration. Pursue direct technical specification relationships with centralized procurement functions at large logistics operators rather than aftermarket distribution partnerships. For Investors and Strategic Acquirers: The window for entry favors tier-one suppliers with captive AI training data governance and documented ISO 26262 functional safety certification. Long-term viability rests on algorithmic transparency capabilities under expanding EU AI Act delegated acts. Watch ECE R79 steering regulation amendment timelines as inflection indicators for camera-dominant versus lidar-fusion architecture shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Image Sensor Design | Captive CMOS wafer access insulates Continental AG and Robert Bosch GmbH from foundry allocation shocks. |
| EU AI Act Algorithmic Transparency Certification | Documented training data provenance satisfies KBA and EMA homologation requirements for emergency braking modules. |
| Eastern European Fleet Market Expansion | Direct tier-one contracts with Polish logistics operators bypass saturated Western European procurement channels. |
| Camera-Radar Fusion Platform Development | 4D imaging radar integration with 8-megapixel front cameras enables single-sensor-stack redundancy for Level 2+ systems. |
| Long-Term Foundry Capacity Reservation | Multi-year wafer agreements with Taiwanese semiconductor manufacturers secure supply priority during consumer electronics demand spikes. |
Methodological Framework
Vehicle production databases, IHS Markit registration data, and Euro NCAP protocol documentation formed the secondary backbone for volume and specification analysis. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet technical specification managers validated secondary findings. Bottom-up and top-down triangulation reconciled module shipment data with vehicle installation rates across German, French, and Swedish production clusters.
Bottom-up modeling built forecasts from segment-level content-per-vehicle assumptions and regional production schedules, while top-down validation checked aggregate figures against macro automotive electronics spending patterns. Segmentation dimensions included camera position, resolution tier, vehicle class, propulsion architecture, and OEM premium-mass-market positioning. CAGRs derived from logistic curve fitting to technology adoption patterns and regulatory mandate phase-in schedules. Forecast inputs incorporated Euro NCAP timeline acceleration effects and EU AI Act delegated act implementation uncertainty.
Several conditions sit outside the modeled scope, including potential lidar cost curve disruption above Level 2 automation, geopolitical semiconductor trade restrictions, and unannounced OEM platform consolidation decisions. Forecasts reflect assumptions about foundry capacity allocation continuity and regulatory timeline adherence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Airbag Electronic Control Unit Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market
Automotive Electrical & Electronics
Automotive Electric Actuator Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Automotive Alternator and Starter Motor Market
Automotive Electrical & Electronics
E-Bike Lights Market
Automotive Electrical & Electronics
Automotive EMC Test Equipment Market
Automotive Electrical & Electronics
Automotive Magnetic Sensor Market
Automotive Electrical & Electronics
South Korea Electric Power Steering (EPS) Sensor Market
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
Automotive Electronic Manufacturing Services Market
Automotive Electrical & Electronics
Automotive E-Axle Market
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market
Automotive Electrical & Electronics
Automotive Ecall Market
Automotive Electrical & Electronics
India Automotive Camera Market