
 Automotive E-Axle Disconnect Actuator Market | 2026-2036
Automotive E-Axle Disconnect Actuator Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive E-Axle Disconnect Actuator Market Insights
Multi-source procurement for precision-machined actuator housings and electromagnetic subassemblies is hardening as OEMs reduce single-supplier exposure in electrified drivetrains. ZF Friedrichshafen leverages its integrated e-axle portfolio to bundle disconnect actuators with torque-vectoring modules. Continental sustains development velocity through dedicated electromagnetic laboratories in Stuttgart and Shanghai. Robert Bosch anchors its position via captive motor-winding capacity and software-defined clutch control algorithms.
An automotive e-axle disconnect actuator is an electromechanical or electromagnetic device that mechanically decouples an electric motor from the driveline when all-wheel-drive torque is unnecessary, typically operating at response times below 100 milliseconds and sustaining torque ratings exceeding 400 Nm to preserve efficiency in battery-electric and hybrid platforms. Brushless DC motor variants dominate current production volumes due to their power density and thermal resilience under sustained highway loads. Electromechanical actuators are capturing margin pools as OEMs phase out hydraulic fluid circuits to simplify assembly and eliminate leak-path liabilities. Stepper motor technology competes for cost-sensitive light-duty applications where positional accuracy requirements are less stringent.
The EPA, NHTSA, and EU F-Gas Regulation collectively mandate driveline efficiency improvements and refrigerant containment that incentivize mechanical decoupling over parasitic losses from permanently engaged e-axles. China's MIIT enforces dual-carbon compliance thresholds that favor actuator-equipped multi-motor architectures in domestic BEV platforms. Stakeholders must monitor how EPA rulemakings on light-duty CO2 standards and EU battery-passport traceability requirements reshape actuator material sourcing and remanufacturing obligations.
Market Dynamics
Electrified all-wheel-drive architectures are forcing actuator suppliers to reconcile sub-100-millisecond response requirements with thermal resilience under sustained highway loads. OEM platform consolidation around battery-electric SUVs and light trucks concentrates procurement leverage among a narrowing set of drivetrain integrators.
Growth Catalysts
- EPA Light-Duty CO2 Standards:Stringent fleet efficiency mandates in the United States compel automakers to eliminate parasitic losses from permanently engaged e-axles, accelerating mechanical decoupling adoption.
- Brushless DC Motor Power Density:Advances in electromagnetic winding techniques enable compact actuator packages that preserve cabin and cargo space in densely packaged BEV platforms.
- China MIIT Dual-Carbon Compliance:Domestic electrification quotas enforce multi-motor architectures with intelligent torque distribution, expanding actuator addressable volume in the world's largest BEV market.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium processing capacity concentrates in China, exposing actuator motor production to geopolitical supply disruptions and export licensing volatility.
- EU F-Gas Thermal System Complexity:Refrigerant containment requirements complicate thermal management integration with electromagnetic actuators, extending validation timelines and engineering overhead.
- Hydraulic Actuator Substitute Persistence:Mature hydraulic disconnect systems retain cost advantages in heavy-duty commercial applications where response-time tolerances exceed 150 milliseconds.
Strategic Opportunities
- India PLI Scheme Electrification:Production-linked incentives for advanced automotive components attract actuator localization for domestic OEMs and export-oriented contract manufacturers.
- Software-Defined Clutch Control:Convergence of motor control algorithms with vehicle-domain architectures enables predictive engagement based on navigation terrain data and driver behavior patterns.
- Remanufacturing Regulatory Tailwinds:EU battery-passport traceability requirements and extended producer responsibility frameworks create circular economy revenue streams for actuator refurbishment services.
Industry Challenges
- Electromagnetic Compatibility Certification:ISO 11452 and CISPR 25 testing protocols for high-voltage actuator systems demand specialized anechoic chamber capacity and extended validation cycles.
- Systems Integration Talent Scarcity:Shortages of engineers fluent in both mechanical driveline design and embedded motor control constrain development velocity at tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive E-Axle Disconnect Actuator Market |
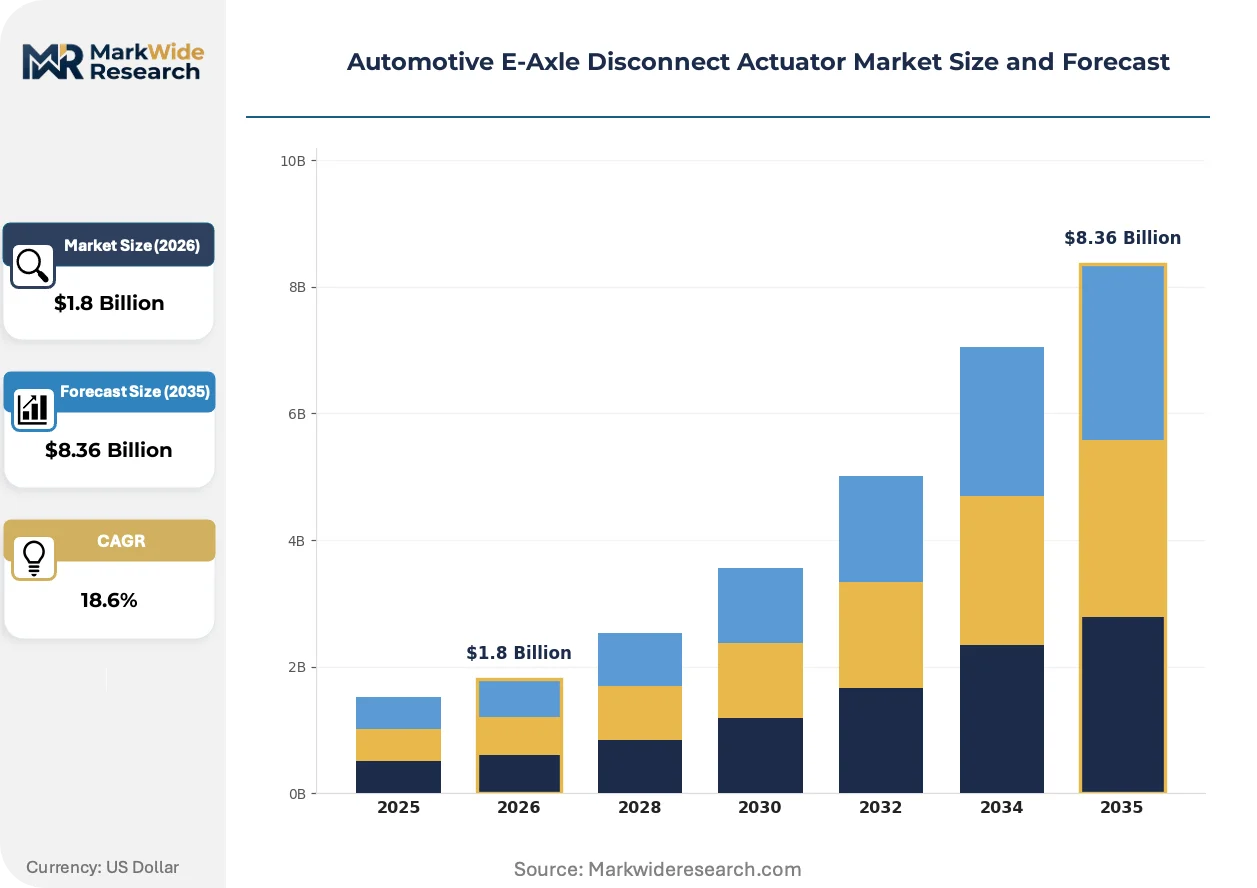
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuators, Hydraulic Actuators, Pneumatic Actuators, Electromechanical Actuators Technology: Brushless DC Motors, Stepper Motors, Servo Motors, Linear Actuators Application: Light-Duty Vehicles, Heavy-Duty Vehicles, Commercial Transport, Passenger Cars End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Robert Bosch, Continental, ZF Friedrichshafen, Denso, Valeo, Nidec, Aisin, GKN Automotive, Magna International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive E-Axle Disconnect Actuator Market Trends and Innovations
Actuator architectures are converging around electromechanical platforms that eliminate hydraulic fluid circuits entirely. This technological pivot compresses assembly complexity while aligning with thermal and emissions regulations tightening across major automotive markets.
Integrated electromagnetic clutch modules are unifying motor-winding, position-sensing, and thermal management into single housings. Tier-one suppliers in Germany and Japan are transitioning production lines to these consolidated packages. This unification is compressing bill-of-material counts and reducing assembly-line footprint requirements for OEM drivetrain plants.
The EU F-Gas Regulation is mandating refrigerant containment protocols that complicate thermal management in electrified drivetrains. Actuator suppliers must now validate electromagnetic performance across expanded temperature ranges without hydraulic cooling loops. European OEMs are responding by specifying actuators with integrated thermal interfaces to battery cooling circuits.
Automaker procurement organizations are consolidating supplier panels for precision-machined housings and electromagnetic subassemblies. Long-term framework agreements with volume commitments are displacing spot-buying for commodity-grade components. This pattern is most visible in Germany and China, where platform-sharing across BEV architectures concentrates purchasing leverage.
Automotive E-Axle Disconnect Actuator Market Segmentation
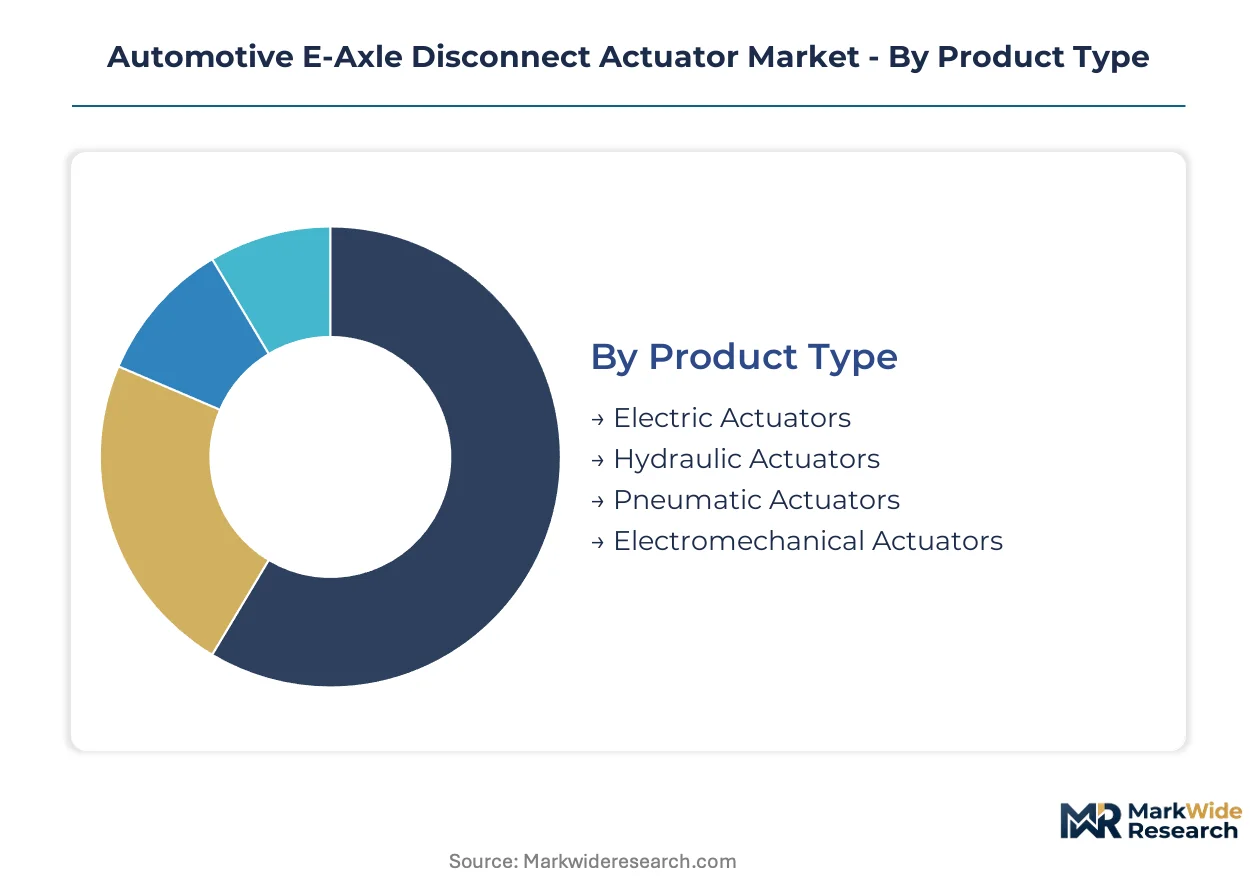
Segmentation reveals where capital deployment and technical risk concentrate across actuator architectures. Procurement patterns diverge sharply between integrated OEM supply chains and fragmented aftermarket channels, while motor technology choices lock in multi-year platform commitments.
Product Type:
Electromechanical platforms demand the steepest upfront tooling investment due to precision-machined housings and electromagnetic winding automation. Hydraulic systems retain lower capital barriers but face rising compliance costs from fluid containment regulations.
- Electric Actuators:Solid-state electromagnetic designs eliminate hydraulic circuits entirely. Demand clusters in Germany and China where OEMs prioritize assembly-line simplification and EU F-Gas thermal compliance over legacy architectures.
- Electromechanical Actuators:Integrated clutch modules unify position-sensing, thermal management, and motor control in single housings. Battery-electric SUV platforms in the United States specify these for sub-100-millisecond response requirements under sustained highway thermal loads.
- Hydraulic Actuators:Mature fluid-power systems persist in heavy-duty commercial segments where response tolerances exceed 150 milliseconds and initial cost sensitivity dominates procurement.
- Pneumatic Actuators:Compressed-air systems occupy niche applications in industrial vehicle conversions and legacy platform retrofits where electrical infrastructure retrofit costs prove prohibitive.
Most installed capacity flows through Electromechanical Actuators. Expansion is steepest in Electric Actuators as OEMs phase out hydraulic circuits to eliminate leak-path liabilities.
Technology:
Brushless DC motor production requires captive rare-earth magnet supply chains and specialized winding equipment, creating the highest fixed-cost barriers to entry. Stepper motor manufacturing scales more readily through standardized component sourcing.
- Brushless DC Motors:Permanent-magnet synchronous designs deliver power density exceeding 5 kW/kg with thermal resilience above 150°C continuous operation. MIIT dual-carbon compliance thresholds in China accelerate procurement for domestic BEV multi-motor architectures.
- Stepper Motors:Open-loop positional control suits cost-sensitive light-duty applications where accuracy tolerances exceed 0.5 degrees. Indian PLI scheme electrification incentives attract stepper actuator localization for entry-level domestic OEM platforms.
- Servo Motors:Closed-loop feedback systems enable predictive clutch engagement algorithms integrated with vehicle-domain controllers. Development concentrates in Stuttgart and Shanghai electromagnetic laboratories.
- Linear Actuators:Direct-drive mechanisms bypass rotary-to-linear conversion losses in specialized torque-vectoring modules. Adoption remains constrained by packaging volume requirements in densely packaged axle assemblies.
Brushless DC Motors absorb the majority of R&D expenditure. Servo Motors are climbing the fastest as software-defined clutch control converges with navigation terrain data integration.
Application:
Heavy-duty vehicle certification cycles impose the longest validation timelines and highest per-unit testing costs, while light-duty platforms amortize development across higher production volumes.
- Light-Duty Vehicles:Battery-electric SUVs and light trucks dominate actuator procurement volumes. EPA light-duty CO2 standards compel mechanical decoupling to eliminate parasitic losses from permanently engaged e-axles.
- Passenger Cars:Compact sedan architectures prioritize packaging efficiency and cabin space preservation. Brushless DC motor variants with integrated thermal interfaces to battery cooling circuits satisfy these constraints.
- Heavy-Duty Vehicles:Commercial truck platforms tolerate longer response times in exchange for durability under cyclical load profiles. Hydraulic substitutes retain cost advantages in this tolerance band.
- Commercial Transport:Fleet operators emphasize total cost of ownership and remanufacturing compatibility. EU battery-passport traceability requirements reshape actuator material sourcing and refurbishment service revenue models.
Light-Duty Vehicles channel the largest share of production capacity. Commercial Transport is expanding most quickly as fleet electrification mandates tighten across Germany and China.
End User:
OEM captive production and long-term framework agreements concentrate procurement leverage, while aftermarket providers face higher inventory carrying costs due to platform fragmentation.
- OEMs:Vertically integrated drivetrain divisions specify actuators within bundled e-axle portfolios. Multi-source procurement policies for precision-machined housings harden as single-supplier exposure reduction becomes a strategic priority.
- Tier-1 Suppliers:Dedicated electromagnetic laboratories and captive motor-winding capacity anchor competitive positioning. Long-term volume commitments with automakers displace spot-buying for commodity-grade subassemblies.
- Vehicle Assemblers:Contract manufacturers serving export-oriented production rely on modular actuator sourcing with standardized mounting interfaces to accommodate multiple OEM platform specifications.
- Aftermarket Providers:Remanufacturing services capture circular economy revenue streams under extended producer responsibility frameworks. Inventory complexity rises with proliferation of BEV platform variants.
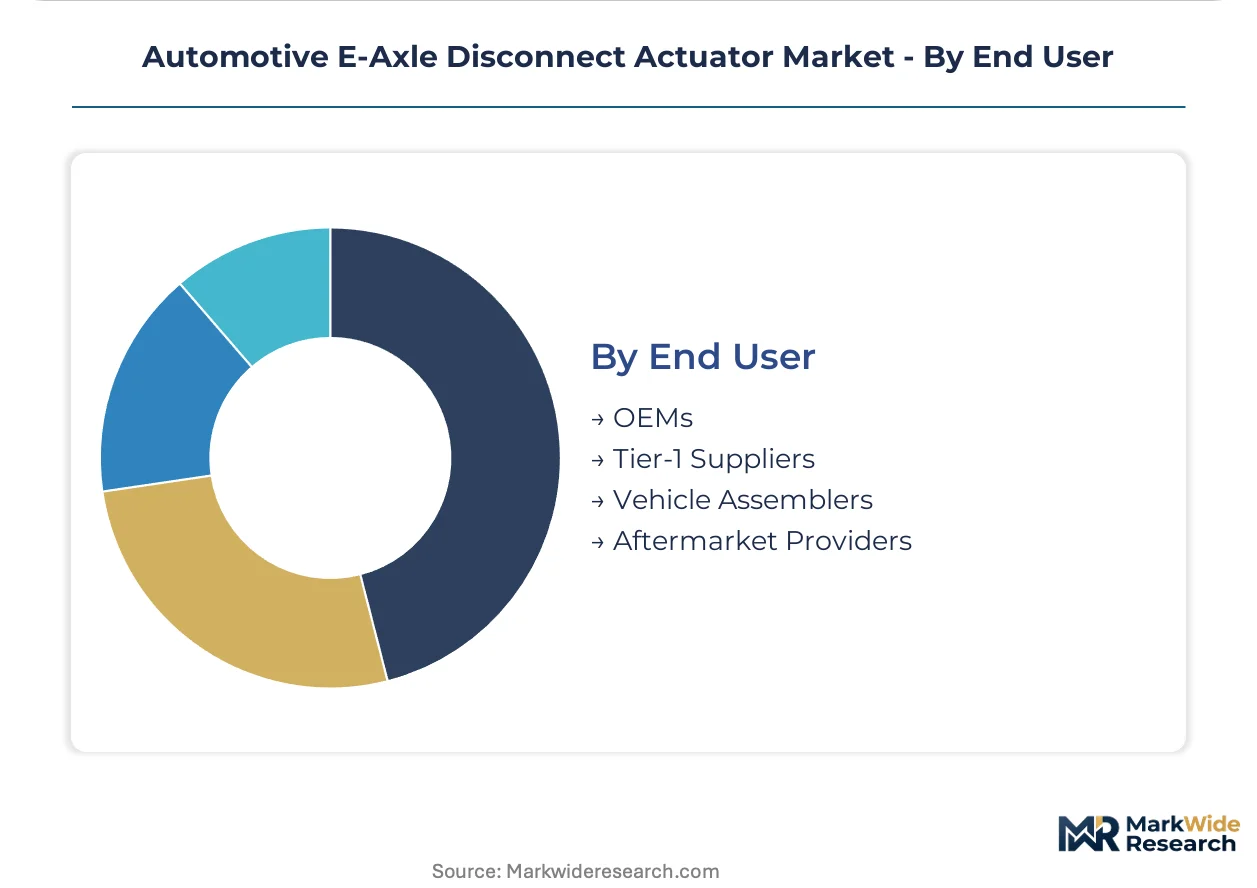
Tier-1 Suppliers control the dominant share of installed production lines. Aftermarket Providers are gaining share fastest as EU regulatory tailwinds strengthen refurbishment service economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Actuator production migrates toward jurisdictions where thermal compliance costs and rare-earth processing tariffs create arbitrage opportunities for drivetrain integrators. OEMs exploit these gaps by qualifying suppliers across multiple regulatory zones while maintaining single-platform engineering specifications.
China
Domestic BEV platforms from BYD and NIO drive procurement volumes for multi-motor disconnect architectures. MIIT dual-carbon compliance thresholds enforce intelligent torque distribution systems that require sub-100-millisecond actuator response. Shanghai and Shenzhen host concentrated electromagnetic laboratory capacity where tier-one suppliers validate thermal resilience above 150°C continuous operation.
Germany
Premium SUV electrification at BMW and Mercedes-Benz concentrates demand for integrated e-axle bundles with torque-vectoring modules. EU F-Gas refrigerant containment mandates complicate thermal management integration, extending validation timelines for electromagnetic actuator suppliers. Stuttgart anchors development velocity through dedicated motor-winding facilities serving both domestic OEMs and export-oriented contract manufacturers.
United States
Light-duty truck electrification at Ford and GM accelerates mechanical decoupling adoption to satisfy EPA fleet CO2 standards. The Inflation Reduction Act domestic content provisions reshape rare-earth magnet sourcing strategies for actuator motor production. Michigan and Tennessee host the primary drivetrain integration plants where multi-source procurement policies for precision-machined housings are hardening.
Japan
Hybrid platform persistence at Toyota and Honda sustains demand for cost-optimized stepper motor variants in entry-level drivetrains. METI carbon neutrality roadmaps favor actuator-equipped multi-motor architectures in next-generation BEV platforms. Nagoya and Tokyo metropolitan areas concentrate electromagnetic compatibility certification capacity for ISO 11452 and CISPR 25 testing protocols.
India
Production-linked incentive schemes for advanced automotive components attract actuator localization for Mahindra and Tata Motors electrification programs. BIS efficiency mandates for domestic commercial transport favor remanufacturing-compatible designs that align with extended producer responsibility frameworks. Tamil Nadu and Gujarat host emerging contract manufacturing clusters serving both domestic OEMs and export markets.
Automotive E-Axle Disconnect Actuator Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined clutch control and integrated thermal management modules. The supplier base concentrates among drivetrain integrators with captive electromagnetic laboratory capacity and long-term framework agreements with OEM platform teams. Two archetypes dominate: diversified automotive conglomerates bundling actuators within e-axle portfolios, and specialized electromagnetic component houses with rare-earth magnet supply chain control. Competitive moves center on multi-source procurement policy enforcement and backward integration into precision-machined housing production.
Among diversified conglomerates, ZF Friedrichshafen AG and Robert Bosch GmbH exemplify the integrated portfolio archetype, each anchoring competitive positioning through bundled e-axle offerings that span disconnect actuators, torque-vectoring modules, and motor control algorithms. Continental AG occupies a position within the electromagnetic specialization tier, with laboratory infrastructure concentrated in Stuttgart and Shanghai that supports validation velocity for thermal resilience requirements. These three entities represent the dominant competitive anchors against which tier-two suppliers and emerging entrants must differentiate through niche thermal interface designs or predictive engagement software.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental |
| ZF Friedrichshafen |
| Denso |
| Valeo |
| Nidec |
| Aisin |
| GKN Automotive |
| Magna International |
| Others |
Pricing and Supply Chain Analysis
Electromechanical actuator platform transitions are compressing assembly complexity while simultaneously redistributing cost economics toward rare-earth magnet supply chains and precision-machining capacity. This technological pivot concentrates pricing power among suppliers with captive motor-winding facilities in China and Germany, while OEM multi-source procurement policies exert countervailing pressure on housing and electromagnetic subassembly margins.
Pricing Analysis
Direct-to-OEM long-term framework agreements handle volume procurement for battery-electric SUV platforms, displacing spot-buying for commodity-grade components. Three-tier pricing structure across premium, standard, and economy levels differentiates by thermal resilience certification and response-time performance, with brushless DC motor variants commanding premiums for sub-100-millisecond specifications. Cost compression in stepper motor tiers is intensifying because Indian PLI scheme localization attracts entry-level suppliers. Fleet operators in commercial transport prove most price-sensitive, while premium German OEMs prioritize thermal interface integration over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from consolidated BEV platform teams at Ford, GM, BMW, and BYD. Neodymium and dysprosium processing capacity concentrates in China, with secondary winding equipment clusters in Germany and Japan. Rare-earth magnet dependencies and precision-machined aluminum housing requirements expose production to export licensing volatility from Chinese SAMR oversight. Distribution runs through tier-one drivetrain integrators with captive electromagnetic laboratories, though aftermarket refurbishment channels are gaining share under EU extended producer responsibility frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
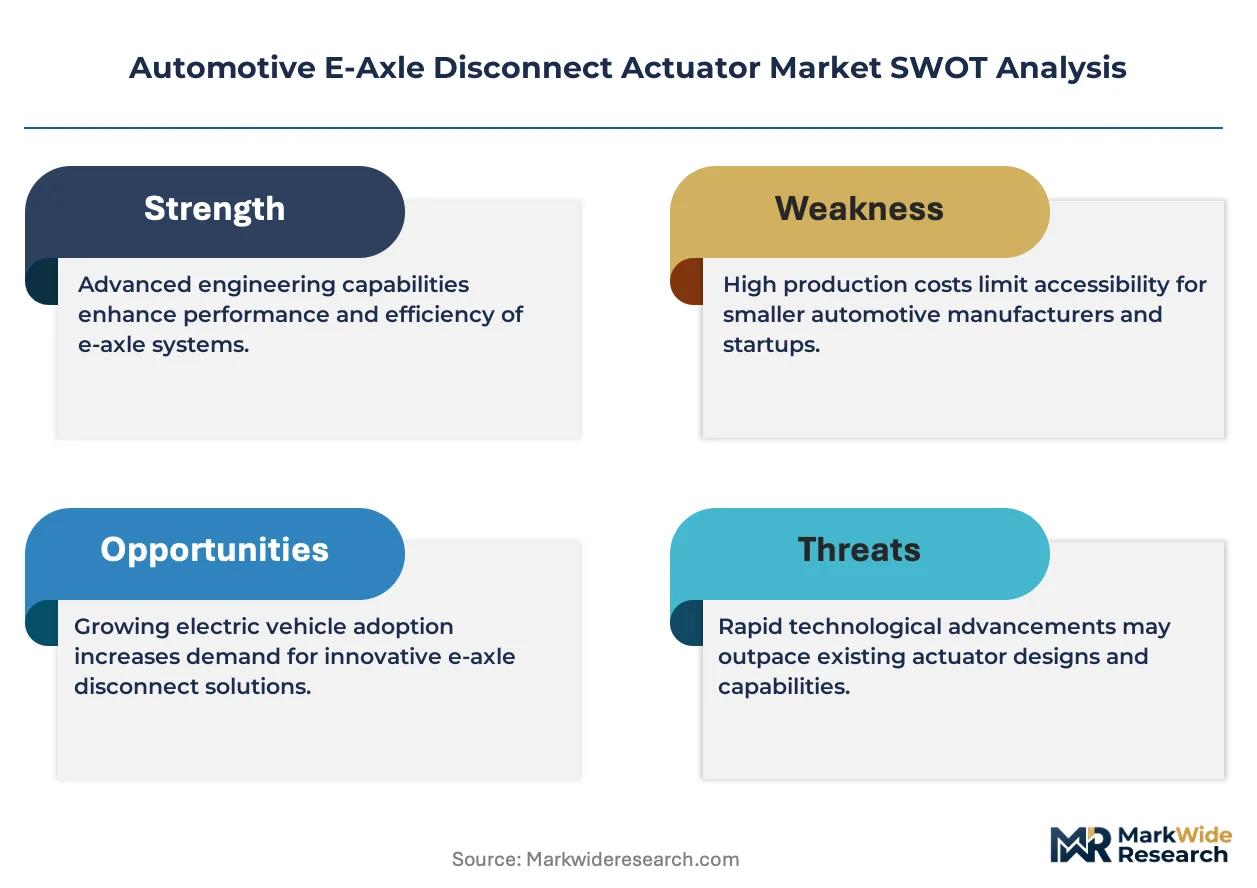
The Automotive E-Axle Disconnect Actuator Market functions as a stable compounder, with regulatory mandates for driveline efficiency and dual-carbon compliance creating durable procurement tailwinds across multiple regulatory jurisdictions.
For Market Incumbents: To counter rare-earth magnet supply concentration, secure dual-source magnet procurement from licensed Chinese processors and alternative Australian rare-earth projects. Deepen backward integration into precision-machined housing production to defend margin position against tier-two Asian suppliers. Prioritize ISO 11452 electromagnetic compatibility certification investment to extend validation barriers around high-voltage actuator architectures. For New Entrants and Emerging Players: Digital aftermarket refurbishment platforms offer the most penetrable route for specialized actuator service providers seeking circular economy revenue streams. Target EU battery-passport traceability requirements as a regulatory wedge to establish remanufacturing credentials before incumbent tier suppliers pivot. Pursue direct fleet operator relationships in commercial transport electrification programs as the primary go-to-market angle, bypassing OEM captive procurement panels. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized electromagnetic component houses with rare-earth magnet supply chain control but limited e-axle bundling relationships. Long-term viability across the analysis window hinges on software-defined clutch control algorithm differentiation and thermal interface IP accumulation. Monitor EPA light-duty CO2 standard rulemaking velocity as the primary inflection indicator for North American procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces tooling costs for OEMs consolidating around battery-electric SUV architectures in Germany and China. |
| Battery Supply Agreement | Secures thermal interface compatibility between actuator cooling circuits and OEM battery management systems. |
| Software-Defined Vehicle Investment | Enables predictive clutch engagement algorithms integrated with navigation terrain data at Continental's Stuttgart laboratory. |
| Geographic Manufacturing Footprint | Localizes production in Tamil Nadu and Gujarat to capture Indian PLI scheme incentives for Mahindra and Tata Motors. |
| Charging Infrastructure Partnership | Aligns actuator thermal validation with high-power charging load profiles in commercial fleet electrification programs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, tier-one supplier procurement leads, aftermarket distributor operations heads, and electromagnetic laboratory technical directors with secondary validation. Primary sources included MIIT dual-carbon compliance filings, EPA light-duty CO2 standard dockets, EU F-Gas Regulation implementation guidance, vehicle production databases, and IHS Markit registration data. Bottom-up actuator shipment modeling and top-down e-axle market sizing were cross-referenced for triangulation.
Segment-weighting approaches distributed value and volume across electromechanical and hydraulic product types, brushless DC and stepper motor technologies, light-duty and heavy-duty vehicle applications, and OEM versus aftermarket end-user channels. CAGRs were derived from regression analysis of historical procurement patterns and regulatory mandate timelines, with automotive-specific inputs including platform-sharing intensity across BEV architectures and rare-earth magnet price elasticity assumptions.
EPA rulemaking delays, MIIT dual-carbon threshold adjustments, and EU battery-passport implementation pace are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented base-case assumptions regarding electrification penetration rates and thermal regulation stringency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
Global Automotive ECU Market
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
EPS Motors Market
Automotive Electrical & Electronics
Electrical Steering Column Lock Market
Automotive Electrical & Electronics
Electric Motor Horn Market
Automotive Electrical & Electronics
Global Automotive Electrical Distribution System Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Automotive Engine Management Sensors Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
Automotive Immersion Cooling Dielectric Fluid Market
Automotive Electrical & Electronics
E-Bike Lights Market
Automotive Electrical & Electronics
Automotive E-Axle Market
Automotive Electrical & Electronics
Stepper Motors Market
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market