
 Automotive EMC Test Equipment Market | 2026-2036
Automotive EMC Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive EMC Test Equipment Market Insights
Multi-source procurement for EMC validation suites is rebalancing toward integrated platform vendors with captive anechoic chamber capabilities. Rohde & Schwarz leverages its vector network analyzer portfolio to anchor premium automotive accounts in Stuttgart and Munich. Keysight Technologies competes through signal integrity instrumentation that extends into 5G-V2X coexistence testing. AMETEK sustains laboratory service contracts with tier-1 suppliers seeking outsourced pre-compliance workflows.
Automotive EMC test equipment comprises shielded enclosures, antenna systems, spectrum analyzers, and signal generators engineered to measure electromagnetic emissions and immunity against CISPR 25 and ISO 11452 thresholds from 150 kHz to 6 GHz. The apparatus validates that power electronics, infotainment modules, and ADAS sensors neither emit disruptive interference nor suffer functional degradation under radiated disturbance. Conducted emission and immunity test systems command the largest installed base, while high-frequency instrumentation for 77-81 GHz radar validation represents the fastest-expanding margin pool. Application demand tilts toward vehicle systems integration over discrete component testing as OEMs consolidate validation gates before platform release.
FCC Part 15 in the United States, ECE R10 across European type-approval regimes, and China's GB/T standards enforced by MIIT collectively mandate pre-market EMC certification for every electronic subsystem. These frameworks compel OEMs and tier-1 suppliers to maintain in-house chambers or secure contracted lab capacity, directly converting regulatory stringency into equipment procurement cycles. Stakeholders must monitor harmonization gaps between regional emission limits and emerging wireless coexistence protocols to calibrate R&D investment and lab expansion timing.
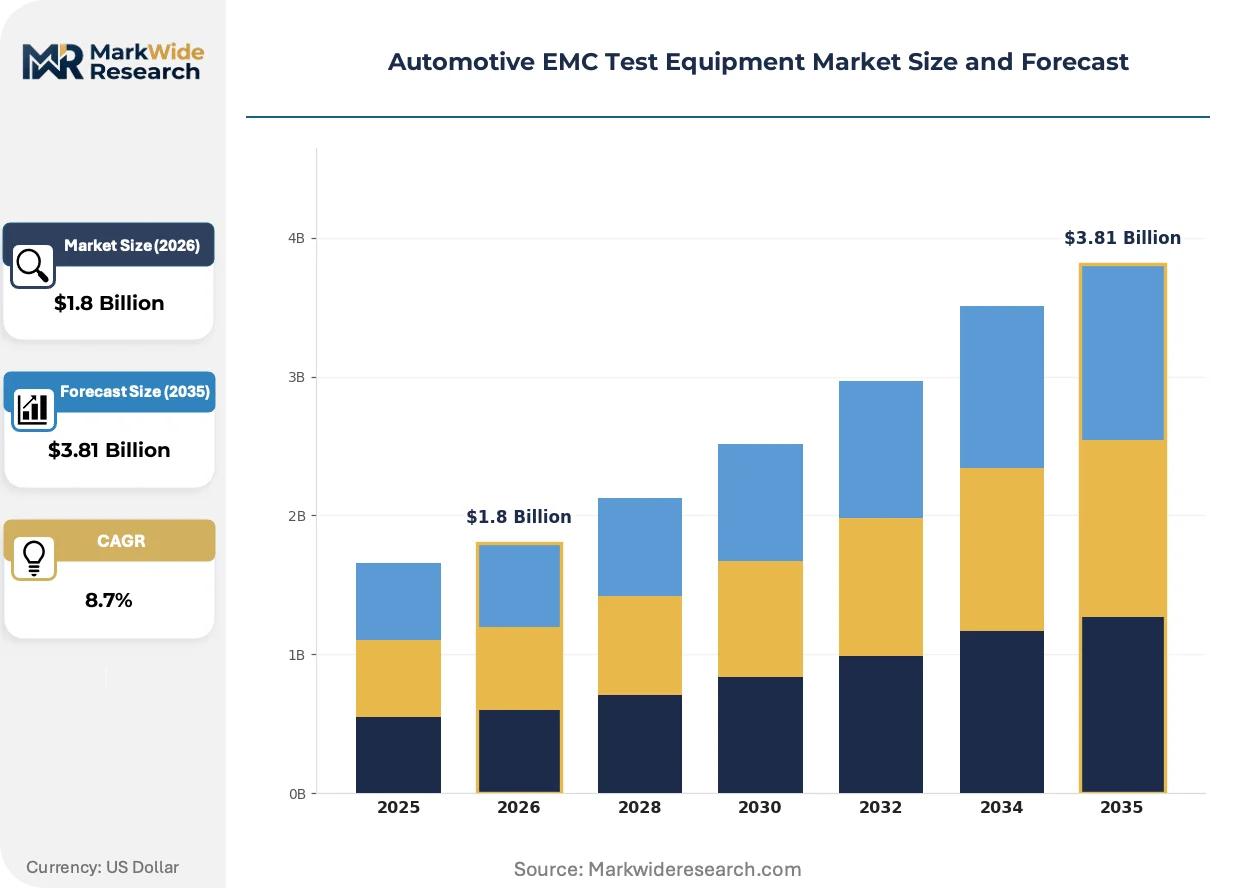
Market Dynamics
Powertrain electrification is compressing EMC validation cycles as OEMs integrate high-voltage inverters, DC-DC converters, and battery management systems into unified platforms requiring simultaneous emission and immunity testing.
Growth Catalysts
- UN ECE R10 Revision 6:Tightened broadband emission limits for electric powertrains force recertification of existing test protocols, driving chamber retrofit demand across German and Japanese engineering centers.
- 77-81 GHz radar proliferation:ADAS sensor density per vehicle is climbing, expanding high-frequency immunity test requirements for automated emergency braking and adaptive cruise control modules.
- China's MIIT GB/T enforcement:Mandatory pre-homologation EMC testing for NEV power electronics creates captive laboratory demand in Shanghai and Shenzhen supplier clusters.
Market Restraints
- Anechoic absorber material costs:Ferrite tile and hybrid foam pricing volatility constrains chamber construction budgets, particularly for mid-tier suppliers in cost-sensitive markets.
- Instrumentation supply concentration:Vector signal generators and real-time spectrum analyzers face extended lead times from specialized RF component foundries concentrated in East Asian manufacturing hubs.
- Frequency range extension limits:Existing test systems require substantial hardware upgrades to address emerging V2X coexistence validation above 6 GHz, creating technical debt for installed base owners.
Strategic Opportunities
- India BIS automotive electronics mandate:Pending compulsory EMC certification for electronic subassemblies opens greenfield laboratory development opportunities in Pune and Chennai supplier corridors.
- Software-defined test automation:Python-based instrument control and AI-driven anomaly detection converge to reduce test cycle duration and enable predictive maintenance of shielded enclosures.
- Mobile/compact chamber formats:Containerized EMC test cells address space-constrained tier-2 supplier facilities seeking pre-compliance capability without permanent infrastructure investment.
Industry Challenges
- RF engineer scarcity:Specialized expertise in antenna calibration, chamber validation, and CISPR 16-1-4 uncertainty analysis remains concentrated among aging practitioner cohorts in Germany and Japan.
- Multi-standard harmonization friction:Divergent interpretation of ISO 11452-2 versus manufacturer-specific test plans creates quoting complexity and scope creep for validation service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive EMC Test Equipment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conducted Emission, Radiated Emission, Immunity Test, High Frequency Application: Vehicle Systems, Electronic Components, Aftermarket Parts, Propulsion Systems Technology: Passive, Active, Hybrid, Wireless End User: OEMs, Tier-1 Suppliers, Testing Labs, Research Institutions |
| Companies Covered | Rohde & Schwarz, Keysight Technologies, AMETEK, Anritsu, AR, Com Power, GAUSS INSTRUMENTS, ESCO Technologies, Fortive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive EMC Test Equipment Market Trends and Innovations
Test instrumentation architectures are pivoting from discrete box instruments toward modular PXIe and AXie platforms that accelerate reconfiguration between emission, immunity, and radar validation workflows.
Real-time spectrum analysis with gapless capture is expanding into automotive EMC suites, enabling detection of intermittent disturbances from switched-mode power supplies during transient load conditions. Tier-1 suppliers in Stuttgart and Munich are adopting these systems to compress debug cycles for 800-volt platform launches. The technology is displacing swept-tune analyzers in pre-compliance environments where intermittent failures previously escaped detection.
Europe's F-Gas Regulation phase-down is forcing chamber operators to transition from SF6-based switchgear to vacuum-insulated alternatives for high-power immunity testing above 200 V/m. Industrial consequence includes extended procurement timelines for RF power amplifiers and revised maintenance protocols. German test houses are responding fastest, with KBA-type approval laboratories completing infrastructure transitions ahead of mandated deadlines.
Validation contracting is consolidating around full-service platform vendors offering integrated chamber design, instrumentation, and accredited calibration under unified service agreements. Discrete equipment procurement from multiple specialist suppliers is losing share to single-source accountability models. This pattern is most pronounced in United States automotive supplier clusters where OEMs push liability upstream through turnkey validation partnerships.
Automotive EMC Test Equipment Market Segmentation
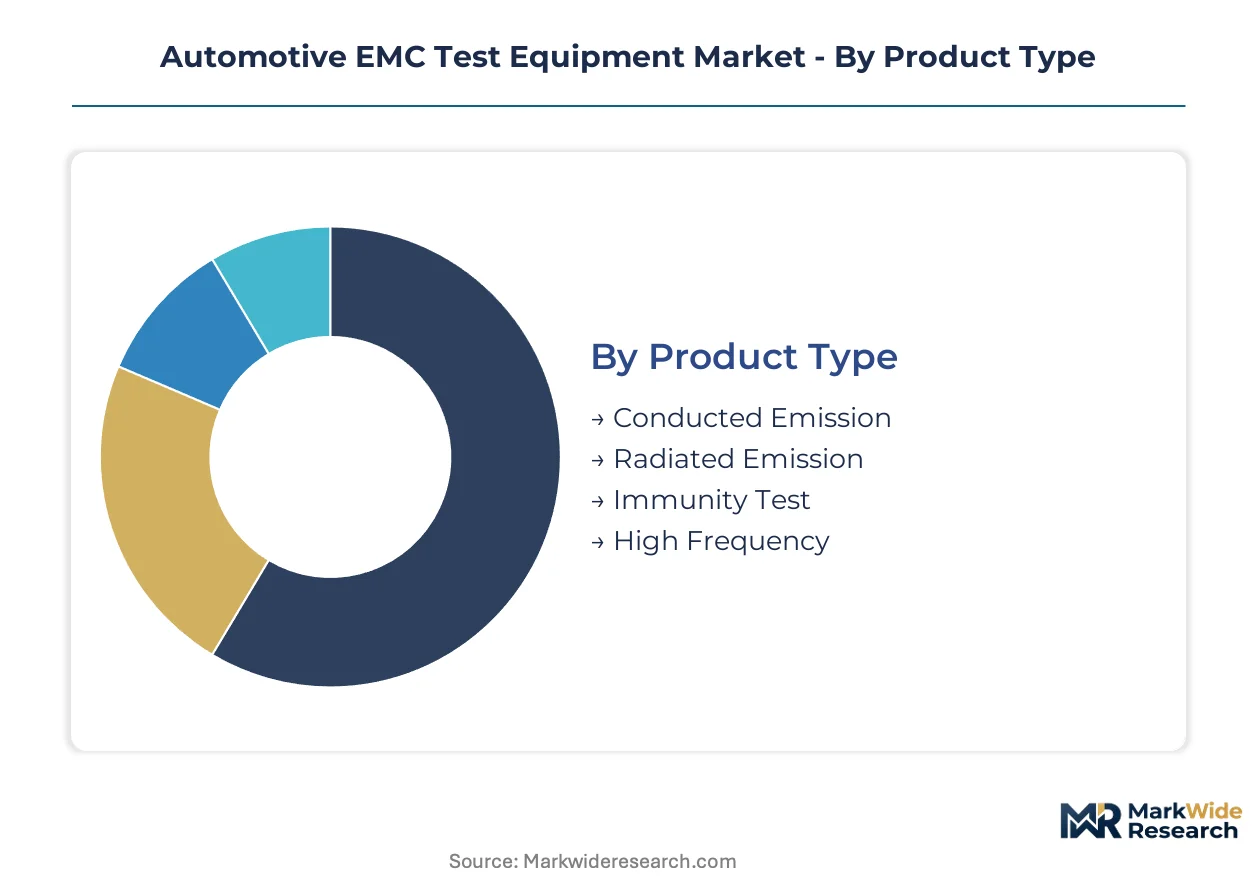
Automotive EMC test equipment segments diverge sharply by capital intensity and technical complexity. Shielded chamber infrastructure and high-frequency instrumentation command premium procurement budgets, while modular conducted emission systems serve broader supplier tiers.
Product Type:
Capital intensity peaks in multi-megahertz chamber systems requiring precision absorber arrays and RF power amplification chains.
- Conducted Emission:Benchtop analyzers and line impedance stabilization networks measure conducted disturbances across 150 kHz to 108 MHz bandwidths. Tier-1 suppliers in Germany cluster procurement around integrated LISN-spectrum analyzer bundles for power electronics validation. CISPR 25 Revision 6 recertification cycles sustain replacement demand.
- Radiated Emission:Anechoic chambers with ferrite-tile and hybrid foam lining capture broadband electromagnetic signatures from 30 MHz to 6 GHz. OEM engineering centers in Japan prioritize 10-meter chamber configurations for full-vehicle testing ahead of type-approval submission. Absorber material cost volatility constrains mid-tier supplier adoption.
- Immunity Test:RF power amplifiers and antenna arrays subject components to controlled electromagnetic fields per ISO 11452 thresholds.
- High Frequency:Millimeter-wave instrumentation addresses 77-81 GHz radar validation for ADAS sensor suites.
Most installed capacity flows through Conducted Emission systems. Expansion is steepest in High Frequency instrumentation.
Application:
Validation scope determines equipment specification, with full-vehicle integration testing requiring substantially larger infrastructure footprints than discrete component workflows.
- Vehicle Systems:Integrated platform validation combines powertrain, infotainment, and chassis electronics in synchronized emission and immunity protocols. OEMs in the United States consolidate pre-release gates at centralized technical centers to compress development calendars. 800-volt architecture proliferation intensifies simultaneous multi-domain testing requirements.
- Electronic Components:Module-level validation targets ECUs, sensors, and display units under controlled bench conditions. Tier-2 suppliers in China's Shenzhen corridor favor compact semi-anechoic chambers for cost-contained pre-compliance screening. GB/T standard enforcement by MIIT mandates pre-homologation certification.
- Aftermarket Parts:Third-party telematics and audio equipment requires supplemental EMC verification for regulatory conformity.
- Propulsion Systems:High-voltage inverter and battery management system validation demands specialized immunity protocols above 200 V/m field strength.
Vehicle Systems absorb the majority of chamber infrastructure investment. Electronic Components show the fastest volume growth in compact test cell procurement.
Technology:
Signal processing architecture separates legacy analog systems from software-defined platforms enabling workflow reconfiguration.
- Passive:Fixed-filter absorber materials and passive antenna configurations provide baseline shielding and measurement capabilities. Established German test houses maintain passive-dominant chambers for standardized CISPR 25 emission routines. Limited reconfigurability constrains adaptation to evolving V2X coexistence protocols.
- Active:Real-time spectrum analyzers with gapless capture detect intermittent disturbances from switched-mode power supplies during transient load conditions. Tier-1 suppliers in Stuttgart deploy active systems to compress debug cycles for electric platform launches. PXIe modular architectures accelerate reconfiguration between test modes.
- Hybrid:Combinations of passive shielding and active signal processing balance cost and capability.
- Wireless:Over-the-air test configurations address 5G-V2X and C-V2X coexistence validation requirements.
Passive technology retains the largest installed base. Active systems are climbing the fastest as real-time detection displaces swept-tune methodologies.
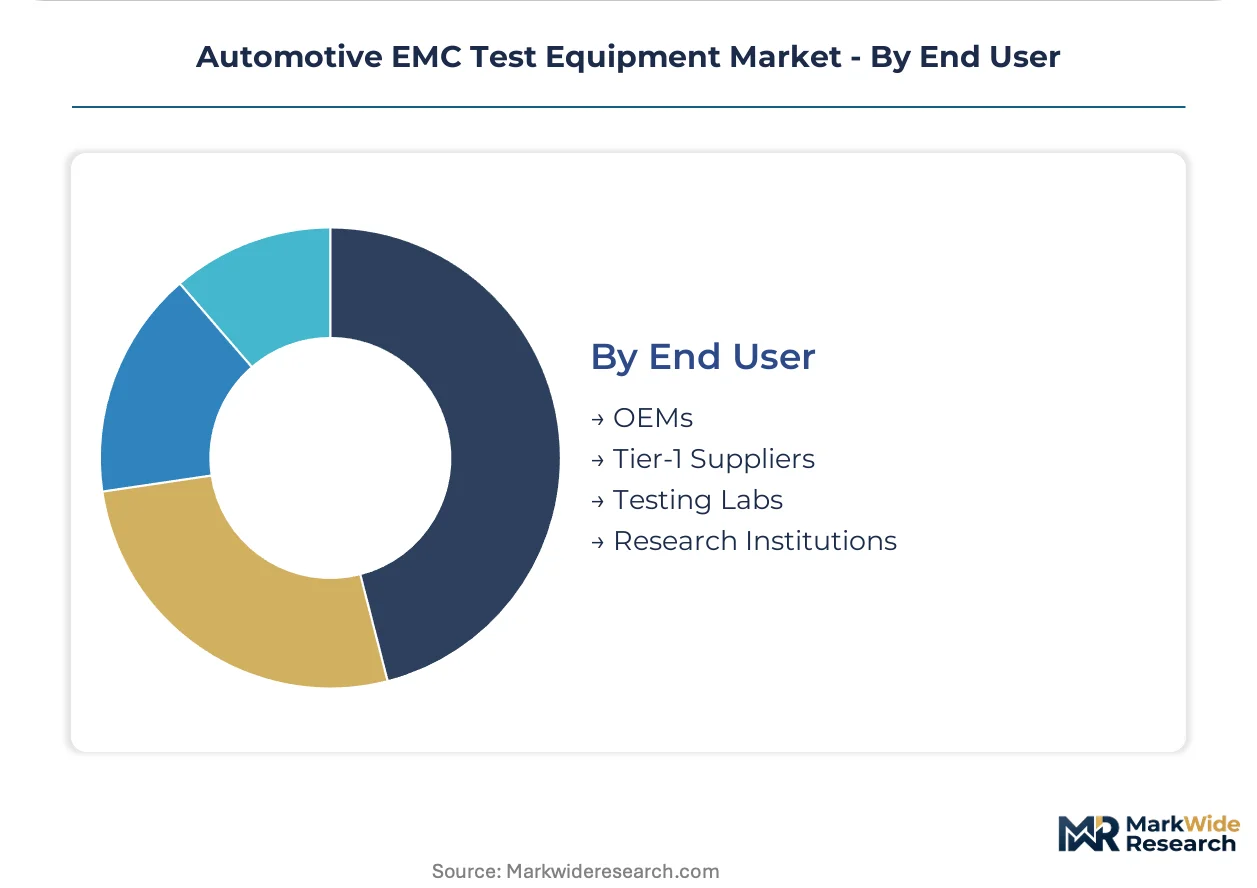
End User:
Procurement authority and validation liability distribution shape equipment specification and service contracting patterns.
- OEMs:In-house technical centers maintain captive chamber capacity for platform-level validation and type-approval submission. Engineering clusters in Munich and Detroit prioritize 10-meter semi-anechoic configurations with integrated vehicle dynamometers. Consolidated validation gates upstream of series production compress external laboratory dependency.
- Tier-1 Suppliers:Module specialists balance in-house pre-compliance capability with contracted accredited laboratory access for final certification. Japanese supplier corridors concentrate procurement around compact 3-meter chambers with multi-standard software suites. Outsourced service agreements with full-service platform vendors gain share over discrete equipment procurement.
- Testing Labs:Independent and OEM-captive facilities provide accredited certification services under unified service agreements.
- Research Institutions:University and consortium laboratories advance measurement methodology and pre-standard protocol development.
Tier-1 Suppliers represent the dominant equipment procurement volume. Testing Labs are expanding capacity fastest under turnkey validation partnership models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive engineering clusters in Stuttgart and Munich anchor EMC test equipment procurement, driven by tier-1 supplier consolidation around captive validation centers for electric platform launches.
United States
OEM technical centers in Detroit and Silicon Valley compress development calendars through centralized pre-release validation gates for 800-volt architectures. FCC Part 15 mandates pre-market EMC certification for every electronic subsystem. Tier-1 suppliers in Michigan balance in-house chamber capacity with outsourced accredited laboratory access.
Germany
KBA-type approval laboratories accelerate infrastructure transitions ahead of F-Gas Regulation deadlines for SF6 phase-down in high-power immunity testing. UN ECE R10 Revision 6 forces recertification of existing test protocols across engineering centers. Stuttgart-based suppliers adopt real-time spectrum analyzers to compress debug cycles.
Japan
METI-aligned supplier corridors concentrate procurement around compact 3-meter chambers with multi-standard software suites for module-level validation. 77-81 GHz radar proliferation expands high-frequency immunity test requirements for ADAS sensor density growth. Nagoya engineering clusters prioritize 10-meter chamber configurations for full-vehicle testing.
China
MIIT GB/T enforcement creates captive laboratory demand in Shanghai and Shenzhen supplier clusters for NEV power electronics pre-homologation. Tier-2 suppliers favor compact semi-anechoic chambers for cost-contained pre-compliance screening. Beijing-Tianjin-Hebei corridors integrate battery management system validation into unified EMC protocols.
India
Pending BIS compulsory EMC certification for electronic subassemblies opens greenfield laboratory development opportunities in Pune and Chennai supplier corridors. Domestic tier-1 suppliers seek mobile chamber formats to address space-constrained facilities without permanent infrastructure investment. Karnataka engineering centers pilot software-defined test automation for cycle compression.
Automotive EMC Test Equipment Market Competitive Landscape
Global majors compete with regional champions across instrumentation architecture and chamber integration capabilities, producing a tiered vendor structure where premium platform vendors capture consolidated validation contracts while specialized RF houses serve discrete component workflows. The competitive terrain separates into three archetypes: integrated full-service platform vendors, modular instrumentation specialists, and laboratory service operators. Dominant competitive moves include strategic partnerships for turnkey validation accountability and geographic expansion through local chamber construction partnerships.
Among German-based instrumentation groups, Rohde & Schwarz GmbH & Co. KG and GAUSS INSTRUMENTS GmbH occupy positions anchoring premium automotive accounts through vector network analyzer and real-time spectrum platforms. Keysight Technologies Inc. represents the scale-driven archetype with signal integrity instrumentation extending into 5G-V2X coexistence testing. AMETEK Inc. sits within the laboratory service tier, sustaining outsourced pre-compliance workflows with tier-1 suppliers seeking contracted capacity rather than captive infrastructure.
| Leading Market Players |
|---|
| Rohde & Schwarz |
| Keysight Technologies |
| AMETEK |
| Anritsu |
| AR |
| Com Power |
| GAUSS INSTRUMENTS |
| ESCO Technologies |
| Fortive |
| Others |
Pricing and Supply Chain Analysis
Anechoic chamber certification grade bifurcation between ISO 17025-accredited facilities and uncertified pre-compliance setups manifests in pricing spreads exceeding three-to-one for identical floor space, with premium-tier vendors capturing value through bundled calibration services while commodity suppliers compete on absorber material sourcing arbitrage from East Asian foundries.
Pricing Analysis
Ferrite tile and hybrid foam input-cost pass-through dominates chamber construction quotes, with absorber material volatility compressing margins for mid-tier German and Japanese suppliers. Three-tier pricing structure across premium, standard, and economy levels separates turnkey validation partnerships from discrete instrumentation procurement and mobile compact chamber rentals. Pricing pressure stems from extended lead times for vector signal generators and real-time spectrum analyzers. Tier-2 suppliers in China's Shenzhen corridor exhibit highest price sensitivity, while OEM technical centers in Stuttgart and Detroit prioritize certification reliability over unit economics.
Supply Chain Analysis
India's BIS automotive electronics mandate and China's MIIT localization requirements are reshaping sourcing patterns toward domestic chamber construction partnerships in Pune and Shanghai. RF power amplifier supply concentrates in Germany, Japan, and the United States, with specialized foundry capacity for millimeter-wave components anchored in East Asian manufacturing hubs. Ferrite tile, hybrid foam absorbers, and precision antenna arrays constitute critical input dependencies. Single-source vulnerability for real-time spectrum analyzer ASICs creates chokepoint exposure. Distribution runs through direct OEM and tier-1 procurement contracts, with laboratory service operators aggregating secondary demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automotive EMC test equipment rests on software-defined test automation compressing chamber utilization cycles and real-time spectrum platforms commanding premium positioning over swept-tune legacy systems.
For Market Incumbents: Hedge against RF engineer scarcity by embedding Python-based instrument control and AI-driven anomaly detection into platform offerings, while securing captive absorber material supply through backward integration into ferrite tile manufacturing or long-term offtake agreements with East Asian foundries. For New Entrants and Emerging Players: Software-defined PXIe modular architectures offer a technology-first wedge into the compact chamber segment serving space-constrained tier-2 suppliers in India's pending BIS enforcement window. Target mobile containerized test cell deployments in Pune and Chennai corridors. Pursue validation-as-a-service partnerships with domestic tier-1 suppliers seeking outsourced pre-compliance without permanent infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with full-service platform vendors consolidating turnkey validation accountability under unified service agreements. Five-to-ten year viability favors vendors integrating chamber design, instrumentation, and accredited calibration. Monitor harmonization progress between UN ECE R10 Revision 6 and China's GB/T standards as inflection indicator for cross-border laboratory consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Test Automation Investment | Python-based control and AI anomaly detection compress validation cycles for 800-volt platform launches. |
| Turnkey Validation Partnership Consolidation | Single-source accountability models displace discrete procurement across United States automotive supplier clusters. |
| Compact Chamber Geographic Expansion | Containerized test cells address space constraints in India's Pune and Chennai supplier corridors. |
| Real-Time Spectrum Platform Migration | Gapless capture displaces swept-tune analyzers in pre-compliance environments for intermittent failure detection. |
| F-Gas Regulation Infrastructure Transition | Vacuum-insulated switchgear adoption ahead of deadlines secures KBA-type approval laboratory positioning in Germany. |
Research Methodology
Direct dialogue with EMC test laboratory directors, RF instrumentation product managers, tier-1 supplier validation engineers, and automotive OEM platform integration leads grounded qualitative assessment, cross-referenced against secondary validation from FCC Part 15 docket filings, UN ECE R10 revision documentation, MIIT GB/T standard releases, and IHS Markit vehicle production databases. Bottom-up equipment procurement tracking and top-down regulatory mandate sizing were triangulated against chamber construction permit records and instrumentation import customs data.
Segment-level value outputs across the projection horizon reflect modeled interactions between propulsion architecture electrification rates, CISPR 25 and ISO 11452 revision timelines, and regional laboratory capacity expansion. Forecasts incorporate vehicle systems versus electronic components application splits, passive versus active technology migration curves, and OEM versus tier-1 versus testing lab end-user procurement authority patterns. CAGRs derive from regression against historical chamber installation cycles and regulatory recertification wave timing.
The model holds under steady regulatory enforcement intensity and absorber material supply continuity; deviation in UN ECE R10 harmonization pace or East Asian foundry capacity constraints would shift equipment procurement timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Emission Sensors Market
Automotive Electrical & Electronics
India Automotive Sensors Market
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Automotive Airbag Electronic Control Unit Market
Automotive Electrical & Electronics
X-By-Wire Systems Market
Automotive Electrical & Electronics
Canada Automotive Electric Actuators Market
Automotive Electrical & Electronics
EPS Motors Market
Automotive Electrical & Electronics
High Voltage DC Relay for Vehicle Market
Automotive Electrical & Electronics
Global Automotive Electronically Controlled Air Suspension System Market
Automotive Electrical & Electronics
Mexico Automotive EPS Market
Automotive Electrical & Electronics
China Electric Power Steering Market
Automotive Electrical & Electronics
Automotive E-Axle Disconnect Actuator Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Automotive Rain Sensor Market
Automotive Electrical & Electronics
Global Automotive Multifunctional Lamp Market
Automotive Electrical & Electronics
South Korea Automotive Electric Actuators Market