
 TPMS Battery Market | 2026-2036
TPMS Battery Market Size, Share, and Industry Trends Forecast 2026-2036
TPMS Battery Market Analytics
UN ECE R64 certification is rotating the competitive landscape toward suppliers with validated automotive-grade cell production. Panasonic Corporation leverages its vertical integration in lithium primary cell manufacturing to sustain qualification with Tier-1 module integrators. Murata Manufacturing Co., Ltd. anchors its position through ceramic-sealed cell architectures that dominate Japanese OEM supply chains. EVE Energy Co., Ltd. competes on cylindrical cell scale, extending capacity to serve European aftermarket distributors.
TPMS batteries are compact primary or secondary electrochemical cells engineered to deliver stable voltage output across temperature extremes from minus forty to one hundred twenty-five degrees Celsius, powering tire pressure monitoring sensors that transmit real-time inflation data to vehicle control modules. Non-rechargeable lithium-ion cells command the technology segment due to decade-long shelf life and minimal self-discharge rates critical for embedded wheel applications. Aftermarket channels carry thinner margins than OEM supply but occupy growing share as vehicle parc ages beyond original battery design life. Passenger vehicles represent the dominant application category, though commercial fleet operators are shifting toward rechargeable NiMH alternatives to reduce wheel service intervals.
NHTSA enforces TPMS functionality under FMVSS 138 in the United States, while ECE R64 governs European type approval, and China's MIIT aligns GB standards with UN regulatory frameworks. These mandates eliminate non-compliant suppliers and compress qualification timelines for new cell entrants. Stakeholders must monitor solid-state thin-film prototypes that promise wider temperature tolerance without chemistry changes.
Market Dynamics
UN ECE R64 and FMVSS 138 mandates are compressing supplier qualification timelines while lithium-thionyl chloride chemistry displaces alkaline alternatives in cold-climate fleet deployments. This dual pressure is reshaping procurement patterns toward automotive-grade cell producers with validated thermal performance.
Growth Catalysts
- Direct TPMS Mandates:NHTSA's FMVSS 138 enforcement in the United States and ECE R64 in Europe eliminate non-compliant suppliers. OEMs in Germany, France, and Japan are accelerating procurement from qualified cell manufacturers.
- Lithium Primary Cell Chemistry:Non-rechargeable lithium-thionyl chloride batteries deliver decade-long shelf life and minimal self-discharge. Fleet operators in Minnesota and Alaska specify these cells for wheel-embedded sensors operating below minus forty degrees Celsius.
- Passenger Vehicle OEM Channel Expansion:Automotive manufacturers in China and South Korea are integrating TPMS modules at the factory floor. This concentrates demand among Tier-1 module integrators with captive battery supply agreements.
Market Restraints
- Lithium Raw Material Volatility:Thionyl chloride and lithium metal prices fluctuate with electrolyte supply chain disruptions. Cell producers face margin compression when feedstock costs spike without pass-through mechanisms.
- Supply Concentration in East Asia:Ceramic-sealed cell architectures and cylindrical form factors concentrate production in Japanese and Chinese manufacturing clusters. European and North American OEMs remain exposed to trans-Pacific logistics disruptions.
- Alkaline Chemistry Lock-in:Aftermarket distributors in price-sensitive regions continue stocking manganese dioxide alternatives. These cells fail in thermal extremes, creating warranty liability for installers.
Strategic Opportunities
- Rechargeable NiMH Fleet Conversion:Commercial operators in long-haul trucking segments are testing nickel-metal hydride alternatives. Wheel service interval reduction justifies higher upfront cell costs through maintenance savings.
- Solid-State Thin-Film Prototypes:Research programs at automotive electronics labs are validating wider temperature tolerance without chemistry changes. Successful qualification would open aerospace and defense adjacent markets.
- Aging Vehicle Parc Aftermarket:Vehicles beyond original battery design life in the United States and Western Europe require replacement cells. Distributors capturing this channel gain recurring revenue independent of new vehicle sales cycles.
Industry Challenges
- Automotive-Grade Certification Timelines:UN ECE R64 type approval requires eighteen to twenty-four months of thermal cycling validation. New cell entrants face cash burn during qualification without revenue offset.
- Embedded System Integration Complexity:TPMS sensors must synchronize with vehicle control modules across multiple communication protocols. Battery voltage stability specifications vary by OEM, fragmenting cell design requirements.
- Electrochemistry Talent Scarcity:Lithium primary cell engineering expertise concentrates among veterans of military and medical device sectors. Automotive battery divisions compete for this limited talent pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TPMS Battery Market |
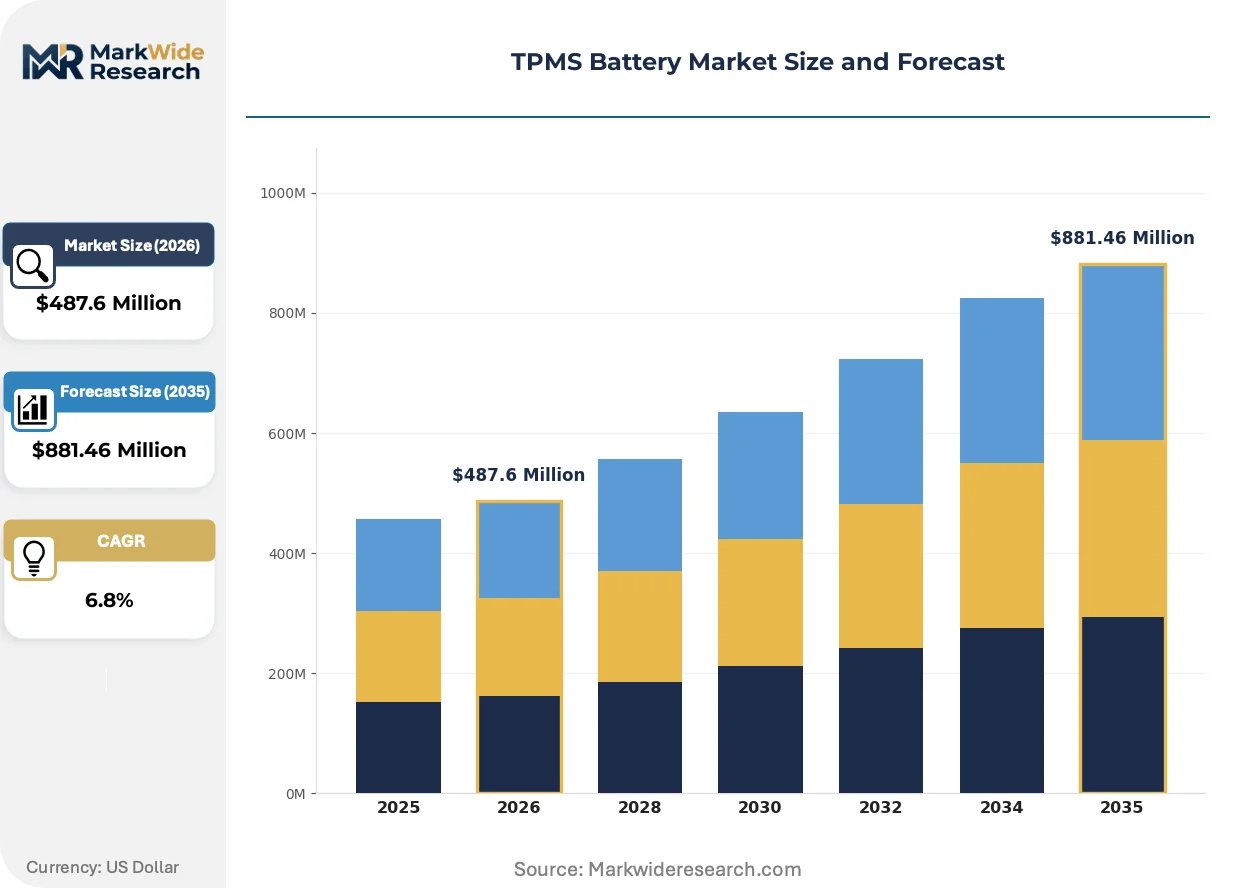
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OEM, Aftermarket, Rechargeable, Non-Rechargeable Technology: Lithium-ion, Alkaline, NiMH, Silver Oxide Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Buses End User: Automotive Manufacturers, Tire Dealers, Fleet Operators, Individual Consumers |
| Companies Covered | Murata Manufacturing Co., Ltd., Panasonic Corporation, Maxell, Ltd., Duracell Inc., EVE Energy Co., Ltd., Renata SA, BE-POWER GmbH, Tadiran Batteries GmbH, Guangzhou Mai Sheng Energy Technology Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TPMS Battery Market Evolving Landscape
Solid-state electrochemistry and ceramic sealing architectures are compressing form factors while regulatory harmonization accelerates cross-border qualification. These forces are converging to redefine competitive positioning among cell producers.
Ceramic-to-metal sealed cell housings are miniaturizing TPMS battery footprints while maintaining hermetic integrity across temperature extremes. Japanese OEM supply chains specify these architectures for wheel-embedded applications where vibration and thermal shock degrade conventional polymer seals. The technology is compressing module integration space, enabling sensor designers to add accelerometer functions without enlarging wheel housing dimensions.
China's MIIT alignment of GB standards with UN regulatory frameworks is eliminating technical barriers to export. Domestic cell producers previously serving industrial instrumentation markets now qualify for automotive Tier-1 supply. European aftermarket distributors are responding by dual-sourcing from validated Chinese cylindrical cell manufacturers to reduce dependency on Japanese supply chains.
Fleet maintenance departments are unbundling tire service from wheel electronics replacement. Commercial operators in the United States negotiate separate contracts for tread replacement versus sensor battery refresh. This pattern is most visible in long-haul trucking verticals where wheel-off intervals are scheduled independently of inflation monitoring system maintenance.
TPMS Battery Market Segmentation
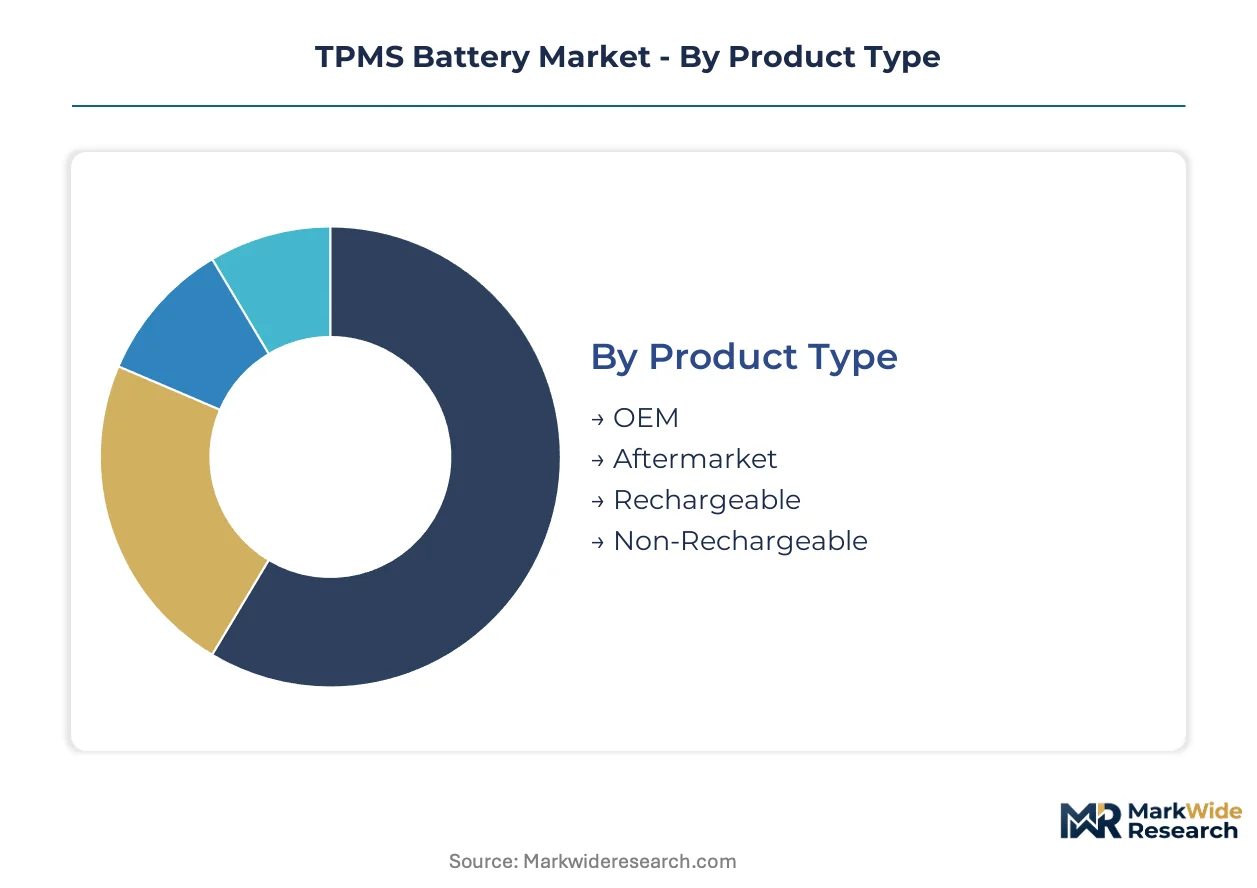
TPMS battery procurement patterns diverge sharply across product origin, electrochemistry, vehicle class, and buyer type. Regulatory mandates in the United States, Germany, and Japan compress qualification timelines unevenly across these dimensions, concentrating volume among automotive-grade certified suppliers while fragmentating aftermarket channels.
Product Type:
FMVSS 138 and ECE R64 mandates create divergent margin structures between factory-installed and replacement channels, with rechargeable alternatives emerging in fleet applications seeking service interval reduction.
- OEM:Factory-integrated cells must survive ten-year vehicle lifespans without maintenance. German and Japanese automotive manufacturers specify lithium-thionyl chloride chemistry exclusively, with Panasonic and Murata securing multi-year supply agreements through validated thermal cycling protocols.
- Aftermarket:Replacement cells face price pressure from manganese dioxide alternatives that fail in sub-zero conditions. Distributors in the United States and Western Europe capture recurring revenue as vehicle parc ages beyond original battery design life, though warranty liability concentrates among installers specifying non-automotive-grade cells.
- Rechargeable:Nickel-metal hydride chemistry penetrates long-haul trucking fleets where wheel-off service intervals justify higher upfront costs through maintenance savings.
- Non-Rechargeable:Primary lithium cells dominate passenger vehicle embedded sensors, with decade-long shelf life eliminating wheel electronics access requirements during vehicle ownership.
Established volume favors OEM; emerging adoption favors Rechargeable.
Technology:
Cost tier differentiation separates validated automotive-grade electrochemistries from price-driven alternatives, with cold-climate fleet specifications accelerating chemistry displacement patterns.
- Lithium-ion:Lithium-thionyl chloride variants deliver stable voltage output from minus forty to one hundred twenty-five degrees Celsius with minimal self-discharge. Minnesota and Alaska fleet operators mandate these cells for wheel-embedded sensors, displacing alkaline alternatives in cold-climate deployments.
- Alkaline:Manganese dioxide chemistry retains share in price-sensitive aftermarket channels despite thermal failure modes. Stocking distributors in emerging markets face warranty exposure when installers specify these cells for extreme-temperature operating environments.
- NiMH:Nickel-metal hydride technology enables wheel service interval reduction through rechargeable architectures, climbing the fastest in commercial fleet segments where downtime costs exceed cell replacement economics.
- Silver Oxide:Limited penetration in TPMS applications due to cost structure, with primary deployment in medical and aerospace battery segments where energy density requirements differ.
Technology maturity concentrates procurement among lithium primary specialists; chemistry displacement creates openings for NiMH qualification.
Application:
Vehicle class determines battery specification stringency, with passenger car volume contrasting against commercial vehicle rechargeability requirements and heavy-duty thermal tolerance demands.
- Passenger Vehicles:Factory-installed TPMS modules in China and South Korea concentrate demand among Tier-1 integrators with captive lithium primary supply. NHTSA enforcement of FMVSS 138 eliminates non-compliant cell suppliers from new vehicle programs.
- Commercial Vehicles:Fleet operators negotiate separate contracts for tire service versus sensor battery refresh, unbundling maintenance categories that OEMs integrate at factory floor.
- Heavy-Duty Trucks:Long-haul verticals specify automotive-grade cells with validated vibration resistance across million-mile duty cycles. Wheel housing thermal shock from braking systems exceeds passenger vehicle profiles.
- Buses:Urban transit procurement favors rechargeable alternatives where depot-based maintenance infrastructure supports scheduled wheel electronics service.
Passenger vehicle scale dominates absolute volume; commercial fleet restructuring favors rechargeable specification.
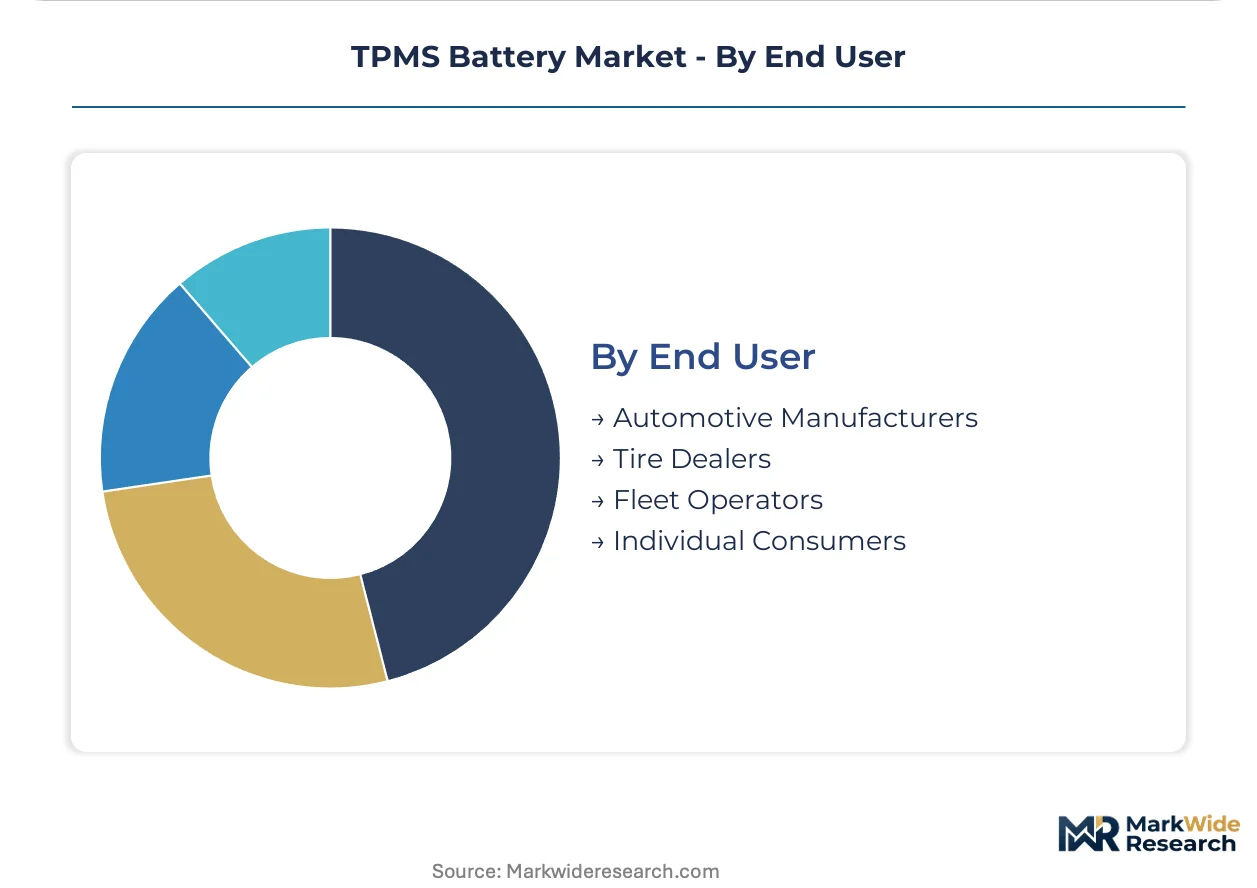
End User:
Customer type determines procurement channel structure, with automotive manufacturer qualification requirements contrasting against fleet operator maintenance unbundling and individual consumer price sensitivity.
- Automotive Manufacturers:Tier-1 module integrators in Germany, France, and Japan require eighteen to twenty-four month ECE R64 thermal cycling validation. UN certification rotates procurement toward cell producers with automotive-grade production lines.
- Tire Dealers:Service bay economics favor rapid replacement over specification matching, creating warranty liability when non-automotive-grade cells substitute for OEM-qualified alternatives.
- Fleet Operators:Maintenance departments in United States long-haul segments schedule wheel-off intervals independently of inflation monitoring system refresh, enabling rechargeable NiMH testing.
- Individual Consumers:Price-driven aftermarket selection concentrates in online channels where specification validation is absent, expanding fastest in aging vehicle parc regions of Western Europe.
Automotive manufacturer concentration favors qualified cell producers; fleet operator unbundling creates rechargeable trial opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA's FMVSS 138 enforcement and ECE R64 type approval mandates are redrawing procurement geography. Automotive-grade cell qualification timelines compress volume concentration toward validated manufacturing clusters in Germany, Japan, China, South Korea, and the United States.
United States
Minnesota and Alaska fleet operators mandate lithium-thionyl chloride cells for sub-zero wheel-embedded sensor performance. NHTSA enforcement of FMVSS 138 eliminates non-compliant suppliers from new vehicle programs. Detroit-area automotive manufacturers concentrate OEM procurement among Tier-1 module integrators with captive battery supply agreements.
Germany
Automotive manufacturers in Stuttgart and Munich accelerate procurement from qualified cell producers as direct TPMS mandates tighten. ECE R64 thermal cycling validation requires eighteen to twenty-four months, rotating procurement toward suppliers with automotive-grade production lines. Bavarian OEM supply chains specify ceramic-sealed cell architectures exclusively.
Japan
Tokyo and Osaka industrial clusters dominate ceramic-sealed cell architecture production for wheel-embedded applications. METI alignment with UN regulatory frameworks accelerates cross-border qualification for domestic producers. Nagoya-area automotive electronics labs validate solid-state thin-film prototypes for wider temperature tolerance.
China
MIIT alignment of GB standards with UN frameworks eliminates technical barriers to export for domestic cell producers. Shenzhen and Dongguan manufacturing clusters extend cylindrical cell capacity to serve European aftermarket distributors. Shanghai and Beijing OEMs integrate TPMS modules at factory floor, concentrating demand among Tier-1 integrators.
South Korea
Seoul Capital Area automotive manufacturers expand TPMS battery procurement as direct mandates tighten. Domestic cell producers qualify for automotive Tier-1 supply through validated thermal performance protocols. Busan-Ulsan industrial zones concentrate on scale production for export-oriented OEM channels.
TPMS Battery Market Competitive Landscape
Player mix skews toward diversified electronics conglomerates with captive battery divisions and specialized primary cell manufacturers. Market structure concentrates among Japanese and Chinese producers with validated automotive-grade certification, while European and North American OEMs remain exposed to trans-Pacific supply dependencies. Two strategic archetypes dominate: vertically integrated electronics majors controlling upstream cell production, and specialized primary battery houses with decades of lithium chemistry expertise. Competitive moves center on capacity expansion in cylindrical form factors and strategic partnerships with Tier-1 module integrators seeking supply security.
Within the diversified electronics tier, Panasonic Corporation and Murata Manufacturing Co., Ltd. exemplify the vertically integrated archetype with in-house lithium primary cell production. EVE Energy Co., Ltd. occupies a position among Chinese cylindrical cell specialists extending capacity to serve European aftermarket channels. BE-POWER GmbH and Tadiran Batteries GmbH represent the specialized European primary cell houses competing on automotive-grade qualification timelines. Maxell, Ltd. and Renata SA sit within the precision battery segment where ceramic sealing expertise differentiates positioning. Guangzhou Mai Sheng Energy Technology Co Ltd anchors the emerging Chinese manufacturer archetype scaling production for export qualification.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| Panasonic Corporation |
| Maxell, Ltd. |
| Duracell Inc. |
| EVE Energy Co., Ltd. |
| Renata SA |
| BE-POWER GmbH |
| Tadiran Batteries GmbH |
| Guangzhou Mai Sheng Energy Technology Co Ltd |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four month ECE R64 qualification timelines compress inventory buffers for European OEMs while concentrating pricing power among Japanese and Chinese cell producers with validated automotive-grade production lines. This lead-time asymmetry feeds directly into contract structures that lock in multi-year supply agreements at premium tiers for certified suppliers.
Pricing Analysis
Certification level (ECE R64/FMVSS 138-grade) creates the primary spread between automotive-qualified and aftermarket-grade cells. Three-tier pricing structure across automotive-certified, industrial-grade, and consumer-economy levels segments buyers by liability tolerance. Cost compression in the aftermarket tier is intensifying because alkaline alternatives from unvalidated producers undercut lithium primary cells on upfront unit cost. Fleet operators represent the least price-sensitive segment due to wheel-off downtime costs, while individual consumers through online channels exhibit highest elasticity.
Supply Chain Analysis
Japan and China anchor ceramic-sealed cylindrical cell production for wheel-embedded applications. Thionyl chloride electrolyte and lithium metal anode supply rests on East Asian chemical processing clusters. Single-source vulnerability concentrates in ceramic-to-metal sealing equipment where Japanese machine tool producers dominate. Distribution runs through Tier-1 module integrators with captive supply agreements to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from solid-state thin-film prototypes that promise wider temperature tolerance without chemistry changes. Defense of market position requires consolidation of certification advantages and supply security.
For Market Incumbents: Consolidate automotive-grade certification moats by accelerating ECE R64 thermal cycling validation throughput. Deepen backward integration into lithium metal refining to offset thionyl chloride feedstock volatility. Lock in multi-year supply agreements with Tier-1 module integrators before Chinese cylindrical cell producers complete European aftermarket qualification.
For New Entrants and Emerging Players: ECE R64 fast-track partnerships with established testing laboratories compress eighteen-month validation windows. Target United States long-haul fleet operators testing rechargeable NiMH alternatives where incumbent lithium primary suppliers lack service infrastructure. Lead with wheel service interval reduction economics rather than upfront cell cost positioning.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state thin-film prototyping programs. Five-to-ten year viability favors specialized primary cell houses with decades of lithium chemistry expertise over diversified electronics conglomerates where battery divisions compete for internal capital. Watch ceramic sealing equipment utilization rates as the inflection signal for capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| ECE R64 Certification Fast-Track | Compresses qualification timelines for new cell entrants competing with Panasonic and Murata. |
| Backward Integration into Lithium Metal | Captures margin from thionyl chloride supply volatility for European primary cell houses. |
| Rechargeable NiMH Fleet Pilot Programs | Opens commercial vehicle segments where wheel service intervals justify higher upfront costs. |
| Ceramic Sealing Capacity Expansion | Enables miniaturized sensor designs with accelerometer functions for Japanese OEM supply chains. |
| Solid-State Thin-Film R&D Partnership | Validates wider temperature tolerance prototypes for aerospace and defense adjacent markets. |
Research Methodology
Initial hypotheses were tested against primary input from Tier-1 module integrator procurement directors, automotive electronics validation engineers, fleet maintenance supervisors, and aftermarket distributor category managers and refined through secondary validation against NHTSA FMVSS 138 enforcement records, ECE R64 type approval databases, MIIT GB standard alignment notices, and vehicle production registration data. Bottom-up cell volume estimates by vehicle class triangulated against top-down OEM procurement spend analysis.
Variance decomposition across electrochemistry type, product origin tier, vehicle class, and end-user channel shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-unit assumptions across OEM, aftermarket, and rechargeable adoption curves. Industry-specific forecast inputs included ECE R64 qualification pipeline tracking and lithium-thionyl chloride feedstock price indices.
Underlying assumptions cover regulatory mandate enforcement continuity and thermal cycling protocol stability, with deviation risk concentrated in solid-state prototype qualification timelines and trans-Pacific logistics disruption frequency. Recalibration cycles align with material shifts in UN regulatory harmonization announcements and OEM platform electrification roadmaps.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Lighting Actuators Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
Europe Automotive Display Market
Automotive Electrical & Electronics
South Korea Electric Power Steering (EPS) Sensor Market
Automotive Electrical & Electronics
Automotive Power Module Packaging Market
Automotive Electrical & Electronics
Automotive Electronic Manufacturing Services Market
Automotive Electrical & Electronics
Automotive Alternator and Starter Motor Market
Automotive Electrical & Electronics
Automotive Ecall Market
Automotive Electrical & Electronics
Global Automotive Charge Air Cooler Market
Automotive Electrical & Electronics
Automotive Scroll E-Compressor Market
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market
Automotive Electrical & Electronics
Russia Automotive Eps Market
Automotive Electrical & Electronics
High Voltage DC Relay for Vehicle Market
Automotive Electrical & Electronics
Automotive Emission Sensors Market
Automotive Electrical & Electronics
Automotive Electronic Expansion Valve Market