
 Automotive Thermal Management System Market | 2026-2036
Automotive Thermal Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Thermal Management System Market Intelligence
The rapid expansion of Electric Vehicles is shifting the balance of complexity from traditional engine cooling to sophisticated battery and electronics thermal management. DENSO Corporation leverages its extensive OEM relationships to supply integrated systems for both internal combustion engine and EV platforms. Valeo specializes in compact and efficient heat pump systems critical for EV range optimization. MAHLE GmbH competes on the strength of its modular components, including advanced radiators and heat exchangers.
An automotive thermal management system is an integrated network of components designed to regulate operating temperatures of the powertrain, battery pack, and passenger cabin. These systems utilize components like heat exchangers and water pumps to circulate coolants such as ethylene glycol mixtures. Within the technology landscape, Active Cooling solutions are rapidly displacing legacy Passive Cooling methods, especially in high-performance applications. The Electric Vehicles application segment represents the fastest-growing area, contrasting with the mature Passenger Cars segment.
Product design is heavily influenced by regulations like the US EPA's emissions standards and Europe's F-Gas Regulation, which governs the use of certain refrigerants. China's GB standards for electric vehicle safety impose strict requirements on battery thermal runaway prevention. OEMs and Tier-1 vendors must therefore navigate a complex matrix of performance, cost, and compliance to secure market position.
Market Dynamics
The core dynamic shaping the automotive thermal management market is the technological pivot from internal combustion engine cooling to the multifaceted demands of electric vehicle systems. This shift elevates complexity, requiring integrated solutions for battery packs, power electronics, and cabin environments simultaneously.
Growth Catalysts
- Stringent Emissions Regulations:Policies like the EU Green Deal mandate significant CO2 reductions, directly accelerating the transition to EVs and creating immense demand for the advanced battery thermal management systems necessary for performance and safety.
- EV Manufacturing Concentration:China's established automotive industrial clusters are becoming epicenters for EV production, driving localized demand for sophisticated and high-volume thermal components like heat exchangers and electric water pumps.
- Technology Displacement:The adoption of Active Cooling solutions is rapidly expanding, particularly in performance EVs and hybrids, as they offer superior thermal control over legacy Passive Cooling methods for managing high heat loads from batteries and electronics.
Market Restraints
- Component Cost and Material Volatility:The high cost of specialized materials, including advanced aluminum alloys for lightweight heat exchangers and specific formulations for coolants like ethylene glycol, presents a significant barrier to cost-effective system design for mass-market vehicles.
- Refrigerant Regulations:Europe's F-Gas Regulation phases out refrigerants with high global warming potential, forcing OEMs and suppliers to invest in research and redesign of air conditioning and heat pump systems to use compliant, often more expensive, alternatives.
- Technical Integration Complexity:Integrating thermal management systems across diverse EV battery pack designs and vehicle platforms remains a major technical hurdle, increasing development costs and timelines for vehicle manufacturers.
Strategic Opportunities
- Heat Pump System Integration:The convergence of battery thermal management and cabin climate control via integrated heat pump systems offers a major opportunity to improve overall EV energy efficiency and extend driving range, creating value for OEMs.
- Charging Infrastructure Cooling:High-power DC fast-charging stations generate significant heat, opening a new application segment for liquid cooling solutions to ensure charger reliability and enable faster charging speeds for consumers.
- Modular Sub-System Development:Tier-1 suppliers can capture value by developing pre-validated, modular thermal management sub-systems that OEMs can integrate into new EV platforms, reducing in-house R&D burdens and accelerating vehicle development cycles.
Industry Challenges
- System-Level Integration:A primary operational challenge is the software and hardware integration of components from various vendors into a cohesive, reliable system, which is critical for optimizing performance and preventing faults in complex EV architectures.
- Compliance with Safety Standards:Adhering to evolving and regionally varied safety regulations, such as China's GB standards for preventing battery thermal runaway, requires extensive and costly validation testing, which can delay product launches.
- Specialized Engineering Talent:The industry faces a shortage of engineers possessing cross-domain expertise in thermodynamics, high-voltage power electronics, and control software, which is essential for developing next-generation thermal systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Thermal Management System Market |
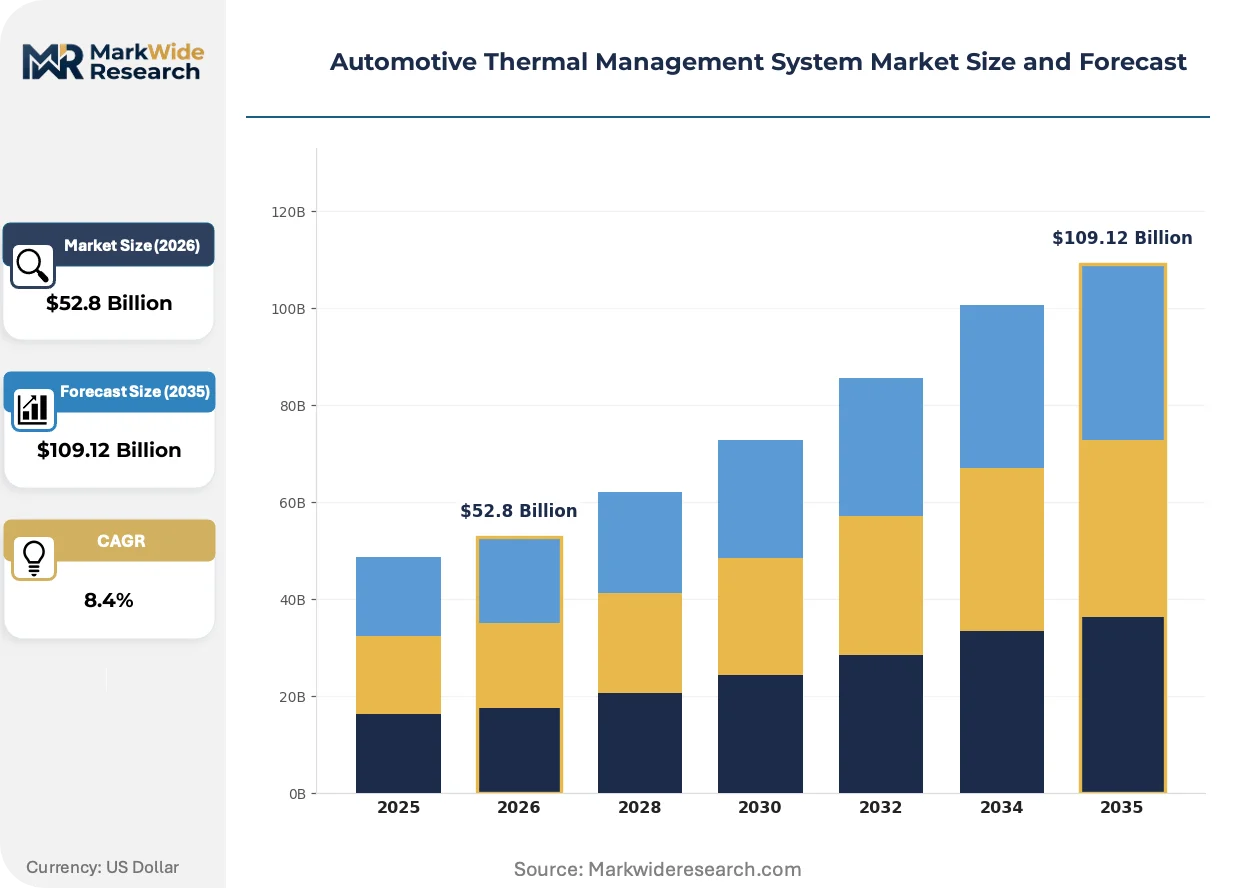
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $109.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiators, Heat Exchangers, Cooling Fans, Thermostats, Water Pumps Technology: Passive Cooling, Active Cooling, Phase Change, Thermoelectric, Liquid Cooling Application: Electric Vehicles, Heavy-Duty Trucks, Commercial Fleets, Passenger Cars, Motorcycles End User: OEMs, Aftermarket Suppliers, Tier-1 Vendors, Fleet Operators, Specialty Vehicle Manufacturers |
| Companies Covered | Valeo, Robert Bosch GmbH, Hanon Systems, Sanden Holdings Corporation, Sanhua Intelligent Controls, DENSO Corporation, BorgWarner, Yinlun Machinery, MAHLE GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Thermal Management System Market Strategic Shifts & Innovations
System intelligence and energy optimization define the market's innovation trajectory. The emphasis is shifting from individual component efficiency to holistically managed thermal networks that balance powertrain performance, battery longevity, and cabin comfort, particularly within electric vehicle platforms.
Predictive thermal management software utilizes an array of sensors and AI-driven algorithms to anticipate heating and cooling requirements before they become critical. Premium EV manufacturers are adopting this technology to maximize driving range and preserve long-term battery health. This intelligent software layer is automating the complex energy trade-offs between vehicle subsystems, replacing older, less efficient static control logic with dynamic optimization.
Regulatory frameworks such as the US EPA's vehicle emissions standards are indirectly compelling automakers to enhance overall powertrain efficiency. This pressure incentivizes the reduction of parasitic energy losses from all auxiliary systems, including thermal management components. The passenger car segment, especially hybrids, is responding by implementing more efficient electric water pumps and variable-speed fans that minimize energy draw during low-demand periods.
A distinct behavioral shift is visible in how automotive OEMs source thermal systems, moving from procuring discrete components to sourcing complete, pre-integrated thermal modules. This change in procurement strategy simplifies vehicle assembly lines and transfers the burden of system integration and validation to specialized Tier-1 suppliers. The trend is most pronounced in new EV platform development within China and Europe, where accelerated time-to-market is a key competitive differentiator.
Automotive Thermal Management System Market Segmentation
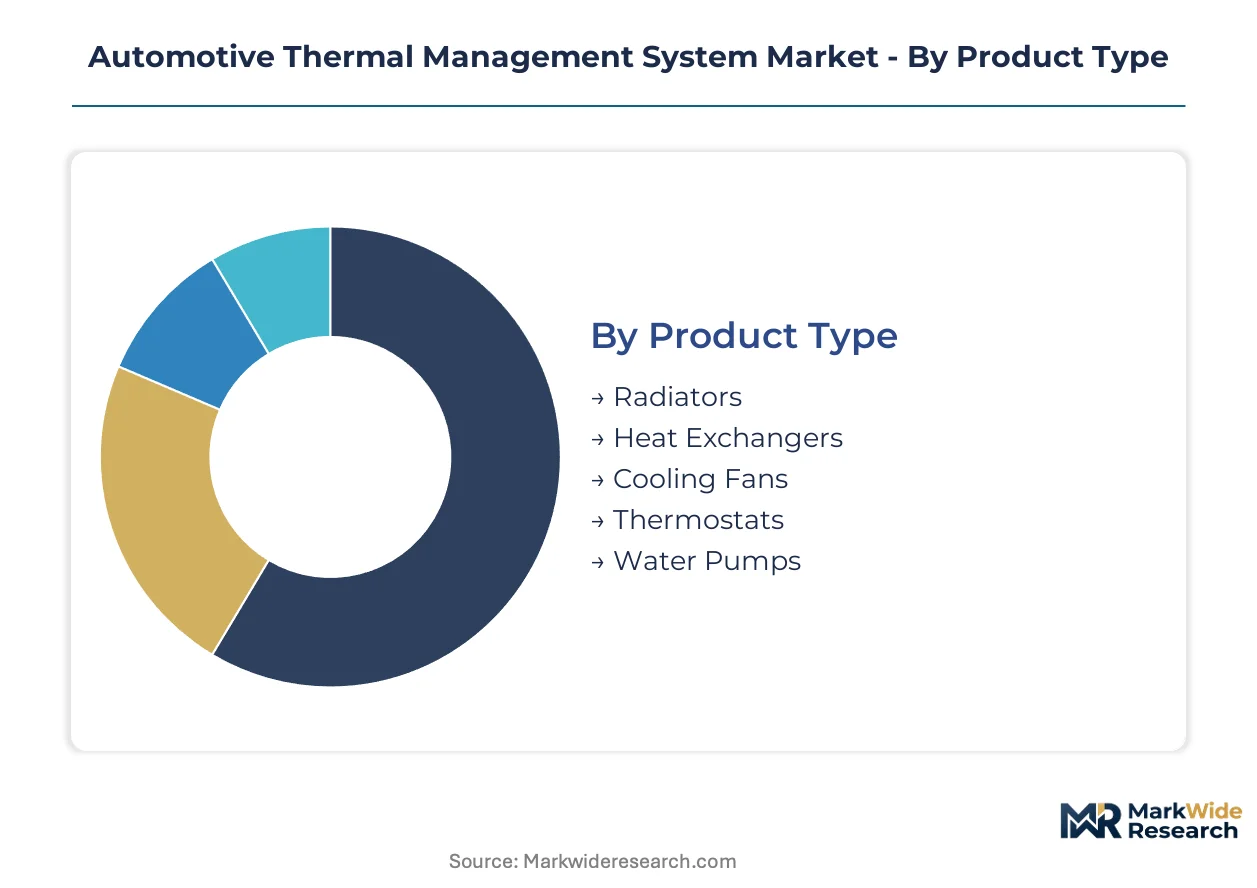
The automotive thermal management market is dissected across multiple dimensions to understand its intricate structure and evolving dynamics. This granular segmentation reveals how technological shifts and regulatory pressures are redefining product demand and market participation. Analyzing these distinct segments provides clarity on where value creation and innovation are concentrating within the industry.
Product Type:
Supply concentration within product types dictates component availability and pricing power for system integrators. Specialized manufacturing processes for advanced materials influence the competitive landscape for these critical thermal components.
- Radiators:These components dissipate heat from the engine coolant to the ambient air, primarily through fin-and-tube designs. Demand remains substantial in internal combustion engine vehicles, with ongoing optimization for lightweight materials and improved heat transfer efficiency.
- Heat Exchangers:Devices facilitating thermal energy transfer between two or more fluids, crucial for battery cooling and cabin climate control in electric vehicles. China's burgeoning EV market drives significant demand for compact and highly efficient heat exchangers.
- Cooling Fans:Electrically or belt-driven fans draw air through radiators and condensers to enhance heat dissipation.
- Thermostats:Mechanical or electronic valves regulate coolant flow to maintain optimal engine operating temperatures.
- Water Pumps:These mechanical or electric devices circulate coolant throughout the thermal management system.
Today's leader: Radiators. Tomorrow's challenger: Heat Exchangers.
Technology:
The adoption of specific thermal management technologies often aligns with vehicle performance requirements and energy efficiency targets. Different technological approaches address varying heat loads and thermal stability needs across automotive platforms.
- Passive Cooling:Relies on natural convection and radiation without external power, typically used in lower-performance applications or as a supplementary system. This method is being displaced by more active solutions due to increasing power densities in modern vehicles.
- Active Cooling:Employs powered components like pumps and fans to actively circulate coolants or refrigerants, providing precise temperature control for high-performance engines and battery packs. Electric Vehicles heavily utilize active cooling for optimal battery longevity and range.
- Phase Change:Utilizes materials that absorb and release latent heat during phase transitions for temporary thermal buffering.
- Thermoelectric:Solid-state devices that use the Peltier effect to create a temperature difference, offering compact spot cooling.
- Liquid Cooling:Circulates a fluid, such as glycol-water mixtures, through channels to remove heat from components.
Active Cooling solutions are expanding most quickly, driven by the proliferation of electric vehicle platforms.
Application:
Customer type and vehicle usage patterns significantly influence the thermal management system design and component specifications. The diverse operational environments of various vehicle applications necessitate tailored thermal solutions.
- Electric Vehicles:Require sophisticated thermal management for battery packs, power electronics, and electric motors to optimize performance and extend range. The EU Green Deal's emissions targets are a primary driver for advanced EV thermal solutions.
- Heavy-Duty Trucks:Demand robust cooling systems for powerful engines and auxiliary components, often operating under extreme loads and temperatures. US EPA emissions standards compel efficiency improvements in these systems.
- Commercial Fleets:Focus on durability and cost-effectiveness for thermal systems in vehicles used for logistics and transportation.
- Passenger Cars:A mature segment with established thermal architectures, now integrating hybrid and mild-hybrid thermal components.
- Motorcycles:Utilize compact and lightweight thermal solutions for engines and, increasingly, for electric drivetrains.
The Electric Vehicles application segment is gaining share fastest, while Passenger Cars maintain significant volume.
End User:
The maturity of end-user relationships and their procurement strategies shape the supply chain dynamics for thermal management systems. Different end-user groups exhibit distinct purchasing behaviors and integration requirements.
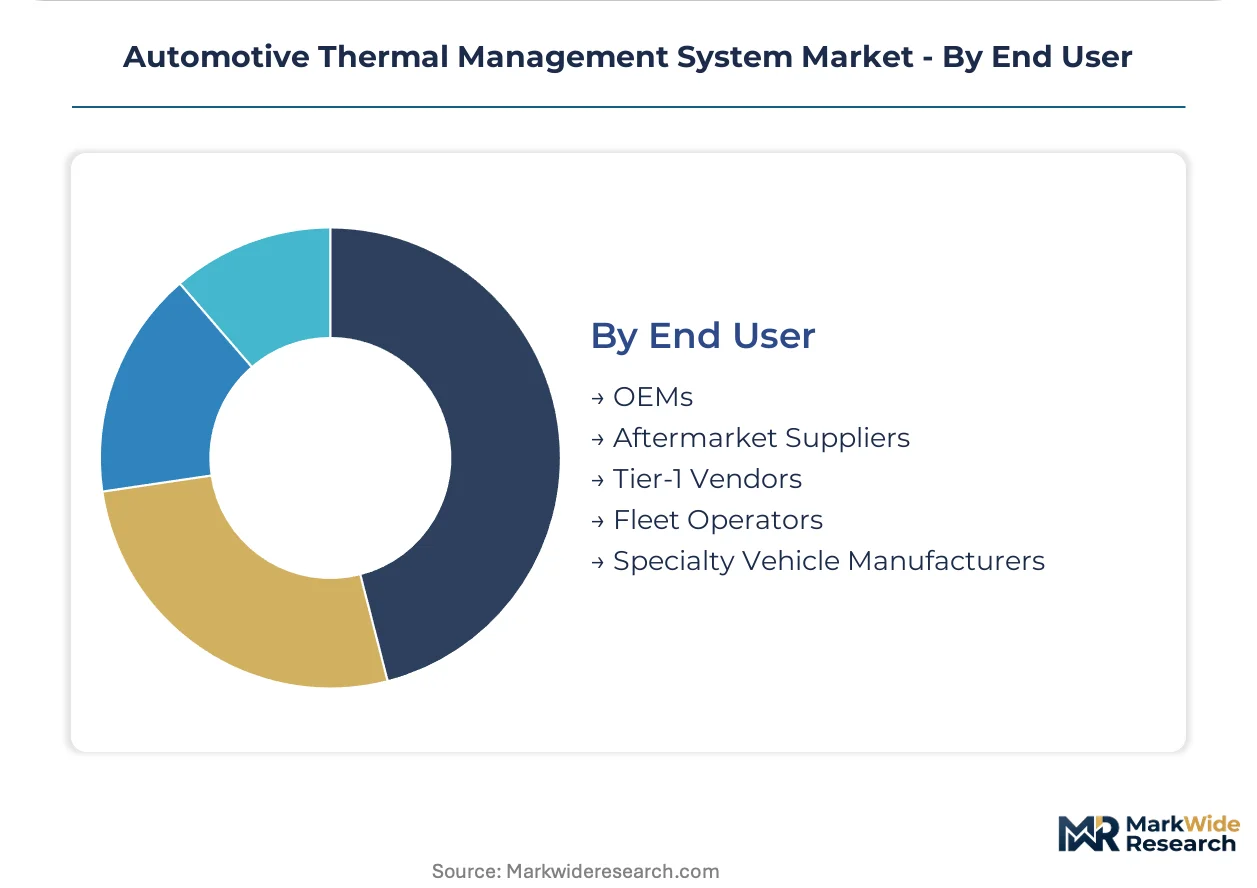
- OEMs:Original Equipment Manufacturers integrate thermal systems directly into vehicle production lines, demanding high volumes and seamless integration. They often collaborate closely with Tier-1 vendors for system development and validation.
- Aftermarket Suppliers:Provide replacement parts and upgrade components for vehicles already in operation, focusing on compatibility and availability. This segment addresses maintenance and repair needs for a diverse vehicle parc.
- Tier-1 Vendors:Specialized suppliers that design, manufacture, and integrate complex thermal modules for OEMs.
- Fleet Operators:Purchase and maintain vehicles in large numbers, prioritizing reliability, longevity, and total cost of ownership for thermal components.
- Specialty Vehicle Manufacturers:Produce low-volume, highly customized vehicles with unique thermal management requirements.
OEMs represent the largest customer base, with Tier-1 Vendors increasingly taking on system integration responsibilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stricter environmental regulations in some regions create compliance cost gaps, influencing where thermal management component production concentrates. Manufacturers seek locations with favorable regulatory environments or robust supply chains to mitigate these costs. This dynamic reshapes global manufacturing footprints.
China
China's immense EV manufacturing concentration drives demand for sophisticated thermal components, particularly heat exchangers. Its GB standards for electric vehicle safety impose stringent requirements on battery thermal runaway prevention. The Yangtze River Delta region has become a key hub for EV production, fostering innovation in localized thermal supply.
Germany
Germany's focus on premium EV development necessitates high-performance thermal solutions for battery and cabin management. The EU Green Deal's stringent emissions targets accelerate demand for advanced thermal systems in electric vehicles. Automotive R&D centers in Bavaria and Baden-Württemberg drive innovation in integrated thermal modules.
United States
The United States sees significant demand for advanced thermal management due to expanding EV market adoption and charging infrastructure build-out. US EPA's emissions standards compel overall powertrain efficiency enhancements, including thermal systems. Michigan's automotive corridor remains a critical center for Tier-1 suppliers developing new thermal technologies.
Japan
Japan's established leadership in hybrid vehicle technology fuels demand for highly energy-efficient thermal components. METI's initiatives promote advanced automotive technologies, including sophisticated thermal management systems for new platforms. Aichi Prefecture, home to major automotive manufacturers, drives the development and production of these systems.
India
India's emerging EV market generates demand for cost-effective yet efficient thermal management solutions, particularly for two-wheelers and smaller passenger EVs. The PLI scheme for automotive components incentivizes localized production of advanced thermal systems. Automotive manufacturing hubs in Chennai and Pune expand their capabilities for thermal component supply.
Automotive Thermal Management System Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the automotive thermal management market. The industry structure exhibits a tiered approach, with large Tier-1 suppliers dominating integrated system provision. Strategic archetypes include global system integrators, specialized component manufacturers, and regional suppliers focusing on specific vehicle types. Dominant competitive moves involve strategic partnerships with OEMs for new EV platforms and continuous portfolio diversification into advanced thermal technologies.
On the premium-tier vector, European entities like Robert Bosch GmbH and Valeo exemplify comprehensive system integration capabilities, offering solutions across diverse vehicle platforms. DENSO Corporation, a Japanese multinational, occupies a strong position as a global Tier-1 vendor, spanning both traditional and electric vehicle thermal management requirements. These firms represent the trend towards pre-validated, modular thermal sub-systems, which reduces OEM development burdens and accelerates vehicle time-to-market. Their scale allows significant investment in advanced material science and control software.
| Leading Market Players |
|---|
| Valeo |
| Robert Bosch GmbH |
| Hanon Systems |
| Sanden Holdings Corporation |
| Sanhua Intelligent Controls |
| DENSO Corporation |
| BorgWarner |
| Yinlun Machinery |
| MAHLE GmbH |
| Others |
Cost & Logistics Intelligence
The widespread adoption of active cooling solutions for electric vehicles simultaneously reshapes component cost economics and supplier concentration. This transition necessitates specialized materials and complex integration, impacting the entire thermal management supply chain.
Pricing Analysis
Direct-to-OEM discounts characterize the primary channel-margin layer for automotive thermal management systems. Pricing stratifies across premium, standard, and economy tiers, driven by customization level for specific EV platforms and compliance with certification standards like China's GB standards. Pricing softness reflects material volatility for advanced aluminum alloys and specialized refrigerants. OEMs producing mass-market vehicles exhibit higher price sensitivity than premium EV manufacturers requiring performance-critical components.
Supply Chain Analysis
Workforce availability in manufacturing hubs across China, Germany, and Japan significantly influences component lead times and production capacities. The supply chain draws from critical raw materials including advanced aluminum alloys, ethylene glycol, and specialized refrigerants. Commodity price volatility for these key materials presents a significant structural risk. Distribution runs through direct-to-OEM channels, with Tier-1 vendors managing complex logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, primarily driven by the increasing integration of higher-value heat pump systems into electric vehicles.
For Market Incumbents: Hedge against technological obsolescence by accelerating R&D in predictive thermal management software and integrated heat pump systems. Invest in advanced material science for lightweight heat exchangers to counter component cost and material volatility. Deepen OEM partnerships for new EV platform integration, securing long-term supply agreements against emerging specialized component manufacturers. Pursue certification investment for battery safety standards like China's GB standards.
For New Entrants and Emerging Players: Europe's F-Gas Regulation opens a window for new entrants offering compliant, low-GWP refrigerant solutions for air conditioning and heat pump systems. Target fast-charging infrastructure cooling solutions, an underpenetrated application segment requiring robust liquid cooling. Focus on modular sub-systems for smaller EV manufacturers, providing pre-validated thermal modules that reduce OEM development burdens. A go-to-market angle emphasizing rapid integration and cost-effectiveness will resonate with these players.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized component manufacturers with strong intellectual property in active cooling or advanced heat exchanger designs. The long-term viability remains strong over the next 5-10 years, anchored by the global EV transition. Acquire firms offering integrated thermal modules, reducing technical integration complexity for OEMs. The signal to watch is the widespread adoption rate of integrated heat pump systems by mass-market OEMs.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Modular EV Thermal Systems | Accelerates OEM vehicle development cycles by reducing integration burdens. |
| Invest in Predictive Thermal Software | Optimizes battery longevity and driving range for premium EV platforms. |
| Expand Heat Pump Production | Improves EV energy efficiency and extends range, addressing consumer concerns. |
| Secure Specialized Material Supply | Mitigates cost volatility for advanced aluminum alloys and refrigerants. |
| Target Fast-Charging Cooling | Creates a new application segment for liquid cooling solutions, ensuring charger reliability. |
Research Approach
Bottom-up electric vehicle modeling reconciled against top-down Tier-1 supplier tracking forms the analytical core of this study. This approach integrates insights from primary interviews with OEM platform engineers, thermal system R&D directors, and regulatory compliance specialists. Secondary validation leverages vehicle production databases, patent filings, and government emissions reports from the US EPA and EU Green Deal.
An input-output matrix frames the quantitative model, projecting market evolution across the analysis window. Segmentation dimensions include product type, technology, application (Electric Vehicles, Heavy-Duty Trucks), end user, and regional production clusters. Compound annual growth rates were derived from historical trends and projected EV adoption rates. Key forecast inputs include regulatory compliance costs and material cost projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical trade tensions impacting material supply. These projections reflect documented assumptions regarding technological advancements and market dynamics. Material deviation in unforeseen regulatory changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market
Automotive Electrical & Electronics
South Africa Automotive Electric Actuators Market
Automotive Electrical & Electronics
X-By-Wire Systems Market
Automotive Electrical & Electronics
Global Automotive ECU Market
Automotive Electrical & Electronics
Automotive EMC Test Equipment Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
Automotive PCB Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Market
Automotive Electrical & Electronics
Automotive Electronic Logging Device (ELD/E-Log) Market
Automotive Electrical & Electronics
UK Automotive Eps Market
Automotive Electrical & Electronics
Automotive Chassis Electronics Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Asia Pacific Automotive Camera Market
Automotive Electrical & Electronics
Switchrack Assemblies Market
Automotive Electrical & Electronics
Nox Automotive Sensors Market
Automotive Electrical & Electronics
Automotive Rain Sensor Market