
 North America Electronic Toll Collection (ETC) Market | 2026-2036
North America Electronic Toll Collection (ETC) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electronic Toll Collection (ETC) Market Analytics
Public-private partnership financing and availability-payment structures is reconfiguring which vendors can bid on multi-state corridor projects. Kapsch TrafficCom leverages its transponder manufacturing scale to anchor turnkey deployments across the Eastern Seaboard. TransCore competes through its dominance of the RFID tag supply chain for legacy system retrofits. Conduent differentiates via specialized back-office clearinghouse software that sustains recurring revenue streams with transportation authorities.
Electronic Toll Collection encompasses automated vehicle identification, classification, and payment processing at highway toll points using dedicated short-range communications, radio-frequency identification, or satellite positioning with onboard units and roadside antennas. The architecture integrates gantries, transponders, and central systems to enable free-flow traffic movement without manual stops. DSRC technology occupies the largest installed base across existing North American infrastructure, while cloud-based deployment models are capturing the fastest expansion as agencies retire aging on-premises data centers. Mobile payment integration represents an emerging margin pool where platform providers are positioning against traditional prepaid account structures.
The Federal Highway Administration administers interoperability mandates that shape transponder compatibility requirements across state lines, while the Federal Communications Commission governs spectrum allocation for DSRC and C-V2X communications that underpin next-generation tolling. State-level departments of transportation in California, Florida, and Texas enforce procurement standards that determine vendor qualification thresholds for large-scale system replacements. Stakeholders must monitor how the shift toward mileage-based user fee pilots reshapes hardware specifications and data governance obligations across the region.
Market Dynamics
State transportation agencies are retiring on-premises data centers for cloud-native back-office architectures, forcing vendors to reconfigure their service delivery models around recurring software subscriptions rather than perpetual hardware licenses.
Growth Catalysts
- MAP-21 Interoperability Mandates:The Federal Highway Administration's ongoing enforcement of transponder compatibility standards across state lines compels legacy system upgrades and opens procurement opportunities for integrated solution providers.
- Texas Triangle Consolidation:Multiple toll authorities in the Dallas-Houston-San Antonio corridor are unifying disparate tag systems, generating concentrated demand for compatible gantry and back-office infrastructure.
- DSRC Spectrum Allocation:The Federal Communications Commission's reserved bandwidth in the 5.9 GHz band provides dedicated communications capacity that accelerates free-flow tolling deployment without cellular dependency.
Market Restraints
- Semiconductor Supply Concentration:Transponder chip fabrication concentrates among a limited set of Asian foundries, exposing North American system integrators to lead-time volatility and input cost spikes.
- Legacy RFID Sunk Costs:Existing tag populations in the Eastern Seaboard create switching friction that slows adoption of next-generation onboard units despite superior technical performance.
- Municipal Budget Cycles:State department of transportation capital appropriations operate on multi-year legislative schedules that mismatch vendor revenue recognition needs and project commissioning timelines.
Strategic Opportunities
- Mileage-Based User Fee Pilots:Oregon and Utah experimental programs for distance-based road charging create demand for GPS-enabled onboard units with integrated payment processing capabilities.
- Mobile Payment Convergence:Smartphone-based tolling applications are displacing dedicated transponder accounts among infrequent users, opening platform licensing opportunities for software specialists.
- C-V2X Technology Migration:Cellular vehicle-to-everything communications standards offer higher bandwidth than DSRC, enabling real-time congestion pricing and dynamic toll rate adjustments.
Industry Challenges
- Cloud Migration Expertise Scarcity:Transportation authorities lack internal capability to architect secure, scalable SaaS transitions, forcing extended reliance on vendor-managed professional services.
- Interoperability Certification Complexity:Multi-state tag compatibility testing protocols impose protracted validation timelines that delay revenue recognition for hardware manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electronic Toll Collection (ETC) Market |
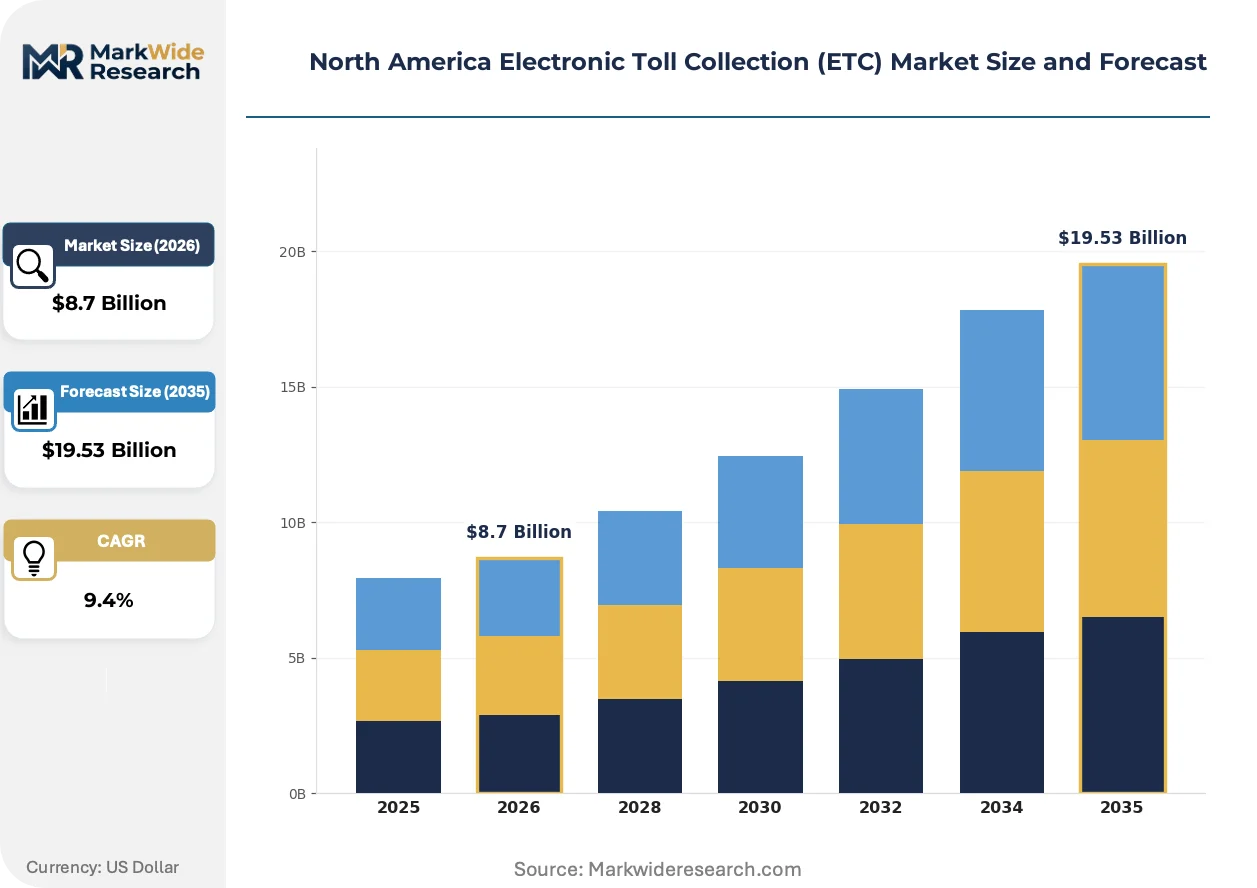
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, DSRC, Bluetooth, GNSS Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Government, Private Operators, Transportation Authorities, Agencies Payment Method: Prepaid Accounts, Credit Cards, Mobile Payments, Cash |
| Companies Covered | Kapsch TrafficCom, TransCore, Conduent, Thales Group, Siemens, TRMI Systems Integration, Cubic Transportation Systems, Neology, EMOVIS, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electronic Toll Collection (ETC) Market Evolving Landscape
Cloud-native deployment models are compressing the traditional tolling value chain by unbundling hardware from software and enabling real-time data analytics that reshape how agencies price roadway access.
Multi-tenant SaaS back-office platforms are digitizing the traditional on-premises clearinghouse function. State transportation agencies in California and Florida are migrating accounts receivable and violation processing to vendor-hosted environments. This architecture is digitizing revenue cycle management by enabling automated reconciliation across multiple toll authorities without physical data center infrastructure.
The Federal Highway Administration's interoperability rulemaking under MAP-21 is mandating cross-jurisdictional tag compatibility. This regulatory pressure forces legacy system operators to retrofit RFID readers for multi-protocol support. The Texas Triangle corridor faces the most acute compliance pressure as the largest multi-authority region without unified tag standards.
Fleet operators are consolidating toll account management through third-party logistics platforms rather than maintaining direct relationships with individual toll authorities. Commercial trucking companies with interstate routes are adopting centralized billing services that aggregate transactions across multiple state systems. This channel shift is most visible in the Midwest-Atlantic freight corridors where large carriers operate dense terminal networks.
North America Electronic Toll Collection (ETC) Market Segmentation
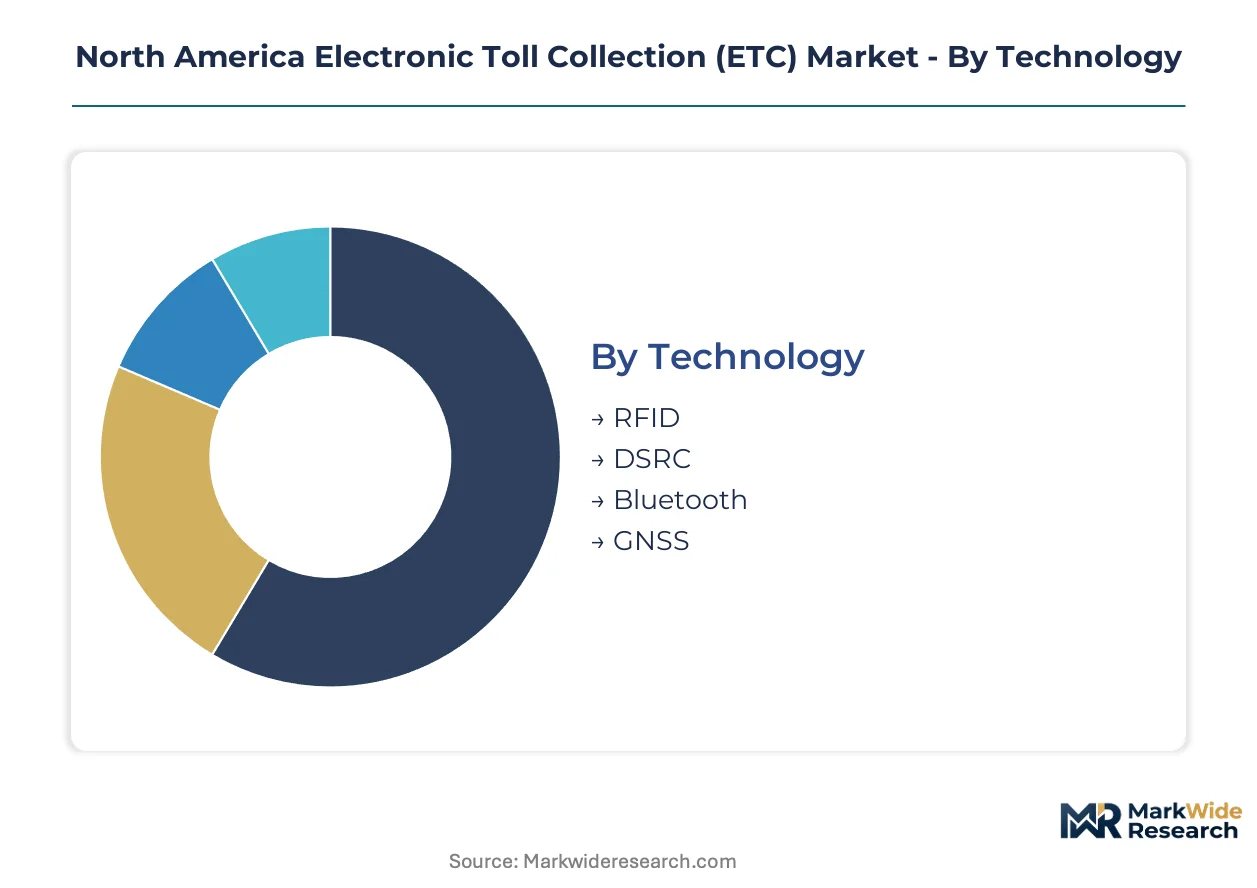
Technology choices in North American tolling infrastructure lock in decades of operational costs and interoperability obligations. Deployment architectures determine whether agencies retain capital flexibility or surrender control to vendor-hosted environments. Payment method preferences reshape customer acquisition economics and back-office complexity.
Technology:
The use-case spectrum spans legacy tag compatibility through satellite-based distance charging, with each protocol carrying distinct infrastructure investment profiles and regulatory compliance requirements.
- RFID:Passive radio-frequency identification tags operating at 915 MHz dominate installed capacity across the Eastern Seaboard. Legacy tag populations in Florida and New Jersey create switching friction that slows migration despite superior technical alternatives.
- DSRC:Dedicated short-range communications in the 5.9 GHz band enables free-flow gantry transactions without cellular dependency. The Federal Communications Commission's reserved spectrum allocation accelerates deployment across the Texas Triangle corridor where multi-authority consolidation demands reliable low-latency handshakes.
- Bluetooth:Short-range wireless protocol supports smartphone-based vehicle identification for infrequent users and rental fleets. California transportation authorities pilot Bluetooth augmentation to reduce transponder distribution costs.
- GNSS:Global navigation satellite system positioning enables mileage-based user fee calculations without roadside infrastructure. Oregon and Utah experimental programs create demand for GPS-enabled onboard units with integrated payment processing.
The dominant share belongs to RFID, while DSRC is closing the gap fastest.
Deployment:
Cost tier separation distinguishes capital-intensive ownership from recurring subscription models, with hybrid architectures emerging as a risk-mitigation pathway for budget-constrained agencies.
- On-Premises:Agency-operated data centers with perpetual software licenses require substantial upfront capital and internal IT staffing. State departments of transportation in the Midwest retain these configurations where legislative appropriations favor asset ownership over operational expenditure.
- Cloud-Based:Vendor-hosted SaaS platforms eliminate physical infrastructure while enabling real-time analytics and automated reconciliation. Florida's SunPass and California's FasTrak migrations demonstrate how cloud-native architectures compress revenue cycle management timelines.
- Hybrid:Split configurations maintain sensitive transaction processing on-premises while offloading analytics and customer portals to cloud environments. Texas toll authorities adopt this model to balance cybersecurity compliance with scalability needs.
- Edge Computing:Distributed processing at gantry locations reduces latency for congestion pricing and dynamic rate adjustments. This architecture gains traction in urban corridors where real-time vehicle classification demands immediate decision-making.
Cloud-based deployment is expanding most quickly, though hybrid retains preference among risk-averse procurement committees.
End User:
Customer type concentration varies by project scale, with multi-state corridors attracting private capital while single-authority upgrades remain publicly financed.
- Government:State departments of transportation procure integrated systems through competitive bidding governed by Federal Highway Administration interoperability mandates. These entities prioritize tag compatibility across jurisdictional boundaries over proprietary feature differentiation.
- Private Operators:Concessionaire-financed toll roads in Texas and Virginia demand turnkey solutions with availability-payment structures that transfer operational risk to vendors.
- Transportation Authorities:Regional toll entities in the Northeast and California manage complex multi-jurisdictional clearinghouse functions requiring specialized back-office software.
- Agencies:Metropolitan planning organizations and bridge districts operate smaller-scale deployments with limited procurement flexibility.
Government entities command the dominant share, while private operators are gaining ground fastest through public-private partnership structures.
Payment Method:
Maturity differentiation separates established prepaid account structures from emerging mobile platforms that target infrequent users with lower friction onboarding.
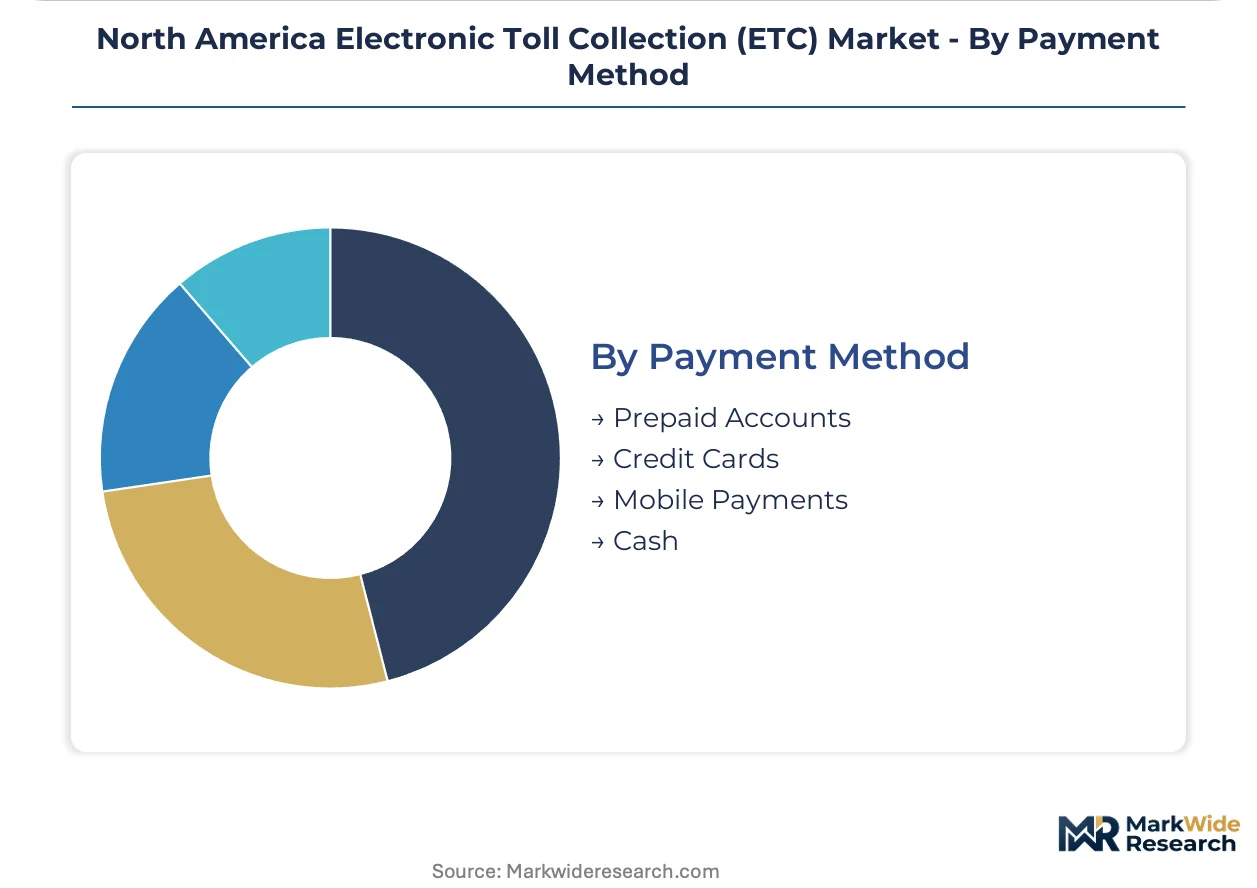
- Prepaid Accounts:Dedicated transponder-linked balances with automatic replenishment sustain recurring revenue for toll authorities. These accounts dominate commercial fleet management where centralized billing reduces administrative overhead.
- Credit Cards:Post-paid transaction processing with per-use billing accommodates occasional users without account maintenance. This method carries higher processing fees that erode margin on low-value transactions.
- Mobile Payments:Smartphone applications with license plate recognition displace transponder requirements for rental cars and out-of-state visitors. Platform providers compete for licensing revenue with transportation authorities seeking reduced customer acquisition costs.
- Cash:Manual lane retention serves unbanked populations and legacy system holdouts. Declining volume threatens the economic viability of staffed infrastructure maintenance.
Prepaid accounts retain the dominant share, while mobile payments are climbing the fastest among technology-forward user segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian procurement committees extract 15-20% vendor concessions unavailable to US counterparts, while Mexican infrastructure budgets operate on compressed federal cycles that favor rapid-deployment contracts over multi-year system builds.
United States
The Texas Triangle corridor generates concentrated demand as Dallas, Houston, and San Antonio toll authorities consolidate legacy tag systems. The Federal Highway Administration enforces MAP-21 interoperability mandates that reshape transponder compatibility requirements across state lines. Florida's SunPass migration to cloud-native architectures demonstrates how state transportation agencies compress revenue cycle management timelines.
Canada
Provincial crown corporations in Ontario and Quebec prioritize availability-payment structures that transfer operational risk to vendors. Transport Canada coordinates with the Federal Highway Administration on cross-border tag compatibility protocols. The Greater Toronto Area anchors demand for multi-jurisdictional clearinghouse infrastructure serving provincial highway networks.
Mexico
Federal highway concessionaires deploy free-flow tolling across the Mexico City-Querétaro-León freight corridor to reduce commercial transit delays. The Secretariat of Communications and Transportation governs spectrum allocation for dedicated short-range communications infrastructure. Nuevo León's Monterrey metro area pilots integrated payment processing for cross-border commercial fleets.
North America Electronic Toll Collection (ETC) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the transponder and antenna supply chains. The vendor base separates into turnkey solution providers, RFID tag fabricators, and back-office software specialists. Three archetypes dominate: European-headquartered infrastructure conglomerates with transponder manufacturing scale, North American system integrators with legacy retrofit expertise, and software-centric vendors with recurring SaaS revenue models. Competitive moves concentrate on cloud migration partnerships and multi-state interoperability certifications.
Within the infrastructure conglomerate tier, Kapsch TrafficCom and Thales Group occupy positions defined by transponder manufacturing integration with turnkey deployment capabilities. TransCore exemplifies the North American system integrator archetype through its concentration on legacy RFID tag supply chains. Conduent represents the software-centric model with specialized back-office clearinghouse platforms that generate recurring revenue streams with transportation authorities.
| Leading Market Players |
|---|
| Kapsch TrafficCom |
| TransCore |
| Conduent |
| Thales Group |
| Siemens |
| TRMI Systems Integration |
| Cubic Transportation Systems |
| Neology |
| EMOVIS |
| Others |
Value Network & Pricing Analysis
Undercapacity at Asian semiconductor foundries is compressing transponder availability and forcing North American system integrators toward premium pricing for expedited component delivery. This supply tightness simultaneously elevates procurement costs for toll authorities and accelerates their migration toward cloud-native architectures that reduce hardware dependency.
Pricing Analysis
The customization-premium spread separates standard RFID tag deployments from configured-to-order multi-protocol gantry systems. SaaS-tiered subscription models dominate cloud-based back-office platforms, while project-based pricing governs turnkey infrastructure builds. Price differentiation rests on certification level—FCC-compliant DSRC modules command premiums over unlicensed alternatives—and customization depth for multi-state interoperability. Cost compression in standard transponder tiers is intensifying because foundry capacity constraints are easing, though margins remain protected in specialized C-V2X-enabled units. Municipal transportation agencies exhibit highest price sensitivity, while private concessionaires in Texas and Virginia absorb premiums for availability-payment structures.
Supply Chain Analysis
Upstream feedstock for transponder chip fabrication concentrates in Taiwan, South Korea, and mainland China, with advanced node production anchored in Taiwanese foundries. The supply chain draws from silicon wafers, RF substrate laminates, and epoxy molding compounds as critical inputs. Single-source vulnerability in 5.9 GHz band RF front-end components exposes integrators to allocation risk during demand spikes. Distribution runs through direct OEM relationships with toll authorities, supplemented by systems integrator channels for retrofit deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment—specifically MAP-21 interoperability mandates—creates high switching costs for transportation agencies locked into certified vendor ecosystems.
For Market Incumbents: Build certification moats by accelerating multi-state interoperability testing protocols before competitors achieve compliance. Deepen backward integration into transponder manufacturing to secure chip supply against Asian foundry volatility. Prioritize cloud migration partnerships with Florida and California agencies to capture recurring SaaS revenue streams that cement long-term relationships. For New Entrants and Emerging Players: Pursue white-space opportunities in mileage-based user fee pilot programs across Oregon and Utah, where GPS-enabled onboard unit demand outpaces incumbent supply capacity. Target Bluetooth-augmented smartphone tolling applications for rental fleet segments that traditional transponder vendors underserve. Position through platform licensing models rather than hardware-heavy competitive bids. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among back-office software specialists with cloud-native clearinghouse platforms. Long-term viability favors vendors with diversified state agency relationships spanning multiple procurement cycles. Acquisition targets should demonstrate active MAP-21 certification pipelines. Cross-border tolling integration between US and Canadian corridors represents the signal to watch as inflection indicator for consolidation activity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-State Interoperability Certification | FHWA MAP-21 compliance opens procurement access across Texas Triangle corridor authorities. |
| Cloud-Native Back-Office Migration | Florida SunPass and California FasTrak deployments demonstrate compressed revenue cycle timelines. |
| Transponder Manufacturing Scale-Up | Captive chip supply insulates against Taiwan foundry allocation volatility during demand spikes. |
| C-V2X Technology Licensing | FCC 5.9 GHz spectrum rules enable next-generation congestion pricing with dynamic rate adjustments. |
| Mileage-Based User Fee Pilot Partnership | Oregon and Utah experimental programs create demand for GPS-enabled integrated payment units. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC spectrum allocation filings, FHWA interoperability rulemaking documents, state DOT procurement databases, and toll authority annual reports. Primary interviews engaged chief technology officers at transportation authorities, procurement directors at state DOTs, systems integration engineers, and back-office software architects. Secondary validation drew from SEC 10-K disclosures of publicly traded vendors, NTTA and TxTag contract award announcements, and ITS America technical standards publications. Bottom-up unit economics for transponder deployments triangulate against top-down market sizing from toll transaction volume data.
Forecast inputs span technology substitution curves between RFID, DSRC, and GNSS protocols; cloud deployment adoption rates across state agency procurement cycles; and interoperability mandate compliance timelines. Segmentation dimensions include technology type, deployment architecture, end-user category, and payment method preference. CAGRs derive from installed base replacement schedules and greenfield corridor development pipelines. Model sensitivity incorporates DSRC spectrum reallocation risk and mileage-based user fee legislative adoption patterns.
Sensitivities concentrate around semiconductor supply normalization timelines, MAP-21 enforcement intensity variations across federal administrations, and state budget appropriation delays. Forecasts embed assumptions regarding multi-protocol reader retrofit economics and cloud migration cost trajectories. Cross-checking against FHWA Highway Statistics and IBTTA transaction volume benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Connected Car Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
Global Automotive Infotainment System Market
Telematics and Infotainment
In Vehicle Infotainment Market
Telematics and Infotainment
Car Generated Data Market
Telematics and Infotainment
Advanced Traveller Information System Market
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
Transport Data Logger Market
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
Global Car Sharing Telematics Market
Telematics and Infotainment
Mobility on Demand (Mod) Market