
 Saudi Arabia Third-Party Logistics (3PL) Market | 2026-2036
Saudi Arabia Third-Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Third-Party Logistics (3PL) Market Analytics
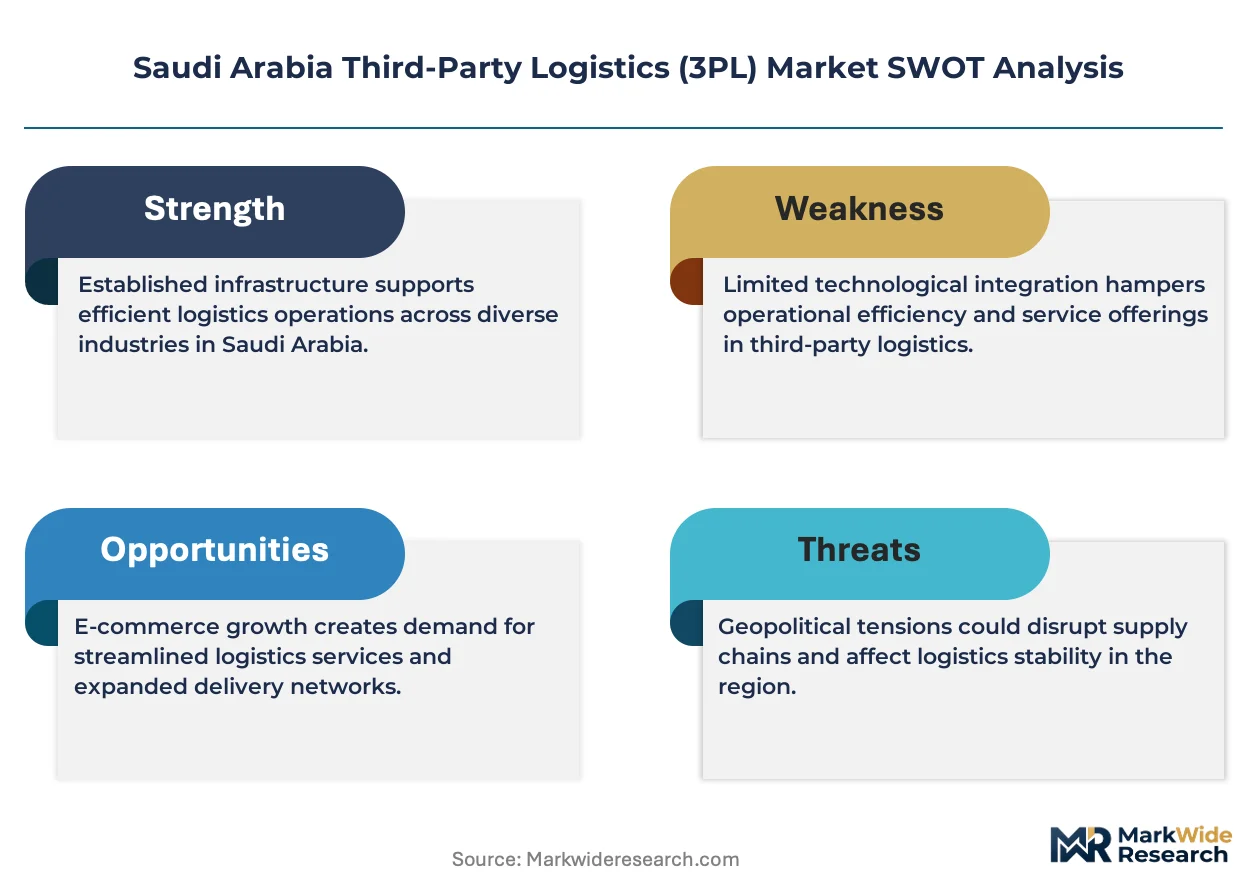
Pharma-grade cold chain certification is redrawing competitive boundaries in Saudi 3PL. DHL Supply Chain & Global Forwarding leverages its European-certified temperature infrastructure to capture vaccine and biologics contracts. Wared Logistics anchors its position through captive port access at King Abdullah Economic City. Logexa differentiates via last-mile density in Jeddah's dense retail corridors.
Third-party logistics encompasses outsourced transportation, warehousing, and inventory management executed under service-level agreements with defined KPIs for order accuracy, damage rates, and on-time delivery. The discipline eliminates capital-intensive asset ownership while granting shippers variable cost structures tied to shipment volume. Transportation services dominate revenue pools given Saudi Arabia's 7,000-kilometer highway network and heavy reliance on road freight for domestic distribution. Warehouse Management Systems represent the fastest-growing technology segment as operators retrofit legacy facilities for real-time inventory visibility. Cloud Logistics adoption lags among mid-tier providers constrained by IT staffing shortages.
SFDA mandates temperature documentation for pharmaceutical shipments, compelling 3PL operators to deploy validated cold chain infrastructure. The Saudi Customs Authority's Bayan single-window platform and SASO's product conformity assessments shape market access timelines for cross-border freight. Stakeholders must weigh regulatory compliance costs against automation investments as customs digitization accelerates.
Market Dynamics
E-commerce fulfillment velocity is compressing order cycle times across Saudi retail networks. The SFDA's cold chain mandates and SASO's product conformity assessments are forcing asset-heavy infrastructure bets that reshape competitive economics.
Growth Catalysts
- Bayan Single-Window Platform:The Saudi Customs Authority's digitized clearance system collapses border processing timelines. Cross-border freight operators gain predictable dwell times at King Abdulaziz Port.
- Pharmaceutical Cold Chain Mandates:SFDA temperature documentation requirements for biologics and vaccines drive outsourcing to certified 3PL operators. Captive fleet investments become uneconomical for mid-size drug distributors.
- Riyadh Industrial Corridor Concentration:Manufacturing inbound volumes from Jubail's petrochemical complexes and Sudair's automotive plants strain bonded warehouse capacity. Third-party operators capture overflow storage demand.
Market Restraints
- Diesel Price Volatility:Road freight dominates Saudi Arabia's 7,000-kilometer highway network. Fuel cost swings compress margins for asset-light operators without fuel surcharge mechanisms.
- IT Talent Scarcity:Cloud Logistics adoption lags among mid-tier providers. Warehouse Management System deployments stall due to staffing gaps in Riyadh and Jeddah tech labor pools.
- Port Access Concentration:King Abdullah Port and Jeddah Islamic Port handle the majority of containerized imports. Bonded yard capacity constraints create queuing costs during peak import seasons.
Strategic Opportunities
- Last-Mile Density in Secondary Cities:Dammam and Khobar retail corridors lack dedicated fulfillment infrastructure. E-commerce platforms seek localized distribution nodes to compress delivery windows.
- Reverse Logistics for Electronics:SASO repair and recycling regulations create compliance-driven service demand. 3PL operators can capture end-of-life product flows from Riyadh's consumer electronics retailers.
- NEOM Logistics Zone Development:The giga-project's planned trade and manufacturing hub requires integrated supply chain services. Early operators gain anchor tenant relationships and long-term contracts.
Industry Challenges
- Warehouse Management System Integration:Legacy facilities in Jeddah's industrial zones require retrofitting for real-time inventory visibility. Capital requirements strain mid-tier operators without parent-company technology subsidies.
- SFDA Certification Timelines:Pharma-grade cold chain validation involves extended qualification periods. Temperature mapping and equipment qualification delay contract start dates for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Third-Party Logistics (3PL) Market |
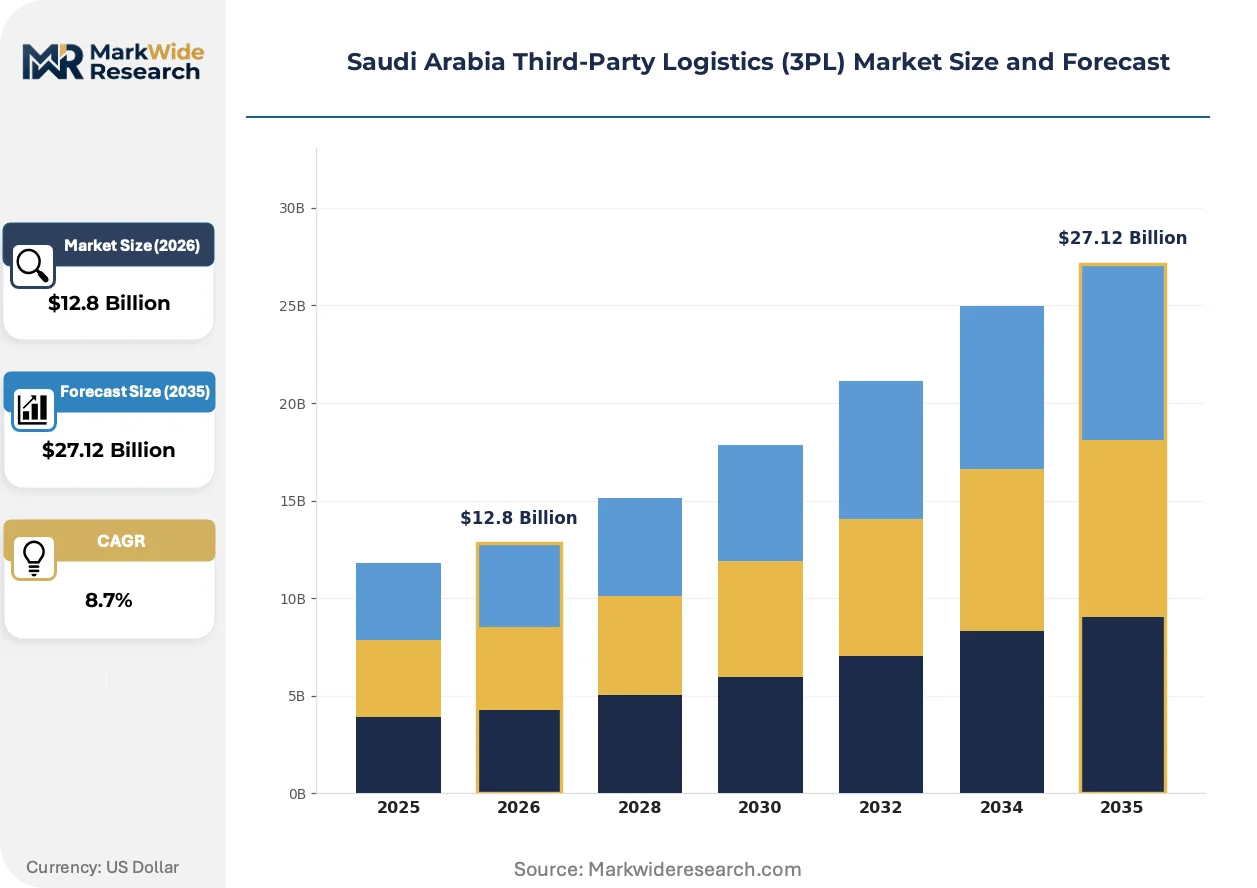
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Value-Added Services Technology: Warehouse Management Systems, Transportation Management Systems, Cloud Logistics, IoT Solutions End User: E-commerce, Retail, Manufacturing, Automotive Delivery Mode: Road, Rail, Air, Sea |
| Companies Covered | PSL Arabia, Logexa, Wared Logistics, DHL Supply Chain & Global Forwarding, Aramex International LLC, SHIPHYPE Fulfillment, ALKARSF, CEVA Logistics AG, 4U Logistic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Third-Party Logistics (3PL) Market Evolving Landscape
Technology convergence and regulatory digitization are reconfiguring asset deployment patterns across Saudi logistics networks. Operators face simultaneous pressure to automate core processes while certifying specialized infrastructure.
Autonomous mobile robots are supplanting manual picking in Riyadh's high-velocity e-commerce fulfillment centers. Majid Al Futtaim Retail and Jarir Bookstore distribution facilities deploy robotic goods-to-person systems to compress order cycle times. Labor cost arbitrage is narrowing as wage inflation in Eastern Province logistics clusters accelerates automation payback periods.
SASO's product conformity assessment integration with the Bayan platform compresses pre-clearance documentation timelines. Importers must pre-submit technical files before vessel arrival at King Abdulaziz Port. Electronics and automotive parts distributors face the steepest compliance learning curves as certificate of conformity requirements expand to additional HS codes.
Consolidated procurement of bundled warehousing and transportation services is displacing standalone contract awards among Saudi supermarket chains. Retailers negotiate integrated service agreements with single accountability for stock availability and on-shelf presence. Danube and Tamimi Supermarkets have shifted toward multi-year partnerships with defined KPIs spanning inventory accuracy and shrinkage rates.
Saudi Arabia Third-Party Logistics (3PL) Market Segmentation
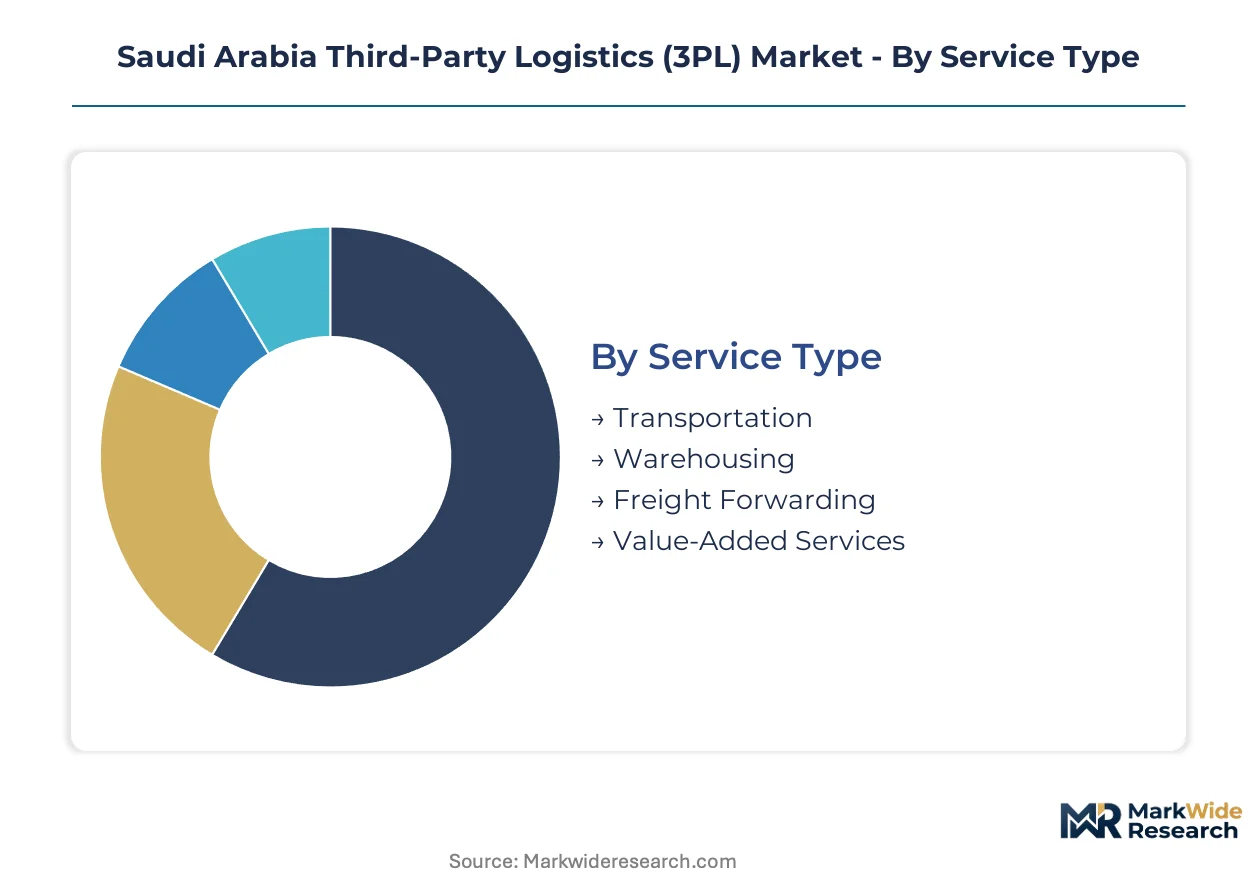
Segmentation in Saudi Arabia's 3PL market reveals how service bundling and technology adoption diverge between domestic distribution networks and export-oriented supply chains. Understanding these splits helps operators allocate capital across Riyadh's industrial corridor versus Jeddah's port-centric infrastructure.
Service Type:
Domestic distribution leans heavily on road-based transportation and warehousing, while freight forwarding and value-added services cluster around King Abdulaziz Port and King Abdullah Economic City for export-bound cargo.
- Transportation:Road freight dominates Saudi Arabia's 7,000-kilometer highway network, with dedicated fleet contracts serving Jubail's petrochemical complexes and Sudair's automotive assembly plants. Diesel price volatility compresses margins for operators lacking fuel surcharge mechanisms in their service-level agreements.
- Warehousing:Bonded storage capacity concentrates in Riyadh's industrial corridor, where overflow demand from manufacturing inbounds strains existing facilities. SFDA-certified cold rooms command premium rates for pharmaceutical and biologics inventory.
- Freight Forwarding:Customs brokerage and documentation services anchor cross-border flows through Jeddah Islamic Port. Bayan single-window integration is displacing traditional paper-based clearance workflows.
- Value-Added Services:Kitting, labeling, and quality inspection support retail distribution networks. SASO conformity pre-assessment integration is expanding service scope for electronics importers.
Transportation commands the established base. The steepest expansion runs through value-added services as retailers seek integrated accountability for stock availability.
Technology:
Investment intensity varies sharply by operator tier, with multinational subsidiaries deploying full technology stacks while mid-tier providers struggle with IT staffing gaps in Riyadh and Jeddah labor markets.
- Warehouse Management Systems:Real-time inventory visibility platforms retrofit legacy facilities in Jeddah's industrial zones. Capital requirements strain operators without parent-company technology subsidies.
- Transportation Management Systems:Route optimization and carrier selection tools reduce empty miles on long-haul corridors connecting Dammam to Riyadh. Fuel cost pass-through algorithms protect margin integrity.
- Cloud Logistics:SaaS-based platforms enable variable-cost scaling for seasonal volume spikes. Adoption lags among mid-tier providers constrained by cybersecurity compliance and data sovereignty concerns.
- IoT Solutions:Cold chain temperature monitoring satisfies SFDA documentation mandates for pharmaceutical shipments. Sensor deployment accelerates in vaccine and biologics distribution networks.
Warehouse Management Systems anchor current infrastructure spending. Cloud Logistics is gaining share fastest as operators seek to avoid heavy capital deployment.
End User:
Demand profiles split between velocity-driven e-commerce fulfillment and compliance-heavy manufacturing supply chains, with retail occupying an intermediate position on both dimensions.
- E-commerce:Same-day and next-day delivery promises compress order cycle times. Last-mile density investments concentrate in Jeddah's dense retail corridors and Riyadh's suburban fulfillment zones.
- Retail:Supermarket chains negotiate multi-year integrated service agreements with defined KPIs spanning inventory accuracy and shrinkage rates. Consolidated procurement is displacing standalone transportation or warehousing contracts.
- Manufacturing:Inbound component logistics and finished goods distribution serve Jubail's petrochemical sector and Sudair's automotive plants. Bonded warehouse overflow demand peaks during production ramp-ups.
- Automotive:Just-in-time sequencing and reverse logistics for parts distribution require specialized handling infrastructure. SASO repair and recycling regulations create compliance-driven service demand for end-of-life flows.
Retail commands the established base. E-commerce is climbing the fastest as platform operators expand fulfillment infrastructure into secondary cities.
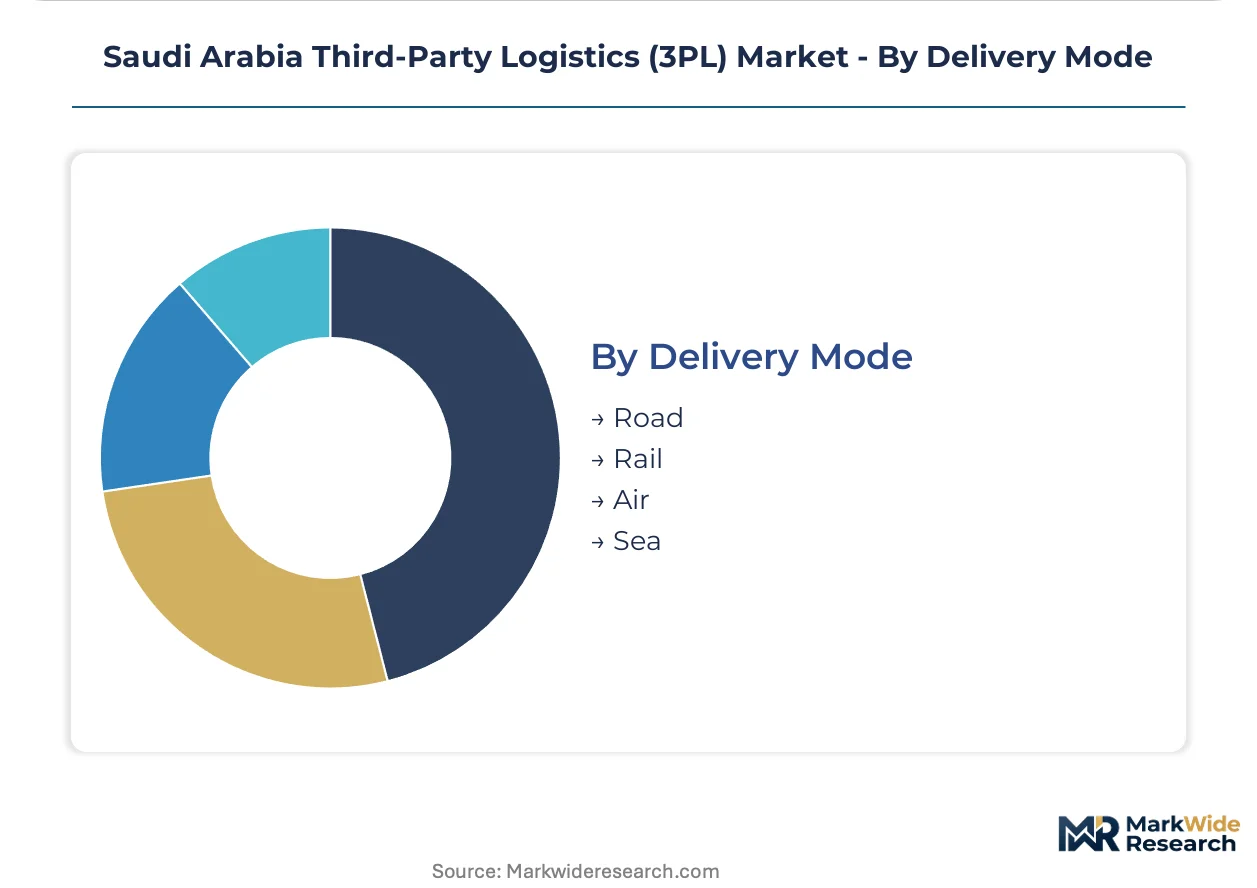
Delivery Mode:
Road freight's dominance reflects Saudi Arabia's continental geography and distributed population centers, while air and sea modes concentrate on specific cargo categories and corridor economics.
- Road:Full-truckload and less-than-truckload services cover the 7,000-kilometer highway network connecting Riyadh, Jeddah, Dammam, and secondary cities. Fleet ownership economics favor dedicated contracts over spot market exposure.
- Rail:Saudi Railway Company's freight corridors link King Abdulaziz Port to Riyadh's industrial zone. Bulk commodity flows and containerized imports utilize rail for long-haul trunk movements.
- Air:Express and time-critical shipments move through King Khalid International and King Abdulaziz International airports. Pharma cold chain certification extends to airside handling facilities.
- Sea:Containerized imports dominate King Abdullah Port and Jeddah Islamic Port volumes. Bonded yard capacity constraints create queuing costs during peak import seasons.
Road commands the established base. Rail is expanding most quickly as port-to-inland corridor investments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics capacity concentrates in Saudi Arabia's central and coastal corridors, with bonded warehouse space trailing manufacturing inflows. The Eastern Province and Riyadh industrial zones absorb the majority of 3PL investment, while port-centric infrastructure clusters around Jeddah and King Abdullah Economic City.
Riyadh
E-commerce fulfillment velocity drives warehouse demand in Riyadh's suburban zones, with same-day delivery promises compressing inventory positioning. SFDA cold chain mandates push pharmaceutical distributors toward certified third-party operators. Sudair's automotive assembly plants generate overflow bonded storage demand during production ramp-ups.
Eastern Province
Jubail's petrochemical complexes require specialized hazardous materials handling and dedicated fleet contracts for inbound feedstock logistics. The Saudi Customs Authority's Bayan platform integration accelerates clearance workflows at King Abdulaziz Port. Dammam and Khobar retail corridors lack localized fulfillment nodes, forcing e-commerce platforms to extend delivery windows.
Western Region
Jeddah Islamic Port handles the majority of containerized consumer goods imports, with bonded yard constraints creating seasonal queuing costs. SASO product conformity pre-assessment requirements compress documentation timelines for electronics distributors. Last-mile density investments concentrate in Jeddah's dense urban retail corridors.
NEOM Northwest
The giga-project's planned trade and manufacturing hub requires integrated supply chain services from ground-up development. Early 3PL operators gain anchor tenant relationships and long-term contract structures. Rail corridor investments linking NEOM to King Abdulaziz Port will reshape intermodal freight economics.
Saudi Arabia Third-Party Logistics (3PL) Market Competitive Landscape
Concentration sits with multinational logistics networks and Saudi-owned port-centric operators. The market exhibits tiered structure: global forwarders with pharma-certified infrastructure, domestic players with captive port access, and regional specialists with last-mile density. Strategic moves center on cold chain certification investments and integrated service bundling for retail accounts.
Within the multinational tier, DHL Supply Chain & Global Forwarding and CEVA Logistics AG represent European-certified temperature infrastructure operators. Wared Logistics anchors the domestic port-access archetype through King Abdullah Economic City positioning. Logexa exemplifies last-mile density specialists concentrated in Jeddah's urban corridors.
| Leading Market Players |
|---|
| PSL Arabia |
| Logexa |
| Wared Logistics |
| DHL Supply Chain & Global Forwarding |
| Aramex International LLC |
| SHIPHYPE Fulfillment |
| ALKARSF |
| CEVA Logistics AG |
| 4U Logistic |
| Others |
Value Network & Pricing Analysis
Bonded warehouse capacity utilization above 85% in Riyadh's industrial corridor has compressed price floors for overflow storage while elevating margins for SFDA-certified cold chain operators. Scale economies at King Abdullah Port anchor the cost structure for cross-border freight, with fuel surcharge mechanisms separating asset-heavy from asset-light competitors.
Pricing Analysis
SFDA cold chain mandates dictate the pricing tier structure across pharmaceutical logistics, with validated temperature infrastructure commanding premium rates over standard warehouse space. Three-tier pricing structure across certified pharma-grade, bonded customs, and standard commercial warehousing segments reflects compliance investment differentials. Cost compression in standard warehousing is intensifying because diesel price volatility erodes margins for operators lacking fuel pass-through clauses. Supermarket chains exhibit highest price sensitivity through consolidated procurement of bundled services, while vaccine distributors show lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Inventory positioning within 50 kilometers of final demand has become the critical lead-time determinant for e-commerce fulfillment promises. Manufacturing inputs draw from China, Germany, and South Korea for automotive and electronics assembly in Sudair and Jubail. Bonded yard capacity constraints at King Abdulaziz Port and Jeddah Islamic Port create single-source vulnerability during peak import seasons. Distribution runs through hub-and-spoke road networks radiating from Riyadh, with rail corridors gaining share for port-to-inland container movements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidated procurement among Saudi supermarket chains has shifted buyer power toward integrated service accountability, fragmenting standalone contract opportunities for mid-tier operators.
For Market Incumbents: Secure pharma-grade cold chain certification ahead of SFDA mandate expansion to capture vaccine and biologics outsourcing from captive distributors. Defend port-access advantages at King Abdullah Economic City through capacity expansion in bonded yard infrastructure, neutralizing emerging entrants lacking customs clearance integration. For New Entrants and Emerging Players: Anchor in Dammam and Khobar retail corridors where last-mile fulfillment infrastructure remains underdeveloped relative to e-commerce platform expansion timelines. Target secondary city distribution nodes with localized inventory positioning to compress delivery windows for platform operators. Lead with cloud-based Warehouse Management System deployment to circumvent IT talent scarcity constraining mid-tier incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with validated cold chain infrastructure and Bayan platform integration capabilities. Long-term viability rests on regulatory compliance moats rather than pure asset scale. Acquisition candidates should demonstrate SFDA certification progress and captive relationships with automotive or pharmaceutical anchor tenants. The inflection signal to watch is NEOM logistics zone tender announcements indicating anchor tenant selection timelines.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Cold Chain Certification | Validates temperature infrastructure for vaccine contracts against uncertified competitors. |
| Bayan Platform Integration | Compresses customs clearance timelines at King Abdulaziz Port for cross-border operators. |
| Last-Mile Density Expansion | Positions inventory within same-day delivery radius of Jeddah's dense retail corridors. |
| Cloud Logistics Deployment | Enables variable-cost scaling without heavy capital deployment for mid-tier providers. |
| NEOM Anchor Tenant Relationship | Secures long-term contract structures from ground-up logistics zone development. |
Research Methodology
Operator-level perspectives from warehouse managers, customs brokerage heads, pharmaceutical supply chain directors, and e-commerce fulfillment executives anchored the qualitative base. Secondary validation drew from Saudi Customs Authority trade statistics, SFDA regulatory filings, SASO conformity assessment databases, and bonded warehouse capacity registries. Bottom-up service revenue estimates triangulated against top-down logistics spend as percentage of GDP benchmarks.
Sensitivity analysis around diesel price trajectories and e-commerce penetration rates tested forecast robustness across the projection horizon. Segmentation dimensions modeled include service type, technology adoption tier, end-use vertical, and delivery mode. CAGRs were derived from logistic curve fitting to historical outsourcing penetration patterns, with pharmaceutical cold chain compliance timelines and NEOM infrastructure rollout schedules serving as industry-specific demand drivers.
Material uncertainties — regulatory enforcement intensity, fuel subsidy policy shifts, and port capacity expansion delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding SFDA mandate scope and Bayan platform adoption velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
North America Shipping Supplies Market
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
United States Contract Logistics Market
Logistics and Shipping
Europe Contract Logistics Market
Logistics and Shipping
ASEAN Cross Border Road Freight Transport Market
Logistics and Shipping
Egypt Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
Singapore Shipping Agency Services Market
Logistics and Shipping
Indonesia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
Retail Logistics Market
Logistics and Shipping
Germany Same Day Delivery Market
Logistics and Shipping
Europe Courier Market
Logistics and Shipping
US FTL Brokerage Market