
 Automotive Camera-Based Side Mirrors Market | 2026-2036
Automotive Camera-Based Side Mirrors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Camera-Based Side Mirrors Market Analysis
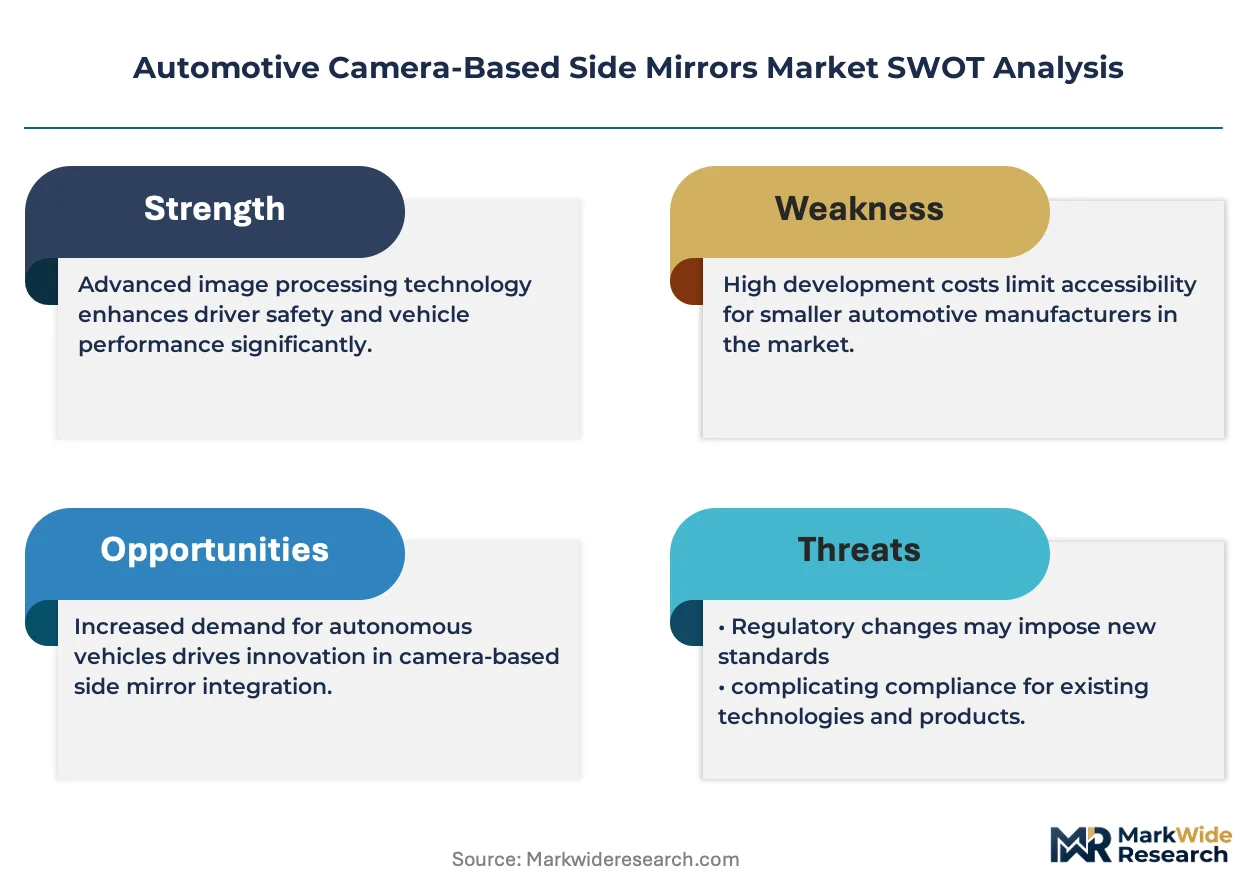
OEM supply channels for exterior vision systems is narrowing as automakers consolidate procurement around full-stack camera-monitor partners. Robert Bosch GmbH leverages its sensor fusion expertise to anchor integrated cockpit-vision contracts with European premium brands. Continental AG competes through its end-to-end domain controller architecture that bundles camera processing with mirror-replacement displays. Magna International Inc. sustains manufacturing scale across multiple vehicle platforms, controlling assembly capacity that smaller rivals cannot replicate.
Automotive camera-based side mirrors replace conventional reflective glass assemblies with exterior-mounted cameras and interior display panels, typically operating at 60 frames per second with high dynamic range sensors to maintain visibility across varying light conditions. These systems eliminate aerodynamic drag from traditional mirror housings while expanding the effective field of view through software-defined visual processing. Digital product variants within the product type segment command the deepest margin pools due to their embedded software content and over-the-air update architectures. Wide-angle technology configurations lead installation volumes among early adopters, though 3D vision implementations represent the fastest-expanding category as depth-perception algorithms mature for highway-merge scenarios.
Europe's ECE R46 framework and the United Nations Economic Commission for Europe's subsequent amendments have established the foundational homologation pathway for camera-based mirror replacement, while Japan's Ministry of Land, Infrastructure, Transport and Tourism has issued complementary type approval guidelines that enable Japanese OEM exports. The United States National Highway Traffic Safety Administration continues evaluating mirrorless exemptions under Federal Motor Vehicle Safety Standard 111, creating a compliance gap that delays full market activation. Stakeholders must monitor regulatory convergence between UN-ECE and NHTSA frameworks to time capital allocation for North American production readiness.
Market Dynamics
Consolidation of exterior vision procurement around full-stack camera-monitor partners is compressing supplier margins while elevating software-defined architectures above hardware-only contracts. This structural concentration favors integrated cockpit-vision providers with sensor fusion capabilities.
Growth Catalysts
- ECE R46 amendment:Europe's regulatory framework now permits camera-monitor systems as legal mirror replacements, removing the primary compliance barrier that stalled deployment across German and Swedish vehicle platforms.
- High dynamic range sensors:60 frames-per-second capture with adaptive exposure algorithms maintains visibility across tunnel-to-daylight transitions, addressing the safety validation threshold that previously blocked adoption.
- Premium EV platforms:Electric vehicle architectures from Lucid Motors and Rivian integrate camera-based mirrors as standard equipment, leveraging aerodynamic drag reduction to extend range.
Market Restraints
- Display panel cost volatility:OLED and high-brightness LCD substrate prices fluctuate with semiconductor foundry capacity allocation, squeezing margin on interior monitor assemblies.
- Federal Motor Vehicle Safety Standard 111:NHTSA's pending exemption evaluation for mirrorless vehicles creates a compliance gap that delays North American market activation and defers capital deployment.
- Conventional mirror substitution:Traditional reflective glass assemblies retain cost advantage below $50 per unit versus $400-$800 camera-monitor systems, limiting mass-market penetration.
Strategic Opportunities
- 3D vision convergence:Depth-perception algorithms maturing for highway-merge scenarios unlock premium tier pricing through enhanced situational awareness beyond flat-image displays.
- Over-the-air update architectures:Embedded software content enables recurring revenue streams through feature subscriptions and field performance optimization.
- Japanese type approval alignment:MLIT guidelines enabling OEM exports from Japan create regulatory harmonization that simplifies multi-homologation programs for German and Swedish manufacturers.
Industry Challenges
- Image processing latency:Sub-50-millisecond end-to-end delay requirements demand specialized silicon design capabilities scarce among traditional mirror suppliers.
- Multi-homologation complexity:Divergent UN-ECE and NHTSA testing protocols force parallel validation programs that extend development timelines and inflate certification budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Camera-Based Side Mirrors Market |
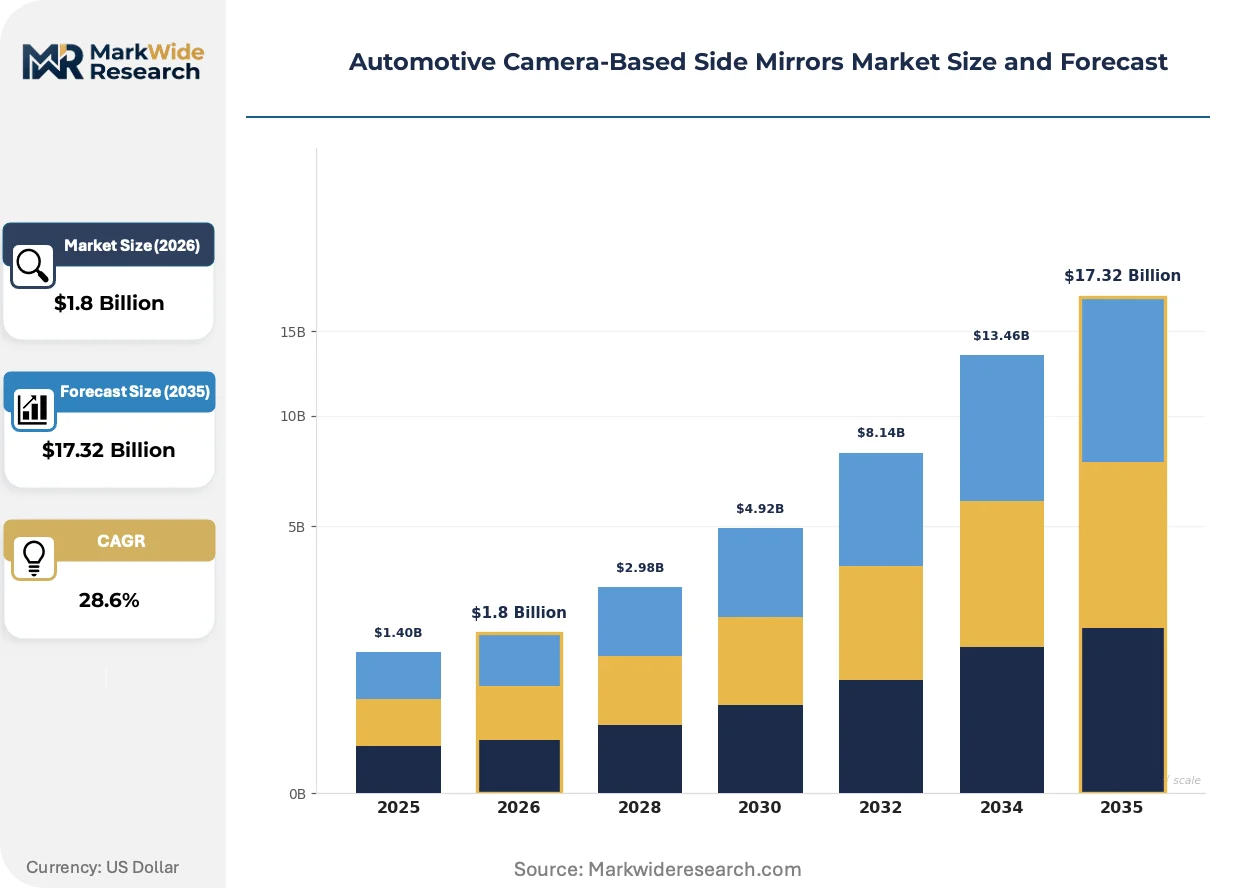
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Adaptive, Digital, Smart Technology: Infrared, Optical, Wide-Angle, 3D Vision End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation: Integrated, Retrofit, Factory-Fitted, Modular |
| Companies Covered | Continental AG, Robert Bosch GmbH, Magna International Inc., Hyundai Mobis Co. Ltd., Denso Corporation, Gentex Corporation, Ficosa Internacional SA, Samvardhana Motherson Reflectec, Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Camera-Based Side Mirrors Market Emerging Trajectories
Software-defined visual processing is collapsing the boundary between exterior sensing and interior display domains, enabling functional upgrades without hardware replacement. This architectural shift reconfigures competitive advantage toward algorithm developers.
Wide-angle camera configurations with electronic field-of-view expansion are collapsing the physical envelope of exterior mirror housings. Premium electric vehicle platforms from BMW and Mercedes-Benz deploy these systems to achieve drag coefficients below 0.20, compressing the aerodynamic penalty that conventional mirrors impose. The technology is collapsing hardware refresh cycles from seven-year model spans to continuous software deployment.
ECE R46 and subsequent UN-ECE amendments have established the foundational homologation pathway for camera-based mirror replacement across European type approval systems. Japan's MLIT has issued complementary guidelines that enable export certification reciprocity, while NHTSA continues evaluating mirrorless exemptions under FMVSS 111. European premium brands secure series production approval first, forcing North American stakeholders into regulatory catch-up positioning.
Fleet procurement of integrated cockpit-vision systems is displacing component-level sourcing for exterior mirrors. German automakers now contract full-stack camera-monitor-display architectures from single suppliers rather than assembling discrete camera and display modules. This bundling concentrates specification authority with sensor fusion specialists and compresses Tier-2 component opportunities in the supply base.
Automotive Camera-Based Side Mirrors Market Segmentation
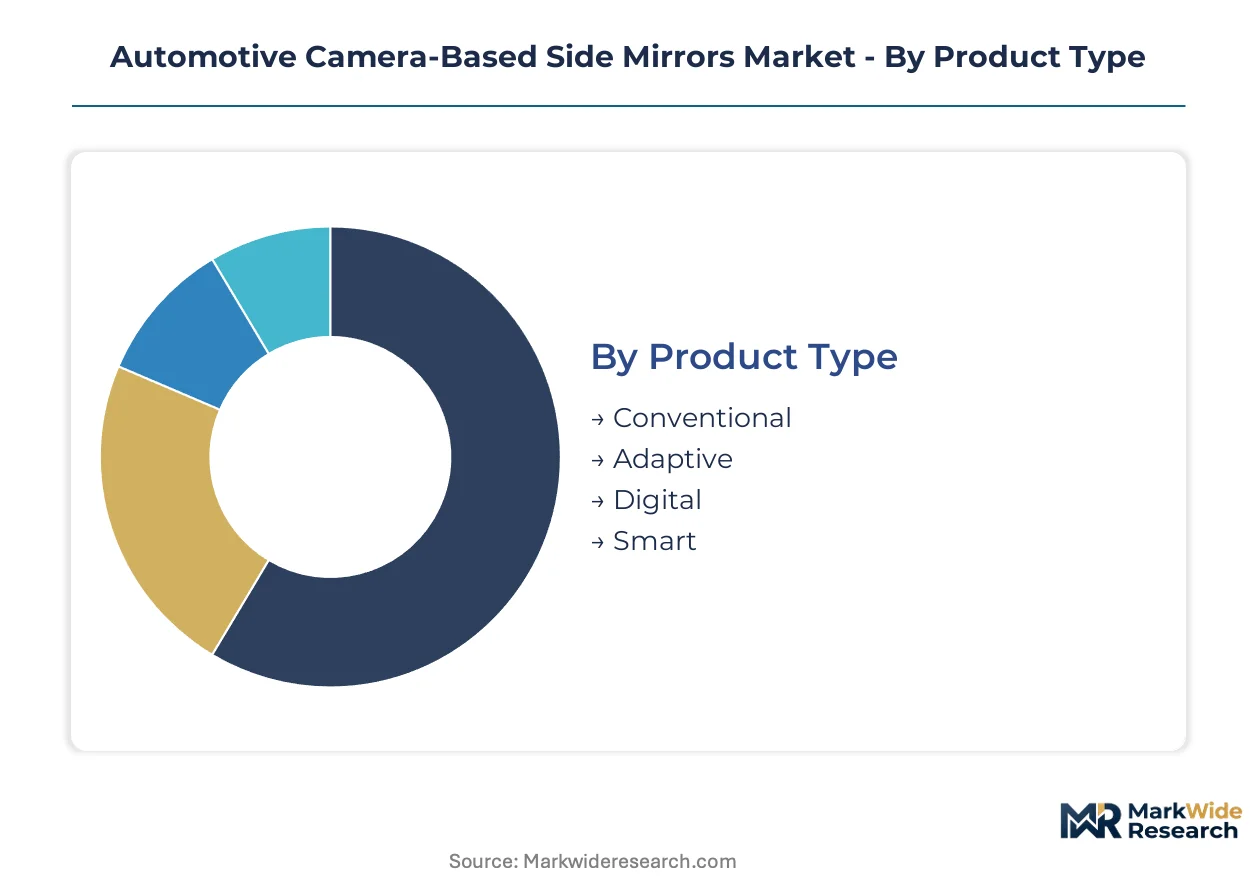
Camera-based mirror systems fragment across hardware sophistication, software integration depth, and supply chain position. Each segment carries distinct margin profiles and regulatory validation requirements that shape procurement decisions.
Product Type:
Applications span from basic compliance-grade systems to software-defined platforms with continuous upgrade paths.
- Digital:Embedded software architectures with over-the-air update capability command premium positioning. European premium EV platforms from BMW and Mercedes-Benz specify these systems for aerodynamic optimization and recurring revenue potential.
- Smart:AI-enabled object detection and predictive field-of-view adjustment differentiate highway safety performance. Lucid Motors integrates these as standard equipment, leveraging sensor fusion with autonomous driving stacks.
- Conventional:Basic camera-monitor configurations without software-defined features serve cost-sensitive fleet retrofits.
- Adaptive:Exposure-adjusting sensors with automatic brightness calibration address tunnel-to-daylight visibility transitions.
The dominant share belongs to Digital, while Smart is closing the gap fastest.
Technology:
Sensor modality determines processing architecture and homologation complexity across regulatory jurisdictions.
- Wide-Angle:Electronic field-of-view expansion eliminates physical mirror housing drag. German OEMs deploy these configurations to achieve sub-0.20 drag coefficients on flagship electric sedans.
- 3D Vision:Depth-perception algorithms using stereoscopic camera pairs enable highway-merge hazard detection. Rivian specifies these for commercial delivery van applications where spatial judgment reduces collision liability.
- Optical:Standard CMOS sensors with fixed focal lengths serve baseline regulatory compliance in markets with limited software validation requirements.
- Infrared:Thermal imaging extensions support low-visibility operation for heavy commercial vehicles in Nordic operating conditions.
Wide-Angle retains the largest installed base, though 3D Vision is expanding most quickly as depth algorithms mature.
End User:
Procurement authority concentrates with entities controlling type approval and assembly integration.
- OEMs:BMW, Mercedes-Benz, and Volkswagen Group direct full-stack architecture specifications. These manufacturers consolidate contracts around sensor fusion specialists with ECE R46 homologation experience.
- Tier-1 Suppliers:Robert Bosch GmbH and Continental AG bundle camera processing with domain controllers. Their integrated cockpit-vision contracts displace discrete component sourcing.
- Vehicle Assemblers:Contract manufacturers for emerging EV brands source pre-validated camera-monitor modules to accelerate production ramp.
- Aftermarket Providers:Retrofit specialists serve commercial fleets in Japan and Europe where regulatory frameworks permit post-factory installation.
OEMs control specification authority, while Tier-1 Suppliers are capturing margin through bundled system integration.
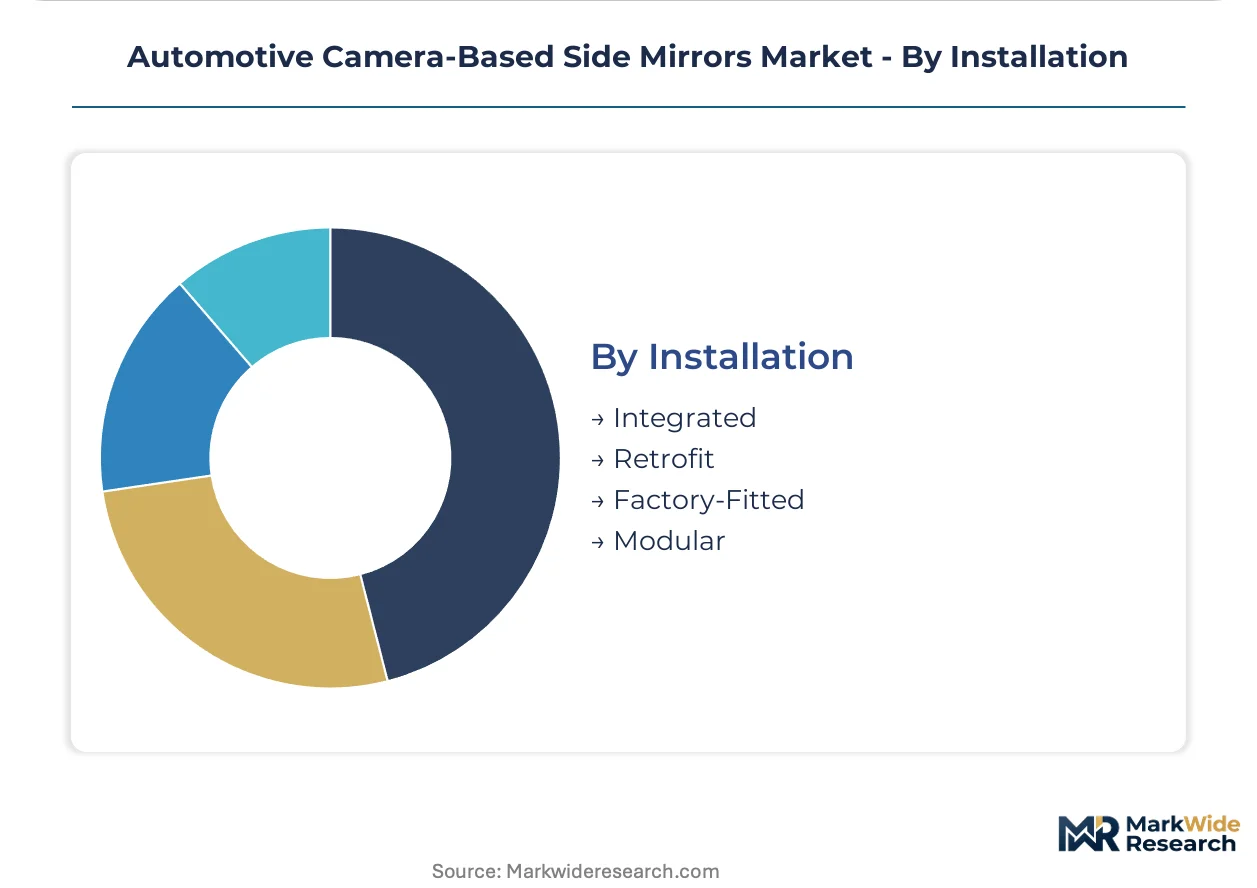
Installation:
Assembly method determines warranty liability and software validation scope.
- Factory-Fitted:Line-integrated installation with full vehicle network validation. This approach dominates German and Swedish production where ECE R46 type approval requires manufacturer-level certification.
- Integrated:Cockpit-domain consolidation where mirror replacement displays merge with instrument cluster and infotainment processing. Magna International scales this architecture across multiple vehicle platforms.
- Modular:Swappable camera and display units for service accessibility. Fleet operators favor this configuration for commercial vehicle uptime optimization.
- Retrofit:Post-assembly installation limited to jurisdictions with explicit aftermarket approval pathways.
Factory-Fitted leads installation volumes, with Integrated gaining share as domain controller architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pricing power through ECE R46 homologation authority while the United States remains captive to NHTSA exemption delays. Japanese type approval reciprocity unlocks export corridors for Asian OEMs. Chinese domestic certification accelerates parallel supply chain development outside Western regulatory frameworks.
Germany
KBA type approval for BMW and Mercedes-Benz series production vehicles anchors European market activation. ECE R46 amendment implementation through Germany's federal motor transport authority removes compliance uncertainty for mirrorless architectures. Stuttgart and Munich engineering clusters concentrate sensor fusion development for integrated cockpit-vision systems.
United States
NHTSA's pending FMVSS 111 exemption evaluation stalls domestic OEM deployment timelines despite fleet demand from premium EV manufacturers. Regulatory divergence from UN-ECE protocols forces parallel validation programs that inflate development budgets. Michigan and California automotive clusters await federal signal to activate capital deployment for mirrorless production lines.
Japan
MLIT type approval guidelines enable Japanese OEM export certification reciprocity with European markets. Toyota and Honda supply chain integration demands accelerate camera-monitor module standardization for multi-homologation programs. Nagoya and Tokyo metropolitan areas concentrate display panel and image processing semiconductor development.
South Korea
Hyundai and Kia platform integration drives domestic specification authority for camera-based mirror systems. MFDS automotive component certification alignment with international standards supports export-oriented production strategies. Seoul Capital Area clusters anchor domain controller and high-dynamic-range sensor manufacturing capacity.
China
MIIT vehicle component certification and GB standards development proceed independently of Western regulatory frameworks. Domestic OEMs including BYD and NIO deploy camera-monitor systems for aerodynamic optimization on flagship EV platforms. Yangtze River Delta manufacturing bases scale camera module assembly outside ECE R46 compliance requirements.
Automotive Camera-Based Side Mirrors Market Vendor Landscape
Full-stack integrators and component specialists split the market between bundled cockpit-vision contracts and discrete hardware supply. German and Japanese conglomerates anchor the consolidated tier through sensor fusion expertise and domain controller architectures. Three archetypes dominate: integrated cockpit-vision providers, manufacturing-scale assemblers, and regional component specialists. Competitive moves concentrate on strategic partnerships for software-defined architectures and capacity expansion across multi-platform vehicle programs.
Among integrated cockpit-vision providers, Robert Bosch GmbH and Continental AG exemplify the full-stack archetype through bundled camera-processing-display architectures. Magna International Inc. occupies a position as the manufacturing-scale anchor with cross-platform assembly capacity. Hyundai Mobis Co. Ltd. represents the Korean specialist tier with domestic OEM integration advantages. These three named entities collectively illustrate how supply chain position—sensor fusion expertise, manufacturing scale, or regional OEM relationships—determines procurement access in a consolidating market.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Magna International Inc. |
| Hyundai Mobis Co. Ltd. |
| Denso Corporation |
| Gentex Corporation |
| Ficosa Internacional SA |
| Samvardhana Motherson Reflectec |
| Valeo SA |
| Others |
Supply Flow & Price Mechanics
Stuttgart engineering clusters anchor high-dynamic-range sensor fabrication capacity, concentrating supply-side leverage among German Tier-1 suppliers who dictate pricing terms to OEMs seeking ECE R46 homologated systems.
Pricing Analysis
Configured-to-order pricing for software-defined camera-monitor architectures commands substantial premiums over standard camera-monitor configurations without over-the-air capability. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and embedded software content, with OEM direct contracts showing least price sensitivity and aftermarket retrofit channels exhibiting highest elasticity. Pricing pressure stems from OLED substrate cost volatility tied to semiconductor foundry allocation constraints. Fleet procurement managers in commercial vehicle segments demonstrate greatest price resistance due to total cost of ownership calculations.
Supply Chain Analysis
Export control regimes restricting high-resolution CMOS sensor technology limit component flows from specific jurisdictions, constraining supplier diversification for 60 frames-per-second capture modules. Manufacturing concentrates in Germany, Japan, and South Korea for domain controller integration and image processing silicon. Raw material dependencies span rare earth elements for sensor substrates, high-brightness LCD glass, and specialized optical coatings. Single-source vulnerability pervades stereoscopic camera pair supply for 3D vision implementations. Distribution runs through consolidated Tier-1 bundling contracts rather than discrete component marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where ECE R46 homologation experience creates entrenched regulatory switching costs that newcomer suppliers cannot readily replicate.
For Market Incumbents: Entrench sensor fusion capabilities through backward integration into specialized image processing silicon design, insulating margin pools from commodity camera module competition. Accelerate capacity addition in Stuttgart and Nagoya manufacturing corridors to preempt emerging EV platform awards. Lock in multi-homologation service contracts with German and Japanese OEMs before NHTSA framework convergence lowers regulatory barriers for challenger suppliers. For New Entrants and Emerging Players: Establish a beachhead in aftermarket retrofit channels serving Japanese commercial fleets where MLIT guidelines permit post-factory installation with reduced validation burdens. Target adaptive exposure-adjusting sensor configurations for Nordic heavy commercial vehicle operators seeking low-visibility operational enhancements. Pursue white-label manufacturing partnerships with Korean domain controller specialists to bypass direct ECE R46 certification requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithm developers with production-proven depth-perception stacks over hardware-only component suppliers facing margin compression. Long-term viability rests on software-defined architectures capable of recurring revenue extraction through feature subscriptions. Monitor NHTSA exemption determinations under FMVSS 111 as the critical inflection signal for North American market activation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | BMW and Mercedes-Benz consolidate camera-monitor specifications across electric vehicle architectures to compress procurement complexity. |
| Software-Defined Vehicle Investment | Lucid Motors integrates mirror replacement displays with autonomous driving sensor fusion stacks for functional convergence. |
| Battery Supply Agreement | Rivian leverages aerodynamic drag reduction from camera-based mirrors to extend commercial delivery van range per charge. |
| Geographic Manufacturing Footprint | Magna International scales cross-platform assembly capacity across multiple OEM production sites to defend incumbent positioning. |
| Charging Infrastructure Partnership | Continental AG bundles domain controller architectures with energy management systems for integrated cockpit-vision contracts. |
Methodological Framework
The analysis maps digital, smart, and adaptive camera-monitor sub-sectors, each validated through primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and ECE R46 homologation specialists. Secondary sources span vehicle production databases, IHS Markit registration data, UN-ECE regulatory filings, and semiconductor foundry capacity disclosures. Bottom-up segment sizing triangulates against top-down OEM procurement budget analysis.
Assumption sets held regulatory convergence timelines and sensor cost curves fixed while varying EV platform launch schedules and fleet electrification rates across the projection horizon. Segmentation dimensions span product type, technology modality, installation method, and regional production cluster. CAGRs derive from installed base growth modeling and content-per-vehicle trajectory analysis calibrated against aerodynamic efficiency targets and autonomous driving sensor fusion roadmaps.
Stress conditions across NHTSA exemption timing, OLED substrate pricing volatility, and 3D vision algorithm maturation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about ECE R46 adoption velocity and premium EV platform proliferation. Material shifts in UN-ECE and NHTSA regulatory harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Automotive Wire Harness Tape Market
Automotive Electronics & Wiring
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market
Automotive Electronics & Wiring
China Automotive Camera Market
Automotive Electronics & Wiring
Digital Tachographs Market
Automotive Electronics & Wiring
Smart Dash Cameras Market
Automotive Electronics & Wiring
Automotive Ultrasonic Technologies Market
Automotive Electronics & Wiring
Automotive Electronics Sensor Aftermarket Market
Automotive Electronics & Wiring
Automotive Cockpit Soc Market
Automotive Electronics & Wiring
Automotive Throttle-By-Wire System Market
Automotive Electronics & Wiring
Automotive Connectivity Control Unit Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Connected Car Devices Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market