
 Drive by Wire Market | 2026-2036
Drive by Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Drive by Wire Market Intelligence
The shift from discrete electronic control units to integrated domain controllers for chassis and powertrain functions is rebalancing buyer choice towards modular system platforms. Robert Bosch GmbH leverages its comprehensive portfolio of sensors, actuators, and software to offer complete systems. Continental AG competes with scalable solutions adaptable across multiple vehicle segments. ZF Friedrichshafen AG differentiates through its expertise in intelligent mechatronic systems for steering and braking.
Drive-by-wire technology replaces mechanical linkages in a vehicle with electronic controls, sensors, and actuators. These systems utilize communication protocols like CAN bus to translate driver inputs into precise vehicle actions, enabling advanced safety and automation features. While brake control represents a mature and foundational application, the steer-by-wire system segment is experiencing significant development, driven by its necessity for higher levels of autonomous vehicles. This makes the autonomous vehicle segment the primary locus of innovation and value capture.
Regulatory frameworks established by bodies like the U.S. National Highway Traffic Safety Administration (NHTSA) and through UNECE regulations mandate stringent safety and performance criteria. Conformance with functional safety standards such as ISO 26262 is essential for market access, requiring robust validation and fail-operational designs. Stakeholders must now focus on navigating emerging cybersecurity regulations and the architectural shift towards software-defined vehicles.
Market Dynamics
The automotive industry's pivot toward centralized and zonal electronic/electrical (E/E) architectures is the central force defining the market. This architectural shift simplifies wiring harnesses and enables the powerful, integrated control systems necessary for autonomous driving functions and software-defined vehicles.
Growth Catalysts
- Autonomous Vehicle Proliferation:The development of Level 3 and higher autonomous vehicles is fundamentally dependent on redundant and responsive drive-by-wire systems for steering, braking, and throttle, creating direct and accelerating demand.
- Safety Regulation Mandates:Frameworks like UNECE regulations for advanced driver-assistance systems and functional safety standards such as ISO 26262 compel automakers to integrate fail-operational electronic control systems for market access.
- Commercial Fleet Efficiency:In logistics and long-haul trucking, drive-by-wire enables features like platooning and predictive cruise control, which offer significant fuel savings and operational cost reductions, spurring adoption.
Market Restraints
- High System Cost:The expense associated with redundant sensors, actuators, and high-integrity electronic control units, particularly for steer-by-wire, remains a significant barrier for adoption in mass-market vehicle segments.
- Cybersecurity Vulnerabilities:The reliance on in-vehicle networks like CAN bus exposes drive-by-wire systems to remote hacking risks, requiring complex and costly security measures to prevent malicious control of vehicle functions.
- Technical Redundancy Complexity:Designing and validating fail-operational systems that guarantee vehicle control in the event of a primary system failure is technically challenging and adds substantial development overhead and cost.
Strategic Opportunities
- Off-Highway Vehicle Automation:A significant opportunity exists to adapt drive-by-wire technology for agricultural tractors, mining trucks, and construction equipment to enable precision operations, remote control, and autonomous functionality.
- Software-Defined Functionality:The shift to software-defined vehicles allows for post-sale feature upgrades and new revenue streams through over-the-air (OTA) updates that can enhance or add drive-by-wire functionalities.
- Aftermarket Retrofit Systems:Developing certified drive-by-wire retrofit kits for commercial vehicle fleets presents a channel to bring advanced safety and automation features to existing assets without full vehicle replacement.
Industry Challenges
- Functional Safety Expertise Gap:A shortage of software and systems engineers with deep expertise in ISO 26262 compliance and the development of safety-critical embedded systems constrains product development capacity across the industry.
- Supply Chain Integration:Ensuring seamless interoperability and data exchange between drive-by-wire modules from different Tier 1 suppliers within a single OEM platform creates significant integration challenges for vehicle manufacturers.
- Validation and Certification Bottlenecks:The extensive volume of simulation and real-world testing required to validate the safety of by-wire systems creates long and expensive certification cycles, delaying time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drive by Wire Market |
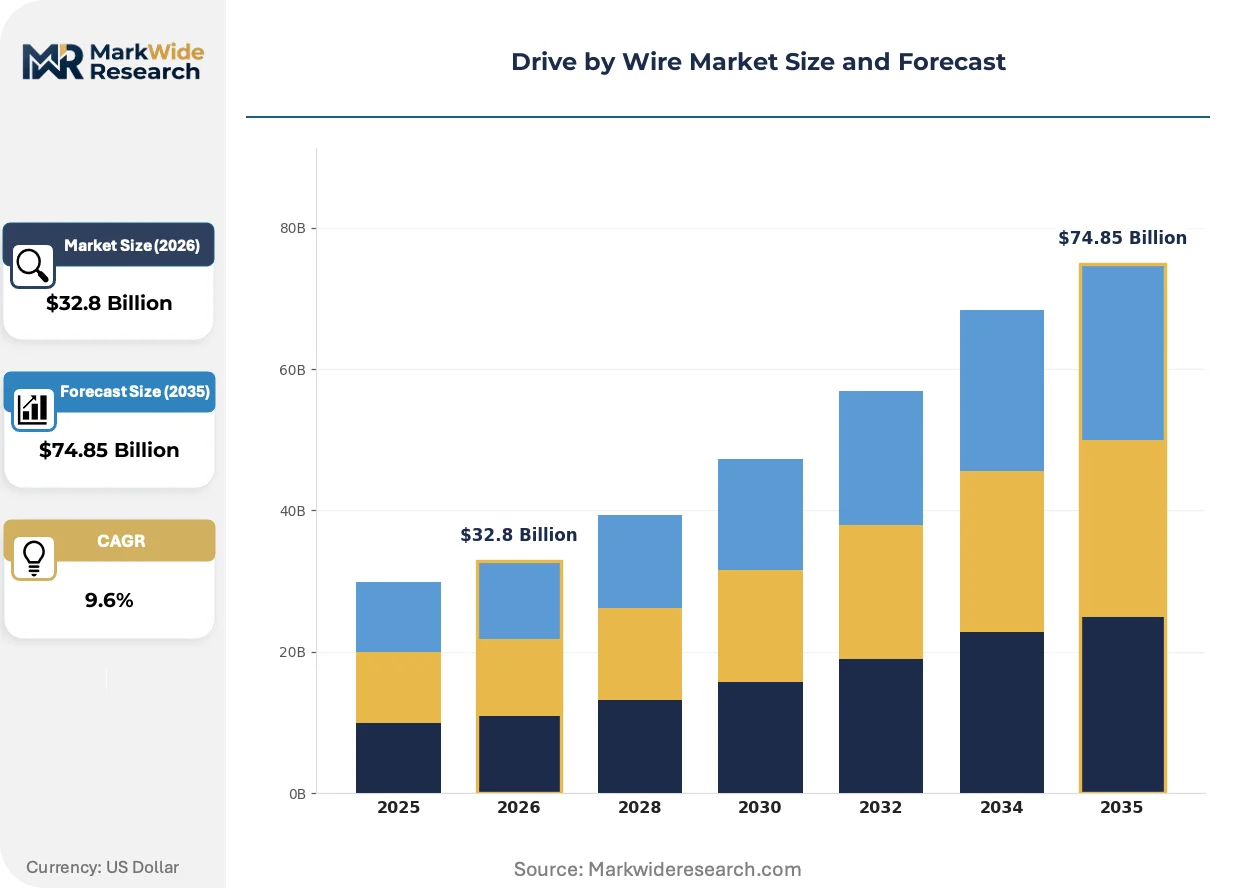
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $74.85 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Throttle Control, Brake Control, Steer-by-Wire, Gear Shifting Component: Actuators, Sensors, Controllers, Wiring Harnesses Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Autonomous Vehicles Feature: Adaptive Cruise Control, Lane Keeping Assist, Electronic Stability Control, Anti-lock Braking System |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Nexteer Automotive, Curtiss-Wright Corporation, DENSO Corporation, Nissan Motor Corporation, Hitachi Automotive Systems, Kongsberg Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drive by Wire Market Strategic Shifts & Innovations
The evolution toward the software-defined vehicle is fundamentally altering how control systems are designed, integrated, and updated. This transition prioritizes modularity and centralized computing power, moving value from discrete hardware components to integrated software platforms and operating systems.
Zonal E/E architecture is a key enabling technology that groups vehicle functions by physical location rather than by specific domain. Automakers are increasingly adopting this approach for next-generation passenger cars and light commercial vehicles to reduce wiring complexity and weight. This architectural shift is unifying previously siloed control domains, such as chassis and powertrain, into powerful, cross-functional domain controllers.
New UNECE regulations, specifically UN R155 for cybersecurity and UN R156 for software updates, are imposing stringent lifecycle management requirements. These rules compel vehicle manufacturers and their suppliers to implement certified management systems for cybersecurity and software updates to gain type approval in key markets. The electronics and software supply chain is most affected, now required to provide verifiable proof of secure development practices.
A clear shift in OEM procurement strategy involves sourcing complete, pre-validated drive-by-wire system platforms instead of individual components. This model disrupts the traditional multi-tier supply chain by favoring large, system-integrator suppliers capable of delivering a full functional stack from sensors to actuators. This pattern is especially visible in Germany and China, where automakers are aggressively pursuing platform-based development for electric vehicles.
Drive by Wire Market Segmentation
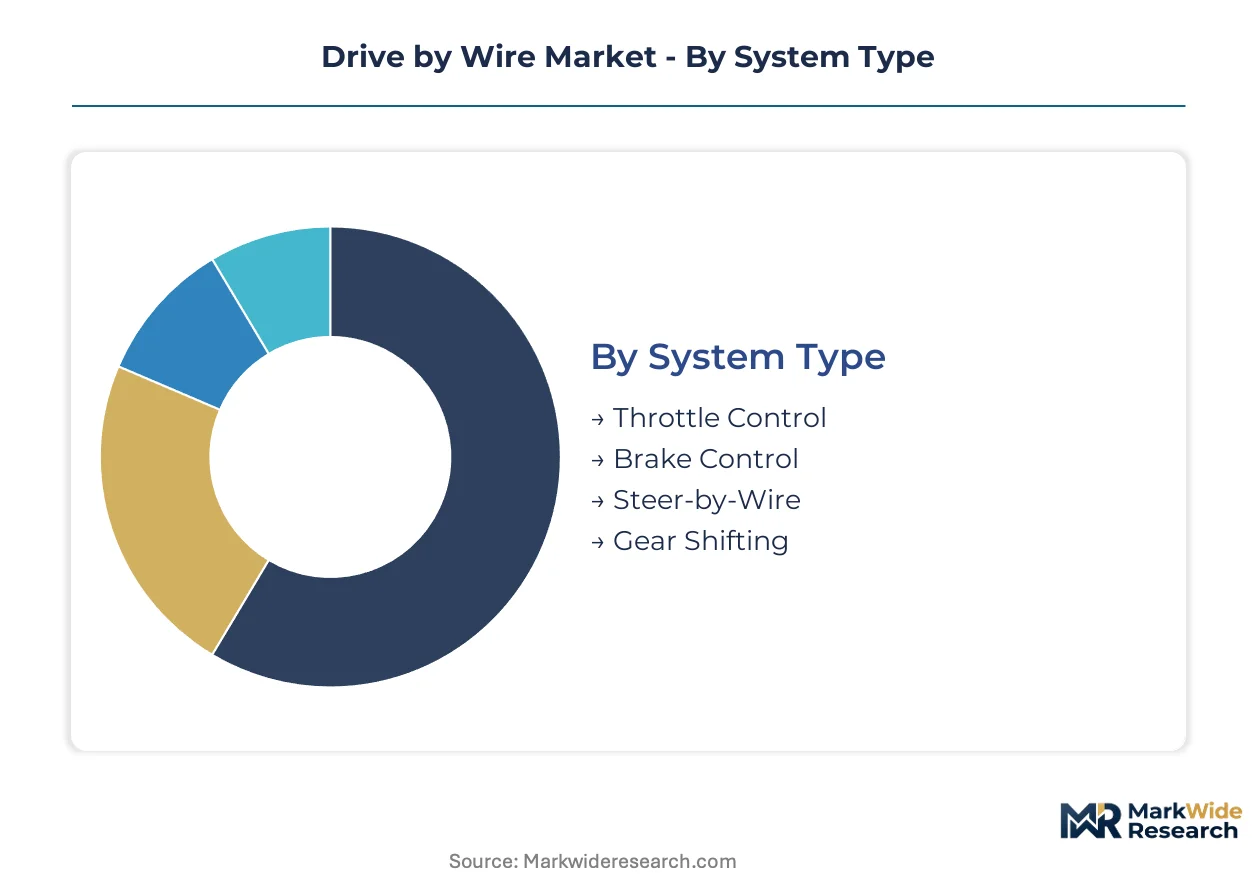
Understanding the Drive by Wire market through its segmentation highlights the diverse technological requirements and application-specific demands across the automotive industry. This granular view reveals where innovation is concentrated and where established technologies continue to drive volume, guiding strategic investments for suppliers and vehicle manufacturers.
System Type:
The upgrade cycle for drive-by-wire systems often dictates technology adoption, moving from established safety applications to advanced autonomous functions.
- Steer-by-Wire:This system replaces the mechanical connection between the steering wheel and the wheels with electronic signals, enabling precise control and advanced autonomous driving features. Demand concentrates in Level 3 and higher autonomous vehicles, particularly within automotive manufacturing centers in Germany and China, driven by the need for enhanced safety and redundancy.
- Brake Control:An electronic system that manages braking force, often incorporating anti-lock braking and electronic stability control, providing improved vehicle stability and shorter stopping distances. This foundational application sees high demand across all vehicle types due to its critical safety function and regulatory mandates from bodies like the U.S. National Highway Traffic Safety Administration (NHTSA).
- Throttle Control:An electronic system that replaces the mechanical accelerator cable with sensors and actuators, allowing for precise engine power management. This mature technology is standard in modern internal combustion and electric vehicles, contributing to fuel efficiency and smoother acceleration profiles.
- Gear Shifting:Electronic gear shifting systems replace mechanical linkages with electrical signals, enabling more compact designs, faster shifts, and integration with advanced powertrain management. This system is increasingly prevalent in electric vehicles and performance-oriented passenger cars.
Brake Control sits at the top of the volume ranking, with Steer-by-Wire climbing the fastest.
Component:
Component selection for drive-by-wire systems hinges on their functional role within the vehicle's electronic architecture.
- Controllers:These electronic control units process sensor data, execute control algorithms, and send commands to actuators, forming the brain of drive-by-wire systems. Demand is concentrating as the industry transitions to centralized and zonal E/E architectures, enabling software-defined vehicle functionalities and integrated domain control.
- Actuators:Electromechanical devices that convert electrical signals into physical motion, directly executing commands for steering, braking, or throttle. High-precision and redundant actuators are critical for safety-critical drive-by-wire functions, seeing strong demand from advanced driver-assistance systems and autonomous vehicle development.
- Sensors:Devices that monitor vehicle parameters such as wheel speed, steering angle, and pedal position, providing crucial input data for the control units. These components are essential for real-time feedback and the accurate operation of all drive-by-wire systems.
- Wiring Harnesses:The network of electrical wires and connectors that transmit power and data between sensors, controllers, and actuators. While drive-by-wire aims to reduce complexity, high-integrity, and robust wiring remains necessary for signal integrity and system reliability in automotive environments.
Controllers and Actuators collectively represent the highest value contribution within the drive-by-wire component ecosystem.
Vehicle Type:
Vehicle type segmentation reveals distinct adoption curves, from high-volume traditional platforms to specialized autonomous fleets.
- Autonomous Vehicles:These vehicles require redundant and highly responsive drive-by-wire systems for all critical functions, enabling Level 3 and higher automation. The segment drives significant innovation and demand for advanced steer-by-wire and brake-by-wire solutions, particularly from manufacturers in Germany and China.
- Passenger Cars:The largest volume segment, integrating drive-by-wire systems primarily for advanced driver-assistance features, safety enhancements, and improved driving comfort. Adoption is widespread for throttle and brake control, with steer-by-wire gaining traction in premium and electric vehicle platforms.
- Commercial Vehicles:This category includes trucks, buses, and vans, where drive-by-wire technology supports fleet efficiency through features like platooning and advanced cruise control. The focus is on robust, durable systems that reduce operational costs and enhance safety for logistics and long-haul operations.
- Electric Vehicles:Drive-by-wire systems are inherently well-suited for electric powertrains, enabling seamless integration of regenerative braking and precise motor control. The absence of mechanical linkages simplifies vehicle design and optimizes energy efficiency for these platforms.
Autonomous Vehicles represent the strategic future for drive-by-wire adoption, while Passenger Cars remain the foundational volume driver.
Feature:
Feature integration into drive-by-wire systems is frequently driven by evolving safety regulations and consumer expectations.
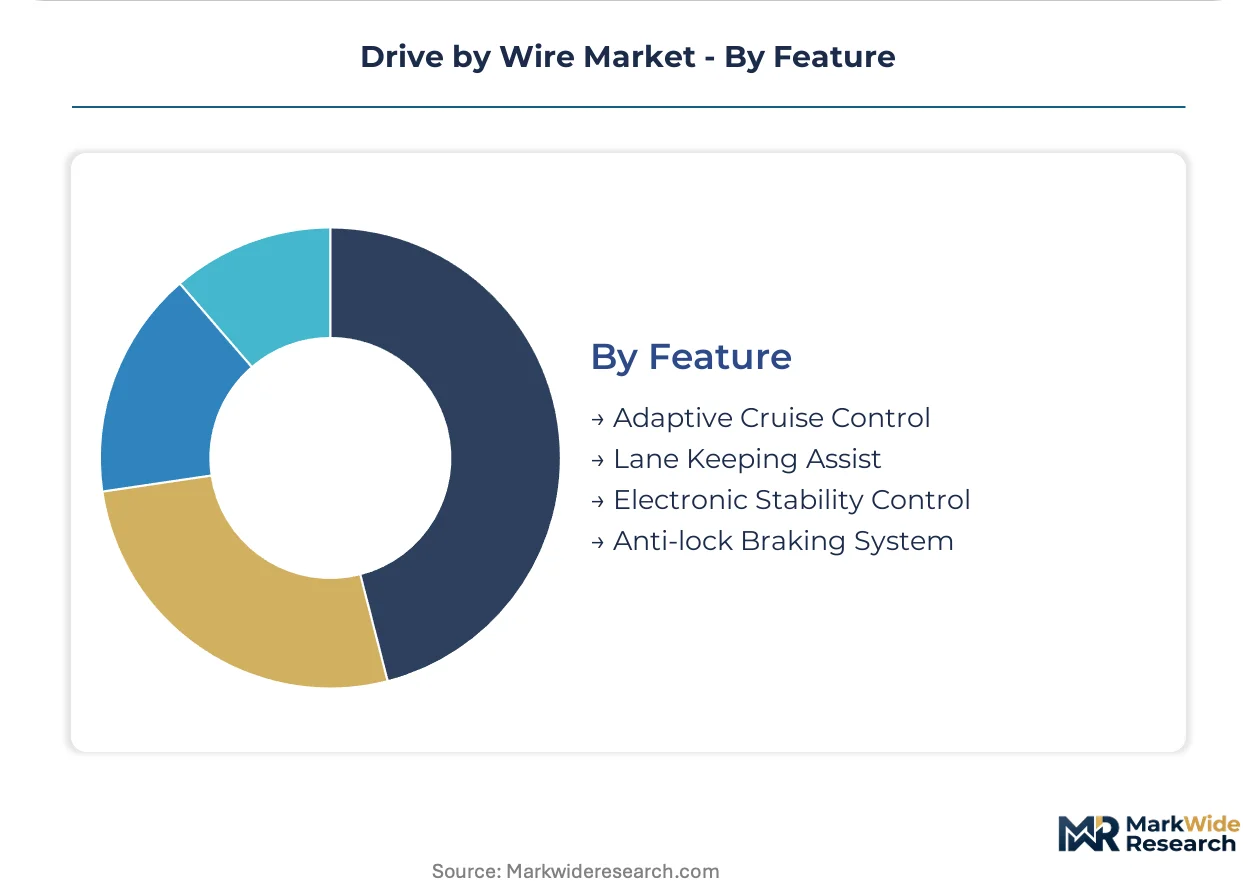
- Electronic Stability Control:A safety system that detects and reduces loss of traction, helping to prevent skidding and loss of control by applying brakes to individual wheels. This feature is mandated by UNECE regulations and the U.S. National Highway Traffic Safety Administration (NHTSA) in many regions, making it a universal application.
- Anti-lock Braking System:This system prevents the wheels from locking up during braking, maintaining steering control and reducing stopping distances on slippery surfaces. It is a mature and widely adopted safety feature, foundational to modern vehicle design and often integrated with other drive-by-wire braking functions.
- Adaptive Cruise Control:A system that automatically adjusts vehicle speed to maintain a safe distance from the car ahead, utilizing throttle and brake-by-wire capabilities. This comfort and safety feature is increasingly common in passenger cars and commercial vehicles.
- Lane Keeping Assist:A feature that helps drivers stay within their lane by providing steering input or warnings, leveraging steer-by-wire technology. This advanced driver assistance system enhances safety and reduces driver fatigue, particularly on highways.
Mandated features like Electronic Stability Control and Anti-lock Braking System form the bedrock of vehicle safety, enabling further advanced driver assistance capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Drive by Wire market's foundational development emerged from established automotive manufacturing hubs, particularly in Europe and Asia. Early innovations in electronic control systems for vehicles, driven by safety and performance demands, paved the way for current advancements. These regions continue to lead in both technological innovation and market adoption for advanced automotive systems.
Germany
German automakers drive demand for sophisticated steer-by-wire and brake control systems, integrating them into premium and autonomous vehicle platforms. UNECE regulations for advanced driver-assistance systems compel robust electronic control systems for market access. Automotive clusters in Stuttgart and Wolfsburg lead in developing and integrating these advanced mechatronic systems.
China
China's aggressive push for electric vehicles and autonomous driving technologies fuels significant demand for drive-by-wire systems. The country's GB standards for vehicle safety and intelligent connected vehicles necessitate high-integrity electronic controls. Manufacturing hubs in Shanghai and Guangzhou are central to the production and deployment of these advanced automotive components.
United States
United States demand for drive-by-wire systems stems from the integration of advanced driver-assistance features and ongoing development of Level 3+ autonomous vehicles. The U.S. National Highway Traffic Safety Administration (NHTSA) mandates various safety technologies, accelerating the adoption of electronic braking and steering. Technology hubs in Silicon Valley and traditional automotive centers in Detroit are innovating in software-defined vehicle architectures.
Japan
Japanese automakers prioritize precision engineering and seamless integration of drive-by-wire systems for advanced driver-assistance systems and electric vehicles. JIS standards for automotive components emphasize reliability and functional safety in electronic control units. Major automotive research and development centers in Toyota City and Yokohama are focusing on next-generation steer-by-wire applications.
Drive by Wire Market Key Industry Players
The competitive structure tilts toward established Tier 1 automotive suppliers offering integrated system solutions. This market exhibits a tiered consolidation, with major players providing comprehensive hardware and software stacks. Strategic archetypes include large system integrators, specialized mechatronics providers, and emerging software-defined vehicle platform developers. Dominant competitive moves involve strategic partnerships with OEMs for platform development and continuous portfolio diversification into new drive-by-wire applications.
Within the large system integrator archetype, Robert Bosch GmbH exemplifies a player leveraging a comprehensive portfolio across sensors, actuators, and software for complete systems, catering to diverse automotive manufacturing requirements. Continental AG occupies a position offering scalable drive-by-wire solutions adaptable across various vehicle segments, emphasizing modularity and cross-platform compatibility. ZF Friedrichshafen AG further anchors the market through its expertise in intelligent mechatronic systems for steering and braking, representing specialized engineering capabilities critical for advanced autonomous functions. These entities collectively underscore the industry's shift towards integrated platform offerings.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Nexteer Automotive |
| Curtiss-Wright Corporation |
| DENSO Corporation |
| Nissan Motor Corporation |
| Hitachi Automotive Systems |
| Kongsberg Automotive |
| Others |
Cost & Logistics Intelligence
Specialized engineering talent concentrations in Germany and China influence drive-by-wire system pricing structures. Labor-cost differentials for functional safety expertise directly impact the cost of advanced control unit development and validation.
Pricing Analysis
Value-based pricing governs drive-by-wire system sales, reflecting the functional safety and performance enhancements delivered. Price differentiation stems from ISO 26262 certification levels and the degree of system integration required for specific OEM platforms. Pricing softness reflects intense competition among Tier 1 suppliers for large-volume passenger car contracts. Autonomous vehicle manufacturers exhibit lower price sensitivity due to critical performance requirements, while mass-market passenger car segments are highly sensitive to system costs.
Supply Chain Analysis
Regional distribution centers facilitate the delivery of drive-by-wire components, often employing hub-and-spoke networks to serve automotive manufacturing clusters. Component supply concentrates in Germany, China, and Japan, which produce high-precision sensors, actuators, and electronic control units. Single-source vulnerability for safety-critical microcontrollers represents a significant supply chain risk. Distribution runs through established Tier 1 automotive suppliers directly to OEM assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drive-by-wire market enters a late-cycle quality story, emphasizing system integrity and performance over cost. Demand is shifting towards premium specifications for fail-operational steer-by-wire solutions in autonomous vehicles.
For Market Incumbents: Lock in long-term platform development contracts with major OEMs to secure future revenue streams. Consolidate functional safety expertise through targeted acquisitions of specialized software engineering firms. The threat of new entrants offering software-defined vehicle platforms necessitates continuous investment in integrated hardware-software solutions. Capacity expansion in advanced microcontroller manufacturing represents a critical lever for supply chain resilience.
For New Entrants and Emerging Players: Online technical forums and developer communities offer a digital channel for showcasing innovative software-defined vehicle architectures. Target off-highway vehicle automation for precision agriculture and mining equipment, which presents a less saturated market. Focus on modular, open-source software stacks for drive-by-wire functionalities to attract smaller OEMs. The aftermarket retrofit segment for commercial vehicle fleets represents the most penetrable application for advanced safety features.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized component manufacturers with strong intellectual property in actuators or sensors but limited software integration. The long-term viability favors entities capable of delivering complete functional safety stacks for autonomous driving. Target mid-sized software firms with deep expertise in ISO 26262 compliance and cybersecurity protocols. The signal to watch is the adoption rate of steer-by-wire in new electric vehicle platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Automotive OEMs reduce complexity and cost through common drive-by-wire architectures across vehicle lines. |
| Software-Defined Vehicle Investment | Tier 1 suppliers enhance their competitive positioning by offering flexible, upgradable control systems via OTA updates. |
| Functional Safety Certification | Manufacturers ensure market access in regions with stringent UNECE regulations by achieving ISO 26262 compliance. |
| Mechatronic System Integration | Suppliers leverage expertise in intelligent steering and braking to deliver advanced autonomous driving capabilities. |
| Off-Highway Application Development | Technology providers unlock new revenue streams by adapting drive-by-wire for agricultural and construction equipment. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, informing the drive-by-wire market analysis. Primary research involved discussions with OEM platform engineers, Tier 1 supplier procurement leads, and functional safety experts. Secondary validation drew from automotive production databases and IHS Markit vehicle registration data. Bottom-up market sizing was cross-referenced with top-down industry revenue figures.
Historical reference periods anchored the forecast framework, providing a baseline for projecting market trajectories across the analysis window. The model segmented demand by system type, component, vehicle type, and key features. Compound annual growth rates were derived through regression analysis of historical adoption patterns. Key inputs included autonomous vehicle deployment schedules and regulatory mandates for functional safety.
The model assumes a particular technology adoption path; alternative pathways for steer-by-wire systems would alter the outlook. Forecasts reflect assumptions regarding regulatory evolution and OEM investment patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Portable Automotive Wi-Fi Router Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market
Automotive Electronics & Wiring
Global Automotive Holographic Display Market
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
Global Automotive Cockpit Electronics Market
Automotive Electronics & Wiring
Brake-By-Wire System Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Automotive Fuse Market
Automotive Electronics & Wiring
Car Speaker Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
Global Automotive Ethernet Market
Automotive Electronics & Wiring
North America Automotive Camera Market
Automotive Electronics & Wiring
Global Vehicle Camera Market