
 Global Automotive Ethernet Market | 2026-2036
Global Automotive Ethernet Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Ethernet Market Analysis
Platform licensing revenue is reshaping competitive economics in automotive connectivity as semiconductor vendors capture recurring value from software-defined vehicle stacks. Broadcom Inc. dominates high-speed PHY development for 10GBase-T1 and Multi-Gig Ethernet implementations. NXP Semiconductors leverages its S32 vehicle compute platforms to anchor zonal gateway designs at major European and North American OEMs. Texas Instruments specializes in power-efficient Ethernet transceivers that extend battery range in electric vehicle architectures.
Automotive Ethernet denotes a family of IEEE-standardized physical layer technologies operating over single unshielded twisted-pair copper cabling at data rates from 100 Mbps to 10 Gbps, employing PAM3 modulation to reduce electromagnetic interference while enabling deterministic latency for safety-critical traffic. Its primary commercial purpose replaces legacy CAN and LIN bus networks with a unified IP-based backbone supporting over-the-air updates and sensor fusion. 1000Base-T1 occupies the largest current volume position as mid-range vehicles adopt centralized compute architectures. Multi-Gig Ethernet represents the fastest-expanding category as lidar and 4K camera arrays saturate legacy bandwidth. Infotainment applications retain mature margins while ADAS and Vehicle-to-Everything segments concentrate growth-oriented investment.
FCC electromagnetic compatibility rules in the United States, EU EMC Directive requirements under CE marking, and UNECE WP.29 cybersecurity mandates collectively shape product certification timelines and design specifications for automotive Ethernet components. OEMs must demonstrate compliance with ISO 26262 functional safety grades and IEEE 802.1 Time-Sensitive Networking protocols before platform approval. Stakeholders should monitor how regional divergence in data sovereignty rules affects cross-border vehicle software architectures and supplier qualification pathways.
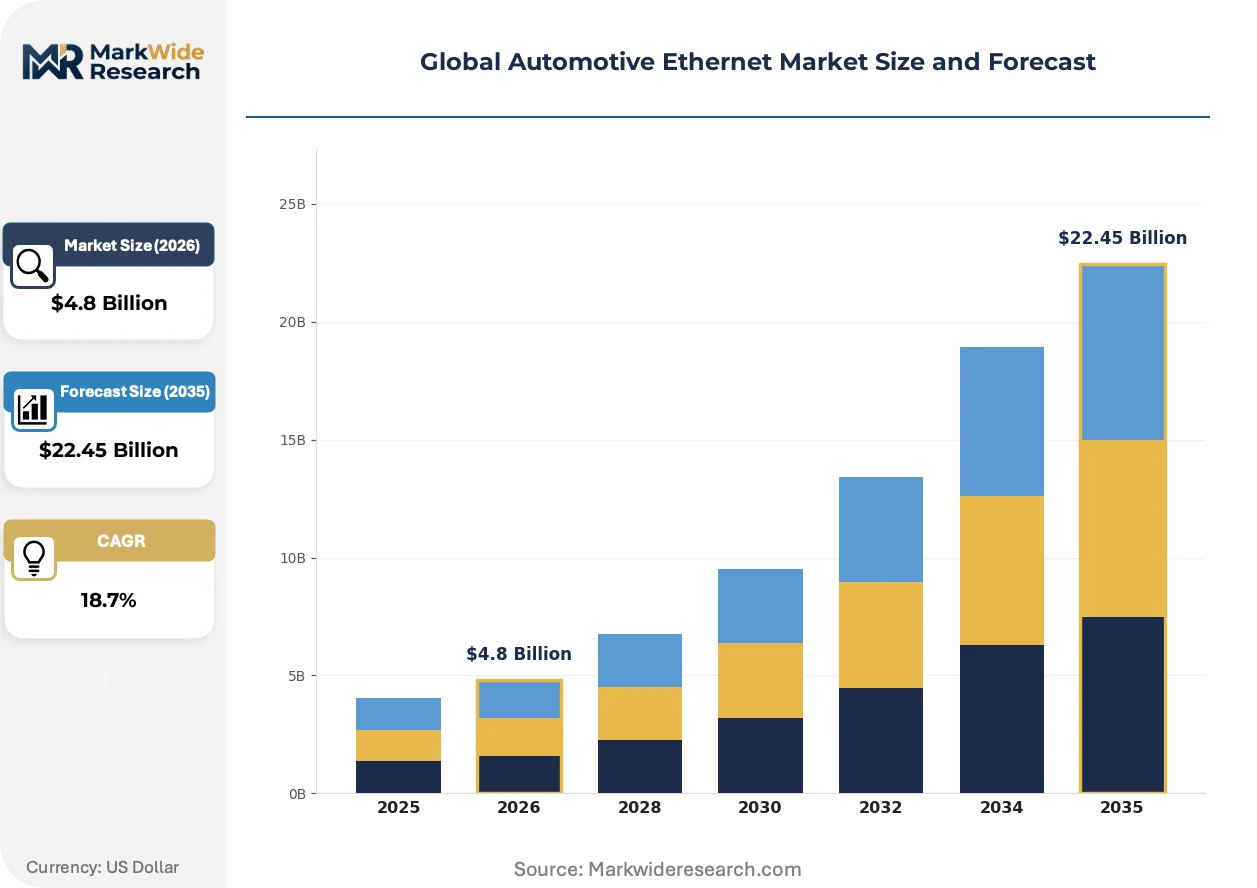
Market Dynamics
OEM migration toward zonal electronic architectures is compressing legacy bus topologies into unified Ethernet backbones, with functional safety requirements under ISO 26262 and IEEE 802.1 Time-Sensitive Networking protocols dictating design specifications across vehicle platforms.
Growth Catalysts
- UNECE WP.29 Cybersecurity Mandates:European regulators now require demonstrable intrusion detection and secure over-the-air update capabilities, forcing OEMs to abandon isolated domain controllers in favor of IP-based Ethernet networks that support centralized security monitoring.
- Lidar and 4K Camera Arrays:Advanced driver-assistance systems in premium vehicle segments now generate multi-gigabit sensor data streams that saturate legacy CAN-FD bandwidth, creating immediate substitution demand for 1000Base-T1 and Multi-Gig Ethernet physical layers.
- German OEM Architecture Leadership:BMW, Mercedes-Benz, and Volkswagen have committed to Ethernet-native electrical platforms across their 2026-2030 vehicle generations, establishing procurement templates that tier-one suppliers must replicate for other marques.
Market Restraints
- Copper Cable Cost Volatility:Unshielded twisted-pair cabling remains commodity-exposed, with automotive-grade conductor purity requirements limiting supplier flexibility when London Metal Exchange copper prices spike.
- PHY Semiconductor Supply Concentration:High-speed 10GBase-T1 physical layer development concentrates among a handful of fabless designers, creating single-source risk for OEMs qualifying new zonal gateway platforms.
- Legacy LIN Bus Persistence:Door modules, seat controllers, and climate actuators in economy vehicle segments continue deploying low-cost LIN networks, delaying full Ethernet penetration below the C-segment.
Strategic Opportunities
- India Automotive Production:Domestic OEMs and joint ventures operating under India's PLI scheme for advanced automotive technology are greenfield-designing electrical architectures that skip CAN-heavy generations entirely.
- Vehicle-to-Everything Communication:C-V2X roadside units and cellular-V2X modules require deterministic low-latency backhaul that IEEE 802.1Qbv time-aware shaping enables, opening adjacent infrastructure revenue streams beyond vehicle sales.
- EU AI Act Compliance Services:Automated driving systems classified as high-risk AI under the European Union's artificial intelligence regulation demand auditable data logging and traceability that Ethernet-based logging architectures provide natively.
Industry Challenges
- Functional Safety Engineer Scarcity:ISO 26262 ASIL-D certification for Ethernet switch fabrics requires specialized hardware-software co-verification expertise that remains concentrated among semiconductor vendors and tier-one integrators.
- Legacy Gateway Migration Complexity:OEMs maintaining multi-decade vehicle fleets must bridge Ethernet backbones to surviving CAN, LIN, and FlexRay domains without compromising real-time performance for powertrain safety functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Ethernet Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 100Base-T1, 1000Base-T1, 10GBase-T1, Multi-Gig Ethernet End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Infotainment, Advanced Driver Assistance Systems, Vehicle-to-Everything, In-Vehicle Networking Technology: Broadband Technologies, Packet Switching, Time-Sensitive Networking, Fiber Optics |
| Companies Covered | Microchip Technology, Vector Informatik, Broadcom Inc., Molex, Keysight Technologies, Marvell Technology, Texas Instruments, Cadence Design Systems, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Ethernet Market Emerging Trajectories
Software-defined vehicle architectures are decoupling hardware refresh cycles from feature deployment, enabling semiconductor vendors to capture recurring revenue through stack licensing rather than one-time PHY sales.
Time-Sensitive Networking is virtualizing deterministic traffic scheduling across converged Ethernet infrastructures. Tier-one suppliers at BMW and Mercedes-Benz are adopting IEEE 802.1Qbv time-aware shapers for brake-by-wire and steer-by-wire signals. This virtualization is collapsing separate safety-critical and infotainment network silos into single physical layers.
FCC electromagnetic compatibility enforcement under Part 15 rules is tightening radiated emission limits for unshielded automotive cabling. Test houses in Michigan and California report extended certification timelines for 10GBase-T1 implementations. Multi-Gig PHY vendors are responding with enhanced digital signal processing firmware rather than shielding material additions.
Fleet procurement departments now specify Ethernet switch port counts and software update bandwidth guarantees as distinct line items in vehicle platform RFPs. Traditional tier-one wiring harness suppliers without stack-level IP are losing gateway socket awards to semiconductor-software integrators. This specification behavior is most visible in German and Swedish OEM electrical architecture sourcing.
Global Automotive Ethernet Market Segmentation
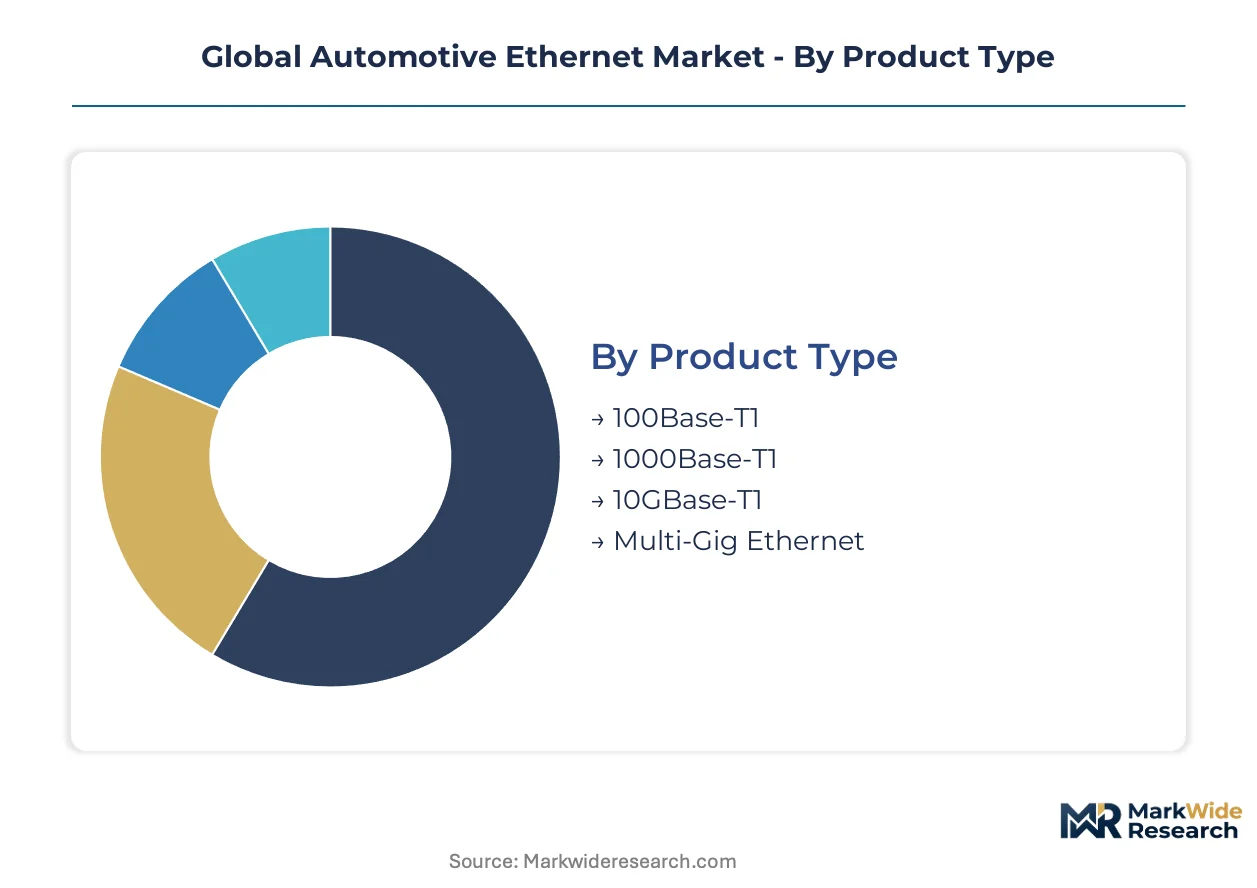
Automotive Ethernet segmentation reveals how physical layer specifications, supply chain position, and functional application intersect to determine procurement economics. OEMs structure supplier qualification pathways around these dimensions, with each category carrying distinct margin profiles and technical barriers.
Product Type:
Mature 100 Mbps implementations coexist with emerging multi-gigabit standards as automakers balance legacy compatibility against sensor bandwidth demands.
- 100Base-T1:Operates at 100 Mbps over single unshielded twisted-pair cabling with PAM3 modulation, enabling deterministic latency for body control modules. Demand concentrates in entry-level C-segment vehicles across India and Southeast Asia where cost sensitivity delays gigabit migration.
- 1000Base-T1:Delivers 1 Gbps throughput using advanced digital signal processing, currently anchoring centralized compute architectures at BMW, Mercedes-Benz, and Volkswagen. German OEM procurement templates establish the qualification baseline that tier-one suppliers replicate for mid-range vehicle platforms globally.
- 10GBase-T1:IEEE-standardized 10 Gbps physical layer targeting lidar fusion and raw camera feed aggregation in premium ADAS configurations.
- Multi-Gig Ethernet:Encompasses 2.5G, 5G, and 25G variants for next-generation zonal gateways handling 4K surround-view camera arrays.
1000Base-T1 retains volume leadership; Multi-Gig Ethernet holds the steepest expansion curve.
End User:
Supply chain position determines technical specification authority and software stack control within vehicle electrical architectures.
- OEMs:Original equipment manufacturers define Ethernet backbone topology and gateway placement, capturing recurring platform licensing revenue through software-defined vehicle stacks. Volkswagen Group and BMW specify switch port counts and over-the-air bandwidth guarantees as distinct RFP line items.
- Tier-1 Suppliers:Integrators such as Bosch, Continental, and Aptiv translate OEM architecture specifications into physical wiring harness and gateway module production. These suppliers face margin compression as semiconductor vendors capture stack-level IP value previously held by wiring specialists.
- Aftermarket Providers:Service retrofitters and diagnostic equipment manufacturers enable legacy vehicle Ethernet connectivity for fleet management and telematics upgrades.
- Vehicle Assemblers:Contract manufacturers and joint venture production facilities execute electrical architecture installation per OEM design authority.
OEMs retain specification control; Tier-1 Suppliers absorb the most intense margin pressure from semiconductor disintermediation.
Application:
Functional safety requirements and bandwidth intensity create divergent qualification pathways across vehicle domains.
- Infotainment:Mature application segment supporting audio streaming, navigation, and rear-seat entertainment with established IEEE 802.1 AVB protocols. Mercedes-Benz S-Class and BMW 7-Series deployments emphasize premium user experience over cost optimization.
- Advanced Driver Assistance Systems:Safety-critical domain requiring ISO 26262 ASIL-D certification for brake-by-wire and steer-by-wire signal paths. Lidar and 4K camera arrays generate multi-gigabit data streams that saturate legacy CAN-FD bandwidth.
- Vehicle-to-Everything:C-V2X roadside infrastructure and cellular-V2X modules demand deterministic low-latency backhaul for collision avoidance and traffic coordination.
- In-Vehicle Networking:Zonal gateway consolidation replacing discrete CAN, LIN, and FlexRay domains with unified IP-based backbone architectures.
Infotainment commands mature margins; ADAS applications concentrate growth-oriented investment and technical talent.
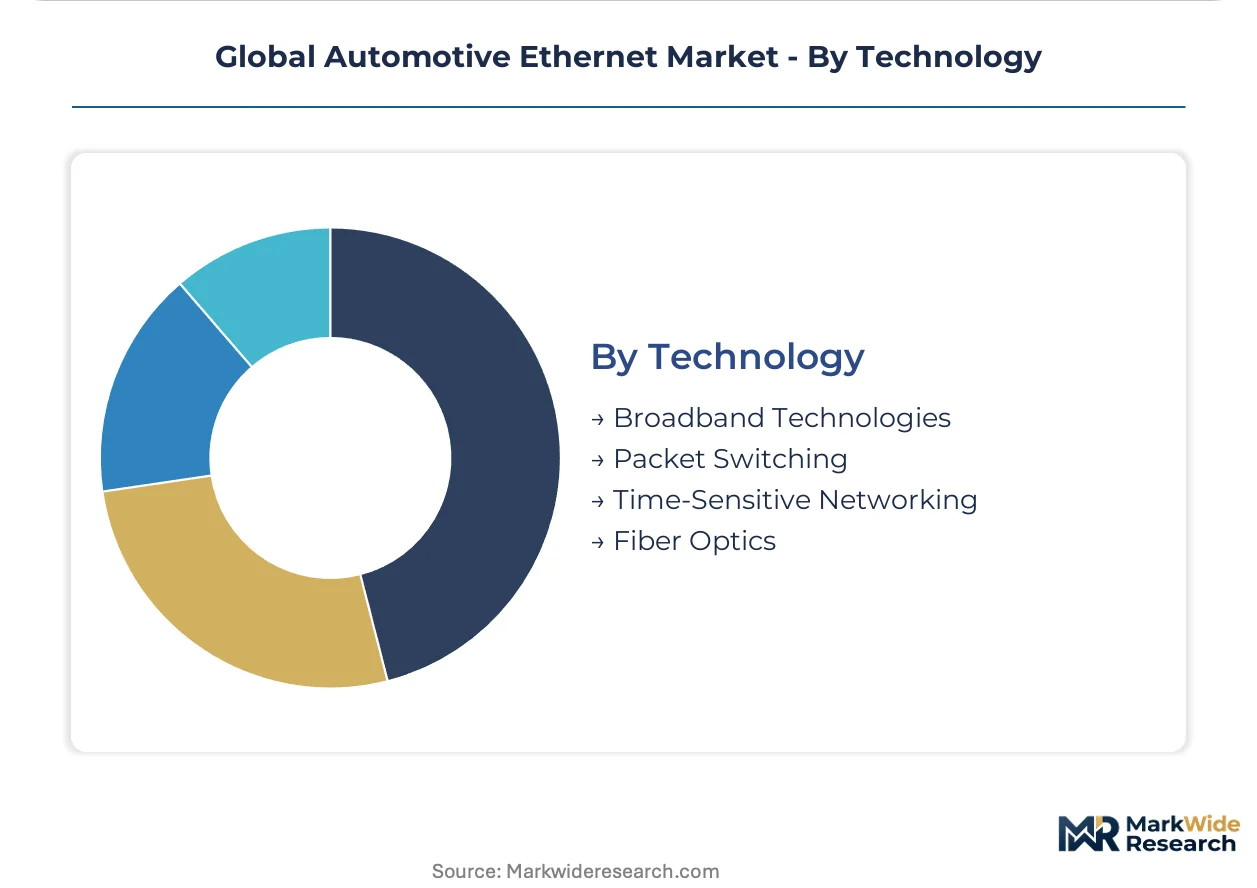
Technology:
Protocol standardization and physical medium selection determine electromagnetic compatibility certification complexity.
- Broadband Technologies:High-frequency signaling methods enabling multi-gigabit throughput over copper infrastructure face tightening FCC Part 15 radiated emission limits in the United States.
- Packet Switching:IP-based data transmission replacing circuit-switched legacy bus architectures enables over-the-air updates and centralized security monitoring mandated by UNECE WP.29.
- Time-Sensitive Networking:IEEE 802.1Qbv time-aware shaping virtualizes deterministic traffic scheduling, collapsing separate safety-critical and infotainment network silos into converged physical layers at BMW and Mercedes-Benz.
- Fiber Optics:Optical physical layers for ultra-high-bandwidth applications in autonomous vehicle prototypes bypass copper electromagnetic interference constraints.
Time-Sensitive Networking is gaining adoption fastest; Broadband Technologies face the most stringent certification headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes Automotive Ethernet for zonal gateway consolidation in premium electrical architectures, while the United States prioritizes cybersecurity-hardened backbones for connected fleets and India pursues greenfield IP-native designs that bypass legacy CAN generations entirely.
Germany
BMW, Mercedes-Benz, and Volkswagen anchor zonal architecture procurement templates that tier-one suppliers replicate globally. UNECE WP.29 cybersecurity mandates under KBA enforcement accelerate Ethernet backbone standardization for intrusion detection and over-the-air update capabilities. Stuttgart and Munich host concentrated semiconductor vendor engineering centers supporting 10GBase-T1 PHY qualification programs.
United States
Fleet operators and premium OEMs demand deterministic low-latency networks for ADAS sensor fusion and telematics data aggregation. FCC Part 15 electromagnetic compatibility enforcement tightens radiated emission limits for unshielded twisted-pair cabling, extending certification timelines for multi-gigabit implementations. Michigan test houses and California automotive R&D clusters drive PHY firmware optimization rather than shielding material additions.
China
Domestic OEMs and joint ventures integrate Ethernet for centralized compute architectures supporting lidar-heavy autonomous driving stacks. MIIT standards harmonization with IEEE 802.1 Time-Sensitive Networking protocols shapes switch fabric qualification pathways. Yangtze River Delta manufacturing clusters concentrate wiring harness production for export-oriented vehicle platforms.
India
Domestic OEMs under the PLI scheme for advanced automotive technology design electrical architectures that skip CAN-heavy generations entirely. BIS certification requirements for automotive-grade conductor purity limit supplier flexibility during copper price volatility. Tamil Nadu and Gujarat production facilities execute greenfield Ethernet backbone installation for compact vehicle segments.
Japan
Premium marques deploy Multi-Gig Ethernet for 4K surround-view camera arrays and raw sensor feed aggregation. METI industrial policy supports domestic semiconductor vendor participation in IEEE 802.1Qbv time-aware shaping standardization. Kanto and Nagoya automotive engineering corridors concentrate functional safety expertise for ISO 26262 ASIL-D switch certification.
Global Automotive Ethernet Market Vendor Landscape
Capability concentration sits with fabless PHY designers commanding high-speed 10GBase-T1 development; scale advantage sits with diversified semiconductor conglomerates leveraging existing automotive customer relationships. The vendor base stratifies across three archetypes: pure-play Ethernet PHY specialists, diversified automotive semiconductor platforms, and tier-one wiring harness integrators losing socket awards to stack-level IP holders. Dominant competitive moves include strategic licensing of software-defined vehicle stacks and geographic expansion into India PLI scheme production corridors.
Within the diversified semiconductor tier, Broadcom Inc., NXP Semiconductors, and Texas Instruments exemplify distinct capability positioning. Broadcom anchors high-speed PHY development archetypes through its focus on 10GBase-T1 and Multi-Gig implementations. NXP Semiconductors occupies the zonal gateway integration position, leveraging S32 vehicle compute platforms for European and North American OEM engagements. Texas Instruments represents power-efficient transceiver specialization, extending battery range in electric vehicle architectures through optimized physical layer designs.
| Leading Market Players |
|---|
| Microchip Technology |
| Vector Informatik |
| Broadcom Inc. |
| Molex |
| Keysight Technologies |
| Marvell Technology |
| Texas Instruments |
| Cadence Design Systems |
| NXP Semiconductors |
| Others |
Supply Flow & Price Mechanics
Stuttgart's concentrated PHY semiconductor engineering centers anchor capacity dynamics that translate directly into downstream pricing leverage for tier-one automotive suppliers. German OEM procurement templates for 1000Base-T1 and 10GBase-T1 implementations establish reference price points that cascade through global wiring harness negotiations.
Pricing Analysis
Long-term offtake agreements dominate semiconductor procurement, with multi-year PHY supply contracts locking in volume commitments from BMW and Volkswagen platform engineers. Price differentiation hinges on ISO 26262 ASIL-D certification grade and volume scale, with uncertified commodity transceivers facing severe cost compression. Pricing pressure stems from copper cable cost volatility under London Metal Exchange fluctuations. Economy vehicle segments exhibit highest price sensitivity, while premium ADAS configurations absorb multi-gigabit PHY premiums without demand elasticity.
Supply Chain Analysis
Contract manufacturing concentrates at TSMC foundries for 10GBase-T1 PHY die production and Yangtze River Delta wiring harness assembly facilities. Raw material dependencies center on high-purity copper conductors, automotive-grade silicon wafers, and specialized PAM3 modulation DSP firmware. Single-source vulnerability pervades high-speed PHY development, where fabless designers command sole qualification status at major OEMs. Distribution runs through tier-one integrators such as Bosch and Continental, who bridge semiconductor vendors to vehicle assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive Ethernet represents a platform-economics inflection where software-defined vehicle stacks displace hardware-refresh revenue models, catalyzed by IEEE 802.1 Time-Sensitive Networking protocol standardization across previously siloed safety-critical and infotainment domains.
For Market Incumbents: Entrench position through captive PHY design capabilities and S32 platform stack licensing at European OEMs. Deepen backward integration into automotive-grade copper refining to offset London Metal Exchange volatility. Prioritize ISO 26262 ASIL-D certification investment as defensive moat against emerging PHY specialists. For New Entrants and Emerging Players: India's PLI scheme production corridors under BIS certification frameworks represent the most penetrable entry point for greenfield Ethernet-native architectures skipping CAN-heavy generations. Target aftermarket diagnostic equipment for legacy fleet Ethernet retrofitting. Pursue direct OEM engagement through software-defined vehicle stack partnerships rather than tier-one wiring harness channel dependence. For Investors and Strategic Acquirers: Long-term, this sits as a semiconductor-platform play because recurring licensing revenue from zonal gateway software stacks displaces one-time PHY sales across vehicle lifecycles. Acquisition targets should emphasize PHY-DSP co-design capabilities with existing UNECE WP.29 cybersecurity qualification. Monitor IEEE 802.1Qbv time-aware shaping adoption rates at BMW and Mercedes-Benz as inflection signal for converged network virtualization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Stack Licensing | NXP Semiconductors and Broadcom capture recurring revenue from Volkswagen platform deployments. |
| 10GBase-T1 PHY Qualification Investment | Stuttgart engineering centers accelerate BMW lidar fusion architecture certification timelines. |
| Backward Integration into Copper Refining | Tier-one suppliers hedge London Metal Exchange volatility for automotive-grade conductor supply. |
| IEEE 802.1Qbv Time-Aware Shaping Adoption | Mercedes-Benz brake-by-wire virtualization collapses separate safety and infotainment network silos. |
| India PLI Scheme Manufacturing Footprint | Tamil Nadu facilities execute greenfield Ethernet backbone installation for compact vehicle segments. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with OEM platform engineers, tier-one supplier procurement leads, semiconductor vendor application specialists, and FCC certification test house directors; and secondary validation through SEC semiconductor filings, IEEE standards documentation, UNECE WP.29 regulatory texts, and vehicle production registration databases. Bottom-up PHY shipment modeling triangulated against top-down OEM electrical architecture spend allocation.
Forecast inputs incorporated vehicle class segmentation, propulsion architecture differentiation, content-per-vehicle scaling for ADAS sensor arrays, and regional production cluster adoption curves. CAGRs were derived from installed base growth and technology substitution elasticity across the projection horizon. Zonal gateway port density assumptions and copper price scenario modeling shaped volume and value outputs.
Stress conditions across London Metal Exchange copper price bands, PHY semiconductor foundry utilization thresholds, and UNECE WP.29 enforcement timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding IEEE 802.1 standardization velocity and German OEM platform template replication rates. Quarterly review of Tier-1 supplier margin compression indicators and India PLI scheme allocation volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
Automotive Wiring Harness Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
UAE Automotive Sensors Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
Automotive Switch Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
Digital Tachographs Market
Automotive Electronics & Wiring
North America Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Smart Antenna Market
Automotive Electronics & Wiring
Car Digital Video Recorder (DVR) Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
Australia Automotive Camera Market
Automotive Electronics & Wiring
Surround View System Market
Automotive Electronics & Wiring
China Automotive Camera Market
Automotive Electronics & Wiring
Automotive Fuse Block Market