
 Digital Tachograph System Market | 2026-2036
Digital Tachograph System Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Tachograph System Market Analysis
Cloud-based data subscription services is realigning revenue models away from one-time hardware sales toward recurring telemetry revenue. Continental Automotive leverages its integrated vehicle electronics portfolio to bundle tachograph modules with telematics platforms. Stoneridge Electronics anchors its position through specialized commercial vehicle display and compliance systems. Robert Bosch GmbH competes across sensor fusion and fleet management software layers.
A digital tachograph system comprises a vehicle-mounted recording device paired with driver smart cards that capture speed, distance, and driving time data through encrypted CAN bus interfaces and GNSS positioning. The primary purpose is enforcing driver hour regulations while enabling fleet managers to audit compliance remotely. Vehicle unit hardware still commands the largest installed base, though cloud-based solutions are capturing disproportionate growth as operators seek over-the-air download capabilities. Software segments concentrate margin pools where analytics and compliance reporting tools command recurring licensing fees.
EU Regulations under the EU Green Deal and F-Gas frameworks indirectly shape tachograph specifications through vehicle electrification mandates that alter CAN bus architectures. Germany's KBA and France's ANSM-equivalent transport regulators enforce type-approval standards that determine market access for new entrants. Stakeholders must monitor how impending revisions to EU tachograph legislation affect data retention periods and cross-border enforcement protocols.
Market Dynamics
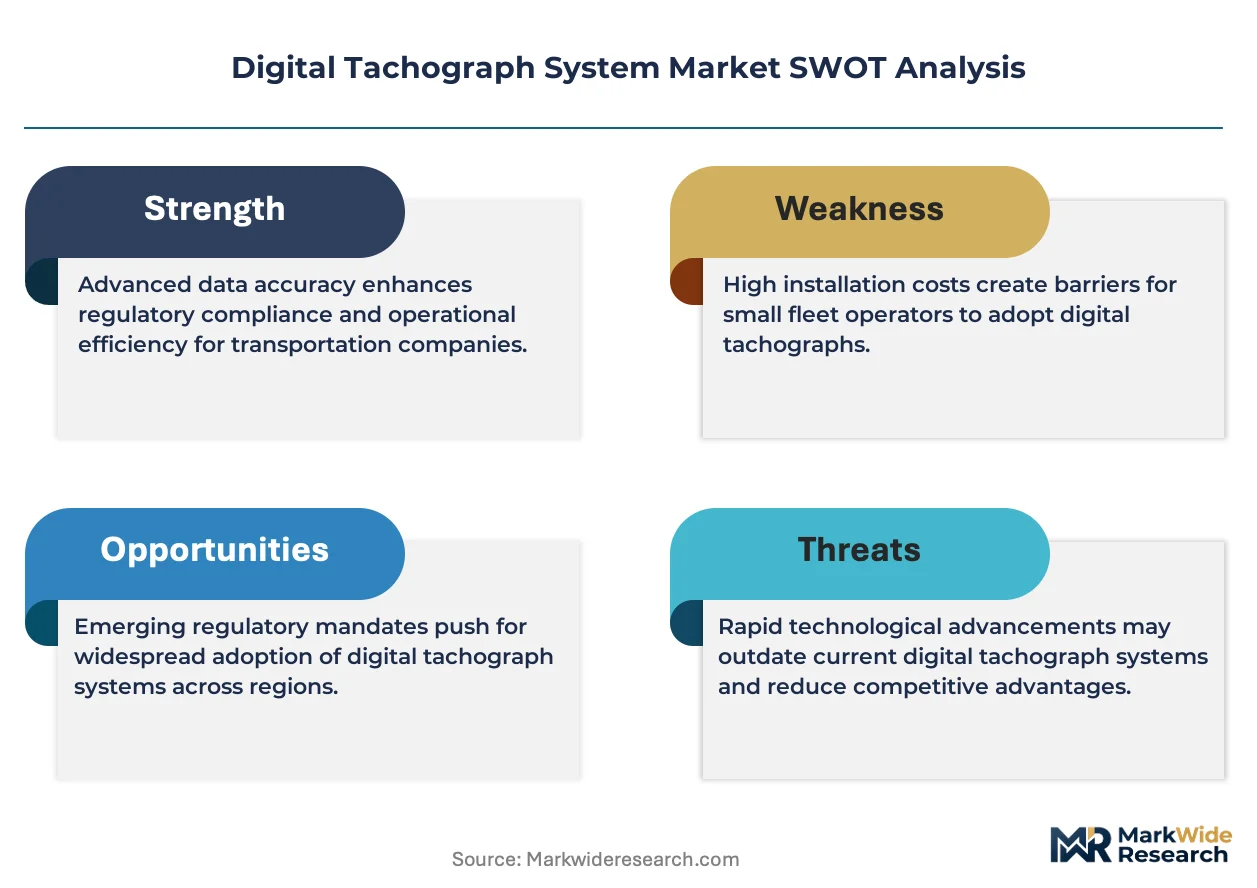
The European Union's mandatory migration toward second-generation smart tachographs (Annex 1C) is compressing hardware replacement cycles across commercial vehicle fleets, forcing operators to absorb simultaneous costs of vehicle unit upgrades, driver card reissuance, and backend system integration.
Growth Catalysts
- EU Annex 1C Mandate:The 2024-2025 enforcement window for upgraded digital tachographs with remote data download capability is compelling fleet-wide hardware refreshes across Germany, France, and Poland.
- Telematics Convergence:Fleet management platforms are absorbing tachograph data streams into unified analytics dashboards, creating bundled demand for integrated vehicle electronics.
- Cross-Border Enforcement Harmonization:The European Labour Authority's coordinated roadside inspection protocols are elevating compliance penalties and accelerating voluntary pre-enforcement upgrades.
Market Restraints
- Semiconductor Supply Concentration:Vehicle unit production depends on automotive-grade microcontrollers sourced from concentrated Asian foundry capacity, exposing lead time volatility.
- Smart Card Manufacturing Bottlenecks:EMV-certified secure element production for driver cards concentrates among a handful of European semiconductor packaging facilities.
- Legacy Fleet Depreciation Cycles:Commercial vehicle replacement timelines averaging seven years delay tachograph refresh rates among cost-constrained operators.
Strategic Opportunities
- Central and Eastern European Fleet Expansion:Polish, Romanian, and Czech logistics operators are digitizing previously paper-based compliance systems, creating first-mover hardware demand.
- Over-the-Air Software Subscriptions:Cloud-based remote tachograph data retrieval is opening recurring revenue streams distinct from one-time vehicle unit sales.
- Electrified Commercial Vehicle Integration:Battery-electric truck architectures require redesigned CAN bus interfaces, creating specification windows for next-generation tachograph suppliers.
Industry Challenges
- Embedded Systems Engineering Talent:Shortages of firmware developers with automotive cybersecurity expertise are extending product development timelines for type-approval submission.
- Multi-Country Certification Complexity:Divergent national interpretations of EU base regulations by Germany's KBA and France's transport authorities create redundant testing burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Tachograph System Market |
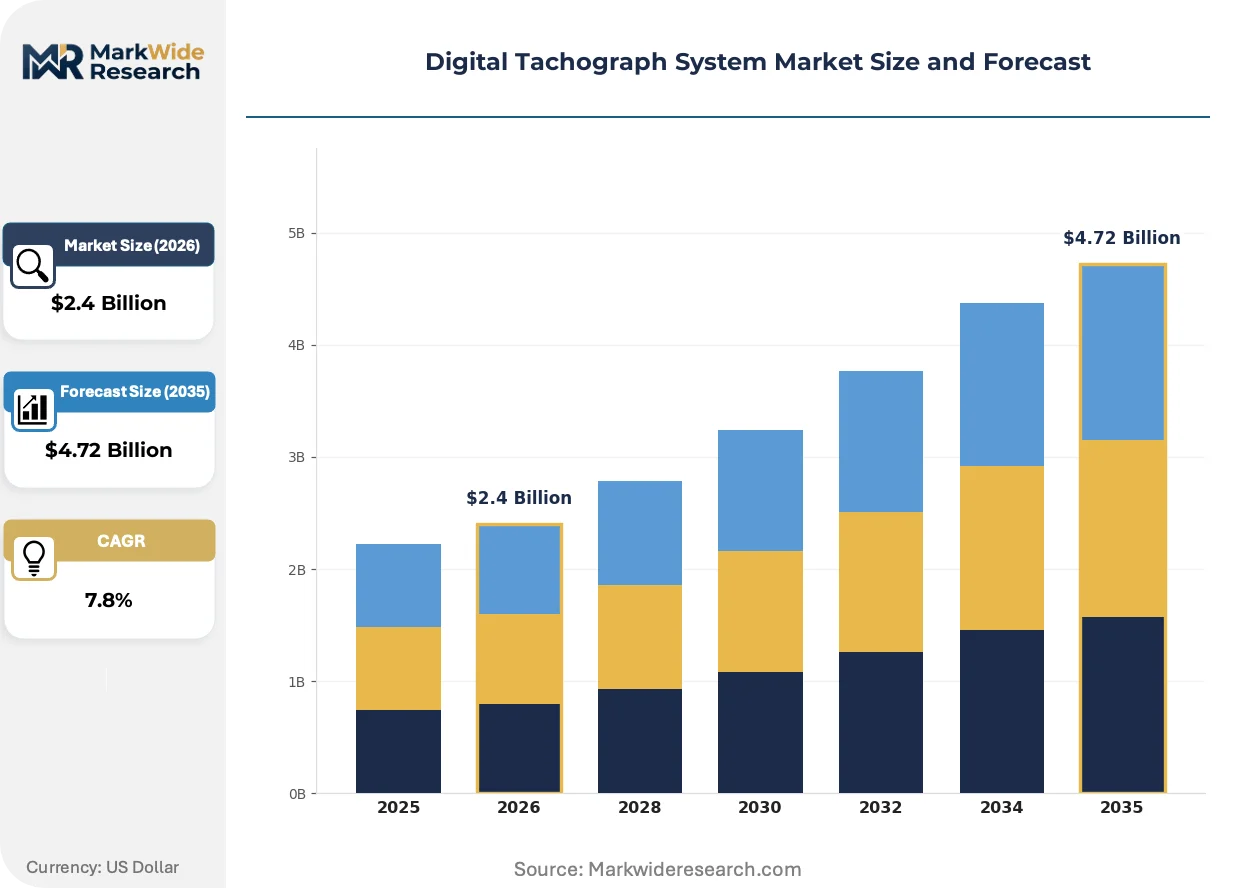
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Driver Card, Vehicle Unit, Downloading Device, Software End User: Transportation Companies, Fleet Operators, Regulatory Authorities, Vehicle Manufacturers Installation Type: Integrated Systems, Standalone Devices, Mobile Solutions, Cloud-Based Solutions Compliance Level: EU Regulations, National Standards, Industry Certifications, Custom Solutions |
| Companies Covered | Continental Automotive, Stoneridge Electronics, Siemens, Veridos, Teletrac Navman, Robert Bosch GmbH, Actia Group, Gemalto, Transics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Tachograph System Market Emerging Trajectories
Remote data retrieval architectures are displacing physical card-based downloads, compressing compliance audit cycles from weeks to hours while embedding tachograph functionality within broader fleet telematics platforms.
GNSS positioning modules with Galileo and GLONASS multi-constellation support are expanding into second-generation vehicle units, enabling geofenced driving hour enforcement and automated cross-border jurisdiction detection. Polish and German fleet operators are adopting these units fastest, driven by intensified roadside inspection cooperation between national enforcement agencies. The technology is expanding into adjacent compliance applications including real-time speed limiter verification and automated toll reconciliation.
France's ANSM-equivalent transport regulator and Germany's KBA are tightening type-approval testing protocols for cybersecurity resilience under evolving EU vehicle type-approval frameworks. Manufacturers must now demonstrate intrusion detection capabilities and secure boot architectures before market entry authorization. Component suppliers are responding by pre-certifying CAN bus interface modules to accelerate customer vehicle unit approval timelines.
Logistics procurement departments are consolidating vendor relationships, preferring tachograph suppliers with integrated telematics platforms over standalone hardware vendors. Large German freight operators are bundling vehicle unit procurement with multi-year data service contracts, compressing supplier margins on hardware while extending subscription revenue visibility. This pattern is most pronounced in temperature-controlled transport segments where regulatory documentation requirements intersect with cargo integrity monitoring needs.
Digital Tachograph System Market Segmentation
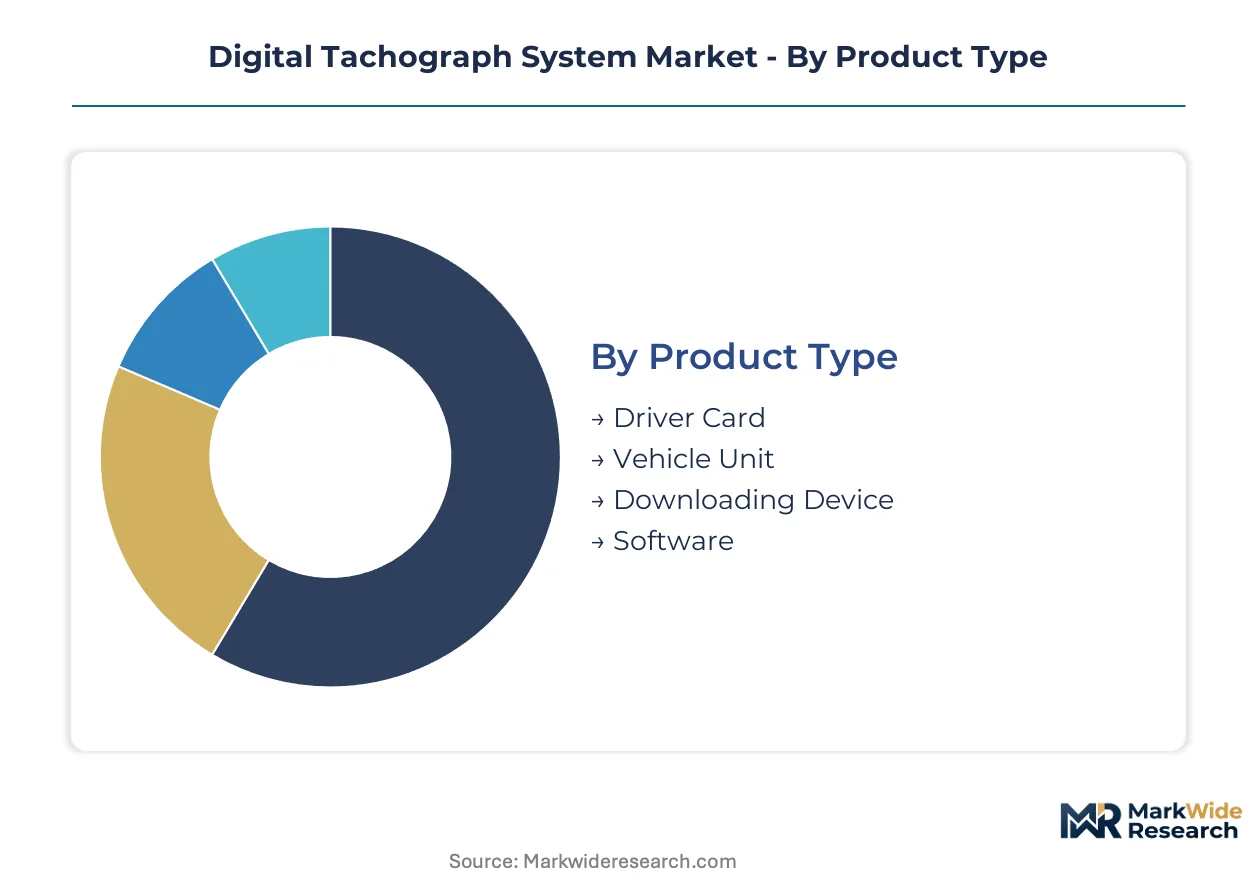
Segmentation in the digital tachograph system market reveals how procurement decisions split between hardware lifecycle investments and recurring service commitments. Fleet operators weigh upfront vehicle unit costs against long-term compliance automation, while regulatory pressure determines which technology tiers achieve market access.
Product Type:
Capital allocation intensity drives purchasing patterns, with fleet managers balancing depreciation schedules against connectivity requirements.
- Vehicle Unit:The onboard recording device captures encrypted speed, distance, and driving time data through CAN bus interfaces and GNSS positioning. German and Polish fleet operators are refreshing these units fastest under Annex 1C enforcement timelines, absorbing simultaneous costs of hardware replacement and backend integration.
- Software:Cloud-based analytics platforms enable remote data retrieval and compliance reporting through subscription licensing. Demand concentrates among large French freight operators bundling multi-year service contracts with hardware procurement, shifting revenue models toward recurring telemetry fees.
- Driver Card:EMV-certified smart cards authenticate driver identity and store encrypted activity records.
- Downloading Device:Physical card readers for local data extraction are declining as over-the-air retrieval expands.
Volume sits with Vehicle Unit; growth tilts toward Software.
End User:
Stakeholder sophistication varies by enforcement exposure and fleet scale.
- Fleet Operators:Commercial vehicle owners managing compliance across multi-jurisdictional routes. Polish and Romanian logistics firms digitizing paper-based systems are creating first-mover hardware demand as roadside inspection cooperation tightens.
- Transportation Companies:Passenger and freight carriers with specialized temperature-controlled or hazardous cargo requirements. These operators in Germany are bundling tachograph procurement with cargo integrity monitoring systems.
- Regulatory Authorities:National transport agencies conducting roadside inspections and type-approval enforcement.
- Vehicle Manufacturers:OEMs integrating tachograph modules at factory installation for new commercial vehicle production.
Fleet Operators command installed base; Transportation Companies are climbing the fastest on compliance bundling.
Installation Type:
Architecture choices reflect fleet modernization stage and IT infrastructure maturity.
- Cloud-Based Solutions:Over-the-air data retrieval and analytics platforms eliminate physical download requirements. German freight operators are adopting these fastest, driven by compressed audit cycles and the European Labour Authority's coordinated inspection protocols.
- Integrated Systems:Tachograph modules embedded within unified telematics platforms. French logistics procurement departments prefer these bundled configurations over standalone hardware, consolidating vendor relationships.
- Standalone Devices:Discrete vehicle units operating independently of broader fleet management systems.
- Mobile Solutions:Portable compliance devices for temporary or rental fleet applications.
Integrated Systems hold current deployment share; Cloud-Based Solutions gain share fastest on subscription economics.
Compliance Level:
Certification tier determines market access and pricing power across European jurisdictions.
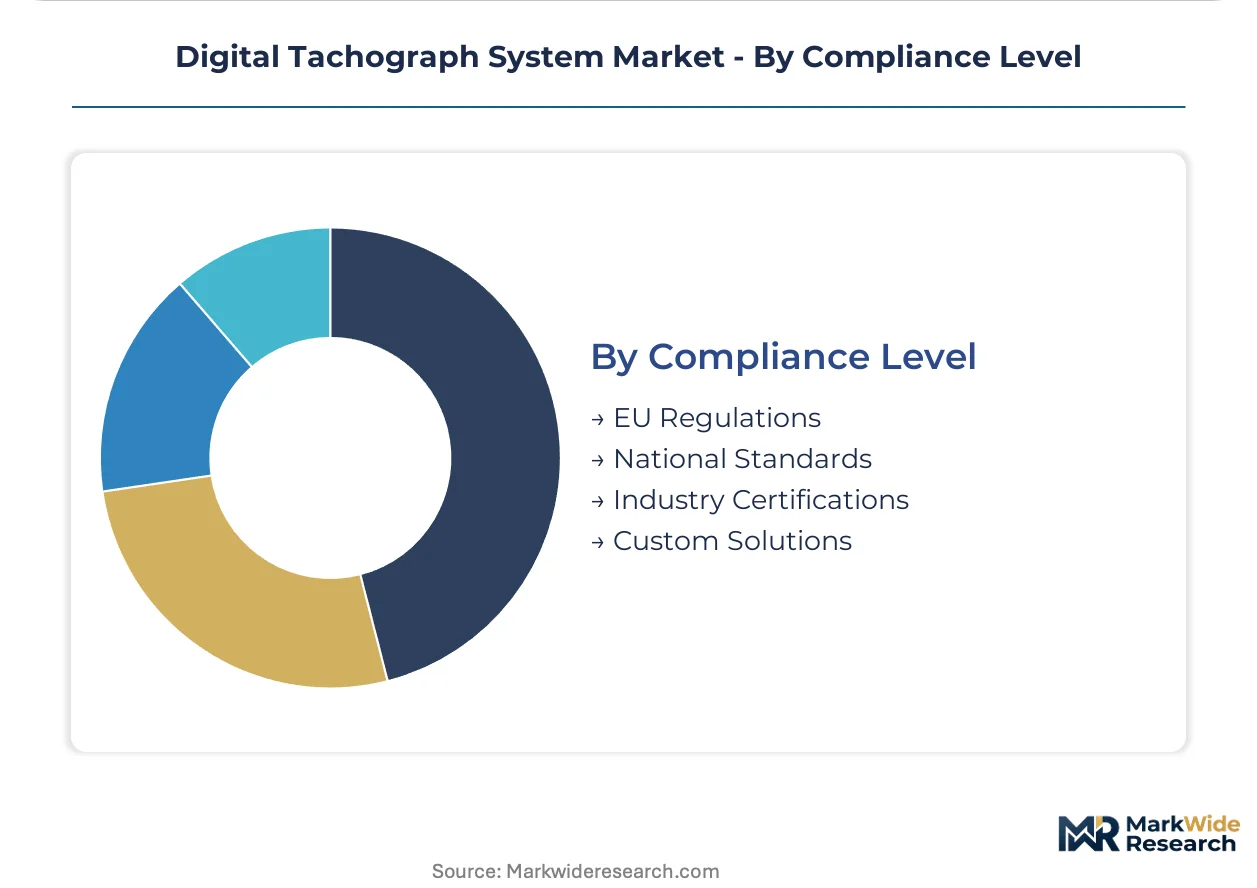
- EU Regulations:Mandatory type-approval under Annex 1C specifications with remote download capability. Germany's KBA and France's transport regulator enforce divergent testing protocols, creating redundant certification burdens for suppliers seeking multi-country market entry.
- National Standards:Country-specific interpretations of base EU frameworks with additional cybersecurity or data retention requirements.
- Industry Certifications:Sector-specific compliance for temperature-controlled transport or hazardous materials carriage.
- Custom Solutions:Bespoke configurations for specialized vehicle architectures or non-standard operational requirements.
EU Regulations anchor procurement specifications; National Standards show steepest expansion trajectory as cybersecurity testing protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors European tachograph system deployment, with Dortmund and Duisburg logistics hubs driving fleet-wide hardware refreshes under Annex 1C enforcement timelines.
Germany
Fleet operators in North Rhine-Westphalia and Bavaria absorb simultaneous costs of vehicle unit upgrades and backend integration. Germany's KBA enforces divergent type-approval testing protocols that create redundant certification burdens for multi-country suppliers. The Frankfurt-Rhine-Main logistics cluster sees fastest adoption of cloud-based remote data retrieval platforms.
France
Paris-based freight operators bundle tachograph procurement with multi-year data service contracts, compressing hardware margins while extending subscription revenue visibility. The country's transport regulator tightens cybersecurity resilience testing under evolving EU vehicle type-approval frameworks. Lyon and Lille logistics corridors concentrate demand for integrated telematics-tachograph systems in temperature-controlled transport segments.
Poland
Warsaw and Krakow logistics firms digitize previously paper-based compliance systems, creating first-mover hardware demand as roadside inspection cooperation with German authorities intensifies. The European Labour Authority's coordinated protocols elevate compliance penalties across cross-border routes. Silesian industrial zones anchor manufacturing supply chains for secure element production serving driver card programs.
United Kingdom
Midlands-based fleet operators navigate post-EU regulatory divergence while maintaining interoperability with continental tachograph standards. The Driver and Vehicle Standards Agency enforces retained EU regulations with pending divergence reviews. London freight corridors concentrate demand for mobile compliance solutions serving rental and temporary fleet applications.
Italy
Milan and Turin commercial vehicle manufacturers integrate tachograph modules at factory installation for new truck production lines. National transport authorities align with EU Green Deal vehicle electrification mandates that alter CAN bus architectures. Emilia-Romagna automotive suppliers pre-certify interface modules to accelerate customer approval timelines.
Digital Tachograph System Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the tachograph value chain, with integrated vehicle electronics manufacturers holding manufacturing depth advantages over specialized software vendors. The vendor base splits between diversified automotive tier-1 suppliers and focused compliance technology specialists. Three archetypes dominate: full-stack platform bundlers, hardware-centric type-approval specialists, and cloud-native analytics providers. Competitive moves concentrate on telematics platform integration and recurring revenue service contracts that displace one-time hardware margins.
Among diversified automotive suppliers, Continental Automotive and Robert Bosch GmbH exemplify full-stack platform bundlers that embed tachograph functionality within broader vehicle electronics portfolios. Stoneridge Electronics occupies a position within the specialized compliance tier, anchoring its market presence through dedicated commercial vehicle display and driver hour management systems. These three entities represent contrasting strategic postures: scale-driven integration versus focused regulatory technology depth.
| Leading Market Players |
|---|
| Continental Automotive |
| Stoneridge Electronics |
| Siemens |
| Veridos |
| Teletrac Navman |
| Robert Bosch GmbH |
| Actia Group |
| Gemalto |
| Transics |
| Others |
Supply Flow & Price Mechanics
Remote data retrieval architectures are compressing cost economics while concentrating supply leverage among cloud-native platform providers. Vehicle unit manufacturers face margin compression as fleet operators shift procurement criteria toward subscription-based telemetry economics rather than hardware durability metrics.
Pricing Analysis
Compliance automation outcomes anchor pricing power across the digital tachograph value chain. The dominant structure separates vehicle unit hardware from recurring software licensing tiers, with differentiation resting on certification grade and after-sales service bundling. Price erosion runs through standalone hardware vendors as integrated telematics platforms capture bundled procurement decisions. Small Polish fleet operators exhibit highest price sensitivity, while German freight carriers prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Freight costs from Asian semiconductor foundries to European assembly plants constitute a material cost layer for vehicle unit production. Supply concentrates in Taiwan and South Korea for automotive-grade microcontrollers, with Germany and Poland anchoring final assembly and type-approval testing. The chain draws from secure element packaging facilities in France and Germany for EMV-certified driver cards. Single-source vulnerability in automotive microcontroller supply creates exposure to lead time volatility. Distribution runs through OEM factory installation channels and aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vertical-integration depth, with control over secure element production and cloud infrastructure emerging as decisive competitive moats. Players lacking upstream captive supply of certified microcontrollers face structural margin disadvantage.
For Market Incumbents: Anchor market position through backward integration into secure element manufacturing or exclusive partnerships with EMV-certified packaging facilities. The threat from cloud-native analytics entrants demands accelerated bundling of hardware with multi-year data service contracts. Certification investment in cybersecurity resilience testing under Germany's KBA protocols creates switching costs that protect installed base. For New Entrants and Emerging Players: EU Annex 1C enforcement in Poland and Romania opens a window for first-mover hardware deployment among logistics operators digitizing paper-based compliance systems. Target temperature-controlled transport segments where regulatory documentation requirements intersect with cargo integrity monitoring needs. Pursue white-label partnerships with established telematics platforms rather than direct OEM sales channels. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified automotive tier-1 suppliers seeking telematics platform completeness. Long-term viability favors entities with recurring revenue visibility above sixty percent of total sales. Watch for inflection when roadside inspection cooperation protocols between Germany and Poland trigger accelerated replacement cycles among mid-sized fleet operators.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Manufacturing Integration | Captive supply of EMV-certified chips insulates against driver card production bottlenecks in European packaging facilities. |
| Cloud Platform Acquisition | Absorption of remote data retrieval capabilities accelerates recurring revenue transition beyond hardware replacement cycles. |
| Cybersecurity Certification Pre-Approval | Pre-certified CAN bus modules compress type-approval timelines with Germany's KBA and France's transport regulator. |
| Polish Fleet Operator Partnership | First-mover positioning among digitizing logistics corridors captures hardware demand before enforcement intensifies. |
| Temperature-Controlled Transport Bundling | Integration with cargo integrity monitoring systems addresses dual compliance requirements in pharmaceutical and food logistics. |
Methodological Framework
Document review covered EU regulatory filings, national transport authority type-approval records, and fleet operator procurement databases, complemented by interviews with commercial vehicle OEM procurement teams, fleet compliance managers, and automotive electronics R&D directors. Secondary validation drew from KBA enforcement statistics, European Labour Authority inspection protocols, and customs data on secure element trade flows. Bottom-up vehicle unit deployment estimates were triangulated against top-down fleet size and replacement cycle projections.
Market size and growth trajectories across the projection horizon reflect segmentation by product type, installation architecture, compliance certification tier, and fleet operator scale. CAGRs were derived from modeled replacement cycle acceleration under Annex 1C mandates and subscription revenue capture rates. Industry-specific inputs included roadside inspection penalty escalation schedules and CAN bus architecture transition timelines for electrified commercial vehicles.
The model assumes a particular technology adoption path; alternative pathways for over-the-air software update architectures would alter the outlook for physical downloading device obsolescence. Forecasts reflect assumptions regarding enforcement harmonization speed and semiconductor supply normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Human Interface System Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
Automotive Antenna Module Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
Automotive Voice Recognition System Market
Automotive Electronics & Wiring
Automotive HMI Market
Automotive Electronics & Wiring
Automotive Ignition Coil Connector Market
Automotive Electronics & Wiring
Russia Automotive Camera Market
Automotive Electronics & Wiring
Latin America Automotive Camera Market
Automotive Electronics & Wiring
Automotive Fuse Block Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Automotive AR Head-Up Display Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Passenger Vehicle Dashboard Camera Market
Automotive Electronics & Wiring
Global Body Control Modules Market
Automotive Electronics & Wiring
In-Car Wireless Charging Market