
 South Africa Automotive Camera Market | 2026-2036
South Africa Automotive Camera Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Automotive Camera Market Analytics
Aftermarket service revenue is fragmenting across diagnostic calibration, software updates, and sensor recalibration as camera complexity rises. Robert Bosch GmbH leverages its embedded software stack to sustain recurring service attachments. Continental AG anchors factory-installed channels through direct OEM relationships. Garmin Ltd competes in the dealer-installed segment with navigation-integrated camera systems.
The South Africa automotive camera comprises image sensors, lens assemblies, and signal processing units engineered to capture visual data for driver assistance, parking guidance, and collision avoidance, typically operating across temperature ranges from minus forty to eighty-five degrees Celsius and transmitting via LVDS or Ethernet protocols to central processing modules. Rear-view cameras dominate factory-installed fitment due to regulatory mandates, while 360-degree camera systems represent the fastest-growing product category as luxury and commercial vehicle buyers prioritize comprehensive surround visibility. Digital camera technology leads technology segmentation with superior low-light performance, whereas infrared cameras occupy niche positions in night-vision applications for premium segments.
South Africa's National Road Traffic Act and SABS vehicle safety standards shape product certification requirements, while the country's automotive production linked incentive scheme influences local sourcing thresholds for camera module assembly. The national automotive regulator enforces homologation protocols that align with UNECE R46 and R79 standards for mirror-replacement and driver assistance systems. Stakeholders must monitor evolving SABS electromagnetic compatibility testing protocols and the Department of Trade, Industry and Competition's local content requirements to secure continued market access and preferential procurement positioning.
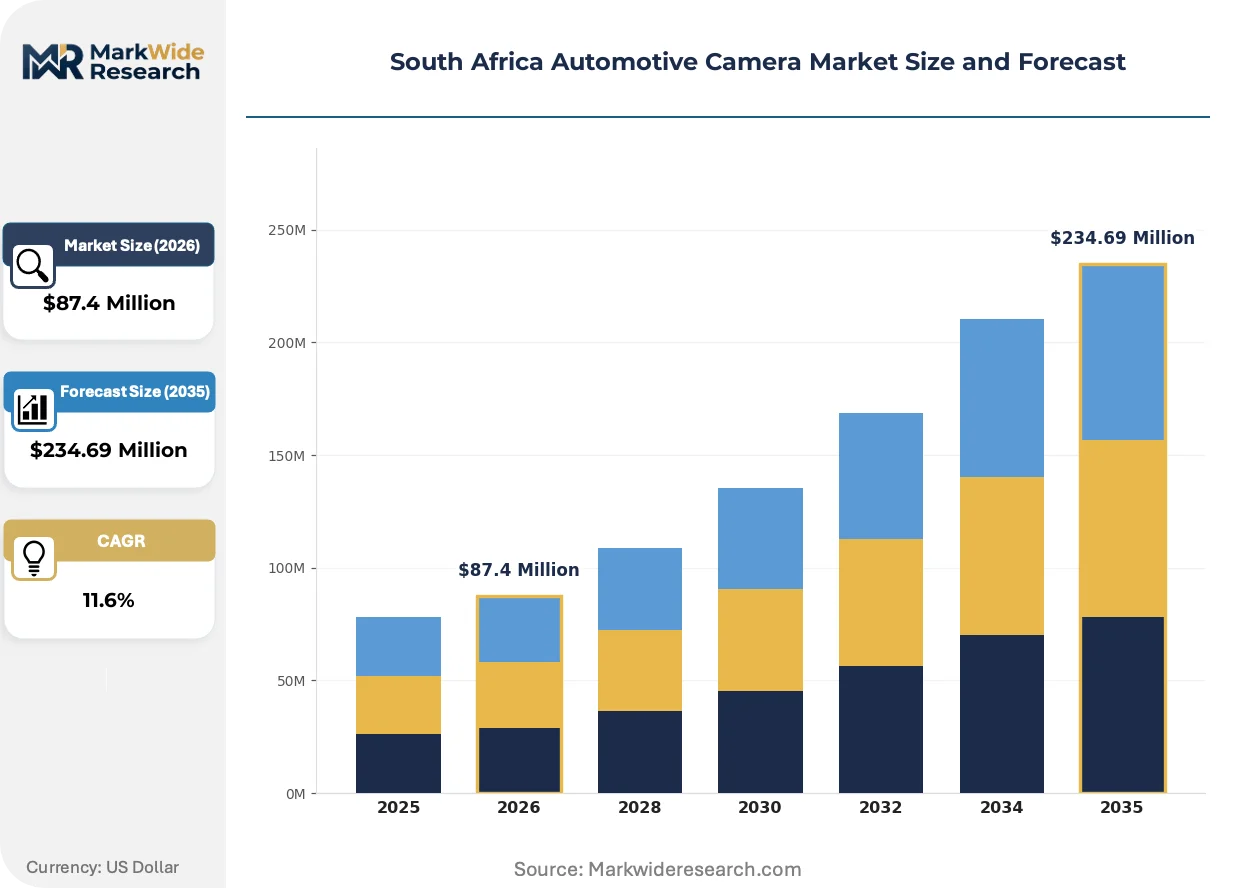
Market Dynamics
Fleet operators across Gauteng and KwaZulu-Natal are accelerating camera deployments for driver monitoring and liability reduction, while the National Road Traffic Act amendments mandating rear-view visibility systems are forcing rapid OEM integration cycles.
Growth Catalysts
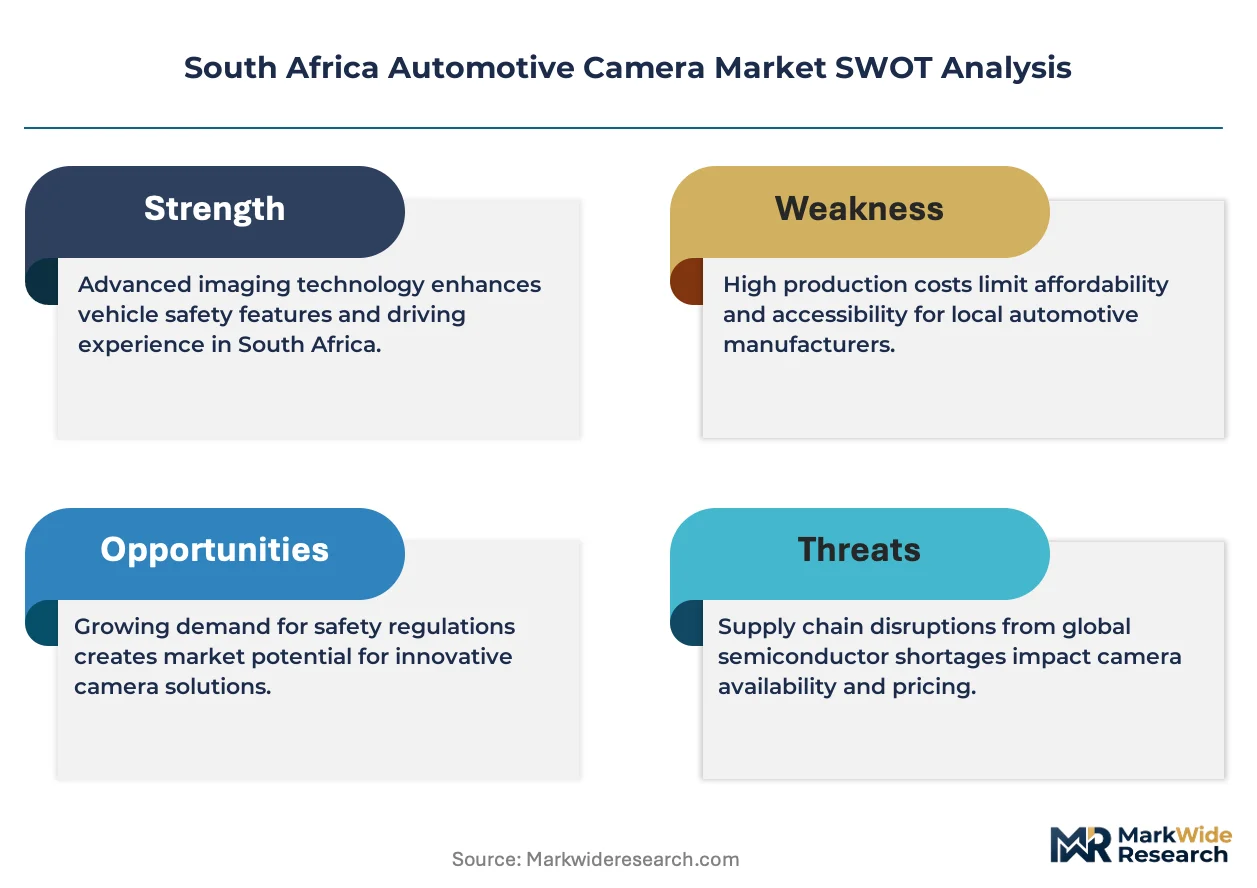
- Regulatory Mandate Expansion:The National Road Traffic Act amendments require rear-view visibility systems in all new vehicles, compelling automakers to standardize camera fitment across passenger and commercial vehicle lines.
- Logistics Hub Concentration:Durban port logistics corridors are embedding 360-degree camera systems in heavy commercial fleets to reduce cargo damage claims and insurance premiums.
- Image Sensor Advancement:Digital CMOS sensors with enhanced low-light performance are enabling reliable operation across South Africa's variable lighting conditions from dawn freight runs to nighttime mining operations.
Market Restraints
- Import Dependency:Over 80 percent of image sensors and lens assemblies originate from East Asian suppliers, exposing assemblers to currency volatility and shipping disruptions through Durban and Cape Town ports.
- Electromagnetic Compatibility Costs:SABS testing protocols for electromagnetic interference require expensive chamber certification, adding 12-18 weeks to product validation timelines for local distributors.
- Smartphone Integration Threat:Aftermarket dashcam demand faces erosion from high-resolution smartphone mounts and third-party recording applications that satisfy basic liability documentation needs.
Strategic Opportunities
- Eastern Cape Manufacturing Corridor:The Coega Special Economic Zone offers tax incentives for automotive component assembly, creating a lower-cost production base for camera module integration serving Sub-Saharan export markets.
- AI-Enabled Driver Analytics:Machine vision algorithms for fatigue detection and distraction monitoring are converging with edge computing hardware, opening subscription-based software revenue streams for fleet management providers.
- Dealer Network Penetration:Independent service workshops in Mpumalanga and Limpopo remain undersupplied with diagnostic calibration equipment, representing a channel expansion opportunity for technical service providers.
Industry Challenges
- Calibration Technician Shortage:Advanced Driver Assistance Systems require precise camera alignment procedures that demand specialized training, yet technical colleges in South Africa graduate fewer than 200 qualified technicians annually.
- Multi-Sensor Integration Complexity:360-degree surround view systems require synchronization of four to six camera feeds with ultrasonic sensors and radar units, complicating wiring harness design and warranty claim resolution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Automotive Camera Market |
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $234.69 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rear-View Cameras, Forward Collision Cameras, 360-Degree Cameras, Parking Assistance Cameras Technology: Analog Cameras, Digital Cameras, Infrared Cameras, HDR Cameras End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation: Factory Installed, Dealer Installed, DIY, Retrofit |
| Companies Covered | Magna International Inc, Robert Bosch GmbH, Gentex Corporation, Continental AG, Autoliv Inc, Valeo SA, Hella KGaA Hueck & Co, Garmin Ltd, Panasonic Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Automotive Camera Market Evolving Landscape
Automotive camera architectures are fragmenting into modular subsystems that separate image capture from processing, enabling software-defined upgrades that extend hardware lifecycles without full replacement.
High-dynamic-range CMOS image sensors are migrating from premium passenger vehicles into mid-range commercial fleets as unit economics improve. Mining operators in the Northern Cape and platinum belt transport contractors are adopting these sensors for dust-penetrating visibility in harsh extraction environments. This technology diffusion is compressing the traditional three-tier equipment hierarchy and forcing suppliers to standardize on single sensor platforms across price segments.
SABS electromagnetic compatibility testing protocols are tightening alignment with UNECE R10 standards, requiring manufacturers to redesign shielding architectures and filtering circuits. Component suppliers serving the South African assembly market must now pre-certify modules in European test facilities before local homologation. The regulatory convergence is favoring multinational tier-1 suppliers with existing global certification portfolios over domestic distributors dependent on third-party testing houses.
Aftermarket procurement is fragmenting from bundled hardware-software packages toward unbundled sensor modules with separately purchased calibration services. Fleet maintenance managers in Johannesburg-Pretoria corridors are sourcing cameras through automotive parts wholesalers while contracting independent technicians for installation and alignment. This channel bifurcation is most pronounced in long-haul trucking segments where cost scrutiny overrides brand loyalty and standardized service intervals dominate replacement timing.
South Africa Automotive Camera Market Segmentation
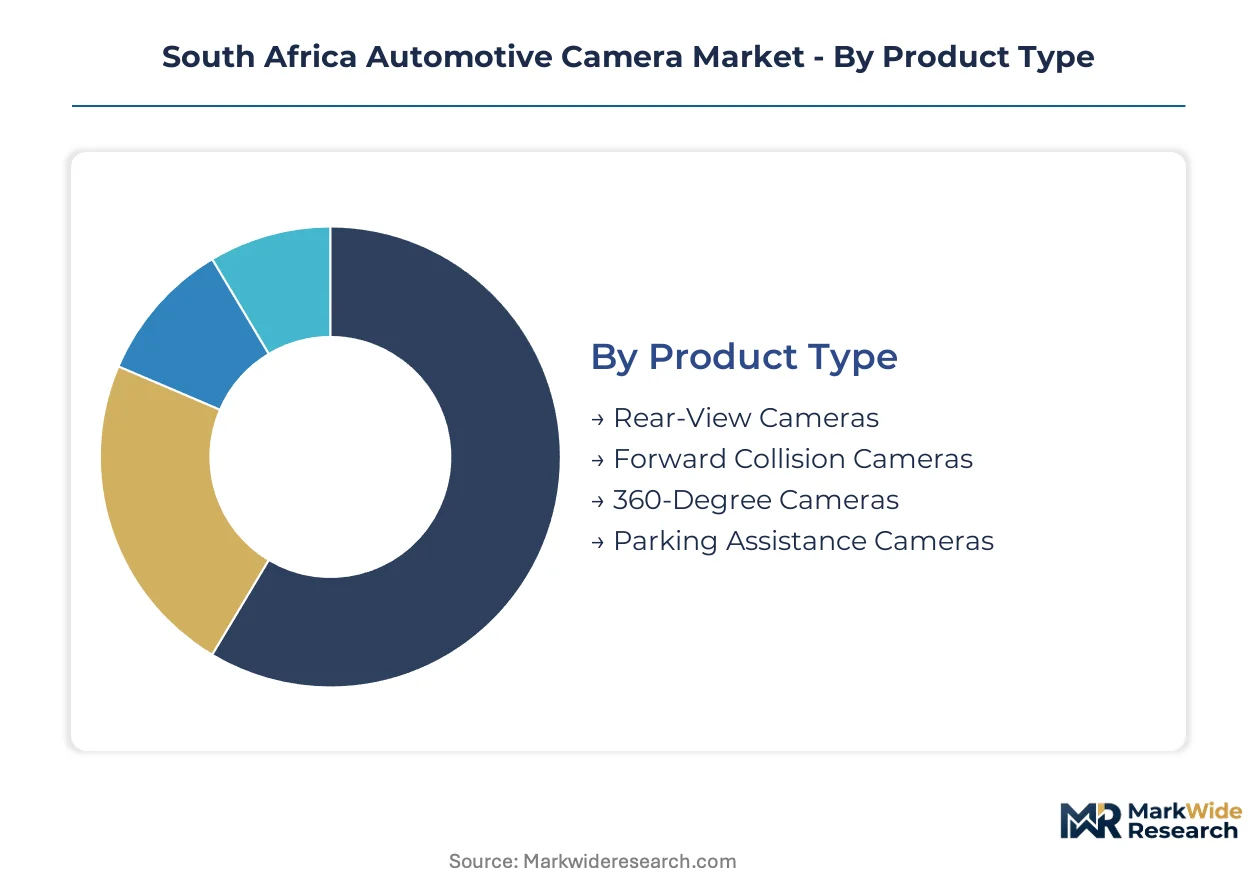
Camera module specifications diverge sharply across South African vehicle production lines, with OEM fitment cycles running 4-6 years while aftermarket refresh rates compress to 18-24 months. Fleet operators in Gauteng and KwaZulu-Natal drive the fastest replacement cadence through wear-intensive commercial applications.
Product Type:
Replacement cycles stretch from 7-year factory-installed rear-view systems to 2-year aftermarket parking units, creating distinct inventory velocity tiers for distributors serving Johannesburg-Pretoria corridors.
- Rear-View Cameras:These single-lens modules integrate with dashboard displays to eliminate rear blind spots during reversing maneuvers. Regulatory mandates under South Africa's National Road Traffic Act amendments compel standardized fitment across all new vehicle registrations, cementing factory-installed dominance in Durban assembly plants.
- 360-Degree Cameras:Multi-lens arrays synthesize bird's-eye visibility through software-stitched video feeds. Mining fleet operators in the Northern Cape and platinum belt transport contractors adopt these systems fastest for maneuvering in confined extraction environments where collision costs exceed hardware investment.
- Forward Collision Cameras:Mono or stereo configurations support automatic emergency braking and lane departure warnings. Premium passenger vehicle lines in the Eastern Cape manufacturing corridor embed these as standard equipment.
- Parking Assistance Cameras:Short-range sensors with wide-angle optics guide low-speed maneuvering in constrained urban spaces. Independent installers in Mpumalanga and Limpopo service this segment through mobile calibration units.
Rear-View Cameras anchors the volume base while 360-Degree Cameras gains share at the steepest rate.
Technology:
Cost structures stratify sharply between legacy analog architectures and digital CMOS platforms, with price multiples of 3-4x separating entry-level from premium sensor tiers.
- Digital Cameras:CMOS image sensors with on-chip analog-to-digital conversion deliver superior low-light performance and noise reduction. Heavy commercial fleets operating dawn freight runs through Johannesburg-Pretoria logistics corridors specify these for reliable operation across South Africa's variable lighting conditions.
- HDR Cameras:High-dynamic-range sensors capture simultaneous shadow and highlight detail through multi-exposure fusion. Mining contractors in dust-heavy extraction environments adopt these fastest for visibility preservation in harsh operating conditions.
- Analog Cameras:Legacy CCD or CMOS architectures with composite video output persist in cost-sensitive retrofit applications. Budget-conscious independent operators in Limpopo maintain limited procurement for basic liability documentation.
- Infrared Cameras:Near-infrared or thermal imaging modules enable night-vision functionality through active illumination or heat signature detection. Premium vehicle assemblers serving diplomatic and executive transport segments in Gauteng integrate these for specialized security applications.
Digital Cameras commands the largest procurement volumes while HDR Cameras expands most quickly in commercial fleet specifications.
End User:
Technical capability requirements separate participants who perform in-house calibration from those outsourcing alignment procedures to certified technicians.
- OEMs:Vehicle manufacturers with direct homologation responsibility under SABS and UNECE standards. Ford, Toyota, and Volkswagen South Africa integrate camera modules at original assembly points in Gauteng and Eastern Cape facilities.
- Tier-1 Suppliers:Robert Bosch GmbH and Continental AG deliver pre-validated camera assemblies with embedded software stacks. These suppliers maintain direct engineering relationships with OEM program offices for specification lock-in.
- Aftermarket Providers:Garmin Ltd and independent distributors serve dealer-installed and DIY channels through navigation-integrated systems. Technical service fragmentation creates recurring revenue attachments for diagnostic calibration.
- Vehicle Assemblers:Contract manufacturers and kit assembly operations serving Sub-Saharan export markets from Coega Special Economic Zone operations. These entities source camera modules through tier-1 distributors rather than direct OEM relationships.
OEMs dominate absolute procurement value while Aftermarket Providers demonstrates the steepest expansion trajectory through fleet retrofit cycles.
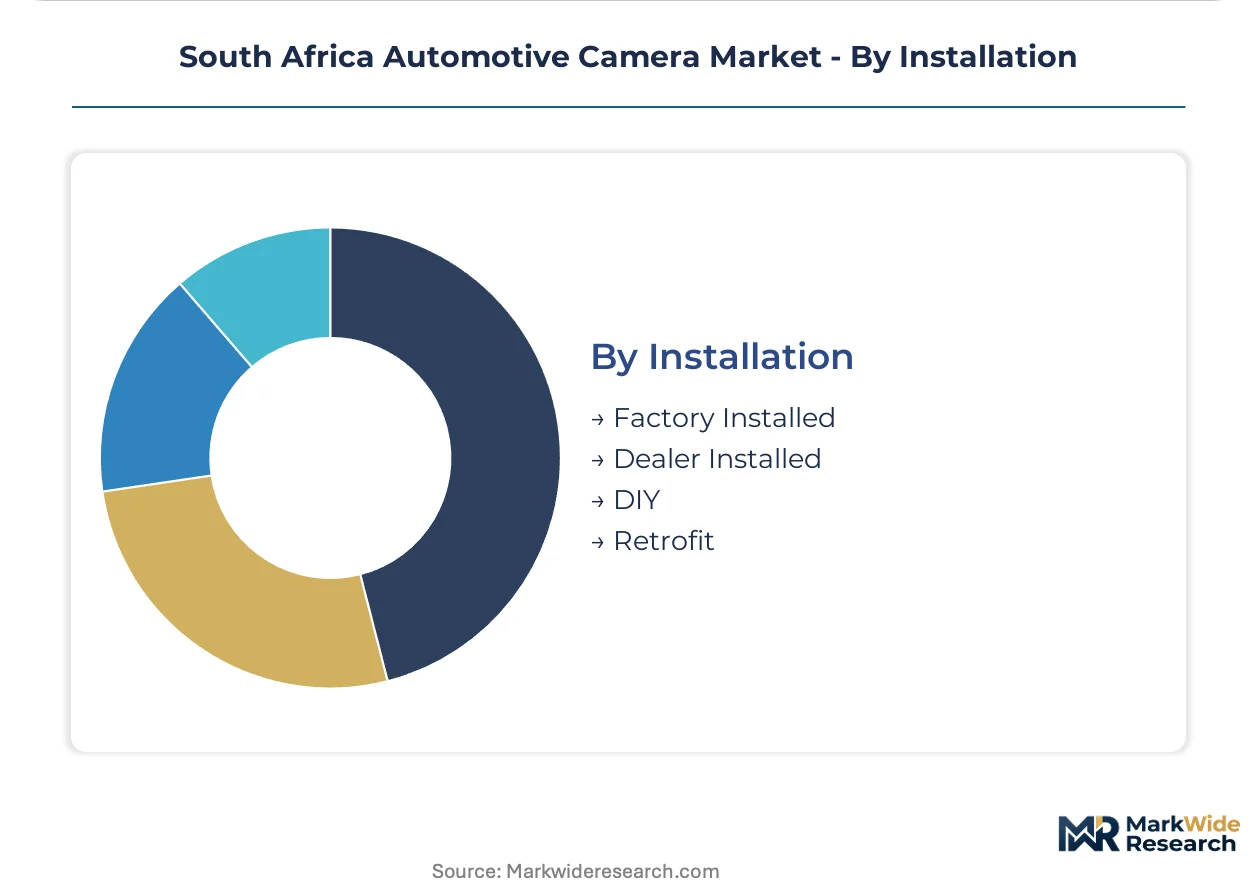
Installation:
Channel economics favor factory integration for regulatory-mandated systems while discretionary upgrades flow through lower-margin aftermarket pathways.
- Factory Installed:Module integration during vehicle assembly with embedded wiring harness design and windshield-integrated mounting. Rear-view visibility mandates under National Road Traffic Act amendments force 100% penetration in new vehicle registrations.
- Dealer Installed:Authorized service centers perform post-sale upgrades with OEM-approved calibration procedures. Franchise networks in Durban and Cape Town concentrate this activity for warranty preservation.
- DIY:Consumer-purchased systems with adhesive mounting and cigarette-lighter power delivery. Smartphone integration threats erode this segment as basic recording needs shift to mobile device mounts.
- Retrofit:Specialist workshops upgrade legacy vehicles with modern camera architectures requiring extensive harness modification. Independent technicians in Mpumalanga service long-haul trucking fleets through mobile deployment models.
Factory Installed captures the dominant revenue share while Retrofit climbs fastest among commercial vehicle operators extending asset lifecycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Camera module assembly concentrates in Gauteng and Eastern Cape manufacturing corridors, with component sourcing flowing through Durban and Cape Town ports. Sub-regional demand patterns diverge sharply between commercial fleet operators and passenger vehicle assemblers.
Gauteng
Fleet operators in Johannesburg-Pretoria logistics corridors deploy driver monitoring systems for liability reduction and insurance premium optimization. The National Road Traffic Act amendments mandate rear-view visibility systems for all new vehicle registrations registered in this province. Ford and Toyota South Africa operate integrated camera fitment lines at their Silverton and Prospecton assembly plants.
KwaZulu-Natal
Durban port logistics hubs embed 360-degree camera systems in heavy commercial fleets to reduce cargo damage claims. SABS homologation protocols align with UNECE R46 standards for mirror-replacement systems. The Dube TradePort special economic zone hosts aftermarket calibration service providers serving long-haul trucking corridors.
Eastern Cape
The Coega Special Economic Zone offers tax incentives for automotive component assembly targeting Sub-Saharan export markets. The Department of Trade, Industry and Competition's local content requirements influence sourcing thresholds for camera module integration. Volkswagen Group South Africa operates its Uitenhage manufacturing facility with embedded rear-view camera fitment for domestic and export vehicle lines.
Western Cape
Cape Town port infrastructure handles image sensor imports from East Asian suppliers, exposing assemblers to currency volatility and shipping disruptions. SABS electromagnetic compatibility testing protocols require expensive chamber certification for products entering this market. Bellville industrial precinct hosts independent diagnostic calibration workshops serving regional aftermarket demand.
Mpumalanga and Limpopo
Independent service workshops in these provinces remain undersupplied with diagnostic calibration equipment for Advanced Driver Assistance Systems. Technical colleges graduate fewer than 200 qualified calibration technicians annually nationwide, constraining service capacity. Mining transport contractors in the platinum belt adopt HDR camera systems for dust-penetrating visibility in harsh extraction environments.
South Africa Automotive Camera Market Competitive Landscape
Embedded software specialists and hardware-integrated tier-1 suppliers split the market along the factory-installed versus aftermarket divide. Market structure tilts toward consolidation among multinational component manufacturers with direct OEM engineering relationships, while distribution channels fragment across dealer networks and independent installers. Two strategic archetypes dominate: technology licensors with recurring service attachments, and scale manufacturers with captive supply agreements. Competitive moves center on diagnostic calibration capability acquisition and Sub-Saharan distribution network expansion.
Within the factory-installed tier, Robert Bosch GmbH and Continental AG occupy positions as embedded software stack providers with direct OEM program office relationships. Garmin Ltd exemplifies the navigation-integrated aftermarket specialist competing through dealer-installed channels. These three entities represent the dominant competitive anchors across South Africa's bifurcated procurement landscape, with technology licensors defending margin positions through software-defined upgrade architectures and hardware-integrated suppliers leveraging volume scale across Gauteng and Eastern Cape assembly corridors.
| Leading Market Players |
|---|
| Magna International Inc |
| Robert Bosch GmbH |
| Gentex Corporation |
| Continental AG |
| Autoliv Inc |
| Valeo SA |
| Hella KGaA Hueck & Co |
| Garmin Ltd |
| Panasonic Corporation |
| Others |
Value Network & Pricing Analysis
Durban port logistics corridors concentrate camera module import volumes, and this geographic chokepoint feeds pricing power downstream to Gauteng-based assemblers who control distribution into Johannesburg-Pretoria manufacturing belts. SABS electromagnetic compatibility certification costs and currency exposure on East Asian component sourcing compress margins for distributors without direct OEM relationships.
Pricing Analysis
After-sales service revenue tiers encompassing diagnostic calibration, software-defined upgrades, and extended warranty contracts drive lifetime value capture for embedded software providers. Pricing stratifies across premium, standard, and economy tiers based on certification grade under UNECE R46 and SABS protocols and volume scale commitments from fleet operators. Cost compression in aftermarket channels is intensifying because smartphone integration threatens basic dashcam demand. Fleet maintenance managers in long-haul trucking segments exhibit highest price sensitivity, while OEM procurement offices prioritize specification lock-in over unit cost.
Supply Chain Analysis
Export-control regimes on advanced CMOS image sensors and signal processing semiconductors limit technology flows from certain jurisdictions, constraining local assembly options. Component sourcing draws from Taiwan, South Korea, and China for image sensors, lens assemblies, and processing units. Raw material dependencies rest on rare-earth elements for sensor substrates, specialized optical glass, and copper-alloy shielding materials. Single-source vulnerability around East Asian sensor manufacturers exposes assemblers to shipping disruptions through Durban and Cape Town ports. Distribution runs through tier-1 supplier direct relationships with OEM program offices and fragmented aftermarket wholesalers serving independent installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across calibration service networks and fleet retrofit cycles creates niche entry points for specialists who can aggregate undersupplied technical capacity in peripheral provinces.
For Market Incumbents: Entrench factory-installed dominance by deepening backward integration into image sensor sourcing and expanding captive calibration service networks in Mpumalanga and Limpopo. Robert Bosch GmbH and Continental AG should preempt emerging AI-enabled driver analytics specialists by acquiring edge-computing hardware capabilities before subscription-based software revenue models mature. For New Entrants and Emerging Players: Mpumalanga and Limpopo independent service workshops represent the most penetrable geography, with diagnostic calibration equipment shortages constraining incumbent service capacity. New entrants should target fleet retrofit cycles in platinum belt mining transport corridors with mobile calibration units and unbundled sensor module procurement. A go-to-market angle through automotive parts wholesalers bypasses franchise dealer network gatekeeping. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compounding play because National Road Traffic Act amendment cycles and SABS protocol tightening create recurring compliance demand that outlasts hardware replacement waves. Acquisition targets should display software-defined upgrade architectures and existing UNECE certification portfolios. The signal to watch is Eastern Cape manufacturing corridor expansion announcements that would validate Coega Special Economic Zone as a Sub-Saharan export hub.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables over-the-air camera system upgrades extending hardware lifecycles without full replacement. |
| Geographic Manufacturing Footprint | Coega Special Economic Zone tax incentives lower cost base for Sub-Saharan export market assembly. |
| Platform Standardization | Single sensor platforms across price segments compress three-tier equipment hierarchy and reduce SKU complexity. |
| Backward Integration into Sensors | Captive supply of CMOS image sensors mitigates currency volatility on East Asian import dependency. |
| Charging Infrastructure Partnership | Camera-integrated charging station monitoring aligns with fleet electrification and liability documentation needs. |
Research Methodology
Cross-validation between primary fieldwork with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet maintenance managers anchors the qualitative findings against secondary validation. Bottom-up and top-down triangulation incorporates vehicle production databases, IHS Markit registration data, SABS homologation records, and customs import manifests for image sensor and lens assembly flows.
Calibration against historical fitment rates and regulatory amendment timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user category, and installation channel alongside regional production cluster dynamics. CAGRs were derived from trend extrapolation adjusted for regulatory mandate phase-in schedules and fleet replacement cycle compression in commercial applications.
Macroeconomic conditions sit as an overlay; deviation in rand-dollar exchange rates and Durban port throughput capacity would shift the trajectory. Forecasts reflect documented assumptions around SABS protocol adoption timelines and UNECE regulatory convergence. Material shifts in National Road Traffic Act enforcement intensity or East Asian supplier consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
North America Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Fuse Block Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
Mlccs for Automotive Electronics Market
Automotive Electronics & Wiring
Automotive Digital Cockpit Market
Automotive Electronics & Wiring
Automotive Logging Device Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Automotive Wireless Module Market
Automotive Electronics & Wiring
Car Digital Video Recorder (DVR) Market
Automotive Electronics & Wiring
Automotive Sparking Cable Market
Automotive Electronics & Wiring
Automotive Data Logger Market
Automotive Electronics & Wiring
Automotive NFC Market
Automotive Electronics & Wiring
Automotive Antenna Module Market