
 Automotive Hydrostatic Fan Drive System Market | 2026-2036
Automotive Hydrostatic Fan Drive System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Hydrostatic Fan Drive System Market Intelligence
Commercial vehicle OEMs are reorganizing thermal management procurement around hydrostatic fan drive systems as engine cooling loads intensify under stricter emission regimes. Parker Hannifin Corporation leverages its integrated motion control portfolio to anchor supply relationships with North American truck builders. Danfoss A/S sustains engineering leadership through variable displacement pump specialization for off-highway applications. Bosch Rexroth AG competes on hydraulic system integration density across European bus and coach platforms.
An automotive hydrostatic fan drive system transmits engine power to cooling fans through a closed-loop hydraulic circuit comprising a variable or fixed displacement pump, hydraulic motor, and electronic control valves, enabling precise speed modulation independent of engine RPM for optimized thermal regulation. Variable displacement configurations command premium positioning due to their fuel efficiency advantages in stop-start duty cycles, while fixed displacement units retain cost-sensitive share in emerging market commercial fleets. Electronic control technology is displacing mechanical alternatives as OEMs mandate CAN-bus integration and predictive thermal management algorithms.
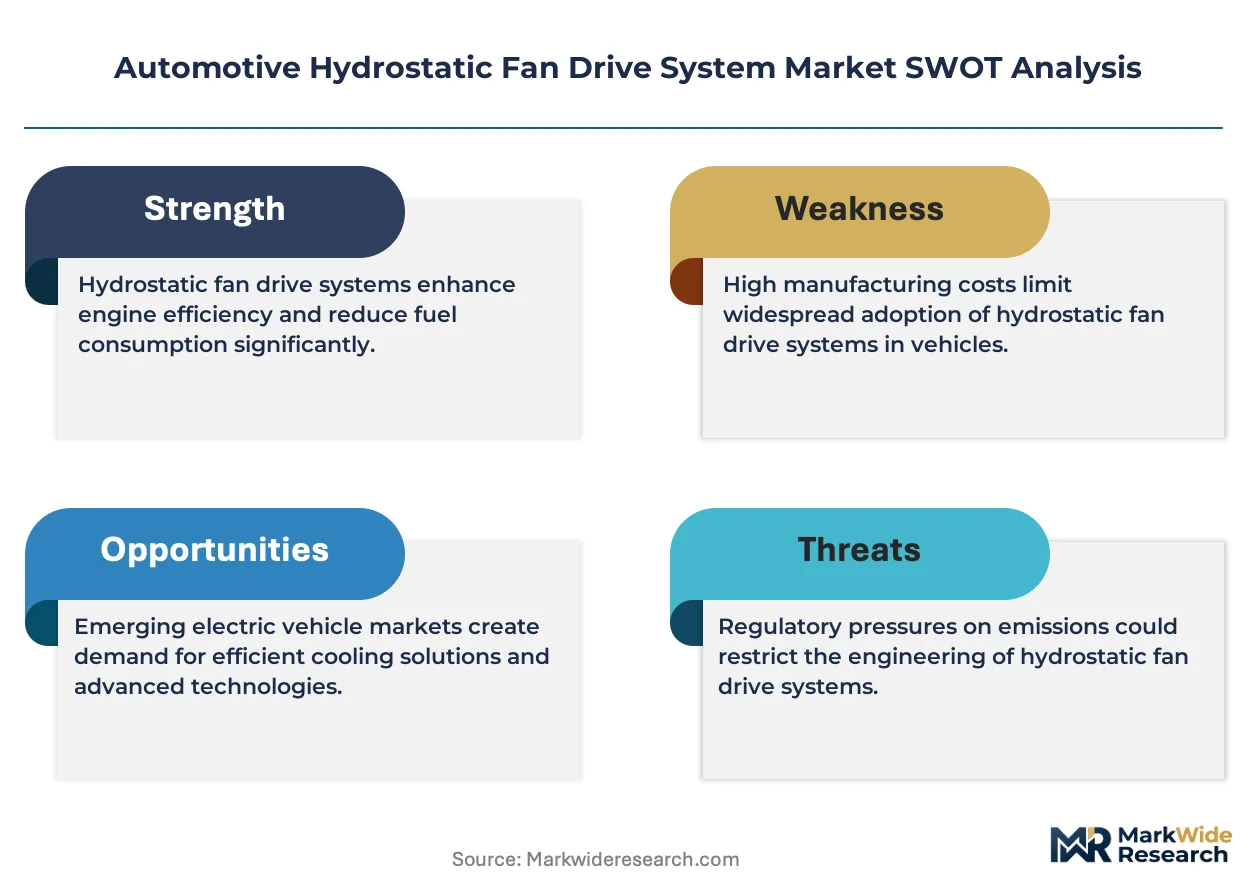
EPA Phase 3 greenhouse gas standards and Euro 7 emission frameworks are mandating tighter engine temperature control bands, directly expanding specification scope for sensor-integrated hydrostatic drives. The EU F-Gas Regulation and REACH chemical compliance further constrain refrigerant and hydraulic fluid selections, reshaping component material strategies. Stakeholders must monitor how EPA and European Commission rulemakings on commercial vehicle CO2 thresholds redefine cooling system power budgets and supplier qualification requirements.
Market Dynamics
Engine downsizing and electrification are forcing commercial vehicle thermal management into closed-loop hydraulic architectures that decouple fan speed from crankshaft RPM, compressing supplier margins while expanding specification complexity.
Growth Catalysts
- EPA Phase 3 greenhouse gas standards:Mandated CO2 reductions for heavy-duty trucks are expanding specification scope for sensor-integrated hydrostatic drives in North American Class 8 vehicles.
- Bus and coach electrification:Battery thermal management requirements in European urban transit fleets are pulling demand for variable displacement pump-motor combinations with CAN-bus integration.
- Stop-start duty cycle optimization:Fuel efficiency algorithms in German heavy-duty manufacturing corridors are specifying electronically controlled fan drives over mechanical alternatives.
Market Restraints
- Hydraulic fluid cost volatility:Synthetic ester base stocks face supply pressure from biofuel feedstock competition, squeezing component margins in fixed displacement segments.
- Supplier concentration in German manufacturing:Precision pump casting capacity clusters along the Rhine-Ruhr corridor, creating single-source vulnerability for European OEM qualification timelines.
- Electric fan drive substitution:High-voltage electric motor architectures for battery-electric trucks threaten hydraulic system relevance in long-haul segments beyond 2030.
Strategic Opportunities
- Indian commercial vehicle modernization:Bharat Stage VI Phase 2 enforcement is opening specification windows for hydrostatic cooling in medium-duty truck production at Chennai and Pune manufacturing hubs.
- Predictive thermal management algorithms:Machine learning integration with engine control units enables anticipatory fan modulation, creating software-differentiated service contracts.
- EU F-Gas Regulation compliance:Refrigerant phase-down mandates are redirecting R&D budgets toward hydraulic cooling architectures as alternative thermal pathways in coach applications.
Industry Challenges
- Embedded systems engineering scarcity:CAN-bus protocol expertise for hydraulic-electronic integration is concentrated among aging specialist workforces in Stuttgart and Detroit engineering centers.
- Multi-standard certification complexity:Simultaneous EPA, Euro 7, and UN ECE type approval requirements are extending validation timelines for new pump-motor combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Hydrostatic Fan Drive System Market |
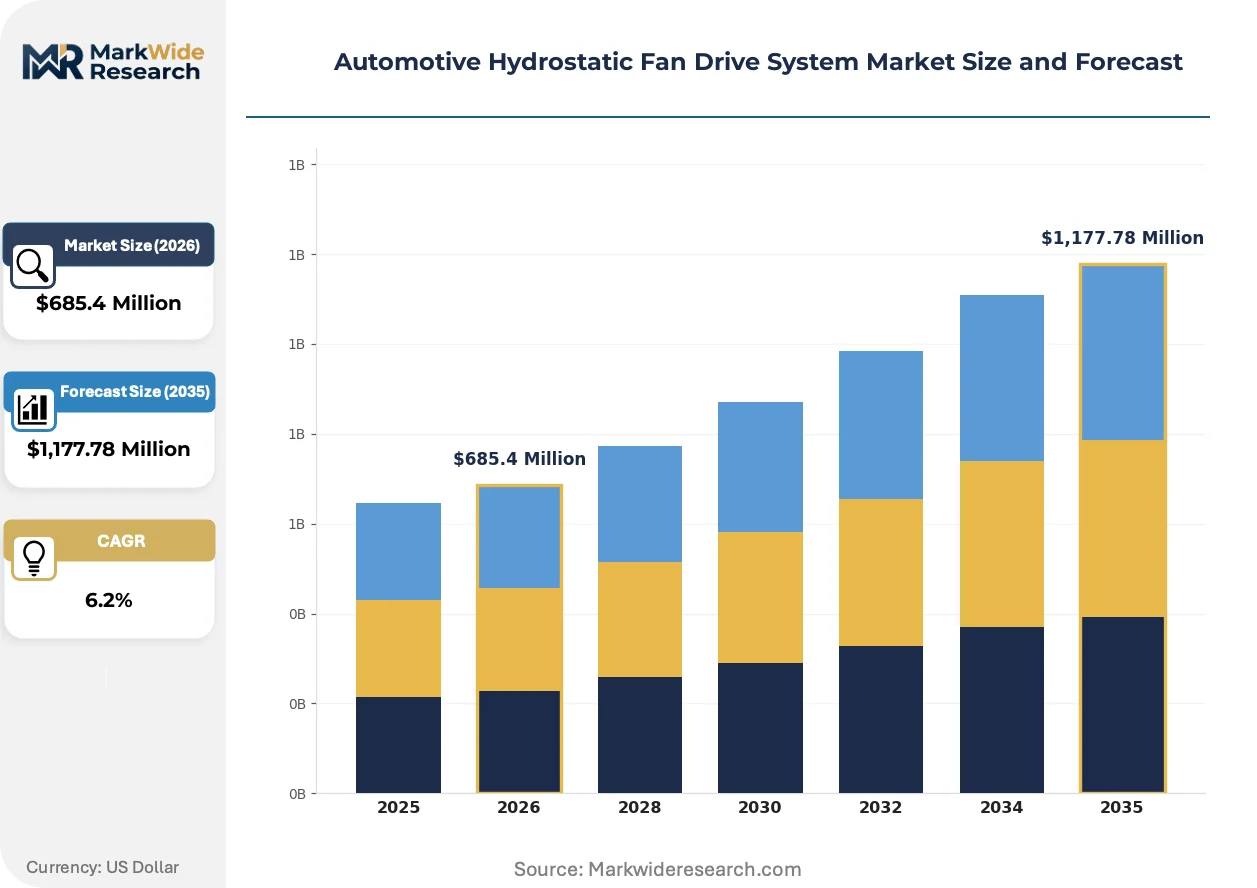
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Variable Displacement, Fixed Displacement, System Kit, Hydraulic Component Application: Cooling Systems, Engine Temperature Control, HVAC Systems, Agricultural Equipment End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Electronic Control, Mechanical Control, Hydraulic Technology, Sensors |
| Companies Covered | Parker Hannifin Corporation, Danfoss A/S, Eaton Corporation, Bosch Rexroth AG, Bucher Hydraulics, JTEKT Corporation, Kawasaki Precision Machinery, HydraForce, Concentric AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Hydrostatic Fan Drive System Market Strategic Shifts & Innovations
Closed-loop hydraulic architectures are fragmenting into application-specific configurations as OEMs abandon universal platforms in favor of thermal management systems calibrated to specific engine duty cycles and emission certification tiers.
Variable displacement pump technology is fragmenting across commercial vehicle segments. Off-highway equipment manufacturers specify swashplate designs with integrated load-sensing for intermittent cooling demands. On-highway truck builders adopt simpler bent-axis configurations for steady-state highway operation. This technical divergence is fragmenting supplier development roadmaps and compressing economies of scale for universal component families.
REACH chemical compliance is constraining hydraulic fluid formulation options across European supply chains. ECHA substance restriction proposals targeting certain anti-wear additives are forcing reformulation of zinc-based chemistry portfolios. Component manufacturers are responding with stainless steel surface treatments that reduce additive dependence in high-pressure pump circuits.
Fleet procurement patterns are compressing supplier qualification cycles as commercial vehicle operators unbundle cooling system specification from powertrain sourcing agreements. Large logistics operators in the US Midwest are issuing direct component contracts to hydraulic specialists, bypassing traditional tier-one integrators. This channel disintermediation is most pronounced in refrigerated transport segments where thermal reliability carries direct cargo value risk.
Automotive Hydrostatic Fan Drive System Market Segmentation
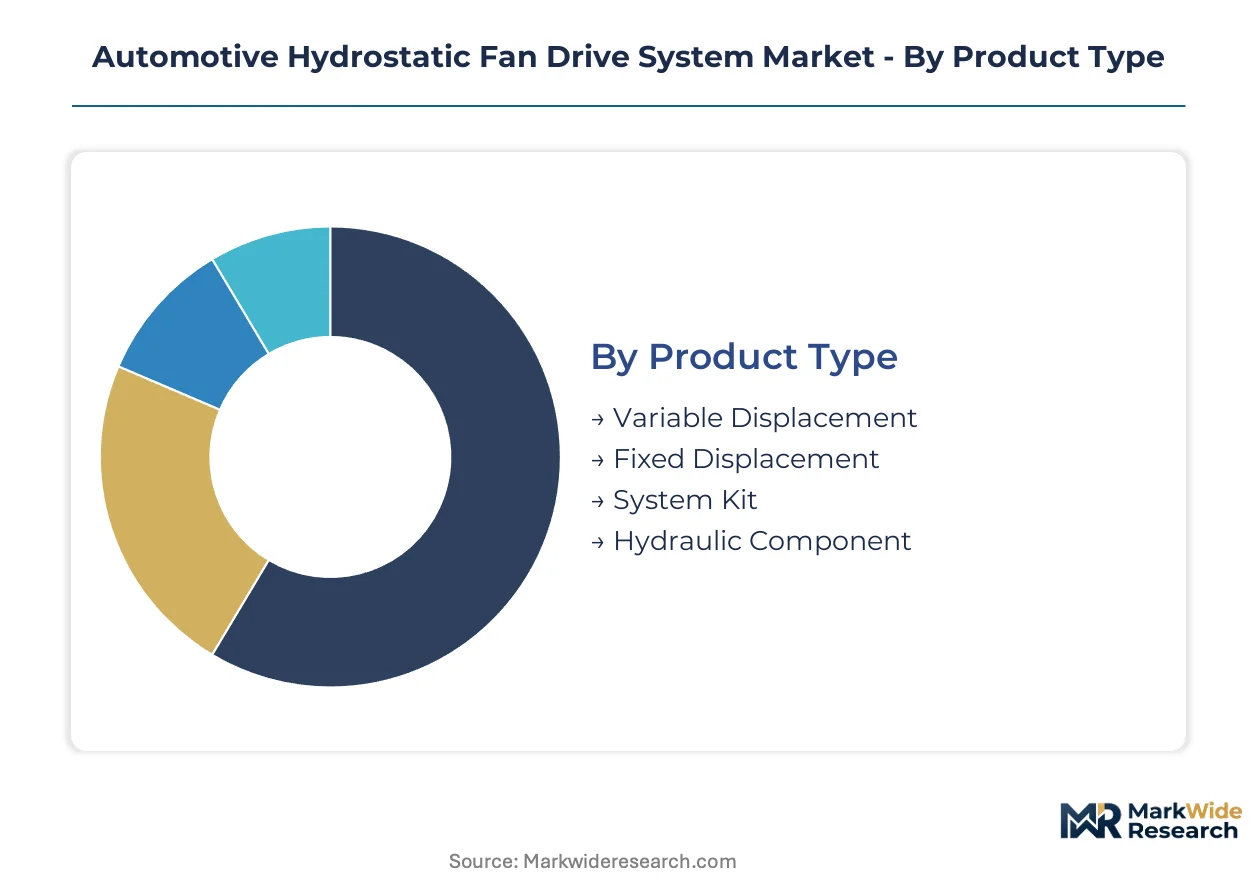
Hydrostatic fan drive system procurement channels diverge sharply by segment, with OEM direct contracts dominating high-complexity variable displacement configurations while aftermarket providers capture standard replacement volumes. Understanding these channel dynamics reveals where supplier margin structures concentrate and where price compression risks intensify.
Product Type:
Variable displacement units flow through OEM direct channels with embedded electronic control packages, while fixed displacement products distribute via tier-1 integrators serving cost-optimized fleet specifications.
- Variable Displacement:Swashplate and bent-axis pump configurations enable precise flow modulation for stop-start duty cycles. German heavy-duty truck manufacturers specify these for Euro 7 compliance, with sensor integration commanding premium positioning through captive supply arrangements.
- Fixed Displacement:Gear pump architectures deliver constant flow rates at lower unit economics. Indian and Brazilian commercial vehicle assemblers source these through tier-1 cooling module suppliers for Bharat Stage VI and Proconve P8 emission tiers.
- System Kit:Pre-assembled pump-motor-control valve combinations reduce installation complexity for mid-size bus manufacturers.
- Hydraulic Component:Individual pumps, motors, and reservoir assemblies serve aftermarket rebuild channels and specialized agricultural equipment retrofits.
Fixed displacement dominates installed base across emerging market commercial fleets. Variable displacement is where expansion concentrates as European and North American emission thresholds tighten.
Application:
Application segmentation tracks thermal load intensity, with high-stress cooling applications commanding integrated electronic architectures and lighter HVAC loads tolerating mechanical control alternatives.
- Cooling Systems:Radiator and charge air cooling circuits in heavy-duty trucks require continuous flow modulation under variable ambient conditions. US Class 8 vehicle production at Michigan and Ohio assembly plants specifies sensor-integrated hydrostatic drives for EPA Phase 3 thermal management mandates.
- Engine Temperature Control:Precision coolant regulation for downsized turbocharged engines demands rapid fan response curves. German Mannheim and Stuttgart engineering corridors concentrate development for these applications.
- HVAC Systems:Cabin climate control circuits prioritize noise reduction and steady-state efficiency over dynamic response.
- Agricultural Equipment:Intermittent cooling loads in combine harvesters and tractors favor robust mechanical control architectures with simplified maintenance protocols.
Engine temperature control commands the highest specification intensity. Cooling systems represent the broadest volume base with steepest expansion trajectory as electrification multiplies thermal management points.
End User:
End user segmentation reflects unbundling trends in commercial vehicle procurement, with direct fleet contracts bypassing traditional tier-1 relationships in refrigerated transport and premium coach segments.
- OEMs:Daimler Truck, Volvo Group, and Traton specify complete hydrostatic modules through multi-year supply agreements with hydraulic specialists. These contracts embed software update obligations and predictive maintenance service tiers.
- Aftermarket Providers:Independent distributors and service networks capture replacement demand for mechanical control units in aging commercial fleets across Eastern European and Latin American markets.
- Tier-1 Suppliers:Cooling module integrators like Mahle and Modine source hydraulic components for assembly into thermal management systems.
- Vehicle Assemblers:Small-volume bus and specialty vehicle manufacturers procure kit configurations for flexible production lines.
OEMs dominate specification authority for new vehicle platforms. Aftermarket providers are gaining share fastest as fleet operators extend vehicle lifecycles and unbundle component replacement from dealer service networks.
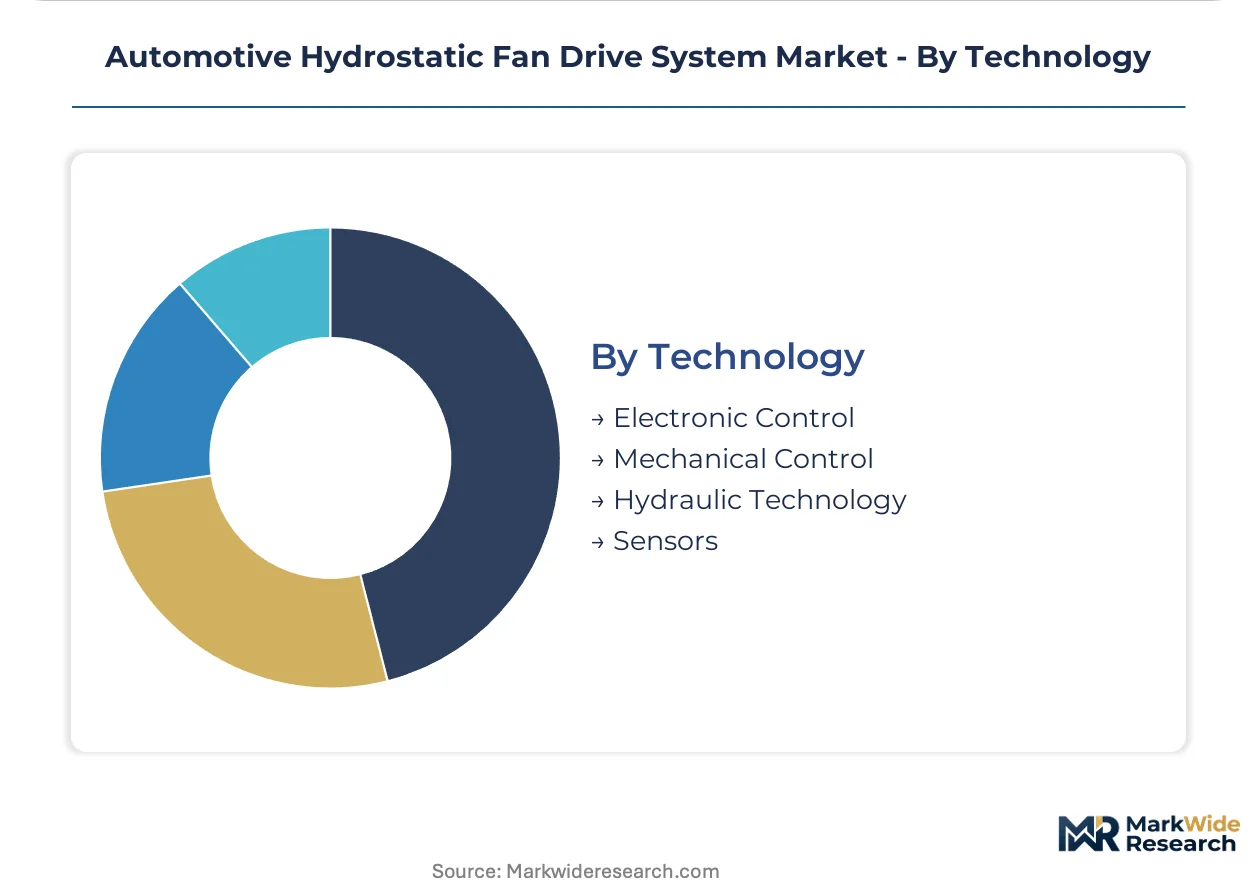
Technology:
Technology segmentation tracks control architecture evolution, with electronic systems displacing mechanical alternatives as CAN-bus integration becomes mandatory across premium commercial vehicle segments.
- Electronic Control:PWM-driven proportional valves and ECU-integrated algorithms enable predictive fan modulation based on engine load, ambient temperature, and route topography. European urban bus fleets specify these for battery thermal management in hybrid platforms.
- Mechanical Control:Spring-loaded pressure compensators and manual adjustment mechanisms retain cost advantage in agricultural and emerging market commercial applications.
- Hydraulic Technology:Core pump-motor circuit architectures span both control types, with closed-loop designs commanding efficiency premiums.
- Sensors:Temperature, pressure, and flow transducers enable closed-loop feedback for electronic control systems, with automotive-grade MEMS devices sourced from specialized tier-2 suppliers.
Mechanical control retains volume leadership in installed base. Electronic control is where supplier R&D investment concentrates as predictive thermal management algorithms differentiate service offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in precision hydraulic component manufacturing, connecting German casting foundries to Austrian and Czech machining centers.
Germany
Heavy-duty truck production at Mannheim and Stuttgart assembly plants drives specification intensity for variable displacement pump-motor combinations. Euro 7 emission standards from the European Commission mandate tighter engine temperature control bands, expanding sensor integration requirements. The Rhine-Ruhr corridor concentrates precision pump casting capacity, creating single-source vulnerability for European OEM qualification timelines.
United States
Class 8 vehicle manufacturing in Michigan and Ohio specifies hydrostatic drives for EPA Phase 3 greenhouse gas compliance. The EPA mandates CO2 reductions for heavy-duty trucks, pulling demand for electronically controlled fan architectures. The I-75 manufacturing belt anchors North American thermal management system integration.
India
Medium-duty truck production at Chennai and Pune hubs opens specification windows under Bharat Stage VI Phase 2 enforcement. The Central Pollution Control Board tightens emission thresholds, compelling engine cooling upgrades. The Delhi-Mumbai Industrial Corridor channels foreign component sourcing into domestic assembly operations.
China
Commercial vehicle electrification multiplies thermal management points across battery and motor cooling circuits. MIIT dual carbon goals accelerate hydraulic system displacement of mechanical alternatives in heavy truck platforms. The Yangtze River Delta clusters foundry and machining capacity for export-oriented pump production.
Japan
Off-highway equipment manufacturers specify load-sensing swashplate designs for intermittent cooling demands in construction machinery. METI energy efficiency standards reshape hydraulic component procurement for domestic excavator and wheel loader production. The Aichi Prefecture engineering corridor concentrates motion control system development.
Automotive Hydrostatic Fan Drive System Market Key Industry Players
Listed leaders compete with private specialists across integrated motion control portfolios, creating a tiered structure where scale-driven conglomerates anchor supply relationships while mid-cap fabricators capture niche specification windows. Three archetypes dominate: diversified industrial conglomerates with captive hydraulic divisions, pure-play motion control specialists, and regional component fabricators serving emerging market assemblers. Competitive moves concentrate on strategic partnerships for CAN-bus protocol integration and geographic expansion into Indian and Southeast Asian commercial vehicle corridors.
Within the diversified industrial tier, Parker Hannifin Corporation and Eaton Corporation exemplify scale-driven positioning across North American and European OEM channels. Danfoss A/S and Bosch Rexroth AG occupy specialist positions within European bus and coach thermal management, with the latter anchoring hydraulic system integration density across premium platforms. Bucher Hydraulics and JTEKT Corporation represent mid-cap fabricators with regional manufacturing footprints serving cost-optimized fleet specifications.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Danfoss A/S |
| Eaton Corporation |
| Bosch Rexroth AG |
| Bucher Hydraulics |
| JTEKT Corporation |
| Kawasaki Precision Machinery |
| HydraForce |
| Concentric AB |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day casting lead times for precision pump housings concentrate pricing power with Rhine-Ruhr corridor foundries serving German OEMs, while tier-1 integrators absorb margin compression through volume commitments to Indian and Brazilian assemblers.
Pricing Analysis
Volume-discount tiering structures stratify across premium sensor-integrated variable displacement modules, standard fixed displacement gear pumps, and economy mechanical control kits. Price differentiation hinges on Euro 7 certification grade and CAN-bus integration depth, with electronic control packages commanding substantial premia over mechanical alternatives. Cost compression in fixed displacement segments intensifies as synthetic ester hydraulic fluid feedstocks face biofuel competition. Fleet operators in refrigerated transport prove least price-sensitive due to cargo value at risk, while emerging market commercial assemblers prioritize unit economics above performance tiers.
Supply Chain Analysis
Strait of Hormuz transit vulnerability exposes European supply chains to Middle Eastern specialty steel alloy dependencies for high-pressure pump castings. Manufacturing gravity centers on Germany, China, and India, with the Yangtze River Delta feeding export-oriented machining capacity. Raw material sourcing draws from Chinese rare earth processing for permanent magnet motors, German precision steel for swashplate housings, and Indian aluminum foundries for cost-optimized gear pump bodies. Single-source vulnerability concentrates in Stuttgart-area CAN-bus controller firmware development. Distribution runs through captive OEM direct channels for premium modules and tier-1 cooling system integrators for standard replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive hydrostatic fan drive systems sit in early-cycle expansion as EPA Phase 3 and Euro 7 emission mandates force thermal management upgrades across heavy-duty vehicle production corridors.
For Market Incumbents: Compound engineering differentiation through predictive thermal management algorithm development and captive sensor integration partnerships that lock OEM specification cycles. Defend margin position by securing multi-year software update service tiers with Daimler Truck and Volvo Group before electric fan architectures mature. Backward integration into precision casting capacity along the Rhine-Ruhr corridor mitigates single-source supply risk. For New Entrants and Emerging Players: Lead with Bharat Stage VI Phase 2 compliance positioning at Chennai and Pune manufacturing hubs where incumbent presence remains thin. Target medium-duty truck cooling module retrofits through direct fleet contracts bypassing traditional tier-1 relationships. White-space exists in agricultural equipment mechanical control replacement cycles across Eastern European service networks. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because emission standards tighten faster than electric substitution timelines in heavy-duty segments. Acquisition candidates include mid-cap hydraulic specialists with embedded systems engineering benches in Stuttgart or Detroit engineering corridors. Watch battery-electric truck production ramp rates at Michigan and Ohio assembly plants as the inflection signal for hydraulic system relevance beyond the projection horizon.| Strategic Initiative | Industry Significance |
|---|---|
| CAN-Bus Protocol Integration Partnership | Enables predictive fan modulation algorithms for Euro 7-compliant German heavy-duty platforms. |
| Backward Integration into Precision Casting | Secures pump housing supply continuity against Rhine-Ruhr corridor single-source vulnerability. |
| Direct Fleet Contract Channel Development | Bypasses tier-1 integrators in US Midwest refrigerated transport segments with cargo value risk. |
| Indian Manufacturing Footprint Expansion | Captures Bharat Stage VI Phase 2 specification windows at Chennai and Pune truck hubs. |
| Software-Defined Service Tier Launch | Creates recurring revenue streams through predictive maintenance contracts with European bus fleets. |
Research Approach
A spread of perspectives from OEM platform engineers, tier-1 cooling module procurement leads, hydraulic component R&D directors, and aftermarket service network managers converged on the working assumptions. Primary fieldwork combined with secondary validation against EPA rulemaking dockets, EU F-Gas Regulation implementation guidance, UN ECE type approval databases, and commercial vehicle production registrations. Bottom-up unit economics triangulated against top-down emission mandate penetration curves.
Segmentation dimensions modeled span product type architecture, application thermal load intensity, end-user procurement channel, and control technology generation across the projection horizon. CAGRs derived from installed base replacement cycles, emission compliance phase-in schedules, and electrification substitution elasticity. Industry-specific inputs incorporated hydraulic fluid formulation constraints under REACH and sensor integration cost curves for automotive-grade MEMS devices.
Forecasts assume regulatory continuity in EPA Phase 3 and Euro 7 frameworks; material policy shifts would require re-modeling thermal management power budgets and supplier qualification timelines. Practitioners should keep alternative scenarios live as battery-electric truck production scale and high-voltage electric fan architecture cost parity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Power Modules Market
Powertrain
Automotive Drivetrain Market
Powertrain
Clutch Friction Plate Market
Powertrain
Brazil Automotive Market
Powertrain
Tuning Box Market
Powertrain
Japan Automotive Engine Oils Market
Powertrain
Automotive Paddle Shifter Market
Powertrain
Automotive Turbocharger Market
Powertrain
Automotive Half Shaft Market
Powertrain
Power Steering Filter Market
Powertrain
Fuel Injection Systems Market
Powertrain
Engine Support Bar Market
Powertrain
Automotive Transmission Repair Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Automotive Park Brake Lever (Handbrake) Market
Powertrain
South Africa Automotive Engine Oils Market