
 Power Steering Filter Market | 2026-2036
Power Steering Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Power Steering Filter Market Outlook
Asian component manufacturing clusters is realigning power steering filter supply chains toward modular platforms. Bosch leverages its filtration engineering depth across hydraulic and electromechanical steering architectures. Mann+Hummel anchors European aftermarket distribution through specialized cartridge and spin-on portfolios. Mahle competes on OEM integration, sustaining close development partnerships with vehicle manufacturers.
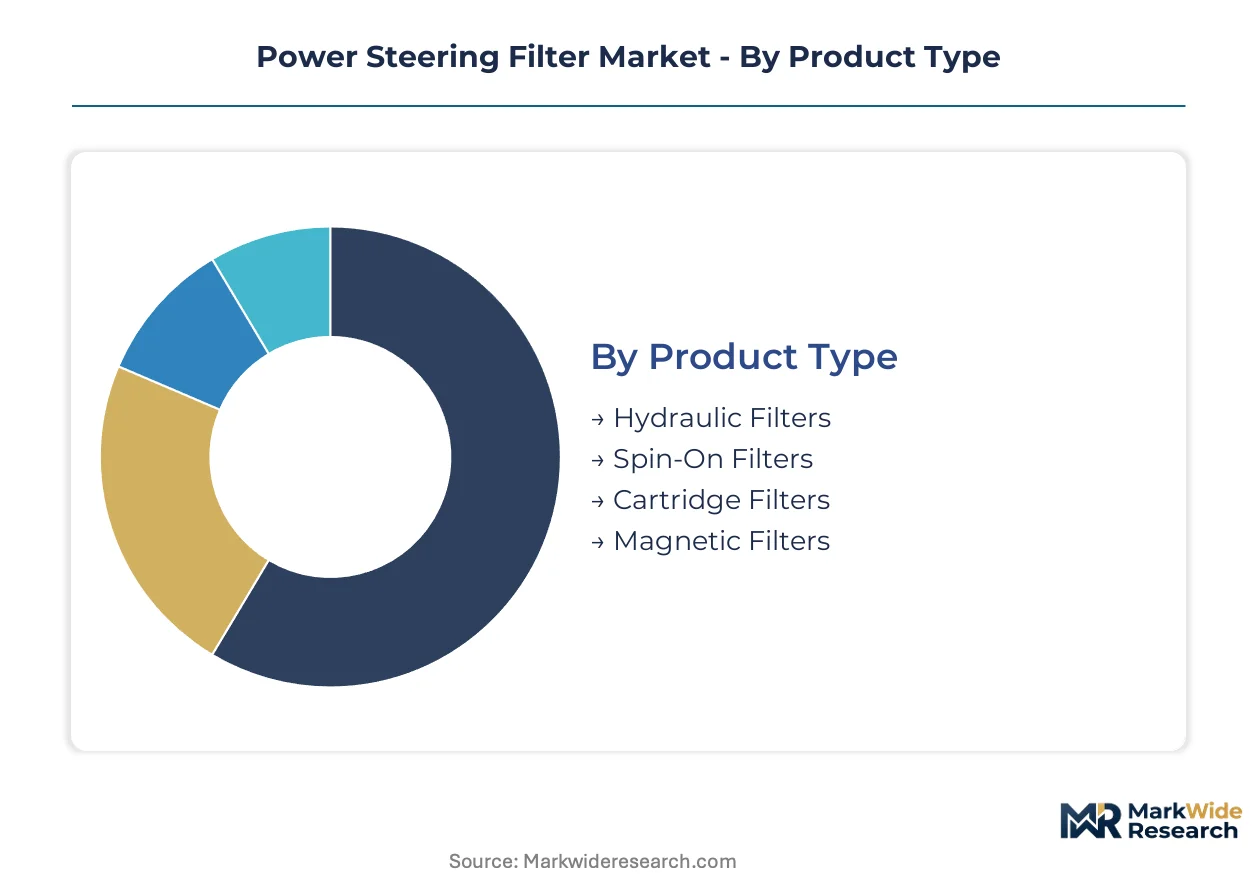
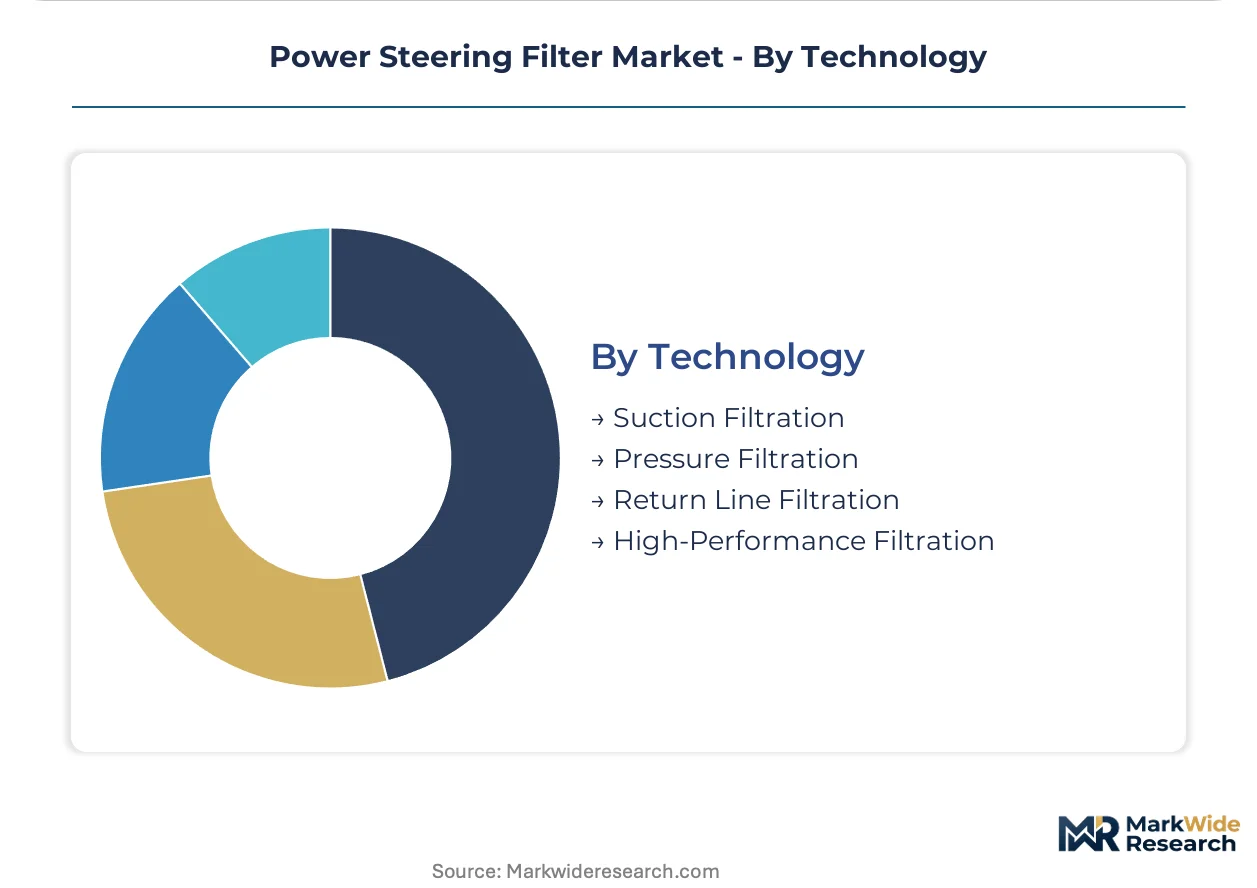
A power steering filter removes particulate contaminants from hydraulic fluid circulating through steering assist systems, typically employing cellulose or synthetic media rated between 10 and 25 microns to protect precision valves and pump assemblies from abrasive wear. Cartridge filters occupy the dominant share among product types due to compact packaging and service-friendly replacement protocols. Pressure filtration technology leads technology segmentation as hydraulic systems migrate to higher operating pressures, while magnetic filters represent the fastest-growing niche for capturing ferrous debris in heavy machinery applications.
EPA emissions durability standards and NHTSA steering system reliability mandates in the United States shape filter replacement intervals and material specifications, while EU REACH restrictions on hydraulic fluid additives indirectly influence compatible filtration media chemistries. China's MIIT fuel consumption regulations and GB standards for automotive components further constrain import and domestic product formulations. Stakeholders must track electromechanical steering penetration rates against residual hydraulic fleet maintenance demand to calibrate capacity allocation between legacy and emerging filtration platforms.
Market Dynamics
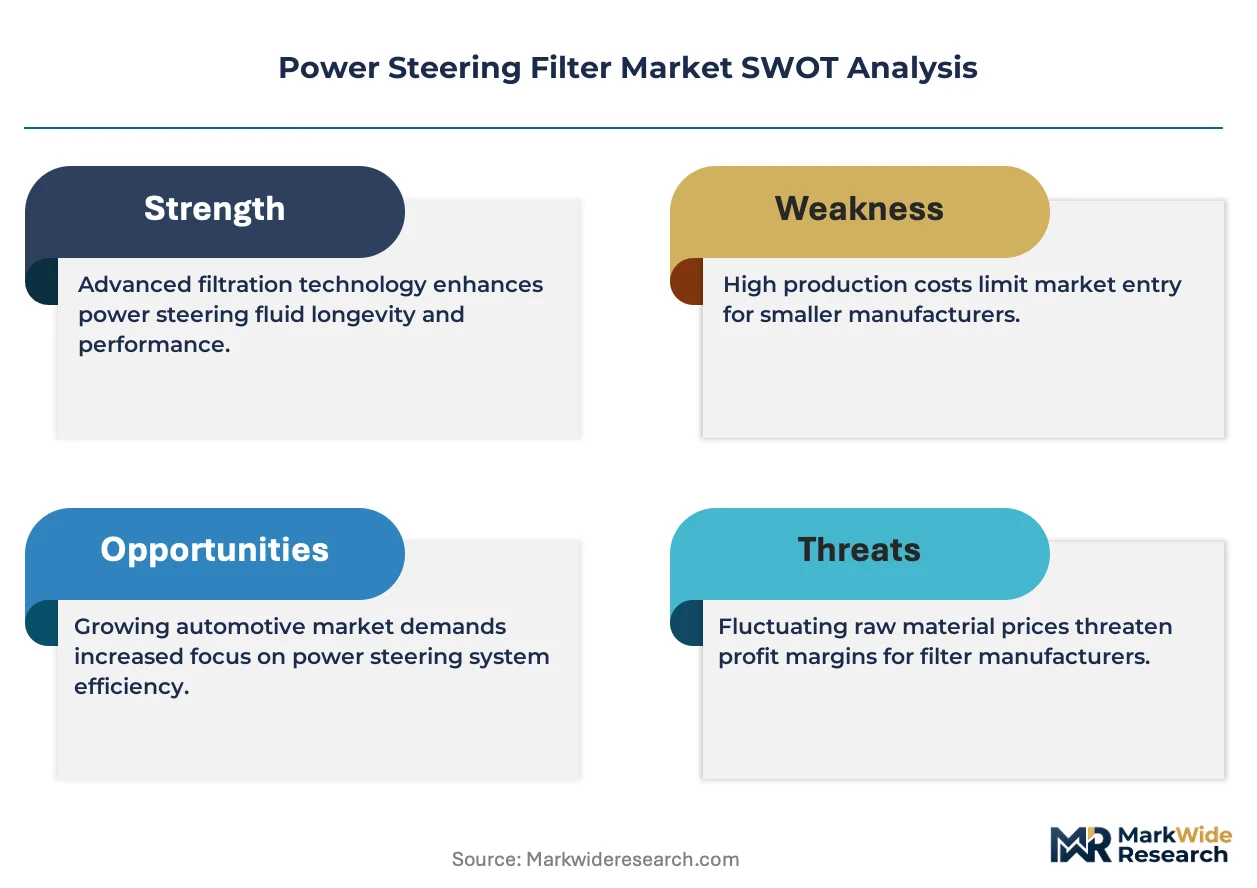
Electromechanical steering architectures are compressing hydraulic filter demand while simultaneously elevating contamination standards for residual hydraulic fleets in heavy commercial vehicles. This technological bifurcation forces suppliers to maintain dual competency across declining and emerging platforms.
Growth Catalysts
- EPA emissions durability standards:Extended vehicle lifecycles under NHTSA reliability mandates lengthen filter replacement intervals, expanding aftermarket service revenue for hydraulic system maintenance.
- Heavy machinery ferrous debris capture:Magnetic filtration technology addresses abrasive wear in mining and construction equipment operating in high-contaminant environments across Australia's Pilbara region.
- Cellulose-to-synthetic media migration:Higher operating pressures in modern hydraulic systems demand advanced synthetic filtration media rated at 10-micron precision thresholds.
Market Restraints
- Electromechanical substitution:Rack-assist electric power steering eliminates hydraulic circuits entirely, removing filter demand from passenger vehicle platforms in premium German segments.
- Cellulose pulp supply concentration:Filter media raw material sourcing clusters in Southeast Asian pulp processing facilities, exposing cost structures to regional logistics volatility.
- REACH additive restrictions:EU chemical regulations on hydraulic fluid formulations constrain compatible filtration media chemistries, extending R&D validation timelines.
Strategic Opportunities
- India commercial vehicle aftermarket:Underpenetrated service networks in tier-two and tier-three cities create white space for cartridge filter distribution partnerships.
- Electromechanical-hybrid architectures:Convergence of hydraulic backup systems with primary electric steering generates demand for compact, high-pressure filtration modules.
- MIIT fuel consumption regulations:China's efficiency mandates incentivize precision hydraulic component protection, sustaining OEM filter specification upgrades.
Industry Challenges
- Electrohydraulic system integration:Legacy hydraulic filter suppliers face capability gaps in electronic control unit compatibility and sensor-integrated filtration monitoring.
- ISO 4406 cleanliness code certification:Extended validation timelines for new media formulations delay product launches amid compressed OEM development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Steering Filter Market |
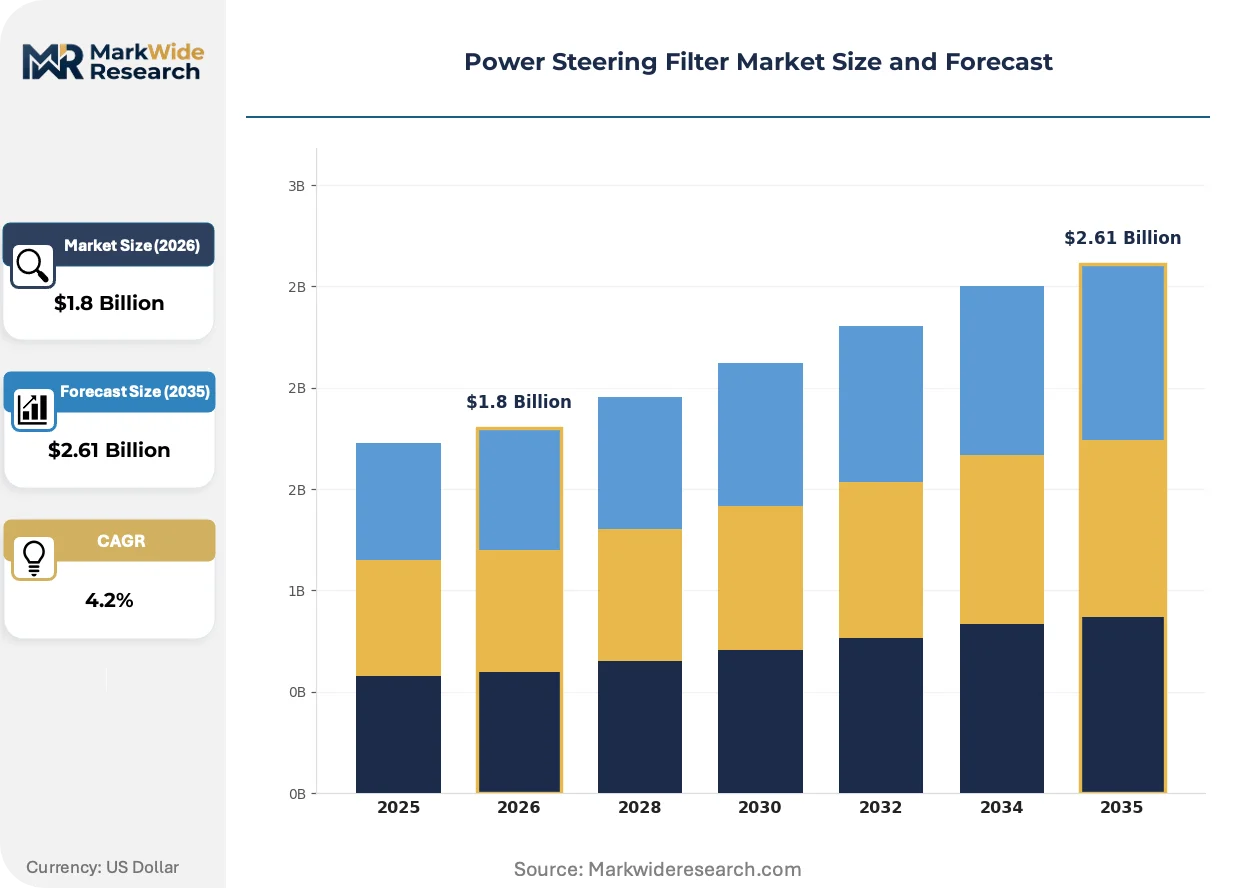
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Filters, Spin-On Filters, Cartridge Filters, Magnetic Filters Application: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Performance Vehicles End User: OEMs, Aftermarket Providers, Vehicle Manufacturers, Repair Shops Technology: Suction Filtration, Pressure Filtration, Return Line Filtration, High-Performance Filtration |
| Companies Covered | Bosch, JTEKT, Nexteer, NSK, Showa, Mobis, Thyssenkrupp, Mann+Hummel, Mahle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Steering Filter Market Strategic Shifts
Synthetic filtration media advances and electromechanical steering penetration are restructuring product development priorities across hydraulic component suppliers. Three distinct shifts are reshaping competitive positioning in power steering filtration.
Synthetic cellulose composite media is overtaking traditional pure cellulose constructions in high-pressure hydraulic circuits. Commercial vehicle OEMs in North America specify these materials for 4000+ PSI operating environments. The technology is overtaking conventional offerings by enabling extended service intervals while maintaining 10-micron absolute ratings under thermal stress.
EU REACH restrictions on hydraulic fluid additive packages are forcing reformulation of compatible filtration media chemistries. Industrial consequences include extended supplier qualification timelines and segmented product portfolios across regulatory zones. Heavy machinery applications in Germany's precision manufacturing corridor face the most acute compliance pressure, driving captive testing investments.
Fleet operators are unbundling after-sales service contracts from initial equipment procurement, creating direct procurement relationships with filter specialists. Traditional distribution through hydraulic system integrators is fragmenting as large mining and logistics fleets negotiate volume agreements. This pattern is most visible in Australia's resource extraction sector, where BHP and Rio Tinto procurement teams source filtration directly.
Power Steering Filter Market Segmentation
Power steering filter segmentation reflects divergent capital requirements across hydraulic and electromechanical architectures. Suppliers must calibrate manufacturing investments against residual hydraulic fleet maintenance demand and emerging electromechanical platform specifications.
Product Type:
Capital intensity varies sharply across filter construction methods, with cartridge and magnetic formats demanding specialized tooling investments that spin-on alternatives avoid.
- Cartridge Filters:Compact cylindrical elements with replaceable media cores dominate passenger vehicle fitments. German precision manufacturing corridors and China's tier-one supplier zones concentrate demand amid stricter contamination control protocols.
- Magnetic Filters:Ferrous debris capture systems employ permanent magnet arrays alongside conventional media. Australia's Pilbara mining region drives specification upgrades as heavy machinery operators unbundle service contracts from equipment procurement.
- Hydraulic Filters:Full-flow and bypass configurations protect pump and valve assemblies in conventional power steering circuits.
- Spin-On Filters:Self-contained canister designs simplify field replacement in commercial vehicle aftermarket channels.
Most installed capacity flows through cartridge formats. Expansion is steepest in magnetic filtration for high-contaminant operating environments.
Application:
Customer procurement patterns segment sharply between OEM-integrated specifications and aftermarket replacement demand across vehicle categories.
- Commercial Vehicles:Heavy-duty hydraulic systems operating at 4000+ PSI require synthetic media rated at 10-micron absolute thresholds. North American fleet operators are extending replacement intervals under EPA emissions durability standards, expanding aftermarket service revenue.
- Heavy Machinery:Mining and construction equipment in Australia's resource extraction sector generates direct procurement relationships with filter specialists. BHP and Rio Tinto procurement teams negotiate volume agreements outside traditional hydraulic system integrator channels.
- Passenger Vehicles:Rack-assist electric power steering eliminates hydraulic circuits entirely in premium German segments, compressing filter demand.
- Performance Vehicles:High-steering-feedback applications sustain specialized hydraulic system specifications.
Commercial vehicle applications command the highest unit values. Heavy machinery is gaining share fastest as fleet operators professionalize filtration procurement.
End User:
Channel structure determines margin capture, with OEM integration requiring validation investments that aftermarket distribution avoids.
- OEMs:Direct vehicle manufacturer partnerships demand ISO 4406 cleanliness code certification and extended validation timelines for new media formulations. Mahle sustains close development relationships with vehicle manufacturers to secure integrated specifications.
- Aftermarket Providers:Mann+Hummel anchors European distribution through specialized cartridge and spin-on portfolios, capturing replacement demand from expanding passenger vehicle fleets.
- Vehicle Manufacturers:Assembly line procurement specifies contamination control protocols for new vehicle production.
- Repair Shops:Service bay replacement demand concentrates in India's tier-two and tier-three cities, creating white space for cartridge filter distribution partnerships.
OEM relationships lock in the longest contract durations. Aftermarket channels are expanding most quickly in underpenetrated service networks.
Technology:
Operating pressure thresholds and filtration precision requirements segment manufacturing capabilities across hydraulic circuit positions.
- Pressure Filtration:Located downstream of hydraulic pumps, these systems manage highest operating stresses in modern circuits. Synthetic cellulose composite media is overtaking traditional pure cellulose constructions in 4000+ PSI environments specified by North American commercial vehicle OEMs.
- High-Performance Filtration:Absolute-rated media at 10-micron thresholds protects precision valves under thermal stress. EU REACH restrictions on hydraulic fluid additive packages force reformulation of compatible media chemistries, extending supplier qualification timelines.
- Suction Filtration:Inlet-side protection prevents pump cavitation damage in conventional hydraulic architectures.
- Return Line Filtration:Circuit-exit positioning captures wear debris before fluid re-enters reservoirs.
Pressure filtration commands the most advanced manufacturing investments. High-performance specifications are climbing the fastest amid regulatory pressure on hydraulic fluid formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing corridor generates stricter contamination control specifications than China's tier-one supplier zones, though both anchor continental demand patterns for hydraulic filtration components.
United States
EPA emissions durability standards and NHTSA steering system reliability mandates extend vehicle lifecycles and expand aftermarket service revenue. Heavy-duty hydraulic systems operating at 4000+ PSI dominate commercial vehicle specifications. Detroit's automotive supplier ecosystem concentrates OEM filter integration partnerships.
Germany
Rack-assist electric power steering eliminates hydraulic circuits in premium passenger segments, compressing traditional filter demand. EU REACH restrictions on hydraulic fluid additives force reformulation of compatible filtration media chemistries. Stuttgart's precision manufacturing corridor sustains captive testing investments for heavy machinery compliance.
China
MIIT fuel consumption regulations and GB standards for automotive components constrain import and domestic product formulations. Tier-one supplier zones in the Yangtze River Delta realign supply chains toward modular platforms. Shanghai's component manufacturing clusters drive specification upgrades for precision hydraulic component protection.
Australia
Mining and construction equipment operators in the Pilbara region unbundle after-sales service contracts from initial equipment procurement. BHP and Rio Tinto procurement teams negotiate direct volume agreements with filter specialists. Perth's resource extraction sector procurement offices professionalize filtration sourcing outside traditional integrator channels.
India
Underpenetrated service networks in tier-two and tier-three cities create white space for cartridge filter distribution partnerships. Commercial vehicle aftermarket expansion outpaces OEM integration timelines. Pune and Chennai automotive corridors concentrate domestic manufacturing capacity for hydraulic system components.
Power Steering Filter Market Competitive Environment
German producers anchor one tier; Japanese specialists hold another through distinct hydraulic and electromechanical steering architectures. The supplier base stratifies across consolidated filtration engineering groups and component-integrated system houses. Three archetypes dominate: diversified automotive suppliers with filtration depth, pure-play filter specialists with aftermarket scale, and steering system integrators with captive filtration units. Competitive moves concentrate on portfolio diversification across hydraulic and electromechanical platforms, plus geographic expansion into underpenetrated aftermarket channels.
Within the diversified supplier tier, Bosch and JTEKT occupy positions spanning hydraulic and electromechanical steering architectures. Mann+Hummel exemplifies the pure-play filtration specialist archetype with European aftermarket distribution scale. Mahle represents the component-integrated approach through close OEM development partnerships. These three anchors illustrate how competitive positioning splits between system breadth, category depth, and manufacturing integration strategies.
| Leading Market Players |
|---|
| Bosch |
| JTEKT |
| Nexteer |
| NSK |
| Showa |
| Mobis |
| Thyssenkrupp |
| Mann+Hummel |
| Mahle |
| Others |
Value Chain & Pricing Dynamics
Synthetic cellulose composite media migration is simultaneously elevating manufacturing cost structures and concentrating production capability among suppliers with advanced material science competencies. This technology shift tightens margin capture for filter specialists while compressing price floors for conventional cellulose offerings across North American and European procurement channels.
Pricing Analysis
Capacity additions in China's Yangtze River Delta supplier zones are reshaping price floors for cartridge filter formats across Asia-Pacific aftermarket channels. Three-tier pricing structure across premium synthetic media, standard cellulose composites, and economy pure-cellulose levels segments buyer procurement patterns. OEM integration contracts command 15-25% premiums over aftermarket spot pricing due to ISO 4406 cleanliness code certification requirements. Commercial vehicle fleet operators in North America exhibit lowest price sensitivity given extended replacement interval economics, while India's tier-two repair shops face acute cost compression from unorganized spare part competition.
Supply Chain Analysis
Reverse-logistics flows for remanufactured hydraulic pump cores and refurbished filter housings are anchoring secondary material recovery networks across Germany's precision manufacturing corridor. Raw material sourcing draws from Southeast Asian cellulose pulp processing facilities, Chinese synthetic fiber production clusters, and Australian rare-earth magnet suppliers for ferrous debris capture systems. Single-source vulnerability concentrates in specialized 10-micron rated media formulations qualified under EU REACH additive restrictions. Distribution runs through hydraulic system integrators for OEM channels, while direct procurement relationships with mining fleets in Australia's Pilbara region fragment traditional aftermarket structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power steering filter manufacturing presents a geographic-arbitrage opportunity between Germany's REACH-constrained formulation costs and China's MIIT-regulated domestic production incentives. Suppliers can capture margin spreads by positioning synthetic media capacity in regulatory-friendly jurisdictions while serving European compliance-driven demand.
For Market Incumbents: Acquire specialized magnetic filtration engineering capabilities to address Australia's mining sector procurement unbundling. Electromechanical steering substitution threatens 30-40% of passenger vehicle hydraulic filter volumes by the analysis window's close. Backward integration into cellulose pulp processing insulates margin structures from Southeast Asian logistics volatility. For New Entrants and Emerging Players: Begin with cartridge filter distribution partnerships in India's tier-two and tier-three commercial vehicle service networks. White space concentrates where organized aftermarket penetration remains below 35% and OEM-authorized service intervals create replacement demand backlogs. Direct fleet contracting models bypass traditional hydraulic system integrator markups. For Investors and Strategic Acquirers: Roll-up economics work for regional aftermarket distributors because fleet operator procurement professionalization fragments legacy channel structures. Five-to-ten year viability hinges on dual-platform competency across residual hydraulic maintenance and electromechanical steering sensor integration. Monitor electromechanical-hybrid architecture penetration rates as the critical inflection signal for legacy filtration capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Media Capacity Expansion | 10-micron absolute rating capability secures North American commercial vehicle OEM specifications at 4000+ PSI thresholds. |
| Magnetic Filtration Technology Licensing | Permanent magnet array designs capture BHP and Rio Tinto direct procurement volumes in Australia's Pilbara region. |
| Electromechanical Platform Partnership | Sensor-integrated filtration monitoring addresses capability gaps in electronic control unit compatibility. |
| India Distribution Channel Acquisition | Tier-two and tier-three city coverage exploits underpenetrated commercial vehicle aftermarket white space. |
| REACH-Compliant Formulation Investment | Captive testing facilities in Germany's precision manufacturing corridor accelerate EU hydraulic fluid additive qualification timelines. |
Study Parameters
Multiple input streams — procurement director interviews at Tier 1 steering system suppliers, production data from vehicle registration databases, and customs records for cellulose pulp and synthetic fiber trade flows — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged aftermarket distribution managers, OEM platform engineers, and fleet maintenance directors across Germany, China, India, and Australia. Secondary validation drew from EPA emissions durability filings, MIIT fuel consumption compliance disclosures, EU ECHA REACH restriction updates, and ISO 4406 cleanliness code certification registries.
Data-stream reconciliation across product type, application, technology, and regional production cluster dimensions generated volume and value outputs across the projection horizon. CAGRs were derived from segment-level growth rate differentials weighted by installed base dynamics and replacement interval economics. Forecast inputs incorporated electromechanical steering penetration trajectories, hydraulic fleet residual maintenance demand curves, and regulatory compliance timeline accelerations.
Several conditions sit outside the modeled scope, including abrupt electromechanical architecture substitution rates exceeding baseline scenarios, cellulose pulp supply disruptions from Southeast Asian logistics constraints, and REACH additive restriction scope expansions. Forecasts reflect base-case assumptions regarding OEM development cycle durations and aftermarket channel consolidation patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Powertrain Domain Control Unit Platforms Market
Powertrain
Mechanical Reciprocating Engine Market
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
Clutch Market
Powertrain
South America Automotive Market
Powertrain
Global Automotive Engine and Engine Mounts Market
Powertrain
North America Torque Vectoring Market
Powertrain
Automotive Engine Air Filter Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Automotive Timing Chain and Belt Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Iridium Spark Plug Market
Powertrain
Automotive Powertrain Components Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Global Driveline Market