
 Automotive Transmission Repair Market | 2026-2036
Automotive Transmission Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Transmission Repair Market Analysis
Multi-sourcing of transmission components is restructuring how independent workshops and dealership networks secure parts. Schaeffler Group leverages its integrated bearing and clutch manufacturing to supply rebuild kits directly to service channels. AAMCO Transmissions, Inc. anchors North American franchise coverage with standardized diagnostic protocols. ZF Friedrichshafen AG competes through remanufactured unit availability and technical training programs.
Automotive transmission repair encompasses the restoration, replacement, and calibration of gearboxes, torque converters, and control modules to restore powertrain efficiency and shift quality. The discipline addresses friction material wear, solenoid failure, and fluid degradation across automatic, manual, CVT, and dual-clutch architectures. Rebuild services capture the largest margin pool as shops perform in-house overhauls rather than sourcing complete remanufactured units. Diagnostic services represent the fastest-expanding segment, driven by electronic control complexity and fleet telematics integration that flags failures before drivability loss.
EPA tailpipe standards and NHTSA safety recalls shape repair frequency by mandating emission-related component longevity. The EU F-Gas Regulation and REACH chemical restrictions limit transmission fluid formulations and sealing materials available in Europe. Stakeholders must monitor electrification transition timelines and hybrid transmission proliferation to calibrate service capacity investments against internal combustion decline curves.
Market Dynamics
Electrification transition timelines are compressing service capacity planning cycles as hybrid transmission architectures proliferate alongside declining pure internal combustion volumes. Fleet telematics integration now flags transmission failures before drivability loss, shifting repair demand from catastrophic failure toward predictive intervention.
Growth Catalysts
- EPA emissions enforcement:Tightened inspection protocols for commercial fleets in the United States mandate preventive maintenance contracts that sustain aftermarket service volumes.
- Extended vehicle ownership cycles:Aging vehicle parc in North American and European markets generates sustained demand for transmission rebuild services rather than new vehicle replacement.
- Electronic control complexity:Advanced mechatronic systems in dual-clutch and CVT architectures drive diagnostic service expansion as independent workshops invest in scan tool capabilities.
Market Restraints
- Specialized tooling capex:Transmission rebuilds require torque converters, valve body fixtures, and clutch pack presses that lock capital in equipment rather than inventory turnover.
- Fluid formulation restrictions:EU F-Gas Regulation and REACH chemical limits constrain transmission fluid and sealing material availability in European service channels.
- Remanufactured unit substitution:ZF Friedrichshafen AG and OEM captive reman programs capture margin that would otherwise flow to in-house rebuild operations.
Strategic Opportunities
- Telematics-integrated service models:Fleet operators in the United States are unbundling transmission maintenance from full-service leases, creating direct workshop relationships.
- Hybrid transmission specialization:Power-split and P2 hybrid architectures require distinct fluid, cooling, and clutch service protocols that generalist shops cannot perform.
- Technical training certification:AAMCO and Schaeffler Group training programs create captive technician pipelines that anchor franchise network expansion.
Industry Challenges
- Mechatronics skill scarcity:Technicians trained on mechanical rebuilds lack proficiency in solenoid characterization, TCM flashing, and CAN bus diagnostics required for modern transmissions.
- Inventory velocity compression:Proliferating transmission variants reduce rebuild kit commonality, forcing shops to hold broader SKU ranges with slower turns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Transmission Repair Market |
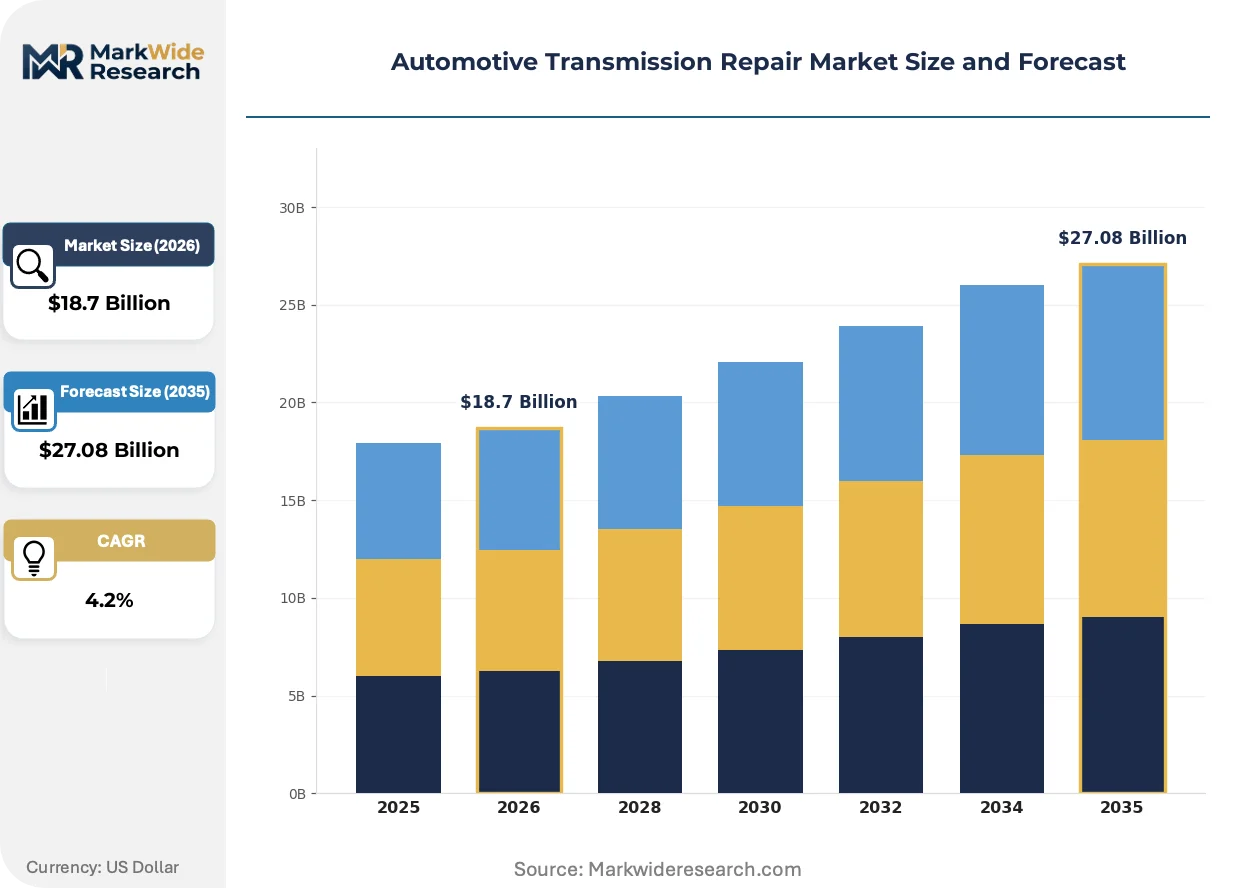
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Rebuild, Replacement, Maintenance, Diagnostic Transmission Type: Automatic, Manual, CVT, Dual-Clutch Vehicle Type: Passenger Cars, Light Trucks, Heavy-Duty Trucks, SUVs End User: Individual Owners, Fleet Operators, Workshops, Dealerships |
| Companies Covered | Lee Myles Autocare & Transmission, Schaeffler Group, AAMCO Transmissions, Inc., Allison Transmission Holdings Inc., ZF Friedrichshafen AG, Monro, Inc., Cottman Transmission and Total Auto Care, BorgWarner Inc., Mister Transmission, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Transmission Repair Market Emerging Trajectories
Diagnostic capability is becoming the primary competitive differentiator as electronic control modules govern shift quality and failure prediction. Shops that integrate fleet telematics data streams capture repair appointments before competitors see the vehicle.
Condition-based monitoring systems are unifying vibration analysis, fluid degradation sensors, and thermal load tracking into single dashboard interfaces. Large fleet operators in the United States deploy these systems across Class 3-8 vehicles to schedule transmission service during planned downtime. This unifying sensor architecture compresses the window between fault detection and workshop arrival, reducing catastrophic failure rates and warranty exposure.
EPA tailpipe standards and NHTSA safety recall protocols now mandate emission-related component longevity that extends transmission service intervals. Manufacturers must certify friction materials and solenoid durability under broader temperature and load cycles. Heavy-duty fleet segments in California face the strictest enforcement, driving adoption of synthetic fluid formulations and external cooler installations.
Service contract unbundling is fragmenting traditional fleet maintenance relationships. National leasing companies now separate powertrain coverage from bumper-to-bumper agreements, allowing transmission specialists to bid directly on multi-year preventive programs. This shift is most visible in the United States where independent workshop networks compete against dealership service lanes on flat-rate pricing transparency.
Automotive Transmission Repair Market Segmentation
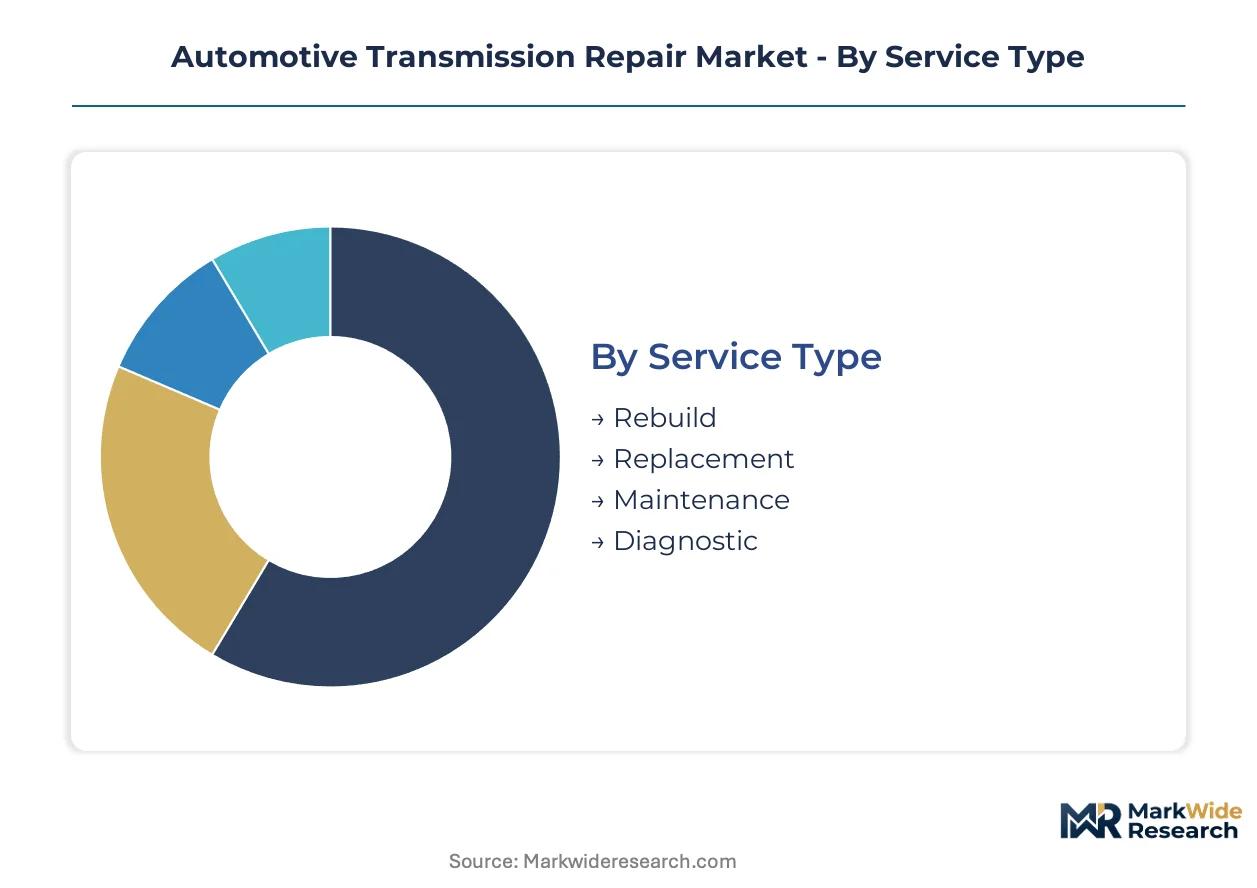
Transmission repair demand fragments across service intensity tiers and vehicle electrification readiness. Segment boundaries blur as hybrid architectures force workshops to cross-train across mechanical and electronic disciplines. Understanding where margin pools concentrate versus where volume flows shapes capital allocation for tooling and technician certification.
Service Type:
Volume concentrates in routine maintenance contracts while premium margin capture shifts toward diagnostic complexity.
- Rebuild:In-house overhaul of gearboxes, torque converters, and valve bodies captures the deepest margin pool as labor hours displace remanufactured unit markups. Demand clusters among independent workshops in the United States where extended vehicle ownership cycles sustain mechanical repair competency.
- Diagnostic:Electronic control module characterization, solenoid testing, and CAN bus fault isolation represent the steepest expansion trajectory as fleet telematics integration flags failures before drivability loss. California-based fleet operators deploy predictive algorithms that compress detection-to-repair windows.
- Replacement:Complete unit swaps dominate warranty channel workflows and catastrophic failure scenarios where downtime costs exceed rebuild labor economics.
- Maintenance:Fluid exchanges, filter replacements, and adaptive learning resets constitute the highest-frequency touchpoint but lowest per-transaction yield.
Mature deployment sits with Rebuild. Newer deployment is concentrated in Diagnostic.
Transmission Type:
Application urgency separates architectures facing obsolescence pressure from those gaining hybrid vehicle share.
- Automatic:Conventional torque converter designs retain the largest installed base across United States light trucks and SUVs, sustaining steady rebuild demand. EPA emissions enforcement on commercial fleets in California and Texas extends service intervals through synthetic fluid mandates.
- Dual-Clutch:Mechatronic complexity drives specialized diagnostic demand as wet and dry clutch variants proliferate in European performance segments. Germany's KBA type-approval requirements for clutch durability certification shape aftermarket parts availability.
- CVT:Belt-and-pulley systems face reliability concerns that accelerate replacement over rebuild economics in high-torque applications.
- Manual:Declining new-vehicle fitment compresses aftermarket volume to enthusiast and emerging-market segments where clutch replacement remains economically rational.
Volume gravity centers on Automatic. Capability investment is concentrating in Dual-Clutch.
Vehicle Type:
Payload duty cycle determines whether preventive maintenance contracts or catastrophic failure repair dominates revenue mix.
- Heavy-Duty Trucks:Class 3-8 commercial vehicles generate the most intensive service intervals under EPA emissions enforcement and fleet telematics monitoring. California Air Resources Board inspection protocols mandate transmission health documentation for diesel particulate filter compliance.
- Light Trucks:North American work truck segments sustain rebuild demand through extended ownership cycles and towing load stress on automatic transmissions. Texas and Florida fleet densities support independent workshop network expansion.
- SUVs:All-wheel-drive transfer case integration complicates service scope as multi-clutch torque vectoring systems require specialized calibration equipment.
- Passenger Cars:Sedan and hatchback transmission repair volume compresses as electrification transition timelines accelerate powertrain replacement over overhaul.
Contract penetration is deepest in Heavy-Duty Trucks. Discretionary spend concentrates in Light Trucks.
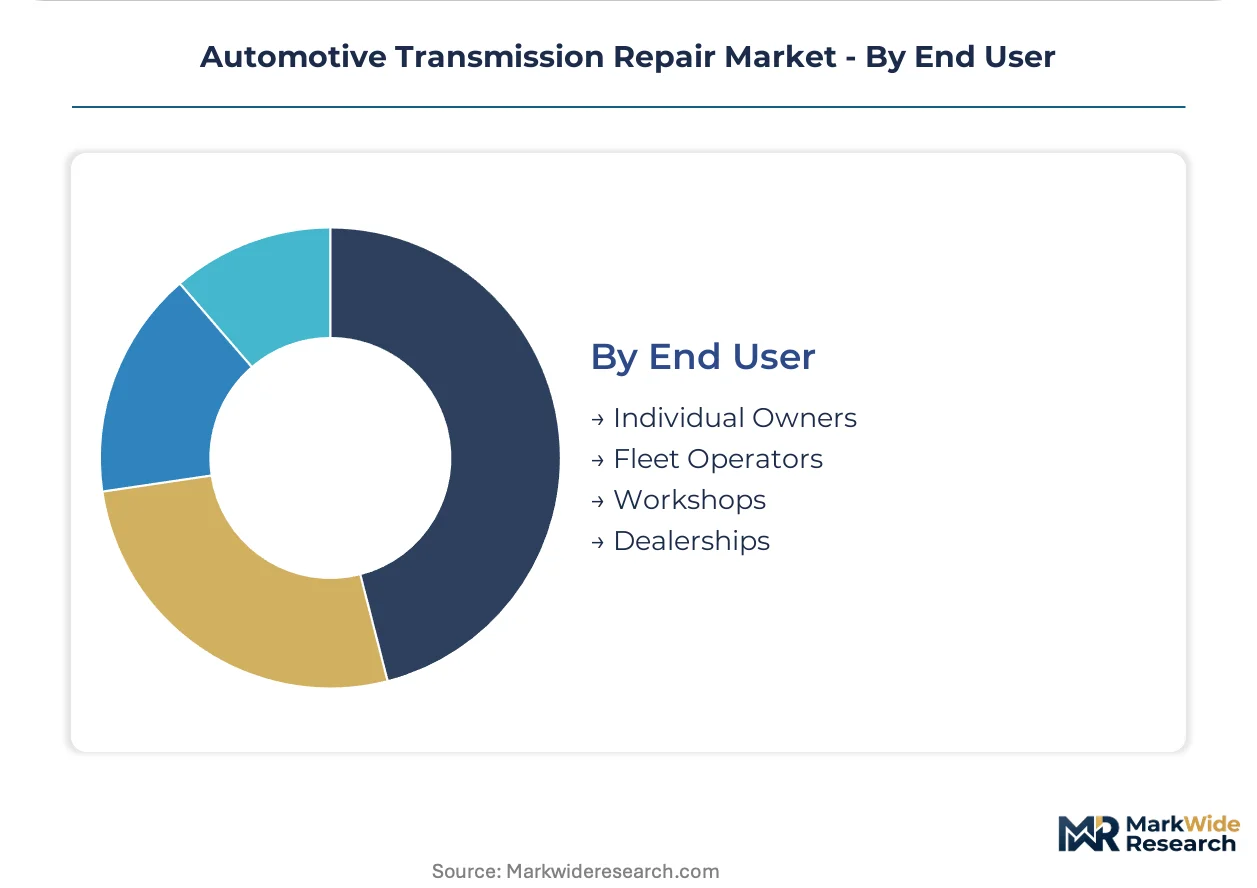
End User:
Procurement sophistication separates price-transparent fleet bidding from relationship-driven individual service retention.
- Fleet Operators:National leasing companies and logistics providers unbundle powertrain coverage from full-service agreements, enabling direct transmission specialist contracts. United States-based operators in Illinois and Ohio pilot condition-based maintenance algorithms that schedule service during planned downtime.
- Workshops:Independent service channels invest in scan tool capabilities and technical training certifications to capture diagnostic-intensive repairs escaping dealership pricing premiums.
- Dealerships:OEM captive service lanes retain warranty work and software-dependent repairs requiring proprietary flashing tools and technical service bulletin access.
- Individual Owners:Retail demand concentrates in catastrophic failure scenarios where towing costs and rental car expenses compress shop selection timelines.
Price discipline is tightest with Fleet Operators. Margin protection is strongest with Dealerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel production corridors in Pennsylvania and Ohio supply the torque converter stampings and clutch plate substrates that anchor North American rebuild capacity. Transmission fluid formulation hubs along the Gulf Coast process base stocks into synthetic ATF blends.
United States
Extended vehicle ownership cycles sustain independent workshop density across Texas and Florida, where light truck towing stress accelerates automatic transmission wear. EPA emissions enforcement through CARB protocols mandates transmission health documentation for heavy-duty diesel compliance. Chicago-based fleet operators pilot condition-based maintenance algorithms that compress detection-to-repair windows.
Germany
Dual-clutch mechatronic complexity drives specialized diagnostic demand among KBA-regulated technical services. REACH chemical restrictions constrain transmission fluid formulations available to independent workshops. Stuttgart-area component suppliers integrate bearing and clutch manufacturing into direct service channel distribution.
China
Rapid vehicle parc expansion generates aftermarket volume concentrated in Yangtze River Delta service clusters. MIIT fuel economy standards accelerate dual-clutch and CVT adoption that requires specialized tooling investment. Shanghai-based workshop networks invest in scan tool capabilities for electronic control module characterization.
Japan
Hybrid transmission proliferation creates distinct service protocols for power-split architectures. METI carbon neutrality roadmaps compress internal combustion service capacity planning cycles. Nagoya-area technical training centers cross-technician mechanical and electronic disciplines.
India
Commercial vehicle density in Maharashtra and Gujarat sustains preventive maintenance contract growth. BIS certification requirements for automotive fluids shape aftermarket parts availability. Chennai-based independent workshops capture diagnostic-intensive repairs escaping dealership pricing premiums.
Automotive Transmission Repair Market Vendor Landscape
Technical training certification dominates the current landscape as franchise networks anchor technician pipelines. The vendor base organizes into three tiers: integrated component manufacturers supplying rebuild kits directly, national franchise operators standardizing diagnostic protocols, and independent workshop chains investing in scan tool capabilities. Consolidation pressure concentrates among mid-scale operators unable to fund mechatronics tooling. Geographic expansion and portfolio diversification represent the primary competitive vectors.
Within the integrated manufacturing tier, Schaeffler Group and ZF Friedrichshafen AG exemplify upstream control strategies that bypass traditional distribution. AAMCO Transmissions, Inc. occupies a position representing standardized franchise coverage with captive technical training infrastructure. These three entities collectively illustrate how capital intensity and certification programs structure competitive positioning across service channel archetypes.
| Leading Market Players |
|---|
| Lee Myles Autocare & Transmission |
| Schaeffler Group |
| AAMCO Transmissions, Inc. |
| Allison Transmission Holdings Inc. |
| ZF Friedrichshafen AG |
| Monro, Inc. |
| Cottman Transmission and Total Auto Care |
| BorgWarner Inc. |
| Mister Transmission |
| Others |
Supply Flow & Price Mechanics
Synthetic ATF base stock costs cascade through three downstream pricing tiers as Gulf Coast formulation hubs supply rebuild kit manufacturers, franchise networks, and independent workshops with differentiated fluid specifications. EPA emissions enforcement in California and Texas mandates premium synthetic grades for heavy-duty fleets, compressing margin on economy-tier maintenance contracts while protecting rebuild service premiums.
Pricing Analysis
Warranty bundling separates OEM captive service lanes from unbundled independent workshop bids as fleet operators negotiate direct powertrain maintenance contracts outside full-service lease agreements. Three-tier pricing structure across premium diagnostic-certified, standard rebuild-capable, and economy fluid-exchange tiers reflects technician certification investment and scan tool capability. Cost compression in the economy tier is intensifying because remanufactured unit substitution from ZF Friedrichshafen AG and captive reman programs erodes in-house rebuild economics. Fleet operators exhibit tightest price discipline through competitive bidding transparency, while individual owners facing catastrophic failure demonstrate lowest sensitivity due to towing and rental car cost compression.
Supply Chain Analysis
Dual-sourcing requirements from national fleet operators mandate qualified suppliers across torque converter stampings from Pennsylvania steel corridors, clutch plate substrates from Ohio manufacturing clusters, and mechatronic solenoids from German KBA-certified component suppliers. Rebuild kit production draws from specialized bearing forgings, friction material laminates, and electronic control modules. Single-source vulnerability concentrates in proprietary TCM flashing equipment and OEM-specific diagnostic protocols. Distribution runs through direct manufacturer-to-workshop channels for integrated suppliers like Schaeffler Group, while independent distributors serve fragmented shop networks with broader SKU coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics technician scarcity props rebuild service pricing as capacity bottlenecks in solenoid characterization and CAN bus diagnostics limit shop throughput against rising electronic control complexity.
For Market Incumbents: Deepen captive technician pipeline investments through AAMCO and Schaeffler Group certification programs to defend against independent workshop scan tool capability convergence. Anchor franchise network density in Texas and Florida light truck corridors where extended ownership cycles sustain automatic transmission rebuild demand. Prioritize hybrid transmission specialization before power-split architecture service protocols commoditize. For New Entrants and Emerging Players: Fleet telematics integration partners represent the most penetrable channel as national leasing companies unbundle powertrain coverage from full-service agreements. Target direct preventive maintenance contracts with Illinois and Ohio-based operators piloting condition-based maintenance algorithms. Pursue technical training certification as the primary go-to-market anchor to secure workshop network admission. For Investors and Strategic Acquirers: CARB enforcement expansion is the leading indicator that California heavy-duty fleet compliance spending will sustain transmission health documentation mandates across adjacent states. Long-term viability favors vertically integrated component suppliers with direct service channel bypass capabilities over mid-scale rebuild operators facing mechatronics tooling capex compression. Monitor EPA emissions protocol adoption velocity in Texas and Florida as the inflection signal for preventive maintenance contract penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Transmission Specialization | Power-split and P2 architecture certification captures margin pools escaping generalist shops. |
| Telematics Integration Partnership | Fleet operator data streams compress detection-to-repair windows before competitors access vehicles. |
| Technical Training Certification | Schaeffler Group and AAMCO programs create captive technician pipelines anchoring network expansion. |
| Direct Service Channel Distribution | Rebuild kit manufacturers bypass traditional distribution to capture margin in independent workshops. |
| Condition-Based Maintenance Algorithms | Illinois and Ohio fleet pilots schedule service during planned downtime reducing catastrophic failure exposure. |
Methodological Framework
Multi-period observation of EPA enforcement protocol adoption, fleet telematics penetration rates, and hybrid vehicle production mix anchored the trend analysis, supplemented by interviews with aftermarket service directors, OEM platform engineers, Tier 1 supplier procurement leads, and independent workshop operators. Secondary validation incorporated NHTSA recall databases, CARB compliance filings, IHS Markit vehicle registration data, and SEC disclosures from transmission component manufacturers. Bottom-up service volume estimates triangulated against top-down vehicle parc aging projections.
Input-output matrices mapped transmission type proliferation, service intensity tier migration, and electrification transition timelines across the projection horizon. Segmentation dimensions modeled included service type, transmission architecture, vehicle payload class, and end-user procurement sophistication. CAGRs derived from logistic diffusion curves for electronic control complexity and fleet telematics integration. Industry-specific forecast inputs encompassed EPA emissions enforcement stringency indices and hybrid transmission service protocol adoption rates.
Caveats apply where electrification transition acceleration, REACH chemical restriction expansion, or mechatronics technician training capacity constraints could materially shift the outlook. Deviation in EPA emissions protocol adoption velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Automotive Drive Shaft Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
Turbine Housing for Automobile Market
Powertrain
Japan Electrically Powered Hydraulic Steering Market
Powertrain
Automatic Transmission Solenoid Pack Market
Powertrain
Powertrain Domain Control Unit Platforms Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Global Automotive Clutch Market
Powertrain
Fuel Cell Powertrain Market
Powertrain
Automotive Performance Tuning Market
Powertrain
Global Automotive Powertrain Management System Market
Powertrain
Electric Two-Wheeler Powertrain and Range Validation Test Systems Market
Powertrain
Gas Engine Market
Powertrain
Exhaust Flexible Couplings Market
Powertrain
Global Driveline Market