
 Automotive Turbocharger Market | 2026-2036
Automotive Turbocharger Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Turbocharger Market Analysis
ISO/TS 16949 qualification is reorganizing supplier tiers across the automotive turbocharger landscape. Garrett Motion Inc. leverages its electric turbocharging R&D to anchor positions in hybrid powertrain programs. BorgWarner Inc. sustains manufacturing scale across North American and European facilities, competing on cost-engineered variable geometry systems. IHI Corporation differentiates through specialized marine and industrial turbocharger expertise that extends into performance automotive segments.
An automotive turbocharger is a forced-induction device that compresses intake air using exhaust-driven turbine wheels typically machined from Inconel or cast nickel-aluminide alloys, enabling smaller displacement engines to achieve power outputs comparable to larger naturally aspirated units while reducing fuel consumption and CO2 emissions. Variable geometry turbochargers capture dominant share in diesel applications where vane-adjustment mechanisms optimize boost across wide engine speed ranges, while electric turbocharging represents the fastest-expanding technology segment as 48V architectures eliminate turbo lag through motor-assisted spooling. Twin-scroll designs concentrate margin pools in premium passenger vehicles where pulse-separated exhaust routing improves transient response.
EPA Tier 3 and Euro 7 emissions frameworks are tightening particulate and NOx limits, forcing OEMs to pair turbocharged downsizing with advanced aftertreatment and raising barrier costs for uncertified suppliers. China's MIIT fuel consumption regulations and India's BIS emission standards are converging toward similar stringency, reshaping market access requirements for turbocharger manufacturers. Stakeholders must monitor electric turbocharging cost curves and battery-electric vehicle penetration rates to calibrate long-term platform investment decisions.
Market Dynamics
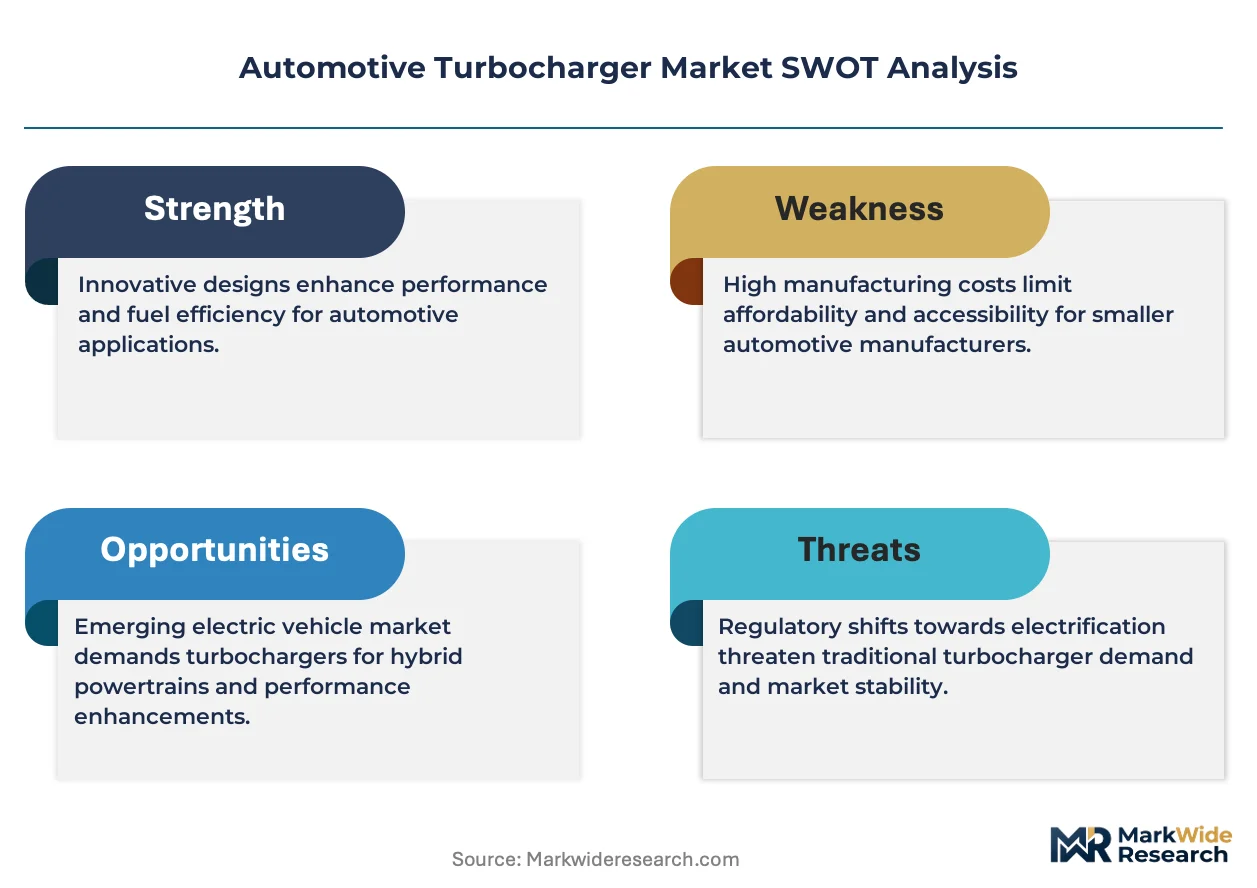
The automotive turbocharger market is experiencing structural compression as 48V mild-hybrid architectures and electric turbocharging technologies decompose traditional mechanical boost systems, forcing suppliers to reconfigure R&D portfolios and manufacturing footprints simultaneously.
Growth Catalysts
- Euro 7 Emissions Framework:The European Union's tightening NOx and particulate limits compel passenger vehicle OEMs to adopt downsized turbocharged engines paired with advanced aftertreatment systems.
- China's MIIT Fuel Consumption Regulations:Domestic automakers and joint ventures in China are accelerating turbocharger penetration to meet corporate average fuel economy mandates.
- Variable Geometry Mechanisms:Vane-adjustment technologies optimize boost pressure across diesel engine speed ranges, sustaining demand in commercial vehicle segments.
Market Restraints
- Inconel Alloy Price Volatility:Exhaust turbine wheels machined from nickel-based superalloys face input cost fluctuations that compress supplier margins.
- Battery-Electric Vehicle Substitution:Full-electric powertrains eliminate turbocharger content entirely, creating long-term displacement risk in passenger segments.
- ISO/TS 16949 Certification Barriers:Reorganized supplier qualification tiers raise barrier costs for uncertified manufacturers seeking OEM program access.
Strategic Opportunities
- India's BIS Emission Standards:Converging regulatory stringency with European frameworks creates white space for cost-engineered turbocharger platforms.
- Marine Turbocharger Crossover:IHI Corporation's specialized marine expertise extends into performance automotive applications, opening premium niche segments.
- Electric-Mechanical Convergence:Integration of 48V motor-assisted spooling with traditional exhaust-driven architectures enables lag elimination without full electrification.
Industry Challenges
- Thermal Management Engineering Talent:Shortages of specialists capable of optimizing turbine wheel aerodynamics and heat flux modeling constrain development timelines.
- Aftertreatment Integration Complexity:Pairing turbocharged downsizing with gasoline particulate filters and selective catalytic reduction systems multiplies calibration validation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Turbocharger Market |
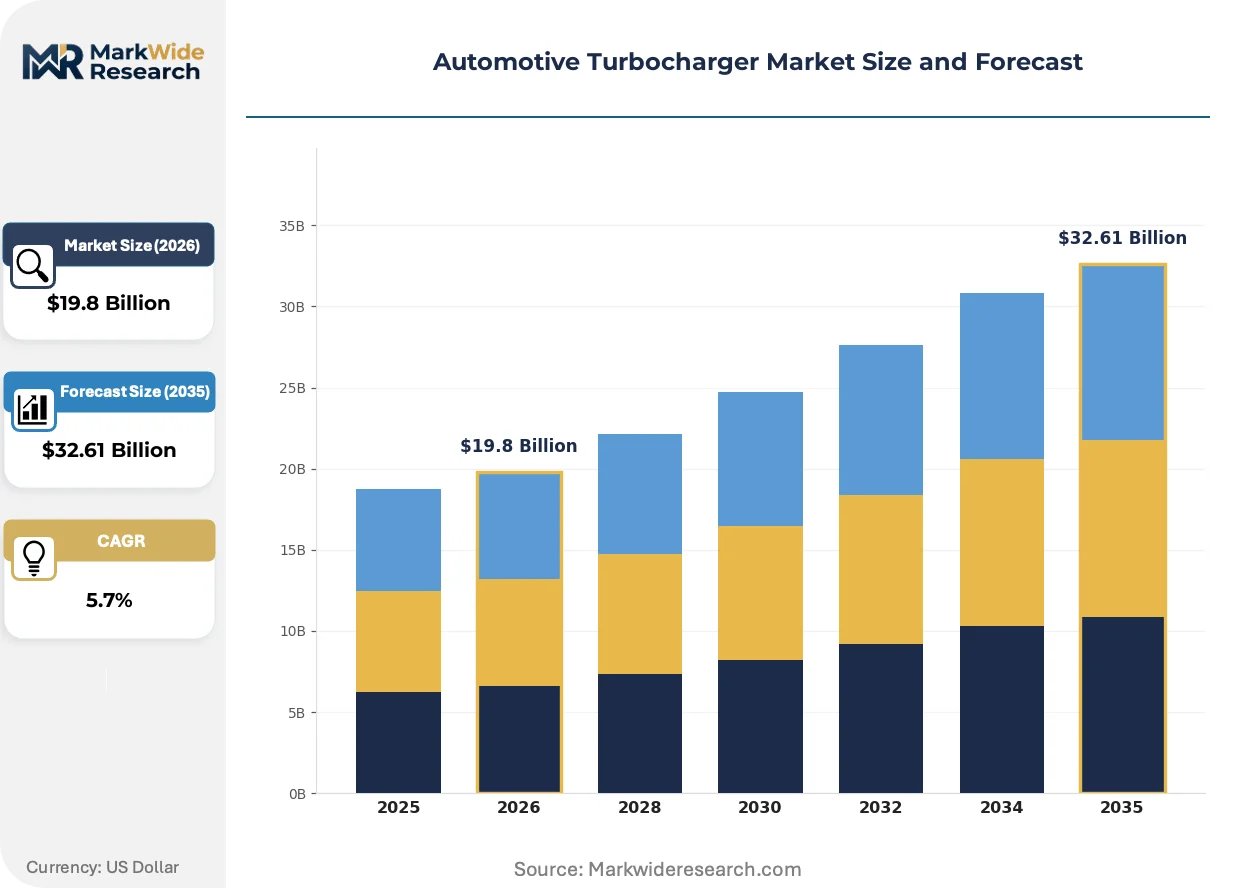
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $32.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Wastegate, External Wastegate, Twin-scroll, Variable Geometry End User: Passenger Vehicles, Commercial Vehicles, Performance Cars, Electric Vehicles Material: Aluminum, Cast Iron, Stainless Steel, Composite Technology: Active Control, Electric Turbocharging, Sequential Turbocharging, Hybrid Turbocharging |
| Companies Covered | BorgWarner Inc., Garrett Motion Inc., Mitsubishi Heavy Industries Ltd., IHI Corporation, Cummins Inc., Continental AG, Robert Bosch GmbH, Schaeffler, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Turbocharger Market Emerging Trajectories
Active thermal management and electrified boost architectures are decomposing conventional turbocharger design paradigms, compressing development cycles and redefining competitive differentiation around software-controlled airflow optimization rather than purely mechanical performance.
Electric turbocharging is decomposing the traditional trade-off between boost response and turbine efficiency. The technology uses integrated motor-generators to eliminate lag during low-rpm operation while recovering exhaust energy at high loads. Passenger vehicle OEMs in Germany and Japan are piloting 48V systems ahead of Euro 7 implementation. This convergence is compressing demand for purely mechanical variable geometry systems in premium segments.
EPA Tier 3 tailpipe standards are forcing gasoline direct-injection engines to adopt particulate filters alongside turbocharged downsizing. The regulation tightens particulate mass and number limits, requiring recalibrated boost strategies that minimize soot formation during transient operation. Light-duty truck manufacturers in the United States are responding with twin-scroll designs that improve combustion stability.
Fleet procurement of turbocharged powertrains is rotating toward total cost of ownership metrics rather than upfront hardware pricing. Leasing companies and commercial operators now weight fuel economy certification and residual value projections more heavily than initial capital expenditure. This behavioral shift concentrates volume with suppliers offering predictive maintenance diagnostics and extended warranty coverage, particularly visible in German commercial vehicle channels.
Automotive Turbocharger Market Segmentation
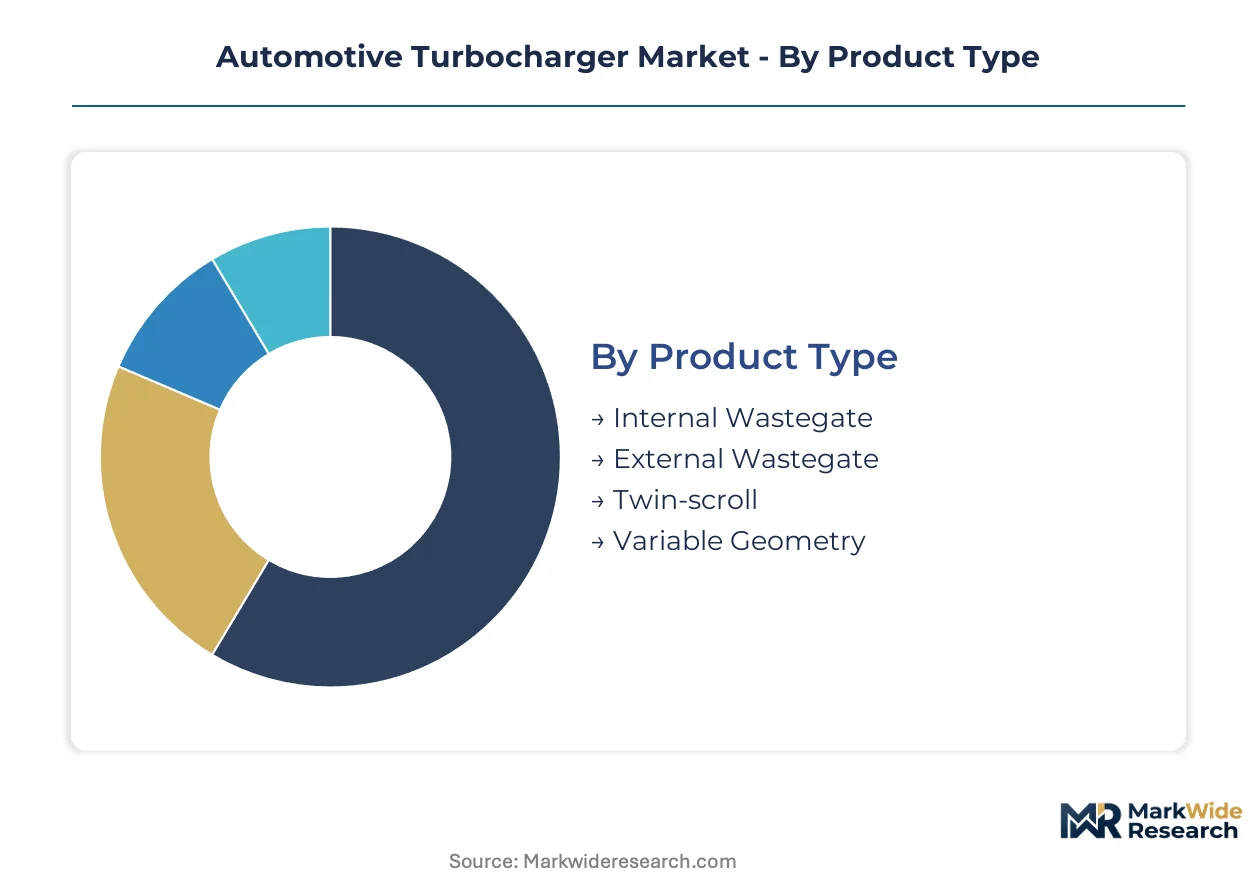
Turbocharger segmentation reveals how engineering trade-offs between response speed, thermal durability, and electrification readiness concentrate value across distinct product architectures. Material selection and control technology choices increasingly determine supplier competitiveness as emissions frameworks tighten.
Product Type:
Margin pools concentrate in vane-adjustment mechanisms and pulse-separated exhaust routing, where thermal engineering complexity sustains pricing power.
- Variable Geometry:Vane-adjustment mechanisms optimize boost pressure across diesel engine speed ranges through hydraulically actuated nozzle rings. Demand concentrates in German commercial vehicle OEMs preparing for Euro 7 implementation, where precise airflow control reduces aftertreatment burden. Cast nickel-aluminide turbine wheels withstand exhaust temperatures exceeding 950°C.
- Twin-scroll:Pulse-separated exhaust routing isolates cylinder firing sequences to preserve kinetic energy in divided turbine inlets. German and Japanese passenger vehicle manufacturers deploy these systems in premium powertrains where transient response determines drivability perception. The architecture commands hardware premiums over single-scroll alternatives.
- Internal Wastegate:Integrated bypass valves divert exhaust flow to limit boost pressure in cost-optimized gasoline applications.
- External Wastegate:Remote-mounted valves enable larger flow capacity for high-boost performance applications.
The dominant share belongs to Variable Geometry, while Twin-scroll is closing the gap fastest in gasoline passenger segments.
End User:
Application-specific thermal cycles and duty profiles segment procurement requirements across vehicle categories with divergent validation protocols.
- Passenger Vehicles:Downsized turbocharged gasoline engines dominate powertrain portfolios at Volkswagen, Toyota, and Hyundai as corporate average fuel economy mandates tighten. Chinese domestic brands and joint ventures are accelerating adoption of 1.0L-1.5L turbocharged three and four-cylinder architectures to satisfy MIIT consumption regulations.
- Commercial Vehicles:Long-haul diesel powertrains rely on variable geometry systems to maintain boost across 1,000-2,000 rpm operating bands where engine braking and gradeability intersect. Fleet operators in Germany weight total cost of ownership metrics including predictive maintenance diagnostics.
- Performance Cars:Motorsport-derived ball-bearing cartridges and titanium aluminide turbine wheels serve low-volume, high-margin segments.
- Electric Vehicles:Battery-electric architectures eliminate mechanical turbocharger content entirely, creating long-term displacement exposure.
Passenger Vehicles retains volume leadership, though Commercial Vehicles offers the most stable margin profile through extended warranty contracts.
Material:
Alloy selection directly determines turbine wheel creep resistance and housing thermal fatigue life under cyclic loading.
- Inconel Superalloys:Nickel-based precipitation-hardened alloys retain tensile strength above 800°C exhaust temperatures. Cast and machined turbine wheels from Inconel 713C or Mar-M-247 dominate heavy-duty diesel applications where thermal management engineering talent constrains development timelines.
- Cast Iron:Gray and ductile iron housings provide cost-effective thermal mass for gasoline passenger vehicle turbochargers.
- Aluminum:Compressor housings exploit aluminum's thermal conductivity and machinability for intake-side components.
- Composite:Polymer matrix compressor housings reduce weight in emerging 48V electric turbocharging architectures.
Inconel Superalloys commands the highest material premiums, while Composite formulations are gaining traction fastest in electrified boost systems.
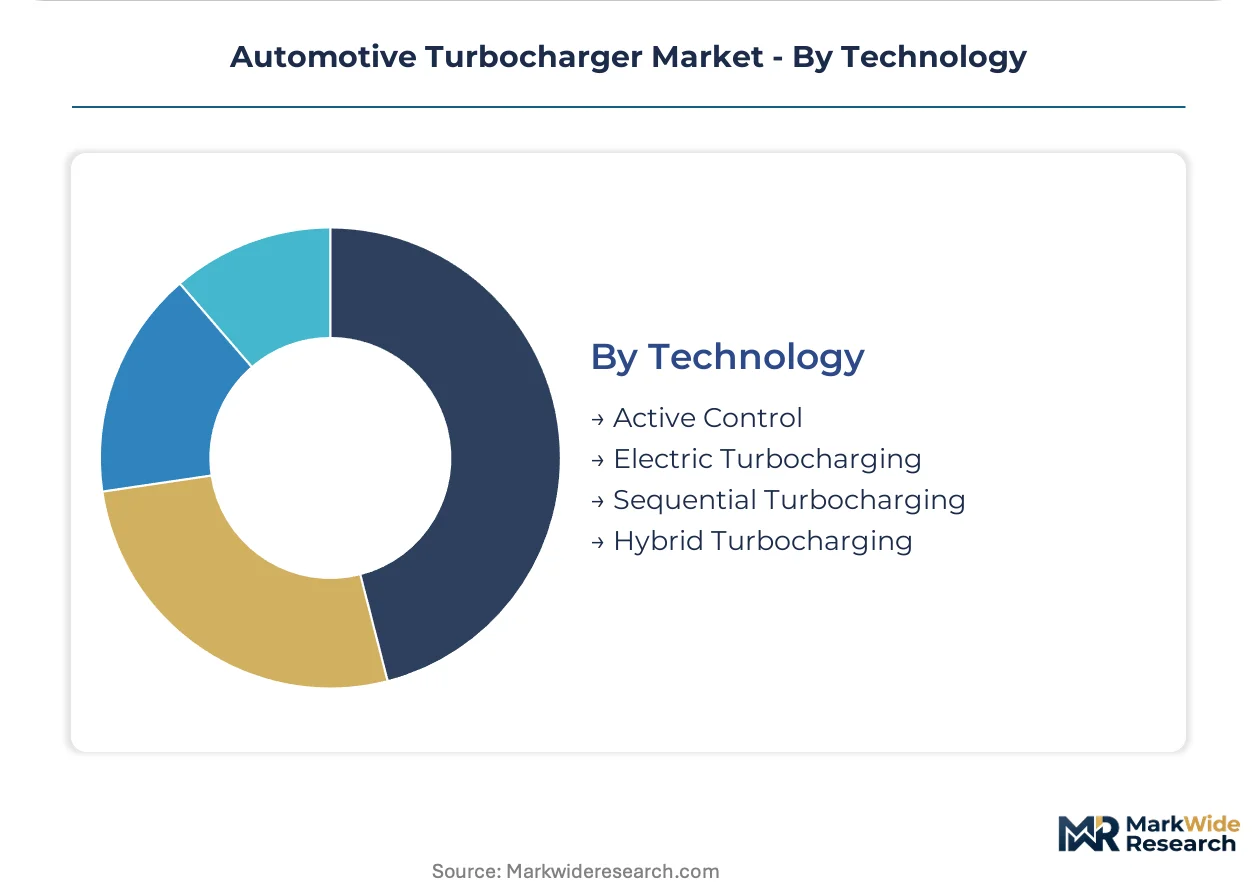
Technology:
Control sophistication separates mechanical legacy systems from electrified architectures that eliminate lag through motor-assisted spooling.
- Electric Turbocharging:Integrated motor-generators mounted on turbocharger shafts eliminate lag during low-rpm operation while recovering exhaust energy at high loads. German OEMs pilot 48V systems ahead of Euro 7 implementation, compressing demand for purely mechanical alternatives in premium segments.
- Hybrid Turbocharging:Combines exhaust-driven turbines with electric motor assistance in staged configurations. Japanese manufacturers are validating these systems for next-generation hybrid powertrains where transient response determines drivability.
- Active Control:Electronic actuators replace pneumatic wastegate control for precise boost pressure modulation.
- Sequential Turbocharging:Multiple turbos of differing sizes optimize efficiency across wide engine speed ranges in heavy-duty applications.
Electric Turbocharging exhibits the steepest expansion trajectory, while Hybrid Turbocharging is consolidating share in 48V mild-hybrid architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement managers in Germany and China concentrate purchasing power for variable geometry and electric turbocharging systems, while Japanese OEMs anchor hybrid powertrain development programs that integrate motor-assisted boost architectures.
China
Domestic brands and joint ventures accelerate adoption of 1.0L-1.5L turbocharged three and four-cylinder engines to satisfy MIIT corporate average fuel consumption mandates. The regulator's Phase V fuel economy standards enforce fleet-wide targets that compress development timelines for downsized powertrains. Manufacturing clusters in Shanghai and Chongqing host turbocharger assembly operations serving BYD, Geely, and SAIC-Volkswagen joint ventures.
Germany
Commercial vehicle OEMs at MAN Truck & Bus and Daimler Truck prepare Euro 7-compliant powertrains relying on vane-adjustment mechanisms to reduce aftertreatment burden. The KBA enforces type-approval protocols that raise validation costs for uncertified suppliers. Stuttgart and Munich anchor development centers where Bosch and Continental calibrate electric turbocharging systems for 48V mild-hybrid architectures.
Japan
Toyota and Honda validate hybrid turbocharging configurations where transient response determines drivability in next-generation powertrains. METI's fuel economy standards tighten fleet obligations through 2030, sustaining R&D investment in motor-assisted spooling technologies. Nagoya and Tokyo metropolitan areas concentrate supplier engineering centers serving domestic OEM hybrid programs.
United States
Light-duty truck manufacturers deploy twin-scroll turbochargers to improve combustion stability under EPA Tier 3 particulate mass and number limits. The agency's tailpipe standards force gasoline direct-injection engines to adopt particulate filters alongside downsized boost systems. Detroit and Dearborn host powertrain development facilities where Ford and Stellantis calibrate boost strategies for full-size pickup segments.
India
Commercial vehicle operators at Tata Motors and Ashok Leyland specify variable geometry systems for long-haul diesel powertrains operating across 1,000-2,000 rpm bands. BIS emission standards converge toward European stringency, opening procurement channels for cost-engineered turbocharger platforms. Pune and Chennai manufacturing corridors attract supplier investments serving domestic OEMs and export programs to Southeast Asian markets.
Automotive Turbocharger Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with captive automotive divisions and specialized turbocharger manufacturers serving marine and performance niches. Market structure concentrates share among five to seven integrated suppliers capable of ISO/TS 16949 certification and electric turbocharging R&D. Two strategic archetypes dominate: vertically integrated powertrain suppliers controlling casting and machining operations, and technology specialists licensing vane-adjustment and motor-generator integration patents. Competitive moves center on 48V architecture partnerships with OEM hybrid programs and backward integration into Inconel superalloy casting capacity.
Among diversified industrial conglomerates, Mitsubishi Heavy Industries Ltd. and IHI Corporation exemplify the vertically integrated archetype with aerospace and marine turbocharger expertise extending into automotive applications. Honeywell International Inc. occupies a position within the technology-licensing tier, leveraging controls and thermal management intellectual property across multiple boost architectures. Garrett Motion Inc. and BorgWarner Inc. sit within the pure-play automotive supplier category, representing the concentrated competitive set where electric turbocharging development timelines determine program access.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Garrett Motion Inc. |
| Mitsubishi Heavy Industries Ltd. |
| IHI Corporation |
| Cummins Inc. |
| Continental AG |
| Robert Bosch GmbH |
| Schaeffler |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Inconel superalloy foundries in Germany and Japan shapes both supplier consolidation and minimum viable pricing for turbine wheel castings, compressing margin structures for uncertified manufacturers while sustaining premiums at ISO/TS 16949-qualified tier-one suppliers.
Pricing Analysis
Cost-plus contracts with London Metal Exchange nickel indexation dominate procurement agreements for Inconel turbine wheels, insulating foundries from raw material volatility while exposing OEMs to alloy price swings. Price differentiation rests on ISO/TS 16949 certification tier and volume scale, with German commercial vehicle OEMs least sensitive due to total cost of ownership metrics and aftermarket bundling. Cost compression in variable geometry mechanisms intensifies as Chinese domestic brands demand cost-engineered platforms for 1.0L-1.5L downsized engines. Fleet operators in India exhibit highest price sensitivity, prioritizing upfront hardware pricing over predictive maintenance diagnostics.
Supply Chain Analysis
Strait of Malacca transit underwrites just-in-time delivery schedules for nickel ore feedstock from Indonesian mines to Japanese and Chinese superalloy processors, creating vulnerability to maritime disruption. Manufacturing concentrates in Germany, China, and Japan, with turbine wheel machining anchored in precision casting clusters serving Bosch and Continental calibration centers. Raw material dependencies include Indonesian nickel laterite, Chilean copper for electric motor windings, and rare earth elements from Chinese separation facilities for permanent magnet generators. Single-source vulnerability pervades Inconel superalloy supply, with three foundries controlling aerospace-grade certification. Distribution runs through captive Tier 1 supplier networks directly into OEM powertrain assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric turbocharging penetration in German and Japanese 48V mild-hybrid programs signals early-cycle expansion, with Euro 7 implementation accelerating OEM adoption timelines beyond baseline forecasts.
For Market Incumbents: Secure captive Inconel superalloy casting capacity through backward integration or long-term offtake agreements with German and Japanese foundries. Defend program access by accelerating electric turbocharging R&D timelines ahead of battery-electric vehicle substitution risk in premium passenger segments. ISO/TS 16949 recertification investments anchor positions in Euro 7-compliant commercial vehicle platforms at MAN Truck & Bus and Daimler Truck. For New Entrants and Emerging Players: Lead with cost-engineered variable geometry platforms targeting India's BIS emission standard convergence, where Tata Motors and Ashok Leyland procurement channels remain less consolidated than European equivalents. White space concentrates in 1.0L-1.5L gasoline applications for Chinese domestic brands seeking MIIT Phase V compliance without premium electric turbocharging content. Go-to-market leverage rests on predictive maintenance software bundling for fleet operators prioritizing total cost of ownership metrics. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified industrial conglomerates with marine and aerospace turbocharger expertise transferable to automotive electric boost architectures. Long-term viability through the technology transition window hinges on 48V motor-generator integration capabilities and hybrid powertrain program access. Acquisition targets should demonstrate ISO/TS 16949 qualification plus electric turbocharging pilot contracts with German or Japanese OEMs. The inflection signal to watch is battery-electric vehicle penetration rates in premium passenger segments, which would compress mechanical turbocharger addressable market.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Turbocharging Platform Development | 48V motor-generator integration eliminates lag for Euro 7 compliance at BMW and Toyota hybrid programs. |
| Inconel Superalloy Backward Integration | Captive casting capacity insulates Garrett and BorgWarner from nickel price volatility and supply disruption. |
| India Cost-Engineered Platform Launch | BIS emission convergence opens procurement channels at Tata Motors with lower certification barriers than Europe. |
| Predictive Maintenance Software Bundling | Diagnostics contracts extend warranty coverage for German fleet operators weighting total cost of ownership. |
| China Joint Venture Manufacturing Expansion | Shanghai and Chongqing assembly operations serve Geely and SAIC-Volkswagen MIIT compliance timelines. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, EPA and KBA type-approval filings, and OEM powertrain disclosure documents. Primary interviews engaged Tier 1 supplier procurement directors, OEM platform engineers calibrating boost strategies, aftermarket distributors serving commercial vehicle fleets, and dealership operations managers. Bottom-up triangulation aggregated content-per-vehicle assumptions across passenger, commercial, and performance segments against top-down market sizing from production forecasts and regulatory mandate timelines.
Segmentation dimensions modeled include propulsion architecture, turbocharger technology type, material grade tier, and regional production cluster concentration. Value outputs across the projection horizon reflect unit economics calibrated to OEM program volumes and supplier pricing disclosures, with CAGRs derived from regression analysis of historical penetration rates against regulatory stringency indices. Industry-specific forecast inputs incorporated MIIT Phase V fleet consumption targets, Euro 7 NOx limit implementation schedules, and battery-electric vehicle substitution curves by vehicle class.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of Euro 7 and MIIT Phase V standards, or accelerated battery-electric vehicle adoption beyond baseline scenarios, would require recalibration. Forecasts reflect documented assumptions regarding nickel alloy price stability, ISO/TS 16949 certification continuity, and 48V mild-hybrid architecture penetration. Practitioners should keep alternative scenarios live as EPA Tier 3 enforcement intensity and Chinese domestic brand procurement consolidation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Engine Air Filter Market
Powertrain
Automotive PTC Heaters Market
Powertrain
Global Hydrogen Combustion Engine Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
France Automotive Engine Oils Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
EV Powertrain Market
Powertrain
Sway Bar Bushing Market
Powertrain
Automotive Hydrostatic Fan Drive System Market
Powertrain
Europe Hill-Start Assist System Market
Powertrain
Transmission Oil Filters Market
Powertrain
Automotive Fuel Pulsation Damper Market
Powertrain
North America Torque Vectoring Market
Powertrain
Clutch Hub Puller Market
Powertrain
New Energy Vehicle Scroll Compressor Market