
 Cloud Logistics Market | 2026-2036
Cloud Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Logistics Market Analytics
Platform modularization is pivoting buyer choice in cloud logistics, as vendors unbundle monolithic suites into interoperable microservices that let shippers purchase only transportation or warehouse modules. Manhattan Associates leverages deep vertical integration across retail and grocery to sustain its position in warehouse management systems. Blue Yonder competes through AI-native supply chain planning, while WiseTech Global anchors its growth on customs and compliance automation layered across global freight forwarding networks.
Cloud logistics denotes the delivery of transportation, warehousing, and fulfillment software through internet-hosted infrastructure, typically architected on containerized microservices with API-first connectivity to IoT sensors, ERP systems, and carrier networks. The primary commercial purpose is to replace on-premise legacy systems with elastic compute resources that scale with shipment volumes and seasonal demand spikes. Transportation Management systems lead in revenue contribution due to freight cost volatility driving real-time procurement automation. Hybrid Cloud deployments represent the fastest-growing architecture as enterprises balance data sovereignty requirements against public cloud scalability. Last-Mile Delivery applications command disproportionate R&D investment as urban density and customer expectations for same-day fulfillment intensify.
FDA traceability mandates for pharmaceutical cold chains, EPA emissions reporting requirements for freight fleets, and FCC spectrum regulations governing IoT device connectivity all shape product roadmaps and market access conditions for cloud logistics providers in the United States. The EU AI Act adds compliance layers for automated decision-making in routing and pricing algorithms. Stakeholders must monitor how diverging data localization regimes across North America, Europe, and Asia-Pacific fragment platform architectures and inflate engineering overhead for multi-territory deployments.
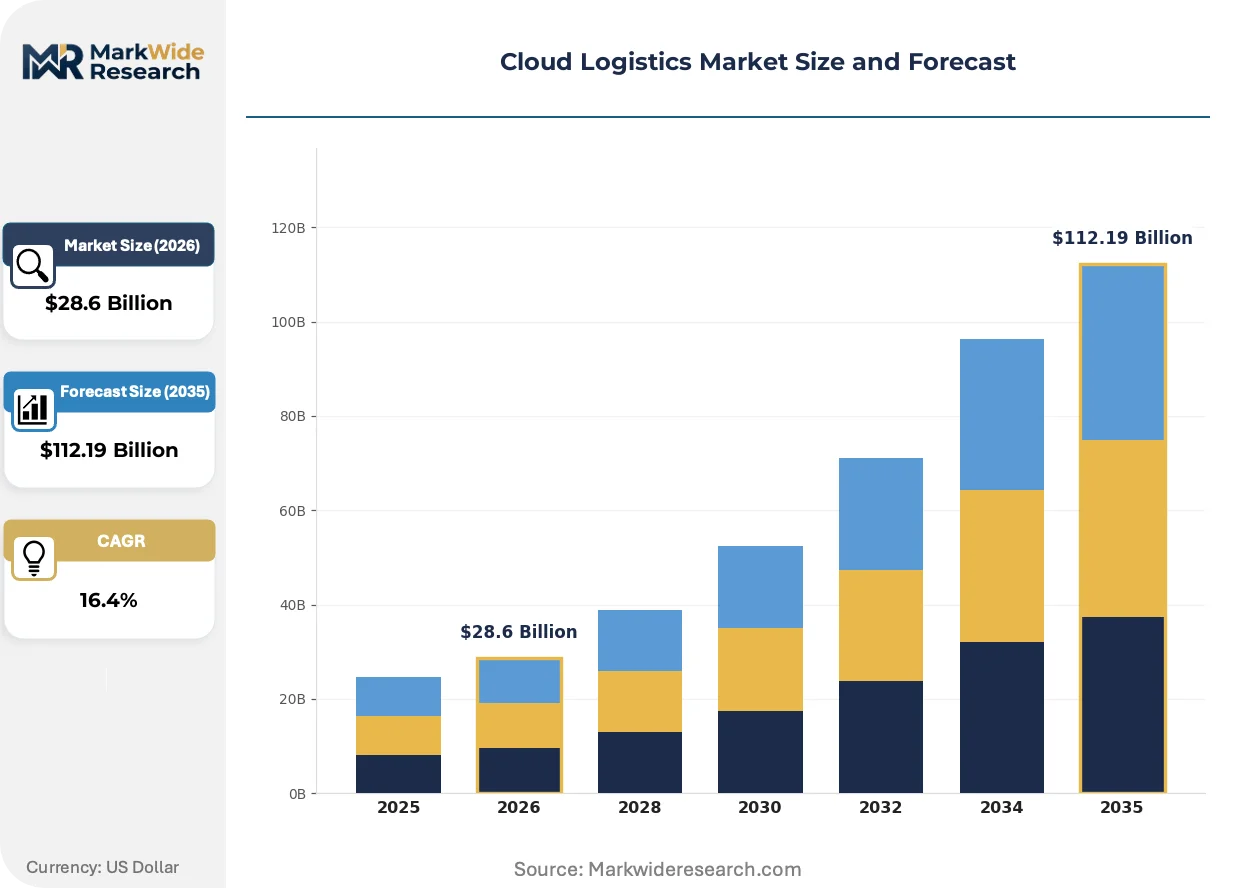
Market Dynamics
Platform modularization is fragmenting vendor power as shippers unbundle monolithic suites into interoperable microservices, letting buyers purchase only transportation or warehouse modules rather than enterprise-wide contracts. This architectural shift redistributes margin from suite providers to specialized point-solution vendors.
Growth Catalysts
- E-commerce inventory orchestration:Real-time stock synchronization across distributed fulfillment nodes drives cloud-native platform adoption among omnichannel retailers managing same-day delivery promises.
- EU AI Act compliance certification:Automated routing algorithms now require pre-deployment validation, creating structured demand for cloud logistics providers with embedded audit trails and explainable decision frameworks.
- German industrial cluster density:Automotive and chemical shippers around Hamburg and Frankfurt are driving multi-cloud adoption as they integrate port logistics with inland distribution networks.
Market Restraints
- Data sovereignty engineering overhead:Diverging localization regimes across Germany, France, and Japan force redundant platform architectures that inflate development costs for multi-territory deployments.
- Legacy ERP integration friction:On-premise warehouse management systems from the 2000s resist API-first connectivity, delaying cloud migration timelines for established shippers.
- Cyber insurance premium escalation:Ransomware targeting IoT sensor networks has doubled coverage costs for fleets operating connected telematics infrastructure.
Strategic Opportunities
- Pharmaceutical cold chain traceability:FDA mandates for temperature-verified shipment records create premium service tiers for cloud platforms with blockchain-anchored documentation.
- India customs modernization:DGFT digitization initiatives and port automation investments open deployment opportunities for compliance-automation modules in freight forwarding.
- Digital twin convergence with IoT:Real-time sensor feeds fused with simulation engines enable predictive disruption modeling for high-value automotive just-in-sequence logistics.
Industry Challenges
- API interoperability standardization gaps:Carrier EDI formats vary across modes, forcing shippers to maintain multiple integration layers that degrade data freshness.
- Cloud infrastructure talent scarcity:Kubernetes orchestration and microservices architecture skills command premium wages that strain mid-market logistics software vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Logistics Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation Management, Warehouse Management, Fleet Management, Order Management Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: E-Commerce, Retail, Third-Party Logistics, Manufacturing Application: Supply Chain Optimization, Inventory Management, Last-Mile Delivery, Freight Tracking |
| Companies Covered | Manhattan Associates, PTV Group, Blue Yonder, Intellias, GoComet, Samsara, Descartes MacroPoint, Innowise, WiseTech Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Logistics Market Evolving Landscape
Artificial intelligence is penetrating operational decision layers faster than infrastructure migration, creating a capability gap between algorithmic sophistication and data pipeline maturity. This tension favors vendors who can embed intelligence without demanding full cloud-native replatforming.
Edge computing nodes deployed at warehouse gates and vehicle cabins are expanding into real-time inventory verification and dynamic route recalculation. Third-party logistics providers operating grocery and pharmaceutical cold chains are adopting these devices fastest, compressing latency between sensor trigger and system response from minutes to milliseconds. The technology is expanding into autonomous exception handling, reducing dispatcher intervention for routine traffic or temperature deviations.
EPA emissions reporting mandates for freight fleets are forcing fuel-consumption telemetry into audit-ready formats. Carriers operating across California, Texas, and Illinois must now aggregate telematics data through cloud platforms that automate Scope 1 calculations for regulatory submission. Heavy-duty trucking and last-mile delivery segments are responding by prioritizing providers with pre-built emissions dashboards over generic fleet management tools.
Subscription-based pricing for transportation management capabilities is displacing perpetual license models among mid-market freight brokers. Monthly per-shipment fees align vendor revenue with customer volume volatility, reducing upfront capex barriers. This shift concentrates in North American brokerage segments where margin compression has made fixed software costs untenable for smaller operators.
Cloud Logistics Market Segmentation
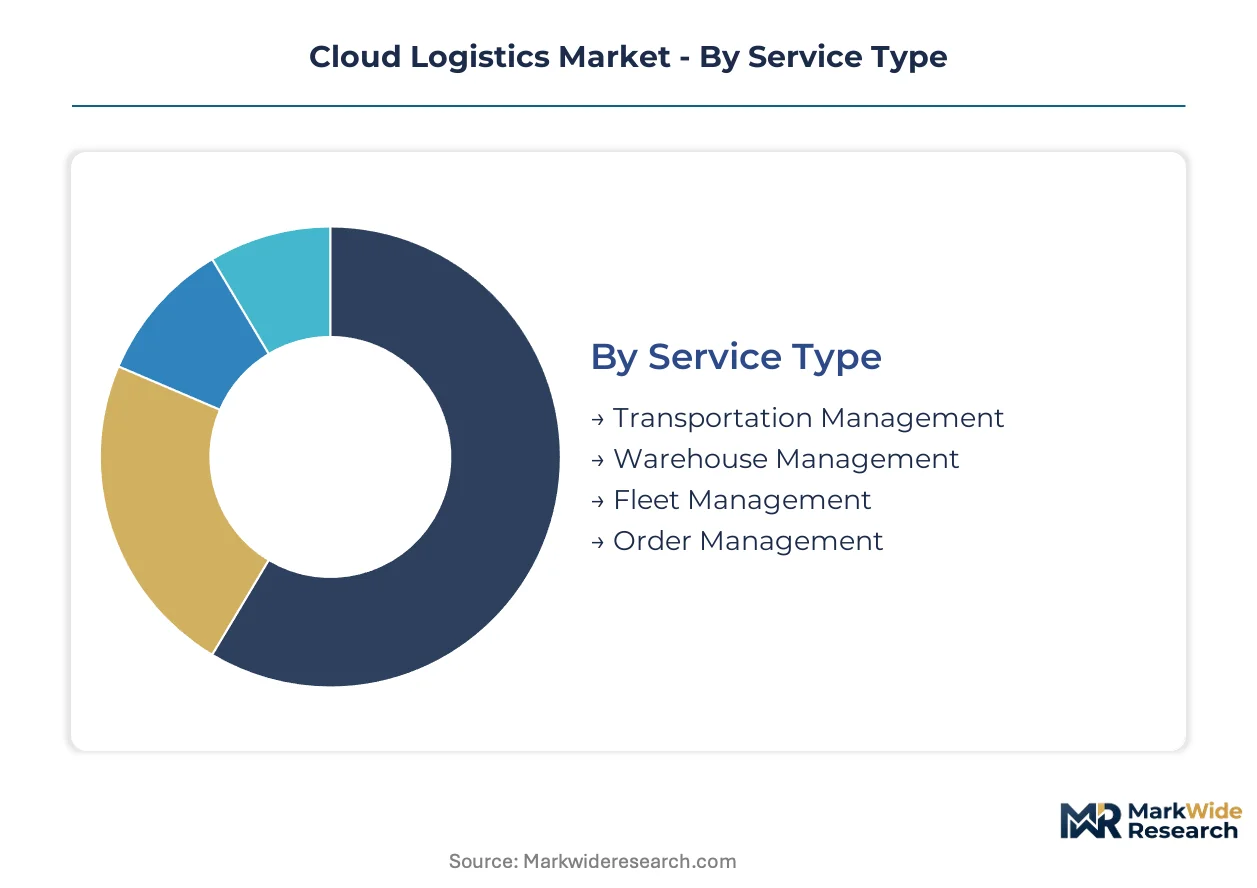
Cloud logistics vendors architect pricing and deployment flexibility around four intersecting dimensions. Service modularity, infrastructure sovereignty, end-use specialization, and application depth collectively determine platform selection criteria and contract value.
Service Type:
Standardization dominates transportation and fleet modules, while warehouse and order management retain higher customization variance due to facility-specific workflows and omnichannel complexity.
- Transportation Management:Freight procurement automation with real-time carrier selection and dynamic rate negotiation. Demand concentrates among North American freight brokers facing margin compression, with subscription pricing displacing perpetual licenses fastest here.
- Warehouse Management:Inventory orchestration systems with directed put-away, wave planning, and labor optimization. Grocery and pharmaceutical cold chains in Germany's Hamburg-Frankfurt corridor drive multi-cloud deployments for temperature-verified storage protocols.
- Fleet Management:Telematics aggregation for fuel monitoring, driver behavior scoring, and predictive maintenance scheduling.
- Order Management:Distributed order promising and fulfillment node selection across omnichannel retail networks.
Most installed capacity flows through Transportation Management. Expansion is steepest in Warehouse Management.
Deployment:
Cost tier stratification separates public cloud entry points from premium sovereign architectures, with hybrid and multi-cloud occupying mid-to-high value bands based on data residency requirements.
- Public Cloud:Shared infrastructure with elastic compute scaling and API-first connectivity to carrier networks. Mid-market freight brokers in North America adopt fastest due to minimal upfront capex and rapid deployment timelines.
- Hybrid Cloud:Split workloads with sensitive data on-premise and burst compute in public environments. German automotive and chemical shippers anchor demand as they balance Hamburg port logistics integration with EU AI Act compliance for automated routing.
- Private Cloud:Dedicated single-tenant infrastructure for defense, pharmaceutical, and high-value cargo operators with audit-intensive regulatory mandates.
- Multi-Cloud:Orchestration across AWS, Azure, and GCP with workload portability and vendor risk distribution.
Public Cloud carries the largest active deployment base. Multi-Cloud is climbing the fastest as sovereignty requirements fragment across jurisdictions.
End User:
Application maturity varies sharply, with e-commerce platforms demanding real-time synchronization while manufacturing retains legacy ERP integration friction.
- E-Commerce:Omnichannel retailers managing same-day delivery promises through distributed fulfillment nodes. This segment is expanding most quickly as inventory orchestration requirements intensify across marketplace and direct-to-consumer channels.
- Third-Party Logistics:Asset-light operators orchestrating capacity across contracted carrier networks with thin-margin efficiency mandates.
- Retail:Brick-and-click operators unifying store and warehouse inventory visibility for buy-online-pickup-in-store fulfillment.
- Manufacturing:Just-in-sequence and just-in-time producers integrating supplier inbound logistics with production scheduling systems.
E-Commerce commands disproportionate R&D investment. Third-Party Logistics shows the steepest pricing pressure due to margin compression.
Application:
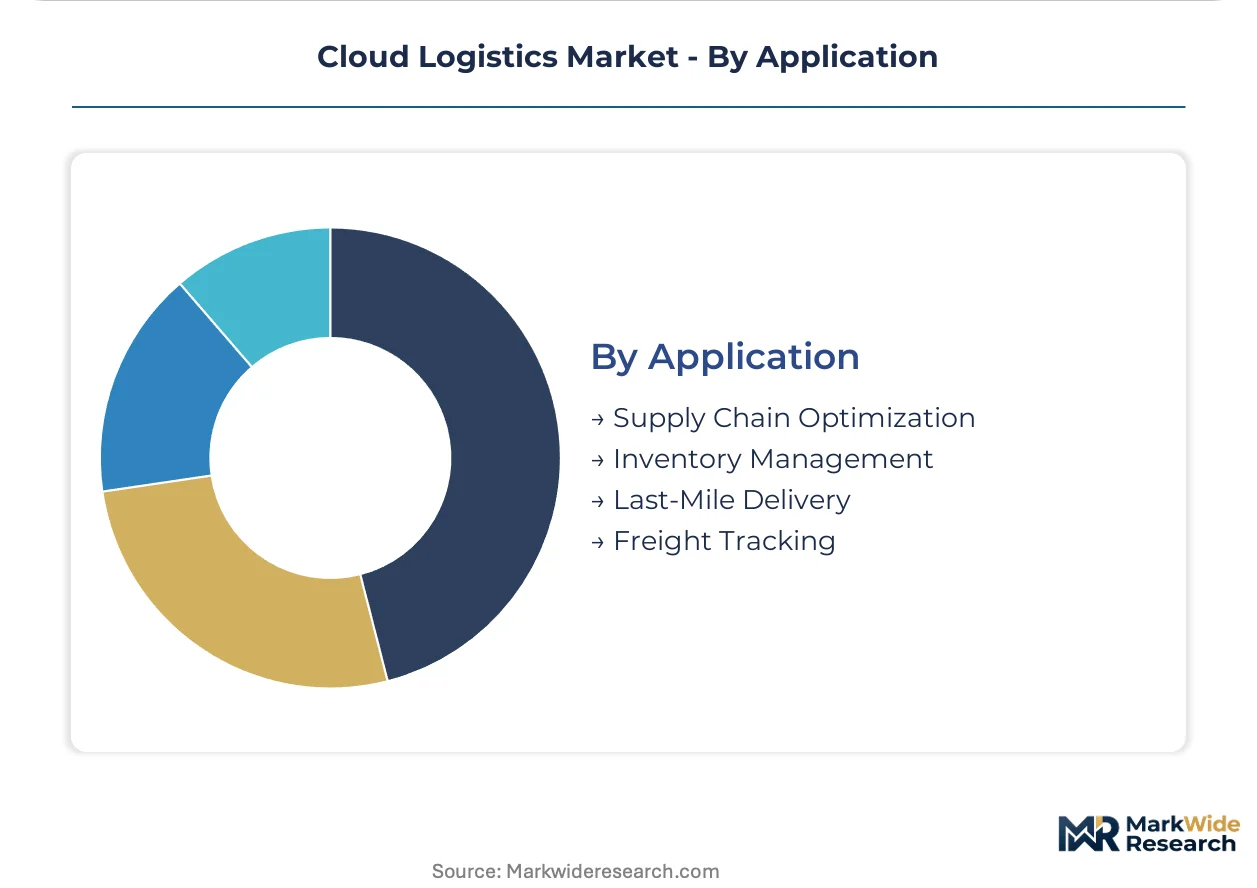
Volume concentration sits with supply chain optimization and inventory management, while last-mile delivery attracts specialized point-solution competition.
- Supply Chain Optimization:Network design, demand forecasting, and scenario planning with AI-native algorithmic decision layers. Blue Yonder and similar vendors compete here through embedded machine learning without requiring full cloud-native replatforming.
- Last-Mile Delivery:Dynamic route recalculation, customer delivery windows, and proof-of-capture verification. Urban density in European and Asian megacities drives edge computing deployment for millisecond-latency dispatch decisions.
- Inventory Management:Real-time stock synchronization across distributed nodes with automated replenishment triggers.
- Freight Tracking:Multi-modal visibility with IoT sensor integration for location, temperature, and shock monitoring.
Supply Chain Optimization holds the deepest enterprise penetration. Last-Mile Delivery is gaining share fastest as same-day expectations intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud logistics infrastructure first achieved commercial scale in the United States through early SaaS freight brokerage platforms, then diffused to European industrial corridors and Asia-Pacific manufacturing hubs as API connectivity standards matured.
United States
FDA traceability mandates for pharmaceutical cold chains and EPA emissions reporting requirements for freight fleets drive platform procurement among healthcare distributors and heavy-duty trucking operators. The FCC governs IoT spectrum allocation for connected vehicle telematics. California's Central Valley and Texas's Dallas-Fort Worth logistics corridor anchor multi-cloud deployments for temperature-controlled pharmaceutical distribution and cross-border Mexican freight coordination.
Germany
Automotive just-in-sequence logistics and chemical bulk shipping demand real-time port-to-plant synchronization around Hamburg and Frankfurt. The EU AI Act requires pre-deployment validation for automated routing algorithms, favoring vendors with embedded audit trails. Industrial clusters along the Rhine-Main and Elbe river systems are consolidating multi-cloud architectures to balance Hamburg port integration with inland distribution network visibility.
China
E-commerce inventory orchestration across distributed fulfillment nodes accelerates cloud-native platform adoption among omnichannel retailers. MIIT standards govern industrial data security and cross-border data flow restrictions. The Yangtze River Delta manufacturing belt around Shanghai and Suzhou drives demand for customs automation modules layered across global freight forwarding networks.
India
DGFT digitization initiatives and port automation investments open deployment opportunities for compliance-automation modules among freight forwarders and customs brokers. The RBI monitors payment system integration for logistics platform settlements. Maharashtra's Mumbai-JNPT corridor and Gujarat's Mundra-Surat industrial zone concentrate cloud logistics adoption for pharmaceutical exports and automotive component supply chains.
Japan
Automotive and electronics manufacturers demand predictive disruption modeling for high-value just-in-sequence logistics with real-time sensor feeds fused to simulation engines. METI promotes supply chain resilience standards and data sovereignty frameworks. The Chubu region around Nagoya and the Kansai industrial corridor anchor multi-cloud deployments integrating Toyota and Panasonic supplier networks with port logistics.
Cloud Logistics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across vertical integration depth and AI-native algorithmic sophistication. The vendor base stratifies into three tiers: suite providers with end-to-end coverage, specialized point-solution vendors with modular microservices, and infrastructure-agnostic platform orchestrators. Dominant competitive moves include strategic partnerships for API interoperability and geographic expansion through compliance-certified localization.
Within the vertical integration tier, Manhattan Associates and Blue Yonder exemplify contrasting archetypes—Manhattan Associates anchors its position through deep retail and grocery warehouse management integration, while Blue Yonder occupies a position defined by AI-native supply chain planning without demanding full cloud-native replatforming. WiseTech Global represents the compliance-automation specialist archetype, with its growth anchored on customs and trade documentation layered across global freight forwarding networks.
| Leading Market Players |
|---|
| Manhattan Associates |
| PTV Group |
| Blue Yonder |
| Intellias |
| GoComet |
| Samsara |
| Descartes MacroPoint |
| Innowise |
| WiseTech Global |
| Others |
Value Network & Pricing Analysis
EPA emissions reporting mandates for freight fleets gate qualified supply and premium-tier pricing access, as carriers operating across California, Texas, and Illinois must now aggregate telematics data through cloud platforms that automate Scope 1 calculations for regulatory submission. This compliance tier separates vendors with pre-built emissions dashboards from generic fleet management tools, concentrating pricing power among audit-ready platform providers.
Pricing Analysis
Subscription-based pricing for transportation management capabilities displaces perpetual license models among mid-market freight brokers, with monthly per-shipment fees aligning vendor revenue with customer volume volatility. Price differentiation rests on EU AI Act certification tier and customization depth for automated routing algorithms. Cost compression in North American brokerage segments intensifies because margin compression has made fixed software costs untenable for smaller operators. Third-party logistics providers show the highest price sensitivity due to thin-margin efficiency mandates, while pharmaceutical cold chain operators demonstrate the lowest.
Supply Chain Analysis
Returns and refurbishment flows for IoT sensor networks and edge computing hardware create secondary supply channels that extend equipment lifecycles and reduce upfront procurement costs for warehouse operators. Manufacturing concentration draws from Taiwan for semiconductor components, China for sensor assembly, and Germany for industrial automation hardware. Raw material dependencies center on rare earth elements for telematics chips, lithium for vehicle battery systems, and specialized polymers for cold chain packaging. Single-source vulnerability in semiconductor fabrication creates chokepoint exposure. Distribution runs through hyperscale cloud provider marketplaces and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cloud logistics market functions as a stable compounder, with e-commerce inventory orchestration driving steady platform adoption across omnichannel retail networks.
For Market Incumbents: Extend API interoperability partnerships to neutralize modularization threats from specialized microservices vendors. Deepen backward integration into edge computing hardware to capture telemetry data layers that emerging entrants cannot replicate. Prioritize EU AI Act compliance certification as a defensive moat against algorithmic audit requirements. For New Entrants and Emerging Players: Begin with India customs modernization initiatives, where DGFT digitization and port automation investments create white-space deployment opportunities for compliance-automation modules. Target pharmaceutical cold chain traceability as the most penetrable application, with FDA mandates for temperature-verified shipment records creating premium service tier demand. Pursue freight forwarder channel partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for specialized point-solution vendors because platform modularization fragments buyer procurement decisions and creates acquisition currency for API-first microservices providers. Long-term viability favors vendors with embedded AI-native algorithmic layers that do not demand full cloud-native replatforming. Monitor EPA emissions reporting enforcement intensity as the signal for regulatory-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Pre-deployment validation requirements favor vendors with embedded audit trails and explainable decision frameworks. |
| Edge Computing Node Deployment | Millisecond-latency inventory verification compresses response times for grocery and pharmaceutical cold chain operators. |
| API Interoperability Partnership | Carrier EDI format standardization reduces integration layer maintenance and improves data freshness across modes. |
| Pharmaceutical Cold Chain Traceability | FDA mandates for temperature-verified shipment records create premium service tiers with blockchain-anchored documentation. |
| Multi-Cloud Architecture Orchestration | Workload portability across AWS, Azure, and GCP addresses data sovereignty fragmentation across Germany, France, and Japan. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with cloud logistics platform executives, freight broker operations directors, pharmaceutical supply chain managers, and customs compliance officers with secondary validation. Secondary sources include SEC 10-K filings from publicly traded vendors, EU regulatory submission databases for AI Act compliance, hyperscaler capex disclosures, and customs automation initiative documentation from DGFT and MIIT. Bottom-up deployment estimates triangulate against top-down market sizing from carrier network data and ERP integration project pipelines.
Granularity-level modeling captures service type, deployment architecture, end-use vertical, and application depth at the country-cluster level, with additional segmentation by regulatory compliance tier for automated routing algorithms. CAGRs derive from shipment volume elasticity coefficients and platform adoption curves across the analysis window. Industry-specific forecast inputs include e-commerce fulfillment node expansion rates and pharmaceutical cold chain regulatory mandate timelines.
Several conditions sit outside the modeled scope, including macroeconomic recession scenarios, major cybersecurity breaches affecting IoT sensor networks, and abrupt shifts in data localization regimes. Forecasts reflect assumptions about continued API standardization progress and cloud infrastructure cost curves. Practitioners should monitor EPA emissions enforcement intensity, EU AI Act audit frequency, and hyperscaler pricing volatility for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
California Freight and Logistics Market
Logistics and Shipping
Project Logistics Market
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Global Sea Air Logistics Market
Logistics and Shipping
North America Freight Forwarding Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
India Contract Logistics Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
ASEAN Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
Asia Pacific Finished Vehicle Logistics Market
Logistics and Shipping
ASEAN Cross Border Road Freight Transport Market