
 Automotive Paddle Shifter Market | 2026-2036
Automotive Paddle Shifter Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Paddle Shifter Market Outlook
Carbon fiber reinforced polymer is expanding its share in paddle shifter construction as automakers shed grams from steering column assemblies. KOSTAL Automotive Electrical Systems leverages integrated electromechanical architectures to anchor supply relationships with European OEMs. Leopold Kostal GmbH & Co. KG sustains manufacturing scale across multiple continents, while Powertrain Control Solutions specializes in aftermarket electronic retrofit kits for performance vehicles.
Automotive paddle shifters are manual gear selection interfaces mounted behind steering wheels, typically actuating via electronic hall-effect sensors or mechanical cable linkages with throw distances under 15 millimeters. Their primary purpose is to deliver driver-initiated shift commands to transmission control units without hand removal from the wheel. Electronic product type variants now lead value generation due to integration with dual-clutch and automatic transmission architectures. Sports cars and passenger cars represent the deepest margin pools, while SUVs emerge as the fastest-growing vehicle type application as family-oriented performance trims proliferate.
NHTSA crashworthiness standards, EPA fuel economy benchmarks, and EU Green Deal decarbonization mandates collectively shape paddle shifter material selection, electronic architecture requirements, and OEM sourcing priorities. ISO 26262 functional safety standards govern electronic shifter signal integrity and fail-safe protocols. Stakeholders must monitor how transmission electrification and steer-by-wire proliferation redefine the physical interface between driver intent and powertrain response.
Market Dynamics
Transmission electrification and steer-by-wire proliferation are compressing the physical interface between driver intent and powertrain response, forcing paddle shifter suppliers to reconceptualize electromechanical architectures for software-defined vehicles.
Growth Catalysts
- EU Green Deal decarbonization mandates:Automakers in Germany and France accelerate lightweighting programs, expanding carbon fiber reinforced polymer adoption in steering column assemblies to shed grams from unsprung mass.
- Dual-clutch transmission proliferation:Performance-oriented passenger car OEMs integrate electronic hall-effect paddle systems as standard fitment, replacing mechanical cable linkages with sub-15 millimeter throw distances.
- Family-oriented performance trim expansion:SUV applications emerge as the fastest-growing vehicle type as manufacturers equip three-row crossovers with driver-initiated shift interfaces previously reserved for sports cars.
Market Restraints
- Steer-by-wire technical immaturity:Fail-safe protocol complexity under ISO 26262 functional safety standards extends development cycles and elevates validation costs for electronic signal integrity systems.
- Rare earth magnet supply concentration:Hall-effect sensor production depends on neodymium supply chains concentrated in China's processing infrastructure, exposing OEMs to export restriction volatility.
- Capacitive touch substitution threat:Haptic feedback steering wheel surfaces developed by premium German automakers threaten to displace physical paddle interfaces in next-generation vehicle architectures.
Strategic Opportunities
- Aftermarket electronic retrofit expansion:Enthusiast segments in Japan and the United States seek plug-and-play paddle shifter kits for legacy automatic transmissions, creating channel diversification beyond OEM supply.
- India PLI scheme localization:Component suppliers can access production-linked incentives by establishing electromechanical assembly operations serving domestic passenger car manufacturers.
- Software-defined vehicle convergence:Integration of paddle shift logic with over-the-air updatable transmission control units enables feature monetization through subscription-based performance calibration tiers.
Industry Challenges
- ISO 26262 ASIL-D certification timelines:Electronic architecture suppliers face 18-24 month validation cycles for fail-safe signal protocols, compressing program launch windows.
- Legacy CAN bus integration friction:New electromechanical paddle systems must maintain backward compatibility with aging vehicle network architectures across multi-year platform lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Paddle Shifter Market |
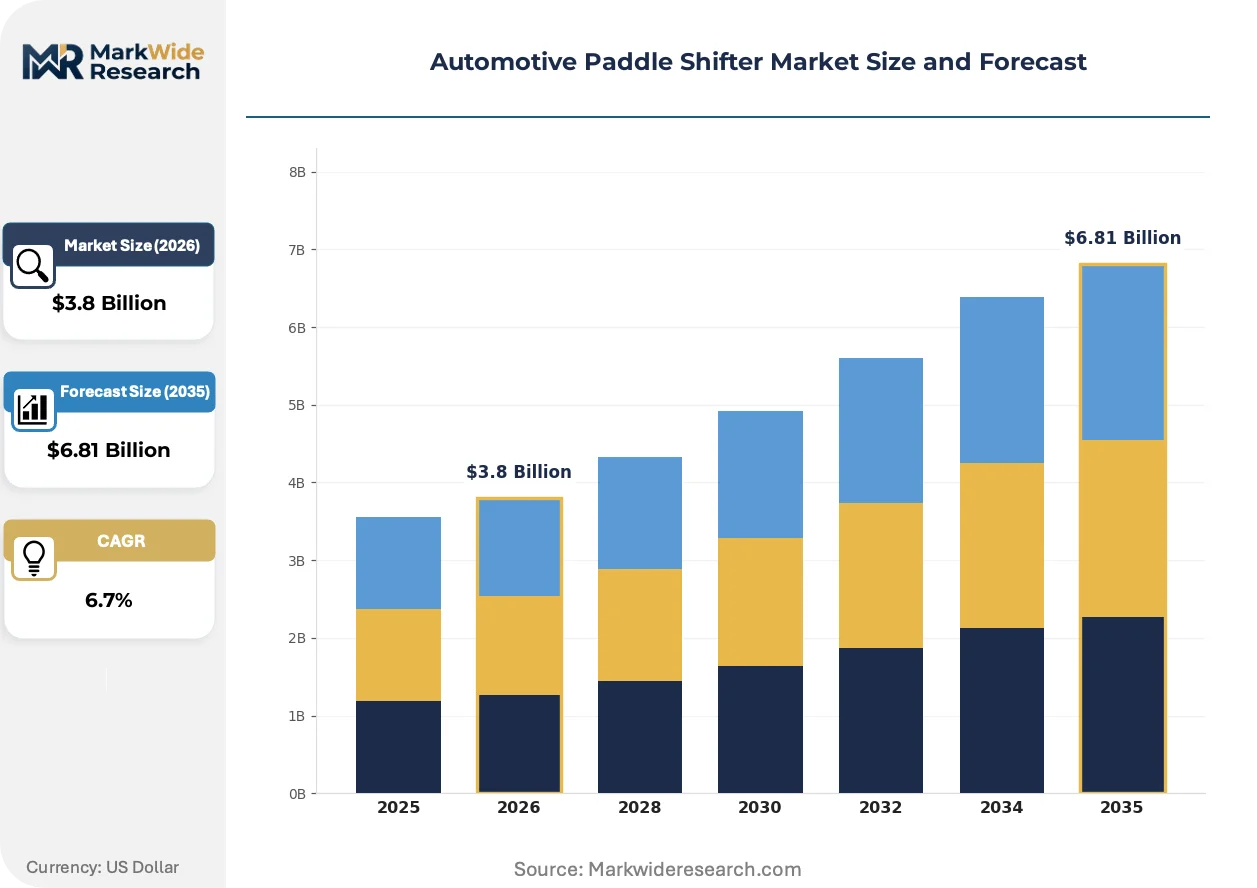
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electronic, Hydraulic, Pneumatic End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Vehicle Type: Passenger Cars, SUVs, Trucks, Sports Cars Technology: Direct Shift, Sequential Manual, Automatic, Dual-Clutch |
| Companies Covered | Bowler Performance Transmissions, Powertrain Control Solutions, GSK InTek Co., Ltd., TCI Automotive, Liberty Vehicle Technologies Ltd., Pro Shift Technologies Ltd., KOSTAL Automotive Electrical Systems, Leopold Kostal GmbH & Co. KG, Hewland Engineering Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Paddle Shifter Market Strategic Shifts
Material science advances and regulatory pressure on vehicle mass are converging to reshape how paddle shifter assemblies are engineered, sourced, and integrated into steering systems. Three developments dominate this evolution.
Carbon fiber reinforced polymer is integrating into steering column brackets and paddle structures to replace die-cast aluminum, cutting component mass by approximately 40 percent. Sports car manufacturers in Italy and Germany now specify CFRP as standard for performance variants, while tier-one suppliers scale thermoplastic processing to meet mid-premium OEM cost targets. This material transition is integrating paddle shifter production into broader lightweighting programs that span interior, chassis, and powertrain systems.
EPA fuel economy benchmarks and NHTSA crashworthiness standards are tightening concurrently, forcing suppliers to optimize for both mass reduction and column intrusion resistance. The regulatory overlap elevates composite material engineering capabilities to a sourcing differentiator, with OEMs prioritizing suppliers holding dual certification for structural and electrical performance. Electronic paddle variants face heightened scrutiny on signal latency under federal motor vehicle safety standards.
Direct sourcing relationships between OEM chassis engineering teams and specialized electromechanical suppliers are displacing traditional tier-two distribution channels. Japanese and German automakers now negotiate paddle shifter specifications at the platform architecture stage, bypassing consolidated steering system integrators. This procurement pattern shift concentrates technical dialogue with component specialists capable of co-developing hall-effect sensor calibration with transmission control unit firmware teams.
Automotive Paddle Shifter Market Segmentation
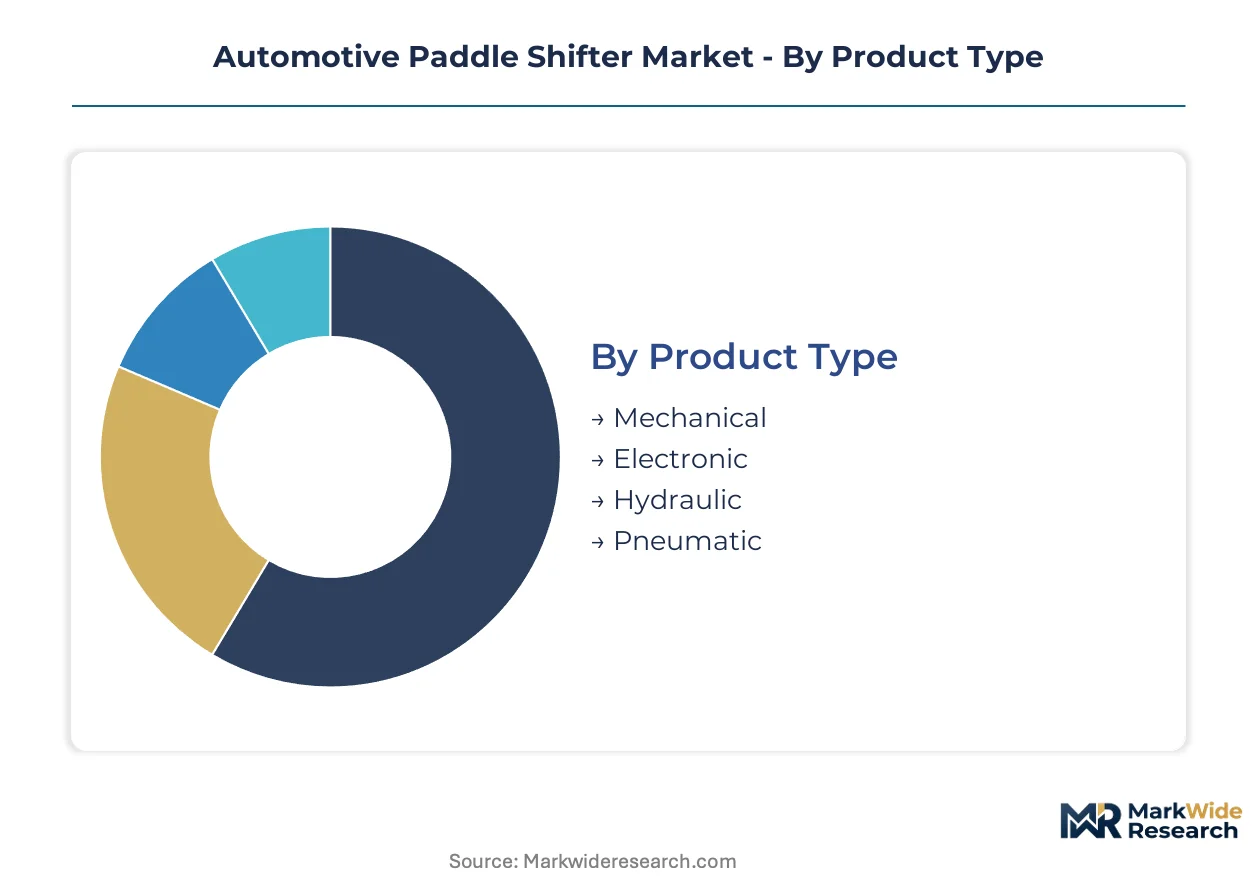
Paddle shifter segmentation reveals how transmission electrification fragments demand across actuation technologies and supply chain tiers. Each dimension exposes different margin pressures, certification requirements, and customer concentration patterns that shape supplier strategy.
Product Type:
Cost tier differentiation separates legacy mechanical systems from premium electronic architectures in procurement decisions.
- Electronic:Hall-effect sensor arrays with sub-15 millimeter throw distances dominate new platform development. German and Japanese OEMs specify these for dual-clutch integration, driven by EU Green Deal lightweighting mandates that favor signal-wire elimination over mechanical linkages.
- Mechanical:Cable-actuated systems persist in cost-sensitive vehicle programs and aftermarket retrofit applications. Demand concentrates in emerging market vehicle assemblers seeking proven durability without electronic validation overhead.
- Hydraulic:Fluid-pressure actuation serves heavy-duty truck segments requiring high-force transmission engagement.
- Pneumatic:Compressed-air systems occupy niche motorsport and industrial vehicle applications with extreme cycle-rate requirements.
Electronic systems lead volumes today; aftermarket mechanical retrofit demand is gaining share fastest.
End User:
Volume concentration varies sharply between captive OEM supply and open aftermarket distribution channels.
- OEMs:Direct platform integration contracts with German, Japanese, and US automakers generate the deepest margin pools. Procurement teams specify paddle shifter architectures at vehicle program inception, locking in multi-year supply agreements tied to transmission control unit co-development.
- Aftermarket Providers:Plug-and-play electronic retrofit kits for legacy automatic transmissions attract enthusiast segments in the United States and Japan. Channel diversification accelerates as vehicle owners seek driver-initiated shift interfaces for family SUVs and aging performance cars.
- Tier-1 Suppliers:Steering system integrators bundle paddle shifters into column module assemblies for OEM resale.
- Vehicle Assemblers:Contract manufacturers in emerging markets source unbranded mechanical systems for localized production.
OEM direct supply dominates revenue; aftermarket electronic retrofit is expanding most quickly.
Vehicle Type:
Application maturity spreads from established sports car fitment toward mass-market family vehicle penetration.
- Sports Cars:CFRP-integrated electronic systems with haptic feedback calibration define the premium tier. Italian and German manufacturers specify these as standard fitment, driven by NHTSA crashworthiness standards that demand optimized column intrusion resistance alongside mass reduction.
- SUVs:Three-row crossovers and performance trims now adopt paddle shifters previously reserved for low-slung coupes. Family-oriented buyers in the United States and Germany seek driver engagement features without manual transmission compromise.
- Passenger Cars:Mid-premium sedans and hatchbacks represent the volume foundation for electronic system scale economies.
- Trucks:Commercial and heavy-duty applications favor mechanical durability over electronic sophistication.
Passenger cars anchor current volumes; SUVs show the steepest expansion trajectory.
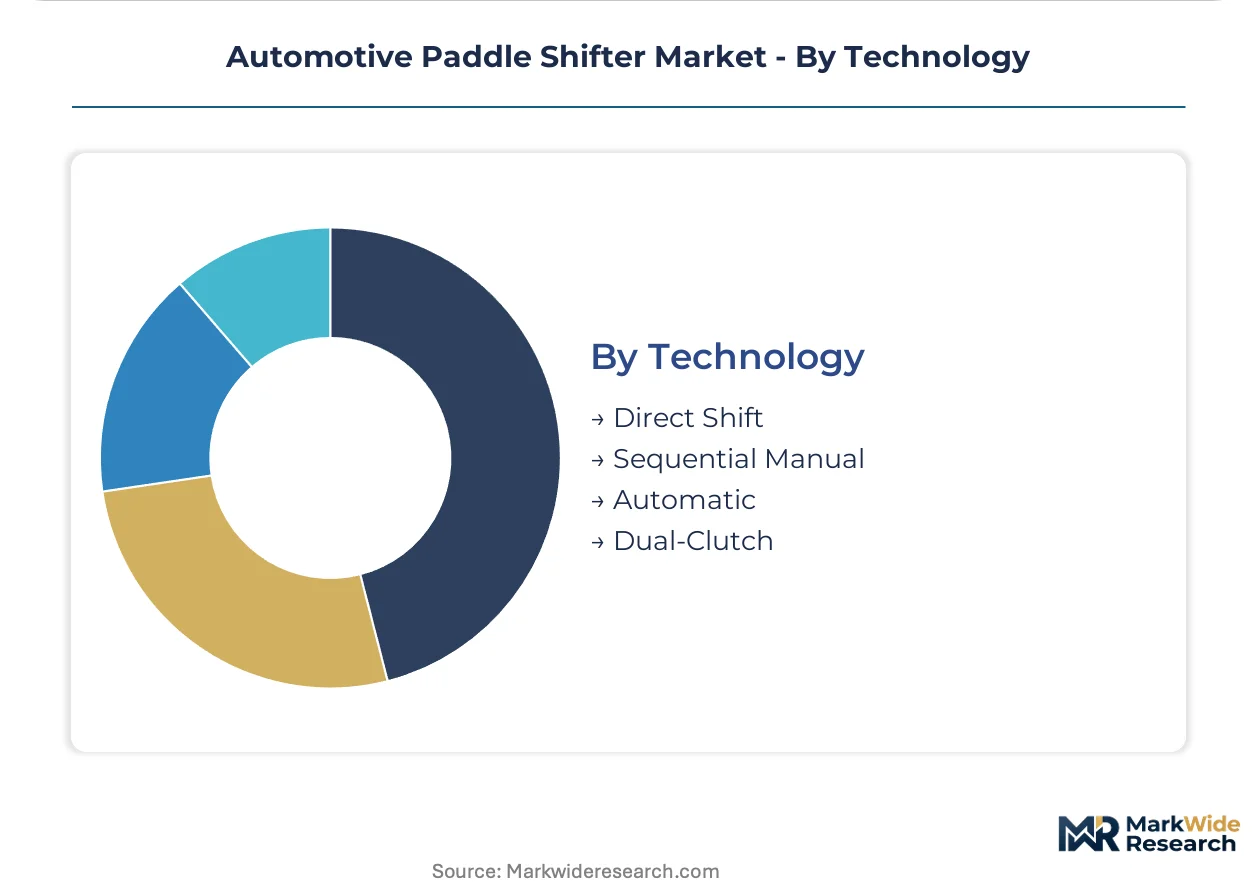
Technology:
Transmission architecture compatibility determines electronic complexity and software integration requirements.
- Dual-Clutch:Millisecond-shift-capable transmissions demand precision hall-effect calibration and ISO 26262 ASIL-D signal integrity. German OEMs lead specification, driven by performance-oriented powertrain programs requiring instantaneous driver intent translation.
- Automatic:Conventional torque-converter transmissions increasingly adopt electronic paddle interfaces as sport-mode enablers. Japanese and US manufacturers expand fitment across mid-range trims, responding to consumer preference for wheel-mounted control without manual clutch operation.
- Direct Shift:Single-clutch automated manual systems persist in cost-optimized European and Asian vehicle programs.
- Sequential Manual:Motorsport-derived dog-engagement systems serve dedicated track vehicles and homologation specials.
Automatic transmission integration leads installed base; dual-clutch applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive engineering clusters anchor production and specification authority for electronic paddle shifter systems. The report identifies concentrated demand across four additional national markets where transmission electrification and performance vehicle manufacturing intersect with distinct regulatory frameworks.
Germany
KBA type-approval requirements and EU Green Deal lightweighting mandates accelerate CFRP adoption in steering column assemblies. Bavaria-based OEM engineering teams specify hall-effect electronic architectures at platform inception, locking in multi-year supply agreements. Stuttgart and Munich clusters concentrate transmission control unit co-development with paddle shifter specialists.
United States
NHTSA Federal Motor Vehicle Safety Standard 114 and EPA fuel economy benchmarks shape electronic signal integrity and mass reduction priorities simultaneously. Detroit-area OEMs integrate paddle shifters into three-row SUV performance trims, expanding family vehicle applications. California enthusiast segments drive aftermarket electronic retrofit kit demand for legacy automatic transmissions.
Japan
METI carbon neutrality roadmaps and JIS functional safety standards govern electromechanical system validation. Nagoya-area transmission manufacturers specify sub-15 millimeter throw distance hall-effect calibration for dual-clutch integration. Osaka-based suppliers anchor direct sourcing relationships with platform engineering teams, bypassing traditional steering system integrators.
China
MIIT new energy vehicle mandates and dual carbon goals accelerate domestic dual-clutch transmission proliferation. Shanghai and Yangtze River Delta clusters concentrate electromechanical assembly operations serving local passenger car manufacturers. Rare earth magnet supply concentration in domestic processing infrastructure exposes OEMs to export restriction volatility for hall-effect sensor production.
India
PLI scheme production-linked incentives attract component suppliers establishing electromechanical assembly operations for domestic passenger car manufacturers. Tamil Nadu and Maharashtra vehicle manufacturing corridors concentrate sourcing decisions for mid-premium sedans and SUVs. BIS certification requirements extend validation timelines for electronic signal integrity systems.
Automotive Paddle Shifter Market Competitive Environment
Direct platform integration contracts dominate the current landscape as OEM chassis engineering teams bypass traditional tier-two distribution channels. The supplier base stratifies across three tiers: integrated electromechanical specialists with firmware co-development capabilities, steering system bundlers serving consolidated column module procurement, and aftermarket retrofit kit providers targeting enthusiast segments. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with suppliers establishing regional assembly operations to satisfy localization mandates.
Among Germany-based electromechanical specialists, KOSTAL Automotive Electrical Systems and Leopold Kostal GmbH & Co. KG exemplify the integrated architecture tier, anchoring supply relationships through multi-continent manufacturing scale. Powertrain Control Solutions occupies a position within the aftermarket retrofit segment, representing channel diversification beyond OEM direct supply. These three entities illustrate how geographic origin and corporate structure correlate with strategic archetype positioning across electronic and mechanical product vectors.
| Leading Market Players |
|---|
| Bowler Performance Transmissions |
| Powertrain Control Solutions |
| GSK InTek Co., Ltd. |
| TCI Automotive |
| Liberty Vehicle Technologies Ltd. |
| Pro Shift Technologies Ltd. |
| KOSTAL Automotive Electrical Systems |
| Leopold Kostal GmbH & Co. KG |
| Hewland Engineering Ltd. |
| Others |
Value Chain & Pricing Dynamics
Rare earth magnet feedstock flows from Chinese processing infrastructure through hall-effect sensor fabrication into three distinct pricing tiers downstream. CFRP composite steering column brackets command premium positioning against die-cast aluminum alternatives, while mechanical cable systems serve cost-optimized vehicle programs in emerging markets.
Pricing Analysis
Neodymium price pass-through from magnet suppliers to sensor manufacturers stratifies electronic paddle systems across premium, standard, and economy certification levels. ISO 26262 ASIL-D validation tier separates German OEM supply contracts from mid-premium Japanese fitments, with aftermarket retrofit kits absorbing the least price sensitivity. Cost compression in mechanical cable assemblies intensifies as Indian vehicle assemblers source unbranded alternatives, while CFRP-integrated electronic variants maintain pricing power through NHTSA crashworthiness compliance bundling.
Supply Chain Analysis
Aftermarket refurbishment flows for legacy mechanical systems create reverse-logistics value recovery in the United States and Japan. Neodymium processing concentrates in China, CFRP prepeg manufacturing anchors in Germany and Japan, and final electromechanical assembly clusters in Mexico and Eastern Europe. Hall-effect sensor production draws from concentrated rare earth supply chains, exposing OEMs to export restriction volatility. Distribution runs through direct platform integration contracts with OEM chassis engineering teams, bypassing traditional tier-two steering system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal lightweighting mandates against EPA fuel economy benchmarks create arbitrage opportunities for suppliers with dual-certification capabilities across Atlantic regulatory regimes.
For Market Incumbents: Acquire CFRP composite processing capabilities to defend margin position against die-cast aluminum substitution. Capacity addition in Mexico addresses NAFTA-origin content requirements for Detroit-area OEM SUV programs. Certification investment in ISO 26262 ASIL-D validation preserves access to German dual-clutch transmission platforms against steer-by-wire displacement threats. For New Entrants and Emerging Players: Enter via plug-and-play electronic retrofit kits for legacy automatic transmissions in California and Osaka enthusiast segments. Aftermarket channel diversification offers the most penetrable white-space, with family SUV owners seeking driver-initiated shift interfaces previously reserved for sports cars. Go-to-market execution partners with established performance parts distributors rather than competing for OEM platform integration contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 26262 validation timelines stretch 18-24 months and specialized electromechanical firmware capabilities concentrate in Bavaria and Nagoya engineering clusters. Acquisition target archetype: mid-cap suppliers holding dual structural-electrical certification with direct OEM platform relationships. Signal to monitor: steer-by-wire technical maturity thresholds that would eliminate physical paddle interfaces entirely.| Strategic Initiative | Industry Significance |
|---|---|
| CFRP Composite Integration | EU Green Deal mandates accelerate 40% mass reduction in steering column assemblies for German OEMs. |
| Hall-Effect Sensor Calibration Partnership | Dual-clutch transmission proliferation in Stuttgart and Munich clusters demands millisecond signal integrity. |
| Aftermarket Electronic Retrofit Expansion | California and Osaka enthusiast segments seek plug-and-play kits for aging performance vehicles. |
| India PLI Localization | Tamil Nadu assembly operations access production-linked incentives for domestic passenger car supply. |
| Software-Defined Vehicle Convergence | Over-the-air transmission calibration enables subscription-based performance tier monetization. |
Study Parameters
Coverage spans Germany, Japan, the United States, China, and India, with primary inputs from each regional cluster combining OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and transmission control unit firmware developers. Secondary validation draws from vehicle production databases, IHS Markit registration data, KBA type-approval filings, and EPA fuel economy certifications. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition separates volume growth from value expansion across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derive from regression analysis of historical fitment rates projected through the modeling period, with specific inputs including dual-clutch transmission proliferation curves, CFRP cost-down trajectories, and steer-by-wire adoption thresholds.
Inputs from OEM engineering teams and Tier 1 procurement leads were available through the study window; gaps in next-generation steer-by-wire development timelines introduce uncertainty bands around physical paddle interface displacement forecasts. Practitioners should monitor MIIT new energy vehicle mandate revisions and NHTSA Federal Motor Vehicle Safety Standard updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Diesel Engine Market
Powertrain
Automotive Clutch Slave Cylinder Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
France Automotive Engine Oils Market
Powertrain
Small Gas Engine Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Automotive Fuel Pressure Regulator Market
Powertrain
Global Driveline Market
Powertrain
Powertrain Domain Control Unit Platforms Market
Powertrain
Automotive Transmission Fluid Market
Powertrain
Transmission Oil Pumps Market
Powertrain
Electrically Powered Hydraulic Steering Market
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
Reciprocating Engine Market