
 Brazil Automotive Market | 2026-2036
Brazil Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Automotive Market Intelligence
The integration of advanced hybrid-flex fuel systems is reconfiguring vehicle powertrain design and manufacturing processes in Brazil. Fiat leverages its historical strength in the popular compact car segment to maintain significant market share. Volkswagen competes through a diversified portfolio, focusing on its SUV lineup. Toyota sustains its brand reputation with a strong focus on hybrid-electric models, particularly popular in major urban centers.
Brazil's automotive sector encompasses the design, manufacturing, and sale of vehicles adapted for local conditions and fuel availability. A key technical feature is the widespread use of flex-fuel engines, engineered to operate on any blend of gasoline and hydrous ethanol. Within vehicle types, SUVs are steadily gaining share from traditional Hatchback models. While the Ethanol fuel type dominates, the Mid-range and Economy market segments represent the largest volume of sales, driven by consumer financing and affordability.
The Rota 2030 program provides the primary strategic direction, offering tax incentives for energy efficiency and technological innovation. Vehicle standards are enforced by CONTRAN for safety and INMETRO for emissions and fuel economy labeling. Navigating the transition from Brazil's established ethanol-based flex-fuel ecosystem to broader electric vehicle adoption presents the central strategic challenge for all manufacturers.
Market Dynamics
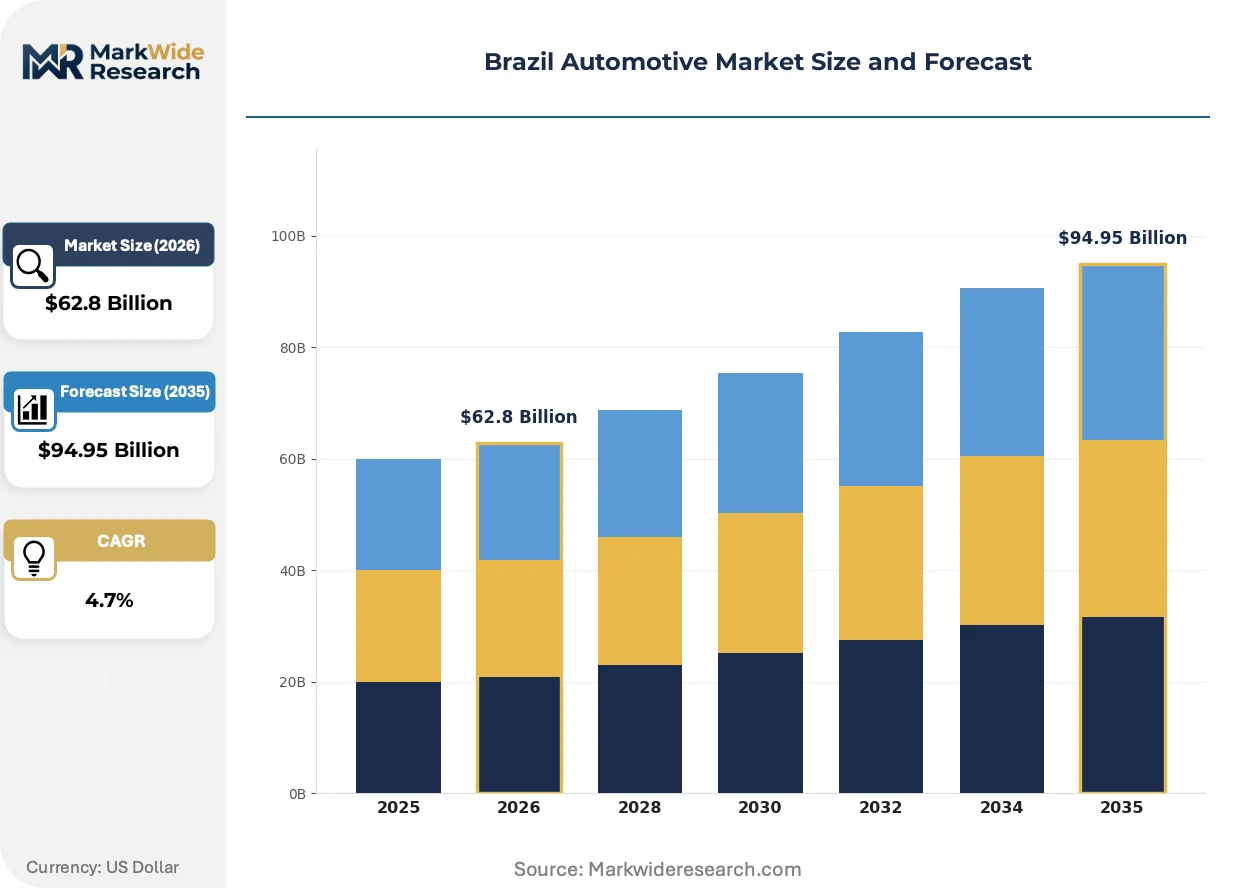
The central dynamic in the Brazil automotive market is the strategic tension between leveraging its deeply embedded ethanol-based flex-fuel infrastructure and the government-mandated push toward electrification and higher energy efficiency, a transition governed by the Rota 2030 program.
Growth Catalysts
- Rota 2030 Incentives:This national policy framework provides significant tax reductions for manufacturers who meet or exceed targets for energy efficiency and local R&D investment, directly stimulating innovation in hybrid-flex and lightweight material technologies.
- Urban SUV Demand:A persistent preference shift among Brazil's middle-class consumers, especially within the Southeast region, for SUVs over traditional sedans and hatchbacks continues to drive sales volume and margin growth in this key segment.
- Credit Availability:The expansion of consumer financing and consortium purchasing plans makes new vehicles more accessible to a broader population, sustaining demand in the high-volume Economy and Mid-range market segments.
Market Restraints
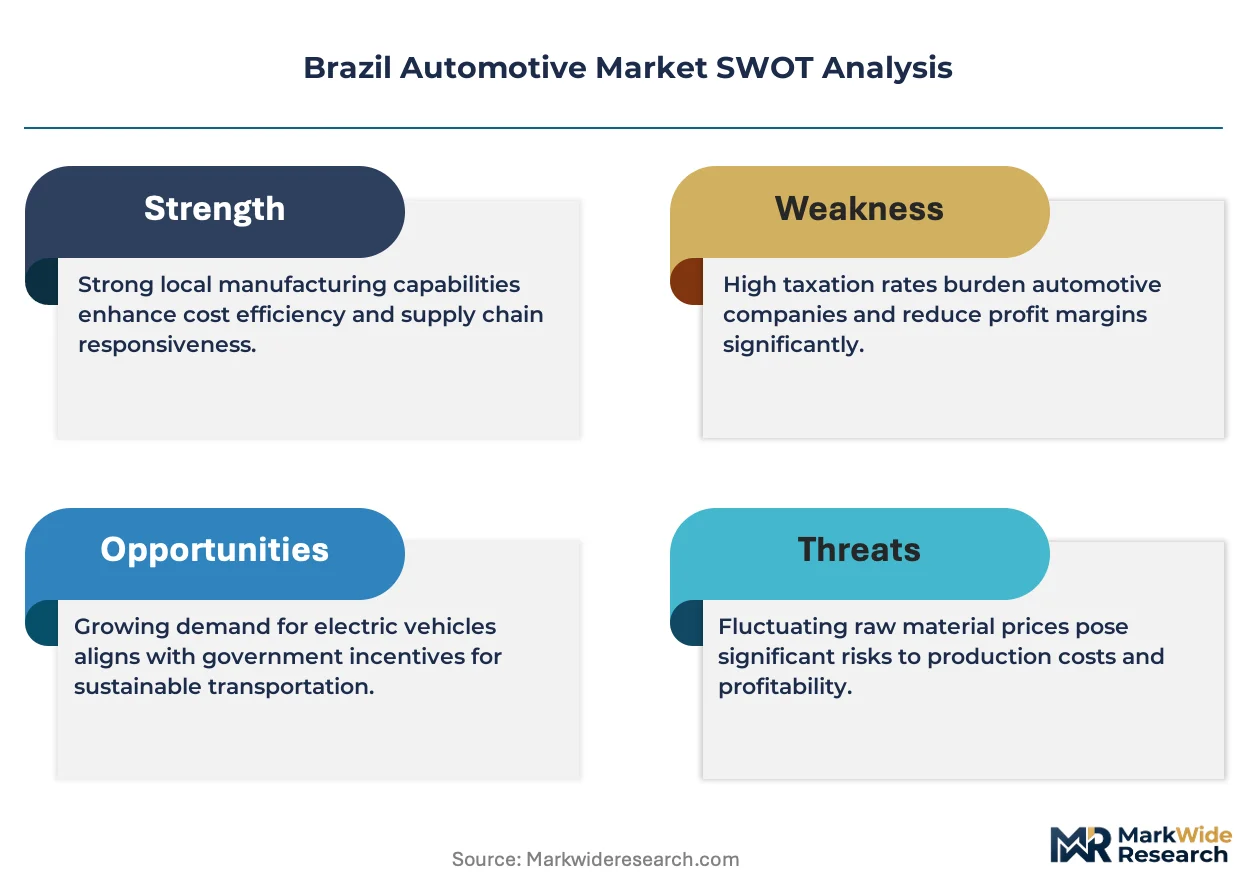
- High Tax Burden:The complex and heavy tax structure, known as "Custo Brasil," inflates final vehicle prices through multiple cascading federal and state taxes, limiting overall market affordability and suppressing potential sales volume.
- EV Charging Deficit:A lack of widespread and reliable public charging infrastructure outside of major metropolitan hubs like São Paulo acts as a significant structural barrier to the mass adoption of pure battery electric vehicles.
- Logistical Bottlenecks:Inefficient port logistics and a heavy reliance on road transport for component and finished vehicle distribution across Brazil's vast territory lead to higher operational costs and potential supply chain delays for manufacturers.
Strategic Opportunities
- Biofuel Electrification:The convergence of Brazil's world-leading ethanol production with electric motor technology creates a unique opportunity to lead in the development and export of advanced hybrid-flex vehicles, a globally relevant transitional technology.
- Northeast Region Expansion:Underpenetrated markets in Brazil's Northeast region present a significant geographic growth opportunity for automakers able to establish effective dealership networks and offer vehicles suited to local purchasing power and road conditions.
- Aftermarket Services:The growing and aging vehicle parc offers a substantial opportunity for expanding branded aftermarket parts and certified service programs, creating stable, high-margin revenue streams for original equipment manufacturers.
Industry Challenges
- Component Localization:Manufacturers face the significant challenge of developing a local supply chain for high-technology components, such as batteries, control units, and semiconductors, to meet the localization requirements of the Rota 2030 program.
- Skilled Labor Shortage:A deficit of engineers and technicians with expertise in EV powertrain design, battery management systems, and connected-car software development hinders the pace of local innovation and production ramp-ups.
- Regulatory Compliance:Adapting vehicle designs and manufacturing processes to meet the progressively stringent emissions and safety standards enforced by INMETRO and CONTRAN requires continuous and substantial capital investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Automotive Market |
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $94.95 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Truck Fuel Type: Petrol, Diesel, Ethanol, Electric Sales Channel: Dealership, Online, Auction, Direct Sales Market Segment: Luxury, Mid-range, Economy, Commercial |
| Companies Covered | Fiat, Volkswagen, Chevrolet, Hyundai, BYD, Toyota, Renault, Honda, Geely, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Automotive Market Strategic Shifts & Innovations
Technological evolution in the Brazilian automotive sector is defined by the hybridization of its legacy flex-fuel engine platforms. This creates a distinct innovation pathway focused on optimizing the interplay between biofuels and electric power, rather than a direct leap to pure EVs.
Advanced hybrid-flex powertrains combine a traditional ethanol-capable internal combustion engine with an electric motor and battery system. Urban consumers in states like São Paulo and Minas Gerais are the primary adopters, drawn by superior fuel economy in congested traffic. This technology is digitizing a vehicle's energy management system, allowing it to autonomously switch or blend power sources to maximize efficiency based on driving conditions.
Brazil's Rota 2030 program is the primary regulatory instrument guiding industry investment. The policy compels automakers to channel capital into research and development for energy efficiency and safety systems in exchange for tax benefits. The passenger car segment, particularly SUVs and compacts, is most impacted as manufacturers re-engineer platforms to achieve higher ratings on the INMETRO fuel economy label.
Consumer preferences are shifting from traditional vehicle ownership toward flexible, subscription-based usage models. This trend is disrupting the standard dealership sales channel, as dedicated mobility firms and automakers' own financial services arms introduce long-term rental packages. The shift is most visible in Brazil's largest urban centers, where corporate clients and younger individuals prioritize cost predictability and access over asset ownership.
Brazil Automotive Market Segmentation
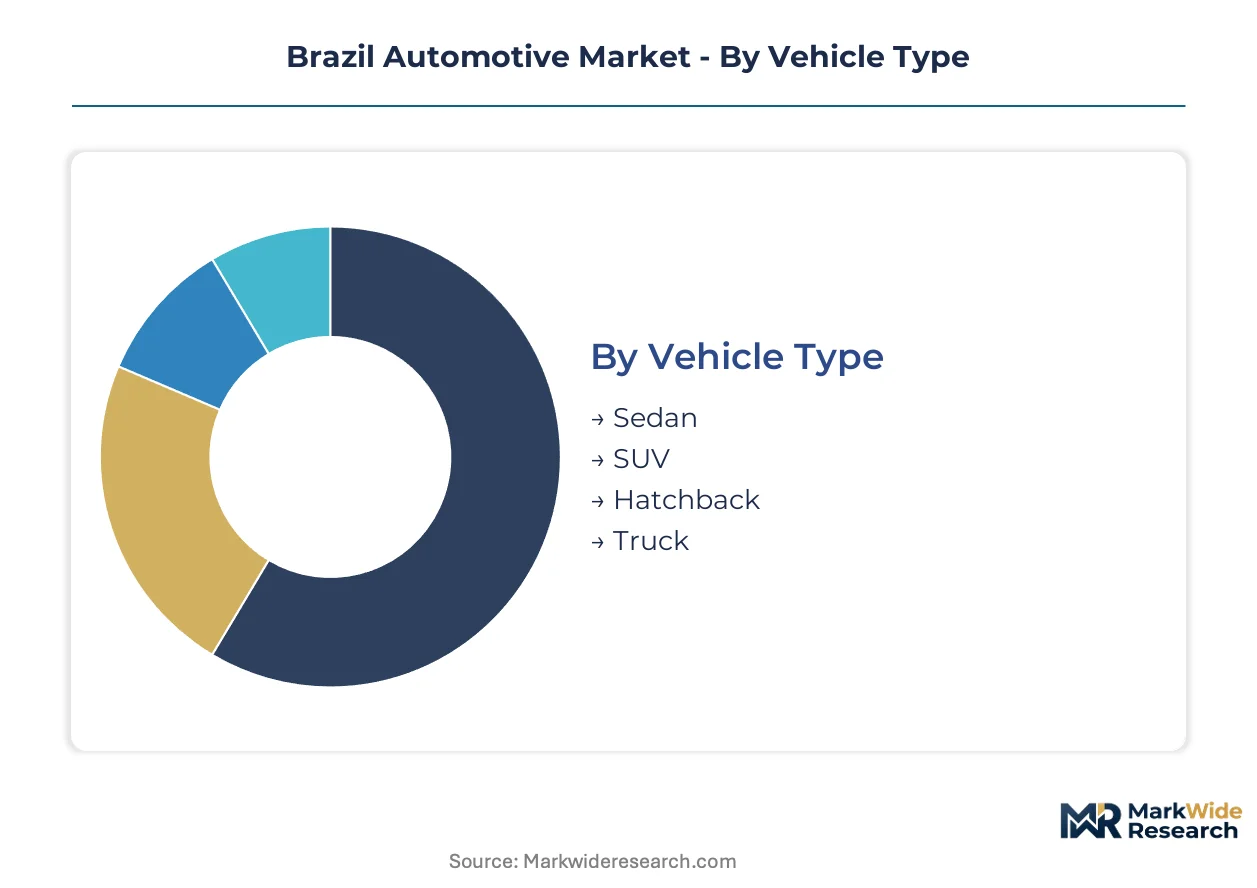
Segmentation in the Brazil automotive market reveals distinct consumer preferences and operational models. Understanding these divisions helps manufacturers tailor product offerings and sales strategies. The market's unique blend of local fuel types and urban demand patterns shapes its various segments.
Vehicle Type:
The maturity spectrum of vehicle types in Brazil shows established categories coexisting with rapidly expanding segments.
- SUV:These vehicles offer higher ground clearance and a commanding driving position, often featuring advanced infotainment systems. Demand concentrates in Brazil's Southeast region, particularly in urban centers, driven by middle-class consumers seeking versatility and perceived safety.
- Hatchback:Compact and agile, these models feature a rear door that swings upward, providing flexible cargo space. Demand, while still significant, is gradually ceding share to SUVs, particularly in major cities, as consumer preferences shift away from traditional compacts.
- Sedan:Traditional three-box vehicles with a separate trunk, sedans cater to family and business users.
- Truck:Light commercial vehicles and pickups serve agricultural, construction, and logistics sectors across Brazil.
Hatchback retains volume leadership; SUV holds the steepest expansion curve.
Fuel Type:
Fuel type segmentation highlights the dominant energy sources and emerging alternatives for propulsion in Brazil.
- Ethanol:This biofuel is widely used in flex-fuel engines, offering a renewable alternative to gasoline and reducing emissions. Its widespread availability and established infrastructure, particularly in agricultural regions, sustain its market dominance.
- Electric:Vehicles powered solely by electric motors, utilizing battery storage for energy, represent a nascent but strategically important segment. Adoption faces constraints due to the lack of widespread charging infrastructure outside major metropolitan hubs.
- Petrol:Traditional gasoline powers a significant portion of Brazil's vehicle fleet, often blended with ethanol.
- Diesel:Primarily used in commercial vehicles and larger SUVs, diesel engines offer high torque and fuel efficiency.
Ethanol maintains a commanding presence due to its established infrastructure; Electric vehicles represent the fastest-growing trajectory.
Sales Channel:
Sales channel segmentation reflects how Brazilian consumers access new vehicles, from traditional showrooms to digital platforms.
- Dealership:Traditional brick-and-mortar showrooms remain the primary point of sale, offering test drives, financing, and after-sales services. This channel caters to a broad customer base seeking personal interaction and comprehensive support during the purchase process.
- Online:Digital platforms and e-commerce websites facilitate vehicle purchases, from initial research to final transaction, often with home delivery options. This channel appeals to tech-savvy urban consumers prioritizing convenience and transparent pricing.
- Auction:Vehicles, often from fleet disposals or repossessions, are sold to individuals or resellers through competitive bidding.
- Direct Sales:Manufacturers sell directly to large corporate fleets, government agencies, or specific institutional clients.
Dealerships offer extensive reach and service integration; Online channels emphasize transactional efficiency for a new generation of buyers.
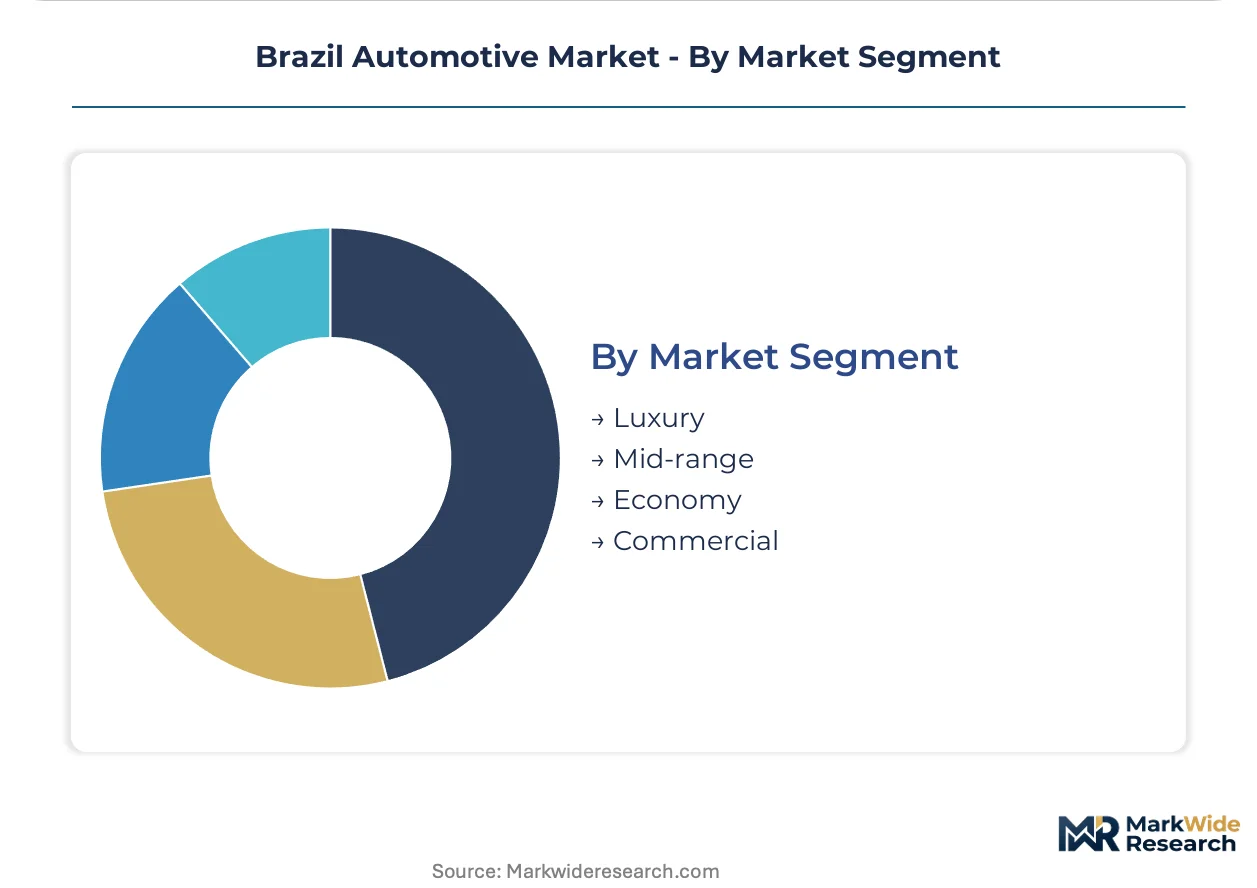
Market Segment:
Market segment analysis reveals the pricing tiers and target demographics that define vehicle affordability and luxury in Brazil.
- Mid-range:These vehicles balance features, performance, and price, appealing to the expanding middle-class consumer base. Consumer financing and consortium purchasing plans significantly sustain demand within this high-volume segment.
- Economy:Focused on affordability and basic functionality, these models represent the entry point for many first-time vehicle owners. Widespread credit availability and low operating costs drive substantial sales volumes in this foundational segment.
- Luxury:Premium vehicles offer advanced technology, superior comfort, and high-end materials, targeting affluent consumers.
- Commercial:This segment includes specialized vehicles and fleet purchases for businesses, transportation, and service industries.
Economy vehicles command the largest sales volume; Luxury models offer higher profit margins per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban middle-class consumers, particularly in Brazil's Southeast region, drive significant demand for new vehicles, especially SUVs. This consumer segment prioritizes vehicle versatility and advanced infotainment systems. Consumer financing and consortium purchasing plans further sustain sales volumes across major Brazilian states.
São Paulo
São Paulo state anchors Brazil's automotive production and consumption, with strong demand for hybrid-flex vehicles. The Rota 2030 program incentivizes energy efficiency investments within its manufacturing hubs. Major automotive clusters in São Paulo, such as those around São Bernardo do Campo, concentrate significant R&D for advanced powertrain technologies.
Minas Gerais
Minas Gerais exhibits consistent demand for economy and mid-range vehicles, supported by expanding consumer credit access. CONTRAN enforces vehicle safety standards across the state's dealerships and service centers. The Betim industrial complex in Minas Gerais remains a critical production site for compact and flex-fuel models.
Rio Grande do Sul
Southern Brazil's Rio Grande do Sul shows a steady preference for pickup trucks and SUVs, catering to agricultural and urban needs. INMETRO fuel economy labeling influences purchasing decisions for new vehicles in its markets. The Gravataí automotive plant in Rio Grande do Sul contributes significantly to national vehicle output, focusing on specific segments.
Bahia
Northeast Brazil's Bahia represents a strategic growth opportunity, with increasing demand for affordable and robust vehicles. The state benefits from federal infrastructure projects that improve logistical access for manufacturers. Camaçari's industrial park in Bahia is a key manufacturing location, attracting investment for local assembly operations.
Brazil Automotive Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure in Brazil's automotive sector. The market sees a mix of established global manufacturers and emerging electric vehicle specialists, each vying for consumer attention. Strategic archetypes include diversified full-line producers and niche players focused on specific vehicle segments like SUVs or electric models. Portfolio diversification, particularly into hybrid-flex technologies, and geographic expansion into underpenetrated regions are dominant competitive moves among these participants.
Within the established full-line producers, Fiat S.p.A. (now part of Stellantis) represents a historical strength in compact car segments, anchoring significant market share through its long-standing presence. German multinational automotive manufacturer Volkswagen AG exemplifies a diversified portfolio, with a strategic focus on its SUV lineup to capture evolving consumer preferences. Japanese-based Toyota Motor Corporation occupies a position as a leader in hybrid-electric models, particularly popular in major urban centers, sustaining its brand reputation through this technological emphasis.
| Leading Market Players |
|---|
| Fiat |
| Volkswagen |
| Chevrolet |
| Hyundai |
| BYD |
| Toyota |
| Renault |
| Honda |
| Geely |
| Others |
Cost & Logistics Intelligence
Component localization requirements under Rota 2030 shape pricing power, as manufacturers absorb higher costs for developing local high-technology component suppliers. This directly impacts vehicle affordability and profit margins.
Pricing Analysis
Cost-plus contract patterns, often indexed to raw material prices and exchange rates, define procurement in Brazil's automotive sector. High federal and state taxes, known as "Custo Brasil," significantly inflate final vehicle prices. This tax burden creates pricing pressure, especially for economy and mid-range segments where consumers are highly price-sensitive. Luxury models, however, exhibit lower price sensitivity due to brand premium and advanced feature sets.
Supply Chain Analysis
Key automotive manufacturing clusters in São Paulo, Minas Gerais, and Bahia concentrate vehicle assembly and component production capacity. Brazil's supply chain relies heavily on imported high-technology components, such as semiconductors and advanced battery cells, due to limited local production. Logistical bottlenecks, stemming from a heavy reliance on road transport across Brazil's vast territory, represent a structural risk. Finished vehicle distribution mainly runs through established dealership networks nationwide.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's automotive market is undergoing high-growth disruption, driven by the Rota 2030 program's push for energy efficiency and hybrid-flex technologies. This regulatory inflection point redefines product development and market dynamics.
For Market Incumbents:Build a deep technological moat around advanced hybrid-flex powertrains, leveraging Brazil's ethanol ecosystem. Invest heavily in local R&D for energy management systems and battery integration to meet Rota 2030 requirements. This defends against pure EV entrants and capitalizes on Brazil's unique biofuel advantage. Expand manufacturing capabilities for high-technology components to reduce reliance on imports and secure competitive positioning.
For New Entrants and Emerging Players:Underpenetrated markets in Brazil's Northeast region represent the most penetrable entry point for new automotive players. Focus on offering robust, affordable vehicles adapted to local road conditions and purchasing power. Develop localized charging solutions or partnerships for hybrid-flex and entry-level electric models. A direct-to-consumer sales model with flexible financing options can gain traction among tech-savvy urban consumers.
For Investors and Strategic Acquirers:Capital is best deployed toward companies specializing in biofuel electrification technology and advanced hybrid-flex powertrain development for long-term viability. Focus on firms with strong R&D capabilities in energy management systems and local component manufacturing for Rota 2030 compliance. Acquisition targets should include established aftermarket service providers offering stable, high-margin revenue streams. The signal to watch is accelerating government incentives for sustainable mobility solutions beyond pure EVs.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces manufacturing complexity and costs across diverse vehicle segments. |
| Battery Supply Agreement | Secures critical components for hybrid and electric vehicle production. |
| Software-Defined Vehicle Investment | Enhances infotainment, safety, and energy management capabilities. |
| Geographic Manufacturing Footprint | Optimizes logistics and market access in key regional hubs. |
| Charging Infrastructure Partnership | Addresses EV adoption barriers and expands customer convenience. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence anchors the qualitative findings. This involved discussions with OEM platform engineers, Tier 1 supplier procurement leads, dealership operations managers, and government regulatory officials. Secondary data sources included INMETRO fuel economy reports, CONTRAN safety standard publications, vehicle production databases, and financial disclosures of key market players. A bottom-up and top-down triangulation approach ensured data accuracy.
Quantitative models were calibrated against historical sales data and industry growth projections across the analysis window. Segmentation dimensions modeled included vehicle class, propulsion architecture, sales channel, and market segment. Compound annual growth rates were derived from a multi-factor regression analysis incorporating economic indicators and regulatory impacts. Key forecast inputs included Rota 2030 investment targets and consumer financing availability.
Macroeconomic conditions sit as an overlay; deviation in interest rates or consumer confidence would shift the trajectory. Forecasts reflect assumptions regarding tax policy stability and infrastructure development. Quarterly review of vehicle registration data and Rota 2030 compliance reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Diesel Engine Management System Market
Powertrain
Automotive Camshaft Market
Powertrain
Global Automotive Fuel Delivery and Injection Systems Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Automotive Driveshaft Couplings Market
Powertrain
Automotive Hydrostatic Fan Drive System Market
Powertrain
Engine Actuators Market
Powertrain
Engine Tuner Market
Powertrain
Small Gas Engine Market
Powertrain
EV Powertrain Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Automotive Turbocharger Market
Powertrain
Emission Control Catalyst for Small Engines Market
Powertrain
Electric Two-Wheeler Powertrain and Range Validation Test Systems Market
Powertrain
Test Automation Systems for Powertrain Dynamometer Market