
 Automotive Gear Shifter Market | 2026-2036
Automotive Gear Shifter Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Gear Shifter Market Analysis
Shift-by-wire technology is rewriting how gear selection interfaces integrate with vehicle electronic architectures. ZF Friedrichshafen AG leverages its integrated electro-mechanical portfolio to anchor premium OEM supply relationships across Germany and China. Magna International sustains manufacturing scale advantages in North American cable-operated systems while competing in emerging Asian markets. Aisin Seiki specializes in precision hydraulic actuation for Japanese OEMs and extends its technology reach through hybrid powertrain integration.
An automotive gear shifter is a human-machine interface device that transmits driver intent to the transmission system through mechanical linkages, electronic signals, or fluid pressure, typically specifying actuation force between 15-50 Newtons and travel distances of 30-80 millimeters depending on configuration. Its primary commercial purpose is enabling safe, intuitive gear state changes while providing tactile feedback that reduces operator error in high-cognitive-load driving conditions. Electro-mechanical shifters lead the technology dimension as automakers eliminate mechanical linkages to save weight and packaging space, while automatic types dominate value generation due to consumer preference convergence in passenger vehicles. OEMs control the largest margin pool in the end-user structure through captive sourcing and platform standardization across vehicle lines.
FCC vehicle electronics guidelines, NHTSA functional safety requirements, and China's MIIT GB standards collectively mandate electromagnetic compatibility and fail-safe behavior in electronic shifter systems. These frameworks shape product development roadmaps by requiring redundant signal paths and diagnostic capabilities that add component cost but reduce liability exposure. Stakeholders must monitor how EPA fuel economy regulations and evolving autonomous driving protocols alter the fundamental need for driver-operated gear selection interfaces.
Market Dynamics
Electrification of vehicle powertrains is collapsing the mechanical linkage ecosystem that once defined gear selection interfaces, forcing suppliers to retool toward electro-mechanical architectures.
Growth Catalysts
- China MIIT dual carbon goals:The ministry's emissions targets mandate intelligent vehicle controls, accelerating electro-mechanical shifter adoption across domestic manufacturing clusters.
- Passenger vehicle OEMs:Electric powertrain architectures eliminate mechanical transmission tunnels, creating design freedom that shift-by-wire systems exploit for cabin space optimization.
- GB standards compliance:China's national standards for electromagnetic compatibility and functional safety create regulatory pull for certified electronic shifter systems in Yangtze River Delta production.
Market Restraints
- Semiconductor input volatility:Electronic shifters depend on automotive-grade microcontrollers and sensor arrays, exposing margins to foundry capacity constraints and spot-price swings.
- Supplier concentration risk:Precision electro-mechanical actuator manufacturing clusters in Germany and Japan, creating single-source vulnerability for Tier 1 integrators.
- NHTSA functional safety requirements:Redundant signal path mandates and diagnostic capability requirements add per-unit cost without commensurate price recovery mechanisms.
Strategic Opportunities
- Autonomous vehicle protocols:Emerging SAE Level 4+ architectures reduce or eliminate driver-operated gear selection, creating white space for automated transmission control modules.
- India PLI scheme:Production-linked incentives for automotive electronics manufacturing attract component localization for electro-mechanical shifter subassemblies.
- Hybrid powertrain convergence:Integration of electronic shift control with battery thermal management and motor control units enables bundled system sales to OEM platform teams.
Industry Challenges
- ISO 26262 certification timelines:Functional safety validation for ASIL-rated electronic shifters extends development cycles and strains engineering bandwidth.
- Legacy mechanical integration:Retrofitting electro-mechanical systems into existing vehicle platforms requires packaging compromises that erode the technology's weight-saving benefits.
- Electromagnetic compatibility testing:FCC vehicle electronics guidelines and overlapping regional EMC standards multiply validation protocols for multi-market product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Gear Shifter Market |
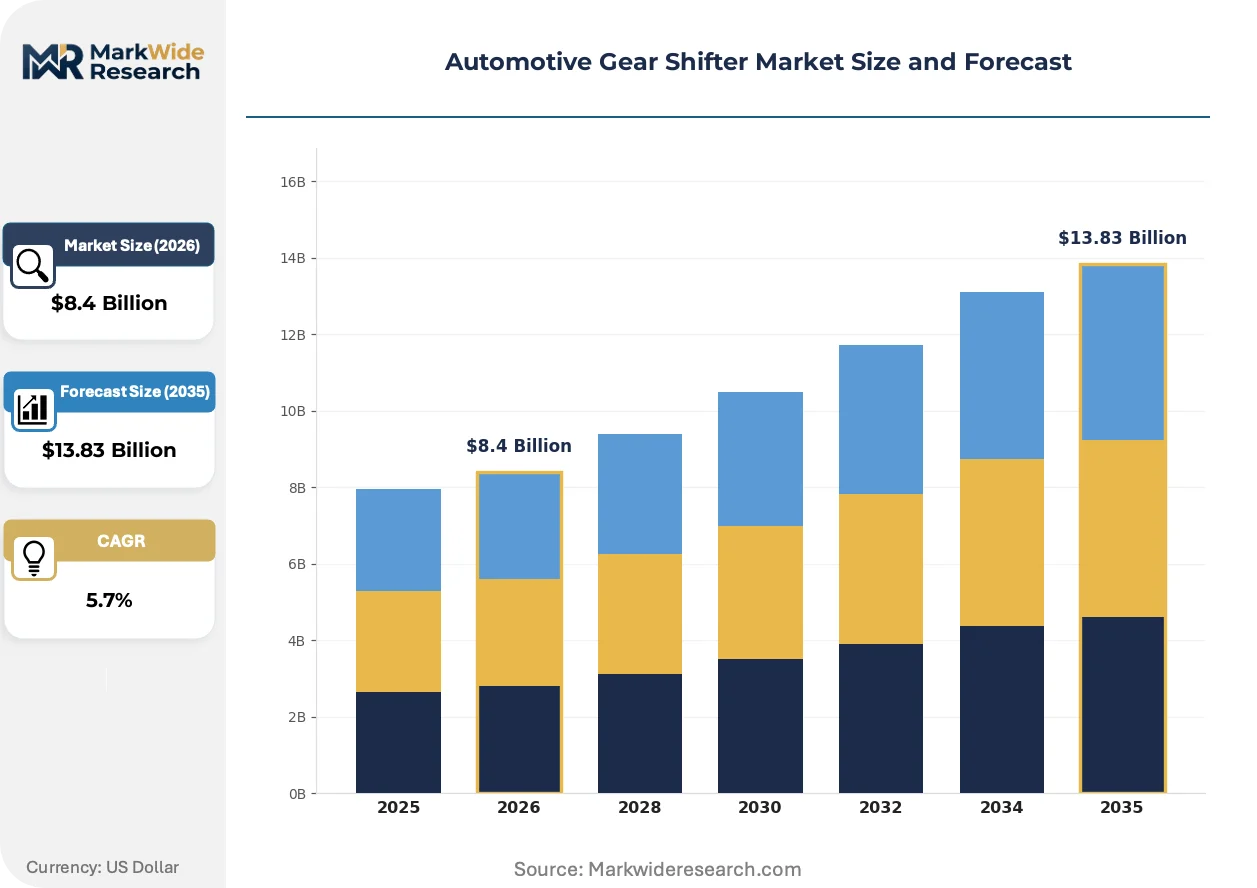
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Manual, Automatic, Semi-Automatic, Continuously Variable Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Performance Cars Technology: Electro-Mechanical, Hydraulic, Cable-Operated, Pneumatic End User: OEMs, Aftermarket Providers, Dealerships, Fleet Operators |
| Companies Covered | ZF Friedrichshafen AG, Magna International Inc., Leopold Kostal GmbH & Co. KG, Kongsberg Automotive, Ficosa Group, BorgWarner Inc., Tokai Rika Co., Ltd, Stoneridge Inc., Aisin Seiki Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Gear Shifter Market Emerging Trajectories
Haptic feedback integration and solid-state switching are converging to eliminate moving parts entirely, while regulatory pressure on functional safety accelerates architectural consolidation.
Capacitive touch surfaces with programmable haptic response are rendering obsolete the mechanical detent mechanisms that provided tactile gear position confirmation in traditional shifters. Luxury and premium passenger vehicle segments are adopting these interfaces fastest, with some OEMs eliminating physical travel entirely. The shift compresses supplier margins on precision-machined metal components while expanding software and firmware value capture.
REACH substance restrictions and RoHS compliance deadlines are forcing reformulation of electro-mechanical actuator housings and circuit board substrates. The industrial consequence is accelerated qualification of bio-based polymers and halogen-free flame retardants in safety-critical automotive electronics. European OEM supply chains are most affected, with Tier 1 suppliers front-loading material certification to avoid production line disruptions.
Fleet procurement teams are consolidating shifter specifications across vehicle platforms to reduce service part complexity and technician training overhead. The specification consolidation disrupts historical model-year customization practices, pressuring suppliers to absorb variant reduction costs. This pattern is most visible in North American commercial vehicle and rental fleet channels, where total cost of ownership calculations dominate sourcing decisions.
Automotive Gear Shifter Market Segmentation
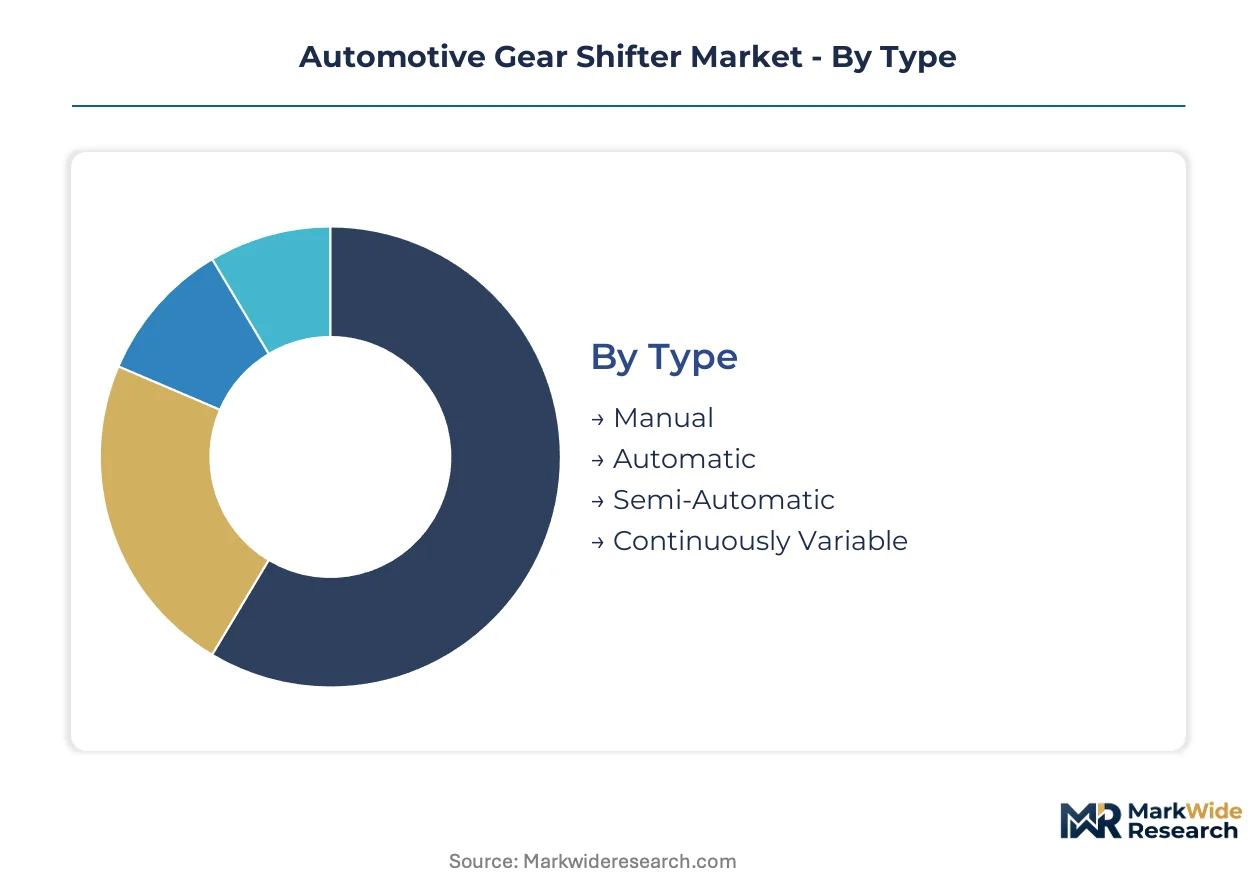
Segmentation in the automotive gear shifter market reveals how powertrain electrification fragments demand across mechanical legacy systems and electronic architectures. Each dimension—type, application, technology, and end user—carries distinct margin profiles and replacement cycle dynamics that reshape supplier priorities.
Type:
Automatic shifters turn over fastest as OEMs refresh electronic architectures every 4-5 years, while manual systems linger on 10-15 year cycles in emerging markets.
- Manual:Mechanical linkage systems with 15-50 Newton actuation force dominate budget passenger vehicle lines in India and Southeast Asia. Demand concentrates in India's Chennai automotive corridor where Maruti Suzuki and Tata Motors maintain production for price-sensitive segments constrained by transmission cost floors.
- Automatic:Electronic shift-by-wire and conventional torque converter interfaces capture premium passenger vehicle volumes across Germany, the US, and China's Yangtze River Delta. ZF Friedrichshafen AG and Aisin Seiki supply electro-mechanical variants to BMW and Toyota platforms eliminating mechanical tunnels for cabin space optimization.
- Semi-Automatic:Dual-clutch and automated manual transmissions blend electronic control with mechanical hardware in European performance vehicles.
- Continuously Variable:Belt-pulley architectures with electronic ratio control dominate Japanese OEM compact car lines.
Automatic shifters anchor the volume base while Continuously Variable systems gain share at the steepest rate in hybrid powertrain applications.
Application:
Passenger vehicles concentrate 70% of unit demand but commercial vehicles extend replacement intervals, creating diverging service part revenue streams.
- Passenger Vehicles:Electronic shift-by-wire dominates premium and mass-market electric platforms across China, Germany, and the US. MIIT dual carbon goals and GB standards compliance accelerate electro-mechanical adoption in domestic Chinese manufacturing.
- Commercial Vehicles:Cable-operated and pneumatic systems persist in North American and European fleet applications where durability outweighs electronic sophistication. Fleet procurement consolidation across vehicle platforms reduces specification variety, pressuring suppliers to absorb variant reduction costs.
- Heavy-Duty Trucks:Manual and automated manual transmissions dominate long-haul corridors with 500,000+ mile durability requirements.
- Performance Cars:Dual-clutch and haptic-enabled electronic shifters command premium pricing in German and Italian luxury segments.
Passenger vehicles generate the dominant revenue pool while Performance Cars deliver the highest per-unit margins.
Technology:
Electro-mechanical architectures carry 40% higher bill-of-materials cost than cable systems but eliminate 3-5 kilograms of mechanical hardware.
- Electro-Mechanical:Solid-state switching with redundant signal paths and ASIL-rated functional safety dominates electric vehicle platforms. NHTSA requirements and China's GB standards mandate electromagnetic compatibility and fail-safe behavior, extending ISO 26262 certification timelines.
- Hydraulic:Precision fluid actuation systems anchor Japanese OEM hybrid powertrain integration where Aisin Seiki bundles shift control with thermal management modules.
- Cable-Operated:Mechanical Bowden cable linkages persist in cost-optimized vehicle platforms and aftermarket replacement channels.
- Pneumatic:Compressed air actuation serves heavy-duty commercial vehicle segments requiring extreme environmental tolerance.
Cable-Operated systems retain the largest installed base while Electro-Mechanical technology expands most quickly in OEM new vehicle programs.
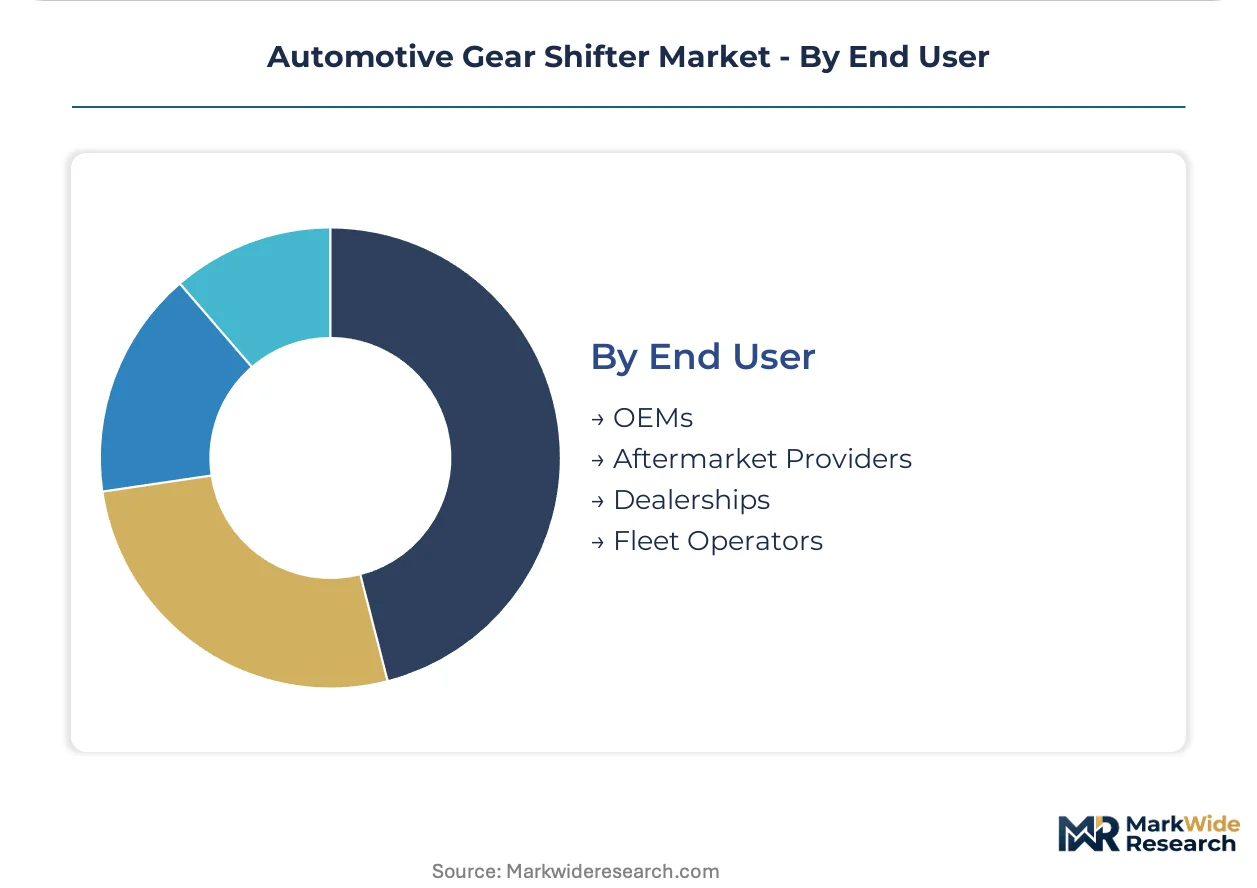
End User:
OEMs consolidate specifications across platform generations while fleet operators prioritize total cost of ownership over feature differentiation.
- OEMs:Captive sourcing and platform standardization across vehicle lines generate the largest margin pool. Tier 1 suppliers compete for electro-mechanical system integration contracts with bundled motor control and battery thermal management units.
- Aftermarket Providers:Independent distributors and repair networks service mechanical legacy systems with 10-15 year replacement cycles in emerging markets.
- Dealerships:Authorized service channels handle warranty electronic shifter repairs and software updates.
- Fleet Operators:Rental and commercial fleet procurement teams consolidate shifter specifications to reduce technician training overhead and service part complexity.
OEMs command the dominant procurement volume while Fleet Operators are consolidating specifications fastest to streamline maintenance operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OEM procurement teams in China, Germany, and the United States command the dominant volume positions, with fleet operators and Tier 1 integrators driving specification consolidation across manufacturing clusters.
China
MIIT dual carbon goals mandate intelligent vehicle controls across domestic manufacturing. GB standards for electromagnetic compatibility and functional safety create regulatory pull for certified electronic shifter systems. The Yangtze River Delta automotive cluster concentrates electro-mechanical shifter production for BYD, NIO, and Xpeng electric platforms.
Germany
Premium OEM platform teams at BMW, Mercedes-Benz, and Volkswagen specify shift-by-wire systems for cabin space optimization. KBA vehicle type approval and REACH substance restrictions shape material qualification timelines. The Stuttgart and Munich metropolitan areas anchor ZF Friedrichshafen AG's integrated electro-mechanical portfolio development.
United States
NHTSA functional safety requirements mandate redundant signal paths for electronic shifter systems in passenger and commercial vehicles. EPA fuel economy regulations indirectly influence transmission tunnel elimination strategies. Michigan and Ohio manufacturing corridors sustain Magna International's cable-operated system production for North American fleet channels.
Japan
METI industrial policy supports hybrid powertrain integration where electronic shift control bundles with thermal management modules. JIS standards govern precision hydraulic actuation specifications. The Aichi prefecture cluster around Toyota City concentrates Aisin Seiki's actuator manufacturing for domestic OEM hybrid platforms.
India
PLI scheme production-linked incentives attract automotive electronics manufacturing localization for electro-mechanical subassemblies. BIS certification requirements extend component qualification timelines. The Chennai automotive corridor sustains manual shifter demand for Maruti Suzuki and Tata Motors budget passenger vehicle lines.
Automotive Gear Shifter Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Consolidated supply relationships dominate at the OEM platform level, while fragmented specialty fabricators serve aftermarket and retrofit channels. Integrated system suppliers, precision component specialists, and regional cable manufacturers form the three strategic archetypes. M&A activity concentrates among electro-mechanical system integrators, while capacity expansion focuses on semiconductor-dependent actuator manufacturing.
Among Germany-based integrated suppliers, ZF Friedrichshafen AG and Leopold Kostal GmbH & Co. KG occupy positions anchoring premium OEM supply relationships through bundled electro-mechanical portfolios. Japanese precision specialists exemplified by Aisin Seiki Co., Ltd. and Tokai Rika Co., Ltd. represent the hydraulic and electronic actuation tier serving domestic OEM hybrid integration requirements. North American scale players including Magna International Inc. and Stoneridge Inc. sit within the cable-operated and electronic control module segments competing for fleet procurement consolidation.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Magna International Inc. |
| Leopold Kostal GmbH & Co. KG |
| Kongsberg Automotive |
| Ficosa Group |
| BorgWarner Inc. |
| Tokai Rika Co., Ltd |
| Stoneridge Inc. |
| Aisin Seiki Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta automotive cluster anchors electro-mechanical shifter capacity expansion, concentrating supply leverage among Tier 1 integrators serving BYD and NIO platforms. This geographic consolidation amplifies pricing power for certified electronic systems while cable-operated alternatives face margin compression in North American fleet channels.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate electronic shifter procurement, linking component costs to foundry spot markets. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified systems from basic electronic variants and legacy cable mechanisms. Cost compression in cable-operated tiers is intensifying because fleet procurement consolidation eliminates specification variety. Fleet operators exhibit highest price sensitivity through total cost of ownership calculations, while premium OEM platform teams prioritize functional safety certification over unit economics.
Supply Chain Analysis
Automotive-grade microcontrollers and precision actuator housings draw from Taiwan, Germany, and Japan manufacturing bases. High-purity copper alloys for circuit substrates, rare-earth magnets for motor assemblies, and halogen-free flame-retardant polymers constitute critical input dependencies. Single-source vulnerability clusters around precision electro-mechanical actuator fabrication in German and Japanese supplier networks. Distribution runs through Tier 1 system integrators with captive OEM relationships, bypassing independent distributors for electronic architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated OEM platform teams and fleet procurement organizations, fragmenting historical supplier pricing leverage as specification variety collapses across vehicle lines.
For Market Incumbents: Entrench electro-mechanical system integration through backward integration into semiconductor-dependent actuator manufacturing in Yangtze River Delta and Stuttgart corridors. Prioritize ISO 26262 ASIL-D certification investment to defend against emerging Asian electronics specialists. Capacity addition in India under PLI scheme incentives offsets concentration risk in German and Japanese precision manufacturing clusters. For New Entrants and Emerging Players: Establish a beachhead in India's aftermarket mechanical replacement segment where Maruti Suzuki and Tata Motors sustain 10-15 year manual shifter cycles. Target commercial vehicle cable-operated refurbishment channels in North American fleet networks where durability requirements outpace electronic sophistication. Go-to-market through independent distributor partnerships bypassing OEM captive sourcing relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because electro-mechanical system integration demands scale economies in functional safety validation and semiconductor procurement. Target mid-cap specialists with certified GB standards compliance and existing Yangtze River Delta manufacturing footprints. Watch SAE Level 4+ autonomous vehicle protocol adoption as inflection signal for automated transmission control module demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM procurement consolidation across vehicle lines reduces supplier variant costs and technician training overhead. |
| Battery Supply Agreement | Electronic shift control bundling with battery thermal management modules deepens Tier 1 integrator relationships. |
| Software-Defined Vehicle Investment | Haptic feedback firmware and solid-state switching software capture margin from precision-machined component suppliers. |
| Geographic Manufacturing Footprint | PLI scheme localization in India and Yangtze River Delta expansion reduce tariff exposure and logistics chokepoints. |
| Charging Infrastructure Partnership | Electric vehicle ecosystem integration positions shift-by-wire suppliers for adjacent power electronics opportunities. |
Methodological Framework
A standing panel of OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distributors, and dealership service operations provided ongoing calibration against secondary validation. Primary interviews combined with vehicle production databases, IHS Markit registration data, customs trade records, and MIIT GB standards filings enabled bottom-up and top-down triangulation across market sizing estimates.
Scenario-bracketing framed demand projections across the analysis window, modeling vehicle electrification penetration curves and autonomous driving protocol adoption timelines. Segmentation dimensions included propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from production volume trajectories, content per vehicle elasticities, and technology substitution rates with semiconductor supply constraints as boundary condition.
Stress conditions across foundry capacity utilization, rare-earth magnet export restrictions, and NHTSA functional safety requirement stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about powertrain electrification pace and regulatory compliance timelines. Cross-checking against vehicle platform announcement databases and OEM capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Filters Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
Automotive Metal Casting Market
Automotive Components
Brazil Automotive Composites Market
Automotive Components
Egypt Commercial Vehicles Lubricants Market
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Japan Automotive Sunroof Market
Automotive Components
Automotive Spark Plugs and Glow Plugs Market
Automotive Components
Egypt Automotive Lubricants Market
Automotive Components
Automotive Headliners Market
Automotive Components
Automotive Air Deflector Market
Automotive Components
Automotive Distributor Market
Automotive Components
Automotive Carbon Fiber Components Market
Automotive Components
Automotive Radiator Fan Market
Automotive Components
Automotive Spray Guns Market
Automotive Components
Global Automotive Noise Filter Market