
 Automotive Metal Casting Market | 2026-2036
Automotive Metal Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Metal Casting Market Analysis
Electric vehicle OEMs is bifurcating demand away from traditional internal combustion engine programs as lightweighting imperatives reshape procurement calendars. Nemak S.A.B. de C.V. anchors its position through captive aluminum smelting and die-casting capacity across Mexico and Europe. GF Casting Solutions differentiates via vacuum-assisted high-pressure die-casting for battery housing enclosures. Rheinmetall Automotive competes on iron-casting scale for commercial vehicle powertrain components, sustaining long-term supply agreements with European truck manufacturers.
Automotive metal casting encompasses the pouring of molten ferrous and non-ferrous alloys into precision molds to produce powertrain, chassis, and structural components with tensile strengths ranging from 150 MPa in gray iron to 340 MPa in A356-T6 aluminum. The process serves as the dominant manufacturing route for engine blocks and transmission housings where net-shape forming minimizes machining waste and cycle cost. Aluminum castings command expanding share in electric vehicle battery trays and motor housings where thermal conductivity and mass reduction intersect. Iron retains dominance in brake components and heavy-duty engine blocks where cost-per-unit and wear resistance override weight targets. Magnesium occupies a narrow but growing niche in steering wheels and seat frames where gram-level savings compound across vehicle platforms.
EPA tailpipe standards, EU CO2 fleet mandates, and China's MIIT dual carbon goals collectively tighten allowable emissions and drive material substitution toward lighter alloys. NHTSA crashworthiness protocols and ECE R94 homologation requirements dictate minimum wall thicknesses and ductility thresholds that constrain foundry process windows. Stakeholders must monitor regulatory divergence between California's Advanced Clean Cars II framework and federal baseline rules, as compliance geography will determine casting alloy specifications and capital allocation priorities.
Market Dynamics
Lightweighting imperatives from electrification are compressing procurement calendars and forcing foundries to retool for thinner-wall, higher-strength aluminum castings. The collision between EPA tailpipe standards and EU CO2 fleet mandates is creating a bifurcated demand landscape where traditional iron-casting capacity faces idling risk.
Growth Catalysts
- EU CO2 fleet mandates:Binding emission targets for passenger car fleets are accelerating aluminum substitution in transmission housings and structural nodes across German and French OEM supply chains.
- High-pressure die-casting:Vacuum-assisted processes for battery tray enclosures are capturing new electric vehicle platform awards from tier-one suppliers co-located with Stuttgart and Munich assembly corridors.
- China MIIT dual carbon goals:Domestic foundries are retooling capacity to serve local electric vehicle motor housing demand, creating alternative supply sources for multinational OEMs.
Market Restraints
- Primary aluminum price volatility:London Metal Exchange pricing swings compress foundry margins and deter long-term contract commitments from risk-averse procurement teams.
- Energy cost concentration:European smelters face structurally higher electricity tariffs versus Middle Eastern and Canadian competitors, eroding cost competitiveness for export-oriented German foundries.
- Gray iron technical ceiling:Tensile strength limitations below 250 MPa prevent material substitution in brake rotors and heavy-duty engine blocks despite weight reduction targets.
Strategic Opportunities
- India PLI scheme for automotive:Component-level incentives are attracting die-casting joint ventures to serve domestic electric vehicle and two-wheeler manufacturers.
- Magnesium steering wheel castings:Gram-level mass savings in interior components compound across vehicle platforms as OEMs pursue aggressive curb weight targets.
- California Advanced Clean Cars II:Stricter state-level mandates create premium pricing corridors for zero-emission vehicle castings that exceed federal baseline specifications.
Industry Challenges
- Tooling engineer scarcity:Multi-cavity die design expertise is concentrating at a handful of specialized firms, extending lead times for new product qualification.
- Heat treatment certification delays:T6 temper qualification for A356 aluminum battery trays requires extended NHTSA crashworthiness validation cycles.
- Legacy ERP integration:Foundry scheduling systems struggle to synchronize with OEM just-in-sequence delivery requirements for mixed powertrain platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Metal Casting Market |
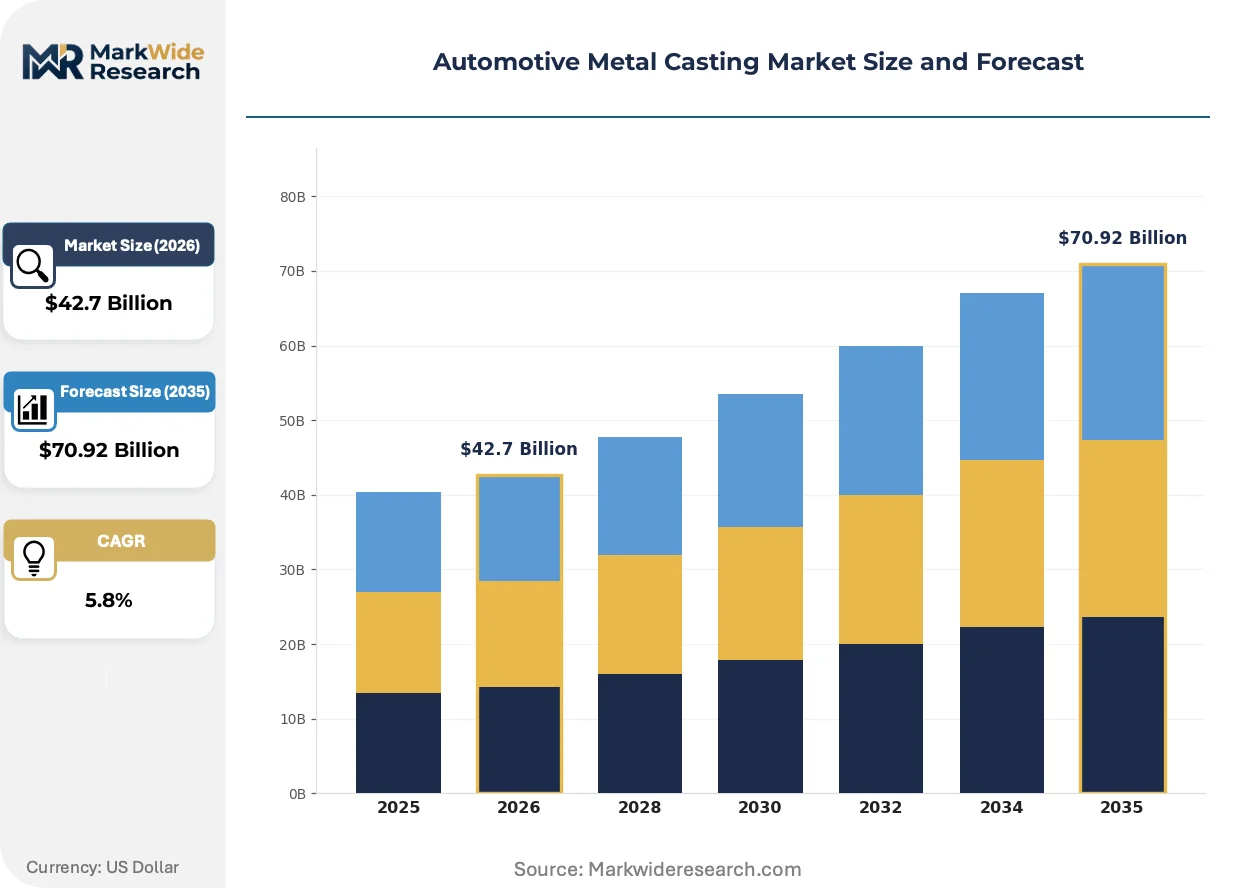
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $70.92 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Blocks, Transmission Housings, Brake Components, Exhaust Manifolds Material: Iron, Aluminum, Magnesium, Titanium Manufacturing Stage: Prototype, Production, Post-Processing, Custom Machining Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Specialty Cars |
| Companies Covered | Nemak S.A.B. de C.V., Ryobi Limited, GF Casting Solutions, Rheinmetall Automotive, Ahresty Corporation, Dynacast, Endurance Technologies Limited, Alcoa Corporation, Precision Castparts Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Metal Casting Market Emerging Trajectories
Process intensification and material science advances are compressing traditional foundry economics while regulatory divergence between jurisdictions fragments standardization efforts. The intersection of thermal management requirements and structural loading is spawning hybrid casting-forging approaches.
Thin-wall high-pressure die-casting for aluminum battery housings is fragmenting the historical separation between structural and thermal management components. Electric vehicle OEMs are consolidating motor, inverter, and battery enclosure sourcing to suppliers capable of integrated thermal-fluid-structural optimization. This convergence is compressing the addressable market for standalone iron foundries while expanding qualification windows for aluminum specialists with captive machining.
REACH substance restrictions on nickel and cobalt compounds are forcing reformulation of high-temperature alloy specifications for exhaust manifolds and turbocharger housings. European foundries face compliance-driven raw material switching costs that Asian competitors circumvent through regulatory arbitrage. The commercial vehicle segment is absorbing the steepest cost increases as heavy-duty engine blocks require elevated temperature resistance that competing materials cannot yet match.
Fleet procurement teams are consolidating casting suppliers to capture volume leverage across electric and internal combustion platform variants. Tier-one suppliers with captive aluminum smelting and in-house tooling design are displacing fragmented merchant foundries from new platform awards. This concentration is most visible in Germany's automotive corridor, where BMW, Mercedes-Benz, and Porsche assembly plants enforce supplier co-location requirements that exclude distant competitors from qualification.
Automotive Metal Casting Market Segmentation
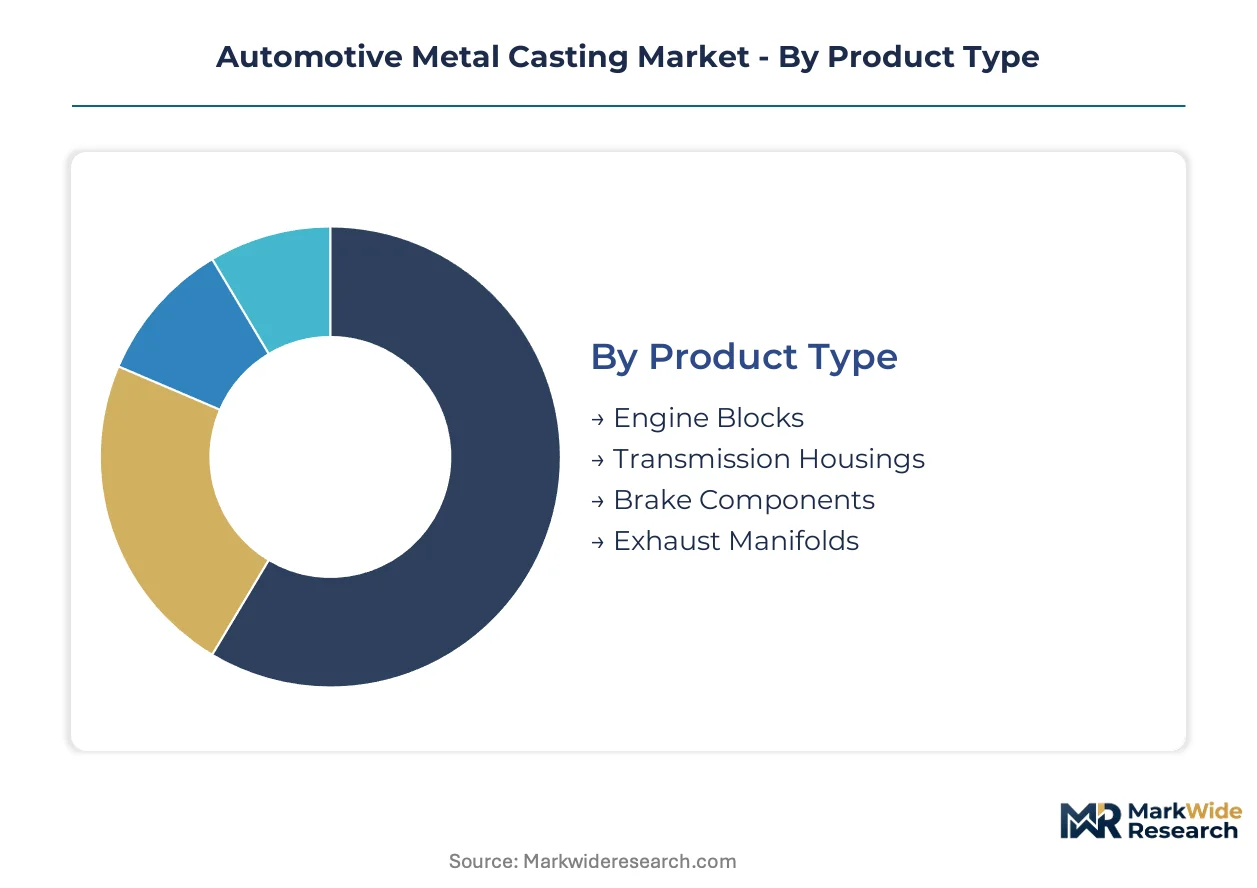
Segmentation in automotive metal casting reveals how procurement channels fragment between legacy powertrain suppliers and emerging electric vehicle specialists. Foundries must align capacity with divergent technical requirements across material grades and manufacturing stages.
Product Type:
Channel flow splits between tier-one suppliers serving German OEMs and merchant foundries supplying aftermarket distributors, with co-location requirements dictating qualification access.
- Engine Blocks:Gray and compacted graphite iron formulations dominate heavy-duty commercial applications where wear resistance trumps mass reduction. Demand concentrates in Stuttgart and Munich corridors where BMW, Mercedes-Benz, and Porsche enforce supplier proximity for just-in-sequence delivery.
- Transmission Housings:A356-T6 aluminum alloys with vacuum-assisted high-pressure die-casting enable wall thickness below 3 millimeters for electric vehicle platforms. Procurement calendars compress as OEMs consolidate motor and gearbox enclosure sourcing to integrated thermal-structural suppliers.
- Brake Components:Vermicular graphite iron retains cost advantage in rotor applications despite weight targets.
- Exhaust Manifolds:High-silicon molybdenum grades face REACH-driven nickel reformulation costs.
Engine blocks dominate installed base. Transmission housings are where expansion concentrates.
Material:
Cost tier stratification separates commodity ferrous alloys from premium non-ferrous grades with divergent margin profiles and capital intensity requirements.
- Iron:Gray, ductile, and compacted graphite variants sustain brake rotor and heavy-duty engine block demand where tensile strength requirements exceed 300 MPa. European foundries face structural electricity cost disadvantages versus Middle Eastern smelters.
- Aluminum:A356, A380, and Silafont-36 alloys capture battery tray and motor housing awards through thermal conductivity and corrosion resistance. China's MIIT dual carbon goals accelerate domestic foundry retooling for electric vehicle motor housing demand.
- Magnesium:AZ91D and AM60B grades occupy steering wheel and seat frame niches where gram-level savings compound.
- Titanium:Ti-6Al-4V castings serve exhaust valve and connecting rod applications in specialty powertrains with extreme temperature requirements.
Iron commands volume share. Aluminum is climbing the fastest on electric vehicle platform penetration.
Manufacturing Stage:
Customer type segmentation separates captive in-house foundries from merchant suppliers with divergent qualification timelines and intellectual property exposure.
- Prototype:Sand casting and investment casting methods enable design iteration for new platform development with lead times under six weeks. Tooling engineer scarcity concentrates multi-cavity die design expertise at specialized firms in Germany and Japan.
- Production:High-pressure die-casting and permanent mold gravity casting scale to annual volumes exceeding 500,000 units for transmission housings. GF Casting Solutions and Nemak anchor capacity through captive aluminum smelting across Mexico and Europe.
- Post-Processing:T6 heat treatment, shot peening, and impregnation operations qualify A356 battery trays for NHTSA crashworthiness protocols.
- Custom Machining:Five-axis CNC finishing integrates with casting cells to deliver net-shape transmission housings to BMW and Porsche assembly plants.
Production stage captures revenue concentration. Prototype services are gaining share fastest on electric vehicle platform proliferation.
Application:
Geography-maturity segmentation aligns foundry certification requirements with regulatory divergence between EPA tailpipe standards and EU CO2 fleet mandates.
- Passenger Vehicles:Aluminum substitution accelerates in C-segment and above where CO2 fleet penalties exceed material cost premiums. German OEM procurement teams consolidate casting suppliers to capture volume leverage across platform variants.
- Commercial Vehicles:Iron-casting scale sustains long-term supply agreements with European truck manufacturers for engine blocks and brake components. Rheinmetall Automotive competes on foundry capacity serving MAN and Scania powertrain programs.
- Electric Vehicles:Battery tray, motor housing, and inverter enclosure demand requires integrated thermal-fluid-structural optimization capabilities. Tier-one suppliers with captive machining displace fragmented merchant foundries from new platform awards.
- Specialty Cars:Low-volume titanium and magnesium applications serve motorsport and luxury segments with tolerance for premium pricing.
Passenger vehicles anchor volume. Electric vehicles represent the steepest expansion trajectory as powertrain architectures consolidate enclosure sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity clusters around automotive assembly corridors where supplier co-location requirements enforce geographic proximity. Germany's Stuttgart-Munich corridor anchors European demand for precision aluminum transmission housings. China's Yangtze River Delta and Mexico's Bajío region compete for export-oriented die-casting investment.
Germany
BMW, Mercedes-Benz, and Porsche procurement teams consolidate transmission housing awards to tier-one suppliers with captive machining. EU CO2 fleet mandates accelerate aluminum substitution in powertrain enclosures. Baden-Württemberg foundries retool for vacuum-assisted high-pressure die-casting to serve electric vehicle platform launches.
China
Domestic electric vehicle OEMs drive motor housing demand through integrated thermal-structural specifications. MIIT dual carbon goals force foundry energy efficiency upgrades and scrap aluminum utilization targets. Yangtze River Delta die-casters expand capacity to serve Tesla, BYD, and NIO assembly plants in Shanghai and Hefei.
United States
EPA tailpipe standards and California's Advanced Clean Cars II framework create divergent compliance corridors for casting alloy specifications. Detroit Three procurement teams prioritize domestic sourcing for heavy-duty engine blocks and commercial vehicle brake components. Southeast states attract aluminum smelting investment through electricity cost advantages versus Midwest legacy foundries.
Mexico
Nearshoring momentum concentrates die-casting investment in Nuevo León and Guanajuato to supply US electric vehicle assembly. Nemak anchors captive aluminum smelting capacity across multiple Bajío facilities. USMCA rules of origin requirements favor integrated casting-machining operations over pure toll processing.
India
PLI scheme incentives attract joint ventures for two-wheeler and electric vehicle die-casting components. Domestic foundries face technical gaps in thin-wall high-pressure die-casting for battery trays. Tamil Nadu and Maharashtra clusters serve Maruti Suzuki, Tata Motors, and Mahindra powertrain programs with iron-casting scale.
Automotive Metal Casting Market Vendor Landscape
Concentration sits with tier-one suppliers possessing captive aluminum smelting and in-house tooling design capabilities. Merchant foundries without machining integration face displacement from new electric vehicle platform awards. Two archetypes dominate: integrated thermal-structural specialists and iron-casting scale players serving commercial vehicle long-cycle agreements. Competitive moves center on co-location compliance with German OEM corridor requirements and backward integration into primary aluminum supply.
Among North American aluminum specialists, Alcoa Corporation anchors primary metal supply leverage that downstream fabricators struggle to replicate. Precision Castparts Corp. occupies a position in precision investment casting for aerospace-adjacent automotive applications. Rheinmetall Automotive exemplifies the iron-casting scale archetype through long-term supply agreements with European truck manufacturers. These three represent divergent capability stacks rather than direct segment overlap.
| Leading Market Players |
|---|
| Nemak S.A.B. de C.V. |
| Ryobi Limited |
| GF Casting Solutions |
| Rheinmetall Automotive |
| Ahresty Corporation |
| Dynacast |
| Endurance Technologies Limited |
| Alcoa Corporation |
| Precision Castparts Corp. |
| Others |
Supply Flow & Price Mechanics
Aluminum substitution for gray iron in transmission housings simultaneously redraws raw material sourcing maps and compresses foundry margin structures as procurement teams renegotiate long-term contracts around London Metal Exchange volatility. EU CO2 fleet mandates and EPA tailpipe standards bifurcate alloy specifications, forcing tier-one suppliers to maintain dual pricing tiers for identical component geometries.
Pricing Analysis
EU CO2 fleet mandates dictate the pricing tier structure across European automotive corridors, separating premium vacuum-assisted die-cast transmission housings from standard gravity-cast alternatives. Price differentiation rests on T6 temper certification and wall-thickness tolerances below three millimeters. Cost compression in standard-grade iron castings is intensifying because European smelters face structurally higher electricity tariffs versus Middle Eastern competitors. Aftermarket distributors exhibit the highest price sensitivity, while German OEM procurement teams prioritize qualification speed over unit cost.
Supply Chain Analysis
Germany and China anchor primary aluminum smelting and precision die-casting capacity for automotive transmission housings and battery enclosures. Raw material flows draw from bauxite refining concentrated in Australia and Guinea, with secondary scrap aluminum feeding Chinese MIIT-mandated recycling targets. Single-source vulnerability concentrates in specialized tooling engineer pools concentrated at German and Japanese multi-cavity die design firms. Distribution runs through tier-one supplier co-location clusters surrounding Stuttgart, Munich, and Shanghai assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive metal casting sits in early-cycle expansion as electric vehicle platform launches accelerate procurement calendars for thin-wall aluminum structural components. Penetration of vacuum-assisted high-pressure die-casting for battery trays is climbing fastest among tier-one suppliers with captive machining integration.
For Market Incumbents: Fortify backward integration into primary aluminum supply to offset London Metal Exchange volatility and secure long-term contract competitiveness against Middle Eastern smelters. Expand captive tooling design capacity in Germany's automotive corridor to compress qualification timelines for new electric vehicle platform awards. Rheinmetall Automotive's iron-casting scale model offers defensive positioning against aluminum substitution in commercial vehicle powertrains. For New Entrants and Emerging Players: T6 temper certification fast-tracks for A356 aluminum battery trays unlock qualification access to BMW and Porsche supply chains where incumbent capacity constraints extend lead times. Target India's PLI scheme corridors for two-wheeler and entry electric vehicle die-casting joint ventures where technical gaps in thin-wall processing persist among domestic foundries. Pursue integrated thermal-structural optimization capabilities as the primary go-to-market differentiator against fragmented merchant foundries. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed tier-one suppliers possessing captive aluminum smelting but lacking electric vehicle platform qualification momentum. Five-to-ten year viability favors integrated specialists over standalone iron foundries facing demand erosion from powertrain electrification. Monitor NHTSA crashworthiness validation cycle completion rates for A356 battery tray programs as the inflection signal for capacity utilization recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aluminum Smelting Expansion | Mitigates London Metal Exchange volatility for European foundries serving BMW and Mercedes-Benz procurement. |
| Vacuum-Assisted High-Pressure Die-Casting Scale-Up | Enables wall-thickness below three millimeters for electric vehicle battery tray enclosures. |
| Multi-Cavity Die Design Capability Acquisition | Compresses tooling engineer scarcity bottlenecks extending new product qualification timelines. |
| Co-Location Manufacturing Footprint | Satisfies just-in-sequence delivery requirements enforced by Porsche and Audi assembly plants. |
| T6 Heat Treatment Certification Investment | Qualifies A356 aluminum castings for NHTSA crashworthiness protocols in battery housing applications. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and vehicle production databases. Primary interviews engaged tier-one supplier procurement directors, OEM platform engineers, foundry operations managers, and aftermarket distribution channel heads. Secondary validation drew from EPA emission standard updates, EU CO2 fleet mandate documentation, MIIT dual carbon policy circulars, and IHS Markit vehicle registration data. Bottom-up casting volume estimates triangulated against top-down automotive production forecasts.
Segmentation dimensions modeled include material grade, manufacturing stage, vehicle propulsion architecture, and regional production cluster across the projection horizon. CAGRs derived from regression analysis of historical capacity utilization, platform launch calendars, and alloy substitution elasticities. Industry-specific forecast inputs incorporated electric vehicle motor housing content-per-vehicle trajectories and REACH-driven nickel reformulation cost pass-through assumptions.
Decision-makers should treat outputs as directional under stable regulatory enforcement of EU CO2 fleet mandates and EPA tailpipe standards; material deviation in compliance timelines or aluminum price volatility spikes would warrant model refresh. Specific risks include NHTSA crashworthiness protocol revisions, European electricity tariff restructuring, and China MIIT scrap aluminum utilization mandate tightening. Recalibration cycles align with material shifts in electric vehicle platform launch schedules and primary aluminum supply contract renewal windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Sun Visor Market
Automotive Components
Alloys for Automotive Market
Automotive Components
Casted Automotive Components Market
Automotive Components
Automotive Bearing Market
Automotive Components
Automotive Backing Plate Market
Automotive Components
Germany Automotive Composites Market
Automotive Components
Automotive Rear End Module Market
Automotive Components
India Automotive Sunroof Market
Automotive Components
Automotive Exhaust Manifolds Market
Automotive Components
GCC Automotive Lubrication Services Market
Automotive Components
Italy Automotive Sunroof Market
Automotive Components
Automobile AC Condensers Market
Automotive Components
Sheet Molding Compound (SMC) for Automotive Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Automated Lubrication Systems Market
Automotive Components
Automotive Light Bars Market