
 Hydraulic Marine Cranes Market | 2026-2036
Hydraulic Marine Cranes Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Marine Cranes Market Analysis
Capital-intensity divergence between custom-engineered heavy-lift specialists and standardized crane assemblers is unwinding competitive tiers across the sector. Huisman Equipment B.V. leverages in-house steel fabrication and hydraulic system integration to dominate bespoke offshore crane contracts. Liebherr-International AG sustains global service density through regionally stocked spare-part depots and certified technician networks. PALFINGER AG competes aggressively in the mid-duty harbor crane segment with modular platform supply strategies.
Hydraulic marine cranes are deck-mounted lifting machines powered by closed-loop hydraulic circuits typically operating at pressures between 250 and 450 bar, engineered to withstand salt-laden atmospheres, vessel motion dynamics, and cyclic loading regimes in open-water environments. Telescopic cranes occupy the largest product category due to their deployment across offshore supply vessels requiring variable outreach with minimal deck footprint. Knuckle boom cranes represent the fastest-expanding product type as offshore platforms adopt articulated geometries for congested deck layouts where vertical lift paths avoid interference with process equipment. Shipyards constitute the most concentrated end-user segment for newbuild crane procurement, while port authorities drive aftermarket refurbishment demand.
Classification regimes including DNV-ST-E273, ABS Guide for Certification of Lifting Appliances, and Lloyd's Register Code for Lifting Appliances mandate proof-load testing, fatigue-life documentation, and material-traceability protocols that extend procurement cycles and elevate engineering costs. The EU Machinery Directive and ISO 4301-4 harmonize safety-rated load indicators and emergency shutdown architectures across European-flagged fleets. Stakeholders must monitor evolving offshore wind turbine installation specifications, as next-generation jack-up vessels demand cranes with integrated personnel-lift certification and active heave compensation.
Market Dynamics
Offshore wind turbine installation specifications are forcing crane manufacturers to integrate active heave compensation and personnel-lift certification into heavy-lift hydraulic systems, compressing development cycles for jack-up vessel fleets.
Growth Catalysts
- DNV-ST-E273 certification mandates:Classification society tightening of fatigue-life documentation and material-traceability protocols is extending replacement demand for aging North Sea crane fleets.
- Subsea construction activity:Decommissioning of mature offshore platforms in Norway's North Sea cluster requires heavy-lift hydraulic marine cranes with extended outreach capabilities for module removal.
- Closed-loop hydraulic circuits:Operating pressure advances to 450 bar enable lighter boom structures without sacrificing lift capacity, reducing vessel deck loading constraints.
Market Restraints
- High-grade alloy steel volatility:Specialized marine-grade structural steel supply concentrates among Scandinavian and Japanese mills, exposing fabricators to input cost swings.
- Proof-load testing bottlenecks:ABS and Lloyd's Register certification queues extend procurement cycles by 4-8 months for custom-engineered heavy-lift units.
- Electromechanical substitution:All-electric deck cranes are penetrating harbor and near-shore segments where duty cycles permit battery-buffered operation without hydraulic infrastructure.
Strategic Opportunities
- Floating offshore wind installation:Pre-assembly of turbine components at portside marshalling yards creates demand for knuckle boom cranes with integrated spreader-bar quick-change systems.
- EU Green Deal vessel retrofit incentives:Harbor crane electrification subsidies in German and Dutch ports are accelerating replacement of aging hydraulic harbor units with hybrid-electric alternatives.
- Digital twin convergence:Integration of IoT load monitoring with predictive maintenance algorithms enables crane-as-a-service revenue models for offshore platform operators.
Industry Challenges
- Certified hydraulic technician scarcity:Specialized skills for maintaining 450 bar closed-loop systems at sea command premium wages, constraining fleet availability for remote platform operations.
- Legacy ABS certification reconciliation:Retrofitting active heave compensation onto existing crane foundations requires structural recertification that conflicts with original design assumptions.
- Spare part harmonization:Proprietary hydraulic manifold designs across OEMs fragment aftermarket inventory, forcing operators to maintain multiple supplier relationships for single-vessel fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Marine Cranes Market |
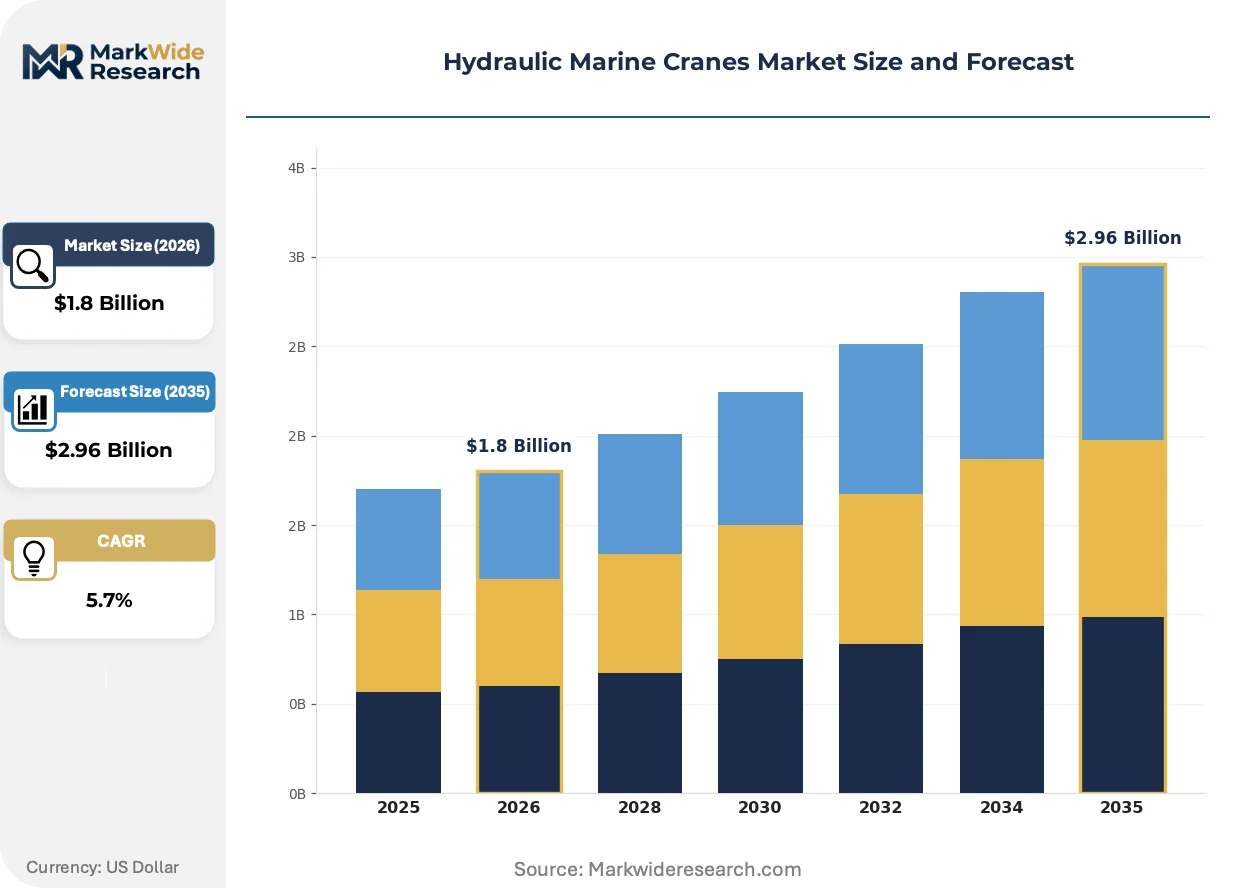
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telescopic Cranes, Knuckle Boom Cranes, Gantry Cranes, Fixed Cranes End User: Shipping Companies, Offshore Platforms, Shipyards, Port Authorities Technology: Hydraulic Systems, Electrical Systems, Tele-Operated Systems, Hybrid Systems Application: Lifting Operations, Cargo Handling, Maintenance Tasks, Barge Operations |
| Companies Covered | Heila Cranes Ltd., Kenz Figee, Cargotec Corporation (MacGregor), Seatrax Inc., PLM Cranes B.V., PALFINGER AG, Huisman Equipment B.V., NOV INC., Liebherr-International AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Marine Cranes Market Emerging Trajectories
Active heave compensation technology is migrating from optional upgrade to baseline specification, reshaping engineering priorities across offshore crane procurement. Three developments are compressing competitive differentiation.
Electro-hydraulic hybrid drive architectures are supplanting conventional fixed-displacement pump systems in newbuild jack-up vessels. Offshore wind turbine installation contractors in the North Sea and Baltic markets specify these configurations for precision load positioning during nacelle mating operations. The technology is compressing allowable sea-state windows, enabling year-round installation campaigns that previously halted in winter months.
The EU Machinery Directive harmonization with ISO 4301-4 is mandating safety-rated load indicators and emergency shutdown architectures across European-flagged fleets. Fabricators serving this market must redesign control system architectures to achieve SIL 2 functional safety ratings. Harbor crane segments in Rotterdam and Hamburg are experiencing accelerated replacement cycles as port authorities enforce the updated certification timelines.
Platform operators are unbundling after-sales service contracts from initial crane procurement, selecting third-party maintenance providers based on regional technician density rather than OEM affiliation. Offshore supply vessel fleets in the Norwegian sector are driving this fragmentation, negotiating separate agreements for hydraulic system overhaul versus structural inspection. The practice is most visible among mid-size vessel operators seeking to reduce total cost of ownership across diversified crane fleets.
Hydraulic Marine Cranes Market Segmentation
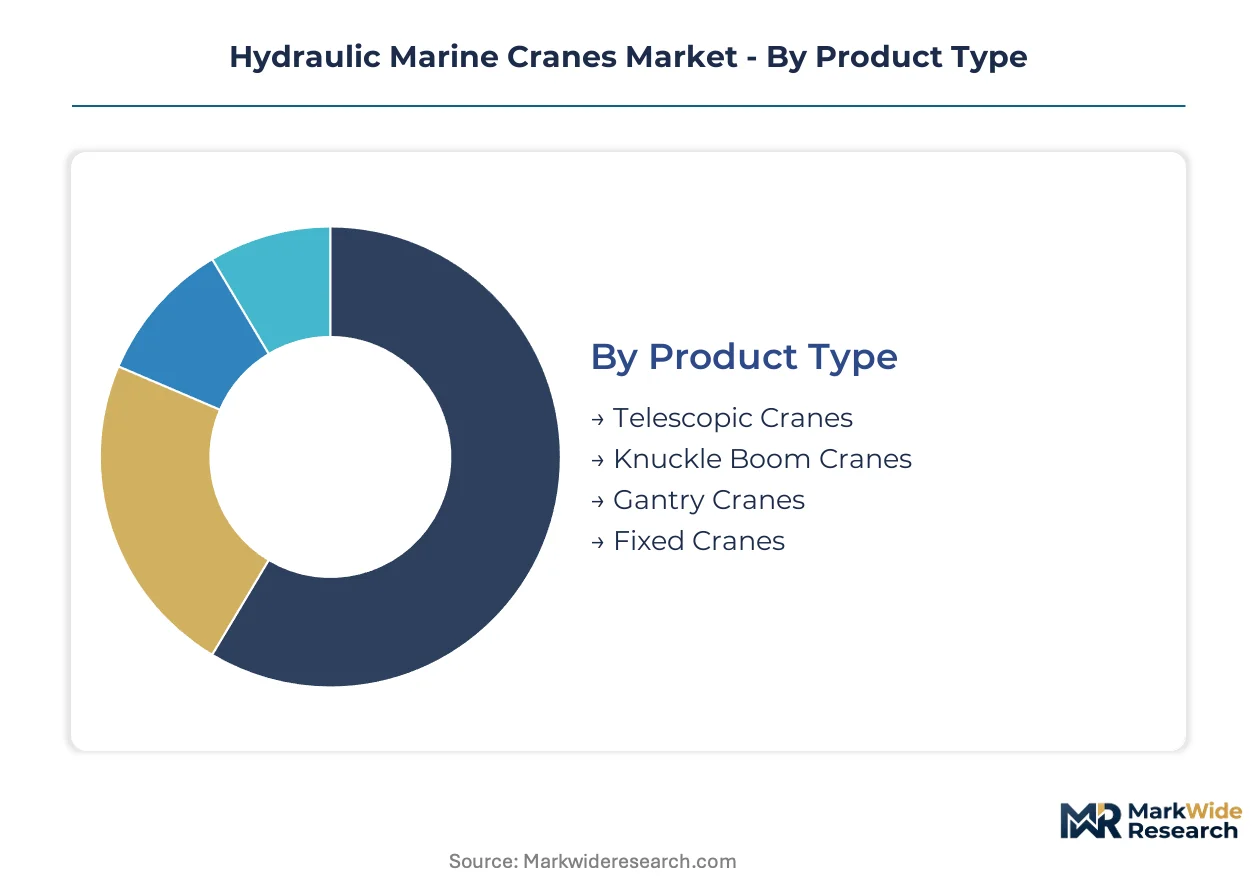
Hydraulic marine crane procurement varies sharply by operational environment, with offshore wind installation contractors demanding active heave compensation while harbor operators prioritize cycle speed. Segmentation reveals where engineering premiums concentrate versus where standardized units compete on cost.
Product Type:
Margin pools concentrate in articulated boom geometries where active heave compensation integration commands pricing premiums over fixed structures.
- Telescopic Cranes:These units deploy nested boom sections extending via hydraulic cylinders to achieve variable outreach with minimal deck footprint. Offshore supply vessels operating in Norway's North Sea cluster specify telescopic configurations for subsea construction support where deck space constraints intersect with heavy-lift requirements. The segment captures the largest installed base across platform supply vessel fleets.
- Knuckle Boom Cranes:Articulated joint geometries enable vertical lift paths that avoid interference with crowded process equipment on offshore platforms. Decommissioning contractors in the North Sea favor knuckle boom units for module removal operations requiring precise load positioning around existing infrastructure. This configuration is climbing the fastest in newbuild specifications for floating offshore wind installation vessels.
- Gantry Cranes:Rail-mounted portal structures span vessel beams or quayside installations for containerized cargo transfer. Rotterdam and Hamburg port authorities deploy gantry systems for harbor bulk handling where throughput volume justifies fixed infrastructure investment.
- Fixed Cranes:Single-pedestal structures with limited slew range serve dedicated lifting stations on offshore platforms. These units dominate legacy platform installations where replacement cycles extend due to foundation recertification costs.
Telescopic cranes hold installed capacity. Knuckle boom cranes are rotating up the share rankings.
End User:
Procurement patterns split between capital-intensive newbuild programs and maintenance-driven replacement cycles.
- Offshore Platforms:Fixed and floating production facilities require heavy-lift units certified for personnel transfer and subsea equipment deployment. Norwegian platform operators in the North Sea cluster are expanding crane fleets to service deeper-water installations, with classification society mandates from DNV and ABS extending replacement demand for aging units. This segment commands the highest engineering premiums.
- Shipyards:Newbuild construction facilities specify multiple crane types across vessel assembly sequences, from module lifting to outfitting operations. South Korean and Chinese shipyards drive volume procurement for commercial vessel construction programs.
- Shipping Companies:Container and bulk carriers install deck cranes for cargo handling at ports lacking shore infrastructure. Greek and Danish shipping lines prioritize standardized units with global service network coverage.
- Port Authorities:Municipal and regional harbor operators manage crane fleets for commercial cargo transfer, with EU Green Deal subsidies in German and Dutch ports accelerating hybrid-electric replacements of aging hydraulic harbor units.
Shipyards dominate newbuild procurement volume. Port authorities are expanding fastest in electrification-driven replacement cycles.
Technology:
Power system architecture determines maintenance burden and regulatory compliance pathways across operating environments.
- Hydraulic Systems:Closed-loop circuits operating at 250-450 bar deliver the power density required for heavy-lift marine applications. DNV-ST-E273 certification mandates for fatigue-life documentation and material-traceability protocols extend procurement cycles for these systems in North Sea operations.
- Hybrid Systems:Electro-hydraulic architectures combine battery buffering with hydraulic actuation to reduce fuel consumption during low-load cycles. Baltic and North Sea offshore wind contractors specify hybrid configurations for jack-up vessels to enable year-round installation campaigns.
- Electrical Systems:All-electric deck cranes penetrate harbor and near-shore segments where duty cycles permit battery-buffered operation without hydraulic infrastructure maintenance.
- Tele-Operated Systems:Remote-controlled units enable personnel removal from hazardous lifting zones, with EU Machinery Directive harmonization mandating SIL 2 functional safety ratings for control architectures.
Hydraulic systems retain the dominant installed base. Hybrid systems are expanding most quickly in offshore wind vessel specifications.
Application:
Operational intensity and certification requirements create divergent equipment specifications across use cases.
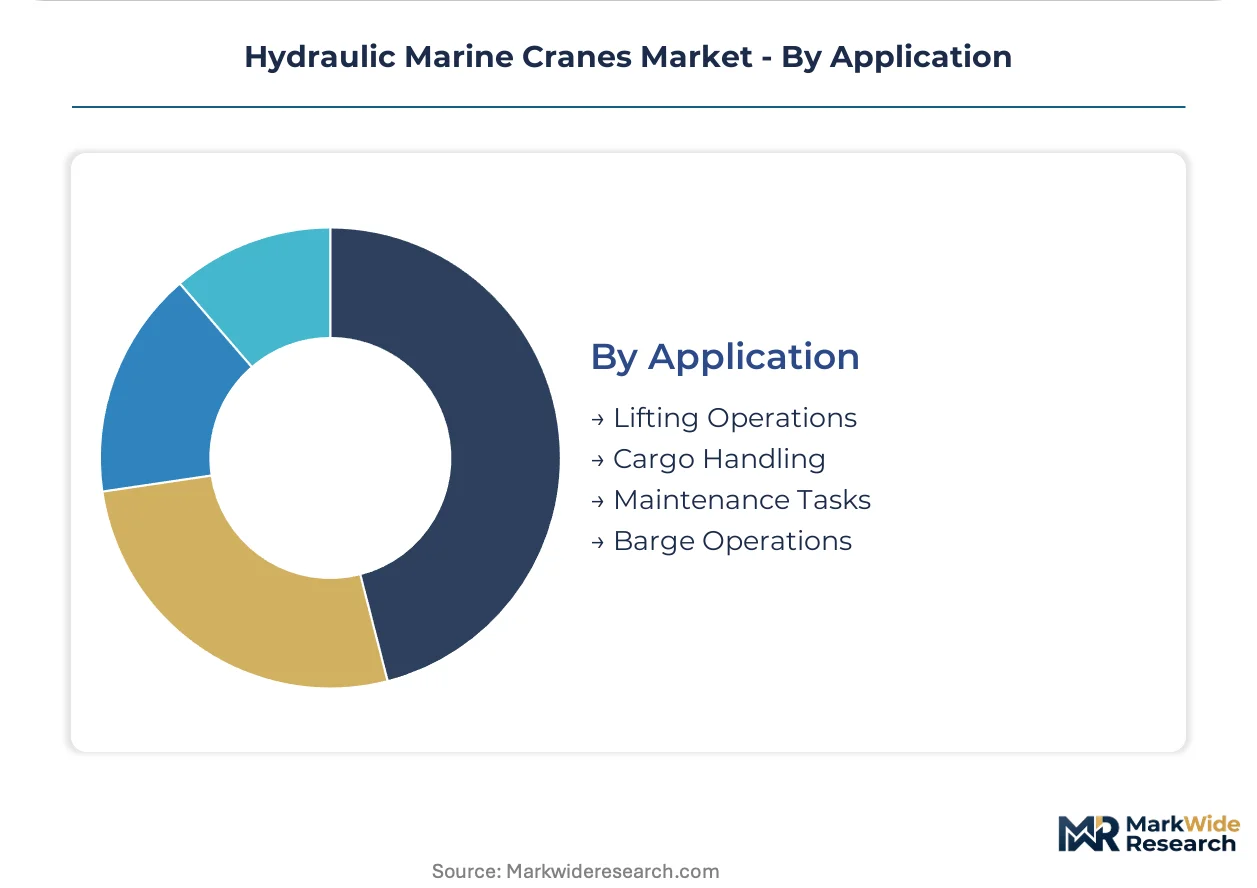
- Lifting Operations:General cargo and equipment hoisting constitutes the core function across all crane deployments, with load rating and outreach specifications varying by vessel type and operational depth.
- Cargo Handling:Container and bulk transfer operations at ports and aboard vessels demand high-cycle reliability and rapid load positioning. Harbor crane segments in Rotterdam enforce updated EU Machinery Directive certification timelines.
- Maintenance Tasks:Platform equipment servicing and vessel repair operations require precise load control and personnel-lift certification. Norwegian offshore supply vessel fleets unbundle after-sales service contracts from initial procurement for these applications.
- Barge Operations:Lighterage and cargo transfer between vessels and barges in open water conditions demand stabilized load handling. Active heave compensation technology is migrating from optional upgrade to baseline specification for this application.
Cargo handling commands the largest equipment population. Maintenance tasks are rotating up the share rankings as platform decommissioning accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-heavy fabrication economies run persistent trade surpluses in hydraulic marine crane components, while import-dependent offshore operators in the North Sea and Gulf of Mexico absorb the majority of finished-system deliveries. Scandinavian and German fabricators dominate high-grade alloy steel crane exports. Asian shipyards drive standardized unit procurement for newbuild commercial fleets.
Norway
Subsea construction and platform decommissioning in the North Sea cluster demands heavy-lift units with extended outreach capabilities. DNV-ST-E273 certification mandates from the classification society extend replacement cycles for aging offshore crane fleets. Stavanger and Bergen anchor the country's offshore equipment engineering concentration, with operators expanding crane fleets to service deeper-water installations.
Germany
Harbor crane electrification subsidies under the EU Green Deal accelerate hybrid-electric replacements of aging hydraulic units in Rotterdam-adjacent logistics corridors. KBA and federal maritime regulators enforce updated EU Machinery Directive timelines for SIL 2 functional safety ratings. Hamburg and Bremerhaven port authorities drive aftermarket refurbishment demand with concentrated fleet modernization programs.
United States
Gulf of Mexico offshore platform operators expand crane fleets to service deeper-water installations in federally leased blocks. ABS Guide for Certification of Lifting Appliances mandates proof-load testing queues that extend procurement cycles for custom-engineered units. Houston anchors the domestic offshore equipment procurement cluster, with engineering offices concentrated in the Energy Corridor.
China
State-owned shipyards drive volume procurement for commercial vessel construction programs with standardized crane specifications. MIIT and GB standards harmonize with ISO 4301-4 for export-oriented manufacturing. Shanghai and Dalian anchor the country's marine crane fabrication concentration, with Yangtze River Delta yards specifying modular platform supply strategies.
Netherlands
EU Green Deal vessel retrofit incentives accelerate harbor crane replacement cycles in Europe's largest port complex. Rotterdam port authorities enforce updated EU Machinery Directive certification timelines for safety-rated load indicators. The Randstad logistics corridor concentrates demand for knuckle boom cranes with integrated spreader-bar quick-change systems for offshore wind component marshalling.
Hydraulic Marine Cranes Market Vendor Landscape
Concentration sits with diversified industrial conglomerates and specialized offshore fabricators rather than standardized crane assemblers. The vendor base splits between premium-tier custom-engineering specialists and mid-duty modular platform suppliers. Two strategic archetypes dominate: vertically integrated steel fabricators with in-house hydraulic system integration, and global service-network operators sustaining regional spare-part density. Competitive moves center on certification queue management and technician network expansion rather than price-based rivalry.
Within the premium-tier custom-engineering segment, Huisman Equipment B.V. and Liebherr-International AG occupy positions defined by divergent capability emphases. Huisman exemplifies the vertically integrated archetype through captive steel fabrication and hydraulic system integration. Liebherr represents the global service-density model with regionally stocked spare-part networks. PALFINGER AG sits within the mid-duty modular segment, competing on platform supply standardization rather than bespoke engineering. These three anchors illustrate how competitive positioning fragments across certification grade, service reach, and production integration rather than converging on single-factor dominance.
| Leading Market Players |
|---|
| Heila Cranes Ltd. |
| Kenz Figee |
| Cargotec Corporation (MacGregor) |
| Seatrax Inc. |
| PLM Cranes B.V. |
| PALFINGER AG |
| Huisman Equipment B.V. |
| NOV INC. |
| Liebherr-International AG |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Norwegian offshore platform operators and Scandinavian steel mills lock in both high-grade alloy supply access and price visibility for heavy-lift hydraulic marine crane fabricators. These arrangements insulate custom-engineering specialists from spot market volatility in marine-grade structural steel while committing buyers to minimum volume thresholds that sustain mill utilization.
Pricing Analysis
Industrial OEM buyers anchor a project-based pricing structure where unit quotations span six-figure to eight-figure ranges depending on certification grade and active heave compensation integration. Three-tier pricing structure across premium, standard, and economy levels separates DNV-ST-E273 certified heavy-lift units from ABS-compliant mid-duty cranes and harbor-standardized alternatives. Pricing pressure stems from electromechanical substitution in near-shore segments where battery-buffered all-electric cranes underbid hydraulic equivalents on total cost of ownership. Port authorities and mid-size vessel operators exhibit highest price sensitivity, while North Sea platform operators prioritize certification compliance over capital expenditure minimization.
Supply Chain Analysis
Strategic stockpiling of specialized marine-grade alloy steel dominates inventory strategy among Scandinavian and Japanese mill customers, with fabricators maintaining six-to-twelve month raw material buffers against supply disruption. Geographic supply concentration centers on Norway, Germany, and South Korea for finished-system assembly, while high-grade structural steel draws from Scandinavian and Japanese primary metallurgy. Critical dependencies include nickel-alloy plate, high-pressure hydraulic manifolds, and certified weld consumables. Single-source vulnerability in proprietary hydraulic component designs fragments aftermarket inventory across OEMs. Distribution runs through direct vessel-yard contracting for newbuild programs and regional service depots for aftermarket refurbishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin convergence and IoT load monitoring are transforming aftermarket service from transactional parts replacement into recurring-revenue platform economics, with predictive maintenance algorithms enabling crane-as-a-service models that bind operators to integrated solution providers.
For Market Incumbents: Compound certification queue advantages by expanding DNV and ABS accredited testing capacity in Stavanger and Houston, locking out competitors facing four-to-eight month proof-load bottlenecks. Deepen backward integration into high-pressure hydraulic system design to defend margin position against electromechanical substitution in harbor segments. Prioritize captive technician training programs addressing certified hydraulic specialist scarcity that constrains fleet availability for remote platform operations. For New Entrants and Emerging Players: Differentiate on active heave compensation retrofit expertise for legacy crane foundations, exploiting structural recertification conflicts that incumbent OEMs avoid. Target EU Green Deal subsidy capture in German and Dutch port electrification programs, where hybrid-electric harbor crane replacement cycles accelerate independently of offshore newbuild demand. Pursue white-label maintenance partnerships with mid-size Norwegian offshore supply vessel operators who have already unbundled service contracts from initial procurement. For Investors and Strategic Acquirers: The market sits at a certification-intensification phase that favors vertically integrated fabricators with in-house steel and hydraulic capabilities over modular assemblers. Long-term viability hinges on exposure to floating offshore wind installation vessel specifications where knuckle boom crane demand is climbing fastest. Watch for DNV-ST-E273 fatigue-life documentation mandates tightening further as North Sea decommissioning accelerates, signaling replacement cycle inflection for aging platform crane fleets.| Strategic Initiative | Industry Significance |
|---|---|
| Active Heave Compensation Integration | DNV certification mandates are compressing development cycles for jack-up vessel fleets in North Sea markets. |
| Technician Network Expansion | Regional certified specialist density determines aftermarket contract capture among Norwegian platform operators. |
| Hybrid-Electric Product Line Development | EU Green Deal subsidies in Rotterdam and Hamburg accelerate harbor crane replacement demand. |
| Digital Twin Platform Deployment | IoT load monitoring enables predictive maintenance revenue models for offshore crane fleets. |
| High-Grade Steel Mill Partnership | Long-term offtake arrangements with Scandinavian mills secure input cost visibility for custom fabrication. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with offshore platform maintenance directors, shipyard procurement leads, classification society surveyors, and hydraulic system service heads; and secondary validation through DNV-ST-E273 certification databases, ABS Guide for Certification of Lifting Appliances documentation, EU Machinery Directive regulatory filings, and customs trade records for marine-grade steel imports. Bottom-up vessel fleet analysis triangulated against top-down market sizing across product type, end user, technology, and application dimensions.
Across the analysis window, the forecasting framework modeled hydraulic marine crane demand through segmentation by boom geometry, operational depth rating, certification tier, and regional regulatory cluster. CAGRs were derived from installed base depreciation curves overlaid with newbuild orderbook analysis and replacement cycle timing. Industry-specific inputs included offshore wind turbine installation vessel specifications, North Sea platform decommissioning schedules, and EU Green Deal retrofit incentive disbursement trajectories.
The analysis sits within stated boundaries; outcomes outside sustained offshore capital expenditure commitment and classification society regulatory stability would require recalibration. Forecasts reflect assumptions regarding DNV and ABS certification timeline continuity, high-grade alloy steel supply elasticity, and electromechanical substitution rates in harbor segments. Revision becomes warranted when active heave compensation technology cost curves cross thresholds that accelerate displacement of conventional hydraulic architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Ship Heat Exchanger Market
Marine
Integrated Bridge System for Ships Market
Marine
Jet Boat Market
Marine
Commercial Hovercraft Market
Marine
Marine Propeller Market
Marine
Boat Hook Market
Marine
Marine Glass Market
Marine
Passenger Vessel Propeller Market
Marine
Ship Rudders Market
Marine
Boat Steering Systems Market
Marine
Marine Chronometers Market
Marine
Marine Fender Market
Marine
Marine Salvage Services Market
Marine
Yacht Shell Doors Market
Marine
Europe Marine Communication Systems Market
Marine
North America Naval Vessels Market