
 Egypt Commercial Vehicles Lubricants Market | 2026-2036
Egypt Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Commercial Vehicles Lubricants Market Foresight
API CK-4 and FA-4 specification upgrades is unwinding older lubricant inventories across Egypt's commercial fleet base. ExxonMobil Corporation leverages its global formulation expertise to supply high-performance engine oils meeting these stringent standards. Royal Dutch Shell PLC anchors its position through an extensive distribution network spanning Alexandria to Aswan. Misr Petroleum competes on cost-advantaged domestic blending capacity, while BP PLC (Castrol) differentiates through technical service partnerships with major fleet operators.
Egypt commercial vehicles lubricants encompass refined petroleum-based and synthetic formulations engineered to reduce friction, dissipate heat, and prevent wear in diesel and gasoline engines operating under severe duty cycles, with viscosity grades typically ranging from SAE 15W-40 to 5W-30 for modern turbocharged powertrains. These fluids serve heavy-duty trucks, buses, and construction machinery subjected to desert heat, dust ingress, and extended drain intervals. Engine oil dominates value capture due to higher volume throughput and premium pricing on synthetic grades, while hydraulic oil represents the fastest-growing category as Egypt's infrastructure fleet expands. Fleet operators command the largest end-user share, with bulk packaging formats preferred by logistics providers running centralized maintenance depots.
Egypt's Ministry of Petroleum and Mineral Resources enforces local content requirements through the Egyptian General Petroleum Corporation, compelling foreign suppliers to blend domestically or partner with state-owned refiners. The Egyptian Organization for Standardization and Quality (EOS) adopts API and ACEA benchmarks for lubricant certification, creating compliance barriers for uncertified imports. Stakeholders must monitor how Cairo's industrial localization policies reshape supplier qualification criteria and procurement patterns for state-affiliated transport fleets.
Market Dynamics
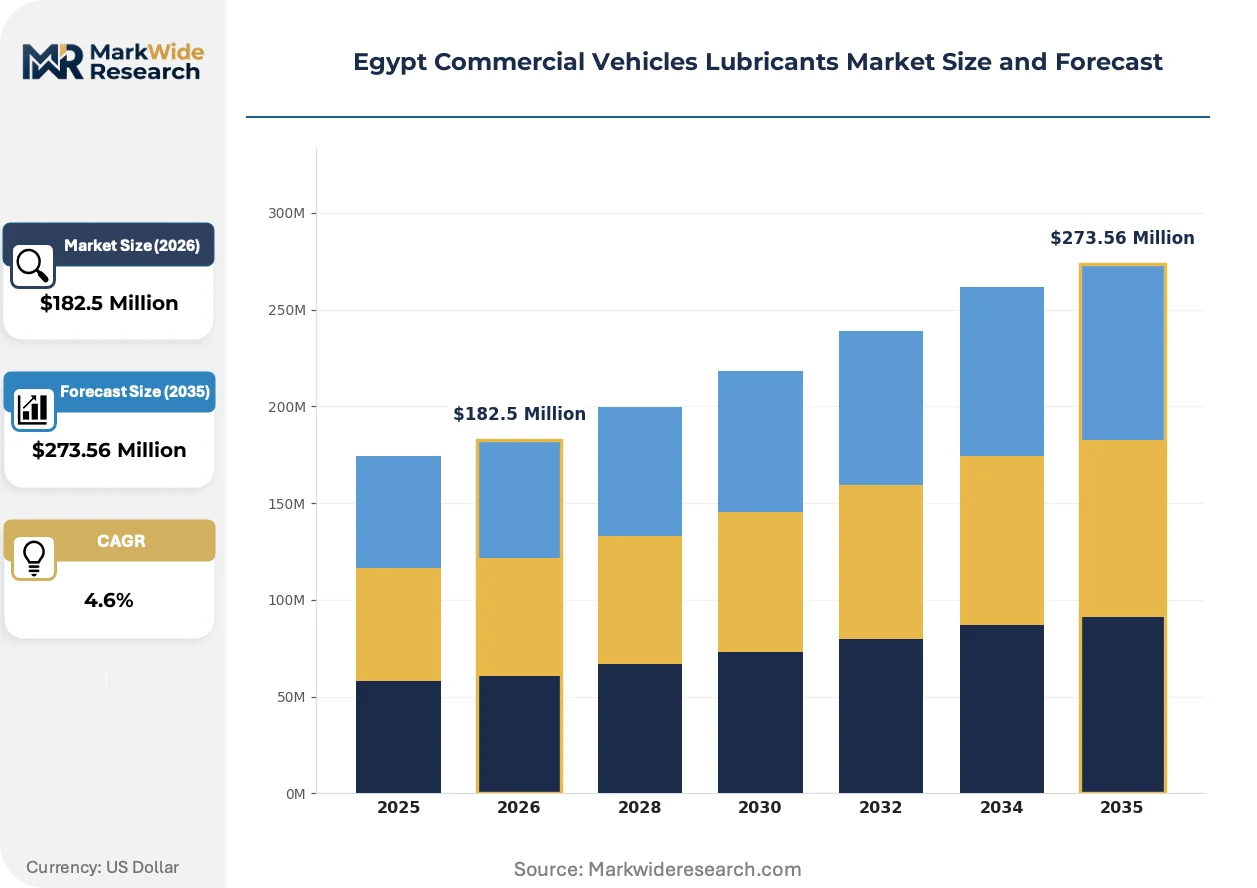
Egypt's commercial vehicle lubricant market pivots on Egyptian General Petroleum Corporation blending mandates that redirect supply chains toward domestic manufacturing, compressing import-dependent distribution models and reshaping procurement patterns for fleet operators across Greater Cairo's logistics corridors.
Growth Catalysts
- Long-haul fleet expansion:Transport corridor deepening between Alexandria and Aswan drives bulk lubricant procurement from centralized maintenance depots serving heavy-duty trucking operations.
- API CK-4/FA-4 specification upgrades:Stringent engine oil standards mandated by the Egyptian Organization for Standardization and Quality force fleet modernization and accelerate synthetic grade adoption.
- Infrastructure machinery deployment:Construction equipment fleets across Suez Canal Economic Zone expansion sites multiply hydraulic oil consumption at double-digit rates.
Market Restraints
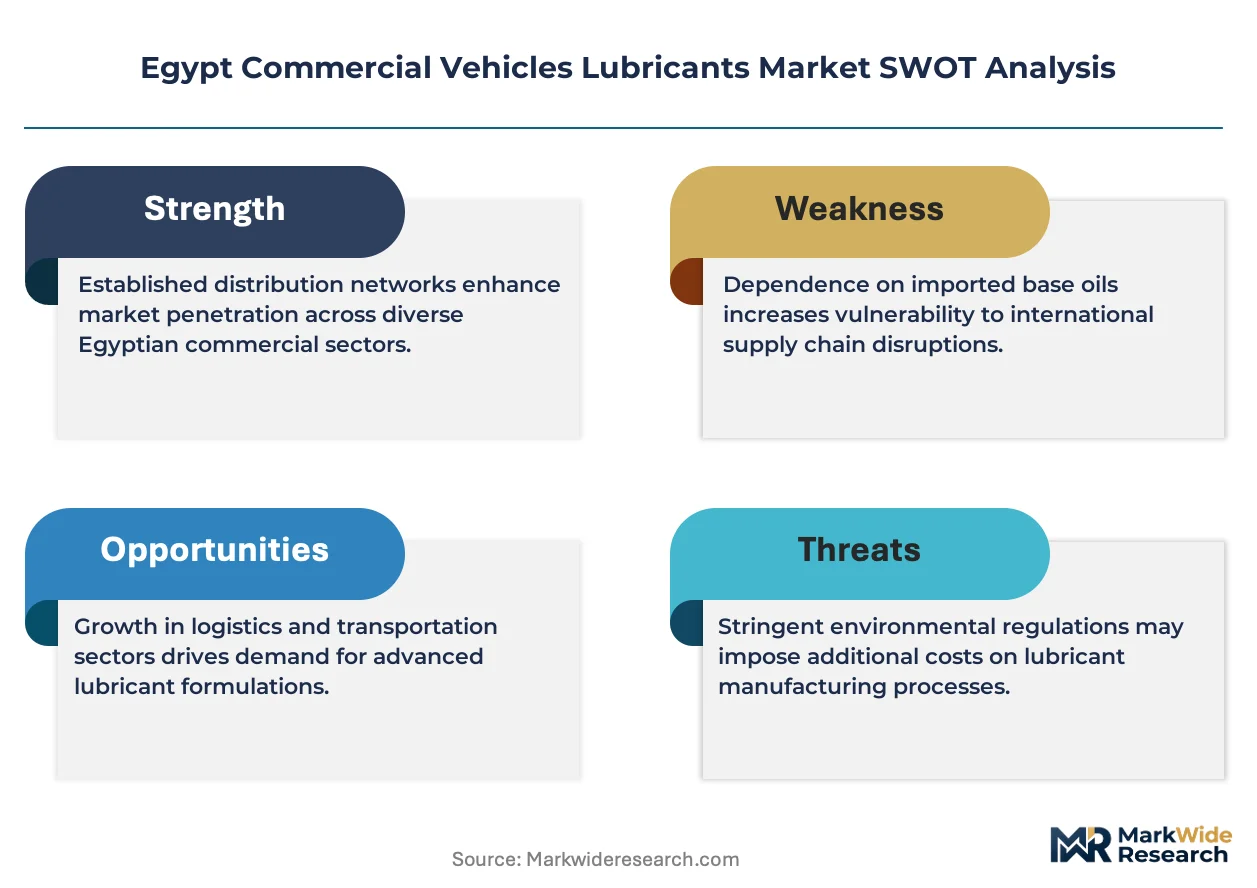
- Base oil import dependency:Egypt's limited Group II/III refining capacity forces blenders to source feedstock from Gulf suppliers, exposing margins to freight and currency volatility.
- Counterfeit lubricant infiltration:Unlicensed blending operations in informal industrial zones erode certified product volumes and create warranty liability exposure for legitimate distributors.
- Extended drain interval technology:Synthetic formulations lasting 50,000+ kilometers compress per-vehicle oil consumption volumes despite premium pricing.
Strategic Opportunities
- Upper Egypt penetration:Aswan and Luxor commercial vehicle densities remain underserved by technical service networks, creating first-mover advantage for depot-based distribution models.
- Used oil re-refining:Ministry of Petroleum and Mineral Resources waste-to-resource incentives enable circular economy positioning for domestic blenders with collection infrastructure.
- Telematics-integrated fluid monitoring:Fleet management systems from logistics providers enable predictive oil change scheduling and premium service bundling.
Industry Challenges
- API certification backlog:Egyptian Organization for Standardization and Quality testing capacity constraints delay new product approvals by 6-12 months, freezing formulation innovation cycles.
- Technical service engineer scarcity:Specialized lubricant application expertise for turbocharged diesel diagnostics concentrates in Alexandria and Cairo, leaving regional fleets dependent on remote support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Commercial Vehicles Lubricants Market |
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $273.56 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Hydraulic Oil Application: Heavy-Duty Trucks, Buses, Utility Vehicles, Construction Machinery End User: Fleet Operators, Transportation Companies, Construction Firms, Logistics Providers Packaging Type: Bulk, Drums, Cans, Pails |
| Companies Covered | ExxonMobil Corporation, Royal Dutch Shell PLC, TotalEnergies, Cooperative Societe des Petroleum, Misr Petroleum, BP PLC (Castrol), Chevron Corporation, FUCHS, Emarat, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Commercial Vehicles Lubricants Market Shifts & Advancements
Formulation chemistry and procurement digitization are compressing traditional supply relationships in Egypt's commercial lubricant sector, with synthetic base stocks and fleet data integration rewriting value capture mechanisms.
Synthetic Group III and Group IV base stocks are displacing mineral formulations in heavy-duty diesel applications across Egypt's temperature-extreme operating environments. Fleet operators running Suez-to-Luxor corridors adopt these fluids to prevent thermal breakdown during summer desert transits. The shift is compressing conventional oil SKU counts at distributor warehouses and redirecting working capital toward premium inventory positions.
Egyptian General Petroleum Corporation local content enforcement tightens procurement eligibility for state-affiliated transport fleets, requiring domestic blending certificates for contract participation. Foreign suppliers must partner with Misr Petroleum or establish captive blending facilities to qualify for Suez Canal Authority and public bus operator tenders. This regulatory friction favors incumbents with existing Egyptian General Petroleum Corporation relationships and raises barriers for direct importers.
Centralized fleet maintenance depots in 10th of Ramadan City and 6th of October City are consolidating lubricant purchasing decisions away from individual driver discretion. Logistics providers negotiate annual volume contracts with technical service attachments, displacing spot purchases from retail petrol station channels. This concentration is visible among cold-chain operators serving Alexandria's pharmaceutical export corridor, where unified procurement platforms now manage fluid specifications across multi-brand truck fleets.
Egypt Commercial Vehicles Lubricants Market Segmentation
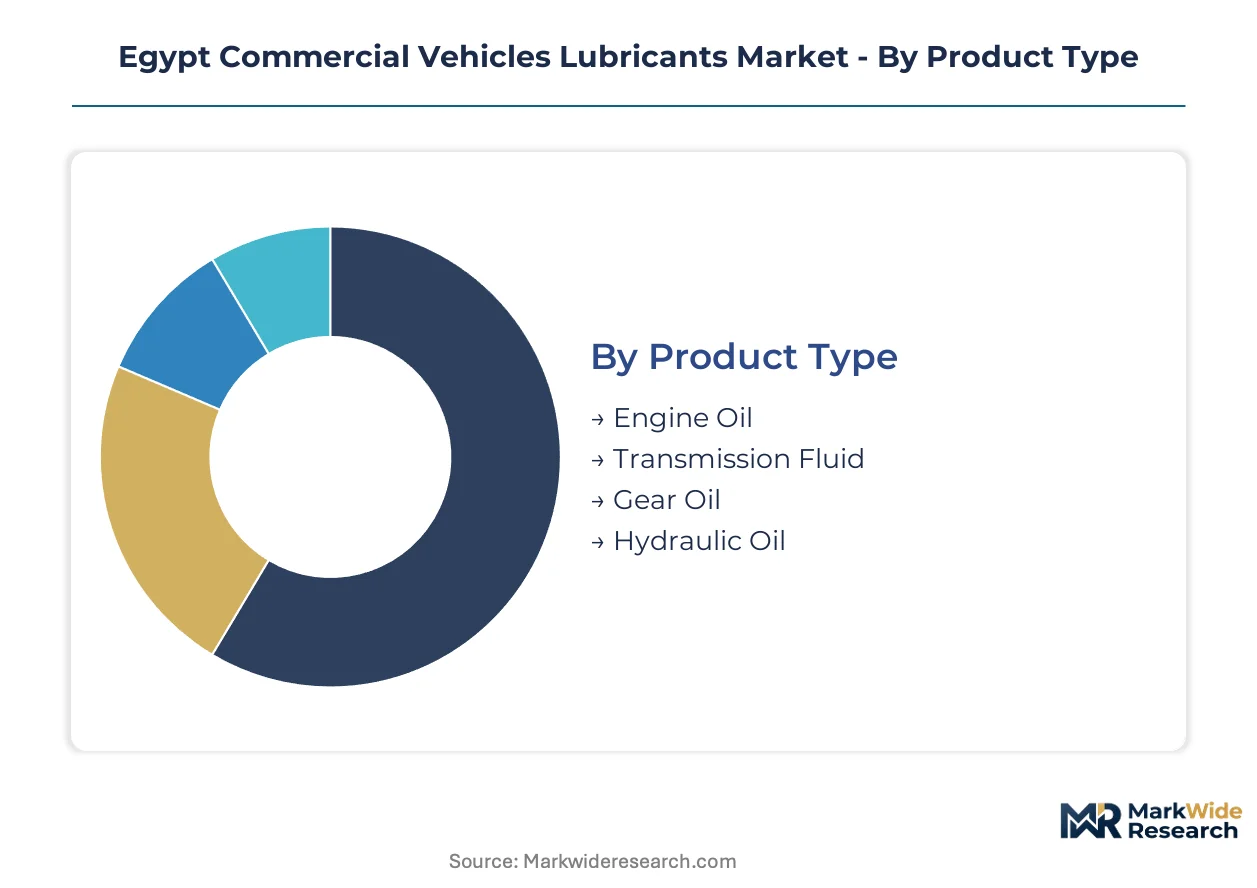
Egypt's commercial vehicle lubricant demand fragments across equipment duty cycles, procurement centralization, and fluid specification requirements. Fleet operators prioritize segments delivering extended drain intervals and warranty compliance under desert operating conditions.
Product Type:
Engine Oil faces substitution pressure from extended-drain synthetic formulations that compress per-vehicle consumption volumes despite premium positioning.
- Engine Oil:Refined petroleum and synthetic formulations spanning SAE 15W-40 to 5W-30 viscosity grades protect turbocharged diesel powertrains against thermal breakdown. Greater Cairo logistics depots drive bulk procurement of API CK-4 certified grades as fleet operators modernize inventory.
- Hydraulic Oil:Anti-wear formulations with high viscosity index maintain fluid film integrity in construction equipment cylinders and pumps. Suez Canal Economic Zone infrastructure expansion multiplies consumption across excavator and crane fleets operating in dust-intensive environments.
- Gear Oil:Extreme-pressure lubricants protect differentials and transmissions in long-haul trucks traversing Upper Egypt corridors.
- Transmission Fluid:Synthetic ATF and manual transmission oils serve bus fleets and utility vehicles with automated gearbox specifications.
Engine Oil retains volume leadership; Hydraulic Oil holds the steepest expansion curve.
Application:
Cost tier differentiation separates premium synthetic adoption rates across equipment categories with varying utilization intensity.
- Heavy-Duty Trucks:Class 8 tractors and rigid trucks operating Alexandria-Aswan corridors consume the highest lubricant volumes per unit. Fleet operators negotiate annual volume contracts with technical service attachments, consolidating procurement away from retail channels.
- Construction Machinery:Excavators, bulldozers, and cranes in Suez Canal zone development sites multiply hydraulic and engine oil demand. Equipment lessors specify OEM-approved formulations to maintain warranty coverage under severe dust and temperature cycling.
- Buses:Public transport and intercity coach fleets in Greater Cairo and Nile Delta cities operate on fixed routes with centralized depot maintenance.
- Utility Vehicles:Light commercial vans and pickup trucks serving last-mile delivery run shorter drain intervals due to stop-start urban duty cycles.
Heavy-Duty Trucks anchor procurement volume; Construction Machinery commands the premium pricing tier.
End User:
Customer type concentration determines packaging format preferences and technical service requirements across Egypt's logistics corridors.
- Fleet Operators:Multi-vehicle owners running 50+ units standardize fluid specifications across mixed-brand fleets to simplify inventory management. 10th of Ramadan City and 6th of October City depots negotiate direct supply agreements with blending facilities.
- Logistics Providers:Cold-chain and pharmaceutical transport specialists in Alexandria's export corridor demand certified formulations with batch traceability for audit compliance.
- Transportation Companies:Intercity bus and freight operators balance cost control with Egyptian Organization for Standardization and Quality certification requirements.
- Construction Firms:Project-based contractors in New Administrative Capital and Suez zone developments purchase through equipment rental channels with fluid-inclusive service contracts.
Fleet Operators dominate bulk consumption; Logistics Providers drive specification upgrading fastest.
Packaging Type:
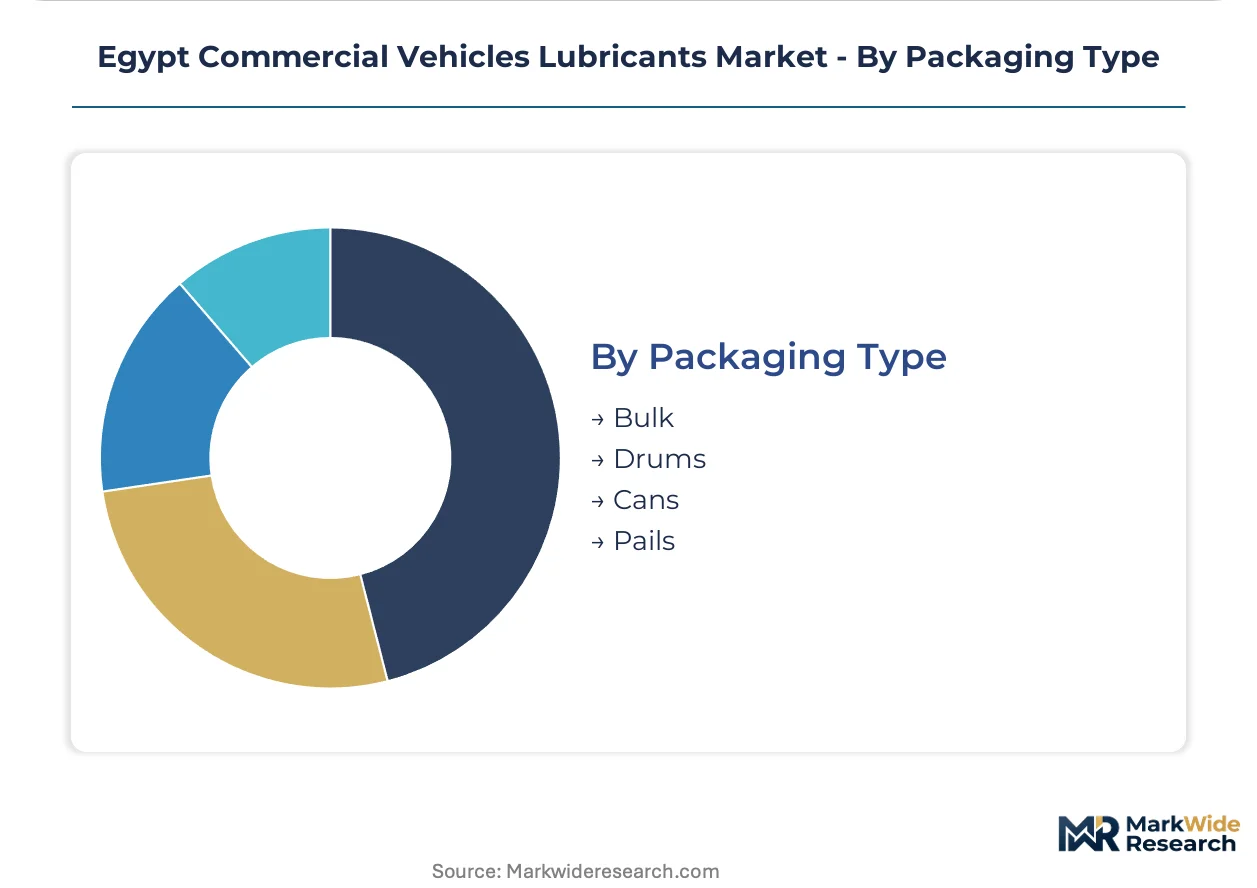
Supply concentration in Greater Cairo blending facilities shapes distribution economics across container formats.
- Bulk:Tanker truck deliveries of 5,000+ liter volumes serve centralized maintenance depots with on-site storage infrastructure. Fleet operators in 6th of October City logistics parks achieve lowest per-liter landed costs through annual contracting.
- Drums:200-liter steel containers balance portability with volume discounting for mid-sized operators lacking bulk storage capacity.
- Pails:20-liter plastic containers serve regional distributors and smaller fleet maintenance bays in Upper Egypt cities.
- Cans:4-5 liter retail formats persist in driver-purchase channels despite procurement centralization trends.
Bulk retains volume leadership; Pails gain share fastest in Upper Egypt penetration strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's commercial vehicle lubricant trade flows reflect a net import position in base oil feedstocks balanced against growing domestic blending capacity. The Egyptian General Petroleum Corporation's localization mandates are redirecting procurement patterns toward domestic manufacturing nodes concentrated in Greater Cairo and Alexandria.
Greater Cairo
10th of Ramadan City and 6th of October City logistics corridors generate the highest lubricant consumption density per square kilometer. The Egyptian Organization for Standardization and Quality enforces API certification requirements that compress informal supplier participation. Fleet operators in these industrial zones negotiate annual bulk contracts with technical service attachments displacing retail petrol station channels.
Alexandria
The port city's cold-chain pharmaceutical export corridor drives demand for certified formulations with batch traceability compliance. Misr Petroleum operates blending capacity serving state-affiliated transport fleets under Egyptian General Petroleum Corporation procurement rules. Logistics providers here standardize fluid specifications across multi-brand truck fleets through unified procurement platforms.
Suez Canal Economic Zone
Infrastructure machinery deployment across canal expansion sites multiplies hydraulic oil consumption at accelerated rates. Construction equipment lessors specify OEM-approved formulations to maintain warranty coverage under severe dust and temperature cycling. The Suez Canal Authority tenders require domestic blending certificates that filter import-dependent suppliers.
Upper Egypt
Aswan and Luxor commercial vehicle densities remain underserved by technical service networks creating first-mover opportunities. Pail-format distribution dominates where bulk storage infrastructure remains limited. Fleet operators here depend on remote diagnostic support from Alexandria-based technical service engineers.
Nile Delta
Intercity bus and freight operators across Mansoura and Tanta balance cost control with Egyptian Organization for Standardization and Quality certification requirements. Regional distributors serve mid-sized operators through 200-liter drum formats lacking centralized depot infrastructure. Public transport procurement centralization is compressing spot purchase volumes from retail channels.
Egypt Commercial Vehicles Lubricants Market Competitive Landscape
Concentration sits with multinational oil majors possessing global formulation expertise and domestic blending partnerships. The supplier base stratifies across three tiers: integrated oil majors with captive base oil supply, regional specialists leveraging Egyptian General Petroleum Corporation relationships, and independent blenders competing on cost-advantaged local production. Competitive moves center on domestic facility investments to satisfy local content requirements and technical service network expansion to capture fleet operator contracts.
Within the multinational tier, ExxonMobil Corporation and Royal Dutch Shell PLC exemplify archetypes combining global R&D scale with Egyptian General Petroleum Corporation-aligned distribution infrastructure. Misr Petroleum occupies a position representing state-affiliated domestic blending capacity competing on procurement eligibility for public fleet tenders. BP PLC (Castrol) sits within the technical service differentiation archetype, anchoring positioning through fleet operator partnerships rather than volume-scale supply.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Royal Dutch Shell PLC |
| TotalEnergies |
| Cooperative Societe des Petroleum |
| Misr Petroleum |
| BP PLC (Castrol) |
| Chevron Corporation |
| FUCHS |
| Emarat |
| Others |
Supply & Pricing Matrix
Annual volume contracts with technical service attachments lock in supply access for fleet operators while compressing price visibility for spot-market participants across Egypt's logistics corridors. Egyptian General Petroleum Corporation blending mandates tether procurement eligibility to domestic manufacturing certificates, reshaping how foreign suppliers structure their Egyptian market entry.
Pricing Analysis
Fleet operators anchor pricing structures through multi-year bulk agreements that trade volume commitment for per-liter discounts and embedded technical support. Three-tier pricing stratification separates API CK-4 synthetic grades from conventional mineral formulations and uncertified economy products, with differentiation resting on certification tier and after-sales service bundling. Pricing pressure intensifies in the economy tier as counterfeit lubricants from informal blending operations erode legitimate volume. Small regional distributors exhibit highest price sensitivity, while state-affiliated transport fleets prioritize certification compliance over unit cost.
Supply Chain Analysis
Strategic stockpiling of Group II and Group III base oils dominates inventory strategy among Egyptian blenders buffering against Gulf supplier lead time variability. Domestic manufacturing draws feedstock primarily from Saudi Arabia, Kuwait, and the United Arab Emirates, with finished lubricant distribution running through Misr Petroleum's Alexandria blending facility and Greater Cairo depot networks. Single-source vulnerability concentrates in base oil import channels exposed to currency volatility and Red Sea logistics chokepoints. Fleet operators in 10th of Ramadan City and 6th of October City receive direct tanker truck deliveries bypassing distributor markup layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's commercial vehicle lubricant market functions as a regulatory moat where Egyptian General Petroleum Corporation certification requirements create switching costs that entrench incumbent positions. Network effects concentrate among suppliers with established technical service engineer pools.
For Market Incumbents: Shield market position by deepening backward integration into captive base oil storage infrastructure at Alexandria port facilities. Counter emerging threats from Gulf-based suppliers seeking direct import channels by accelerating API certification investment to compress approval timelines. Channel control through exclusive depot-based distribution agreements in 6th of October City logistics parks reinforces volume lock-in against price-aggressive challengers. For New Entrants and Emerging Players: Differentiate on telematics-integrated fluid monitoring services targeting cold-chain logistics providers in Alexandria's pharmaceutical export corridor. Upper Egypt penetration offers the most penetrable white-space geography, with Aswan and Luxor fleet densities underserved by technical support networks. A depot-based distribution partnership model with regional maintenance operators enables rapid footprint expansion without capital-intensive blending facility investment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated blenders with Egyptian General Petroleum Corporation relationships and existing certification portfolios. Long-term viability hinges on circular economy positioning through used oil re-refining infrastructure capturing Ministry of Petroleum and Mineral Resources waste-to-resource incentives. Monitor API certification backlog resolution at the Egyptian Organization for Standardization and Quality as the signal indicating when formulation innovation cycles normalize.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Blending Facility Investment | Egyptian General Petroleum Corporation procurement rules filter import-dependent suppliers from state tender participation. |
| Technical Service Network Expansion | Fleet operator contracts in Greater Cairo logistics zones attach lubricant supply to diagnostic support agreements. |
| Used Oil Re-refining Infrastructure | Ministry of Petroleum and Mineral Resources incentives enable circular economy positioning against linear competitors. |
| Telematics Integration Partnership | Predictive maintenance platforms from logistics providers create premium service bundling opportunities. |
| Upper Egypt Distribution Partnership | Pail-format penetration in Aswan and Luxor captures underserved commercial vehicle density. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, Egyptian Organization for Standardization and Quality certification records, and Egyptian General Petroleum Corporation procurement disclosures. Interviews with fleet maintenance directors, blending facility operations managers, lubricant distribution channel partners, and technical service engineers informed demand-side and supply-side perspectives. Bottom-up volume modeling triangulates against top-down market sizing derived from commercial vehicle registration databases and per-vehicle consumption benchmarks.
Segmentation dimensions modeled span product type, application equipment category, end-user procurement centralization level, and packaging format preferences across the projection horizon. CAGRs derive from regression analysis of historical consumption patterns against fleet expansion trajectories and specification upgrade cycles. Industry-specific forecast inputs incorporate API CK-4 adoption curves and Suez Canal Economic Zone construction machinery deployment schedules.
Material uncertainties — base oil import cost volatility, Egyptian Organization for Standardization and Quality testing capacity constraints, counterfeit infiltration rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement continuity and fleet modernization pacing. Revision becomes warranted when Egyptian General Petroleum Corporation localization policy intensity crosses thresholds that fundamentally alter supplier qualification economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Asia-Pacific Automotive Plastics Market
Automotive Components
Europe Automotive AHSS Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Automotive Axle Market
Automotive Components
Automotive Part Cleaners and Degreasers Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
India Automotive Stamping Market
Automotive Components
Global Automotive Water Valve Market
Automotive Components
Automotive Carbon Ceramic Brakes Market
Automotive Components
Automotive Spark Plug Market
Automotive Components
Morocco Automotive Lubricants Market
Automotive Components
Global Automotive Chrome Accessories Market
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
North America Automotive Hydraulic Actuators Market
Automotive Components
Remote Automotive Exhaust Sensing Market