
 Automotive Filters Market | 2026-2036
Automotive Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Filters Market Analysis
German filtration manufacturing is hardening against Asian cost competition through precision-engineered synthetic media. MANN+HUMMEL leverages captive R&D centers in Stuttgart to develop multi-layer cabin filter architectures. MAHLE GmbH anchors European OEM supply through backward integration into nonwoven substrate production. Donaldson Company, Inc. competes in North American heavy-duty channels with proprietary PowerCore radial seal technology.
Automotive filters are engineered separation devices constructed from pleated paper, synthetic fiber, or sintered substrates, designed to remove particulate and chemical contaminants from air, oil, fuel, and cabin ventilation streams with specified efficiency ratings and pressure-drop thresholds. Oil filters retain wear metals and soot to protect engine bearing surfaces, while cabin filters incorporate activated carbon layers to adsorb nitrogen oxides and volatile organic compounds. Air filters for passenger vehicles command the largest volume pool due to universal fitment across combustion and hybrid architectures, though synthetic fiber materials are gaining share as OEMs specify extended service intervals. Aftermarket providers represent a structurally fragmented channel where margin pools concentrate in branded premium tiers with certified compatibility databases.
EPA tailpipe and evaporative emissions rules, Euro 7 standards from the European Commission, and China's GB national standards collectively mandate filtration efficiency thresholds that obsolete legacy cellulose-only designs. NHTSA fuel economy regulations indirectly shape demand by pressuring engine airflow optimization, which places tighter tolerances on intake filter pressure-drop characteristics. Stakeholders must monitor how battery electric vehicle thermal management systems redefine filter duty cycles and service access points.
Market Dynamics
Fleet operators in commercial logistics are extending replacement cycles while simultaneously upgrading to higher-efficiency filtration systems, compressing margin pools for mid-tier suppliers and concentrating volume with premium synthetic media providers.
Growth Catalysts
- Euro 7 emissions rules:The European Commission's tightened particulate matter standards force material upgrades across pleated media, accelerating synthetic fiber substitution for cellulose in OEM supply contracts.
- Electrified vehicle platforms:Domestic Chinese OEMs are expanding battery thermal management and specialized cabin filtration requirements, creating new filter categories with distinct duty cycles.
- Extended service intervals:Synthetic fiber materials specified by OEMs for intake systems reduce maintenance frequency, locking in higher per-unit value capture for certified suppliers.
Market Restraints
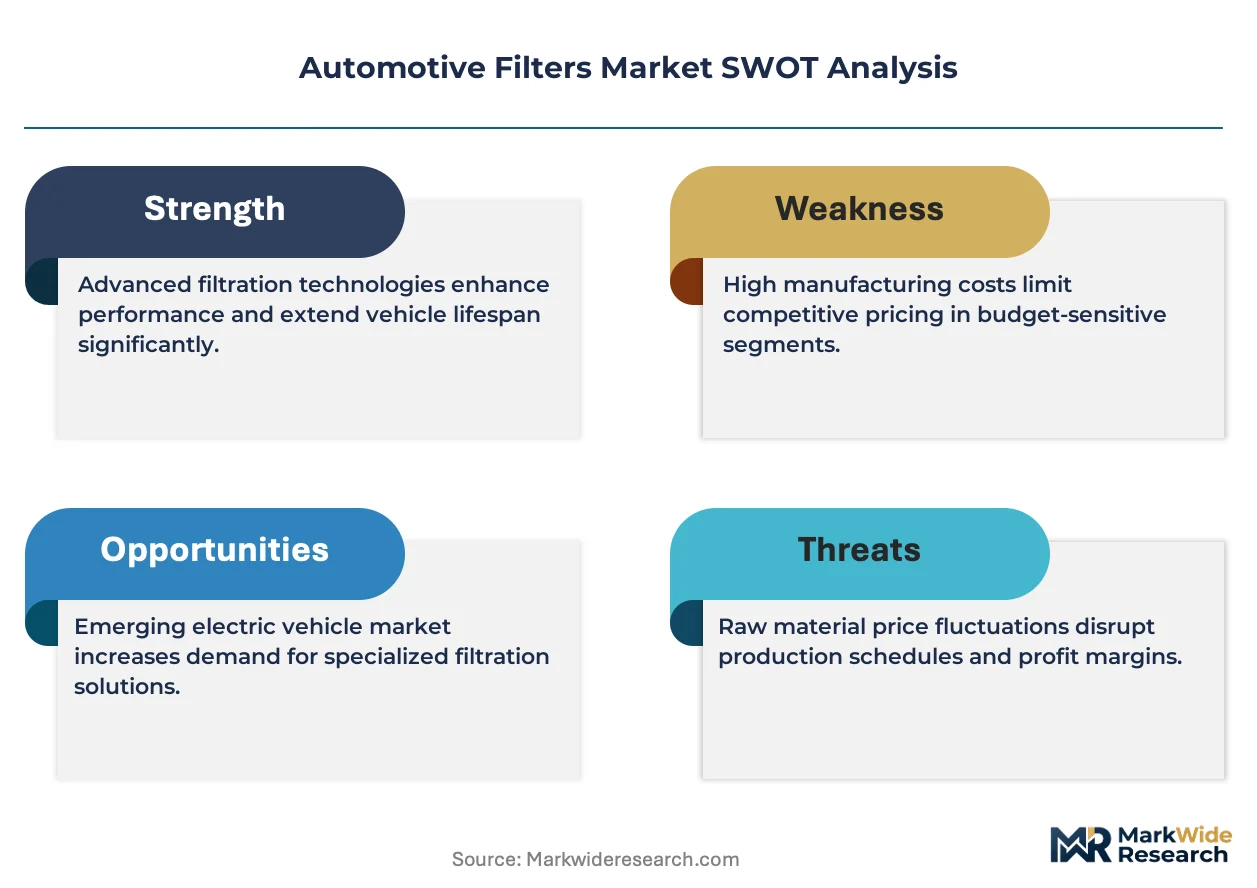
- Cellulose substrate cost volatility:Pulp input prices fluctuate with forestry harvest cycles and energy costs, squeezing margin for legacy paper-based filter producers.
- Asian manufacturing concentration:Cost-competitive pleated media production clusters in China and Southeast Asia pressure European and North American margin structures on commodity-grade products.
- Technical limitation in high-temperature BEV applications:Thermal management filters for battery packs face material degradation thresholds above 150°C, constraining polymer selection and unit economics.
Strategic Opportunities
- Underpenetrated Indian aftermarket:Organized service networks in tier-2 and tier-3 cities remain fragmented, offering white space for branded filter distributors with certified compatibility databases.
- Activated carbon convergence with cabin sensors:Integration of filtration media with interior air quality monitoring systems creates bundled value propositions for premium vehicle segments.
- US IRA clean vehicle incentives:Tax credits for domestic EV production indirectly stimulate filter demand for battery thermal management and cabin air systems assembled in North American plants.
Industry Challenges
- Multi-material lamination skill gaps:Precision bonding of synthetic nonwoven layers with activated carbon requires specialized technicians scarce in traditional paper-filter manufacturing regions.
- EPA certification timeline compression:Evolving evaporative emissions test protocols demand accelerated validation cycles, straining R&D throughput for mid-cap suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Filters Market |
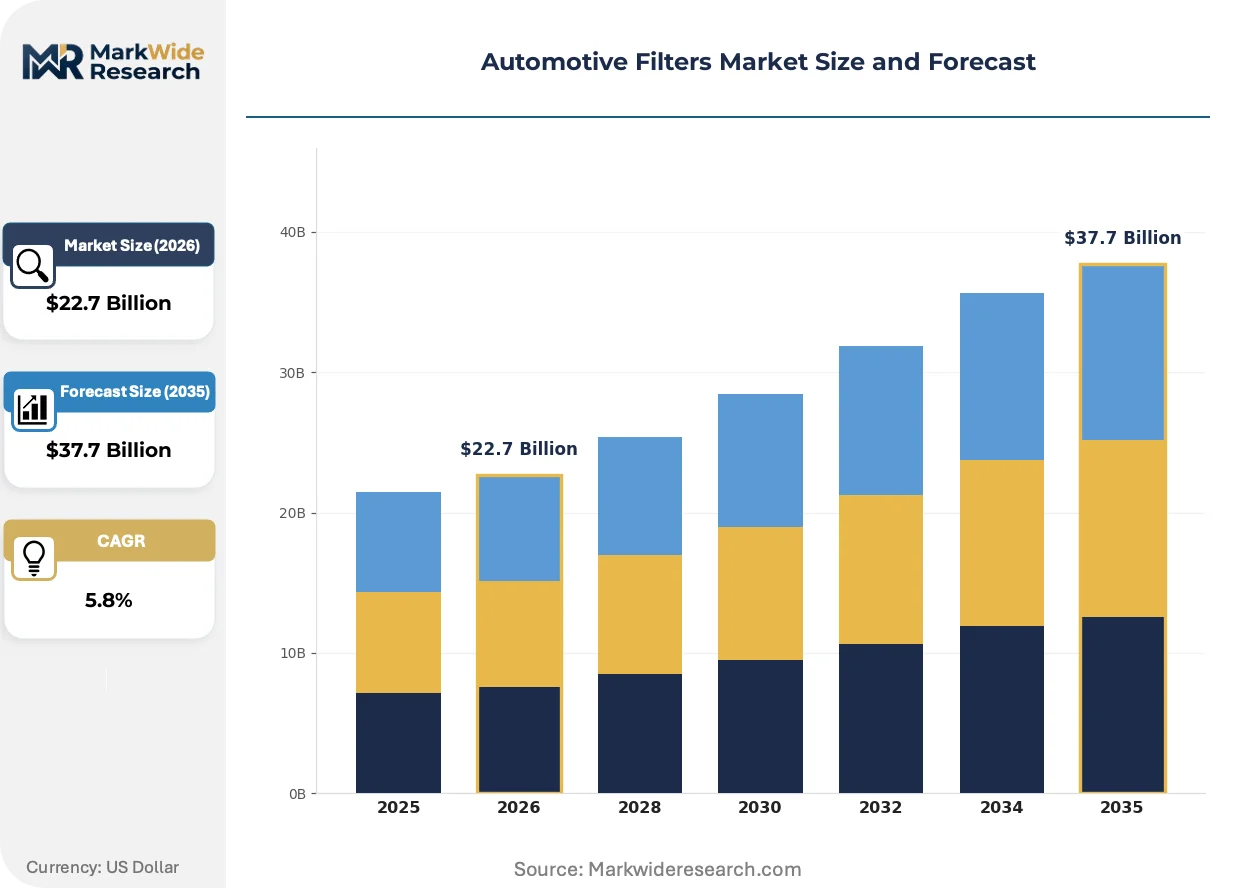
| Market Size in 2026 | $22.7 Billion |
| Market Size in 2035 | $37.7 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Filter Type: Oil Filters, Air Filters, Fuel Filters, Cabin Filters End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Material: Pleated Paper, Synthetic Fiber, Foam, Steel Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Sports Cars |
| Companies Covered | MANN+HUMMEL, MAHLE GmbH, Donaldson Company, Inc., Robert Bosch GmbH, Toyota Boshoku Corporation, Parker Hannifin Corp, DENSO Corporation, UFI Filters SPA, Hengst SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Filters Market Emerging Trajectories
Synthetic media architectures are displacing legacy cellulose across all filter categories, while regulatory pressure on particulate capture efficiency and thermal management requirements for electrified vehicles reshape specification standards.
Electrospun nanofiber surface layers are automating sub-micron particulate capture without the pressure-drop penalties of denser meltblown substrates. Tier-1 suppliers in Stuttgart and Detroit are qualifying these materials for extended 30,000-mile service intervals. The technology is automating quality differentiation between premium OEM contracts and aftermarket commodity tiers.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) are forcing reformulation of water-repellent treatments applied to air intake media. European filter manufacturers face 2025 compliance deadlines for alternative chemistries in pleated paper and synthetic blends. Heavy-duty commercial vehicle segments are absorbing the highest cost impact as hydrophobic performance specifications tighten.
Direct-to-fleet procurement platforms are compressing traditional distribution layers in North American commercial vehicle aftermarket channels. Large logistics operators with centralized maintenance systems now negotiate annual filter supply contracts bypassing regional jobbers. This pattern is most visible among long-haul trucking fleets operating across the US Midwest and Southeast corridors.
Automotive Filters Market Segmentation
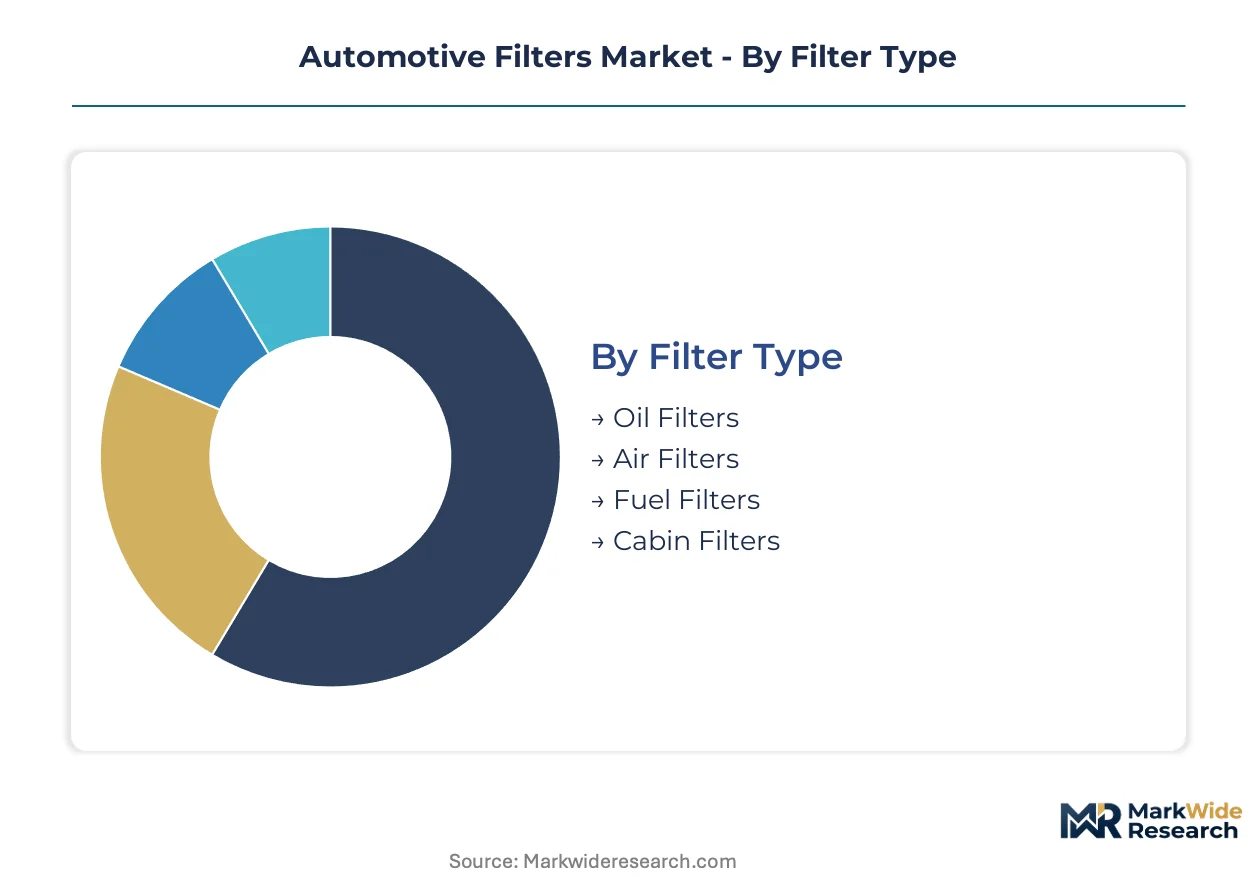
Automotive filter procurement splits sharply between standardized high-volume contracts and precision-engineered specifications. OEMs demand certified compatibility databases while aftermarket channels fragment across price tiers and regional service networks.
Filter Type:
Standardization dominates oil and air filtration, whereas cabin and fuel systems require greater customization for vehicle-specific HVAC architectures and engine calibrations.
- Oil Filters:Spin-on and cartridge configurations retain wear metals and soot through pleated cellulose or synthetic media. Demand concentrates in commercial vehicle fleet maintenance programs extending replacement cycles, pressuring suppliers toward higher-efficiency synthetic substrates.
- Air Filters:Intake systems for combustion and hybrid architectures command universal fitment volumes. China's domestic OEMs specify extended service intervals, locking in synthetic fiber substitution for legacy paper designs across electrified platforms.
- Fuel Filters:Water separation and particulate retention protect high-pressure common rail injectors from contamination.
- Cabin Filters:Activated carbon layers adsorb nitrogen oxides and volatile organic compounds for interior air quality.
Most installed capacity flows through Air Filters. Expansion is steepest in Cabin Filters.
End User:
Margin concentration follows certification requirements, with OEMs capturing premium tiers and aftermarket channels fragmenting across service network density.
- OEMs:Original equipment manufacturers specify filtration efficiency thresholds through certified supply contracts with backward-integrated substrate producers. European and North American OEMs mandate Euro 7 and EPA-compliant synthetic media, concentrating volume with tier-1 suppliers possessing captive R&D centers.
- Aftermarket Providers:Branded distributors compete through certified compatibility databases and premium tier positioning. India's tier-2 and tier-3 cities present white space for organized service networks with fragmented regional jobber structures.
- Vehicle Assemblers:Contract manufacturers source filters through consolidated procurement platforms for domestic production.
- Repair Shops:Independent service centers access filters through traditional distribution layers or direct-to-fleet procurement platforms.
Volume concentrates with OEMs. Aftermarket Providers are gaining share fastest through direct-to-fleet platform adoption.
Material:
Cost structure shifts from pulp-linked volatility toward petrochemical-based synthetic stability, with performance specifications dictating material selection.
- Pleated Paper:Cellulose substrates face cost volatility from forestry harvest cycles and energy inputs. Legacy producers in Southeast Asia compete on commodity-grade volumes while European manufacturers harden positioning through precision-engineered alternatives.
- Synthetic Fiber:Multi-layer nonwoven architectures enable sub-micron particulate capture without pressure-drop penalties. Stuttgart and Detroit tier-1 suppliers qualify electrospun nanofiber surface layers for extended service intervals, automating quality differentiation.
- Foam:Open-cell polyurethane structures serve pre-filter and coarse filtration applications.
- Steel:Perforated and expanded metal substrates provide structural support in high-temperature oil and fuel filtration.
Most production volume shifts through Synthetic Fiber. Expansion is climbing the fastest in Synthetic Fiber as REACH PFAS restrictions force reformulation investments.
Application:
Duty cycle intensity and thermal management requirements segment demand between consumer replacement patterns and commercial fleet operating conditions.
- Passenger Vehicles:Universal air and cabin filter fitment across combustion, hybrid, and battery electric architectures. China's expanding electrified platforms create specialized battery thermal management filter categories with distinct service access points.
- Commercial Vehicles:Fleet operators in North American long-haul corridors negotiate annual supply contracts bypassing regional jobbers. Centralized maintenance systems compress traditional distribution layers while upgrading to higher-efficiency filtration systems.
- Heavy-Duty Trucks:Severe-duty oil and fuel filtration protects engine bearing surfaces under extended drain intervals.
- Sports Cars:High-performance intake systems prioritize airflow optimization with tighter pressure-drop tolerances.
Most filter consumption originates from Passenger Vehicles. Commercial Vehicles show the steepest expansion trajectory through fleet consolidation and direct procurement platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers migrate toward jurisdictions with favorable cost-of-compliance structures while maintaining proximity to demand clusters. Filter substrate production concentrates where petrochemical feedstock access intersects with automotive assembly density.
United States
Commercial fleet operators in the Midwest and Southeast corridors negotiate annual supply contracts through direct-to-fleet procurement platforms. EPA tailpipe and evaporative emissions rules mandate filtration efficiency thresholds that accelerate synthetic fiber substitution. Detroit hosts tier-1 supplier R&D centers qualifying electrospun nanofiber layers for extended service intervals.
Germany
Stuttgart anchors precision-engineered synthetic media development through captive R&D centers serving European OEM supply contracts. Euro 7 emissions rules from the European Commission force material upgrades across pleated media, accelerating cellulose displacement. Baden-Württemberg manufacturing clusters harden positioning against Asian cost competition through multi-layer cabin filter architectures.
China
Domestic OEMs expanding electrified vehicle platforms drive specialized cabin and battery thermal management filter categories. GB national standards collectively mandate filtration efficiency thresholds alongside evolving evaporative emissions protocols. Yangtze River Delta production clusters absorb volume concentration as cost-competitive pleated media manufacturing scales.
India
Organized service networks in tier-2 and tier-3 cities present white space for branded filter distributors with certified compatibility databases. Central bank liquidity provisions and PLI scheme incentives indirectly support automotive component manufacturing scale-up. Maharashtra and Gujarat industrial corridors attract substrate production investments serving domestic OEM expansion.
Japan
Automotive assemblers source precision filtration components through consolidated procurement platforms for hybrid and battery electric architectures. METI industrial policy frameworks support advanced materials development for high-temperature thermal management applications. Kanto and Kansai manufacturing belts maintain specialized supply relationships with domestic OEM qualification systems.
Automotive Filters Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue electrified vehicle thermal management specializations. The vendor base stratifies across premium synthetic media providers, backward-integrated substrate producers, and commodity-grade cellulose fabricators. Three archetypes dominate: tier-1 systems integrators with captive R&D, mid-cap specialists in multi-material lamination, and scale-driven regional manufacturers. Competitive moves concentrate on strategic partnerships for nanofiber technology licensing and geographic expansion into underpenetrated aftermarket channels.
Among Germany-based fabricators, MANN+HUMMEL GmbH and MAHLE GmbH exemplify the tier-1 systems integrator archetype through Stuttgart-anchored development centers. Donaldson Company, Inc. occupies a position representing North American heavy-duty channel specialization. These three entities anchor the competitive structure without exhausting the participant universe.
| Leading Market Players |
|---|
| MANN+HUMMEL |
| MAHLE GmbH |
| Donaldson Company, Inc. |
| Robert Bosch GmbH |
| Toyota Boshoku Corporation |
| Parker Hannifin Corp |
| DENSO Corporation |
| UFI Filters SPA |
| Hengst SE |
| Others |
Supply Flow & Price Mechanics
Tier-1 OEM procurement teams in Stuttgart and Detroit anchor contract structures around multi-year synthetic media supply agreements with built-in volume escalators. These concentrated buyers extract pricing leverage through backward-integrated substrate qualification requirements while compressing margin pools for mid-tier cellulose suppliers locked into spot-market pulp exposure.
Pricing Analysis
Distributor margin layers in the North American aftermarket absorb the steepest compression as direct-to-fleet procurement platforms eliminate regional jobber markups. Pricing stratifies across premium, standard, and economy tiers with differentiation driven by ISO-certified compatibility databases and electrospun nanofiber performance specifications. Cost compression in commodity-grade cellulose segments is intensifying because Yangtze River Delta manufacturers export at converted cost parity. Fleet operators with centralized maintenance systems show lowest price sensitivity while independent repair shops in India's tier-3 cities face acute budget constraints.
Supply Chain Analysis
Freight cost differentials between containerized ocean lanes and overland European corridors shape sourcing decisions for activated carbon and synthetic nonwoven inputs. Manufacturing concentration clusters in China, Germany, and the United States with Baden-Württemberg and Michigan anchoring precision-engineered output. Raw material flows draw from petrochemical feedstocks in the US Gulf Coast, specialty pulp from Nordic forestry operations, and activated carbon from Southeast Asian coconut shell processing. Single-source vulnerability in electrospun nanofiber equipment constrains capacity expansion for mid-cap specialists. Distribution runs through consolidated OEM supply contracts and fragmented aftermarket jobber networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic fiber substitution and extended service interval specifications create margin expansion headroom for certified suppliers with captive R&D infrastructure. Cellulose substrate volatility accelerates the premium-tier shift toward multi-layer architectures with higher per-unit value capture.
For Market Incumbents: Lock in electrospun nanofiber capacity through equipment pre-commitments with Stuttgart-based technology licensors before REACH PFAS compliance deadlines strain polymer formulation pipelines. Deepen backward integration into nonwoven substrate production to defend margin position against Yangtze River Delta cost competitors. Prioritize certification investment for Euro 7 and EPA evaporative emissions protocols to disqualify mid-cap challengers from OEM supply contracts. For New Entrants and Emerging Players: Electrospun surface-layer specialization offers the most penetrable wedge for battery thermal management filter categories where incumbent qualification cycles lag BEV platform launches. Target India's tier-2 and tier-3 aftermarket cities through certified compatibility databases paired with organized service network partnerships. Pursue direct-to-fleet platform integration as the primary go-to-market angle for North American commercial vehicle segments. For Investors and Strategic Acquirers: Tier-1 automotive suppliers with thermal management system portfolios are the most active acquirer in this space, seeking filtration technology to bundle with battery pack and HVAC module contracts. The five-to-ten year viability window favors targets with electrospun nanofiber process patents and established OEM qualification relationships. Acquisition target archetypes include mid-cap specialists in multi-material lamination with stranded capacity in European manufacturing clusters. Monitor EPA certification timeline compression as the inflection signal for R&D throughput constraints that would trigger distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Electrospun Nanofiber Capacity Expansion | Captures extended service interval specifications from Detroit and Stuttgart OEM procurement teams. |
| Backward Integration into Nonwoven Substrates | Secures margin control against pulp price volatility and REACH PFAS reformulation cost pass-through. |
| Direct-to-Fleet Platform Partnership | Bypasses distributor markup layers in Midwest and Southeast long-haul trucking corridors. |
| Battery Thermal Management Filter Development | Addresses material degradation thresholds above 150°C in Chinese OEM electrified platforms. |
| Indian Aftermarket Service Network Buildout | Establishes first-mover position in tier-2 and tier-3 cities with fragmented jobber structures. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors in North America and Europe, fleet maintenance operators, and filtration media R&D leads. Secondary validation drew from EPA certification filings, Euro 7 regulatory drafts, vehicle production databases, IHS Markit registration data, and customs trade records for synthetic fiber and activated carbon inputs. Bottom-up segment sizing triangulated against top-down OEM production forecasts across the analysis window.
Segment-weighting approaches distributed volume and value across filter type, material architecture, end-user channel, and regional production cluster dimensions throughout the forecast period. CAGRs derived from installed base modeling, replacement cycle elasticity estimates, and content-per-vehicle trajectories for electrified platforms. Industry-specific inputs included Euro 7 implementation phasing, EPA evaporative emissions test protocol evolution, and Chinese GB standards alignment with battery thermal management duty cycles.
The model holds under stable regulatory implementation schedules and petrochemical feedstock pricing; deviation in cellulose pulp harvest cycles or REACH PFAS restriction acceleration would shift synthetic fiber substitution trajectories and margin pool distributions. Stakeholders should weight assumptions against their own operating context and qualification pipeline visibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Active Seat Headrests Market
Automotive Components
Automotive Seat Frame Market
Automotive Components
Automotive Actuators Market
Automotive Components
Automotive Commutator Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
Intelligent Torque Controlled Coupling (ITCC) Market
Automotive Components
Automotive Gudgeon Pin Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Argentina Automotive Electric Actuators Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Automotive Radiator Fan Market
Automotive Components
Automobile Accessories Market
Automotive Components
Asia-Pacific Automotive Parts and Components Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Automotive Fuel Injection System Market