
 Automotive Radiator Fan Market | 2026-2036
Automotive Radiator Fan Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Radiator Fan Market Outlook
Chinese motor manufacturing clusters are pivoting toward brushless DC production for automotive thermal applications. Robert Bosch GmbH leverages its integrated electronics division to supply precision motor controllers for electric fan modules. Valeo SA sustains competitive positioning through dedicated thermal systems R&D facilities across European automotive corridors. Johnson Electric Holdings Limited anchors Asia-Pacific supply chains with high-volume manufacturing plants serving regional OEM assembly networks.
An automotive radiator fan is a motorized axial or centrifugal blower assembly designed to force airflow across a heat exchanger core, typically operating at 12-24 volts DC with rotational speeds exceeding 2,000 RPM to maintain optimal coolant temperatures. Its primary industrial purpose is to regulate engine thermal equilibrium during idle and low-speed operation when natural convection proves insufficient. Electric fan configurations now dominate OEM installations as automakers phase out belt-driven mechanical units to reduce parasitic engine load and improve fuel efficiency. Brushless DC technology leads technology segmentation due to superior energy conversion efficiency and extended service intervals compared with conventional AC motor architectures.
The EPA enforces Corporate Average Fuel Economy standards that penalize manufacturers for excess engine cooling energy consumption, directly accelerating electric fan substitution across US vehicle programs. EMA and REACH frameworks in Europe mandate material compliance and recyclability thresholds for polymer fan housings and electronic components, raising compliance costs for non-integrated suppliers. NHTSA safety protocols govern blade containment and electrical fault protection, shaping product validation requirements for tier-1 certification. Stakeholders must monitor regulatory divergence between emissions-driven efficiency mandates and safety-driven design constraints when allocating R&D budgets across regional product portfolios.
Market Dynamics
The transition from belt-driven mechanical fans to electric motor architectures constitutes the dominant structural force restructuring automotive cooling supply chains. This electrification pivot eliminates parasitic engine load while enabling precise thermal control algorithms that optimize fuel efficiency across variable operating conditions.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Penalties for excess cooling energy consumption accelerate electric fan substitution across US vehicle programs. OEMs redesign thermal systems to minimize electrical draw.
- Brushless DC motor technology:Superior energy conversion efficiency and extended service intervals displace conventional AC architectures in tier-1 sourcing specifications.
- China EV production clusters:Domestic battery electric vehicle scaling creates concentrated demand for high-efficiency thermal management components from local suppliers.
Market Restraints
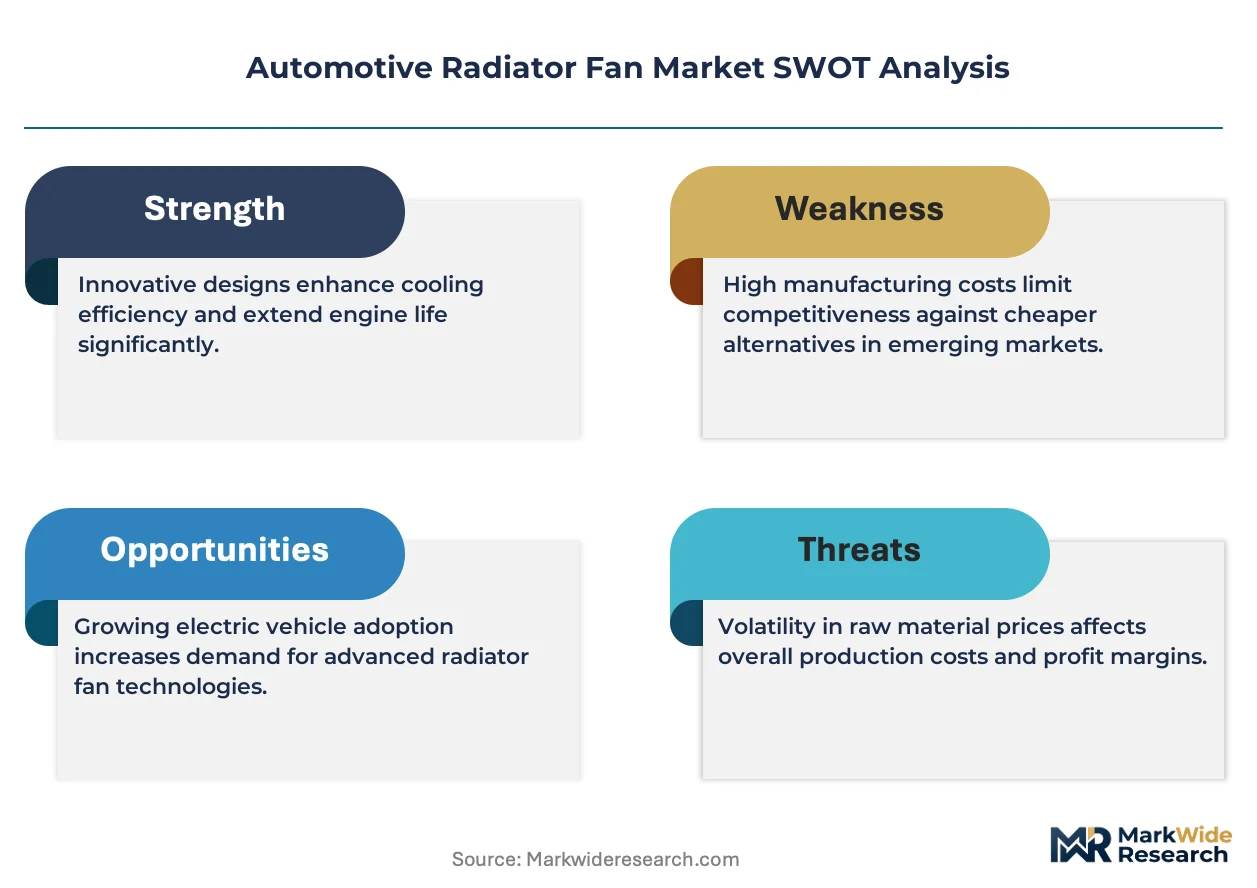
- Copper and rare-earth magnet cost volatility:Brushless DC motors depend on neodymium and copper windings subject to commodity price swings. Input cost uncertainty compresses margin visibility for motor manufacturers.
- European REACH compliance burden:Material recyclability thresholds for polymer fan housings and electronic components raise fixed costs for non-integrated suppliers lacking in-house polymer recycling capabilities.
- Mechanical fan residual installed base:Belt-driven units persist in commercial vehicle segments where upfront cost sensitivity outweighs lifecycle efficiency gains.
Strategic Opportunities
- India automotive thermal systems:Underpenetrated electric fan adoption in domestic passenger vehicle production creates white space for component localization under PLI scheme incentives.
- Autonomous vehicle thermal loads:Sensor fusion computers and LiDAR arrays generate supplemental cooling requirements distinct from powertrain thermal management.
- Vehicle-to-grid bidirectional charging:Thermal management during extended stationary power export creates new operating profiles demanding adaptive fan control algorithms.
Industry Challenges
- Embedded software certification:ISO 26262 functional safety validation for motor control firmware extends development timelines and requires specialized automotive systems engineering talent.
- Legacy platform integration:Retrofitting electric fan modules into existing engine bay architectures demands mechanical redesign without full vehicle program investment authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Radiator Fan Market |
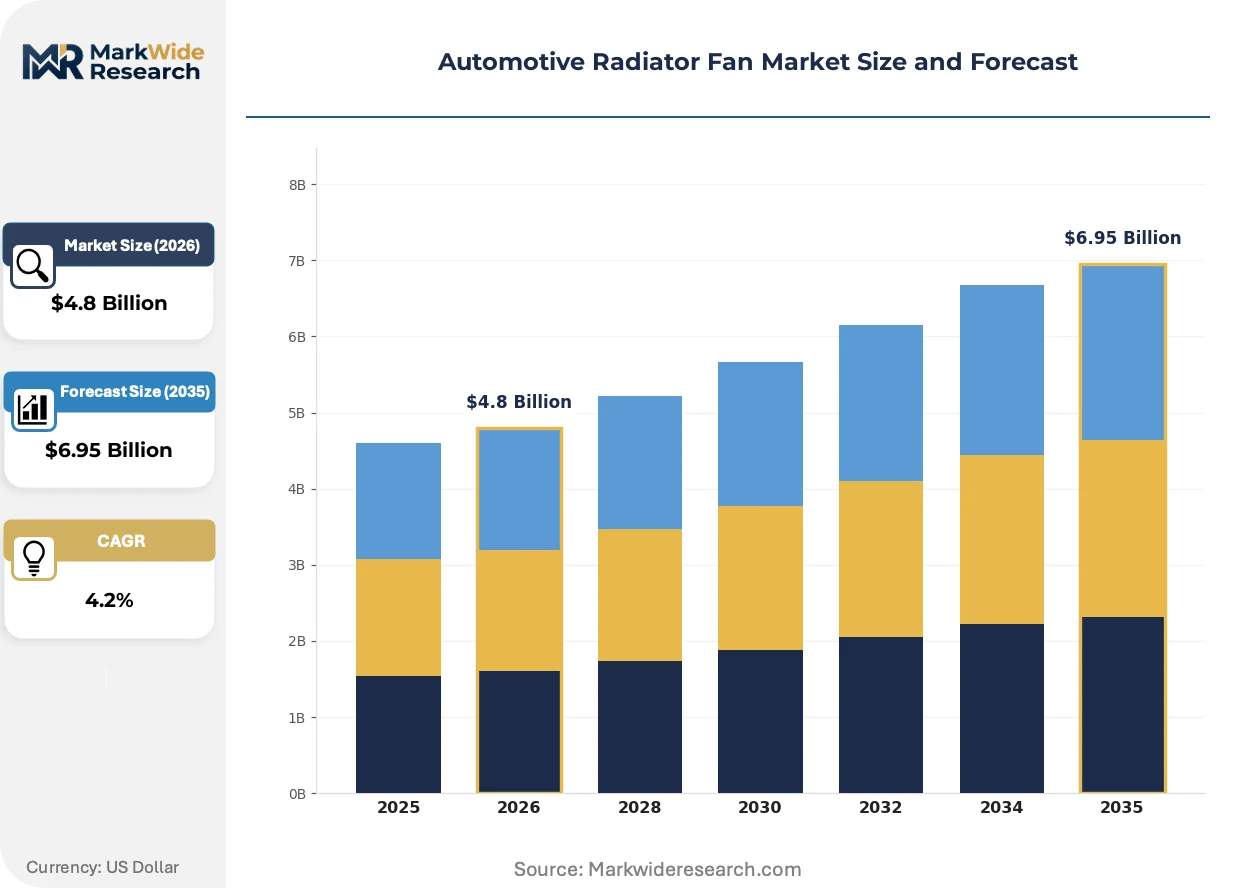
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pusher Fan, Puller Fan, Dual Fan, Electric Fan Technology: Brushless DC, AC, Solar, Mechanical End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Installation Type: Direct Fit, Universal Fit, Custom Fit, Manual Installation |
| Companies Covered | Robert Bosch GmbH, Johnson Electric Holdings Limited, Valeo SA, Nidec Corporation, Hella KGaA Hueck & Co., DENSO Corporation, BorgWarner Inc, Standard Motor Products, Mahle GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Radiator Fan Market Strategic Shifts
Active thermal management intelligence is displacing fixed-speed fan operation across OEM specifications. Predictive cooling algorithms now modulate airflow based on anticipated thermal load rather than reactive temperature thresholds.
Brushless DC motor controllers with integrated power electronics are automating real-time speed adjustment based on coolant temperature, vehicle speed, and air conditioning demand signals. Tier-1 suppliers embed these controllers directly into fan shroud assemblies. The technology is automating the elimination of separate engine control module fan control circuits.
REACH framework amendments in Europe mandate expanded substance disclosure for polymer compounds used in under-hood applications. ECHA enforcement prioritizes fan housing materials containing recycled content thresholds. European OEMs now specify post-consumer recycled polyamide grades in thermal module sourcing requirements.
Fleet operators and leasing companies now contract thermal system performance rather than component procurement. Powertrain-as-a-service agreements transfer cooling system lifecycle responsibility to tier-1 module suppliers. This unbundling concentrates most visibly in German commercial vehicle procurement where total cost of ownership guarantees dominate specification decisions.
Automotive Radiator Fan Market Segmentation
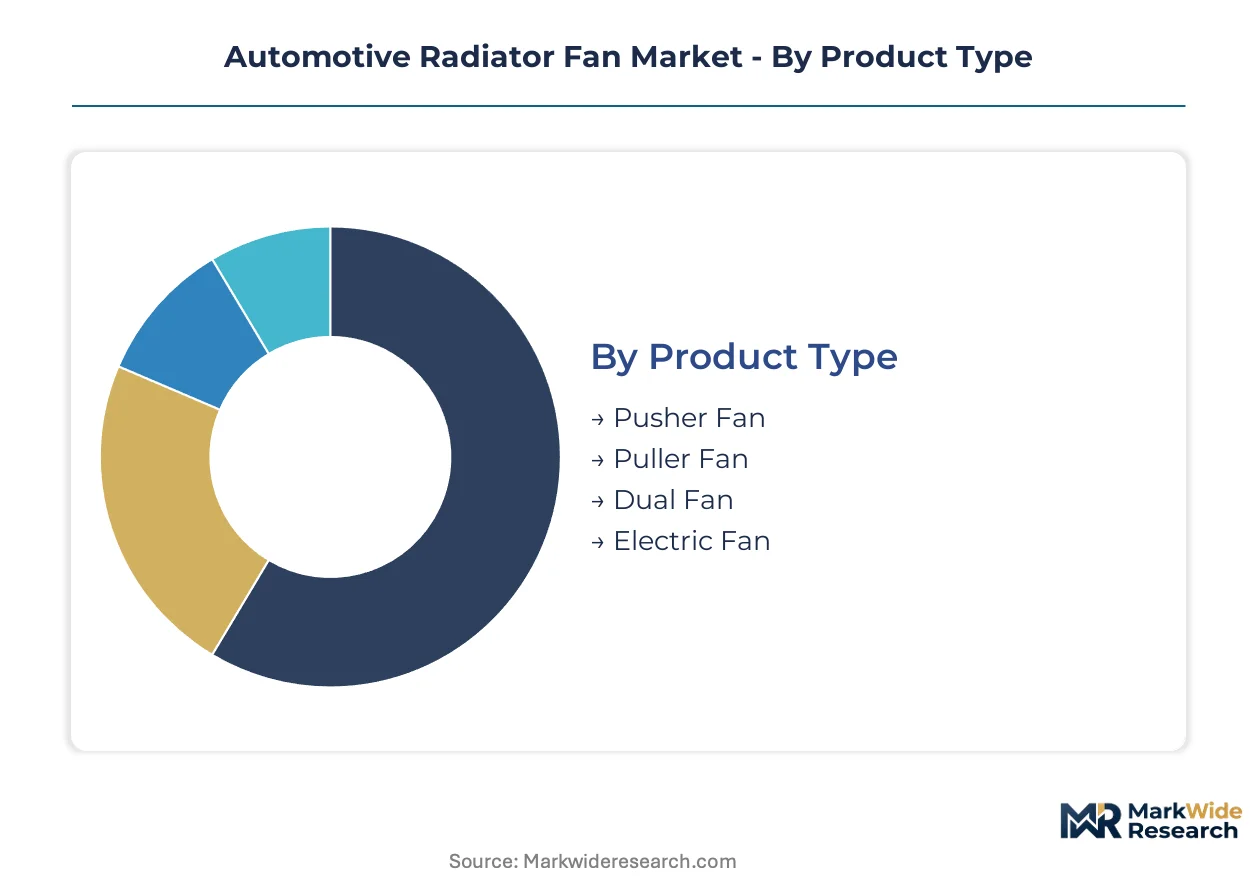
Automotive radiator fan procurement decisions hinge on thermal load requirements, electrification roadmaps, and integration complexity. Each segmentation dimension reveals distinct margin structures and supplier capability thresholds that reshape competitive positioning across vehicle programs.
Product Type:
Vehicle thermal architecture dictates fan configuration selection, with engine bay packaging constraints and cooling duty cycles driving specification divergence.
- Electric Fan:Brushless DC motor assemblies with integrated controllers dominate new vehicle programs. EPA Corporate Average Fuel Economy penalties for parasitic losses compel OEMs to eliminate belt-driven alternatives across US passenger vehicle production.
- Dual Fan:Tandem axial configurations with independent speed zones serve high-performance powertrains and hybrid thermal systems. Demand concentrates in German luxury vehicle manufacturing where precise coolant temperature management protects turbocharged engine durability.
- Puller Fan:Behind-radiator mounting extracts heated air through the core. Fleet operators specify puller designs for commercial vehicle segments where service access and blade protection outweigh efficiency optimization priorities.
- Pusher Fan:Front-mounted blowers force ambient air across heat exchangers. Japanese kei-car manufacturers retain pusher configurations for compact engine bay layouts with minimal frontal area.
Electric Fan leads on scale; Dual Fan leads on momentum.
Technology:
Motor architecture selection separates suppliers with in-house electronics integration from commodity motor assemblers.
- Brushless DC:Electronically commutated motors with permanent magnet rotors achieve conversion efficiencies exceeding 85%. Tier-1 sourcing specifications from Valeo and Robert Bosch GmbH mandate brushless architectures for electric vehicle thermal modules.
- Mechanical:Belt-driven fans with viscous clutches persist in heavy-duty commercial applications. Upfront cost sensitivity in Indian truck manufacturing sustains mechanical fan procurement despite lifecycle efficiency penalties.
- AC:Alternating current induction motors serve aftermarket replacement markets where controller compatibility constraints limit brushless retrofit feasibility.
- Solar:Photovoltaic-powered auxiliary fans address idle cooling in recreational vehicle and marine applications. Niche demand from Australian caravan manufacturers exploits high solar irradiance conditions.
Brushless DC commands volume concentration; Solar gains share fastest.
End User:
Procurement authority distribution determines pricing power and technical specification depth across the value chain.
- OEMs:Original equipment manufacturers issue thermal system performance specifications and validate fan modules for entire vehicle program lifecycles. Ford and General Motors source integrated fan-shroud-controller assemblies under multi-year blanket orders.
- Tier-1 Suppliers:Thermal module specialists consolidate component procurement and assume design responsibility. Mahle Behr and Hanon Systems negotiate motor supply agreements with Johnson Electric Holdings Limited for regional assembly networks.
- Vehicle Assemblers:Contract manufacturers and kit builders procure fan modules through distributor channels. Brazilian flex-fuel conversion shops represent fragmented demand with minimal specification leverage.
- Aftermarket Providers:Independent distributors and service chains stock replacement units for aging vehicle parc. RockAuto and O'Reilly Auto Parts compete on catalog breadth and same-day availability.
OEMs lead on scale; Tier-1 Suppliers lead on momentum.
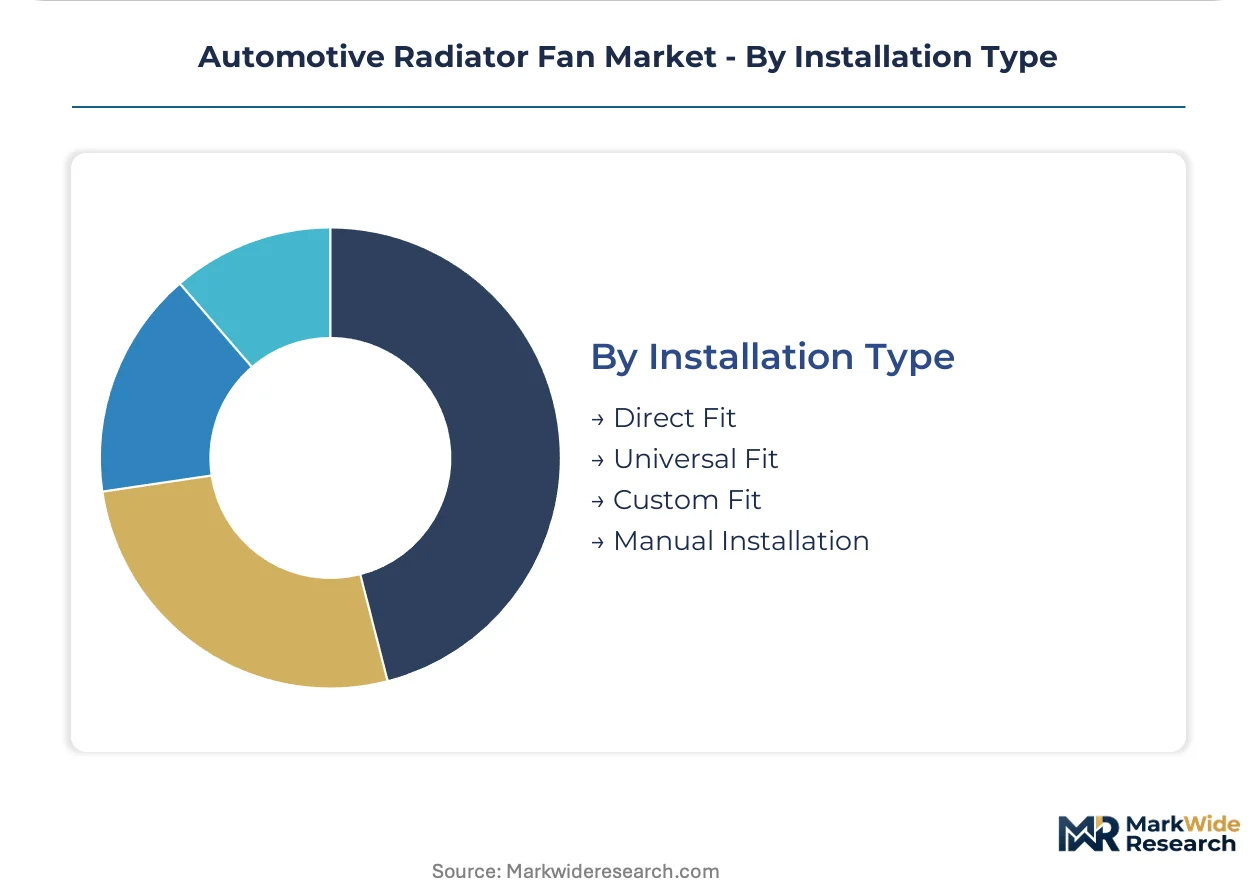
Installation Type:
Integration complexity separates captive OEM supply from open aftermarket distribution.
- Direct Fit:Vehicle-specific brackets, connectors, and calibration files enable plug-and-replace service procedures. Ford F-150 and Toyota Camry program volumes justify dedicated tooling for direct-fit fan module production.
- Custom Fit:Engineered solutions for modified powertrains and racing applications. Australian V8 Supercar teams commission custom fan configurations for sustained high-load circuit conditions.
- Universal Fit:Adjustable mounting hardware serves multiple vehicle platforms. Price-sensitive consumers in Mexican independent repair shops select universal units despite fitment labor premiums.
- Manual Installation:Basic fan assemblies requiring wiring modification and bracket fabrication. Hobbyist restoration projects in US classic car clubs absorb manual installation complexity for cost minimization.
Direct Fit leads on scale; Custom Fit leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting production toward jurisdictions where REACH compliance costs and EPA efficiency penalties create divergent cost structures. Chinese motor clusters capture tier-1 contracts as European suppliers absorb ECHA disclosure burdens.
United States
EPA Corporate Average Fuel Economy penalties compel Detroit automakers to eliminate belt-driven mechanical fans across light-duty truck programs. NHTSA blade containment protocols shape validation requirements for electric fan module certification. Michigan and Ohio thermal system plants supply Ford F-150 and General Motors Silverado assembly lines with integrated fan-shroud-controller assemblies.
Germany
EMA material compliance mandates and REACH recyclability thresholds raise fixed costs for polymer fan housing production. KBA type-approval procedures govern aftermarket replacement part homologation. Bavarian automotive corridors host Valeo and Robert Bosch GmbH R&D facilities developing brushless DC motor controllers for European OEM thermal modules.
China
Domestic battery electric vehicle scaling concentrates demand for high-efficiency thermal management components. MIIT new energy vehicle subsidies and dual carbon goals accelerate electric fan substitution in powertrain cooling systems. Yangtze River Delta manufacturing clusters supply BYD, NIO, and XPeng assembly networks with locally sourced brushless DC motor modules.
Japan
Kei-car manufacturers retain pusher fan configurations for compact engine bay layouts with minimal frontal area. METI energy efficiency standards drive precision motor controller development for hybrid thermal systems. Nagoya-area suppliers serve Toyota and Honda regional assembly networks with dedicated cooling module production lines.
India
Underpenetrated electric fan adoption in domestic passenger vehicle production creates localization opportunities under PLI scheme incentives. BIS automotive component standards govern thermal module safety and performance certification. Tamil Nadu and Gujarat manufacturing zones host Johnson Electric Holdings Limited plants serving Maruti Suzuki and Hyundai Motor India assembly networks.
Automotive Radiator Fan Market Competitive Environment
German and Japanese producers anchor one tier; Chinese specialists hold contract manufacturing scale. The vendor base separates into integrated electronics-motor suppliers, pure-play motor fabricators, and thermal system module assemblers. Three archetypes dominate: vertically integrated automotive conglomerates with captive electronics divisions; independent motor manufacturers with regional manufacturing footprints; and thermal module specialists outsourcing motor procurement. Competitive moves center on backward integration into controller electronics and geographic expansion through joint ventures with regional OEMs.
Within the integrated conglomerate tier, Robert Bosch GmbH and DENSO Corporation exemplify full-stack thermal system capability spanning motor production through controller firmware. Johnson Electric Holdings Limited occupies a position among independent motor specialists with Asia-Pacific manufacturing concentration. Valeo SA anchors the thermal module specialist archetype, consolidating component sourcing under European automotive corridor supply relationships. These three patterns represent the structural segmentation determining pricing power and specification influence across OEM procurement channels.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Johnson Electric Holdings Limited |
| Valeo SA |
| Nidec Corporation |
| Hella KGaA Hueck & Co. |
| DENSO Corporation |
| BorgWarner Inc |
| Standard Motor Products |
| Mahle GmbH |
| Others |
Value Chain & Pricing Dynamics
Brushless DC motor adoption simultaneously compresses unit manufacturing economics and concentrates procurement leverage among integrated electronics suppliers. The shift from mechanical to electric architectures eliminates commodity belt-drive suppliers while elevating controller-embedded module vendors to tier-1 negotiation positions.
Pricing Analysis
Distributor margin layers in aftermarket channels absorb 35-45% of ex-factory module costs before reaching independent repair shops. Pricing stratifies across premium, standard, and economy tiers based on ISO 26262 functional safety certification grade and volume commitment scale. Cost compression in standard-grade brushless DC units is intensifying because Chinese motor clusters capture OEM sourcing contracts. Fleet operators exhibit highest price sensitivity due to total cost of ownership procurement models, while German luxury OEMs prioritize thermal performance guarantees over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with neodymium rare-earth magnet processors concentrated in China. Motor winding production draws from copper suppliers in Chile and Indonesia, with controller electronics anchored in Taiwan and South Korea. Tariff exposure on Chinese-manufactured permanent magnet rotors threatens margin stability for non-integrated assemblers. Distribution runs through tier-1 thermal module specialists who consolidate motor procurement under blanket order agreements with regional OEM assembly networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Corporate Average Fuel Economy penalty structures compound demand for electric fan substitution, making this market a regulatory compounder where compliance-driven replacement cycles override discretionary procurement delays.
For Market Incumbents: Acquire controller firmware development capabilities to defend against pure-play motor fabricators gaining specification influence. Johnson Electric Holdings Limited and Robert Bosch GmbH already embed power electronics into shroud assemblies, compressing margins for non-integrated competitors. Prioritize backward integration into rare-earth magnet recycling to offset commodity volatility in brushless DC motor inputs. For New Entrants and Emerging Players: Begin with India passenger vehicle electric fan localization under PLI scheme incentives, where underpenetrated adoption creates white space absent entrenched supplier relationships. Target aftermarket direct-fit modules for US light-duty truck parc, leveraging catalog breadth competition against RockAuto and O'Reilly Auto Parts. Pursue sensor fusion cooling partnerships with autonomous vehicle compute platform developers as a specification entry point. For Investors and Strategic Acquirers: Valuations sit cheapest among independent motor manufacturers lacking controller integration, presenting consolidation targets for automotive electronics conglomerates. Long-term viability hinges on tier-1 thermal module supplier status with multi-year OEM blanket orders. Watch EPA enforcement intensity on CAFE penalties as the inflection signal determining electric fan substitution velocity versus mechanical residual base persistence.| Strategic Initiative | Industry Significance |
|---|---|
| Controller Integration Investment | Embedding power electronics into fan shroud assemblies eliminates separate engine control module circuits at Valeo and Robert Bosch GmbH. |
| Rare-Earth Magnet Recycling Partnership | Securing post-consumer neodymium feedstock hedges commodity volatility for brushless DC motor manufacturers serving EPA-regulated OEMs. |
| India Manufacturing Localization | Tamil Nadu and Gujarat plant investments capture PLI scheme incentives under BIS certification for Maruti Suzuki and Hyundai Motor India supply. |
| Autonomous Vehicle Thermal Module Development | LiDAR and sensor fusion cooling requirements open specification channels distinct from powertrain thermal management at tier-1 suppliers. |
| REACH-Compliant Polymer Sourcing | Post-consumer recycled polyamide grades satisfy ECHA enforcement priorities for European OEM thermal module procurement. |
Study Parameters
Bottom-up vehicle production modeling reconciled against top-down supplier shipment tracking forms the analytical core of this study. Primary interviews with tier-1 thermal module procurement officers, OEM platform engineers, aftermarket distribution managers, and brushless DC motor R&D directors combined with secondary validation from vehicle production databases, IHS Markit registration data, EPA CAFE compliance filings, and ECHA substance disclosure registers. Cross-referencing motor controller specifications against thermal system performance requirements enabled triangulation of adoption rates across propulsion architectures.
Historical trendline analysis of electric fan penetration rates in US light-duty vehicles established baseline substitution curves, then projected forward across the analysis window using EPA regulatory phase-in schedules and OEM electrification roadmaps. Segmentation modeling covered vehicle class, propulsion architecture, content per vehicle, motor technology tier, and regional production cluster. CAGRs derived from unit volume trajectories weighted by regional regulatory enforcement intensity and local supplier capacity expansion announcements.
Several conditions sit outside the modeled scope, including unannounced OEM platform cancellations, rare-earth export restriction implementations, and autonomous vehicle deployment timeline accelerations. Forecasts reflect documented assumptions about EPA penalty enforcement consistency and MIIT subsidy continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Selector Lever Market
Automotive Components
Automotive Exhaust Headers Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
UAE Automotive Composites Market
Automotive Components
Automotive Exhaust Silencer Market
Automotive Components
Regenerative Suspension System Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Automotive Push Rods Market
Automotive Components
Automotive Evaporative Emission Control (EVAP) System Market
Automotive Components
Global Automotive Composite Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Global Automotive Water Separation Systems Market
Automotive Components
Automobile Fluid Pipe Products Market
Automotive Components
China Automotive Actuators Market
Automotive Components
Global Automotive Interior Plastic Components Market