
 Automotive Automatic Tire Inflation System (ATIS) Market | 2026-2036
Automotive Automatic Tire Inflation System (ATIS) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Automatic Tire Inflation System (ATIS) Market Outlook
Fleet operators are redrawing procurement priorities away from individual owner-operators toward consolidated logistics enterprises running thousand-plus vehicle networks. SAF-HOLLAND SE anchors its position through dedicated axle-integrated ATIS architectures for North American trailer OEMs. Continental AG leverages its tire-pressure sensor ecosystem to bundle monitoring hardware with inflation actuators. Aperia Technologies, Inc. specializes in self-powered rotary pump designs that eliminate external air-line dependencies for regional delivery fleets.
An automotive automatic tire inflation system maintains optimal tire pressure through active air delivery during vehicle operation, typically employing rotary union couplings, onboard compressors, or axle-mounted pumps to sustain pressures between 80 and 120 psi in commercial tire applications. Factory-installed on-board systems dominate revenue contribution due to OEM bundling contracts with heavy-truck manufacturers, while retrofitting channels expand fastest among mid-size fleet operators seeking to extend existing asset life cycles. Pneumatic systems retain the largest installed base, though electronic control architectures are displacing mechanical regulators in premium configurations where CAN-bus integration enables real-time telematics feedback.
NHTSA mandates in the United States and UN ECE Regulation 141 in Europe shape minimum performance thresholds for tire-pressure monitoring and automatic inflation on commercial vehicles above 3.5 tonnes gross weight. The EPA SmartWay program reinforces fuel-efficiency incentives that compress payback periods for ATIS capital expenditure. Stakeholders must monitor pending amendments to FMVSS No. 138 that could mandate active inflation rather than passive monitoring alone, forcing technology roadmap recalibration across supplier engineering teams.
Market Dynamics
Fleet consolidation among thousand-plus vehicle logistics networks is compressing supplier margins while elevating technical integration requirements for axle-mounted ATIS architectures.
Growth Catalysts
- EPA SmartWay program:Fuel-efficiency certification requirements shorten capital expenditure payback periods for heavy-duty trailer operators adopting continuous tire pressure management.
- Cross-border freight corridors:Dense commercial traffic between Texas and California sustains retrofit installation demand among regional less-than-truckload carriers.
- CAN-bus integration:Real-time telematics feedback loops enable predictive maintenance scheduling that reduces roadside tire failure incidents.
Market Restraints
- Stainless steel rotary union sourcing:Concentrated supply from German precision machining specialists creates input cost volatility during commodity price spikes.
- Mechanical regulator installed base:Legacy pneumatic architectures in ten-year depreciation cycles slow electronic control displacement despite superior performance.
- FMVSS No. 138 pending amendments:Uncertainty around active inflation mandates versus passive monitoring delays procurement decisions among risk-averse fleet managers.
Strategic Opportunities
- Regional delivery electrification:Last-mile electric truck fleets require ATIS compatibility with regenerative braking thermal profiles and reduced maintenance windows.
- UN ECE Regulation 141:European commercial vehicle mandates above 3.5 tonnes gross weight create export pathways for North American axle-integrated system suppliers.
- Self-powered rotary pump architectures:Elimination of external air-line dependencies opens retrofit penetration among mid-size operators without shop infrastructure.
Industry Challenges
- Pneumatic-electronic hybrid certification:Dual validation requirements for mechanical backup systems extend engineering timelines and testing expenditure.
- Telematics protocol fragmentation:Proprietary fleet management software interfaces force redundant integration engineering across customer deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Automatic Tire Inflation System (ATIS) Market |
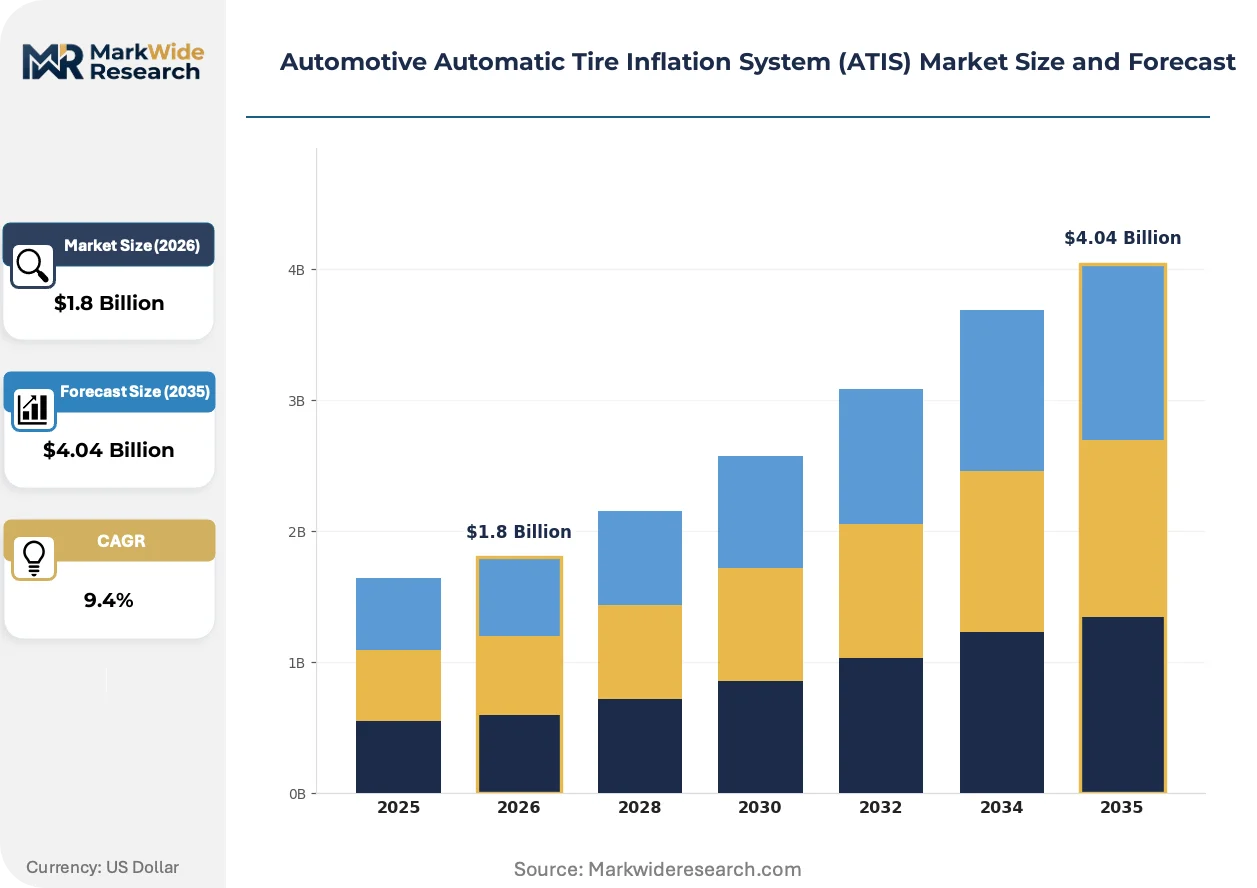
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-board Systems, Portable Units, Centralized Systems, Hybrid Units Technology: Pressure Monitoring, Pneumatic Systems, Electronic Control, Mechanical Control End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Manufacturers Installation: Factory-installed, Retrofitting, Mobile Installation, Professional Installation |
| Companies Covered | Parker Hannifin Corporation, Continental AG, Aperia Technologies, Inc., SAF-HOLLAND SE, Hendrickson USA, LLC, Meritor, Inc., Goodyear Tire & Rubber Company, Pressure Systems International, Inc., Dana Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Automatic Tire Inflation System (ATIS) Market Strategic Shifts
Electronic control architectures are displacing legacy mechanical systems as fleet operators prioritize data-driven maintenance optimization over first-cost minimization.
Axle-integrated compressor designs with brushless DC motors are displacing belt-driven onboard compressor systems in premium heavy-truck configurations. Long-haul fleet operators running refrigerated trailers adopt these units fastest due to continuous duty-cycle demands. The shift is displacing aftermarket retrofit channels for factory-installed options as OEM bundling contracts consolidate procurement authority.
NHTSA commercial vehicle safety mandates are tightening pressure-monitoring thresholds for long-haul trucks above 26,000 pounds gross vehicle weight. The regulatory pressure accelerates engineering resource allocation toward active inflation rather than passive sensor deployment. United States-based trailer manufacturers face the steepest compliance timeline compression.
Consolidated logistics enterprises are centralizing ATIS procurement through dedicated fleet engineering departments rather than decentralized maintenance supervisors. Independent distributor networks lose volume to direct OEM relationships as buyer concentration intensifies. The pattern concentrates in United States cross-border freight corridors where largest fleet operators maintain captive technical staff.
Automotive Automatic Tire Inflation System (ATIS) Market Segmentation
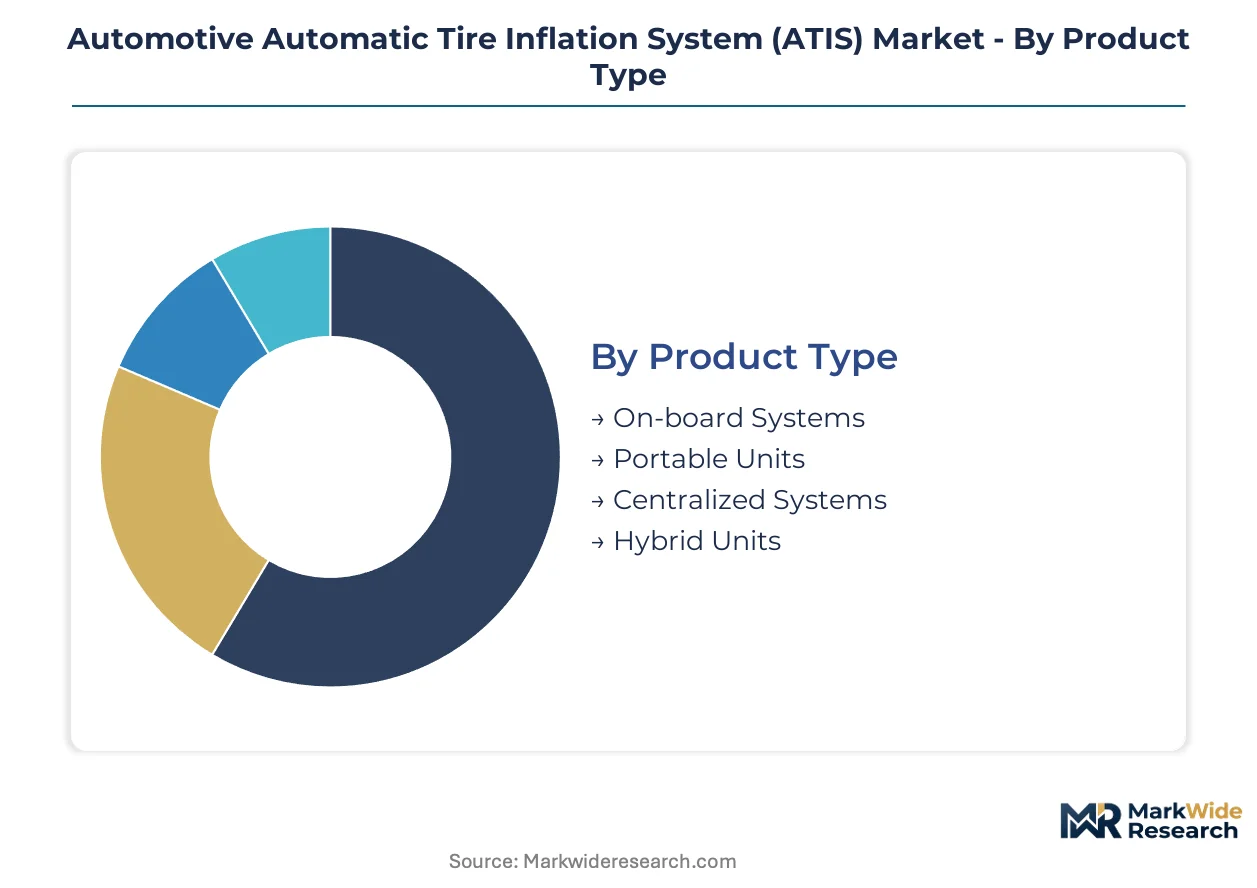
ATIS procurement patterns fragment sharply between factory-integrated architectures and aftermarket retrofit channels, with margin pools concentrating where axle-integrated designs meet consolidated fleet purchasing power. Technology choices determine integration complexity, while installation modality shapes supplier route-to-market economics.
Product Type:
Margin pools concentrate in axle-integrated architectures where OEM bundling contracts lock in multi-year supply agreements and technical integration fees.
- On-board Systems:Factory-integrated compressor and rotary union assemblies mounted directly to vehicle axles or chassis frames, sustaining pressures between 80 and 120 psi through continuous duty cycles. Demand clusters among refrigerated trailer operators running Texas-California freight corridors where NHTSA compliance timelines compress procurement decisions.
- Centralized Systems:Single compressor units distributing regulated air through dedicated line networks to multiple axle positions, common in heavy-haul configurations above 26,000 pounds gross vehicle weight. Fleet operators running thousand-plus vehicle networks in United States cross-border corridors favor these units for maintenance standardization.
- Portable Units:Self-contained inflation devices for emergency roadside deployment, typically employing battery-powered compressors.
- Hybrid Units:Dual-mode architectures combining onboard and portable functionality for flexible deployment across mixed fleet operations.
On-board systems hold installed capacity. Centralized systems are rotating up the share rankings.
Technology:
Cost tier stratification separates electronic architectures commanding premium pricing from legacy pneumatic systems competing on first-cost minimization.
- Electronic Control:CAN-bus integrated architectures with real-time pressure sensing, algorithmic setpoint management, and telematics feedback loops enabling predictive maintenance scheduling. Premium heavy-truck configurations above 26,000 pounds gross vehicle weight adopt these fastest due to EPA SmartWay fuel-efficiency certification requirements.
- Pneumatic Systems:Mechanical regulator-based architectures employing diaphragm valves and spring-loaded pressure switches without electronic intervention, retaining the largest installed base among ten-year depreciation cycle fleets. Regional less-than-truckload carriers in United States freight corridors maintain these for repair simplicity.
- Pressure Monitoring:Passive sensor arrays detecting underinflation without active air delivery, currently dominant in regulatory compliance-only deployments.
- Mechanical Control:Legacy governor-based architectures with physical linkage actuation, concentrated in retrofit installations where electronic integration proves cost-prohibitive.
Pneumatic systems hold installed capacity. Electronic control is gaining share fastest.
End User:
Customer type concentration determines contract structure, with consolidated logistics enterprises extracting volume pricing unavailable to fragmented owner-operator segments.
- Fleet Operators:Thousand-plus vehicle logistics networks with dedicated engineering departments centralizing ATIS procurement through direct OEM relationships rather than distributor networks. United States cross-border freight corridors sustain densest adoption among refrigerated trailer and dry van operators seeking to reduce tire-related downtime.
- OEMs:Heavy-truck and trailer manufacturers bundling axle-integrated systems into factory configurations, capturing integration margins through multi-year supply agreements with axle and chassis suppliers.
- Aftermarket Providers:Independent distributors and service networks targeting mid-size fleet operators seeking to extend existing asset life cycles without factory installation.
- Vehicle Manufacturers:Light and medium-duty truck producers integrating simplified ATIS variants for vocational applications.
Fleet operators hold installed capacity. Aftermarket providers are rotating up the share rankings.
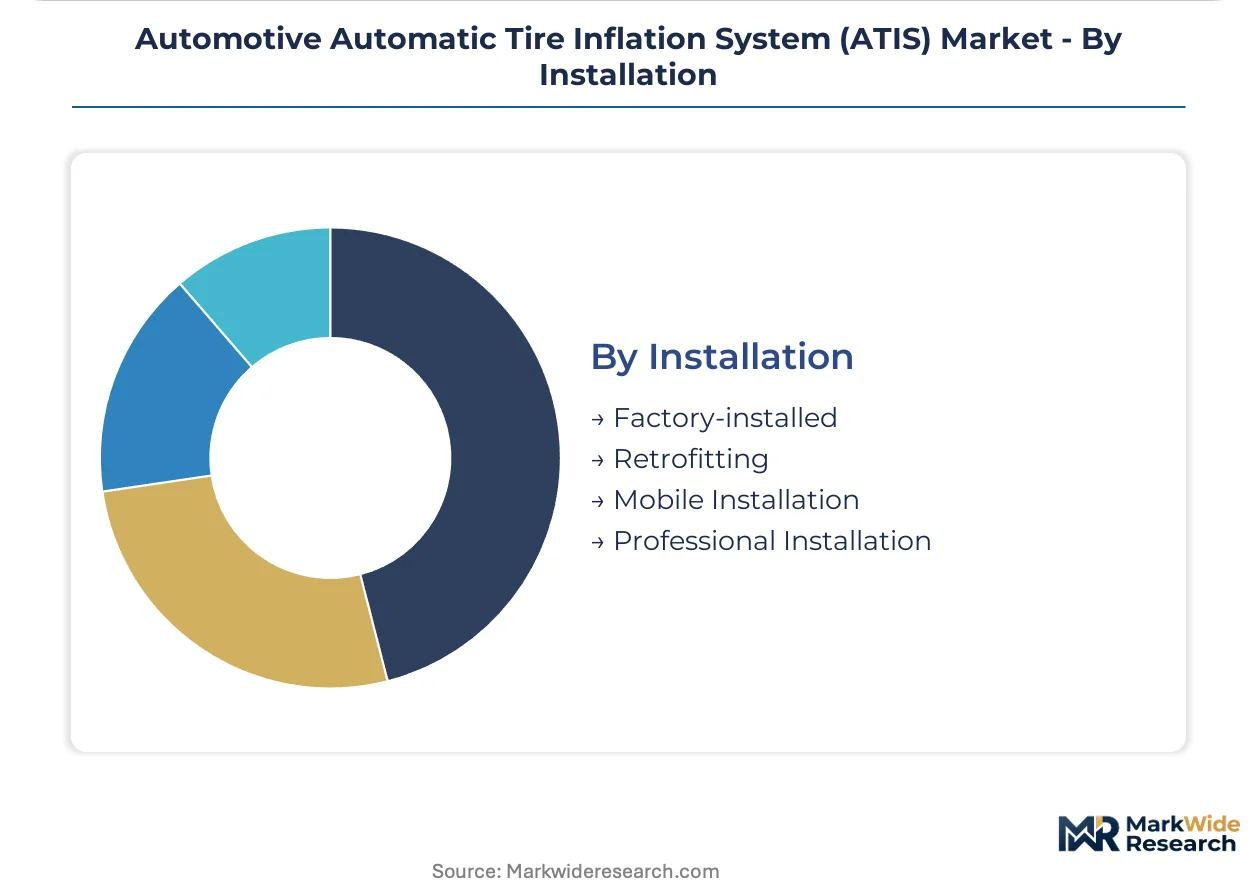
Installation:
Volume distribution favors factory-installed configurations where OEM bundling contracts consolidate procurement authority, while retrofitting channels expand through self-powered architectures eliminating shop infrastructure requirements.
- Factory-installed:Axle-integrated systems mounted during original vehicle assembly, dominant in revenue contribution due to OEM technical integration and warranty bundling. United States trailer manufacturers face steepest NHTSA compliance timeline compression for configurations above 26,000 pounds gross vehicle weight.
- Retrofitting:Post-assembly installation of axle-mounted or portable systems, expanding fastest among mid-size fleet operators through self-powered rotary pump designs eliminating external air-line dependencies. Regional delivery fleets in Texas and California freight corridors drive this channel.
- Professional Installation:Dealer or authorized service center deployment with warranty coverage and technical certification.
- Mobile Installation:On-site service deployment for fleet operators minimizing vehicle downtime.
Factory-installed holds installed capacity. Retrofitting is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 10 corridor linking Texas to California sustains North America's densest ATIS retrofit installation base, while regulatory pressure from Washington D.C. accelerates factory-integrated adoption timelines.
United States
Cross-border freight traffic between Texas and California drives retrofit demand among regional less-than-truckload carriers seeking tire-related downtime reduction. NHTSA commercial vehicle safety mandates tighten pressure-monitoring thresholds for long-haul trucks above 26,000 pounds gross vehicle weight. Dallas-Fort Worth anchors the largest concentration of refrigerated trailer operators adopting axle-integrated systems for SmartWay fuel-efficiency certification.
Germany
Precision machining specialists in Baden-Württemberg supply stainless steel rotary unions to North American axle manufacturers, creating input cost linkages across the Atlantic. UN ECE Regulation 141 shapes minimum performance thresholds for tire-pressure monitoring on commercial vehicles above 3.5 tonnes gross weight. Stuttgart's automotive engineering cluster concentrates R&D resources toward electronic control architectures with CAN-bus telematics integration.
China
Domestic heavy-truck production volumes in Shandong and Hubei provinces generate factory-installed ATIS demand for export-oriented logistics fleets. MIIT fuel-efficiency standards for commercial vehicles compress payback period calculations for continuous tire pressure management systems. The Yangtze River Delta manufacturing corridor hosts component suppliers targeting axle-integrated compressor assemblies for regional delivery electrification.
Mexico
Maquiladora assembly plants along the northern border states integrate ATIS into heavy-truck configurations destined for United States cross-border freight corridors. NOM-044-SEMARNAT emissions regulations for heavy-duty vehicles indirectly pressure tire maintenance optimization for fuel economy compliance. Nuevo León's Monterrey industrial hub concentrates trailer OEM technical integration capacity serving consolidated logistics enterprises.
Automotive Automatic Tire Inflation System (ATIS) Market Competitive Environment
Concentration sits with diversified automotive suppliers and dedicated axle-integrated system specialists rather than pure-play tire manufacturers. The vendor base spans three tiers: multinational conglomerates with pneumatic component portfolios, mid-size specialists in rotary pump architectures, and regional retrofit distributors. Strategic moves center on OEM bundling contract capture and backward integration into precision machining capacity for rotary union production.
Among Germany-based diversified suppliers, Continental AG anchors the electronic control architecture tier through tire-pressure sensor ecosystem bundling. SAF-HOLLAND SE exemplifies the axle-integrated specialist archetype with dedicated architectures for North American trailer OEMs. Aperia Technologies, Inc. occupies a position within the self-powered rotary pump segment, eliminating external air-line dependencies for regional delivery fleet retrofit penetration.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Continental AG |
| Aperia Technologies, Inc. |
| SAF-HOLLAND SE |
| Hendrickson USA, LLC |
| Meritor, Inc. |
| Goodyear Tire & Rubber Company |
| Pressure Systems International, Inc. |
| Dana Incorporated |
| Others |
Value Chain & Pricing Dynamics
Multi-year OEM bundling contracts with axle manufacturers lock in both stainless steel rotary union supply access and fixed-price visibility for North American trailer producers facing NHTSA compliance deadlines. Fleet procurement centralization extracts volume discounts that compress supplier margins while elevating technical integration fees.
Pricing Analysis
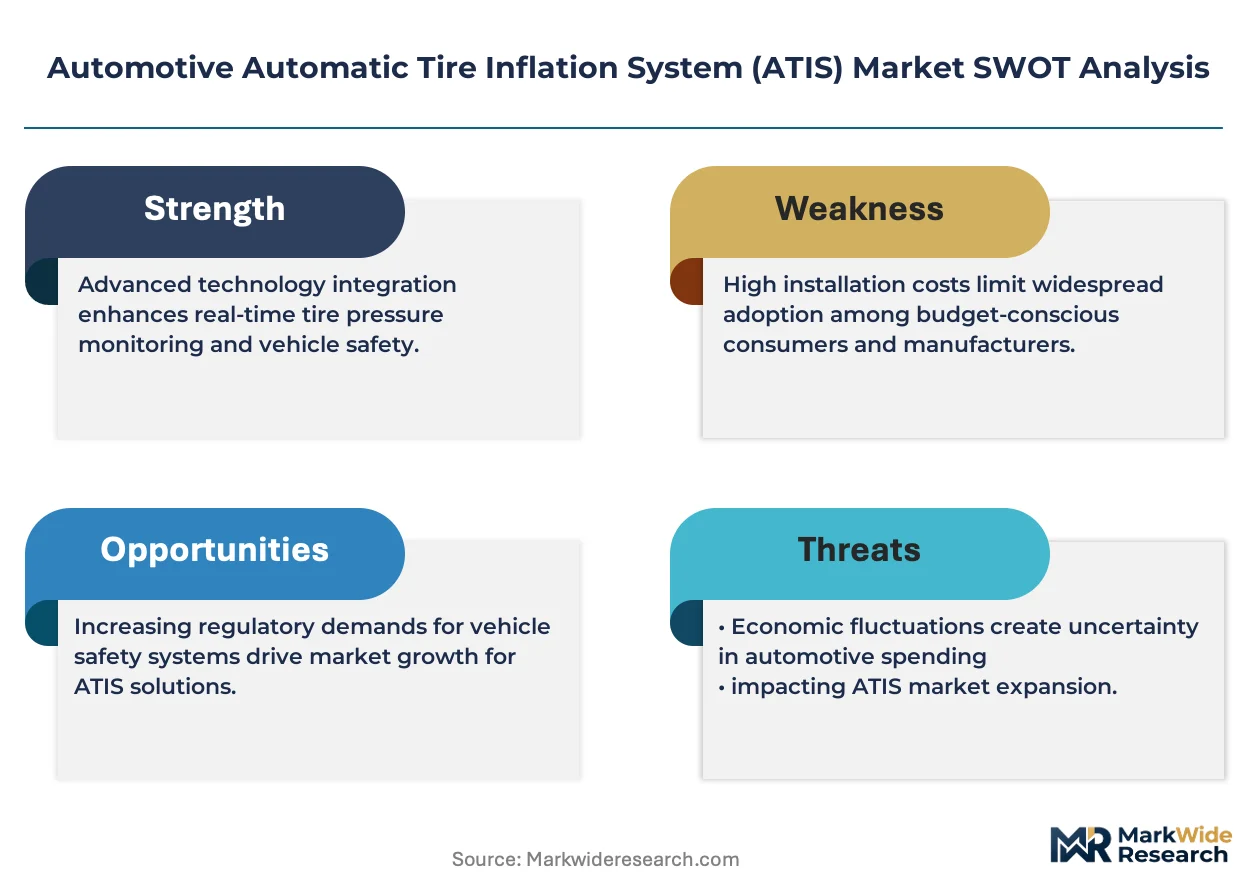
Three-tier pricing structure across premium, standard, and economy levels dominates ATIS procurement, with electronic CAN-bus architectures commanding premium positioning against legacy pneumatic alternatives. Price differentiation hinges on EPA SmartWay certification status and axle-integrated versus portable installation modality. Cost compression in economy tiers is intensifying because mid-size fleet operators prioritize first-cost minimization over predictive maintenance capabilities. Owner-operators exhibit highest price sensitivity, while thousand-plus vehicle logistics networks negotiate least-cost options through dedicated engineering departments.
Supply Chain Analysis
Inventory buffers for precision-machined rotary unions extend to sixteen weeks, creating procurement rigidity for United States trailer OEMs during commodity volatility spikes. German precision machining specialists in Baden-Württemberg, Chinese component suppliers in the Yangtze River Delta, and Mexican maquiladora assembly plants in Nuevo León constitute the three-node supply geography. Raw material dependencies center on specialty stainless steel alloys, brushless DC motors, and CAN-bus controller chips. Single-source vulnerability for German rotary union production poses structural risk given trans-Atlantic logistics chokepoints. Distribution runs through direct OEM technical integration channels rather than independent aftermarket networks for factory-installed configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ATIS procurement is shifting toward platform-based ecosystem competition where CAN-bus telematics interoperability determines supplier stickiness, mirroring broader automotive software-defined vehicle transitions.
For Market Incumbents: Compound defensive positioning through captive precision machining capacity for rotary union production and exclusive axle-integrated design partnerships with refrigerated trailer OEMs serving Texas-California freight corridors. Electronic control architecture R&D investment represents the critical lever against self-powered rotary pump substitutes threatening retrofit channel displacement. Backward integration into brushless DC motor supply insulates margin pools from commodity volatility. For New Entrants and Emerging Players: Predictive maintenance software layers atop existing pneumatic installations present the most penetrable service gap, as incumbent suppliers under-serve ten-year depreciation cycle fleets with algorithmic pressure optimization. Regional less-than-truckload carriers in United States cross-border corridors offer lowest competitive density for mobile installation service models. Partnership routes with independent distributor networks bypass direct OEM relationship requirements. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with captive rotary pump manufacturing and established EPA SmartWay certification pathways. Long-term viability centers on regulatory tailwinds converting passive monitoring mandates to active inflation requirements across North American and European commercial vehicle fleets. Pending FMVSS No. 138 amendments signal the critical inflection indicator for technology roadmap validation.| Strategic Initiative | Industry Significance |
|---|---|
| Axle-Integrated System Partnership | Locks in multi-year supply agreements with refrigerated trailer OEMs serving NHTSA-regulated corridors. |
| CAN-Bus Telematics Integration | Enables predictive maintenance scheduling that reduces roadside tire failure incidents for fleet operators. |
| Self-Powered Rotary Pump Development | Eliminates external air-line dependencies, opening retrofit penetration among mid-size operators without shop infrastructure. |
| Precision Machining Backward Integration | Captive stainless steel rotary union production insulates margins from German supplier concentration risk. |
| EPA SmartWay Certification Investment | Accelerates fleet procurement decisions by shortening fuel-efficiency payback period calculations. |
Study Parameters
Operator-level perspectives from fleet engineering directors, OEM platform integration managers, aftermarket distributor principals, and NHTSA regulatory affairs specialists anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against EPA SmartWay program filings, NHTSA regulatory dockets, SEC 10-K disclosures from diversified automotive suppliers, and vehicle production databases tracking axle-integrated system penetration. Bottom-up installation volume estimates triangulated against top-down market sizing derived from heavy-truck and trailer production forecasts.
Sensitivity analysis around regulatory mandate timing and fleet electrification adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, control technology modality, end-user procurement structure, and installation channel. CAGRs were derived from regression analysis of historical adoption patterns against fleet size expansion and compliance deadline proximity. Industry-specific forecast inputs incorporated NHTSA rulemaking comment periods and UN ECE Regulation 141 implementation timelines.
Material uncertainties — pending FMVSS No. 138 amendment scope, stainless steel commodity price trajectories, and regional delivery electrification thermal profile compatibility — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding fleet consolidation velocity and regulatory enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Asia-Pacific Aircraft Tires Market
Tires and Wheels
Asia-Pacific Alloy Wheels Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
Solid Tire Market
Tires and Wheels
Automotive Winter Tire Market
Tires and Wheels
Tubeless Tire Market
Tires and Wheels
Run Flat Tire Inserts Market
Tires and Wheels
North America OTR Tire Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Automotive Racing Slicks Tire Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
Europe Tire Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Two Wheeler Tire Market
Tires and Wheels
Indirect Tire Pressure Monitoring System Market