
 Automotive Spray Guns Market | 2026-2036
Automotive Spray Guns Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Spray Guns Market Analysis
Aftermarket service revenue is reconfiguring profit pools across the automotive refinishing value chain. Graco Inc. leverages its fluid handling expertise to dominate industrial distribution channels. SATA GmbH & Co. KG anchors premium positioning through German-engineered precision spray technology. ANEST IWATA Corporation extends its reach across Asia-Pacific manufacturing clusters with localized production networks.
Automotive spray guns are precision fluid delivery devices engineered to atomize paint, primer, and coating materials through controlled air pressure or electrostatic charge, typically operating at 10-29 PSI for HVLP systems to maximize transfer efficiency and minimize overspray. Their primary commercial purpose centers on achieving uniform film thickness across vehicle body panels while complying with volatile organic compound emission thresholds. HVLP technology leads the product type landscape due to regulatory mandates on transfer efficiency, while electrostatic systems within the technology dimension command premium placement in OEM assembly lines where robotic integration demands consistent wrap-around coverage. The end-user structure tilts toward body shops and automotive repair centers as vehicle parc aging sustains collision work volumes independent of new car sales cycles.
EPA oversight in the United States enforces National Emission Standards for Hazardous Air Pollutants that directly limit conventional spray gun deployment in professional refinishing environments. The EU F-Gas Regulation and REACH framework constrain solvent-based coating formulations, indirectly elevating equipment precision requirements to maintain finish quality with compliant materials. China's MEE administers parallel VOC control zones that shape import certification pathways for foreign spray gun manufacturers. Stakeholders must monitor how dual carbon goals across Beijing, Brussels, and Washington recalibrate the cost structure of electrostatic versus conventional atomization technologies.
Market Dynamics
Transfer efficiency mandates from EPA and EU F-Gas Regulation are compressing the viable technology set for professional refinishing, forcing capital deployment toward HVLP and electrostatic platforms while marginalizing conventional high-pressure systems.
Growth Catalysts
- Vehicle Parc Aging:Rising average vehicle age across Germany, the United States, and China sustains collision repair volumes independent of new car production cycles, anchoring aftermarket demand for precision application equipment.
- REACH Framework Stringency:The EU's chemical registration requirements constrain solvent-based coating formulations, elevating equipment precision requirements to maintain finish quality with compliant low-VOC materials.
- Robotic Integration:OEM assembly lines are adopting electrostatic spray systems to achieve consistent wrap-around coverage on complex body geometries, creating specification pull-through from top-tier manufacturers.
Market Restraints
- Capital Intensity:Electrostatic system deployment requires substantial upfront investment in charging equipment and containment infrastructure, limiting penetration among independent body shops.
- Input Cost Volatility:Precision-machined air caps and fluid nozzles depend on specialized aluminum alloys and stainless steel grades subject to commodity price swings.
- Technical Limitation:Electrostatic technology performs poorly on non-conductive substrates and complex interior cavities, restricting application scope in certain repair scenarios.
Strategic Opportunities
- Underpenetrated Geography:India's collision repair infrastructure remains fragmented, with organized multi-shop operators beginning to standardize on HVLP platforms as BIS certification requirements mature.
- Technology Convergence:Integration of IoT sensors with pneumatic spray guns enables real-time transfer efficiency monitoring, creating data service revenue streams alongside hardware sales.
- Regulatory Tailwind:China's dual carbon goals accelerate MEE enforcement of VOC control zones, expanding the addressable market for compliant application equipment in tier-two manufacturing cities.
Industry Challenges
- Certification Timeline Compression:EPA NESHAP compliance documentation and EU CE marking processes extend product launch cycles, straining R&D amortization schedules for equipment manufacturers.
- Integration Complexity:Legacy pneumatic infrastructure in established body shops resists retrofit with electrostatic charging systems, requiring costly electrical upgrades and technician retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Spray Guns Market |
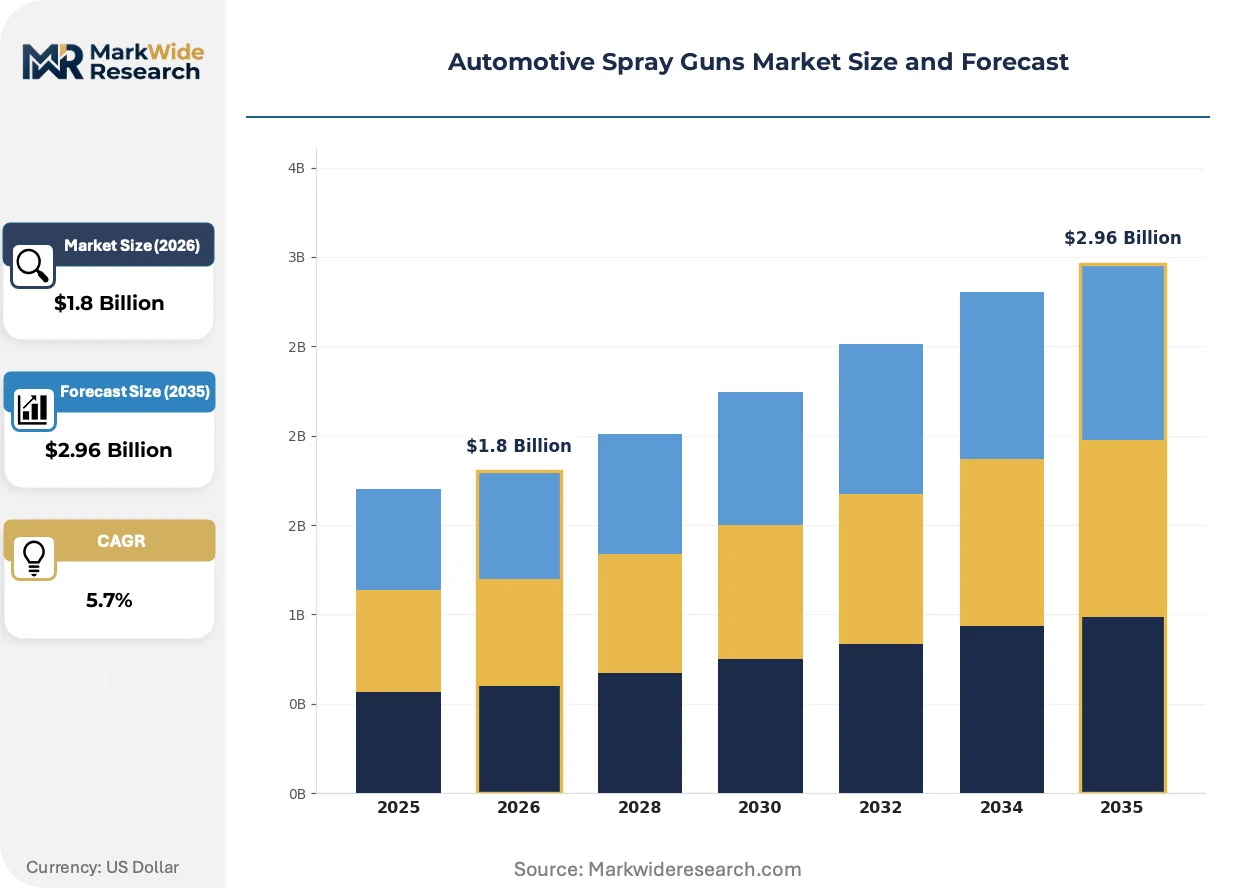
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, HVLP, LVLP, Airless End User: OEMs, Body Shops, Automotive Repair Centers, Aftermarket Providers Technology: Electrostatic, Manual, Automatic, Hybrid Application: Coating, Priming, Detailing, Paint Removal |
| Companies Covered | DeVilbiss Automotive Refinishing, Fuji Spray, Graco Inc., Binks, Wagner SprayTech, SATA GmbH & Co. KG, 3M Company, Walcom, ANEST IWATA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Spray Guns Market Emerging Trajectories
Connected application equipment and predictive maintenance protocols are reconfiguring how refinishing operations manage consumables, downtime, and quality assurance across distributed shop networks.
Smart spray gun technology is digitizing fluid delivery monitoring through embedded pressure sensors and wireless data transmission. Collision repair chains with centralized fleet management are piloting these systems to standardize finish quality across locations. Real-time atomization analytics compress warranty exposure and reduce material waste through immediate operator feedback.
The EU F-Gas Regulation tightens restrictions on fluorinated greenhouse gases used in certain coating propellants and cleaning processes. This regulatory pressure accelerates formulation changes toward waterborne and high-solids coatings that demand more precise application equipment. German and French refinishing markets are responding fastest, with equipment distributors bundling compliance training with HVLP system sales.
Refinishing procurement is consolidating through national purchasing cooperatives that aggregate volume across independent body shops. These groups negotiate direct relationships with spray gun manufacturers, bypassing traditional industrial distribution channels. The United States exhibits the most advanced cooperative formation, with regional associations achieving price transparency previously unavailable to smaller operators.
Automotive Spray Guns Market Segmentation
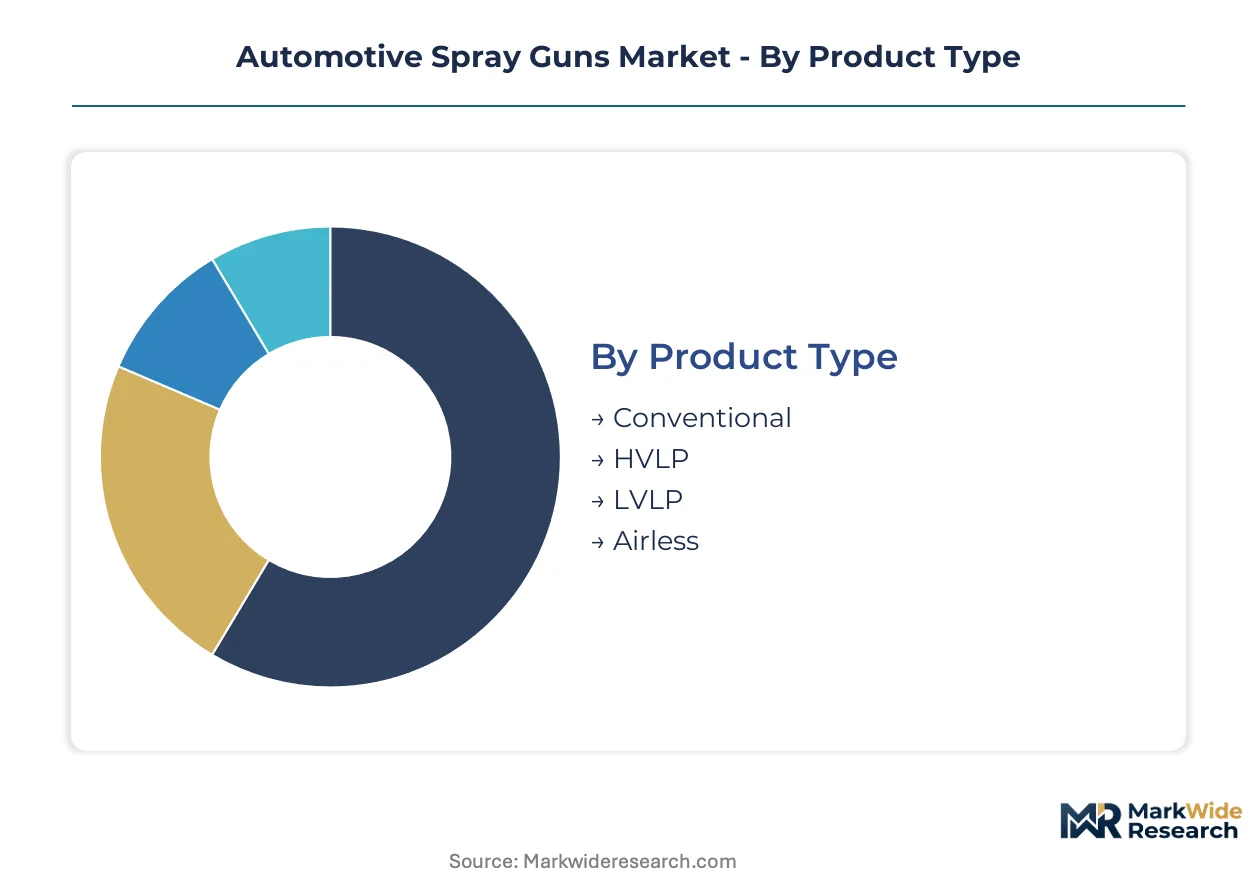
Equipment specification and operator certification requirements fragment the automotive spray gun landscape across distinct performance tiers and deployment contexts. Segmentation clarity enables targeted procurement strategies for collision repair chains, OEM assembly integrators, and independent refinishing operators navigating divergent regulatory compliance pathways.
Product Type:
Cost tier differentiation separates entry-level pneumatic systems from precision-engineered platforms commanding premium placement in certified refinishing environments.
- Conventional:High-pressure atomization systems operating above 40 PSI deliver rapid material deposition but generate substantial overspray. Demand concentrates in developing markets where EPA and EU F-Gas compliance enforcement remains uneven, particularly among uncertified independent operators in India and Mexico.
- HVLP:High-volume low-pressure technology restricts operating pressure to 10 PSI, achieving transfer efficiency above 65% to satisfy EPA NESHAP mandates. German and United States collision repair centers anchor demand as VOC control zones tighten enforcement and insurance carriers mandate certified equipment for warranty coverage.
- LVLP:Low-volume low-pressure systems reduce air consumption by 20-30% versus HVLP alternatives, appealing to mobile refinishing operators and small-footprint body shops with constrained compressor capacity.
- Airless:Hydraulic pressure atomization eliminates compressed air dependency, serving heavy-duty coating applications on commercial vehicle undercarriages and fleet maintenance depots.
HVLP holds installed capacity. LVLP is rotating up the share rankings.
End User:
Customer type determines specification stringency, with OEM procurement teams enforcing robotic integration standards that diverge sharply from aftermarket repair workflows.
- OEMs:Original equipment manufacturers deploy electrostatic automatic systems in climate-controlled paint booths, requiring nanometer-level film thickness consistency. Assembly line integration demands ISO-certified equipment with predictive maintenance protocols and centralized fluid monitoring.
- Body Shops:Independent collision repair facilities purchase pneumatic HVLP platforms through distributor networks, prioritizing technician ergonomics and quick-change fluid tip configurations. United States regional purchasing cooperatives now aggregate volume across multi-shop operators, reshaping procurement leverage.
- Automotive Repair Centers:Franchise and dealership-affiliated service bays balance throughput velocity with manufacturer certification requirements, driving specification convergence toward mid-tier HVLP systems with warranty-backed support.
- Aftermarket Providers:Mobile refinishing specialists and restoration workshops purchase portable LVLP and conventional systems for off-site deployment, accepting lower transfer efficiency for operational flexibility.
Body Shops command volume concentration. Automotive Repair Centers are climbing the fastest as dealership service integration deepens.
Technology:
Maturity gradients separate established pneumatic platforms from emerging electrostatic and hybrid architectures requiring substantial infrastructure investment.
- Electrostatic:Charged particle attraction achieves wrap-around coverage on complex geometries with transfer efficiency exceeding 85%. OEM assembly lines in Germany and China specify these systems for robotic deployment, though conductive substrate requirements limit repair scenario applicability.
- Manual:Handheld pneumatic guns remain dominant in aftermarket refinishing due to technician familiarity and minimal electrical infrastructure requirements. Skill dependency creates performance variance that connected monitoring systems now address.
- Automatic:Fixed-mount robotic spray systems integrate with conveyor-based paint booths, serving high-volume production environments where consistency outweighs flexibility.
- Hybrid:Dual-mode platforms switch between manual and automatic operation, appealing to mid-tier body shops seeking production scalability without full robotic commitment.
Manual technology holds installed capacity. Hybrid systems are rotating up the share rankings.
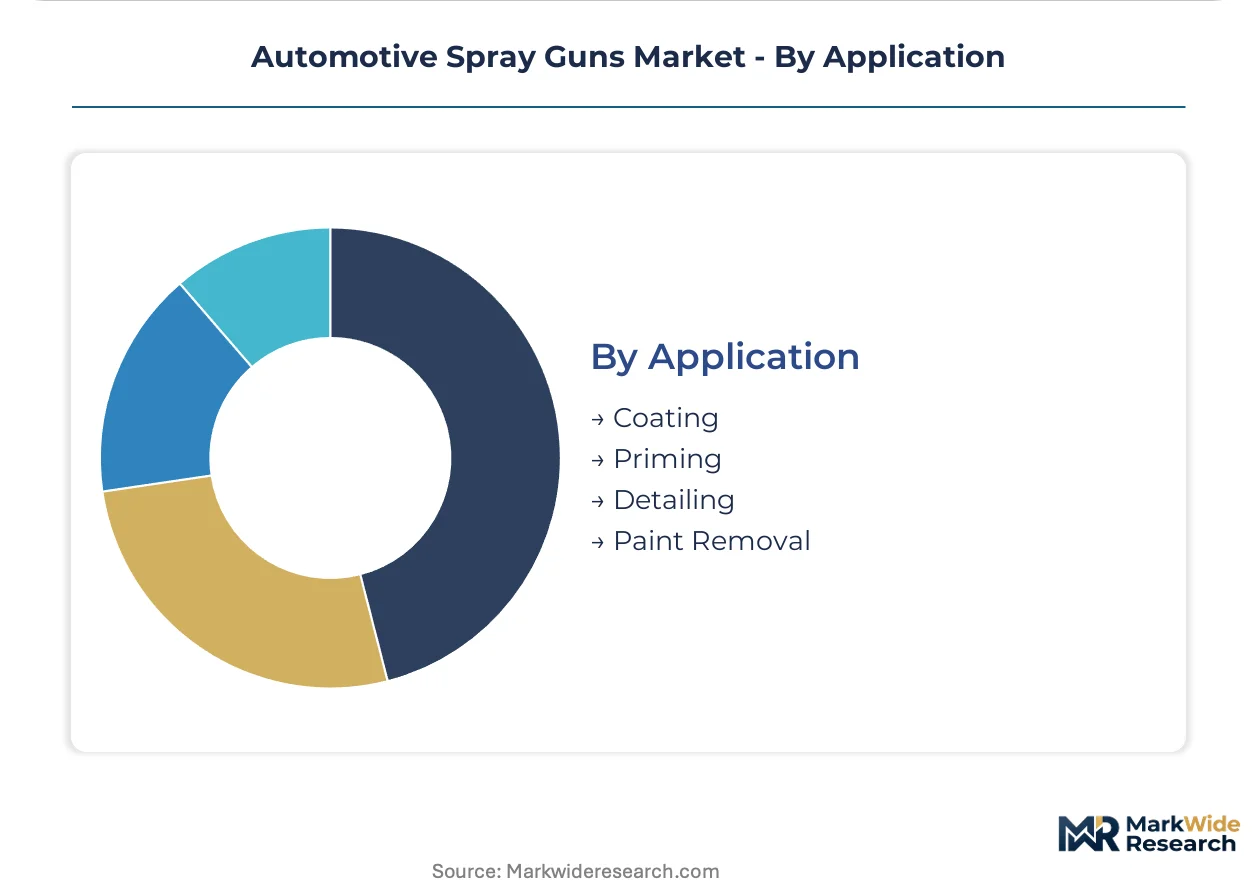
Application:
Volume concentration and margin structure diverge across refinishing workflow stages, with coating commanding the largest equipment deployment and priming presenting the steepest specification escalation.
- Coating:Basecoat and clearcoat application demands the highest transfer efficiency to minimize material waste and VOC emissions. HVLP and electrostatic systems dominate this stage across certified refinishing operations in the United States, Germany, and China.
- Priming:Epoxy and urethane primer surfacer application requires heavier film build, favoring high-volume delivery systems with larger fluid nozzle orifices. Surface preparation quality directly impacts final finish adhesion, elevating equipment precision requirements.
- Detailing:Touch-up and spot repair operations utilize mini-HVLP and airbrush configurations for localized material deposition, serving dealership reconnaissance departments and luxury vehicle specialists.
- Paint Removal:Media blasting and chemical stripping preparation stages employ specialized abrasive delivery equipment distinct from coating application platforms, typically sourced from separate industrial supply channels.
Coating holds installed capacity. Detailing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German collision repair centers absorb premium HVLP equipment costs through insurance-backed procurement, while Indian independent operators prioritize low-capital conventional systems despite compliance risks.
Germany
KBA certification requirements and insurer-mandated equipment standards drive specification rigor in collision repair chains. The EU F-Gas Regulation and REACH framework constrain solvent formulations, elevating precision equipment requirements. Stuttgart and Munich industrial corridors host dense concentrations of certified body shops standardizing on German-engineered HVLP platforms.
United States
Regional purchasing cooperatives aggregate volume across multi-shop operators, reshaping procurement leverage toward mid-tier equipment tiers. EPA NESHAP enforcement in VOC control zones accelerates HVLP adoption in California, Texas, and Northeast corridor states. Detroit and Los Angeles metropolitan areas concentrate collision repair infrastructure with deepening dealership service integration.
China
Automotive production density in tier-one manufacturing cities sustains OEM demand for electrostatic robotic systems. MEE dual carbon goals and VOC control zone enforcement expand compliant equipment markets in Shanghai, Guangzhou, and Chengdu. Yangtze River Delta and Pearl River Delta clusters anchor both manufacturing and refinishing service infrastructure.
India
Organized multi-shop operators are standardizing on HVLP platforms as BIS certification requirements mature and insurance penetration deepens. The country's national environmental regulator is tightening VOC emission norms in Delhi-NCR and Maharashtra. Mumbai and Chennai industrial corridors exhibit fastest equipment upgrade cycles among franchise-affiliated repair centers.
Japan
JIS standards and METI industrial policy shape equipment specification pathways for domestic and export markets. Precision manufacturing heritage sustains premium positioning for Japanese-engineered spray technology. Nagoya and Osaka industrial clusters concentrate automotive supplier networks with integrated refinishing service capabilities.
Automotive Spray Guns Market Vendor Landscape
Precision-engineering specialists and fluid-handling conglomerates split the market along performance-tier lines. Consolidation pressure concentrates among mid-cap equipment fabricators seeking scale to amortize regulatory compliance costs. Two strategic archetypes dominate: German-engineered precision platforms commanding certification-dependent premiums, and diversified industrial suppliers leveraging distribution breadth. Competitive moves center on technology licensing partnerships and geographic expansion into underpenetrated Asian markets.
Within the precision-engineering tier, SATA GmbH & Co. KG and ANEST IWATA Corporation exemplify archetype differentiation through regional manufacturing heritage. Graco Inc. anchors the diversified industrial supplier category with fluid handling expertise extending across coating application verticals. These three entities occupy positions that reflect broader market stratification between certification-premium and volume-access segments.
| Leading Market Players |
|---|
| DeVilbiss Automotive Refinishing |
| Fuji Spray |
| Graco Inc. |
| Binks |
| Wagner SprayTech |
| SATA GmbH & Co. KG |
| 3M Company |
| Walcom |
| ANEST IWATA Corporation |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor channels precision-machined components from Stuttgart to Rotterdam at volatile fuel-surcharge rates, compressing margins for mid-tier distributors while amplifying price premiums for German-engineered HVLP platforms in certified collision repair chains.
Pricing Analysis
After-sales service revenue from fluid tip replacements and calibration contracts drives lifetime value beyond the initial equipment transaction. Three-tier pricing structure across premium, standard, and economy levels separates SATA and ANEST IWATA's certification-premium platforms from Graco's volume-access mid-tier and unbranded conventional imports. Cost compression in economy tiers intensifies because Indian and Mexican independent operators prioritize low-capital entry points over EPA compliance. Franchise-affiliated automotive repair centers exhibit lowest price sensitivity due to insurance-backed procurement, while mobile aftermarket providers face acute margin pressure from compressor fuel and transport logistics.
Supply Chain Analysis
Contract manufacturing concentration for precision air caps and fluid nozzles rests with specialized metalworking foundries in Germany, Japan, and China's Yangtze River Delta. Specialized aluminum alloys 7075-T6 and 316L stainless steel for corrosion-resistant components draw from aerospace and medical device supply channels. Single-source vulnerability concentrates in electrostatic charging module production, where German and Japanese component specialists maintain proprietary winding techniques. Distribution runs through industrial fluid-handling distributors and collision repair purchasing cooperatives that aggregate volume across multi-shop operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat where EPA NESHAP and EU F-Gas certification requirements create asymmetric compliance burdens that favor incumbents with amortized documentation infrastructure.
For Market Incumbents: Build switching-cost moats through captive calibration service networks that lock body shops into proprietary fluid tip ecosystems. Deepen vertical integration into precision-machined air cap production to secure supply against commodity volatility. Consolidate distributor relationships in India's emerging organized repair chains before BIS certification requirements mature and open specification windows.
For New Entrants and Emerging Players: India's fragmented collision repair infrastructure presents the most penetrable white-space opportunity, with multi-shop operators standardizing equipment procurement as insurance penetration deepens. Target mobile refinishing specialists with portable LVLP platforms emphasizing compressor efficiency over transfer efficiency compliance. Pursue technology licensing partnerships with established electrostatic specialists to bypass R&D amortization barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized coating application divisions lacking dedicated aftermarket service infrastructure. Long-term viability centers on regulatory compliance automation and IoT-enabled predictive maintenance revenue streams. Monitor MEE enforcement intensity in China's tier-two manufacturing cities as inflection signal for electrostatic system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification-First Product Development | EPA NESHAP pre-approval accelerates body shop procurement cycles and insurance carrier acceptance. |
| IoT Sensor Integration | Real-time transfer efficiency monitoring creates recurring data service revenue alongside hardware sales. |
| Regional Manufacturing Footprint | Localized assembly in Shanghai and Chennai reduces import duty exposure and MEE certification timelines. |
| Aftermarket Service Network Expansion | Captive calibration and fluid tip replacement locks body shops into proprietary consumable ecosystems. |
| Purchasing Cooperative Partnership | Direct relationships with US regional cooperatives bypass distributor markups and standardize specifications. |
Methodological Framework
Initial hypotheses were tested against primary input from collision repair center operators, automotive OEM procurement specialists, industrial equipment distributors, and EPA compliance consultants, and refined through secondary validation across SEC 10-K filings, customs trade databases, IHS Markit vehicle production data, and EPA NESHAP enforcement records. Bottom-up demand modeling from equipment replacement cycles and top-down market sizing from coating material consumption volumes were triangulated against installed base estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled across product type tiers, end-user procurement structures, technology maturity gradients, and application workflow stages. CAGRs were derived from regression analysis of historical equipment shipments against vehicle parc aging curves and regulatory compliance enforcement intensity. Forecast inputs incorporated collision repair volume elasticity to insurance claim frequency and electrostatic system adoption rates in OEM assembly line retrofits.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed equipment manufacturers or technology convergence plays from industrial IoT platforms would shift outcomes beyond modeled ranges. Quarterly review of MEE enforcement bulletins, EU F-Gas Regulation amendment proposals, and US insurance carrier equipment mandate updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Aftermarket for Brake Components Market
Automotive Components
Global Automotive Chrome Accessories Market
Automotive Components
Global Automotive Water Valve Market
Automotive Components
GCC Automotive Lubrication Services Market
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Automotive Carbon Fiber Components Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
Automotive Engine Encapsulation Market
Automotive Components
North America Automotive Heat Shield Market
Automotive Components
India Automotive Glass Fiber Composites Market
Automotive Components
Egypt Commercial Vehicles Lubricants Market
Automotive Components
Automotive Heater Core Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Global Automotive Structural Sheet Metal Market